
 Japan Protective Coatings Market | 2026-2036
Japan Protective Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Protective Coatings Market Foresight
Kansai region capacity expansion around Osaka Bay is fragmenting domestic supply architecture. Nippon Paint Holdings Co., Ltd. leverages its captive resin production to control raw material flows across marine and industrial segments. Kansai Paint Co., Ltd. anchors its position through deep relationships with Japanese shipbuilders and heavy engineering contractors. PPG Industries, Inc. competes by importing specialized aerospace and automotive refinish technologies from its North American R&D base.
Japan protective coatings comprise formulated polymer systems—typically epoxy, polyurethane, or acrylic resins cross-linked with curing agents and loaded with corrosion-inhibiting pigments—applied at dry film thicknesses ranging from 75 to 500 micrometers to shield substrates from chemical attack, moisture ingress, and thermal degradation. Epoxy formulations dominate the corrosion protection application layer due to their adhesion strength and chemical resistance in marine and industrial settings, while water-based acrylics are gaining share in construction aesthetics as contractors face stricter site VOC limits. Powder coating technology occupies a narrow but high-margin niche in automotive underbody and appliance applications where transfer efficiency and zero solvent emissions justify capital-intensive electrostatic lines.
METI enforces Industrial Safety and Health Act standards that mandate workplace VOC exposure limits, while JIS K 5660 and JIS K 5661 set performance benchmarks for architectural and heavy-duty coatings respectively, forcing reformulation cycles every three to five years. The PMDA and Ministry of Land, Infrastructure, Transport and Tourism coordinate on infrastructure asset management protocols that specify coating system lifecycles for public works, directly influencing contractor procurement specifications. Stakeholders must track how Japan's carbon neutrality roadmap for 2050 will tighten embodied carbon accounting across coating raw material supply chains.
Market Dynamics
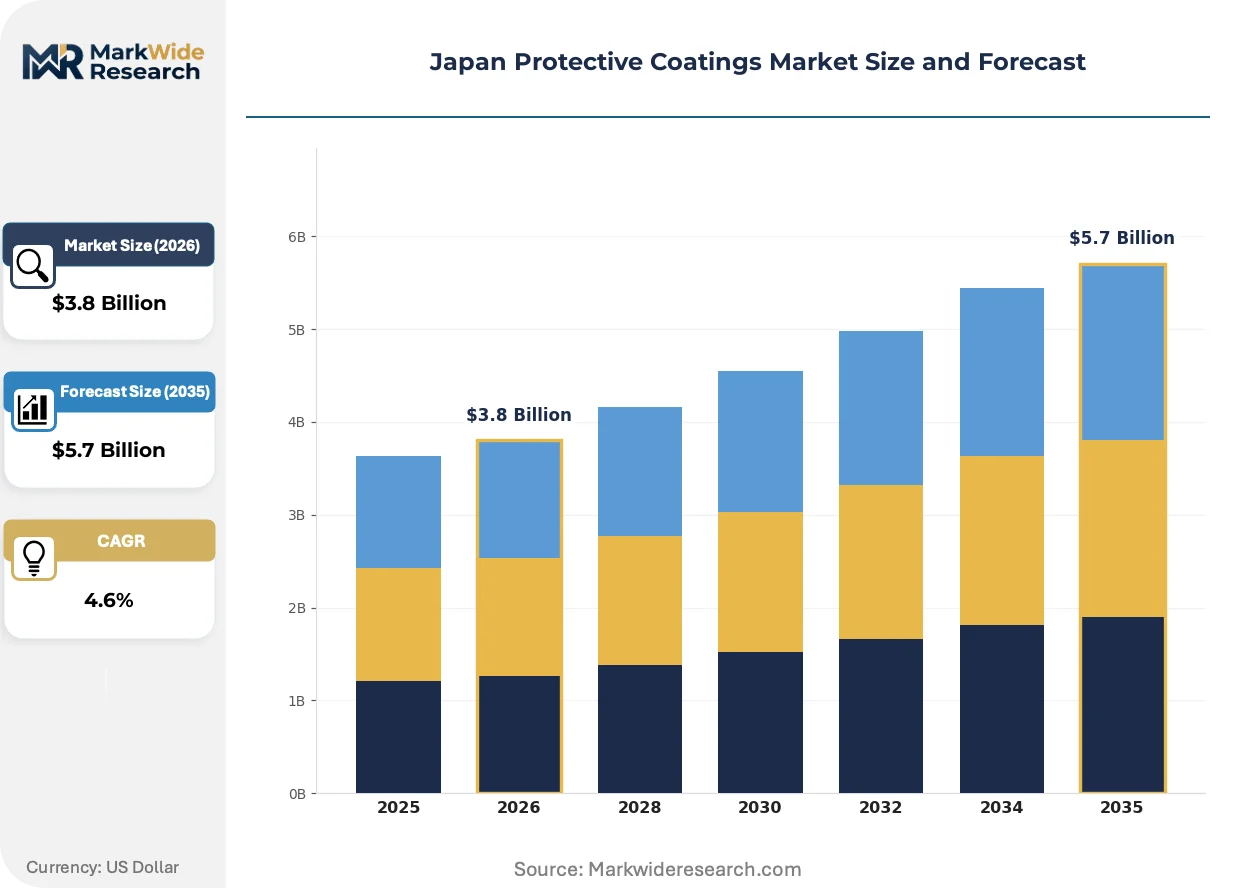
METI's solvent-to-water-based transition mandate is restructuring Japan's protective coatings value chain, forcing reformulation investments and raw material sourcing reconfigurations across the archipelago.
Growth Catalysts
- Infrastructure rehabilitation:Japan's aging bridge and tunnel networks are accelerating epoxy and polyurethane consumption as asset owners execute lifecycle extension programs under Ministry of Land, Infrastructure, Transport and Tourism protocols.
- VOC emission tightening:METI's Industrial Safety and Health Act standards are compelling contractors to specify water-based acrylic systems for construction aesthetics applications.
- Kanto industrial corridor concentration:Tokyo, Kanagawa, and Chiba prefectures are generating sustained procurement volume from marine, automotive, and heavy engineering facilities.
Market Restraints
- Petrochemical input volatility:Epoxy resin and isocyanate feedstock costs fluctuate with naphtha and propylene pricing, compressing margin predictability for formulators.
- Kansai capacity fragmentation:Osaka Bay region supply expansion is dispersing domestic production architecture and diluting economies of scale.
- JIS reformulation cycles:Three-to-five-year mandatory standard updates under JIS K 5660 and JIS K 5661 force recurrent R&D expenditure without guaranteed volume recovery.
Strategic Opportunities
- Carbon neutrality roadmap alignment:Japan's 2050 net-zero commitment is tightening embodied carbon accounting, creating first-mover advantage for bio-based resin suppliers.
- Powder coating niche expansion:Automotive underbody and appliance segments with electrostatic line infrastructure present high-margin, zero-VOC emission positioning.
- Prefecture-level procurement centralization:Consolidated public works tendering in Hokkaido and Kyushu offers volume aggregation for compliant coating system providers.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in water-based cross-linking chemistry is concentrating at legacy suppliers, constraining new entrant technical staffing.
- Electrostatic line capex barriers:Powder coating adoption requires capital-intensive equipment installation that mid-tier contractors cannot finance independently.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Protective Coatings Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyurethane, Acrylic, Alkyd End User: Construction, Automotive, Marine, Industrial Application: Corrosion Protection, Fire Protection, Aesthetics, Adhesion Technology: Solvent-Based, Water-Based, Powder Coating, Radiation Cure |
| Companies Covered | Nippon Paint Holdings Co., Ltd., Axalta Coating Systems Ltd., Akzo Nobel N.V., Sika AG, Jotun A/S, PPG Industries, Inc., Kansai Paint Co., Ltd., Wacker Chemie AG, The Sherwin-Williams Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Protective Coatings Market Shifts & Advancements
Digital formulation platforms and predictive lifecycle modeling are compressing Japan's coating specification timelines, while regulatory carbon accounting is embedding into procurement decisions.
Self-healing microcapsule technology is virtualizing maintenance scheduling for infrastructure owners. Bridge operators in the Kanto corridor are piloting autonomous crack-sealing systems that extend recoating intervals. This capability is virtualizing the traditional inspection-repair cycle into continuous substrate protection.
METI's tightened VOC exposure limits under the Industrial Safety and Health Act are mandating workplace air quality monitoring. Shipyards and heavy engineering contractors are retrofitting spray booths with closed-loop solvent recovery. Marine newbuild segments are responding fastest by specifying high-solids epoxy systems that maintain performance while reducing emission volumes.
Asset owners are unbundling coating lifecycle responsibility from general construction contracts. Tokyo metropolitan infrastructure funds now procure performance-guaranteed protection systems with embedded inspection telemetry. This restructuring is most visible in public-private partnership bridge rehabilitation programs where outcome accountability shifts to applicator-consortium arrangements.
Japan Protective Coatings Market Segmentation
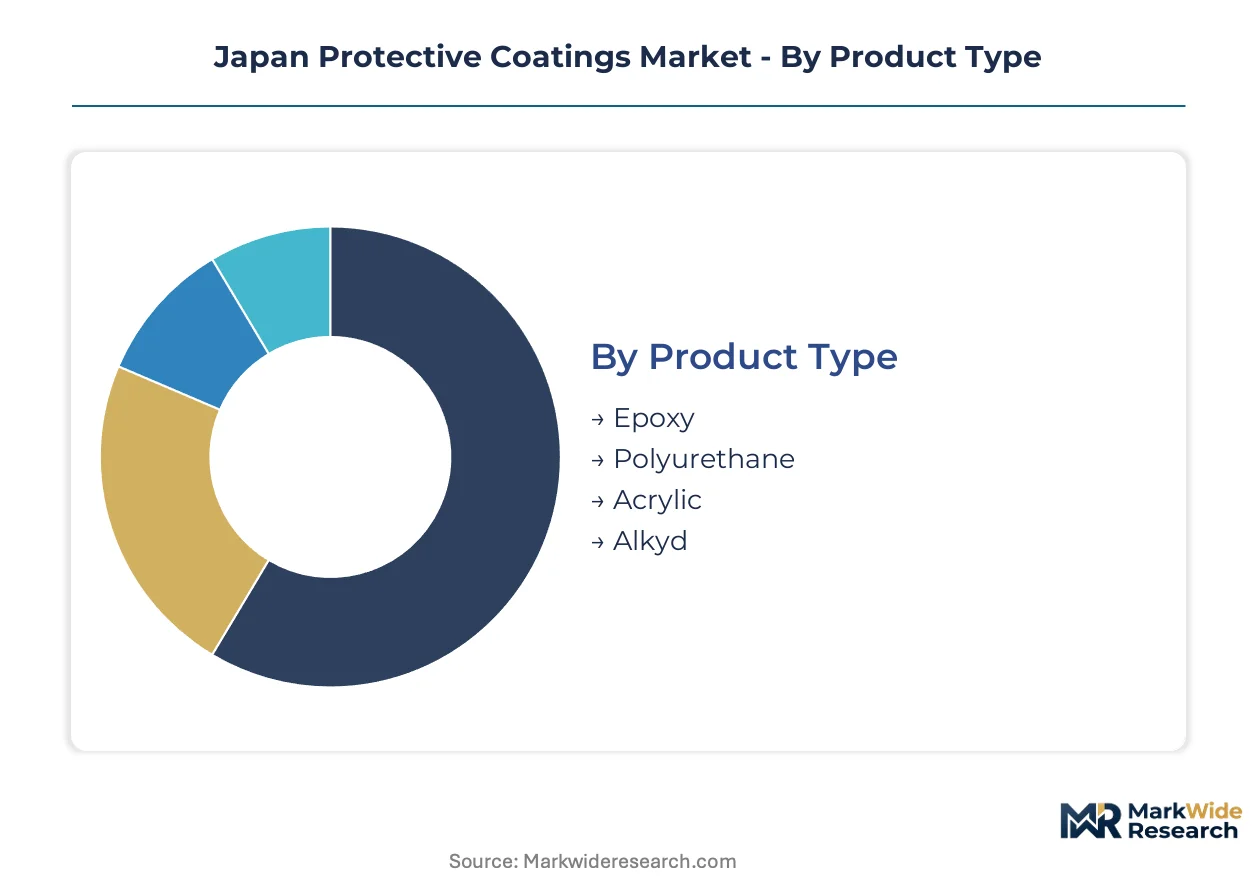
Protective coatings segmentation in Japan reveals divergent replacement cycles across chemistry types and application settings. Asset owners specify coating systems based on substrate exposure severity, regulatory compliance windows, and lifecycle cost modeling rather than upfront material cost alone.
Product Type:
Epoxy systems carry the longest recoating intervals in heavy-duty settings, while acrylics turn over fastest in construction aesthetics applications where color refresh cycles dominate.
- Epoxy:Cross-linked bisphenol-A or novolac resin systems deliver 75-500 micrometer dry film thickness with superior chemical resistance and substrate adhesion. Demand concentrates in Kanto corridor bridge rehabilitation programs where Ministry of Land, Infrastructure, Transport and Tourism protocols specify 15-20 year protection lifecycles.
- Polyurethane:Aliphatic and aromatic isocyanate-cured formulations provide UV stability and abrasion resistance for exterior exposure. Osaka Bay shipyards and heavy engineering contractors specify these systems for deck and superstructure applications facing salt spray and mechanical wear.
- Acrylic:Water-borne and solvent-borne resin systems serve construction aesthetics with faster drying and lower odor profiles. METI VOC limits are accelerating water-based uptake in Tokyo metropolitan refurbishment contracts.
- Alkyd:Traditional oil-modified polyester resins retain share in maintenance touch-up and light industrial settings where cost sensitivity overrides performance specifications.
Epoxy dominates installed base in infrastructure and marine assets. Acrylic is where expansion concentrates as water-based technology displaces solvent systems under tightening emission standards.
End User:
Construction procurement cycles track public works budgeting rhythms, while marine demand follows newbuild and drydock scheduling at Osaka Bay and Kanto shipyards.
- Construction:Bridge, tunnel, and building envelope applications specify high-build epoxy and polyurethane systems for concrete and steel protection. Tokyo metropolitan infrastructure funds are unbundling coating lifecycle responsibility into performance-guaranteed contracts with embedded inspection telemetry.
- Marine:Newbuild and maintenance coating of commercial vessels, offshore structures, and port facilities drives high-solids epoxy consumption. Japanese shipbuilders specify systems meeting Nippon Kaiji Kyokai classification society corrosion protection notations.
- Industrial:Petrochemical, power generation, and manufacturing facility maintenance requires chemical-resistant tank linings and pipe coatings. Refinery turnarounds in Chiba prefecture generate concentrated demand spikes.
- Automotive:OEM and refinish applications favor polyurethane clearcoats and electrocoat primers with precise film build control. Powder coating lines serve underbody and wheel arch protection with zero solvent emission profiles.
Marine and construction segments anchor volume concentration. Industrial maintenance is climbing fastest as aging facility infrastructure reaches recoating thresholds.
Application:
Corrosion protection specifications carry the most stringent performance requirements and longest validation cycles, while aesthetics applications permit faster material substitution.
- Corrosion Protection:Barrier and inhibitive coating systems prevent electrochemical degradation of steel substrates in marine atmospheric and immersion zones. Kanto bridge operators are piloting self-healing microcapsule technologies that virtualize traditional inspection-repair cycles.
- Fire Protection:Intumescent and cementitious coatings provide passive fire resistance for structural steel in commercial and industrial buildings. Building code enforcement in Tokyo and Osaka drives specification of certified systems with documented thickness and cure validation.
- Aesthetics:Decorative and color-retentive finishes for architectural metal and concrete surfaces. Water-based acrylics are gaining share as contractors face METI workplace VOC exposure limits on construction sites.
- Adhesion:Tie-coat and primer systems engineered for substrate-specific bonding to galvanized steel, aluminum, or existing aged coatings. Surface preparation standards under JIS K 5600 series dictate compatibility requirements.
Corrosion protection dominates specification complexity and supplier qualification barriers. Fire protection is gaining fastest as building safety retrofits accelerate in dense urban corridors.
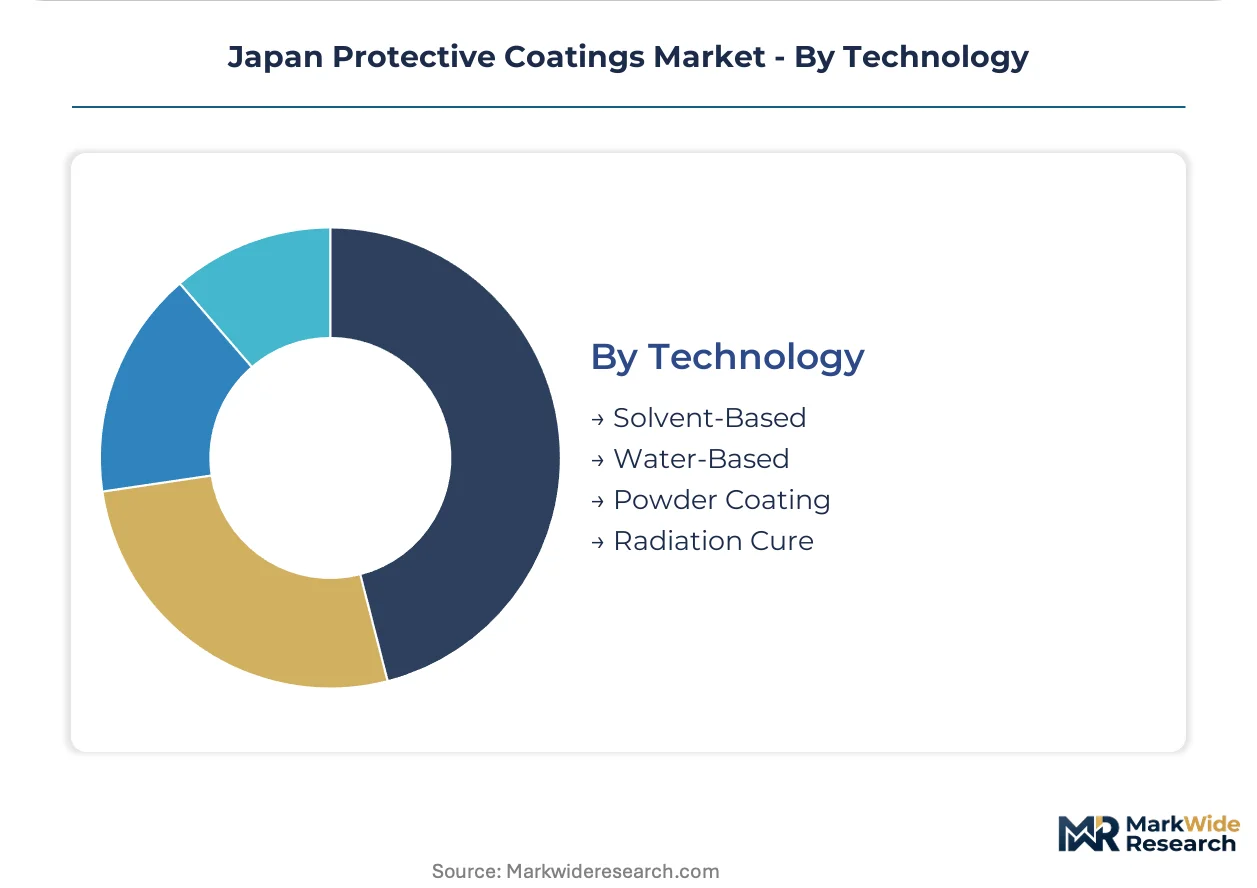
Technology:
Solvent-based systems retain performance advantages in severe exposure settings, while water-based and powder technologies are displacing them where regulatory compliance and application efficiency matter more.
- Solvent-Based:Conventional organic solvent carriers enable high-solids epoxy and polyurethane formulations with excellent flow and substrate wetting. METI Industrial Safety and Health Act standards are forcing closed-loop spray booth retrofits that raise application costs.
- Water-Based:Acrylic and epoxy dispersions with reduced VOC content serve construction and light industrial markets. Contractors in Tokyo and Kanagawa prefectures are specifying these systems to meet site air quality monitoring requirements.
- Powder Coating:Thermoset epoxy and polyester powders applied via electrostatic spray to metal substrates with near-zero overspray waste. Automotive underbody and appliance manufacturers with captive electrostatic lines capture transfer efficiency and emission compliance advantages.
- Radiation Cure:UV and electron beam curable coatings for specialty applications requiring instant cure and minimal thermal exposure. Narrow penetration in Japanese protective coatings due to substrate geometry limitations and capital equipment requirements.
Solvent-based chemistry dominates severe-service installed base. Water-based systems are expanding most quickly as METI mandates restructure contractor procurement specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
METI governs Japan's protective coatings sector through Industrial Safety and Health Act standards that mandate workplace VOC exposure limits. Prefecture-level procurement patterns concentrate demand in industrial corridors where infrastructure rehabilitation accelerates.
Kanto/Tokyo
Bridge and tunnel lifecycle extension programs drive epoxy consumption across Tokyo, Kanagawa, and Chiba prefectures. Ministry of Land, Infrastructure, Transport and Tourism protocols specify 15-20 year protection lifecycles for steel substrates. Tokyo metropolitan infrastructure funds now procure performance-guaranteed protection systems with embedded inspection telemetry.
Kansai/Osaka
Osaka Bay shipyards and heavy engineering contractors specify polyurethane systems for deck and superstructure applications facing salt spray exposure. METI VOC limits are accelerating closed-loop spray booth retrofits at marine facilities. Kansai Paint Co., Ltd. anchors regional supply relationships through captive resin production.
Chubu/Nagoya
Automotive OEM and industrial machinery manufacturing generates concentrated demand for powder coating lines. Aichi prefecture electrostatic line infrastructure serves underbody and appliance applications with zero solvent emission profiles. Refinery turnarounds in nearby Chiba generate spillover maintenance demand.
Kyushu
Consolidated public works tendering offers volume aggregation opportunities for compliant coating system providers. Fukuoka and Kitakyushu industrial zones host aging petrochemical and power generation facilities reaching recoating thresholds. Prefecture-level procurement centralization is restructuring contractor qualification requirements.
Hokkaido
Severe marine atmospheric exposure conditions drive specification of high-solids epoxy systems for port and coastal infrastructure. Cold climate application constraints favor solvent-based formulations with extended cure windows. Sapporo metropolitan area building code enforcement is accelerating fire protection coating retrofits.
Japan Protective Coatings Market Competitive Landscape
Integrated domestic chemical groups and multinational specialty coatings divisions split the market between captive resin control and imported technology transfer. The vendor base concentrates around legacy suppliers with deep shipbuilder and public works contractor relationships. Two strategic archetypes dominate: resin-integrated formulators with backward supply chain control, and technology licensors leveraging overseas R&D specialization. Capacity expansion and formulation reformulation cycles constitute the dominant competitive moves as METI mandates restructure procurement specifications.
Among resin-integrated Japanese suppliers, Nippon Paint Holdings Co., Ltd. and Kansai Paint Co., Ltd. exemplify the domestic archetype with captive production capabilities. PPG Industries, Inc. occupies a position representing the multinational technology transfer model, importing specialized aerospace and automotive refinish capabilities from North American R&D infrastructure. These three companies anchor the competitive structure without exhaustively representing all market participants.
| Leading Market Players |
|---|
| Nippon Paint Holdings Co., Ltd. |
| Axalta Coating Systems Ltd. |
| Akzo Nobel N.V. |
| Sika AG |
| Jotun A/S |
| PPG Industries, Inc. |
| Kansai Paint Co., Ltd. |
| Wacker Chemie AG |
| The Sherwin-Williams Company |
| Others |
Supply & Pricing Matrix
Osaka Bay capacity expansion has pushed regional utilization rates below optimal thresholds, forcing formulators to absorb feedstock volatility through margin compression rather than price pass-through. This utilization-driven pricing posture is reshaping procurement negotiations across Kanto and Kansai corridors.
Pricing Analysis
Kanto-to-Kansai price spreads for high-solids epoxy systems have widened as Chiba prefecture refineries concentrate supply leverage. Project-based contracting dominates, with price differentiation anchored in JIS K 5661 certification tier and volume scale. Pricing pressure stems from petrochemical input volatility, with naphtha-linked resin costs squeezing mid-tier formulators. Municipal infrastructure funds show lowest price sensitivity due to lifecycle-cost modeling, while maintenance contractors face acute margin compression.
Supply Chain Analysis
Tariff exposure between Japan and South Korea dominates supply chain risk planning for isocyanate and specialty additive sourcing. Domestic production concentrates in Chiba and Osaka Bay, with critical epoxy resin precursors drawn from South Korea and China. Raw material dependencies center on bisphenol-A, propylene derivatives, and corrosion-inhibiting pigments. Single-source vulnerability runs through Kansai Paint's captive resin architecture. Distribution runs through authorized applicator networks with direct shipyard and public works contractor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's protective coatings sector is approaching a platform-economics inflection as asset owners unbundle lifecycle responsibility and embed inspection telemetry into procurement specifications. This interoperability shift between coating performance and digital infrastructure is restructuring competitive moats.
For Market Incumbents: Entrench JIS certification leadership through accelerated water-based reformulation cycles ahead of METI's next VOC tightening. Deepen backward integration into bio-based resin precursors to preempt carbon neutrality accounting requirements. Lock in exclusive applicator consortium arrangements for Tokyo metropolitan infrastructure funds before procurement centralization completes.
For New Entrants and Emerging Players: Establish a beachhead in Kyushu prefecture-level tender aggregation where incumbent relationships remain thinner. Target Hokkaido cold-climate specialty formulations where solvent-based cure windows retain technical necessity. Lead with powder coating system partnerships for Chubu automotive suppliers seeking zero-VOC compliance without electrostatic line capex.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among formulators with performance-guaranteed infrastructure contracts embedding inspection telemetry. Five-to-ten-year viability favors resin-integrated players with captive supply control over raw material carbon accounting. Watch for METI's next Industrial Safety and Health Act revision timeline as the signal for accelerated water-based substitution inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Resins | Captive supply of low-embodied-carbon precursors aligns with Japan's 2050 neutrality roadmap. |
| Performance-Guaranteed Contracting | Tokyo metropolitan funds now procure outcome accountability shifting margin to lifecycle expertise. |
| Water-Based Reformulation Investment | METI VOC mandates force three-to-five-year JIS cycles that concentrate R&D at legacy suppliers. |
| Powder Coating Line Partnerships | Automotive underbody applications offer high-margin zero-emission positioning without full capex burden. |
| Prefecture-Level Procurement Centralization | Kyushu and Hokkaido tender aggregation rewards compliant system providers with volume concentration. |
Research Methodology
The analysis maps epoxy, polyurethane, acrylic, and powder coating sub-sectors, each validated through plant managers at Chiba and Osaka Bay formulators, procurement leads at Kanto shipyards, technical R&D directors, and public works contractors. Primary interviews triangulated against customs data, METI industrial production statistics, JIS standard revision records, and Ministry of Land, Infrastructure, Transport and Tourism infrastructure asset management protocols. Bottom-up coating consumption estimates and top-down chemical industry value flows were reconciled across segmentation dimensions.
Assumptions held fixed include METI regulatory enforcement timelines and JIS reformulation cycle periodicity, while feedstock cost trajectories and infrastructure rehabilitation funding levels were varied across scenarios. The projection horizon spans chemistry type, end-use industry, application severity, and technology platform, with CAGRs derived from regression against historical coating intensity per infrastructure yen deployed. Modeled inputs include bridge and tunnel asset age distributions, shipyard drydock scheduling patterns, and automotive production content-per-vehicle estimates.
Sensitivities concentrate around naphtha price volatility, METI VOC standard acceleration, and carbon accounting implementation pace. Forecasts reflect documented assumptions on regulatory trajectory and feedstock market structure. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Zero Friction Coatings Market
Coatings
Physical Vapor Deposition (PVD) Coatings Market
Coatings
Wire Enamels Market
Coatings
North America Powder Coatings Market
Coatings
Global Metal Coatings Market
Coatings
FBE Coatings Market
Coatings
Global UV-Cured Coatings Market
Coatings
Coating Pre-Treatment Market
Coatings
US Protective Coatings Market
Coatings
Emulsion Coatings Market
Coatings
Anti Soiling Coating Market
Coatings
United States Industrial Wood Coatings Market
Coatings
Compound Coating Market
Coatings
Self-Cleaning Coatings Market
Coatings
Italy Automotive OEM Coatings Market
Coatings
Phosphate Conversion Coatings Market