
 Marine Coatings Market | 2026-2036
Marine Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Coatings Market Analysis
The IMO 2023 Antifouling Systems Convention amendment is consolidating the cost-of-entry calculus for marine coatings suppliers, forcing reformulation investments that favor well-capitalized incumbents. AkzoNobel N.V. leverages its Intershield and Intersleek product architectures to sustain premium positioning across deep-sea commercial fleets. Jotun anchors its competitive stance through SeaQuantum antifouling systems deployed at major Asian shipyards. Hempel A/S differentiates via HEMPAGUARD silicone-hybrid technology that extends dry-dock intervals for container operators.
Marine coatings are protective and functional layers engineered from epoxy resins, zinc silicates, copper-based biocides, and silicone polymers, applied to submerged and atmospheric zones of vessels and offshore assets to prevent corrosion, reduce drag, and inhibit biological fouling. The antifouling segment commands the largest value share due to fuel-efficiency mandates and dry-dock cycle compression, while specialty coatings for offshore structures represent the fastest-expanding margin pool as operators extend platform lifespans in harsh North Sea and Gulf of Mexico environments. Water-based technology formulations are gaining traction in shipyard applications where VOC thresholds tighten, though solvent-based systems retain dominance in heavy-duty ballast tank specifications.
The European Chemicals Agency (ECHA) restricts copper oxide and cybutryne under REACH annex XVII, compelling suppliers to certify biocide-free alternatives for EU-flagged vessels. The US EPA regulates antifouling active ingredients through FIFRA pesticide registration, creating divergent compliance pathways for coatings sold into American versus European fleets. China's Ministry of Ecology and Environment (MEE) enforces GB standards on VOC emissions from marine maintenance yards, reshaping procurement criteria for domestic shipbuilders. Stakeholders must monitor regulatory divergence between biocide-restrictive and performance-driven jurisdictions when allocating R&D budgets and regional manufacturing capacity.
Market Dynamics
IMO 2023 biocide discharge thresholds are forcing wholesale reformulation across antifouling portfolios, compressing supplier margins while accelerating consolidation among well-capitalized incumbents capable of absorbing multi-year R&D cycles.
Growth Catalysts
- Fleet renewal schedules:Offshore structure maintenance programs in the North Sea and Gulf of Mexico are extending platform lifespans, generating sustained demand for high-performance protective coatings in corrosive environments.
- REACH Annex XVII restrictions:ECHA's tightening controls on copper oxide and cybutryne are compelling EU-flagged operators to certify biocide-free alternatives, creating premium positioning for compliant formulations.
- Silicone-hybrid technology:Extended dry-dock intervals enabled by advanced foul-release surfaces are reducing operational downtime for container operators, driving specification upgrades across deep-sea commercial fleets.
Market Restraints
- Epoxy resin price volatility:Petrochemical feedstock fluctuations and energy costs are compressing formulation margins, particularly for solvent-based ballast tank specifications where material intensity runs highest.
- Supply concentration in Asian shipyards:Procurement gravity around South Korea's Ulsan and Geoje clusters creates dependency risk for coatings suppliers without localized manufacturing or technical service presence.
- Biocide efficacy degradation:Accelerated resistance development in target fouling organisms is shortening effective protection windows, undermining performance guarantees and warranty structures.
Strategic Opportunities
- Water-based formulation expansion:VOC threshold tightening at China's MEE-compliant maintenance yards is opening specification pathways for low-emission technologies previously confined to niche applications.
- Offshore wind foundation coatings:Emerging demand for splash-zone protection on monopile and jacket structures represents an adjacent application with differentiated performance requirements and limited incumbent saturation.
- US EPA FIFRA registration pathways:Divergent active ingredient approval timelines versus EU REACH processes create arbitrage potential for suppliers with parallel regulatory capabilities and regional formulation flexibility.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in silicone-polymer hybrid systems and biocide-free active development is concentrating at a handful of research-intensive suppliers, constraining talent mobility.
- Dry-dock scheduling compression:Accelerated vessel turnaround requirements at major Asian yards are reducing application windows, demanding faster-cure technologies without compromising film integrity or specification compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Coatings Market |
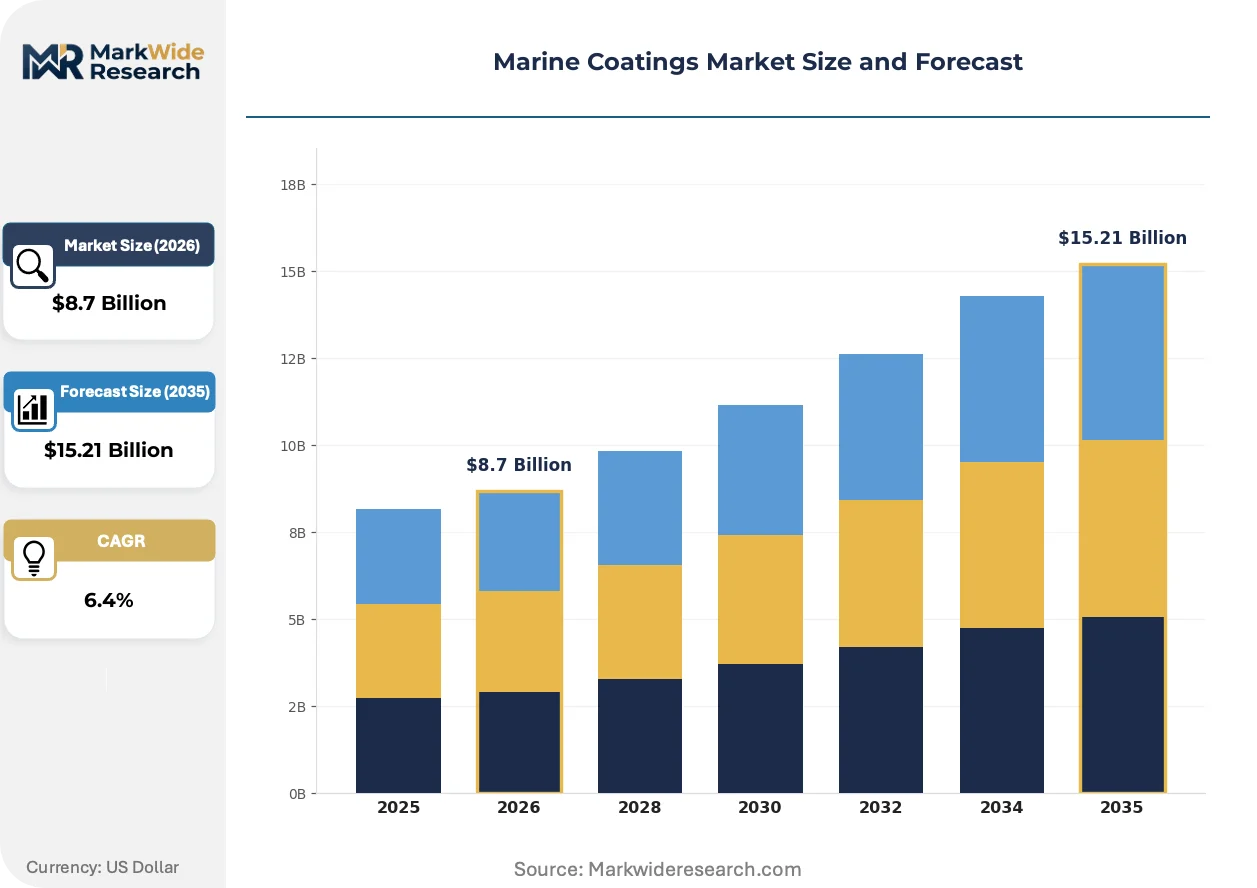
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anti-corrosive, Antifouling, Specialty Coatings, Topcoats Application: Shipbuilding, Offshore Structures, Recreational Vessels, Commercial Vessels Technology: Water-based, Solvent-based, Powder Coating, Hybrid Coatings End User: Naval, Commercial Shipping, Fishing Industry, Pleasure Craft |
| Companies Covered | AkzoNobel N.V., Jotun, PPG Industries Inc., Hempel A/S, The Sherwin-Williams Company, Chugoku Marine Paints Ltd., BASF SE, Kansai Paint Co. Ltd., KCC Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Coatings Market Emerging Trajectories
Coatings technology is bifurcating between high-performance foul-release systems for fuel efficiency and compliant low-biocide formulations for regulatory access, with application methodology and cure chemistry emerging as critical differentiators.
Silicone-polymer foul-release surfaces are absorbing specification share from traditional copper-based antifouling across container and cruise segments where fuel efficiency mandates dominate operating economics. Major operators in Singapore and Rotterdam are mandating these systems for newbuilds, compressing the viable technology set for suppliers without hybrid-platform capabilities. The shift is absorbing R&D budgets that might otherwise flow into incremental biocide improvements, reshaping competitive positioning around polymer science rather than pesticidal chemistry.
REACH Annex XVII amendments on cybutryne and copper oxide are forcing dual-track formulation portfolios for suppliers serving both EU and non-EU flagged fleets. The regulatory divergence is fragmenting product architectures, with coatings sold into American markets following distinct EPA FIFRA registration pathways that emphasize active ingredient toxicity testing over the hazard-based approach favored by ECHA. Container operators with mixed-flag fleets are absorbing compliance complexity through consolidated supplier relationships that bundle regulatory documentation with technical service.
Shipyard procurement is consolidating around integrated coating packages that bundle surface preparation, application, and performance warranties into single-source contracts. Major Korean and Chinese builders are displacing spot-purchase of materials in favor of turnkey solutions where suppliers assume application risk and dry-dock cycle guarantees. This behavioral shift is most visible at Geoje Island facilities, where coatings procurement now flows through yard-level master service agreements rather than owner-direct specifications, compressing supplier margins while locking in volume commitments.
Marine Coatings Market Segmentation
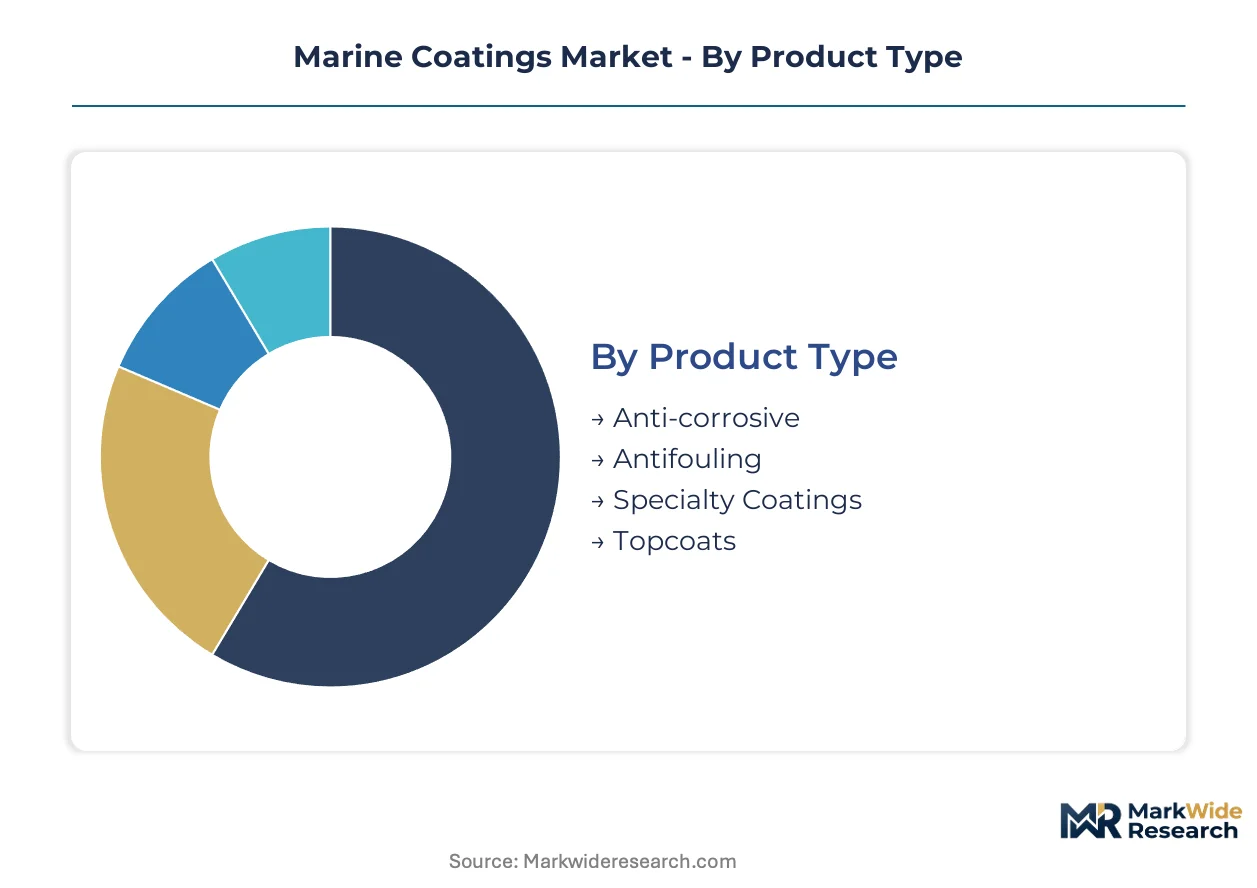
Marine coatings segmentation reflects divergent regulatory burdens across product architectures. Certification pathways under EPA FIFRA, ECHA REACH, and China's GB standards fragment supplier portfolios and reshape procurement criteria for fleet operators.
Product Type:
EPA FIFRA registration dominates antifouling formulations sold into US-flagged fleets, while ECHA REACH Annex XVII compliance governs EU commercial shipping specifications. Anti-corrosive systems face less stringent active-ingredient scrutiny but must meet IMO PSPC performance standards for ballast tank protection.
- Antifouling:Copper-based biocides and silicone-polymer foul-release surfaces prevent biological attachment on submerged hulls. Demand concentrates at South Korean shipyards in Ulsan and Geoje, where fuel-efficiency mandates from major container operators drive specification upgrades. IMO 2023 discharge thresholds are forcing reformulation investments that favor well-capitalized incumbents with parallel EPA and ECHA registration capabilities.
- Anti-corrosive:Epoxy resin and zinc silicate systems protect ballast tanks, cargo holds, and structural steel from saltwater degradation. Procurement runs heaviest at Chinese maintenance yards subject to MEE VOC enforcement, where solvent-based specifications retain dominance despite tightening emission thresholds. Extended dry-dock intervals for aging tanker fleets sustain replacement demand.
- Specialty Coatings:High-performance formulations for splash zones and cryogenic cargo containment.
- Topcoats:Aesthetic and UV-resistant finishes for superstructures and deck equipment.
Leading the category by volume: Anti-corrosive. Expanding most quickly: Specialty Coatings for offshore wind foundations.
Application:
Cost tier stratification separates capital-intensive newbuild specifications from maintenance-driven spot purchases. Shipbuilding contracts bundle coatings into turnkey yard agreements, while offshore structure work demands specialized application expertise.
- Shipbuilding:Newbuild specifications at Korean and Chinese yards integrate surface preparation, application, and performance warranties into single-source contracts. Procurement gravity around Geoje Island facilities has displaced owner-direct purchasing in favor of yard-level master service agreements.
- Offshore Structures:Splash-zone and atmospheric protection for platforms in the North Sea and Gulf of Mexico extends asset lifespans against corrosive environments. Operators compress dry-dock cycles through silicone-hybrid technologies that reduce maintenance frequency.
- Commercial Vessels:Deep-sea fleet maintenance drives antifouling replacement cycles.
- Recreational Vessels:Pleasure craft and yacht applications with premium aesthetic requirements.
Shipbuilding commands the largest absolute spend. Offshore Structures gain share fastest as wind foundation demand emerges.
Technology:
Application methodology and cure chemistry differentiate performance tiers. Water-based formulations penetrate maintenance yards where VOC thresholds tighten, while solvent systems retain specification in heavy-duty corrosion protection.
- Solvent-based:Epoxy and polyurethane systems deliver film integrity and chemical resistance for ballast tanks and cargo holds. Specifications remain dominant at Chinese yards where GB standards on VOC emissions are reshaping procurement toward compliant alternatives.
- Water-based:Low-emission acrylic and epoxy formulations gain traction in shipyard maintenance applications. China's MEE enforcement at major repair facilities is opening specification pathways previously confined to niche European applications.
- Hybrid Coatings:Silicone-polymer systems combining foul-release performance with application efficiency.
- Powder Coating:Thermoset formulations for specialized components and superstructure elements.
Solvent-based technology retains the installed base. Water-based formulations climb the fastest on regulatory tailwinds.
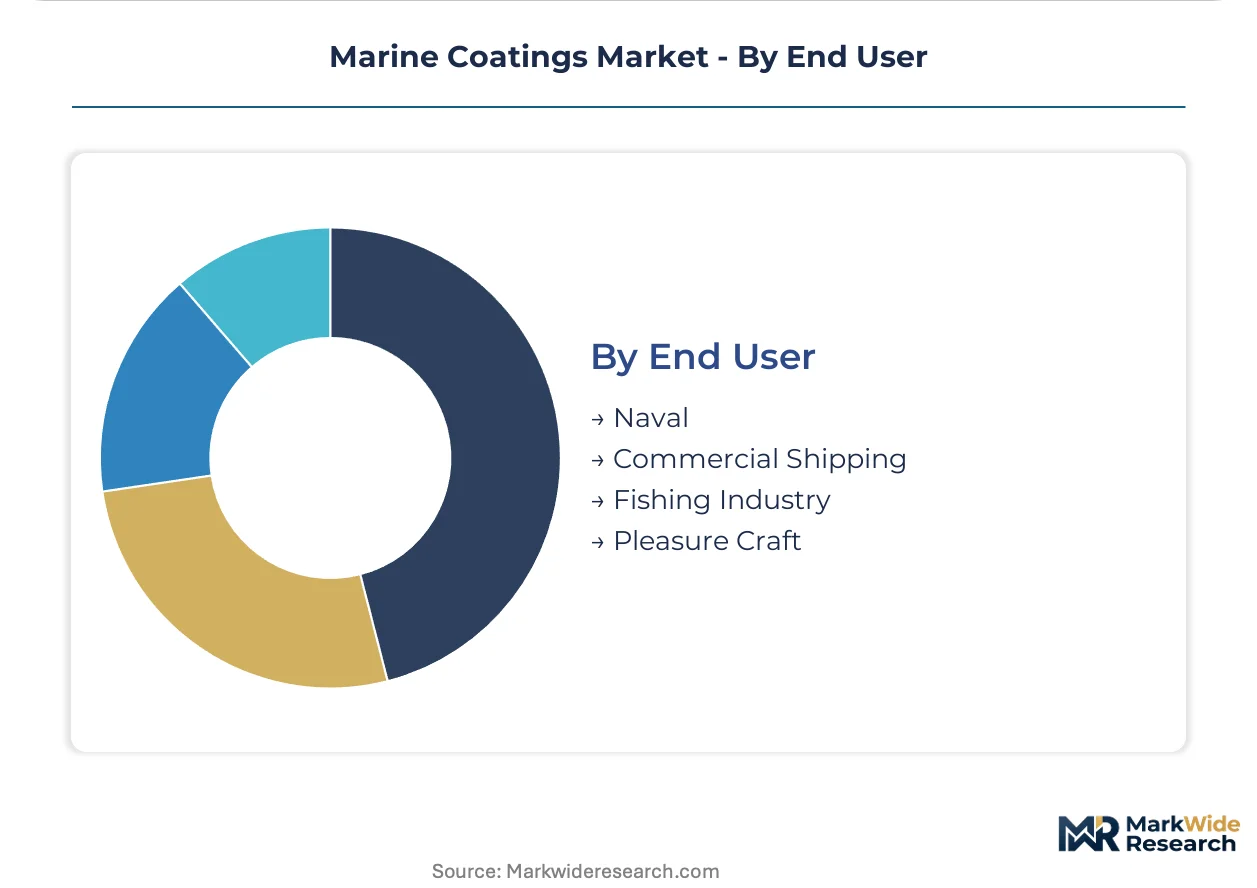
End User:
Customer type determines specification authority and procurement behavior. Naval fleets mandate domestic sourcing and security-cleared application crews, while commercial operators prioritize fuel-efficiency economics.
- Commercial Shipping:Container, tanker, and bulk carrier operators specify coatings based on fuel-efficiency payback calculations. Singapore and Rotterdam port authorities are mandating foul-release systems for newbuilds, compressing viable supplier sets.
- Naval:Military fleets require security-cleared manufacturing and application protocols with domestic content preferences. Specifications emphasize signature reduction and corrosion protection over commercial fuel-efficiency metrics.
- Fishing Industry:Cost-sensitive fleet operators with compressed maintenance budgets.
- Pleasure Craft:Yacht and recreational boat owners with premium aesthetic and performance demands.
Commercial Shipping dominates procurement volume. Naval represents the highest-margin segment on security and certification barriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shipbuilding procurement concentrates at Asian yards where fuel-efficiency mandates and regulatory divergence create differentiated specification demands across flag states.
South Korea
Container newbuilds at Geoje Island and Ulsan drive antifouling specification upgrades as major operators mandate silicone-hybrid foul-release systems. The Ministry of Trade, Industry and Energy supports green shipbuilding initiatives through technology development grants. Korean yards now bundle coatings into turnkey master service agreements that displace owner-direct purchasing.
China
Maintenance yard activity at Zhoushan and Guangzhou sustains anti-corrosive replacement demand for aging tanker fleets. The Ministry of Ecology and Environment enforces GB standards on VOC emissions, reshaping procurement toward water-based formulations at major repair facilities. Domestic shipbuilders face tightening environmental compliance while scaling output.
United States
Offshore structure maintenance in the Gulf of Mexico extends platform lifespans through high-performance protective coatings. The EPA regulates antifouling active ingredients through FIFRA pesticide registration, creating distinct compliance pathways from EU hazard-based approaches. Houston anchors technical service operations for suppliers serving deepwater operators.
Germany
Container fleet operators at Hamburg and Bremerhaven specify compliant coatings for EU-flagged vessels under tightening biocide restrictions. ECHA REACH Annex XVII amendments on copper oxide and cybutryne force certification of biocide-free alternatives. German yards specialize in cruise ship newbuilds with premium aesthetic and performance requirements.
Japan
Domestic shipbuilding at Nagasaki and Kure maintains demand for advanced foul-release technologies on LNG carriers and bulkers. METI promotes maritime decarbonization through fuel-efficiency standards that accelerate coating specification upgrades. Japanese suppliers leverage polymer science capabilities developed in adjacent electronics materials sectors.
Marine Coatings Market Vendor Landscape
European producers anchor the premium formulation tier; Asian specialists hold volume positions in shipyard-direct supply. The vendor base concentrates around well-capitalized incumbents capable of absorbing multi-year R&D cycles for regulatory compliance. Three archetypes dominate: integrated coating-applicators with turnkey service capabilities, polymer science specialists with silicone-hybrid platforms, and regional suppliers with yard-level relationships. Consolidation proceeds through yard-level master service agreements and technology licensing for biocide-free alternatives.
Among Netherlands-based multinationals, AkzoNobel N.V. exemplifies the integrated premium archetype with established foul-release product architectures. Norwegian specialist Jotun occupies a parallel position in antifouling systems deployment at major Asian yards. Danish producer Hempel A/S represents the silicone-hybrid technology vector with extended dry-dock interval offerings for container operators.
| Leading Market Players |
|---|
| AkzoNobel N.V. |
| Jotun |
| PPG Industries Inc. |
| Hempel A/S |
| The Sherwin-Williams Company |
| Chugoku Marine Paints Ltd. |
| BASF SE |
| Kansai Paint Co. Ltd. |
| KCC Corporation |
| Others |
Supply Flow & Price Mechanics
Korean and Chinese shipyard operators concentrate procurement authority through master service agreements, compressing supplier margins while shifting pricing power toward bundled turnkey solutions. This buyer consolidation forces coatings suppliers to absorb application risk and dry-dock cycle guarantees in exchange for volume commitments.
Pricing Analysis
Short lead-time premiums dominate contract structures at Geoje Island and Ulsan facilities, where accelerated vessel turnaround demands command price escalation. Three-tier pricing structure across premium silicone-hybrid, standard copper-based biocide, and economy anti-corrosive tiers separates performance guarantees. Cost compression in solvent-based ballast tank specifications intensifies due to epoxy resin feedstock volatility. Small regional suppliers serving fishing fleets exhibit highest price sensitivity; container operators with fuel-efficiency mandates show lowest.
Supply Chain Analysis
Formulation chemist scarcity in Denmark, Norway, and the Netherlands constrains capacity expansion for silicone-polymer hybrid systems. Manufacturing draws from epoxy resin, zinc silicate, and copper oxide feedstocks anchored in petrochemical complexes. Single-source vulnerability runs through South Korean shipyard clusters at Ulsan and Geoje. Distribution runs through yard-level technical service partnerships rather than owner-direct channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Marine coatings competition has become a vertical-integration race, with incumbents pursuing backward integration into biocide-free active ingredient supply and forward integration into shipyard application services.
For Market Incumbents: Hedge against regulatory divergence by maintaining parallel EPA FIFRA and ECHA REACH registration capabilities. Secure captive supply of silicone-polymer precursors to defend formulation margins against specialty chemical feedstock volatility. Deepen technical service presence at Zhoushan and Guangzhou maintenance yards to offset Korean shipyard procurement consolidation. For New Entrants and Emerging Players: Silicone-hybrid technology platforms offer the most penetrable wedge for specialty offshore wind foundation coatings, where performance requirements differ from marine vessel specifications and incumbent saturation remains limited. Target China's MEE-compliant maintenance yards with water-based formulation capabilities that established suppliers have underdeveloped. Pursue licensing partnerships with Japanese polymer science specialists to accelerate technology credibility. For Investors and Strategic Acquirers: The window for entry favors mid-cap suppliers with biocide-free certification pipelines and established Asian shipyard relationships. Long-term viability hinges on regulatory compliance capabilities spanning multiple jurisdictions rather than single-market dominance. Watch for IMO amendments tightening discharge thresholds as the inflection indicator for consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Biocide-Free Actives | Captive supply of compliant ingredients insulates against ECHA REACH Annex XVII restriction impacts. |
| Shipyard Technical Service Expansion | Localized application crews at Korean and Chinese facilities secure procurement access under master service agreements. |
| Silicone-Polymer R&D Partnership | Collaboration with Japanese electronics materials specialists accelerates foul-release technology development timelines. |
| Offshore Wind Foundation Certification | Splash-zone protection credentials open adjacent demand from North Sea and Gulf of Mexico wind developers. |
| Dual-Track Regulatory Registration | Parallel EPA FIFRA and ECHA REACH capabilities enable specification access across US-flagged and EU-flagged fleets. |
Methodological Framework
Multi-period observation of fleet renewal schedules, dry-dock interval compression, and regulatory amendment timelines anchored the trend analysis, supplemented by interviews with shipyard procurement managers, coatings formulation chemists, marine classification society surveyors, and offshore platform maintenance directors. Secondary validation drew from IMO convention documentation, EPA FIFRA registration databases, ECHA REACH restriction proposals, and Korean shipbuilding association output statistics. Bottom-up vessel count and coating consumption estimates triangulated against top-down market value assessments.
Input-output matrices modeled coating demand across product type, application, technology, and end user dimensions over the projection horizon. CAGRs derived from segment-level volume trajectories and value-per-unit assumptions indexed to raw material cost movements. Industry-specific forecast inputs included offshore wind foundation installation pipelines and IMO environmental regulation implementation schedules.
Several conditions sit outside the modeled scope, including geopolitical disruption of Asian shipbuilding output, breakthrough biocide resistance in target fouling organisms, and abrupt feedstock cost shocks beyond historical volatility bands. Forecasts reflect assumptions about regulatory implementation timelines and fleet operator compliance behavior. Material deviation in IMO amendment adoption rates or shipyard consolidation patterns warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Fire Retardant Coatings Market
Coatings
Asia-Pacific Epoxy Powder Coatings Market
Coatings
Corrosion Protection Polymer Coating Market
Coatings
Anti-Microbial Coatings Market
Coatings
Perfluoroalkoxy (PFA) Coatings Market
Coatings
Graphene Coatings Market
Coatings
High Temperature Coatings Market
Coatings
Asia-Pacific Superhydrophobic Coating Market
Coatings
In-Mold Coatings Market
Coatings
Hydrophilic Coatings Market
Coatings
Global Performance Coating Market
Coatings
Soft Touch Polyurethane Coatings Market
Coatings
Global Low Temperature Powder Coatings Market
Coatings
Stain Resistant Coatings Market
Coatings
Packaging Coatings Market
Coatings
Camouflage Coatings Market