
 ASEAN Paints and Coatings Market | 2026-2036
ASEAN Paints and Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
ASEAN Paints and Coatings Market Outlook
Buyer concentration among ASEAN construction firms is restructuring as mega-project developers consolidate procurement while smaller contractors fragment across provincial markets. Akzo Nobel N.V. leverages its regional distribution network to serve these diverging buyer tiers. Hempel A/S anchors its position through marine coating specialization across Southeast Asian shipyards. PPG Industries, Inc. competes by sustaining R&D intensity in automotive OEM supply chains.
Paints and coatings are liquid, powder, or UV-curable film-forming materials composed of binders, pigments, solvents or water carriers, and functional additives, applied to substrates to provide protection, decoration, or specialized surface properties. Architectural coatings command the largest volume share as urban residential and commercial building stock expands across Jakarta, Bangkok, and Ho Chi Minh City. Waterborne technology leads growth due to regulatory pressure on solventborne emissions, while powder coatings occupy the industrial machinery segment where durability requirements dominate specification decisions. Protective coatings carry the deepest margin pools given their performance-critical role in infrastructure and energy installations.
Indonesia's green building regulations, Thailand's VOC emission standards under its Pollution Control Department, and Vietnam's chemical safety decrees are collectively elevating product compliance costs and reshaping formulation roadmaps. The report notes that manufacturers must navigate this multi-jurisdictional compliance map to maintain market access across ASEAN member states. Stakeholders should monitor how national implementation timelines for these frameworks diverge and where local testing certification creates bottleneck risks for imported formulations.
Market Dynamics
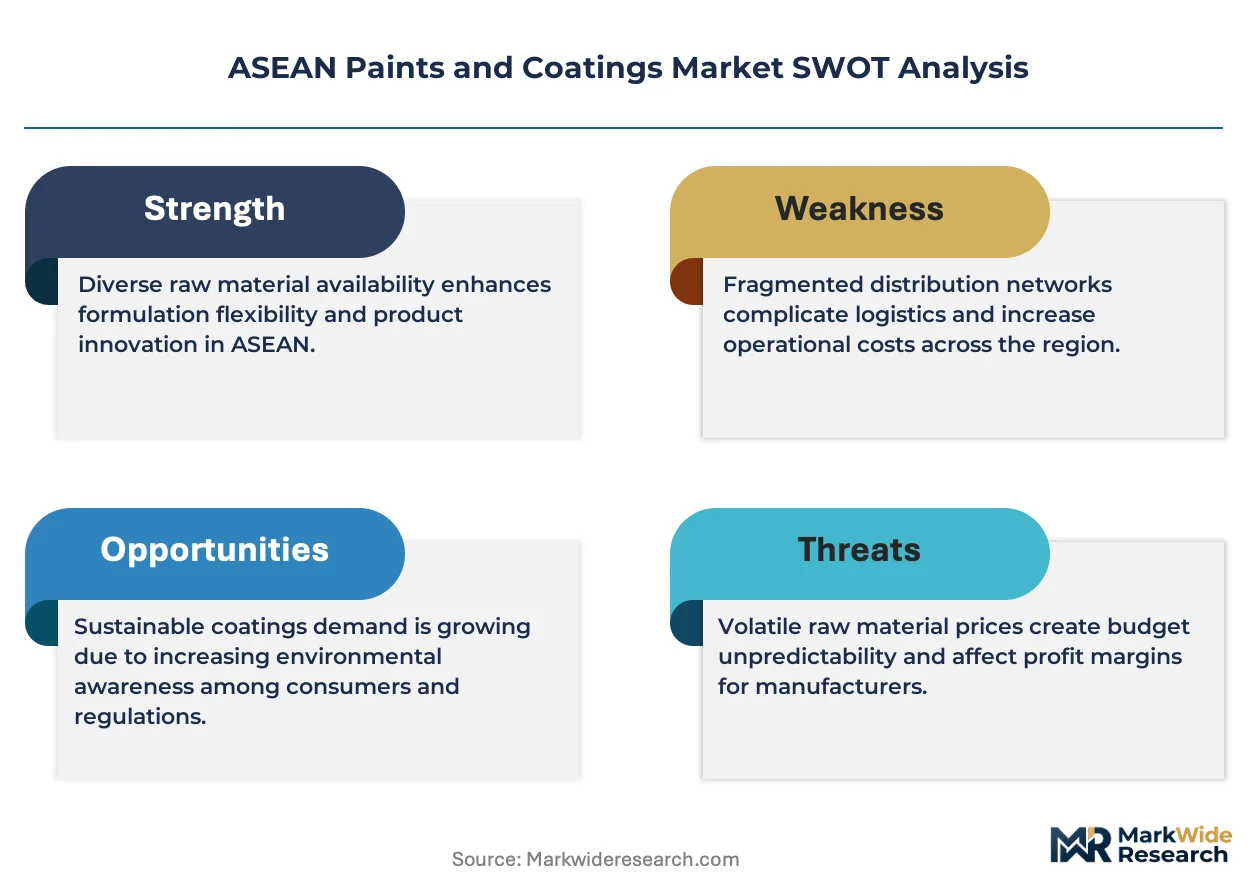
Waterborne formulation conversion is compressing solventborne capacity across Southeast Asian manufacturing bases as Indonesia's green building code and Thailand's Pollution Control Department standards harden compliance thresholds.
Growth Catalysts
- Indonesia's Green Building Council certification:Mandatory energy-efficiency ratings for commercial structures are redirecting specification toward low-emission architectural coatings. Jakarta's commercial developers now embed VOC limits into tender documents.
- Marine dry-docking cycles:Vietnam's shipyard expansion along the Cai Mep-Thi Vai corridor is generating protective coating demand for vessel maintenance. Shipowners are consolidating supplier relationships to secure application-window availability.
- Waterborne resin technology:Acrylic and polyurethane dispersions are achieving parity with solventborne durability in tropical humidity conditions. Thai and Malaysian formulators are retooling production lines to capture this specification shift.
Market Restraints
- Titanium dioxide feedstock concentration:Chinese sulfate-process pigment suppliers control critical raw material flows into ASEAN blending operations. Price volatility in ilmenite ore transmits directly to coating cost structures.
- Solventborne capacity stranding:Indonesian and Thai plants with legacy alkyd production configurations face accelerated obsolescence. Asset write-down pressures are constraining reinvestment cycles for mid-tier manufacturers.
- Multi-jurisdictional testing regimes:Vietnam's chemical safety decrees require separate certification from Indonesian national standards. Cross-border formulation registration creates timeline friction for regional product launches.
Strategic Opportunities
- Philippines provincial construction:Mindanao and Visayas infrastructure programs remain undersupplied by certified coating distributors. Local contractor networks present first-mover positioning for compliance-ready waterborne systems.
- Photovoltaic installation coatings:Anti-reflective and weatherable backsheet films for solar farms are emerging as specification categories. Thai and Vietnamese renewable energy procurement is driving pilot adoption.
- Digital color-matching platforms:Cloud-based spectrophotometry tools are enabling remote specification for dispersed Indonesian archipelago projects. Hardware-software bundles create stickiness with provincial applicator networks.
Industry Challenges
- Applicator skill standardization:Waterborne film formation requires modified spray technique and environmental control. Training certification gaps in Vietnam's informal construction labor pool generate defect liability exposure.
- Legacy inventory absorption:Distributors hold solventborne stocks that conflict with tightening Thailand VOC limits. Channel write-off negotiations are straining manufacturer-distributor credit terms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ASEAN Paints and Coatings Market |
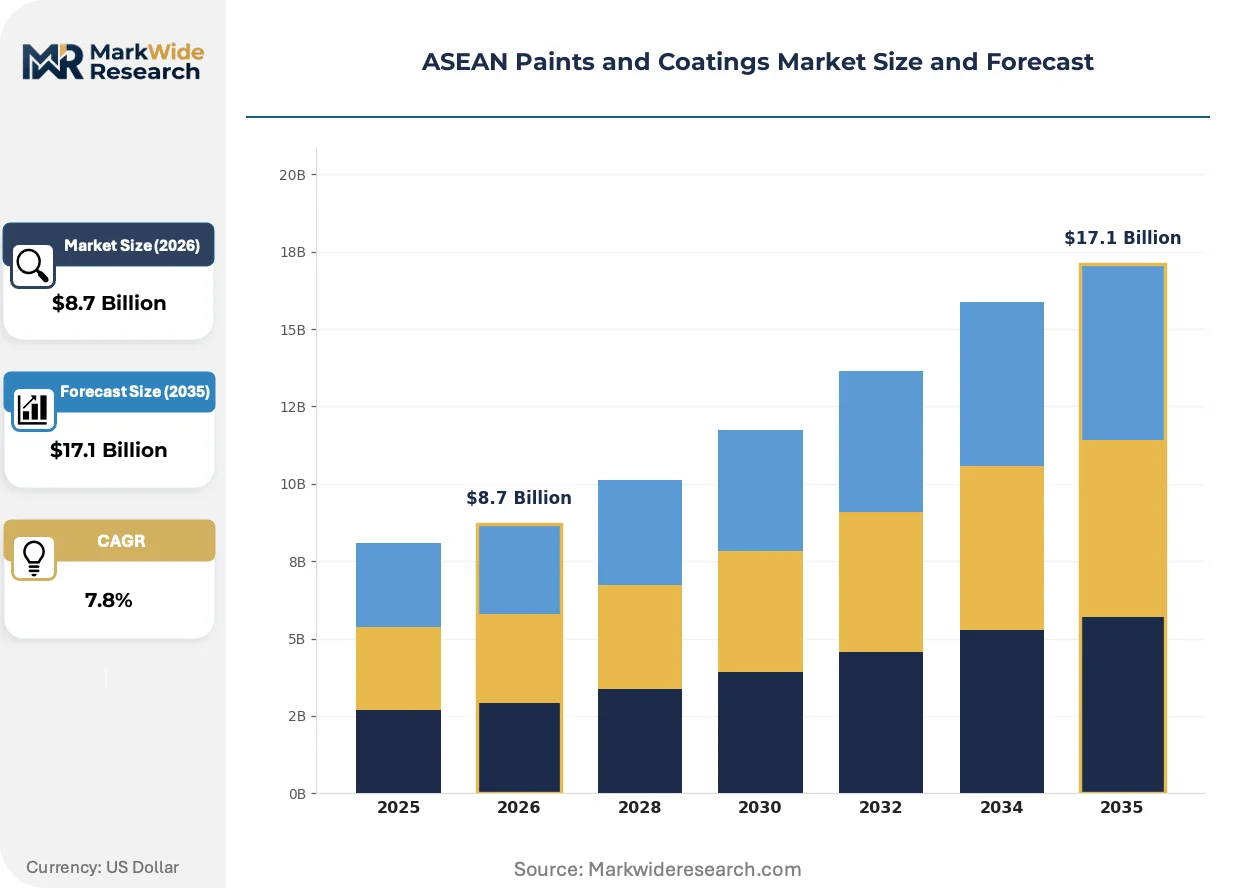
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.1 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Architectural Coatings, Industrial Coatings, Automotive Coatings, Protective Coatings, Marine Coatings Technology: Waterborne, Solventborne, Powder Coatings, UV Curable, Radiation Curing Application: Commercial Buildings, Infrastructure Projects, Vehicle Manufacturing, Shipbuilding, Machinery Equipment End User: Construction Firms, Transportation OEMs, Heavy Equipment Makers, Energy Installers, Metal Fabricators |
| Companies Covered | Akzo Nobel N.V., Hempel A/S, Nippon Paint Holdings Co., Ltd., PPG Industries, Inc., Jotun A/S, Kansai Paint Co., Ltd., The Sherwin-Williams Company, Avian Brands, Asian Paints Limited, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ASEAN Paints and Coatings Market Strategic Shifts
Digital specification tools and bio-based binder chemistry are restructuring how coatings are selected, formulated, and applied across Southeast Asian project sites.
Self-healing polymer networks are converging with infrastructure protective coating specifications. Bridge and pipeline operators in Indonesia and Malaysia are piloting microcapsule-based systems that autonomously seal mechanical damage. This capability is compressing maintenance-cycle frequency and shifting warranty negotiation leverage toward applicators with certified installation protocols.
Thailand's Pollution Control Department is tightening VOC emission thresholds for architectural and industrial maintenance categories. Manufacturers must reformulate alkyd and epoxy systems or surrender market access. Indonesian formulators are accelerating waterborne acrylic development to preempt similar regulatory alignment.
Consolidated procurement by mega-project developers is fragmenting distributor influence across ASEAN construction supply chains. Bangkok and Jakarta-based contractors now negotiate direct supply agreements with manufacturers, bypassing traditional channel intermediaries. This disintermediation is most visible in Vietnam's industrial corridor where foreign-invested manufacturing facilities specify globally consistent coating systems.
ASEAN Paints and Coatings Market Segmentation
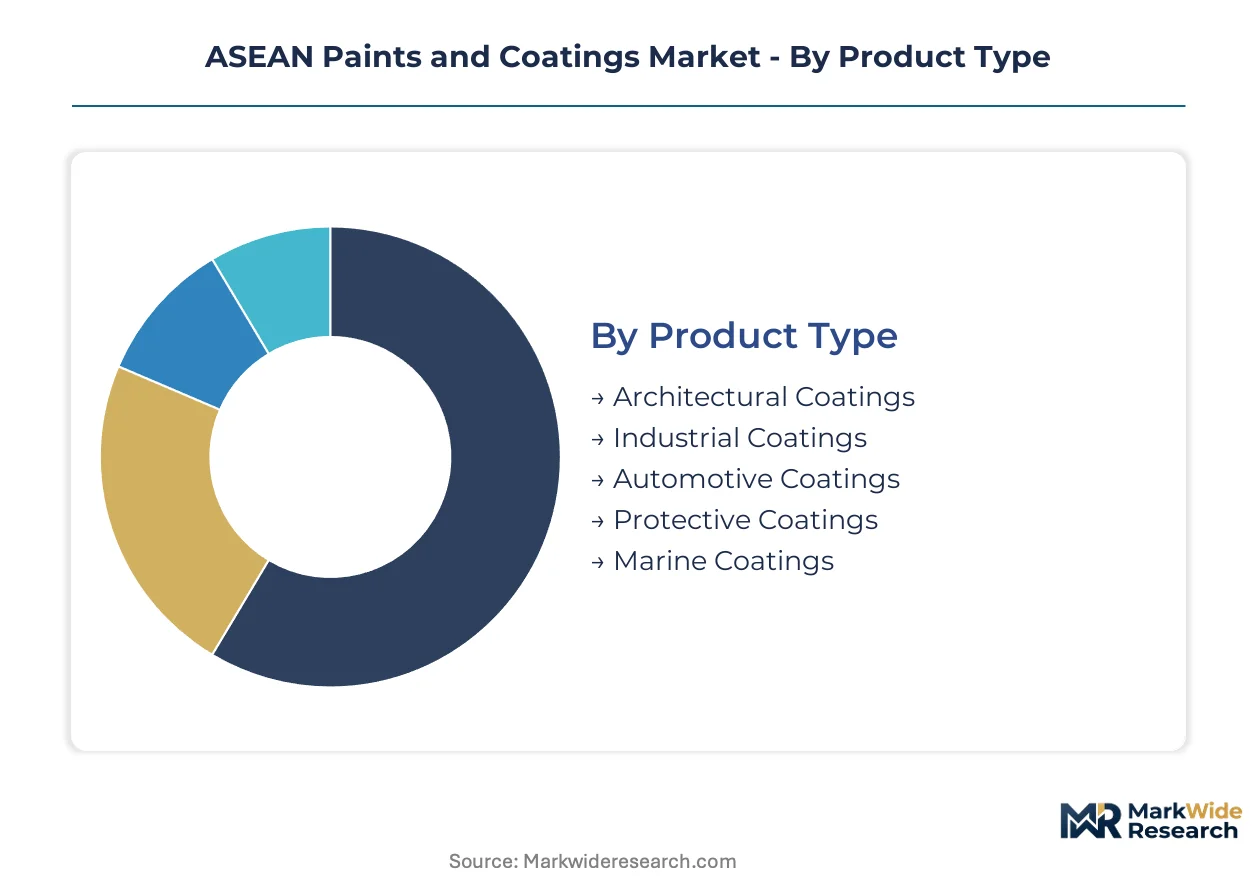
Segmentation across ASEAN's paints and coatings market reveals how specification requirements diverge between urban construction corridors and industrial manufacturing zones. Technology choices and end-user procurement patterns are reshaping competitive positioning as regulatory frameworks harden compliance thresholds across member states.
Product Type:
Waterborne resin chemistry and VOC compliance specifications are redefining performance benchmarks across product categories.
- Architectural Coatings:Waterborne acrylic and latex systems dominate residential and commercial building applications across Jakarta, Bangkok, and Ho Chi Minh City. Indonesia's green building code and Thailand's Pollution Control Department standards are embedding low-emission requirements into tender specifications for new commercial developments.
- Protective Coatings:Epoxy and polyurethane systems provide corrosion protection for infrastructure and energy installations across Vietnam's industrial corridor and Indonesia's urban construction belt. These formulations command premium pricing due to performance-critical roles in extending asset lifecycles.
- Industrial Coatings:Applied to machinery and equipment across Thai and Malaysian manufacturing facilities where durability under tropical humidity conditions drives specification.
- Automotive Coatings:OEM and refinish systems serving vehicle assembly plants in Thailand and Indonesia with color-matching and weatherability requirements.
- Marine Coatings:Anti-corrosive and anti-fouling systems for vessel maintenance across Vietnam's Cai Mep-Thi Vai shipyard corridor and Indonesian port facilities.
Architectural coatings lead on scale; protective coatings lead on momentum as infrastructure investment accelerates across Southeast Asia.
Technology:
Formulation platforms are diverging based on emission compliance costs and application efficiency requirements.
- Waterborne:Acrylic and polyurethane dispersions achieving solventborne parity in tropical conditions. Thai and Malaysian formulators are retooling production lines to capture specification shifts driven by Indonesia's green building regulations and Thailand's tightening VOC limits.
- Powder Coatings:Solvent-free application for industrial machinery and metal fabrication where film thickness and durability specifications dominate. Energy curing efficiency supports adoption across ASEAN manufacturing export zones.
- Solventborne:Legacy alkyd and epoxy systems facing accelerated obsolescence as regulatory thresholds harden; capacity stranding risks concentrate in Indonesian and Thai plants with dated production configurations.
- UV Curable:Rapid-cure systems for wood coatings and specialty applications where production throughput requirements justify capital investment in curing equipment.
- Radiation Curing:Electron beam and UV-initiated polymerization for high-performance industrial finishes requiring immediate handling properties.
Waterborne technology leads on scale; powder coatings lead on momentum as industrial machinery demand expands.
Application:
End-use environments are fragmenting specification requirements across building, transportation, and industrial asset classes.
- Commercial Buildings:Interior and exterior architectural finishes across Jakarta, Bangkok, and Ho Chi Minh City commercial developments where aesthetic durability and emission compliance converge in specification decisions.
- Infrastructure Projects:Bridge, pipeline, and public works protective systems across Indonesia and Vietnam where maintenance-cycle compression drives performance requirements.
- Vehicle Manufacturing:OEM coating lines for Thai and Indonesian automotive assembly plants requiring color consistency and chip resistance.
- Shipbuilding:New construction and maintenance coatings for Vietnamese and Indonesian shipyards where dry-docking cycles generate recurring demand.
- Machinery Equipment:Industrial finishes for metal fabrication and heavy equipment production across ASEAN manufacturing hubs.
Commercial buildings lead on scale; infrastructure projects lead on momentum as public investment programs accelerate.
End User:
Procurement consolidation among large developers is fragmenting distributor influence across buyer tiers.
- Construction Firms:Mega-project developers in Bangkok and Jakarta negotiate direct supply agreements, bypassing traditional channel intermediaries, while provincial contractors fragment across undersupplied markets in the Philippines and Indonesia's outer islands.
- Transportation OEMs:Automotive and marine manufacturers specifying globally consistent coating systems with certified application protocols.
- Heavy Equipment Makers:Machinery manufacturers in Thai and Vietnamese industrial zones requiring durable finishes for export markets.
- Energy Installers:Solar farm and power infrastructure developers driving emerging demand for weatherable coatings and anti-reflective films.
- Metal Fabricators:Small and mid-tier manufacturers sourcing through distributor networks with limited technical specification support.
Construction firms lead on scale; energy installers lead on momentum as renewable energy procurement expands across Thailand and Vietnam.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled applicator pools cluster around Jakarta, Bangkok, and Ho Chi Minh City, anchoring specification expertise for waterborne systems across the region. These urban centers concentrate certified contractor networks capable of meeting tightening VOC compliance standards.
Indonesia
Jakarta's commercial developers embed VOC limits directly into tender documents, redirecting procurement toward low-emission architectural finishes. The national green building code mandates energy-efficiency ratings for commercial structures. Surabaya's industrial zones and Bandung's manufacturing belt are absorbing waterborne capacity as legacy solventborne plants face obsolescence.
Thailand
Bangkok-based mega-project developers negotiate direct supply agreements, bypassing traditional distributor channels. The Pollution Control Department hardens VOC emission thresholds for architectural and industrial maintenance categories. Rayong's Eastern Economic Corridor automotive assembly plants specify globally consistent coating systems with certified application protocols.
Vietnam
The Cai Mep-Thi Vai shipyard corridor generates protective coating demand from marine dry-docking cycles. Chemical safety decrees require separate certification from Indonesian national standards, creating timeline friction. Ho Chi Minh City's industrial corridor concentrates foreign-invested manufacturing facilities specifying durable finishes for export markets.
Malaysia
Thai and Malaysian formulators retool production lines to capture waterborne specification shifts driven by regional regulatory alignment. The country's port facilities and industrial machinery manufacturers drive powder coating adoption where film thickness requirements dominate. Penang's electronics manufacturing zones and Johor's logistics corridors anchor industrial finish demand.
Philippines
Mindanao and Visayas infrastructure programs remain undersupplied by certified coating distributors, presenting first-mover positioning for compliance-ready waterborne systems. Local contractor networks lack standardized applicator training for modified spray techniques. Cebu and Davao construction markets fragment across provincial buyers with limited technical specification support.
ASEAN Paints and Coatings Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across ASEAN's tiered market structure. The vendor base separates into three strategic archetypes: global formulation leaders with regional distribution networks, marine and protective coating specialists anchoring shipyard relationships, and emerging local players capturing provincial construction fragmentation. Competitive moves concentrate on portfolio diversification into waterborne chemistry and strategic partnerships with mega-project developers seeking direct supply agreements.
Within the global diversified tier, Akzo Nobel N.V. and PPG Industries, Inc. represent multinational formulators with regional manufacturing footprints. Hempel A/S exemplifies the specialist archetype, occupying a position tied to marine and protective applications. Asian Paints Limited anchors the emerging market expansion vector, sitting within a broader competitive set targeting provincial distributor gaps across Indonesia's outer islands and Philippine secondary cities.
| Leading Market Players |
|---|
| Akzo Nobel N.V. |
| Hempel A/S |
| Nippon Paint Holdings Co., Ltd. |
| PPG Industries, Inc. |
| Jotun A/S |
| Kansai Paint Co., Ltd. |
| The Sherwin-Williams Company |
| Avian Brands |
| Asian Paints Limited |
| Others |
Value Chain & Pricing Dynamics
Waterborne formulation conversion across Thai and Malaysian production lines simultaneously compresses unit production costs and concentrates supply capability among certified formulators. This technology transition rewards early movers with procurement leverage while stranding legacy solventborne capacity.
Pricing Analysis
Bundled application-service packages command premiums over unbundled product-only transactions, particularly in Vietnam's marine dry-docking corridor where certified contractor availability constrains project scheduling. Three-tier pricing structure across premium performance, standard compliance, and economy-grade tiers reflects certification grade and volume scale differentiation. Cost compression in economy-grade architectural coatings is intensifying because Chinese titanium dioxide suppliers transmit ilmenite ore volatility directly into ASEAN blending operations. Provincial contractors in Mindanao and Visayas exhibit highest price sensitivity, while Bangkok and Jakarta mega-project developers prioritize specification compliance over unit cost.
Supply Chain Analysis
Certification gating under Indonesia's green building code and Thailand's Pollution Control Department standards restricts supply eligibility to formulators with validated testing documentation. Geographic concentration centers on Thailand, Malaysia, and Vietnam as primary manufacturing hubs, with raw material dependencies spanning Chinese sulfate-process titanium dioxide, Singaporean petrochemical solvents, and Japanese specialty additives. Single-source vulnerability concentrates in Chinese pigment feedstock flows. Distribution runs through Jakarta, Bangkok, and Ho Chi Minh City-based distributor networks serving tiered contractor segments, with direct supply agreements increasingly bypassing traditional channel intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion trajectories favor manufacturers capturing waterborne specification premiums while legacy solventborne competitors absorb asset write-downs. Thai and Vietnamese formulators with retooled production lines command procurement leverage as compliance thresholds harden.
For Market Incumbents: Anchor defensive positioning through backward integration into waterborne resin production and captive supply of acrylic dispersions. Secure certification investment under Vietnam's chemical safety decrees and Indonesia's green building standards to maintain market access. Defend against emerging local players by locking direct supply agreements with Bangkok and Jakarta mega-project developers, constraining distributor channel fragmentation.
For New Entrants and Emerging Players: Digital color-matching platforms offer technology-first entry into Indonesia's undersupplied outer islands where cloud-based spectrophotometry tools enable remote specification. Target Philippine provincial construction in Mindanao and Visayas, where certified coating distributors remain scarce and local contractor networks lack technical specification support. Pursue hardware-software bundle go-to-market positioning to create applicator network stickiness.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier solventborne manufacturers facing accelerated obsolescence from Thai and Indonesian regulatory alignment. Long-term viability favors waterborne-capable formulators with established mega-project developer relationships. Monitor Indonesia's national green building code implementation timeline as inflection indicator for specification shift velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Waterborne Resins | Captive acrylic dispersion supply secures margin control against Chinese feedstock volatility. |
| Certification Investment under Multi-Jurisdictional Standards | Parallel Indonesia green building and Thailand Pollution Control Department registration accelerates market access. |
| Direct Supply Agreement with Mega-Project Developers | Bangkok and Jakarta contractor consolidation enables bypass of traditional distributor intermediaries. |
| Digital Color-Matching Platform Deployment | Cloud-based spectrophotometry bundles create stickiness across Indonesia's dispersed archipelago projects. |
| Photovoltaic Installation Coating Development | Anti-reflective film specification for Thai and Vietnamese solar farms opens renewable energy procurement channels. |
Study Parameters
Bottom-up construction sector modeling reconciled against top-down chemical manufacturing tracking forms the analytical core of this study. Primary interviews with plant managers at Thai and Malaysian formulators, procurement leads at Jakarta commercial developers, marine coating specification engineers across Vietnam's Cai Mep-Thi Vai corridor, and distributor channel partners in Philippine secondary cities combined with secondary validation from customs/trade data, ASEAN chemical industry association reports, and national regulatory filings. This approach triangulates demand-side project pipelines with supply-side capacity configurations.
Historical trendline analysis of waterborne technology penetration rates, VOC regulatory implementation timelines, and marine dry-docking cycle patterns established baseline trajectories. The forecast framework models segmentation across product type, technology platform, application environment, and end-user procurement tier, with CAGRs derived from regression analysis of specification shift velocity and capacity conversion rates. Industry-specific inputs include Indonesian green building code adoption curves and Thai Pollution Control Department enforcement intensity assumptions.
The model holds under stable regulatory implementation schedules; deviation in Indonesia's green building certification timeline or Thai VOC threshold acceleration would shift waterborne adoption trajectories. Forecasts reflect assumptions regarding applicator training certification expansion and titanium dioxide supply continuity. A model refresh is warranted upon material change in Chinese pigment export policy or ASEAN member state regulatory alignment pace.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Polyurethane Resins Paints and Coatings Market
Paints & Coatings
GCC Paints and Coatings Market
Paints & Coatings
Nigeria Paint and Protective Coatings Market
Paints & Coatings
Asia-Pacific Paints and Coatings Market
Paints & Coatings
Anti-Fungal and Anti-Bacterial Paints Market
Paints & Coatings
Automotive Coatings Market
Paints & Coatings
Automotive Paints Market
Paints & Coatings
Global Texture Paint Market
Paints & Coatings
Bahrain Paints and Coatings Market
Paints & Coatings
South America Paints and Coatings Market
Paints & Coatings
Paint Sprayer Market
Paints & Coatings
Paints and Coatings Market
Paints & Coatings
Saudi Arabia Architectural Paints Market
Paints & Coatings
Automotive Paints and Coatings Market
Paints & Coatings
Faux Paints and Coatings Market
Paints & Coatings
Mexico Paints and Coatings Market