
 Medical Virtual Reality Operating Systems Market | 2026-2036
Medical Virtual Reality Operating Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Virtual Reality Operating Systems Market Insights
Platform licensing revenue is reconfiguring margin pools away from perpetual software sales toward recurring subscription models in medical VR operating systems. Microsoft Corporation leverages its Azure cloud infrastructure to anchor hospital deployments with hybrid deployment architectures. Meta Platforms, Inc. competes through specialized hardware-software integration for surgical visualization. Siemens Healthineers AG sustains R&D intensity in orthopedics-focused VR modules for preoperative planning.
Medical Virtual Reality Operating Systems comprise software platforms, specialized headsets, haptic peripherals, and integration middleware designed to render immersive three-dimensional anatomical environments with sub-20 millisecond latency to prevent simulator sickness. These systems enable preoperative rehearsal, intraoperative navigation overlay, and postoperative rehabilitation through real-time spatial computing. Software segments capture the dominant margin pool due to recurring license economics, while hardware faces commoditization pressure from consumer VR headset manufacturers. Integration Services segments are expanding fastest as hospitals demand turnkey deployment of cloud-based systems linking electronic health records with immersive surgical planning environments. Support Services remain mature with established vendors competing on response time guarantees rather than technical differentiation.
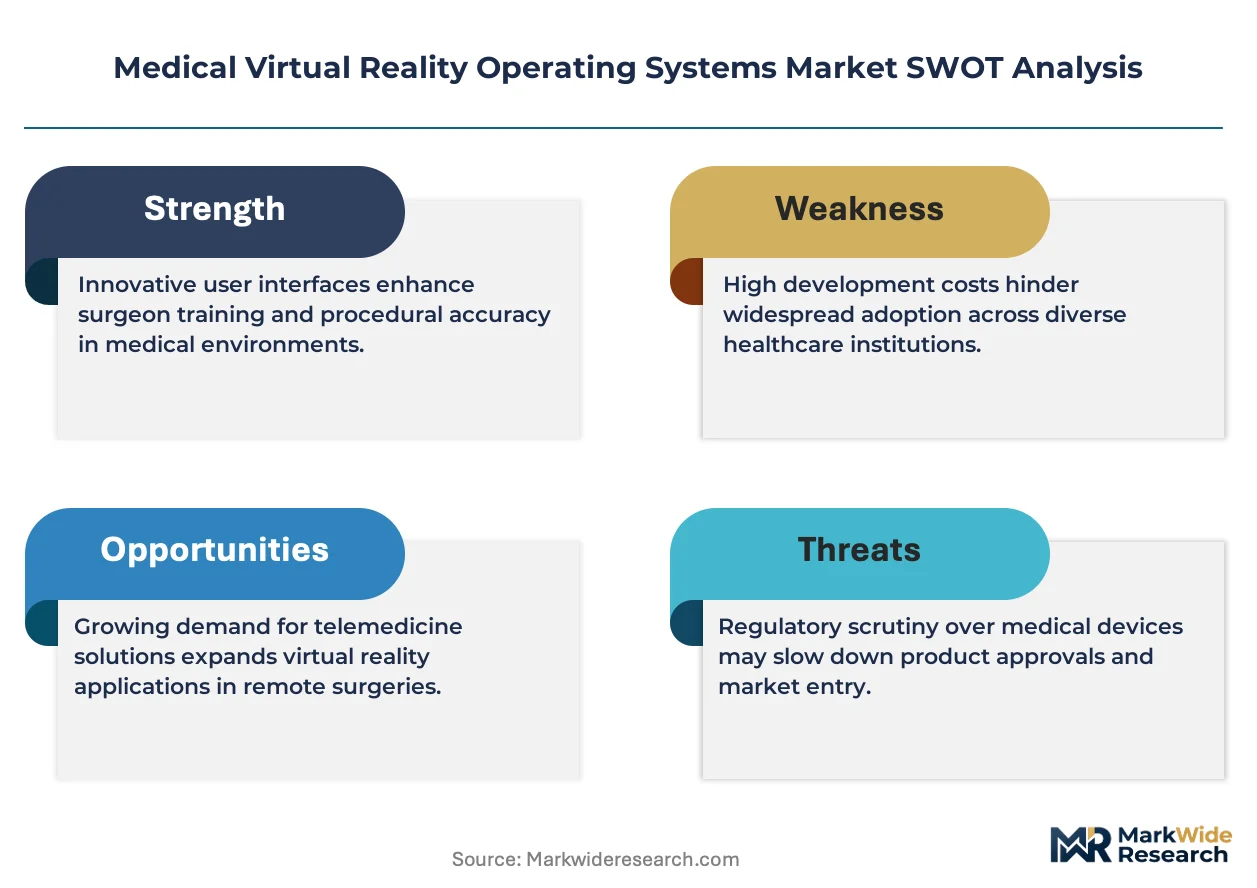
FDA regulates these systems as medical device software under 21 CFR Part 820 quality system requirements, while HIPAA mandates encryption standards for patient data rendered in immersive environments. The EU AI Act introduces risk classification obligations for autonomous surgical guidance algorithms deployed through VR platforms. Stakeholders must monitor evolving cybersecurity frameworks as cloud-based deployment expands the attack surface for patient data breaches in immersive clinical settings.
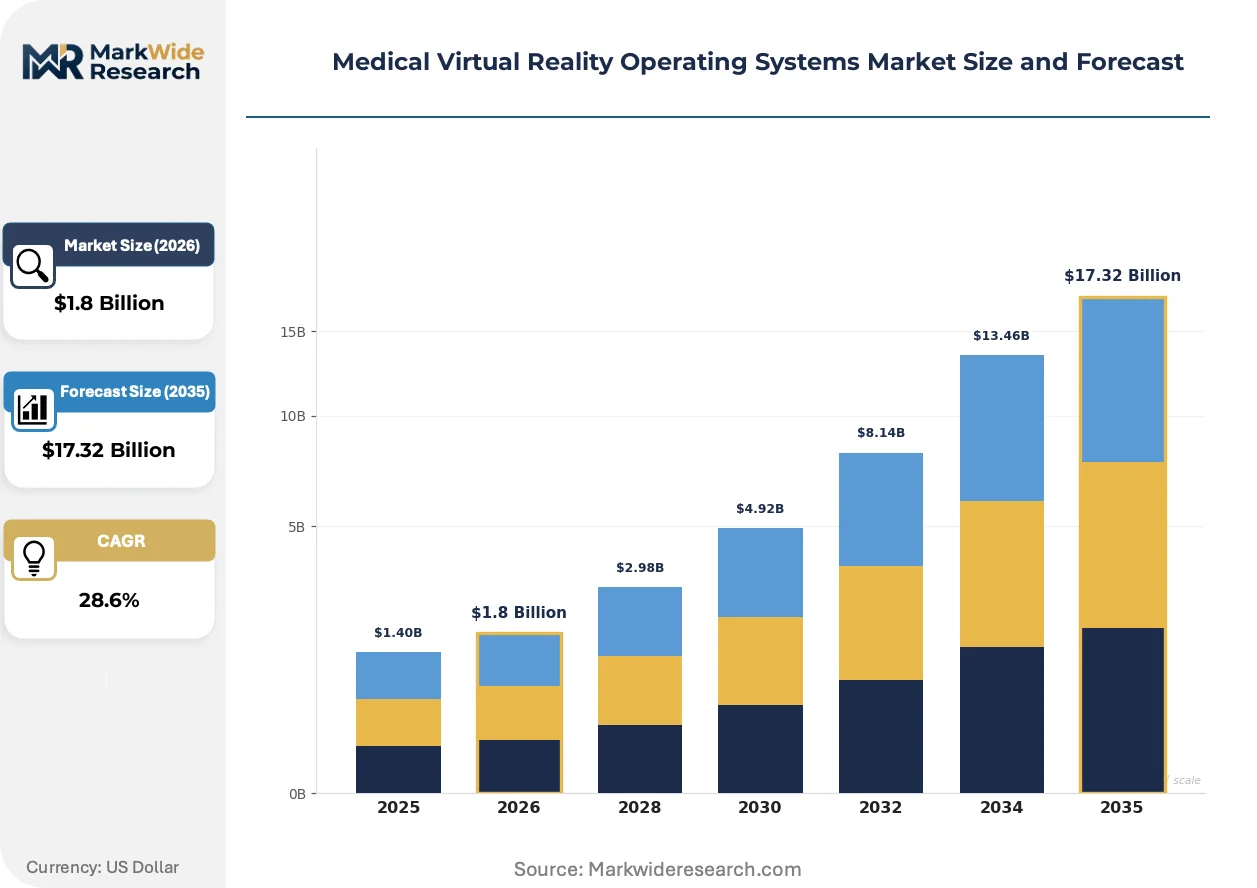
Market Dynamics
Platform licensing economics are reconfiguring margin pools away from perpetual software sales toward recurring subscription models, while FDA 21 CFR Part 820 compliance requirements compress commercialization timelines for new entrants.
Growth Catalysts
- FDA 510(k) Pathway Streamlining:Accelerated clearance protocols for VR surgical planning tools reduce time-to-market for software modules, enabling faster hospital procurement cycles.
- Academic Medical Center Expansion:Surgical training programs at university-affiliated hospitals are mandating immersive simulation hours, creating institutional demand pull.
- Cloud-Hybrid Deployment Architectures:Microsoft Azure infrastructure integration allows seamless electronic health record connectivity, lowering IT friction for hospital adoption.
Market Restraints
- Specialized Hardware Cost Structure:Haptic peripherals and sub-20 millisecond latency headsets carry premium input costs that strain capital budgets at mid-tier hospitals.
- Consumer VR Commoditization Pressure:Meta Platforms and consumer headset manufacturers are eroding hardware margins through volume-scale production economics.
- EU AI Act Risk Classification:Autonomous surgical guidance algorithms face elevated compliance burdens under emerging European artificial intelligence liability frameworks.
Strategic Opportunities
- Postoperative Rehabilitation Applications:Pain management and physical therapy modules represent underdeveloped use cases with direct-to-patient revenue potential.
- Integration Services White Space:Turnkey deployment of cloud-based systems linking immersive environments with hospital IT infrastructure commands premium pricing.
- German Orthopedic Preoperative Planning:Siemens Healthineers R&D intensity signals regulatory-validated demand for joint replacement visualization tools.
Industry Challenges
- Simulator Sickness Mitigation:Sub-20 millisecond latency engineering requires specialized talent scarce in conventional medical device development pipelines.
- HIPAA Encryption Complexity:Patient data rendered in immersive cloud environments demands cybersecurity architecture beyond standard hospital IT capabilities.
- Legacy EHR Integration Friction:Middleware development for electronic health record connectivity consumes disproportionate implementation resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Virtual Reality Operating Systems Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $17.32 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Hardware, Integration Services, Support Services Therapy Area: Orthopedics, Neurosurgery, Rehabilitation, Pain Management End User: Hospitals, Surgical Centers, Research Institutions, Clinics Deployment: On-Premises, Cloud-Based, Hybrid, Mobile |
| Companies Covered | Microsoft Corporation, Meta Platforms, Inc., Siemens Healthineers AG, Koninklijke Philips N.V., HTC Corporation, Osso VR, Inc., XRHealth Inc., AppliedVR, Inc., Google LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Virtual Reality Operating Systems Market Trends and Innovations
Real-time spatial computing capabilities are compressing the boundary between preoperative rehearsal and intraoperative navigation, forcing platform vendors to unify software architectures across clinical workflow stages.
Pass-through mixed reality visualization is rendering obsolete conventional monitor-based surgical navigation systems. Academic medical centers in the United States are adopting these overlays for complex spinal procedures within eighteen-month procurement cycles. The structural consequence is collapsing hardware categories into unified headset platforms.
EU AI Act risk-tier classification obligations are reshaping algorithm deployment strategies for autonomous guidance features. Vendors must now maintain technical documentation and human oversight protocols for surgical decision-support modules. European orthopedic applications face the steepest compliance ramp, with Swissmedic and BfArM interpreting enforcement thresholds variably.
Hospital procurement committees are unbundling after-sales service contracts from initial platform licensing, compressing vendor recurring revenue predictability. Third-party IT integrators are capturing implementation and training margins previously retained by original equipment manufacturers. This pattern concentrates in United States hospital systems with dedicated digital health procurement functions.
Medical Virtual Reality Operating Systems Market Segmentation
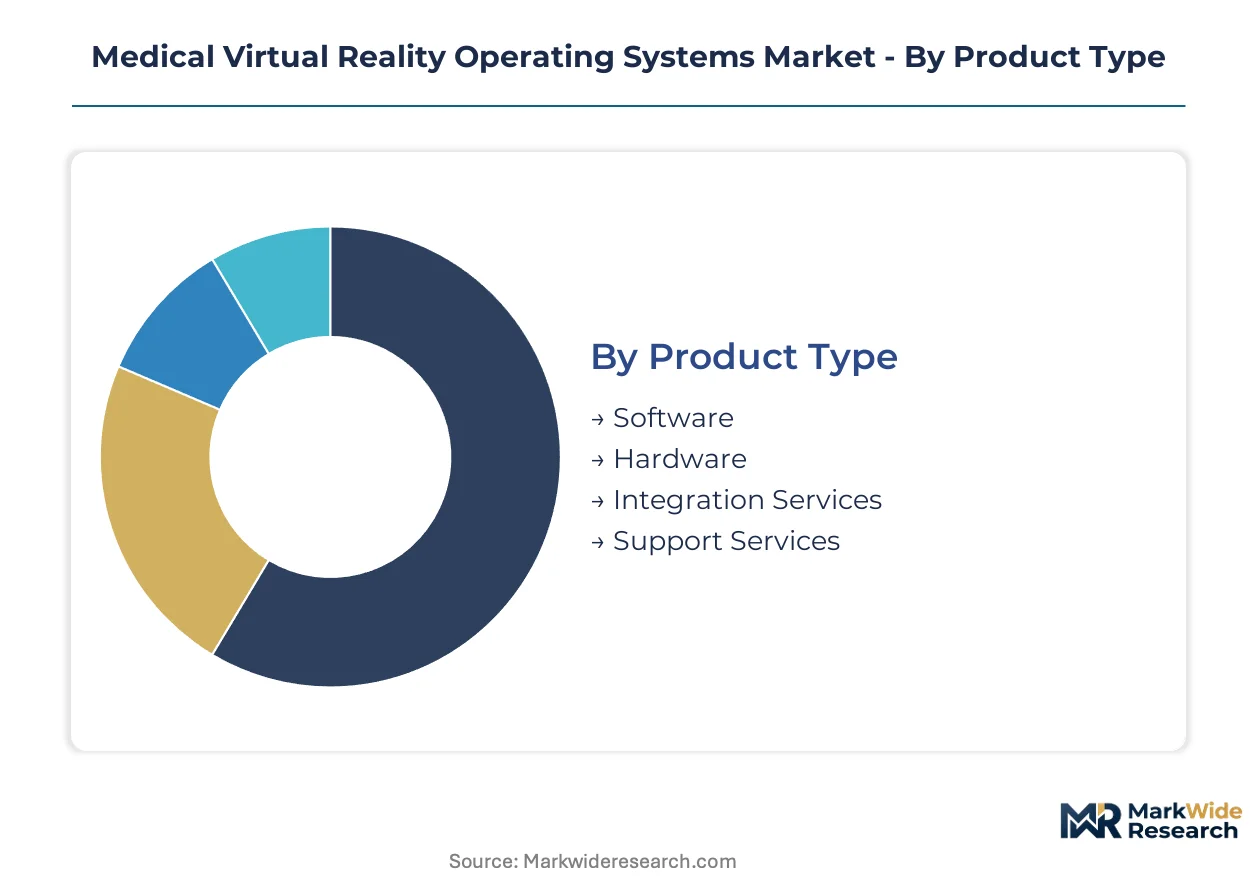
Segmentation in medical VR operating systems reveals divergent margin economics across software and hardware layers. Hospital procurement patterns vary sharply by deployment architecture and therapeutic application.
Product Type:
Mature segments anchor recurring revenue while emerging categories capture implementation complexity premiums.
- Software:Recurring license platforms render anatomical environments with sub-20 millisecond latency requirements. Academic medical centers in the United States drive institutional procurement of surgical simulation modules with mandated training hours.
- Hardware:Specialized headsets and haptic peripherals carry premium input costs that strain mid-tier hospital capital budgets. Meta Platforms' volume-scale production economics erode margins for dedicated medical device manufacturers.
- Integration Services:Turnkey deployment linking immersive environments with electronic health records commands premium pricing.
- Support Services:Response time guarantees dominate vendor competition with limited technical differentiation.
Software handles the majority of throughput; Integration Services is the fastest mover on share.
Therapy Area:
Application concentration follows regulatory validation pathways and reimbursement clarity.
- Orthopedics:Joint replacement visualization tools command validated demand from Siemens Healthineers R&D intensity. German hospital systems invest in preoperative planning modules with regulatory clearance.
- Neurosurgery:Complex spinal procedures adopt pass-through mixed reality overlays within compressed procurement cycles. United States academic centers mandate immersive simulation for resident certification.
- Rehabilitation:Physical therapy modules target direct-to-patient revenue streams.
- Pain Management:Underdeveloped use cases hold expansion potential in postoperative settings.
Orthopedics captures the installed base; Rehabilitation is climbing the fastest on adoption curves.
End User:
Customer scale determines deployment architecture preferences and service bundling tolerance.
- Hospitals:Dedicated digital health procurement functions unbundle after-sales contracts from initial licensing. United States health systems with cloud-hybrid architectures drive Azure-integrated deployments.
- Surgical Centers:Capital constraints favor subscription models over perpetual software sales.
- Research Institutions:Academic medical centers mandate immersive simulation hours creating institutional demand pull.
- Clinics:Limited IT infrastructure restricts adoption to consumer-grade hardware configurations.
Hospitals absorb the dominant procurement volume; Research Institutions are gaining share fastest on training mandates.
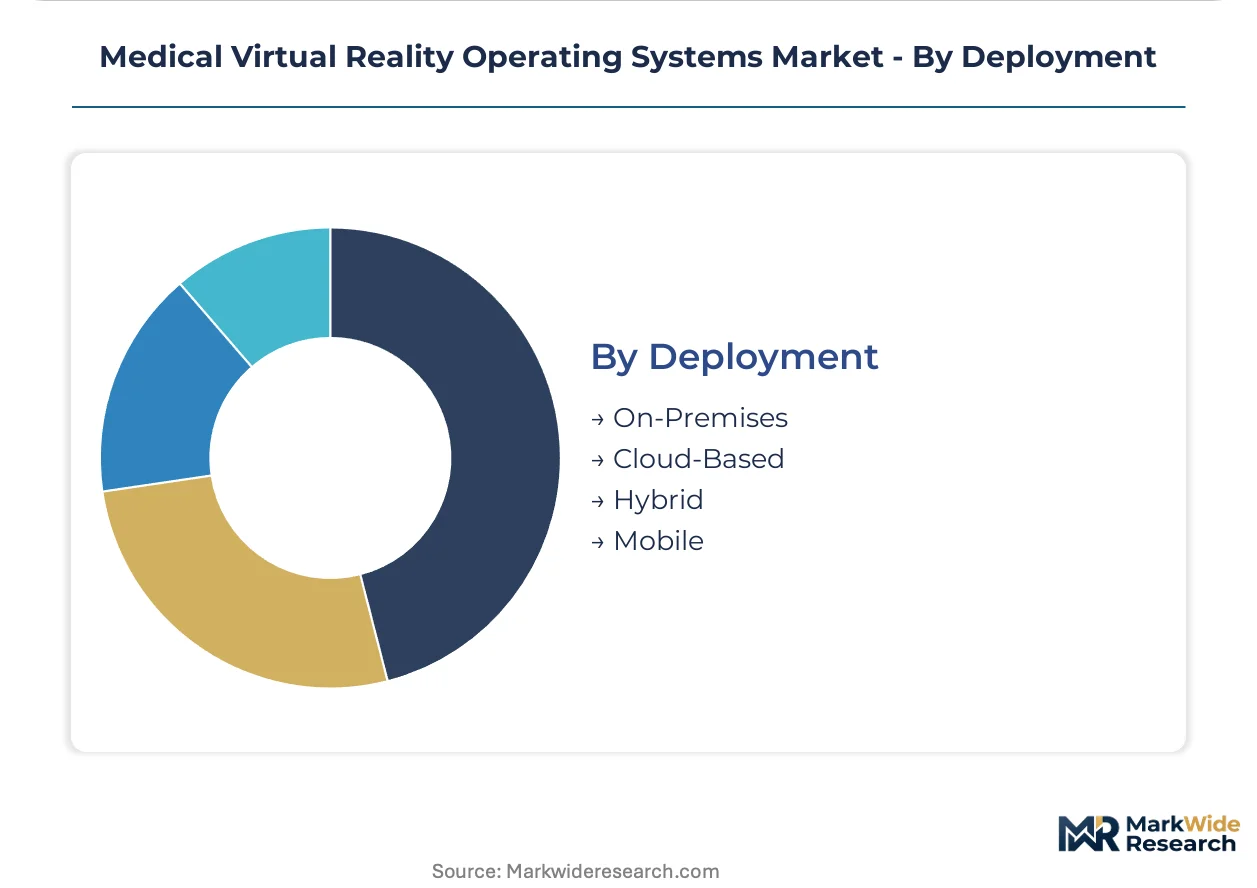
Deployment:
Infrastructure requirements stratify by data sovereignty tolerance and latency sensitivity.
- On-Premises:Local server installations satisfy HIPAA encryption mandates for sensitive patient data. Legacy electronic health record integration consumes disproportionate middleware resources.
- Cloud-Based:Microsoft Azure infrastructure enables seamless connectivity with hospital IT systems. Expanded attack surfaces demand cybersecurity architecture beyond standard capabilities.
- Hybrid:Balances latency performance with scalability for multi-site health systems.
- Mobile:Consumer headset compatibility opens rehabilitation and pain management applications.
Cloud-Based carries the deployment momentum; Hybrid is expanding most quickly on enterprise adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States hospital systems demonstrate the least price elasticity, absorbing premium hardware and subscription licensing without procurement delays. German orthopedic centers show moderate sensitivity, prioritizing regulatory-validated modules over cost minimization. Indian and Southeast Asian markets exhibit acute price consciousness, favoring consumer-grade hardware adaptations and open-source software frameworks.
United States
Academic medical centers in Boston, Houston, and the San Francisco Bay Area mandate immersive simulation hours for surgical resident certification. FDA 510(k) pathway streamlining accelerates clearance timelines for VR surgical planning tools. The Mayo Clinic and Cleveland Clinic anchor demand for cloud-hybrid deployments integrated with Microsoft Azure infrastructure.
Germany
University hospitals in Munich, Berlin, and Heidelberg drive procurement of joint replacement visualization modules. BfArM interprets EU AI Act enforcement thresholds variably, creating compliance complexity for autonomous surgical guidance algorithms. Siemens Healthineers sustains R&D intensity in Baden-Württemberg, validating preoperative planning demand across German orthopedic networks.
United Kingdom
NHS England digital health procurement functions unbundle after-sales service contracts from initial platform licensing. MHRA regulates VR surgical software as medical devices under UK MDR 2002 post-Brexit frameworks. London teaching hospitals and the Oxford-Cambridge corridor concentrate demand for neurosurgical mixed reality overlays.
Japan
PMDA medical device software requirements compress commercialization timelines for foreign entrants targeting Tokyo and Osaka hospital systems. METI funding programs support domestic VR surgical visualization development. Nagoya and Kyoto medical device clusters specialize in haptic peripheral engineering for sub-20 millisecond latency systems.
India
CDSCO medical device rules classify VR surgical planning tools as Class A or B devices depending on autonomous guidance features. Apollo Hospitals and Max Healthcare in Delhi-NCR and Bengaluru pilot cost-reduced deployments using consumer headset hardware. National Medical Commission training mandates create institutional demand pull for simulation-based surgical education.
Medical Virtual Reality Operating Systems Market Competitive Landscape
Cloud infrastructure incumbents and specialized medical device manufacturers split the market along deployment architecture lines. Microsoft Corporation leverages Azure dominance to anchor hospital IT integration, while Meta Platforms competes through volume-scale hardware production. Siemens Healthineers occupies the regulatory-validated orthopedic niche. Strategic moves concentrate on cloud-hybrid partnership structures and FDA 510(k) clearance acceleration for software modules.
Within the cloud-architecture tier, Microsoft Corporation represents the infrastructure-anchored archetype, embedding VR platforms within existing hospital IT contracts. Meta Platforms, Inc. exemplifies the consumer-hardware-adjacent position, eroding dedicated medical device margins through scale economics. Siemens Healthineers AG occupies the specialty-validated segment, leveraging German regulatory intensity to differentiate orthopedic preoperative planning offerings. These three anchors illustrate how competitive positioning stratifies across deployment model, hardware scale, and therapeutic specialization vectors.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Meta Platforms, Inc. |
| Siemens Healthineers AG |
| Koninklijke Philips N.V. |
| HTC Corporation |
| Osso VR, Inc. |
| XRHealth Inc. |
| AppliedVR, Inc. |
| Google LLC |
| Others |
Pricing and Supply Chain Analysis
FDA 21 CFR Part 820 compliance chokepoints determine both tier spreads and supply chain configuration, compressing commercialization timelines for new entrants while forcing established vendors toward Azure-anchored subscription bundles that absorb certification costs.
Pricing Analysis
After-sales service contracts drive lifetime value as hospital procurement committees unbundle implementation from initial platform licensing. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated surgical planning modules from training-only configurations and consumer-grade rehabilitation applications. Cost compression in hardware tiers is intensifying because Meta Platforms' volume-scale production economics erode dedicated medical device margins. Mid-tier surgical centers exhibit acute price sensitivity, while United States academic medical centers absorb premium subscription licensing without procurement delays.
Supply Chain Analysis
Export-control restrictions on sub-20 millisecond latency display technologies limit flows from Taiwanese semiconductor foundries and Japanese precision optics manufacturers. Hardware assembly draws from China, Mexico, and Vietnam, while specialized haptic peripheral engineering centers on Nagoya and Kyoto medical device clusters. Single-source vulnerability concentrates in Azure cloud infrastructure for hospital IT integration. Distribution runs through third-party IT integrators capturing implementation margins previously retained by original equipment manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflect as Microsoft Azure ecosystem integration collapses hardware categories into unified headset architectures, forcing interoperability standards across preoperative rehearsal and intraoperative navigation workflows.
For Market Incumbents: Harden cloud-hybrid deployment architectures against third-party IT integrator margin capture by embedding after-sales service contracts within initial platform licensing. Fortify orthopedic preoperative planning modules against Siemens Healthineers R&D intensity through accelerated FDA 510(k) clearance timelines for autonomous surgical guidance algorithms.
For New Entrants and Emerging Players: Establish a beachhead in postoperative rehabilitation applications where direct-to-patient revenue streams remain underdeveloped and regulatory validation pathways are less congested. Penetrate Indian and Southeast Asian markets through consumer-grade hardware adaptations paired with open-source software frameworks that bypass premium haptic peripheral costs.
For Investors and Strategic Acquirers: EU AI Act risk-tier classification reshapes the acquisition landscape, elevating technical documentation and human oversight protocol requirements for surgical decision-support modules. Target mid-cap specialists with validated orthopedic visualization tools and existing BfArM compliance infrastructure. Watch Swissmedic enforcement threshold interpretations as inflection indicators for European market access viability.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Acceleration | Compressed timelines enable faster hospital procurement cycles for surgical planning modules. |
| Azure Cloud-Hybrid Partnership | Microsoft infrastructure anchors electronic health record connectivity for multi-site health systems. |
| Orthopedic Preoperative Planning Module | Regulatory-validated demand from German hospital networks differentiates specialized offerings. |
| Third-Party IT Integrator Acquisition | Captures implementation and training margins unbundled from original platform licensing. |
| Consumer Hardware Adaptation Program | Meta Platforms volume economics enable cost-reduced deployments in price-sensitive markets. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with VR platform engineers, hospital purchasing committee members, biomedical engineers, and GPO contracts managers; and secondary validation against FDA 510(k) filings, hospital procurement databases, CMS Medicare reimbursement data, and hyperscaler capex disclosures. Bottom-up and top-down triangulation cross-checked segment-level assumptions.
Forecast inputs considered deployment architecture, therapeutic application, end-user scale, and regional regulatory cluster across the analysis window. CAGRs were derived from modeled adoption curves for cloud-based versus on-premises installations, with surgical training mandate expansion and EU AI Act compliance ramp as medical VR-specific demand drivers.
Stress conditions across FDA clearance timeline compression, Azure infrastructure pricing volatility, and haptic peripheral supply constraints were modeled; outcomes outside those bands fall beyond the analytical envelope. Material shifts in EU AI Act enforcement threshold interpretations or HIPAA encryption standard revisions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
Europe Digital Therapeutic (Dtx) Market
Digital Health Solutions
Digital Healthcare Solutions Market
Digital Health Solutions
Digital Twins in Healthcare Market
Digital Health Solutions
Smart Cards in Healthcare Market
Digital Health Solutions
Global Emergency Medical Services Billing Software Market
Digital Health Solutions
Digital Brain Health Market
Digital Health Solutions
Europe Digital Health Market
Digital Health Solutions
Global Clinical Workflow Solutions Market
Digital Health Solutions
Connected Health and Wellness Devices Market
Digital Health Solutions
Artificial Intelligence in Precision Medicine Market
Digital Health Solutions
Teleradiology Software Market
Digital Health Solutions
Mhealth Apps Market
Digital Health Solutions
Amblyopia Treatment Softwares Market
Digital Health Solutions
Mixed Reality in Healthcare Market
Digital Health Solutions
Long Term Post-Acute Care Software Market
Digital Health Solutions
Advanced Clinical Decision Support Platforms Market