
 North America Virtual Reality (VR) Health Market | 2026-2036
North America Virtual Reality (VR) Health Market Size, Share, and Industry Trends Forecast 2026-2036
North America Virtual Reality (VR) Health Market Analytics
Market Context with Strategic Players
Canada's health-tech manufacturing base is narrowing the hardware supply gap for clinical-grade VR systems. Meta Platforms leverages its consumer VR ecosystem to extend into FDA-regulated therapeutic applications. Siemens Healthineers anchors its position through imaging-integrated surgical simulation platforms. Philips Healthcare competes with hospital-focused deployment services that bundle hardware, software, and training.
Technical Definition and Structural Segments
North America Virtual Reality (VR) Health comprises immersive computing systems with sub-20 millisecond motion-to-photon latency, stereoscopic displays exceeding 90 frames per second, and six-degrees-of-freedom tracking for clinical validation in medical procedures. These systems deliver spatially accurate sensory substitution for pain modulation, motor-skill rehabilitation, and procedural training in controlled clinical environments. Software applications command margin concentration due to recurring licensing models and lower marginal distribution costs versus headset hardware. Therapeutic applications lead volume adoption, while pain management represents the fastest-expanding use case as opioid-alternative protocols gain institutional traction. Simulation-based technology dominates hospital procurement budgets, though mixed reality systems are penetrating surgical planning workflows.
Regulatory Frame and Forward-Looking Close
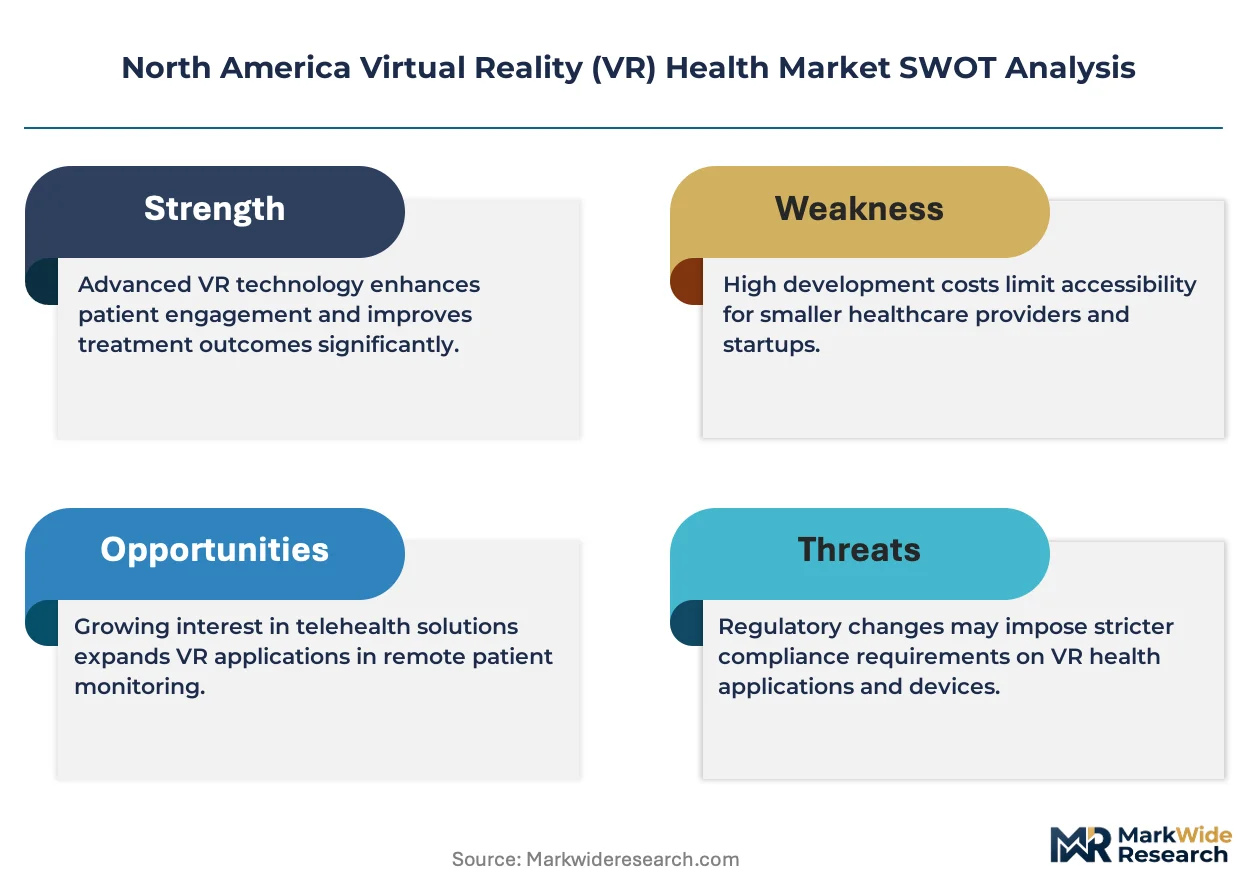
FDA's Software as a Medical Device framework, HIPAA privacy safeguards, and Health Canada's Medical Device Licensing program collectively shape product development roadmaps and market access requirements across North America. These standards enforce clinical evidence thresholds, data security architectures, and quality management systems that filter out undercapitalized entrants. Stakeholders must monitor reimbursement code evolution for digital therapeutics, as payer acceptance will determine whether VR health transitions from pilot budgets to standard-of-care procurement.
Market Dynamics
FDA's Software as a Medical Device framework is compressing commercialization timelines for therapeutic VR applications, forcing developers to front-load clinical evidence generation before market entry rather than retrofitting compliance post-launch.
Growth Catalysts
- Post-stroke rehabilitation protocols:Hospital systems across the United States are embedding VR-assisted motor therapy into standard discharge pathways, creating institutional pull for validated hardware-software bundles.
- Health Canada's Medical Device Licensing program:Streamlined pathways for digital therapeutics are accelerating cross-border product launches, reducing regulatory duplication between Canadian and American markets.
- Opioid-alternative pain management:CMS reimbursement experimentation for non-pharmacological interventions is driving inpatient and outpatient adoption of immersive analgesia systems.
Market Restraints
- Clinical-grade headset supply concentration:Manufacturing of sub-20 millisecond latency displays concentrates in East Asian component foundries, exposing North American integrators to single-source risk.
- HIPAA compliance architecture costs:End-to-end encryption and audit-ready data pipelines add substantial fixed costs to software development, filtering out undercapitalized entrants.
- Substitute therapy modalities:Traditional physical therapy equipment and telehealth platforms retain institutional preference in budget-constrained rural hospital networks.
Strategic Opportunities
- Home-based rehabilitation services:Untapped demand exists for FDA-cleared VR systems that transition patients from clinical settings to remote monitoring environments.
- AI-driven haptic feedback convergence:Integration of machine learning with force-feedback gloves is creating new procedural training categories for surgical residents.
- Texas and Florida health system procurement:Rapidly expanding hospital networks in these states lack incumbent VR vendors, presenting first-mover advantages for deployment-ready platforms.
Industry Challenges
- Clinical evidence generation timelines:Randomized controlled trials for FDA breakthrough device designation require 18-36 month investment cycles before revenue realization.
- Interoperability with electronic health records:Integration with Epic and Cerner systems demands specialized health informatics talent that vendors struggle to recruit.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Virtual Reality (VR) Health Market |
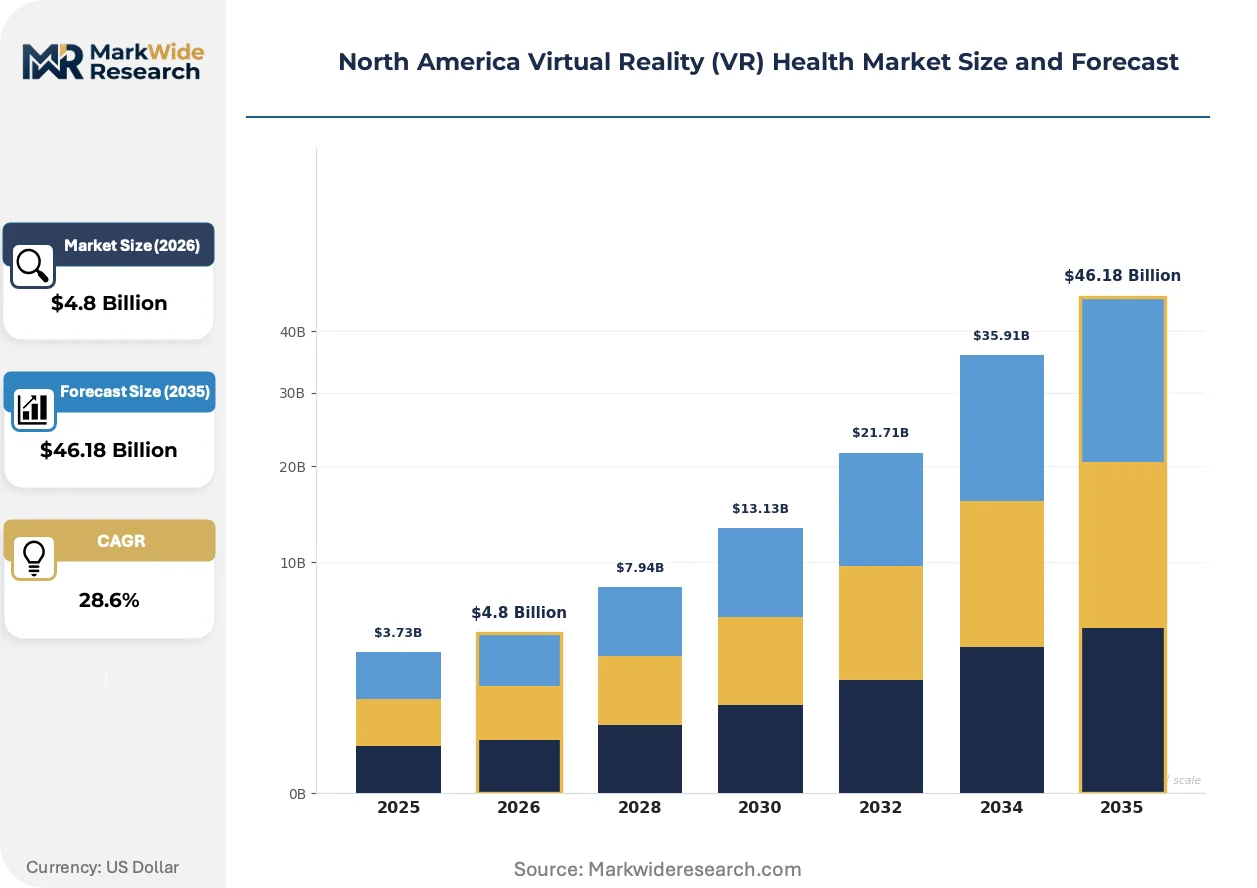
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $46.18 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Headsets, Software, Controllers, Accessories Application: Therapeutic, Training, Rehabilitation, Pain Management End User: Hospitals, Clinics, Rehabilitation Centers, Research Institutions Technology: Immersive VR, Augmented Reality, Mixed Reality, Simulation-based |
| Companies Covered | Siemens Healthineers AG, MindMaze SA, Microsoft Corporation, Philips Healthcare, GE Healthcare, Meta Platforms, Inc., CAE Healthcare, XRHealth, HTC Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Virtual Reality (VR) Health Market Evolving Landscape
Spatial computing architectures are collapsing the boundary between simulation and live intervention, enabling real-time physiological feedback loops that were previously confined to research laboratories.
Eye-tracking integration with pupillometry sensors is virtualizing pain assessment protocols, allowing clinicians to quantify analgesic response without patient self-reporting. Veterans Affairs medical centers are piloting these systems for chronic pain cohorts. The technology is virtualizing subjective symptom measurement into objective biometric streams that integrate directly with treatment algorithms.
FDA's breakthrough device designation pathway is compressing review timelines for VR-based cognitive behavioral therapy platforms, rewarding sponsors who submit robust pivotal trial data. Mental health applications targeting PTSD and anxiety disorders are securing priority review status. Canadian developers are leveraging this regulatory reciprocity to access American reimbursement codes through parallel Health Canada submissions.
Hospital procurement committees are unbundling hardware purchases from software licensing, forcing vendors to compete on recurring platform fees rather than upfront capital expenditure. Academic medical centers in California's health-tech corridor are leading this shift toward subscription-based clinical service models. The pattern concentrates vendor selection authority within health system innovation offices rather than traditional supply chain departments.
North America Virtual Reality (VR) Health Market Segmentation
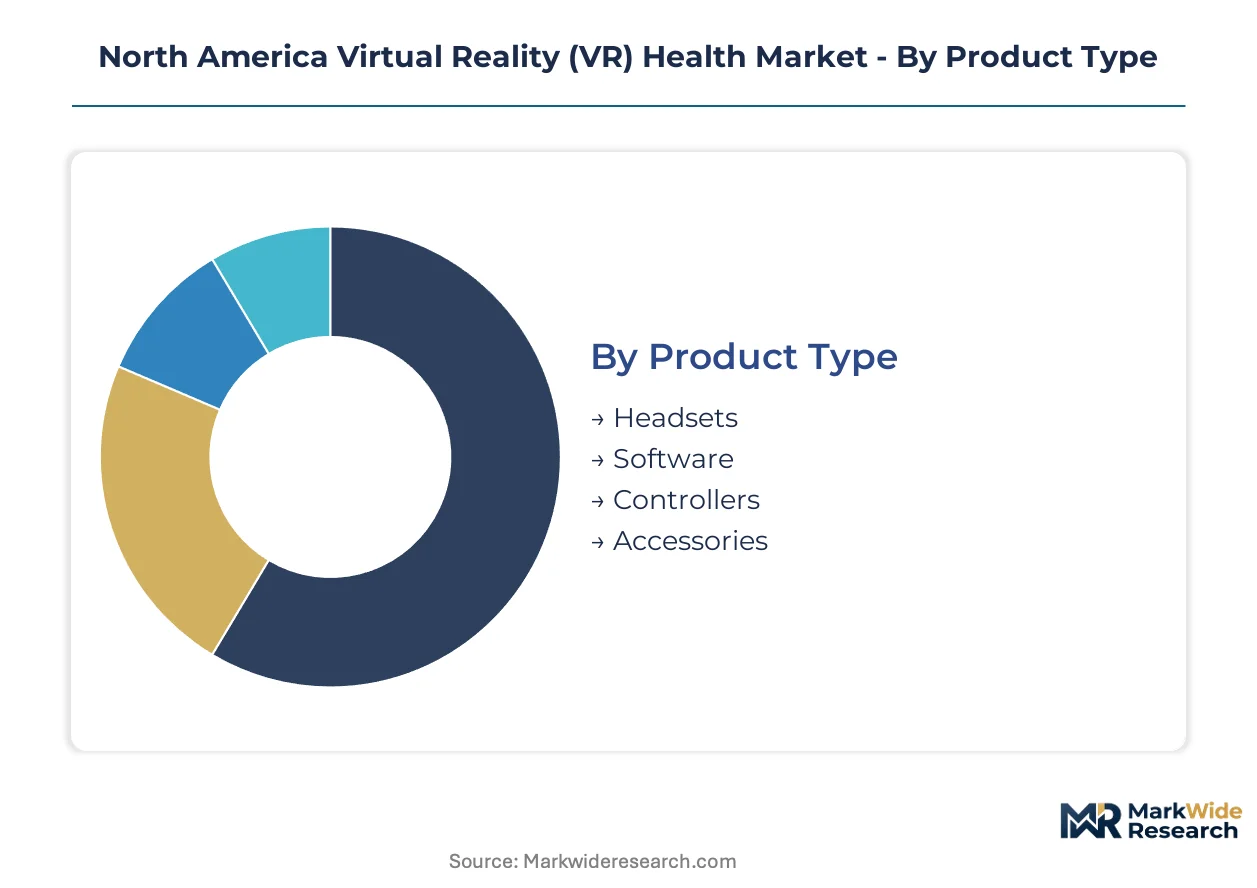
Segmentation in VR health reveals divergent margin structures and procurement pathways across hardware, software, and service layers. Product type determines capital intensity, while application focus shapes regulatory complexity and reimbursement eligibility.
Product Type:
The use-case spectrum spans high-volume hardware deployment to recurring software licensing with fundamentally different margin profiles.
- Headsets:Clinical-grade units require sub-20 millisecond motion-to-photon latency and six-degrees-of-freedom tracking validated for sterile environments. Procurement concentrates in California health systems and Texas hospital networks where capital budgets accommodate FDA-cleared devices. Supply chain exposure to East Asian display foundries creates procurement risk for North American integrators.
- Software:Therapeutic applications and procedural training modules command recurring licensing models with lower marginal distribution costs than hardware. Demand clusters in academic medical centers pursuing FDA breakthrough device designation for cognitive behavioral therapy platforms.
- Controllers:Hand-tracking peripherals and force-feedback interfaces enable motor-skill rehabilitation protocols. Rehabilitation centers across the United States embed these into stroke recovery discharge pathways.
- Accessories:Sanitization stations, mounting hardware, and biometric sensors extend system utility in clinical workflows.
Established volume favors Headsets; emerging adoption favors Software.
Application:
Margin concentration shifts toward intervention categories with clearest reimbursement pathways.
- Therapeutic:Mental health applications targeting PTSD and anxiety disorders secure FDA priority review status through robust pivotal trial data. Veterans Affairs medical centers pilot these systems for chronic pain cohorts.
- Pain Management:Immersive analgesia systems are expanding most quickly as CMS reimbursement experimentation for non-pharmacological interventions drives inpatient and outpatient adoption. Opioid-alternative protocols gain institutional traction fastest in this category.
- Training:Surgical simulation platforms integrate with imaging systems for resident education. Academic medical centers bundle these with subscription-based clinical service models.
- Rehabilitation:Post-stroke motor therapy protocols embed into standard discharge pathways, creating institutional pull for validated hardware-software bundles.
Procurement maturity favors Training; regulatory tailwinds favor Pain Management.
End User:
Customer type determines deployment complexity and data architecture requirements.
- Hospitals:Epic and Cerner integration demands specialized health informatics talent. Procurement committees unbundle hardware from software licensing, shifting vendor selection authority to innovation offices.
- Rehabilitation Centers:Stroke recovery programs across the United States are embedding VR-assisted motor therapy into standard discharge pathways.
- Clinics:Outpatient settings pursue CMS reimbursement codes for digital therapeutics, with payer acceptance determining standard-of-care procurement.
- Research Institutions:Eye-tracking with pupillometry sensors virtualizes pain assessment protocols, quantifying analgesic response without patient self-reporting.
Budget authority concentrates in Hospitals; growth velocity concentrates in Rehabilitation Centers.
Technology:
Architecture choice determines latency tolerance and clinical validation requirements.
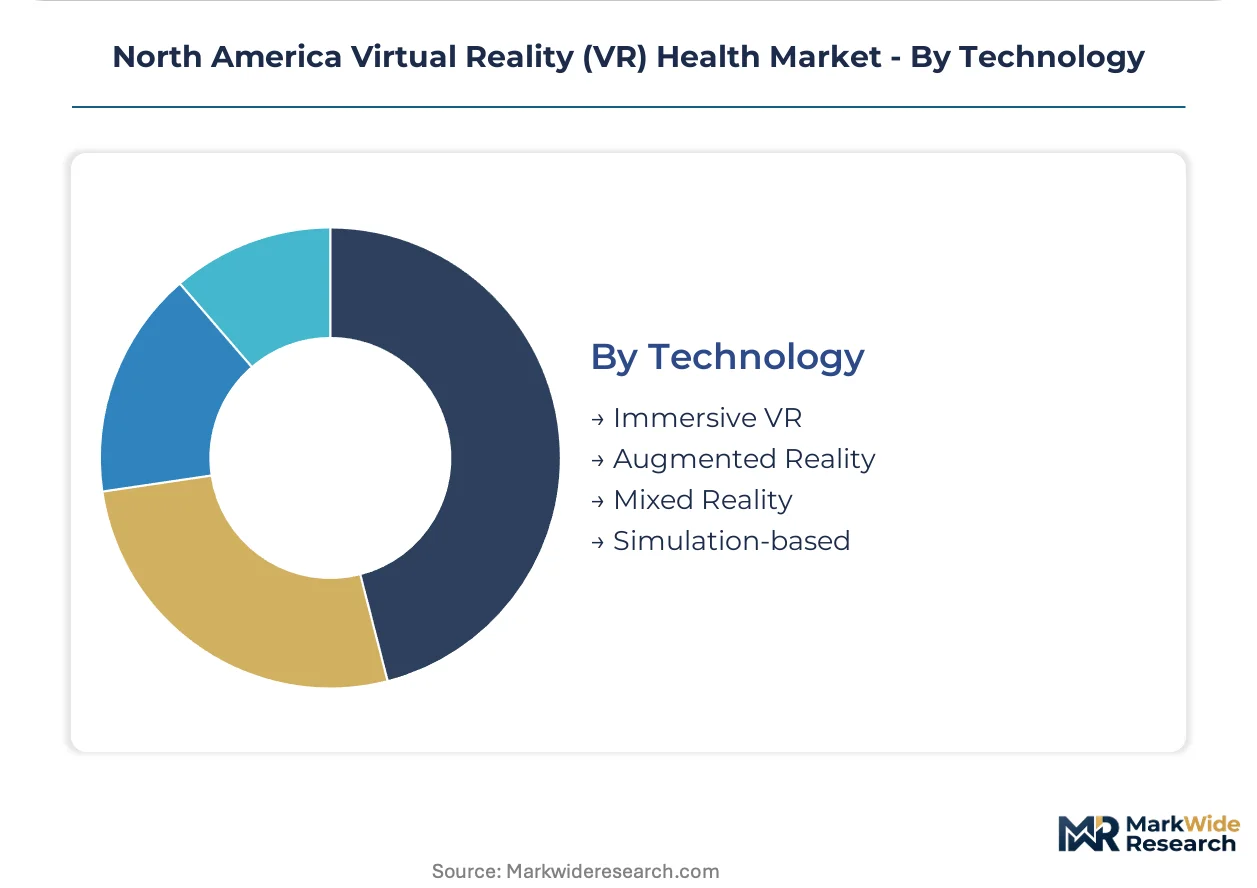
- Immersive VR:Fully occluded headsets dominate pain management and mental health therapeutic applications where environmental control matters.
- Simulation-based:Surgical planning and resident training platforms anchor hospital procurement budgets with imaging-integrated workflows.
- Mixed Reality:Real-time physiological feedback loops enable live intervention support, penetrating surgical planning workflows in academic medical centers.
- Augmented Reality:Overlay applications retain peripheral awareness for procedural guidance in operating environments.
Current spend concentrates in Simulation-based; capability expansion favors Mixed Reality.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Component manufacturing for clinical-grade VR systems concentrates in East Asian foundries, while North American integrators and software developers capture value downstream through FDA-cleared therapeutic platforms and hospital deployment services.
United States
California's health-tech corridor anchors demand concentration, where hospital systems and venture capital clusters co-locate to accelerate product commercialization. FDA's Software as a Medical Device framework compresses review timelines for breakthrough device designations, particularly for PTSD and anxiety-targeting cognitive behavioral therapy platforms. Texas and Florida hospital networks lack incumbent VR vendors, creating first-mover opportunities for deployment-ready platforms in rapidly expanding procurement budgets.
Canada
Health Canada's Medical Device Licensing program streamlines pathways for digital therapeutics, accelerating cross-border product launches and reducing regulatory duplication with American markets. The country's health-tech manufacturing base narrows hardware supply gaps for clinical-grade VR systems. Ontario and Quebec host emerging clusters of VR health developers leveraging regulatory reciprocity to access United States reimbursement codes through parallel submissions.
Mexico
Medical device manufacturing hubs in Baja California and Chihuahua supply component assembly for North American integrators, though clinical-grade display sourcing remains import-dependent. The national pharmaceutical regulator maintains alignment with FDA quality standards for cross-border medical device trade. Mexico City Metro health systems pilot VR-assisted rehabilitation protocols, creating demand anchors for hardware-software bundles in Latin America's second-largest medical device market.
North America Virtual Reality (VR) Health Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in display and sensor manufacturing. The vendor base stratifies across three tiers: imaging-integrated surgical simulation platforms, consumer-ecosystem extensions into regulated therapeutics, and pure-play digital therapeutic developers. Dominant competitive moves include strategic partnerships with academic medical centers for clinical evidence generation and unbundling of hardware purchases from recurring software licensing to capture subscription revenue streams.
Within the imaging-integrated platform tier, Siemens Healthineers AG and GE Healthcare exemplify archetypes anchoring hospital procurement through surgical simulation bundled with diagnostic equipment. Meta Platforms, Inc. represents the consumer-ecosystem extension model, leveraging mass-market VR infrastructure toward FDA-regulated therapeutic applications. Among pure-play digital therapeutic developers, XRHealth occupies a position exemplifying the specialized, reimbursement-code-focused vendor segment targeting outpatient and home-based care transitions.
| Leading Market Players |
|---|
| Siemens Healthineers AG |
| MindMaze SA |
| Microsoft Corporation |
| Philips Healthcare |
| GE Healthcare |
| Meta Platforms, Inc. |
| CAE Healthcare |
| XRHealth |
| HTC Corporation |
| Others |
Value Network & Pricing Analysis
The Port of Long Beach freight corridor transmits East Asian component costs directly into California health system procurement budgets, compressing margins for hardware integrators while amplifying price spreads between FDA-cleared therapeutic platforms and uncertified consumer-grade alternatives.
Pricing Analysis
FDA's Software as a Medical Device framework dictates the pricing tier structure across the North American VR health landscape. Three-tier pricing structure across premium, standard, and economy levels separates breakthrough device designation holders from 510(k) pathway followers and uncertified wellness applications. Price differentiation rests on clinical validation depth and CMS reimbursement eligibility. Pricing pressure stems from hospital procurement committees unbundling hardware from software licensing. Budget-constrained rural hospital networks exhibit highest price sensitivity; academic medical centers in California's health-tech corridor demonstrate lowest.
Supply Chain Analysis
Quanta Computer and Foxconn hold contract manufacturing capacity for clinical-grade VR headsets, concentrating final assembly in Taiwan and mainland China. Display foundries in South Korea and Japan supply sub-20 millisecond latency panels. Raw material dependencies include rare-earth magnets for haptic actuators, gallium nitride semiconductors for display drivers, and medical-grade polymers for sterile housings. Single-source vulnerability concentrates in advanced OLED microdisplay production. Distribution runs through hospital GPO contracts and direct-to-health-system innovation offices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized health informatics talent capable of Epic and Cerner integration commands premium compensation, creating a binding constraint on vendor scaling velocity and consolidating advantage among incumbents with captive engineering capacity.
For Market Incumbents: Entrench position through exclusive partnerships with Veterans Affairs medical centers for chronic pain cohort evidence generation. Acquire FDA breakthrough device designation for PTSD platforms before competitor pivotal trials conclude. Defend against Meta Platforms' consumer-ecosystem extension by deepening clinical workflow integration. For New Entrants and Emerging Players: Establish a beachhead in Texas and Florida hospital networks lacking incumbent VR vendors. Target home-based rehabilitation services as the most penetrable segment, where FDA-cleared remote monitoring systems face minimal established competition. Pursue direct contracting with rapidly expanding health systems bypassing traditional GPO channels. For Investors and Strategic Acquirers: Pure-play digital therapeutic developers with parallel Health Canada and FDA submissions represent the highest-conviction acquisition archetype across the analysis window. Long-term viability hinges on reimbursement code capture rather than hardware volume. Monitor CMS National Coverage Determination announcements for immersive analgesia as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Submission | Compresses review timelines for PTSD and anxiety-targeting cognitive behavioral therapy platforms. |
| Hospital System Partnership | Academic medical centers in California bundle surgical simulation with subscription-based clinical service models. |
| Reimbursement Strategy | CMS experimentation for non-pharmacological pain interventions determines standard-of-care procurement eligibility. |
| Software Companion Development | AI-driven haptic feedback integration creates new procedural training categories for surgical residents. |
| Cross-Border Regulatory Alignment | Parallel Health Canada submissions leverage regulatory reciprocity to access American reimbursement codes. |
Research Methodology
A spread of perspectives from hospital purchasing committees, biomedical engineers, GPO contracts managers, and health system innovation officers converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) and De Novo filings, CMS National Coverage Determination databases, and hospital procurement contract repositories. Bottom-up demand modeling triangulated against top-down health system capital expenditure surveys.
Demand-supply balance framing anchored the analytical framework across the analysis window. Segmentation dimensions included product type, application focus, end user category, and technology architecture. CAGRs derived from logistic diffusion curves fitted to historical adoption patterns in comparable digital therapeutic categories. Forecast inputs incorporated FDA review timeline distributions and Health Canada Medical Device Licensing throughput rates.
Macroeconomic conditions sit as an overlay; deviation in health system capital expenditure cycles or CMS reimbursement policy would shift the trajectory materially. Forecasts reflect documented assumptions regarding regulatory pathway efficiency and clinical evidence generation timelines. Quarterly review of FDA breakthrough device designation awards and CMS National Coverage Determination filings is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
AI in Patient Engagement Market
Digital Health Solutions
Care Management Solutions Market
Digital Health Solutions
Connected Health and Wellness Devices Market
Digital Health Solutions
North America Digital Health Market
Digital Health Solutions
Medical Virtual Reality Operating Systems Market
Digital Health Solutions
Digital Therapeutics and Wellness Market
Digital Health Solutions
Healthcare Navigation Platform Market
Digital Health Solutions
Connected Health and Wellness Solutions Market
Digital Health Solutions
Mhealth Services Market
Digital Health Solutions
US Patient Engagement Solutions Market
Digital Health Solutions
Middle East and Africa Heart Failure Software Market
Digital Health Solutions
Global Plastic Surgery Software Market
Digital Health Solutions
Europe Eclinical Solutions Market
Digital Health Solutions
Connected Healthcare Market
Digital Health Solutions
Medical Animation Market
Digital Health Solutions
Mhealth Apps Market