
 Global Preventive Healthcare Technologies and Services Market | 2026-2036
Global Preventive Healthcare Technologies and Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global Preventive Healthcare Technologies and Services Market Foresight
Subscription-based leasing for remote patient monitoring infrastructure is narrowing the capital barrier for mid-sized diagnostic laboratories seeking enterprise-grade capabilities. Abbott Laboratories leverages its vertically integrated sensor manufacturing to sustain price competitiveness in continuous glucose monitoring. Teladoc Health anchors its position through channel control over employer-sponsored virtual primary care networks. Myriad Genetics specializes in hereditary cancer risk assessment, occupying a defensible niche in genomic screening.
Preventive healthcare technologies and services encompass systems designed to intercept disease onset through biometric surveillance, predictive analytics, and behavioral intervention rather than reactive treatment. These platforms integrate wearable photoplethysmography sensors, multiplex immunoassay diagnostic kits, and cloud-native telehealth architectures to enable continuous physiological monitoring and early pathological detection. Wearable Devices and Health Monitoring Sensors command the largest installed base, though Telehealth Platforms capture disproportionate margin expansion as reimbursement codes broaden for virtual preventive encounters. Screening Services within the service type dimension exhibit the steepest growth trajectory, propelled by employer mandates and payer incentive structures that reward population-level risk reduction.
The FDA regulates wearable and diagnostic device safety through 510(k) and De Novo pathways, while HIPAA governs data interoperability standards that constrain platform architecture choices for vendors serving US providers. The EMA's Medical Device Regulation in Europe imposes stricter clinical evidence requirements, fragmenting compliance costs for manufacturers seeking transatlantic market access. Stakeholders must monitor evolving reimbursement parity between in-person and virtual preventive encounters as payer policies determine addressable market boundaries.
Market Dynamics
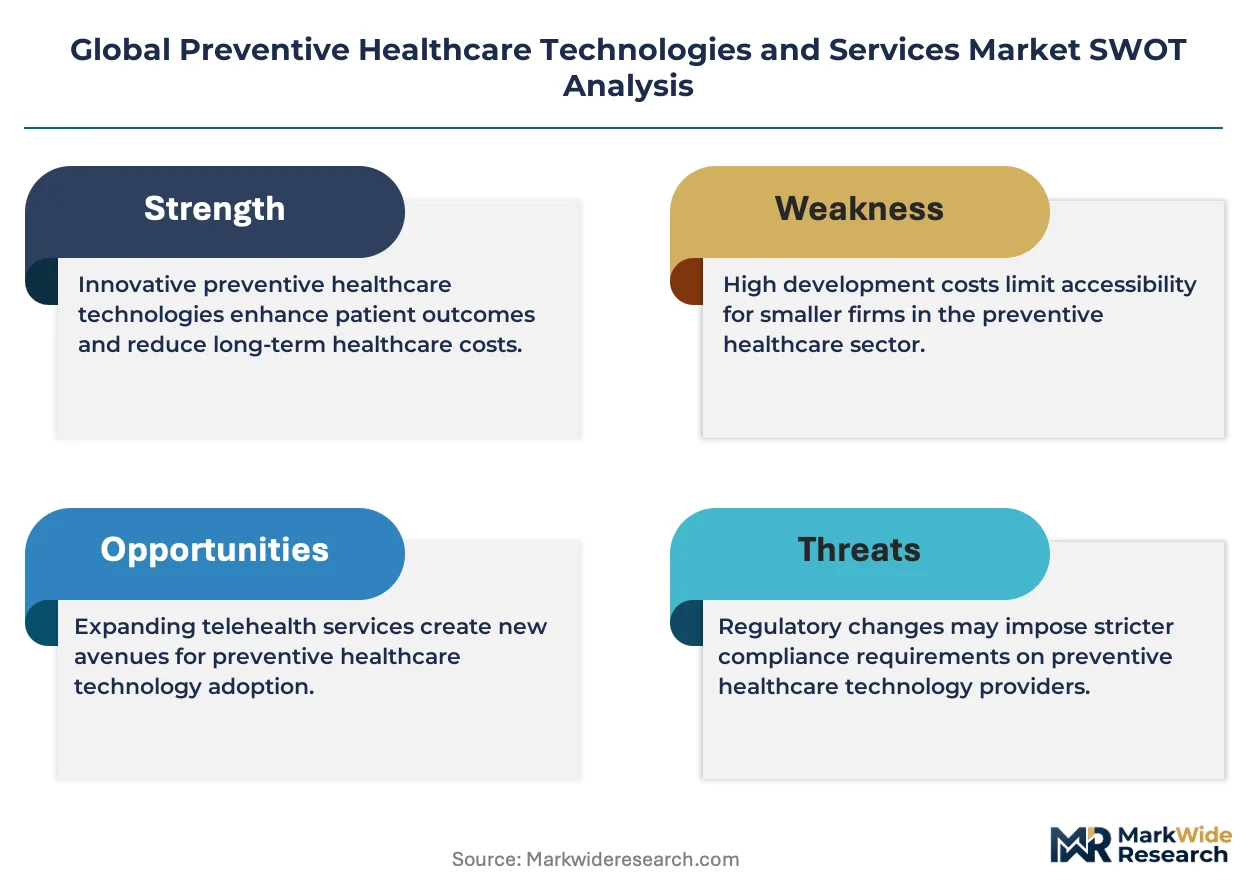
Employer-sponsored biometric surveillance programs are compressing the sales cycle for preventive health platforms as Fortune 500 firms mandate continuous glucose monitoring and virtual primary care integration for covered populations.
Growth Catalysts
- CMS reimbursement parity:Medicare's expanded billing codes for remote patient monitoring incentivize US health systems to deploy wearable diagnostic infrastructure at scale.
- Photoplethysmography miniaturization:Optical sensor cost curves enable sub-$50 consumer wearables with clinical-grade arrhythmia detection.
- Employer mandate density:Self-insured corporations in the United States now require preventive screening participation as a condition of premium discounts.
Market Restraints
- EMA MDR compliance burden:Stricter clinical evidence requirements for wearable medical devices fragment certification costs for manufacturers seeking European market access.
- Semiconductor supply concentration:Taiwan-dominant fabrication of biosensor ASICs creates input vulnerability for continuous monitoring device producers.
- HIPAA interoperability constraints:Data architecture restrictions limit platform vendor flexibility when serving US provider networks.
Strategic Opportunities
- India's diagnostic infrastructure gap:Subscription-based remote patient monitoring leasing narrows capital barriers for mid-sized laboratories in tier-2 cities.
- AI-photoplethysmography convergence:Machine learning-enhanced optical sensors enable non-invasive blood pressure monitoring without cuff-based calibration.
- Japan's Silver Wellness mandate:METI incentives for elderly preventive care adoption create channel openings for telehealth-integrated screening platforms.
Industry Challenges
- FDA 510(k) timeline compression:De Novo pathway backlog for novel wearable diagnostics extends time-to-revenue for sensor innovators.
- Legacy EHR integration friction:HL7 FHIR standardization gaps force costly middleware development for telehealth platform vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Preventive Healthcare Technologies and Services Market |
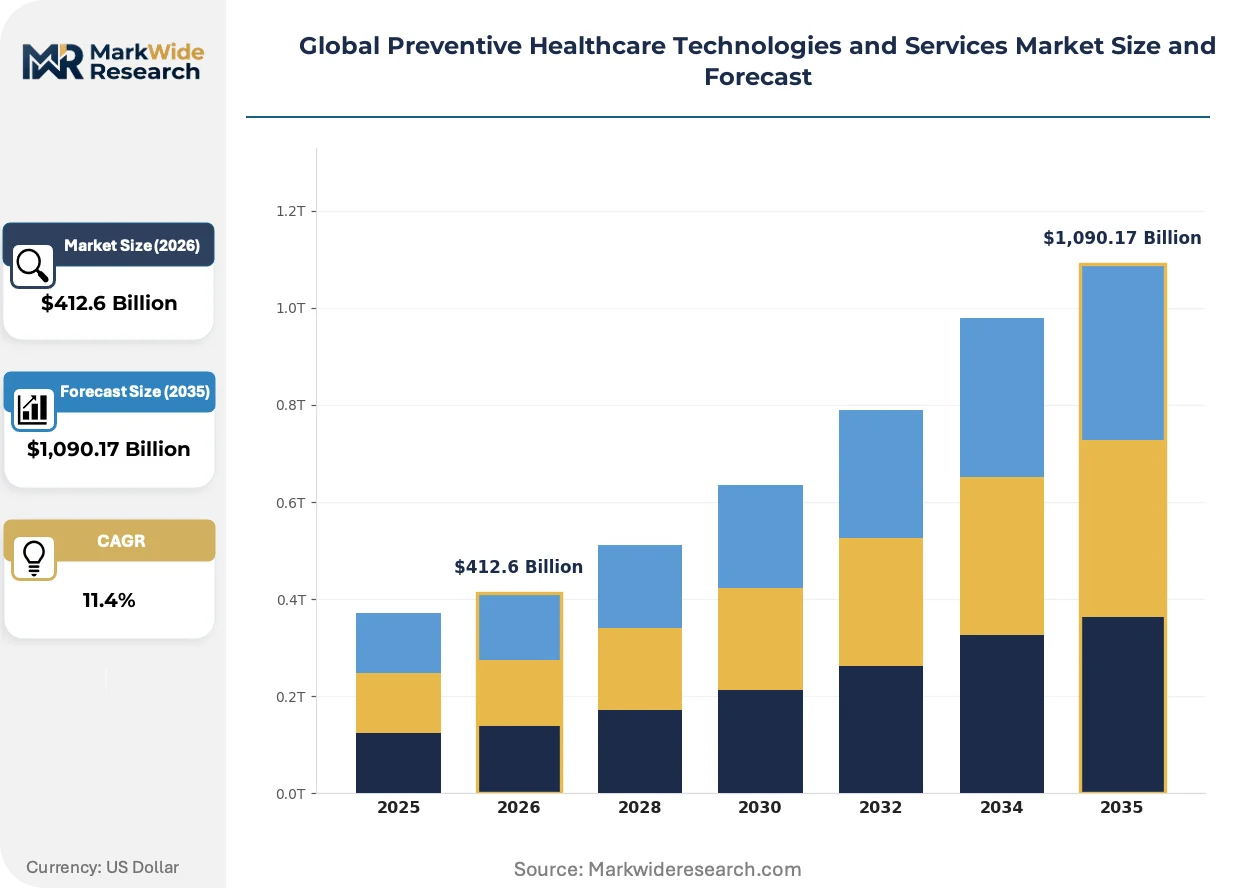
| Market Size in 2026 | $412.6 Billion |
| Market Size in 2035 | $1,090.17 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Diagnostic Kits, Health Monitoring Sensors, Telehealth Platforms, Vaccination Technologies, Nutritional Supplements Service Type: Risk Assessment, Health Coaching, Screening Services, Immunization Programs, Data Analytics, Behavioral Therapy Application: Chronic Disease Prevention, Infectious Disease Control, Lifestyle Management, Early Detection, Mental Wellness, Occupational Health End User: Primary Care Clinics, Diagnostic Laboratories, Corporate Wellness Programs, Fitness Centers, Insurance Providers, Government Agencies |
| Companies Covered | Merck & Co. Inc., Pfizer Inc., GlaxoSmithKline plc, Medtronic plc, Abbott Laboratories, Teladoc Health, UnitedHealth Group, McKesson Corporation, Myriad Genetics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Preventive Healthcare Technologies and Services Market Shifts & Advancements
Multiplex biomarker detection and ambient sensing architectures are collapsing the distinction between clinical and consumer-grade preventive monitoring, forcing platform vendors to recalibrate certification strategies and pricing architectures simultaneously.
Photoplethysmography-based cuffless blood pressure monitoring is rendering obsolete traditional oscillometric devices in employer wellness deployments. Large self-insured corporations in the United States are adopting wrist-worn continuous cardiovascular surveillance for covered workforces. The technology is rendering obsolete the annual biometric screening model by enabling daily physiological tracking at comparable accuracy.
EMA's Medical Device Regulation imposes post-market clinical follow-up obligations on wearable diagnostic manufacturers seeking CE marking. European health technology assessments now require real-world evidence generation for preventive screening algorithms. Continuous glucose monitoring vendors are responding by establishing prospective registry studies across Germany and France.
Employer procurement of preventive health services is consolidating through direct contracting with virtual primary care networks. Benefits consultants are disintermediating traditional payer channels for biometric monitoring program deployment. This concentration is most visible among technology sector employers in California and Washington state seeking integrated telehealth-screening bundles.
Global Preventive Healthcare Technologies and Services Market Segmentation
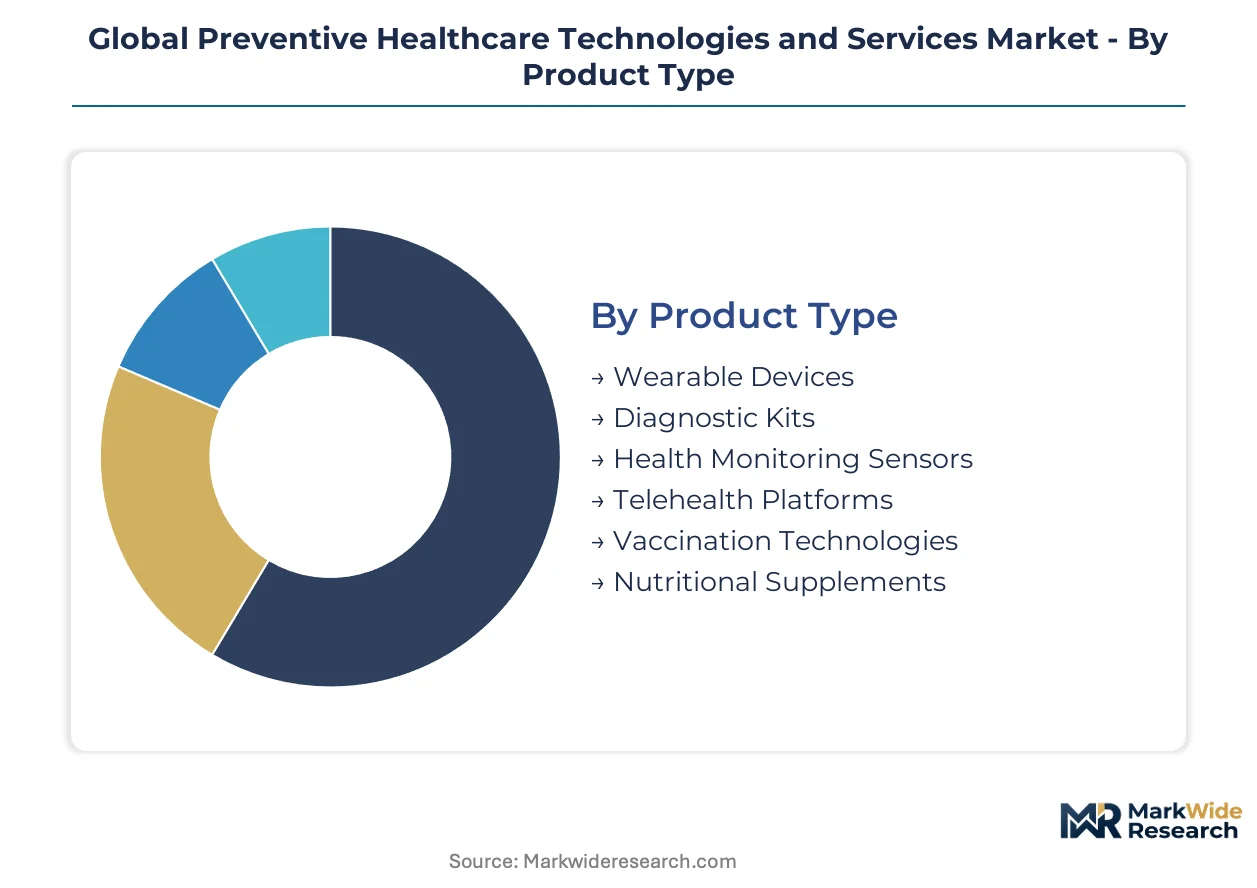
Segmentation in preventive healthcare reveals how technology maturity and reimbursement pathways split addressable markets. Each dimension carries distinct capital intensity, regulatory exposure, and margin profiles that determine vendor positioning strategies.
Product Type:
Mature hardware segments face margin compression from commoditization, while emerging software-native platforms capture expanding reimbursement codes.
- Telehealth Platforms:Cloud-native architectures integrating synchronous video consultation with asynchronous messaging and remote device data ingestion. Demand concentrates among self-insured US employers bundling virtual primary care with biometric screening mandates.
- Wearable Devices:Photoplethysmography-enabled wrist-worn sensors providing continuous cardiovascular and metabolic surveillance. Corporate wellness procurement in California and Washington state drives volume through direct contracting models.
- Diagnostic Kits:Multiplex immunoassay platforms for home-based biomarker detection.
- Health Monitoring Sensors:Patch-based electrocardiogram and continuous glucose monitors.
- Vaccination Technologies:mRNA formulation and cold-chain delivery systems for prophylactic immunization.
- Nutritional Supplements:Evidence-based micronutrient and probiotic formulations targeting metabolic health.
Wearable Devices handles the majority of throughput; Telehealth Platforms is the fastest mover on share.
Service Type:
Cost tier stratification separates capital-intensive screening infrastructure from high-margin digital coaching delivered at marginal cost near zero.
- Screening Services:Biometric assessment protocols combining laboratory diagnostics with imaging and genetic risk scoring. Payer incentive structures rewarding population-level risk reduction propel expansion among US insurance providers.
- Data Analytics:Predictive risk stratification engines processing claims, wearable telemetry, and social determinants. Health systems in Germany and France deploy these tools to satisfy EMA post-market clinical follow-up obligations for preventive algorithms.
- Risk Assessment:Actuarial and clinical models quantifying individual disease probability.
- Health Coaching:Behavioral intervention delivered through mobile applications and telephonic engagement.
- Immunization Programs:Population-scale vaccine administration and coverage tracking.
- Behavioral Therapy:Digital cognitive behavioral interventions for stress and anxiety prevention.
Screening Services commands the highest absolute spend; Data Analytics is expanding most quickly as evidence requirements stiffen.
Application:
Volume concentration tracks chronic disease burden, while margin expansion follows emerging reimbursement for mental wellness and occupational health categories.
- Chronic Disease Prevention:Continuous monitoring and intervention targeting diabetes, cardiovascular disease, and metabolic syndrome. Medicare's remote patient monitoring billing codes accelerate US health system deployment of wearable infrastructure.
- Early Detection:Genomic and biomarker surveillance intercepting oncological and neurological conditions prior to symptom onset. Japan's METI Silver Wellness incentives create procurement channels for telehealth-integrated screening platforms.
- Infectious Disease Control:Vaccination and syndromic surveillance for pathogen containment.
- Lifestyle Management:Nutrition, sleep, and physical activity optimization programs.
- Mental Wellness:Preventive psychological screening and stress management interventions.
- Occupational Health:Workforce-specific risk mitigation and regulatory compliance monitoring.
Chronic Disease Prevention handles the majority of throughput; Early Detection is climbing the fastest on policy tailwinds.
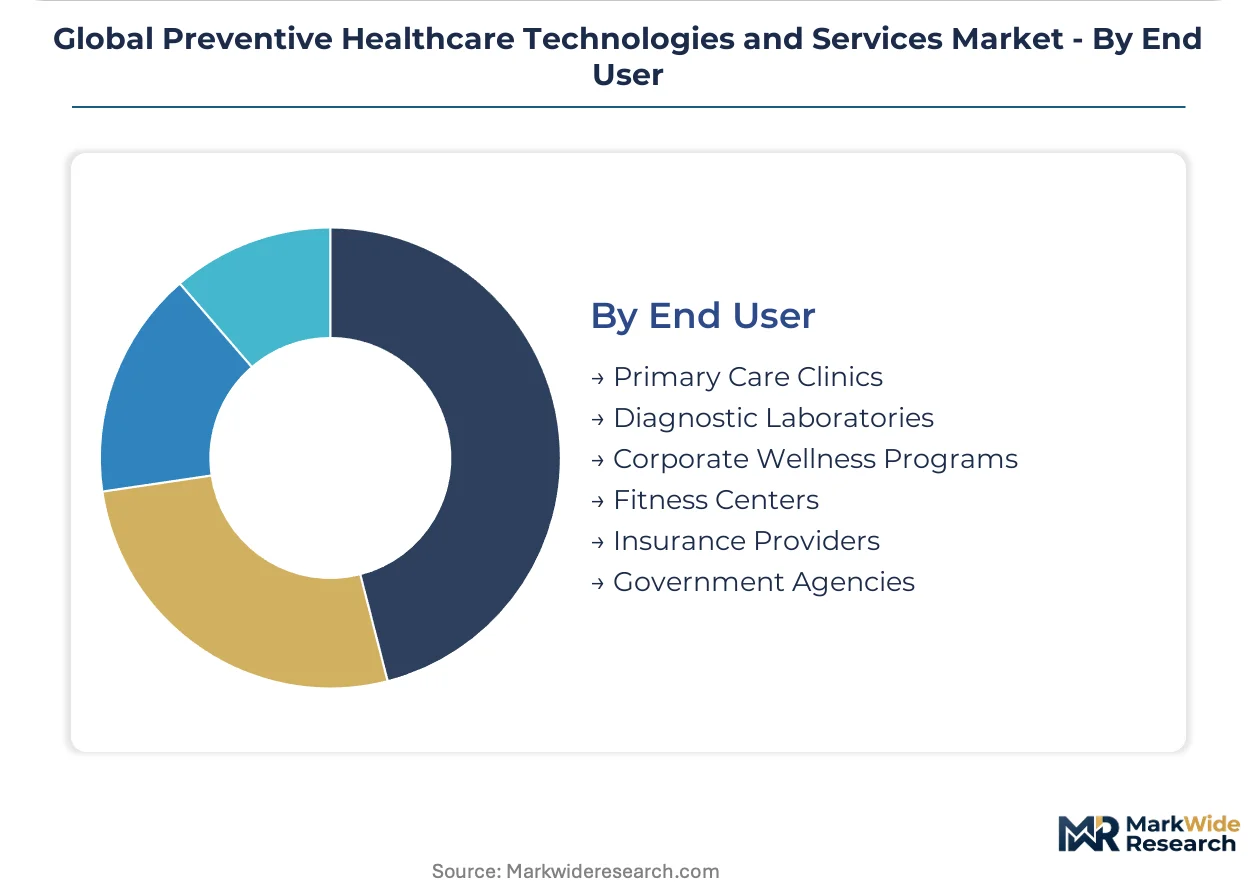
End User:
Customer type determines sales cycle length and procurement sophistication, from fragmented fitness center purchasing to consolidated government tender processes.
- Corporate Wellness Programs:Employer-sponsored biometric surveillance and virtual care integration for covered populations. Fortune 500 mandates in the United States compress sales cycles for integrated telehealth-screening bundles.
- Primary Care Clinics:Frontline delivery sites for preventive counseling and routine screening. India's tier-2 cities present openings for subscription-based remote patient monitoring leasing to mid-sized laboratories.
- Diagnostic Laboratories:Centralized processing facilities for biomarker and genetic analysis.
- Fitness Centers:Consumer-facing venues for basic physiological monitoring and coaching.
- Insurance Providers:Payer organizations designing benefit structures and risk adjustment.
- Government Agencies:Public health authorities managing population immunization and surveillance.
Corporate Wellness Programs handles the majority of throughput; Primary Care Clinics is gaining share fastest on emerging market infrastructure builds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
US employers extract pricing premiums from integrated telehealth-screening bundles that German manufacturers cannot match under stricter EMA compliance burdens. Japanese procurement channels reward longitudinal evidence generation that Indian subscription models bypass entirely.
United States
Fortune 500 self-insured corporations mandate continuous glucose monitoring and virtual primary care integration for covered populations. FDA 510(k) and De Novo pathways govern wearable diagnostic safety, though pathway backlogs extend time-to-revenue for sensor innovators. Silicon Valley and Seattle technology employers consolidate procurement through direct contracting with virtual primary care networks.
Germany
Health technology assessments now require real-world evidence generation for preventive screening algorithms seeking reimbursement. EMA Medical Device Regulation imposes post-market clinical follow-up obligations on wearable diagnostic manufacturers pursuing CE marking. Continuous glucose monitoring vendors establish prospective registry studies across Bavaria and Baden-Württemberg to satisfy clinical evidence requirements.
Japan
METI Silver Wellness incentives for elderly preventive care adoption create procurement channels for telehealth-integrated screening platforms. PMDA regulates software as medical device through risk-based classification that constrains algorithm deployment timelines. Kanto region health systems pilot ambient sensing architectures for cardiovascular surveillance in senior residential facilities.
India
Mid-sized diagnostic laboratories in tier-2 cities adopt subscription-based remote patient monitoring leasing to narrow capital barriers for enterprise-grade capabilities. CDSCO regulates in-vitro diagnostic kits through import license requirements that fragment market entry pathways. Maharashtra and Karnataka diagnostic clusters expand photoplethysmography-enabled screening infrastructure through equipment-as-a-service arrangements.
United Kingdom
NHS England procurement frameworks prioritize population-level risk reduction through biometric surveillance program deployment. MHRA operates post-Brexit regulatory autonomy that diverges from EMA MDR timelines for wearable device certification. London and Southeast England health systems integrate predictive analytics engines processing claims and wearable telemetry for risk stratification.
Global Preventive Healthcare Technologies and Services Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream capturing margin on sensor and assay supply. The vendor base concentrates around three strategic archetypes: vertically integrated diagnostic conglomerates with captive manufacturing, cloud-native telehealth platforms controlling employer channel access, and genomic screening specialists occupying defensible hereditary risk niches. Dominant competitive moves include backward integration into sensor fabrication and strategic partnerships with self-insured employers for direct contracting bypass.
Among US-based platform vendors, Teladoc Health and UnitedHealth Group anchor the virtual primary care integration tier, each representing distinct employer channel control strategies. Myriad Genetics exemplifies the genomic screening specialist archetype, occupying hereditary cancer risk assessment as a defensible niche against broader diagnostic portfolios. Abbott Laboratories sits within the vertically integrated tier through captive sensor manufacturing that sustains price competitiveness in continuous glucose monitoring.
| Leading Market Players |
|---|
| Merck & Co. Inc. |
| Pfizer Inc. |
| GlaxoSmithKline plc |
| Medtronic plc |
| Abbott Laboratories |
| Teladoc Health |
| UnitedHealth Group |
| McKesson Corporation |
| Myriad Genetics |
| Others |
Supply & Pricing Matrix
The Shanghai-Los Angeles transpacific freight corridor absorbs semiconductor and biosensor cargo flows, with container rate volatility transmitting directly into landed costs for continuous glucose monitoring hardware. This logistics chokepoint amplifies price differentiation between vertically integrated manufacturers holding captive sensor fabrication and contract-dependent assemblers exposed to spot-market component costs.
Pricing Analysis
Self-insured employer procurement anchors a three-tier pricing structure across premium, standard, and economy levels in the preventive health platform market. Price differentiation stems from FDA 510(k) certification tier and enterprise-scale deployment volume, with Fortune 500 direct contracting commanding steepest discounts. Cost compression in the economy tier is intensifying because photoplethysmography sensor commoditization enables sub-$50 consumer alternatives. Diagnostic laboratories exhibit highest price sensitivity, while integrated telehealth-screening bundles show inelastic demand among technology sector employers.
Supply Chain Analysis
Taiwan Semiconductor Manufacturing and Foxconn Electronics concentrate contract manufacturing capacity for biosensor ASICs and wearable device assembly. Component sourcing draws from Taiwanese foundries for photoplethysmography chips, South Korean display panels, and Chinese lithium-polymer cells. Single-source vulnerability in Taiwan-dominant fabrication creates input risk for continuous monitoring producers. Distribution runs through direct contracting with self-insured employers and GPO-negotiated hospital system agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Preventive healthcare incumbents face substitution pressure from AI-native diagnostics platforms that collapse the distinction between screening and treatment initiation. Defense requires consolidating control over data architecture and employer channel relationships before algorithmic care navigation displaces traditional platform vendors.
For Market Incumbents: Entrench position through backward integration into photoplethysmography sensor fabrication and exclusive contracting with self-insured employers for biometric surveillance program deployment. Threat from cloud-native telehealth entrants demands channel control investment. Priority lever sits with Medicare reimbursement strategy for remote patient monitoring codes.
For New Entrants and Emerging Players: Build out presence in India's tier-2 diagnostic laboratory market through subscription-based remote patient monitoring leasing models. White space concentrates in mid-sized laboratories lacking capital for enterprise-grade infrastructure. Go-to-market angle leverages equipment-as-a-service arrangements bypassing upfront procurement cycles.
For Investors and Strategic Acquirers: Genomic screening specialists with hereditary cancer risk assessment capabilities offer acquisition exposure to high-margin niche defensibility against broader diagnostic portfolios. Long-term viability favors platforms integrating AI-photoplethysmography convergence for cuffless cardiovascular monitoring. Signal to watch is FDA De Novo pathway clearance velocity for novel wearable diagnostics.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerates time-to-revenue for photoplethysmography-enabled arrhythmia detection wearables in employer wellness deployments. |
| CE Marking Pathway | Unlocks German and French procurement channels under EMA MDR post-market clinical follow-up obligations. |
| Hospital System Partnership | Secures channel access for telehealth-integrated screening platforms through GPO contract consolidation. |
| Software Companion Development | Enables HIPAA-compliant data ingestion from wearable sensors into EHR architectures via HL7 FHIR integration. |
| Reimbursement Strategy | Captures Medicare remote patient monitoring billing codes driving US health system infrastructure deployment. |
Research Methodology
Initial hypotheses were tested against primary input from biomedical engineers, hospital purchasing committee members, GPO contracts managers, and employer benefits directors and refined through secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and EMA CE marking registries. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the preventive healthcare technology stack.
Demand-supply balance modeling anchored the analytical framework across the projection horizon, with segmentation dimensions spanning product type, service type, application, and end user. CAGRs derived from regression analysis of historical adoption curves adjusted for regulatory inflection points. Forecast inputs incorporated Medicare reimbursement code expansion velocity and employer mandate density metrics.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by diagnostic conglomerates or rapid AI-photoplethysmography convergence by technology entrants would shift outcomes beyond modeled boundaries. Quarterly review of FDA De Novo pathway backlog duration and employer direct contracting announcement velocity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
Digital Patient Engagement Solutions Market
Digital Health Solutions
Connected Healthcare Market
Digital Health Solutions
Medical Virtual Reality Operating Systems Market
Digital Health Solutions
Asia-Pacific Heart Failure Software Market
Digital Health Solutions
Digital Assistants in Healthcare Market
Digital Health Solutions
Artificial Intelligence in Medicine Market
Digital Health Solutions
Global Clinical Decision Support System Market
Digital Health Solutions
VR in Healthcare Market
Digital Health Solutions
Global Physical Therapy Software Market
Digital Health Solutions
Amblyopia Treatment Softwares Market
Digital Health Solutions
Connected Health and Wellness Devices Market
Digital Health Solutions
Mhealth Apps Market
Digital Health Solutions
Mobile Tablets in Healthcare Market
Digital Health Solutions
Patient Engagement Platforms Market
Digital Health Solutions
Pharmacovigilance (PV) and Drug Safety Software Market
Digital Health Solutions
Lifestyle Diseases Apps Market