
 Artificial Intelligence (AI) Accelerator Market | 2026-2036
Artificial Intelligence (AI) Accelerator Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Intelligence (AI) Accelerator Market Outlook
Hyperscale cloud operators is collapsing the traditional enterprise server procurement model that long dominated AI accelerator deployment. NVIDIA anchors the training segment through its vertically integrated CUDA ecosystem and foundry partnerships. AMD competes aggressively on price-performance for inference workloads in data center environments. Qualcomm positions its accelerator portfolio at the edge, targeting power-constrained robotics and autonomous systems with custom ASIC architectures.
An artificial intelligence accelerator is a specialized computational processor architected to execute matrix multiplication, tensor operations, and neural network inference at throughput levels exceeding general-purpose CPUs by orders of magnitude, typically fabricated on advanced nodes with high-bandwidth memory integration. Its primary commercial purpose is to reduce latency and energy consumption for machine learning workloads across cloud, edge, and embedded deployments. GPU product types currently dominate revenue volumes given their programmability across training and inference stages, while ASIC designs capture expanding share in hyperscale inference where workload specificity permits die-area optimization. Deep learning technology applications anchor current shipments, though natural language processing demand is accelerating with transformer-model proliferation across enterprise and consumer platforms.
The US Department of Commerce export controls and the EU AI Act create divergent compliance frameworks that fragment product roadmaps and regional availability for accelerator vendors. China's MIIT domestic substitution mandates and SAMR antitrust scrutiny further constrain cross-border deployment patterns for training clusters. Stakeholders must monitor how sovereign compute initiatives and chip-specific trade restrictions reshape supply chain geography and customer access rules without warning.
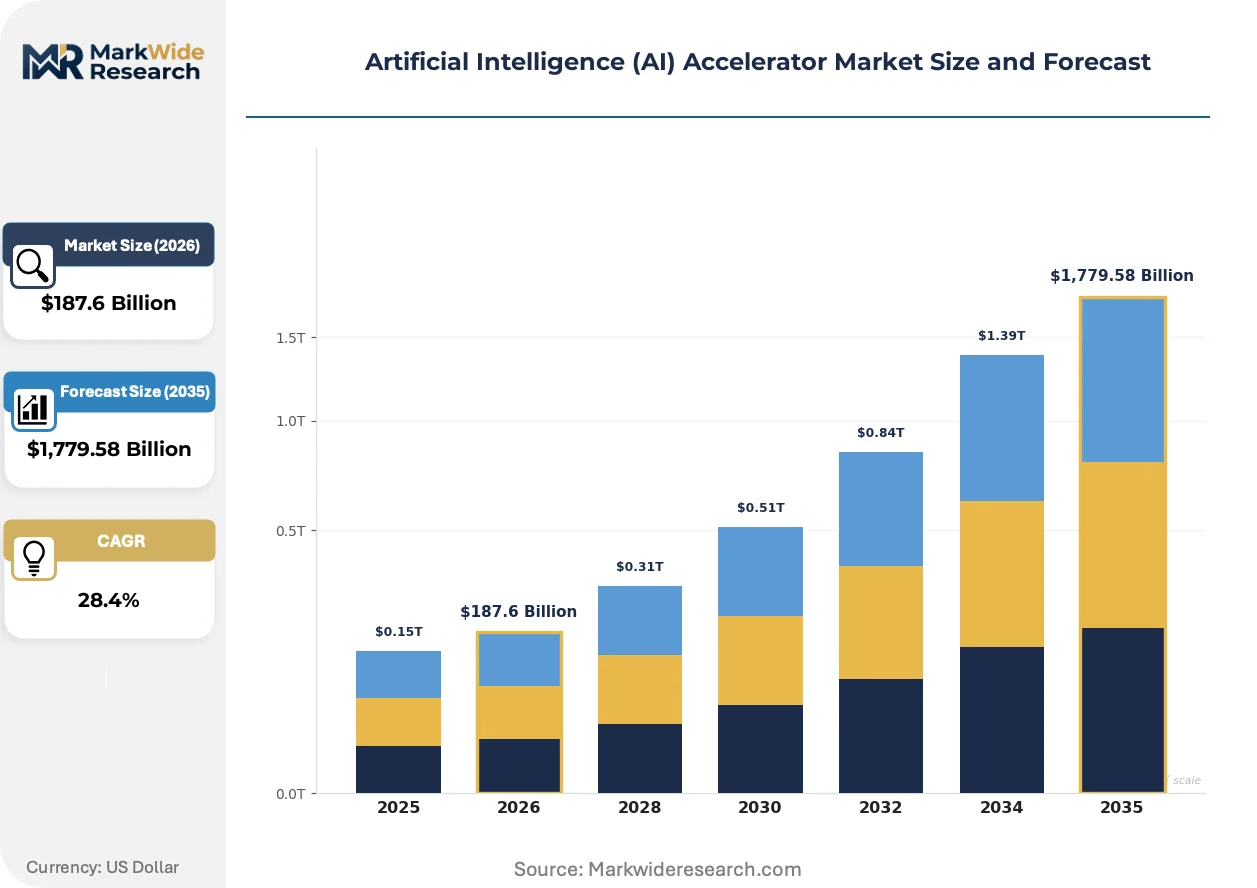
Market Dynamics
Hyperscale cloud operators are consolidating procurement power around sovereign AI mandates, forcing accelerator vendors to fragment product roadmaps across export-controlled and open-market variants. This structural tension between scale economics and geopolitical compartmentalization now governs capacity planning, foundry allocation, and customer access rules.
Growth Catalysts
- Transformer-model proliferation:Natural language processing workloads are expanding accelerator attach rates in enterprise data centers beyond traditional computer vision deployments.
- US CHIPS Act incentives:Domestic fabrication subsidies are reshoring advanced packaging capacity for training-class GPUs and HBM integration.
- EU AI Act compliance requirements:Risk-classification mandates for high-stakes AI systems are creating certified-hardware procurement specifications across financial and healthcare sectors.
Market Restraints
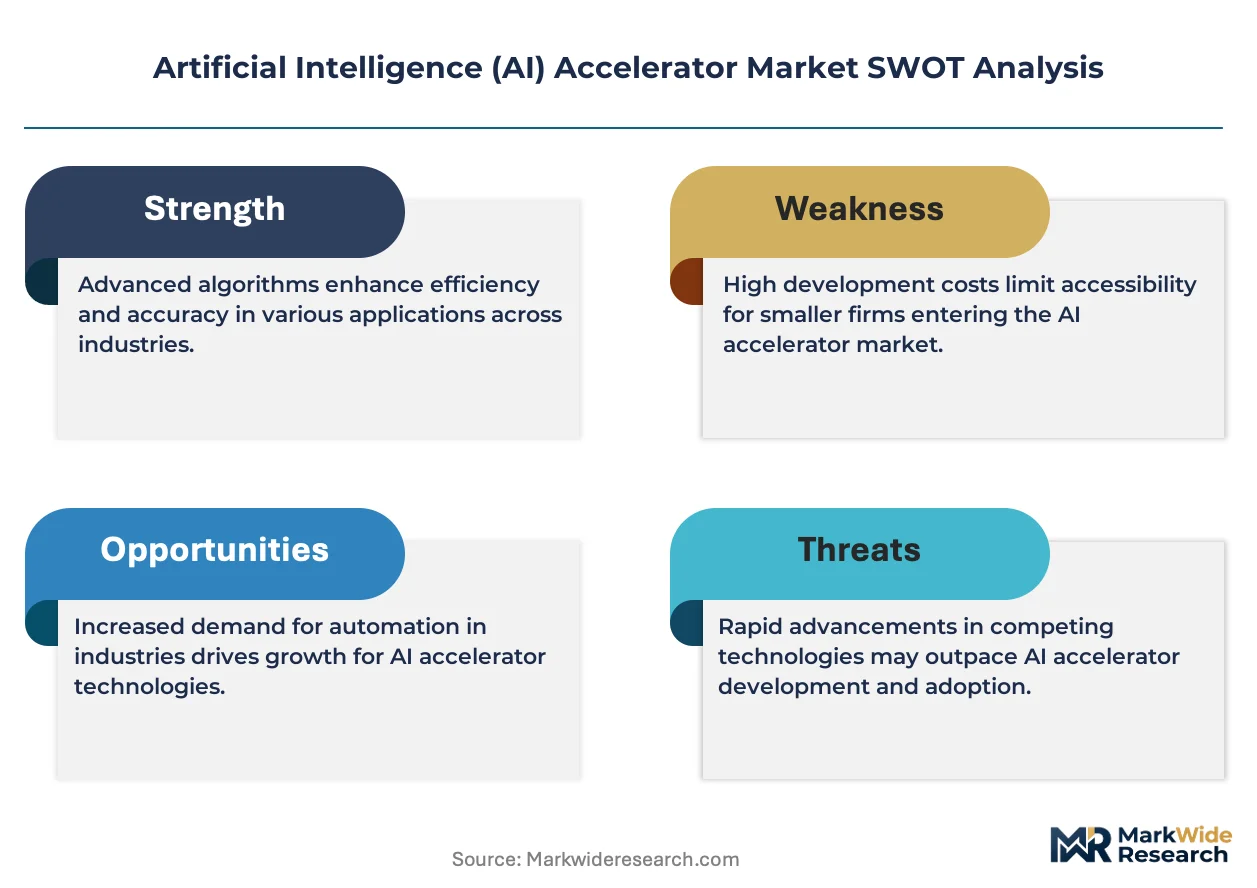
- Advanced node concentration:Taiwan-based foundry dominance in 5nm and below processes creates single-point-of-failure exposure for leading-edge accelerator supply.
- HBM supply bottleneck:High-bandwidth memory die stacking yields constrain output volumes for training-class accelerators regardless of logic wafer availability.
- US Commerce Department export controls:Chip-specific licensing thresholds are severing Chinese hyperscalers from training-cluster procurement channels.
Strategic Opportunities
- Edge robotics integration:Power-constrained autonomous systems in warehouse and agricultural environments are opening ASIC-optimized accelerator sockets below 75W TDP.
- India PLI scheme for electronics:Domestic assembly incentives are attracting packaging and test investments for inference accelerators serving South Asian cloud regions.
- Photonic interconnect convergence:Co-packaged optical I/O is enabling rack-scale training clusters beyond copper trace limitations in hyperscale facilities.
Industry Challenges
- CUDA software stack portability:Kernel optimization expertise concentrated around NVIDIA's proprietary ecosystem creates vendor-switching friction for enterprise AI teams.
- Multi-die thermal management:Chiplet-based accelerator designs are encountering package-level heat dissipation limits that degrade sustained throughput in dense server configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Intelligence (AI) Accelerator Market |
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $1,779.58 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: GPU, TPU, FPGA, ASIC Technology: Machine Learning, Deep Learning, Natural Language Processing, Computer Vision Use Case: Robotics, Autonomous Vehicles, Healthcare Analytics, Fraud Detection End User: SMEs, Large Enterprises, Research Institutions, Government Agencies |
| Companies Covered | Google, Groq, NVIDIA, Graphcore, Cerebras, AMD, Amazon Web Services, Qualcomm, Intel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Intelligence (AI) Accelerator Market Strategic Shifts
Accelerator architectures are bifurcating between monolithic training engines and disaggregated inference tiles, with interconnect technology and memory hierarchy becoming the primary differentiation vectors. This hardware specialization is compressing general-purpose server refresh cycles.
Custom ASIC designs optimized for transformer inference are displacing programmable GPU allocations in hyperscale recommendation and search workloads. Google, Amazon Web Services, and Microsoft are deploying internally developed silicon for stable, high-volume model serving. This captive silicon strategy is compressing merchant accelerator margins in the largest addressable inference sockets.
EU AI Act risk-tier classification is mandating traceability and auditability features in high-stakes deployment hardware. Accelerator vendors must now embed logging, attestation, and deterministic execution modes to serve European financial, healthcare, and public-sector buyers. Germany's KBA and France's CNIL are issuing complementary technical guidance that fragments compliance testing requirements.
Hyperscale buyers are consolidating procurement around direct foundry relationships and custom silicon development, bypassing traditional server OEM channels. Dell, HPE, and Lenovo are losing attach rate in training-cluster sales as cloud operators source bare accelerators for self-integrated racks. This disintermediation is most advanced in US and Chinese facilities, where vertical integration into system design is now standard practice.
Artificial Intelligence (AI) Accelerator Market Segmentation
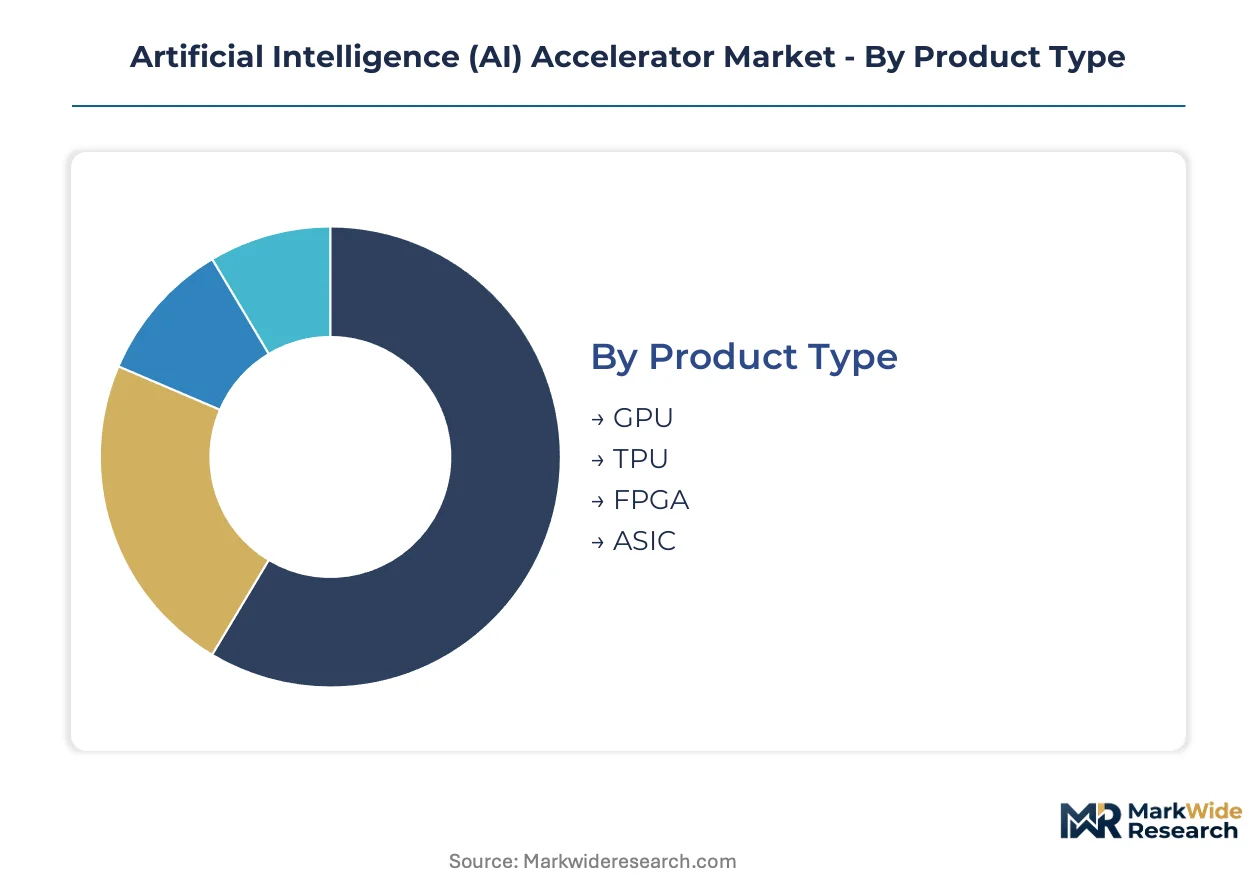
Accelerator procurement patterns diverge sharply across deployment contexts, with workload specificity dictating silicon selection. Vendors must architect product portfolios that span programmable training engines through fixed-function inference tiles without fragmenting R&D economies.
Product Type:
ASIC designs exert the strongest substitution pressure on legacy programmable architectures as hyperscale operators pursue die-area optimization for stable inference workloads.
- GPU:General-purpose parallel processors with CUDA programmability dominate training clusters and research environments. NVIDIA's foundry partnerships and memory integration anchor procurement in United States hyperscale facilities where transformer-model training concentrates.
- ASIC:Custom silicon eliminates redundant logic for specific neural network topologies, slashing power and cost per inference. Google and Amazon Web Services deploy captive TPU and Inferentia designs across their data center footprints, compressing merchant accelerator margins in high-volume search and recommendation sockets.
- TPU:Google's tensor processing unit exemplifies domain-specific acceleration for matrix-heavy workloads.
- FPGA:Reconfigurable logic serves prototype-to-production pipelines and low-volume specialized inference.
GPU retains volume leadership; ASIC holds the steepest expansion curve.
Technology:
Cost tier stratification separates premium training-class silicon from edge-optimized inference engines serving power-constrained deployments.
- Deep Learning:Multi-layer neural network training and inference consume the majority of high-bandwidth memory-equipped accelerator shipments. United States cloud operators anchor demand for convolutional and recurrent architectures in computer vision and speech recognition pipelines.
- Natural Language Processing:Transformer-based large language models are accelerating attach rates for tensor-optimized silicon in enterprise data centers. Attention mechanisms and billion-parameter architectures strain memory bandwidth, favoring accelerators with HBM integration and optical interconnect support.
- Machine Learning:Traditional statistical methods and shallow networks persist in legacy enterprise analytics.
- Computer Vision:Image classification and object detection workloads concentrate in automotive and industrial inspection applications.
Deep Learning commands the largest revenue base; Natural Language Processing is climbing the fastest.
Use Case:
Application maturity determines whether buyers accept fixed-function ASICs or demand programmable architectures that evolve with model architectures.
- Autonomous Vehicles:Multi-sensor fusion and real-time path planning impose latency constraints that favor low-precision tensor cores and deterministic execution. Development fleets in California and Arizona consume training-class GPUs for simulation, while production intent targets sub-75W ASICs for cabin and edge compute.
- Healthcare Analytics:Diagnostic imaging and drug discovery workloads require both training-scale clusters and regulated inference deployment. FDA scrutiny of AI-enabled medical devices creates certified-hardware procurement specifications that favor vendors with quality management systems and traceable supply chains.
- Robotics:Warehouse automation and agricultural systems prioritize power efficiency over raw throughput.
- Fraud Detection:Financial services deploy real-time transaction scoring across distributed inference nodes.
Healthcare Analytics sustains premium pricing; Autonomous Vehicles is gaining share fastest.
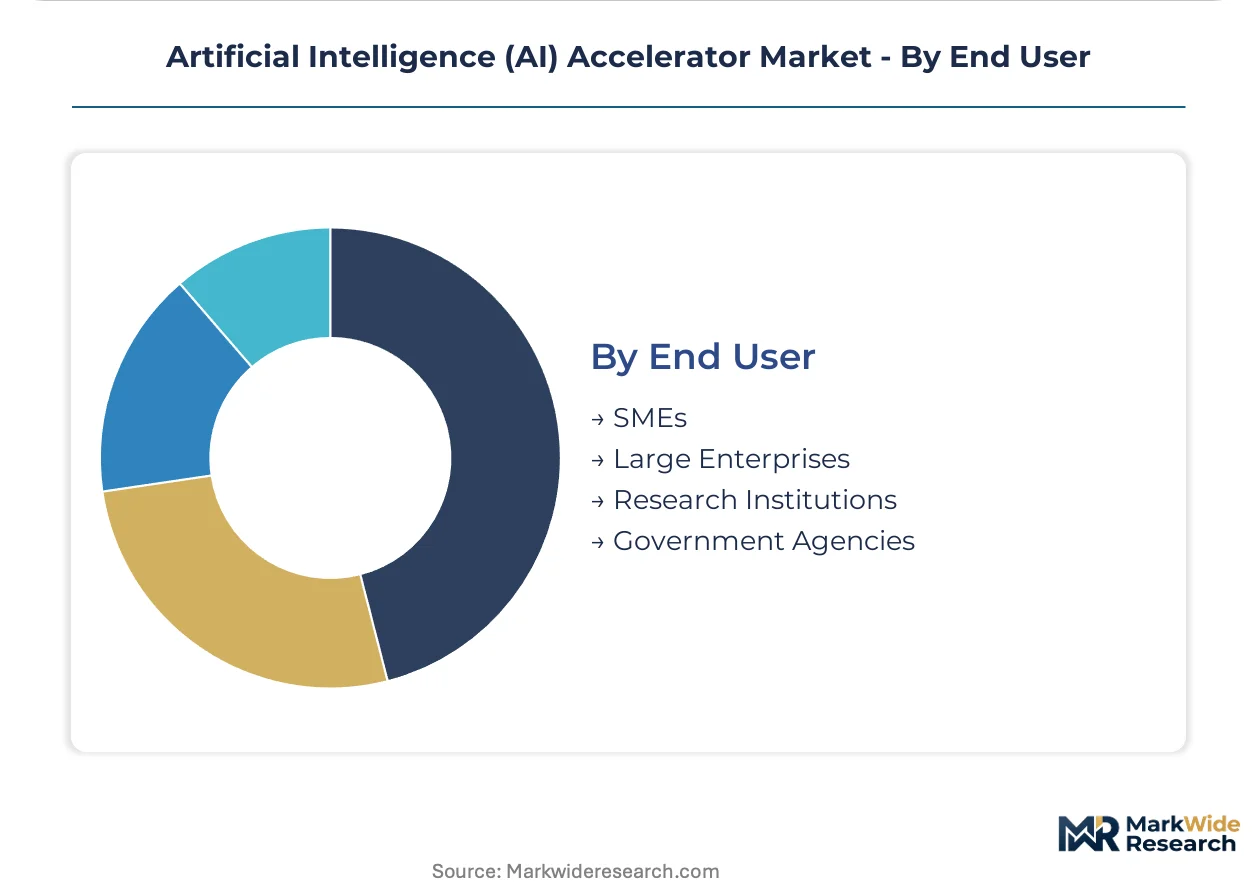
End User:
Customer type dictates procurement channel structure, with direct foundry relationships displacing traditional server OEM intermediation at the largest scale tiers.
- Large Enterprises:Fortune 500 technology, financial services, and healthcare operators maintain dedicated AI infrastructure teams that source bare accelerators for self-integrated racks. Procurement concentrates in United States and Chinese facilities where vertical integration into system design is now standard practice.
- Research Institutions:National laboratories and university consortia access accelerators through federal grants and shared computing allocations. United States Department of Energy facilities and NSF-funded centers anchor demand for training-class GPU clusters with Infiniband interconnect.
- SMEs:Mid-market buyers rely on cloud rental and managed services rather than capital deployment.
- Government Agencies:Defense and intelligence applications impose security and supply chain constraints that fragment product availability.
Large Enterprises dominate procurement volume; Research Institutions maintain the steepest infrastructure expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwan-based foundries ship the majority of advanced-node silicon to United States hyperscale operators, creating a trade corridor that concentrates training-class accelerator supply in North American cloud facilities despite fabrication occurring offshore.
United States
Hyperscale cloud operators anchor procurement for transformer-model training clusters, with demand concentrating in Northern Virginia and Oregon data center hubs. The Department of Commerce export controls fragment product availability for Chinese-bound shipments. NVIDIA's CUDA-integrated foundry partnerships dominate supply to San Francisco Bay Area and Seattle metro facilities.
China
Domestic hyperscalers face severed access to training-class GPUs under US licensing thresholds, accelerating MIIT substitution mandates for indigenous accelerator development. SAMR antitrust scrutiny constrains cross-border technology licensing. Yangtze River Delta clusters in Shanghai and Hangzhou concentrate captive ASIC design for inference workloads.
Germany
Automotive OEMs and industrial automation drive demand for power-constrained edge accelerators in Bavaria and Baden-Württemberg manufacturing corridors. The KBA issues technical guidance on deterministic execution for autonomous systems hardware. Berlin-Brandenburg research consortia access training clusters through federal HPC allocations.
India
PLI scheme incentives attract packaging and test investments for inference accelerators serving South Asian cloud regions. Domestic cloud operators expand procurement for natural language processing workloads in local languages. Karnataka's Bengaluru cluster anchors system integration for data center deployments.
United Kingdom
Financial services and pharmaceutical sectors generate certified-hardware demand under emerging auditability frameworks. London-based hedge funds and algorithmic trading operations deploy low-latency inference accelerators. Greater Manchester and Cambridge research partnerships access GPU clusters through UKRI funding streams.
Artificial Intelligence (AI) Accelerator Market Competitive Environment
Player mix skews toward vertically integrated hyperscale operators with captive silicon programs alongside merchant semiconductor vendors with foundry-dependent supply chains. The structure concentrates training-class supply around CUDA-integrated ecosystems while fragmenting inference allocation across ASIC and programmable alternatives. Two archetypes dominate: cloud operators with internal silicon design teams, and fabless semiconductor vendors licensing IP blocks. Competitive moves center on foundry capacity reservation and strategic partnerships for advanced packaging.
Within the cloud-operator tier, Google, Amazon Web Services, and NVIDIA represent divergent approaches to accelerator supply. Google and Amazon Web Services exemplify the captive silicon archetype through internally developed tensor processing and inference-optimized designs. NVIDIA occupies a position as the dominant merchant vendor with vertically integrated software stacks. AMD sits within the challenger tier competing on price-performance metrics for data center inference deployments.
| Leading Market Players |
|---|
| Groq |
| NVIDIA |
| Graphcore |
| Cerebras |
| AMD |
| Amazon Web Services |
| Qualcomm |
| Intel |
| Others |
Value Chain & Pricing Dynamics
Twenty-six-week lead times for advanced-node wafers concentrate pricing power with Taiwan-based foundry operators, while HBM die stacking yields constrain training-class accelerator availability regardless of logic wafer supply. This structural tightness rewards vendors with captive foundry relationships and long-term capacity reservations.
Pricing Analysis
Current-generation training-class GPUs command substantial premiums over prior-generation inference-optimized silicon, while next-generation chiplets with co-packaged optics are entering at premium-mid-economy pricing differentiation. Pricing stratifies across premium, standard, and economy tiers based on memory bandwidth tier and CUDA ecosystem certification level. Cost compression in standard-tier inference accelerators is intensifying because hyperscale captive silicon programs displace merchant volumes. SMEs exhibit highest price sensitivity through cloud rental preferences, while sovereign AI mandates make government buyers least sensitive to unit cost.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication for advanced-node logic and HBM memory respectively, while the United States concentrates advanced packaging capacity through CHIPS Act reshoring incentives. The supply chain draws from cobalt and tantalum for interconnect metallization, photoresist chemicals for lithography, and specialized substrates for 2.5D/3D integration. Single-source vulnerability in 5nm and below foundry capacity creates exposure to trade restriction disruption. Distribution runs through direct foundry relationships for hyperscale operators and server OEM channels for enterprise buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Accelerator procurement is shifting toward service-attach models where software licensing and managed inference workloads expand recurring revenue faster than bare silicon sales. This service-layer expansion outpaces hardware shipment growth across hyperscale and enterprise deployment contexts.
For Market Incumbents: Secure multi-year foundry capacity reservations at 3nm and below nodes to defend against AMD and Intel foundry partnerships. Deepen backward integration into advanced packaging to capture margin from HBM integration and substrate supply. Lock in certification pathways under EU AI Act and FDA device frameworks to create switching costs for regulated buyers facing custom silicon alternatives.
For New Entrants and Emerging Players: Anchor in edge robotics and warehouse automation sockets below 75W TDP where NVIDIA's training-optimized portfolio lacks power efficiency. Target India's PLI scheme assembly incentives for inference accelerator packaging serving South Asian cloud regions. Pursue photonic interconnect partnerships with hyperscale operators seeking rack-scale optical I/O differentiation.
For Investors and Strategic Acquirers: Long-term, this sits as a captive silicon consolidation play because hyperscale operators with internal design teams are compressing merchant margins in high-volume inference sockets. Acquisition targets should exhibit domain-specific ASIC architectures for stable transformer workloads. The signal to watch is export control threshold adjustments that fragment product roadmaps into controlled and open-market variants.
| Strategic Initiative | Industry Significance |
|---|---|
| Custom Silicon Development | Google and Amazon Web Services deploy captive TPU and Inferentia designs across hyperscale footprints. |
| Advanced Packaging Investment | CHIPS Act subsidies reshore HBM integration capacity for training-class GPU supply security. |
| Photonic Interconnect Partnership | Co-packaged optical I/O enables rack-scale training clusters beyond copper trace limitations. |
| Regulatory Certification Pathway | EU AI Act mandates embed logging and attestation features for European financial sector procurement. |
| Edge ASIC Optimization | Power-constrained robotics applications open sockets below 75W TDP for Qualcomm and emerging entrants. |
Study Parameters
A standing panel of hyperscale infrastructure executives, semiconductor foundry account managers, AI research lab directors, and server OEM procurement leads provided ongoing calibration throughout the study period. Primary interviews with these stakeholders combined with secondary validation against SEC hyperscaler capex disclosures, foundry utilization reports, and customs trade data. Bottom-up shipment modeling and top-down demand aggregation triangulated volume estimates across the analysis window.
Consistency checks validated outputs against external benchmarks including hyperscaler infrastructure spending disclosures and foundry revenue breakdowns by node. Segmentation modeling spanned product type, technology application, use case maturity, and end-user scale tier across the projection horizon. CAGRs derived from fitted growth curves incorporating transformer-model proliferation rates, sovereign AI mandate implementation timelines, and export control threshold adjustments. Industry-specific inputs included HBM supply forecasts and advanced packaging capacity buildout schedules.
Decision-makers should treat outputs as directional under assumptions of sustained transformer-model training demand and stable foundry capacity allocation; material deviation in either driver would warrant model refresh. Recalibration cycles align with material shifts in US Commerce Department licensing thresholds, EU AI Act implementation guidance, and foundry node transition schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
North America Conversational AI Market
Artificial Intelligence (AI)
Edge AI Software Market
Artificial Intelligence (AI)
Neural Network Market
Artificial Intelligence (AI)
Intelligent Assistant Embedded Consumer Devices Market
Artificial Intelligence (AI)
Artificial Intelligence in Robots Market
Artificial Intelligence (AI)
Generative AI Market
Artificial Intelligence (AI)
Global Ambient Intelligence Market
Artificial Intelligence (AI)
Europe Generative AI Market
Artificial Intelligence (AI)
Enterprise Generative AI Market
Artificial Intelligence (AI)
Embedded Intelligence Market
Artificial Intelligence (AI)
Artificial Intelligence in Workspace Market
Artificial Intelligence (AI)
Autonomous Agents Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in BFSI Market
Artificial Intelligence (AI)
Far-Field Speech and Voice Recognition Market
Artificial Intelligence (AI)
Automotive Gesture Recognition Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Automotive Market