
 Neural Network Market | 2026-2036
Neural Network Market Size, Share, and Industry Trends Forecast 2026-2036
Neural Network Market Intelligence
Asset-light leasing models for GPU clusters are reshaping competitive entry in neural network training, allowing mid-sized enterprises to bypass billion-dollar capital expenditures. NVIDIA Corporation dominates high-performance silicon supply through captive foundry partnerships and proprietary interconnect standards. Google LLC leverages its TPU infrastructure and data center scale to sustain price advantages on long-horizon model training contracts. Microsoft Corporation anchors enterprise distribution through Azure's co-selling agreements with Fortune 500 IT departments.
A neural network consists of layered artificial neurons with weighted connections trained via backpropagation to minimize loss functions, typically requiring tensor-processing hardware with high-bandwidth memory and parallel compute architectures. These systems perform pattern recognition, prediction, and generative tasks across industrial automation, financial risk modeling, and clinical decision support. Image recognition applications occupy mature margin pools in security and autonomous systems, while natural language processing segments attract the fastest-growing enterprise software budgets. Cloud-based deployment leads volume, though edge computing configurations are gaining traction in latency-sensitive manufacturing and telecommunications use cases.
The Federal Trade Commission scrutinizes training-data sourcing practices, while the EU AI Act imposes conformity assessments on high-risk neural network deployments in healthcare and finance. China's SAMR enforces algorithmic recommendation regulations that shape product architectures for models serving consumer platforms. Stakeholders must monitor diverging compliance cost structures across jurisdictions when selecting training locations and customer segments.
Market Dynamics
GPU cluster leasing models are collapsing capital barriers for mid-sized enterprises, forcing hyperscalers to defend pricing power through long-horizon training contracts rather than hardware dominance alone.
Growth Catalysts
- EU AI Act conformity assessments:Healthcare and finance enterprises now mandate explainable model architectures, creating procurement pull for audit-ready neural network platforms.
- Diagnostic imaging workloads:Hospital systems deploy convolutional networks for radiology screening, accelerating FDA 510(k) clearance timelines for computer-aided detection tools.
- Cloud inference services:Manufacturing and telecommunications operators adopt edge-deployed neural networks for latency-sensitive quality control and predictive maintenance.
Market Restraints
- High-bandwidth memory supply concentration:Foundry capacity for HBM3 and HBM3E stacks concentrates in South Korea and Taiwan, exposing training infrastructure procurement to geopolitical disruption.
- Training data licensing friction:FTC scrutiny of web-scraped datasets forces enterprises into expensive synthetic data generation or negotiated content licensing.
- Transformer architecture saturation:State-space models and recurrent alternatives challenge attention-based scaling laws, threatening incumbent hardware-software co-optimization investments.
Strategic Opportunities
- India's semiconductor PLI scheme:Domestic GPU assembly and packaging incentives attract design houses seeking to diversify supply chains beyond East Asian concentration.
- Neuromorphic silicon convergence:Spiking neural network hardware paired with event-based sensors opens ultra-low-power inference for battery-constrained industrial IoT.
- Asset-light federated learning:Pharmaceutical consortiums adopt privacy-preserving distributed training, bypassing centralized data aggregation and cross-border transfer restrictions.
Industry Challenges
- MLops talent scarcity:Pipeline engineering and model observability functions command premium compensation, constraining deployment velocity for non-technology enterprises.
- Interoperability with legacy SCADA:Manufacturing neural network deployments require costly protocol translation layers for brownfield automation infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neural Network Market |
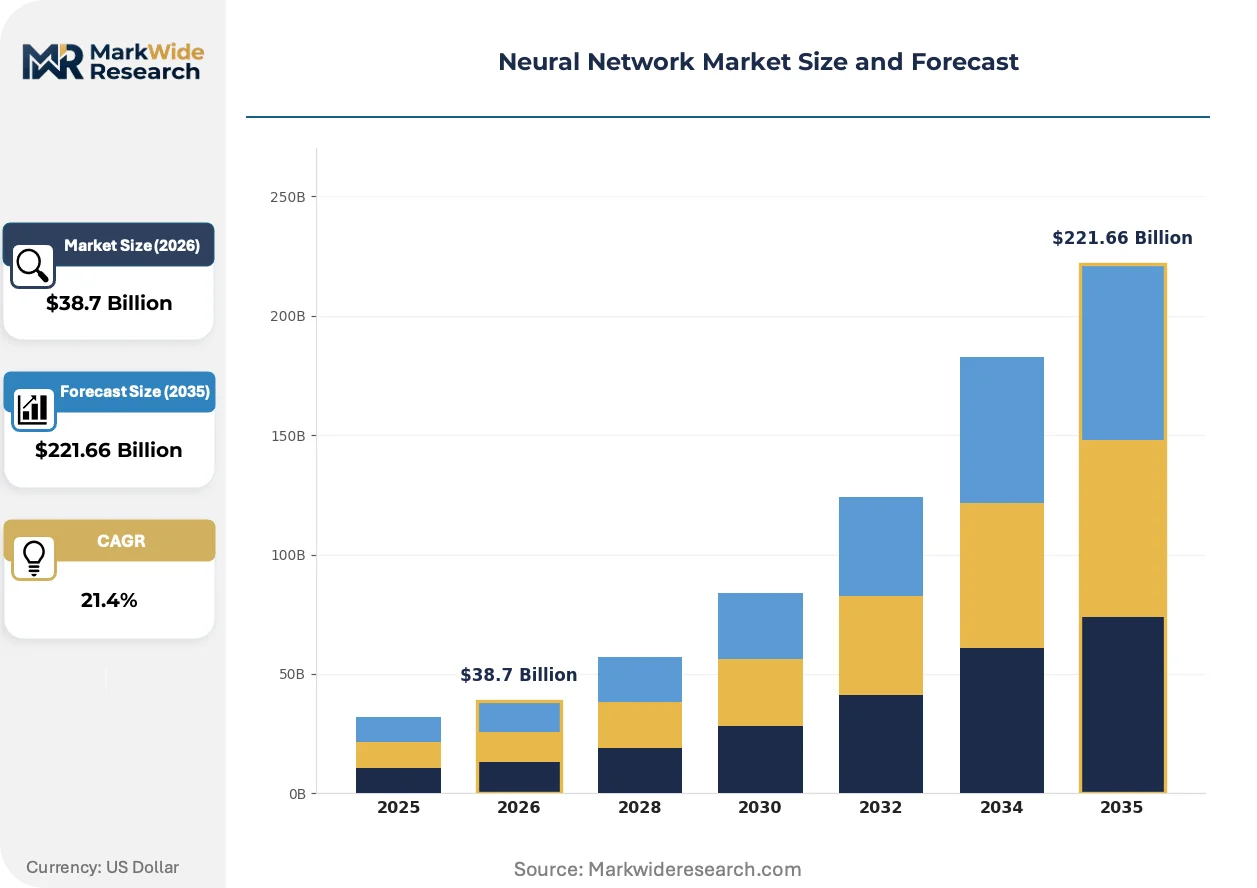
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $221.66 Billion |
| CAGR (2026 – 2036) | 21.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Image Recognition, Natural Language Processing, Fraud Detection, Predictive Analytics Deployment: Cloud-based, On-premises, Hybrid, Edge Computing End User: Healthcare, Finance, Retail, Telecommunications Technology: Deep Learning, Convolutional Neural Networks, Recurrent Neural Networks, Generative Adversarial Networks |
| Companies Covered | NVIDIA Corporation, Google LLC, Microsoft Corporation, IBM Corporation, Amazon Web Services, Inc., Intel Corporation, OpenAI, Huawei Technologies Co., Ltd., Baidu, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neural Network Market Strategic Shifts & Innovations
Foundation model commoditization is compressing value capture toward specialized fine-tuning layers and proprietary data moats, while hardware efficiency gains outpace algorithmic scaling demands.
Mixture-of-experts architectures are collapsing training cost curves for trillion-parameter models. Enterprise software vendors adopt sparse activation patterns to serve Fortune 500 contracts without proportional compute expansion. This efficiency surge is collapsing the historical correlation between model capability and capital expenditure, enabling mid-market SaaS providers to compete on task-specific performance rather than scale.
The EU AI Act's high-risk system registry imposes pre-market conformity assessments on clinical decision support and credit scoring neural networks. German and French notified bodies are certifying quality management systems for algorithmic transparency. Healthcare providers in the Netherlands and Sweden are restructuring procurement specifications to mandate explainability documentation ahead of enforcement deadlines.
Buyers are consolidating training contracts under multi-year reserved capacity agreements with single hyperscalers, abandoning spot-instance arbitrage. Financial services firms in Singapore and Switzerland negotiate fixed-price inference tiers covering model versioning and regulatory update cycles. This preference compression favors cloud providers with integrated compliance tooling over bare-metal alternatives.
Neural Network Market Segmentation
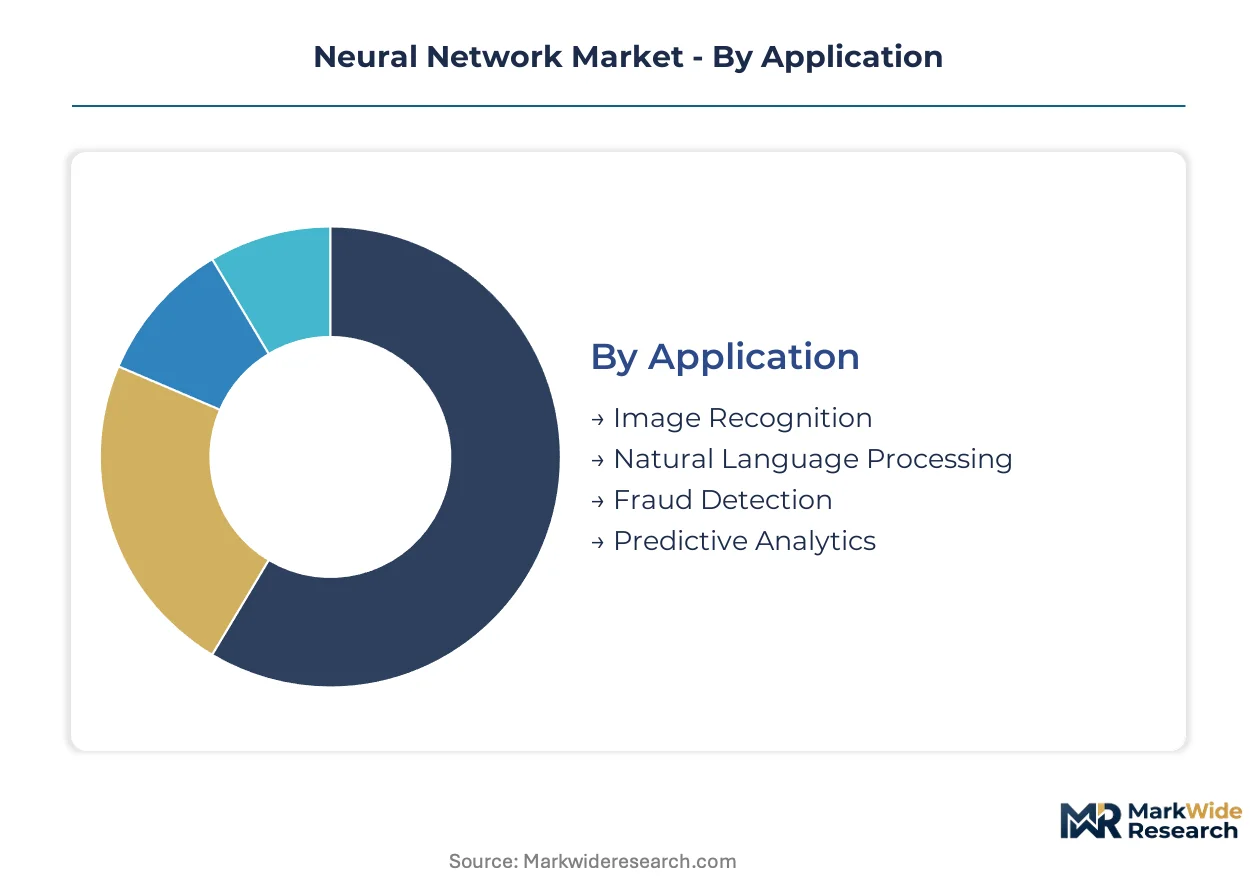
Neural network architectures diverge sharply across inference latency requirements, data sovereignty constraints, and regulatory exposure profiles. Procurement patterns cluster around deployment topology and end-use risk classification rather than raw model capability.
Application:
Use-case spectrum spans mature computer vision workloads to emergent generative interfaces, with divergence in hardware requirements and compliance overhead.
- Image Recognition:Convolutional architectures process visual inputs for quality control, security screening, and autonomous navigation. Manufacturing lines in Germany and Japan deploy these systems for defect detection, constrained by FDA 510(k) timelines for clinical variants.
- Natural Language Processing:Transformer-based models handle text generation, sentiment analysis, and document classification. Enterprise software budgets in the United States and United Kingdom concentrate here, driven by EU AI Act documentation mandates for high-risk deployments.
- Fraud Detection:Real-time transaction scoring using anomaly detection on tabular data.
- Predictive Analytics:Time-series forecasting for demand planning and equipment failure prediction.
Established volume favors image recognition; emerging adoption favors natural language processing.
Deployment:
Cost tier determines infrastructure ownership models, from reserved cloud capacity to captive edge silicon.
- Cloud-based:Hyperscaler-managed GPU clusters with elastic scaling and integrated MLOps tooling. Financial services firms in Singapore negotiate multi-year reserved capacity agreements covering model versioning and regulatory update cycles.
- Edge Computing:Localized inference on constrained hardware for latency-critical manufacturing and telecommunications use cases. German automotive suppliers deploy these configurations for real-time quality control, bypassing cloud round-trip delays.
- On-premises:Self-managed data center installations for classified or sensitive workloads.
- Hybrid:Split architectures training in cloud and inferring at edge or on-premises.
Cloud-based deployments anchor current procurement volume; edge computing configurations are climbing the fastest as latency requirements harden.
End User:
Customer type dictates compliance surface area and integration complexity with legacy infrastructure.
- Healthcare:Diagnostic imaging and clinical decision support systems face FDA premarket notification and EU MDR conformity assessment. Hospital systems in the Netherlands and Sweden now mandate explainability documentation in procurement specifications.
- Finance:Credit scoring and algorithmic trading models trigger SEC scrutiny and EU AI Act high-risk system registry requirements. Swiss and Singaporean banks negotiate fixed-price inference tiers with integrated audit trails.
- Retail:Recommendation engines and demand forecasting with lighter regulatory exposure.
- Telecommunications:Network optimization and predictive maintenance at infrastructure scale.
Healthcare commands premium pricing for audit-ready architectures; finance is expanding most quickly as algorithmic accountability frameworks mature.
Technology:
Maturity gradient separates production-hardened architectures from experimental alternatives challenging scaling laws.
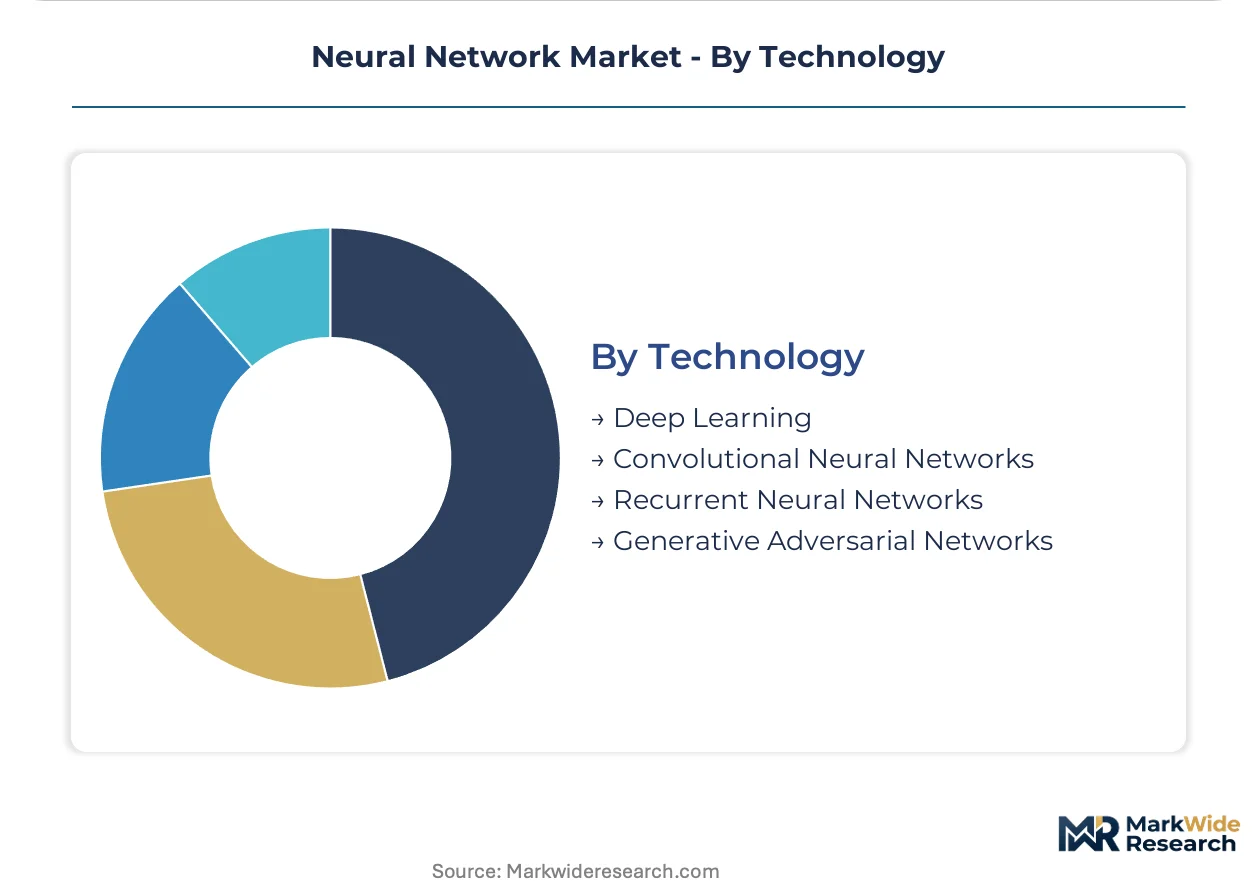
- Deep Learning:Multi-layer perceptrons and feedforward networks forming the baseline for most commercial applications. These architectures dominate brownfield manufacturing integrations where interoperability with legacy SCADA systems is required.
- Convolutional Neural Networks:Specialized for spatial data with weight-sharing reducing parameter count. Radiological screening tools using these architectures are accelerating FDA clearance timelines in the United States.
- Recurrent Neural Networks:Sequential data processing with memory mechanisms for time-series applications.
- Generative Adversarial Networks:Adversarial training frameworks for synthetic data generation and content creation.
Deep learning and convolutional networks hold established production share; generative adversarial networks are gaining share fastest for synthetic training data generation under FTC licensing pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Neural network infrastructure flows reflect stark trade imbalances: the United States and China run substantial surpluses in AI training hardware and cloud services, while European and Asian importers absorb these capabilities through licensing and capacity agreements. Export controls on advanced semiconductors are fragmenting procurement routes, forcing buyers to diversify sourcing across multiple jurisdictions.
United States
Cloud hyperscalers and defense contractors anchor the largest procurement pipelines for GPU clusters and inference services. The FTC scrutinizes training-data sourcing practices, pressuring enterprises toward synthetic data generation or negotiated licensing. Austin and Seattle host concentrated engineering talent pools where asset-light leasing models for training infrastructure are reshaping competitive entry.
China
SAMR enforces algorithmic recommendation regulations that constrain product architectures for consumer-facing neural networks. Domestic cloud providers and fintech operators drive demand for localized training capacity amid export control pressures. Beijing and Shenzhen industrial clusters are accelerating domestic GPU design and packaging capabilities to reduce import dependency.
Germany
Automotive suppliers and industrial automation firms deploy edge-computing neural networks for real-time quality control. The EU AI Act imposes conformity assessments on manufacturing and healthcare deployments, restructuring procurement specifications. Bavaria's industrial corridor concentrates neuromorphic silicon research partnerships between automotive OEMs and semiconductor foundries.
India
The semiconductor PLI scheme attracts GPU assembly and packaging design houses seeking supply chain diversification beyond East Asian concentration. Domestic IT services firms and pharmaceutical consortiums adopt federated learning for privacy-preserving model training. Bengaluru and Hyderabad clusters concentrate MLOps engineering talent for export-oriented AI services.
Singapore
Financial services firms negotiate fixed-price inference tiers covering model versioning and regulatory update cycles. The Monetary Authority of Singapore mandates algorithmic audit trails for credit-scoring neural networks. The city-state's data center capacity serves as a regional hub for Southeast Asian enterprises requiring low-latency cloud training access.
Neural Network Market Key Industry Players
On the supply side, the industry is consolidating around three distinct capability layers: captive silicon design, hyperscale cloud infrastructure, and specialized model development. Hyperscalers defend pricing power through long-horizon training contracts and integrated compliance tooling. Strategic archetypes span vertically integrated hardware-software stacks, cloud-native service platforms, and research-origin model laboratories. Competitive moves concentrate on reserved capacity agreements and geographic diversification of training locations.
Within the vertically integrated hardware tier, NVIDIA Corporation anchors high-performance silicon supply through captive foundry partnerships. Google LLC and Microsoft Corporation occupy cloud-native platform positions, leveraging data center scale and enterprise distribution channels respectively. These three exemplify divergent paths to market position: proprietary interconnect standards, custom accelerator architectures, and co-selling agreements with Fortune 500 IT departments.
| Leading Market Players |
|---|
| NVIDIA Corporation |
| Google LLC |
| Microsoft Corporation |
| IBM Corporation |
| Amazon Web Services, Inc. |
| Intel Corporation |
| OpenAI |
| Huawei Technologies Co., Ltd. |
| Baidu, Inc. |
| Others |
Cost & Logistics Intelligence
HBM3 and HBM3E foundry capacity in South Korea and Taiwan concentrates upstream margin capture for training infrastructure, pushing downstream value toward reserved multi-year cloud contracts and specialized fine-tuning layers where buyer lock-in substitutes for hardware ownership.
Pricing Analysis
Industrial OEM buyers anchor a contract-based pricing structure for edge-deployed inference hardware, with three-tier differentiation across premium certified, standard commercial, and economy unvalidated tiers. Cost compression in economy tiers intensifies as Chinese domestic GPU alternatives enter assembly channels. Healthcare providers exhibit lowest price sensitivity due to FDA 510(k) compliance requirements, while mid-market SaaS vendors face acute margin pressure from hyperscaler bundling.
Supply Chain Analysis
TSMC and Samsung Foundry hold captive advanced packaging capacity for high-bandwidth memory stacks. Taiwan, South Korea, and the United States concentrate upstream silicon fabrication, while India and Vietnam attract downstream GPU assembly through PLI incentives. Single-source vulnerability in HBM3E supply exposes procurement to export control disruption. Distribution runs through hyperscaler direct sales and specialized AI infrastructure resellers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The neural network market constitutes a high-growth disruption as EU AI Act enforcement deadlines force enterprise procurement toward audit-ready architectures, compressing competitive timelines for compliance tooling integration.
For Market Incumbents: Insulate position through captive foundry partnerships for HBM supply security and long-horizon reserved capacity agreements that embed MLOps tooling. State-space model alternatives threaten transformer-based hardware-software co-optimization investments. Vertical integration into neuromorphic silicon R&D in Germany and India diversifies architecture exposure. For New Entrants and Emerging Players: Build out federated learning platforms for pharmaceutical consortiums in India and Singapore, bypassing centralized data aggregation restrictions. Edge computing for German automotive quality control represents the most penetrable segment. Go-to-market through system integrators with existing SCADA protocol expertise reduces legacy integration friction. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed cloud infrastructure specialists holding reserved GPU capacity contracts. Five-to-ten year viability hinges on regulatory compliance tooling integration rather than raw compute scale. Watch FDA 510(k) clearance velocity for computer-aided detection tools as inflection indicator for healthcare procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Conformity Certification | German notified bodies certify quality management systems, unlocking high-risk healthcare procurement. |
| HBM Supply Diversification Partnership | India's PLI scheme attracts packaging design houses beyond Taiwan-South Korea concentration. |
| Federated Learning Platform Launch | Pharmaceutical consortiums in Singapore adopt privacy-preserving training for cross-border compliance. |
| Neuromorphic Silicon Joint Venture | Bavarian automotive OEMs partner with foundries for ultra-low-power industrial IoT inference. |
| Reserved Capacity Multi-Year Agreement | Swiss banks negotiate fixed-price inference tiers with integrated SEC audit trail capabilities. |
Research Approach
The analysis maps convolutional architectures for diagnostic imaging, transformer-based NLP platforms, edge inference hardware, and federated learning systems, each validated through CTOs at hyperscalers, hospital procurement committees, MLOps engineering directors, and automotive platform engineers. Primary interview insights triangulate against SEC hyperscaler capex disclosures, FDA 510(k) clearance databases, EU AI Act implementation guidance, and cloud infrastructure trade data. Bottom-up deployment volume estimates reconcile with top-down semiconductor consumption figures.
Assumptions held fixed include EU AI Act enforcement timelines, HBM3E foundry capacity expansion rates, and export control regime stability; variables stress-tested include transformer architecture displacement rates and synthetic data generation cost curves. Segmentation models incorporate deployment topology, end-use risk classification, regulatory jurisdiction, and organization size tier. CAGRs derive from installed base growth, replacement cycles, and pricing trajectory synthesis across the projection horizon.
Stress conditions across HBM supply disruption, EU AI Act delay scenarios, and state-space model adoption velocity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these assumptions and acknowledge revision risk from semiconductor trade policy shifts, algorithmic accountability framework divergence, and neuromorphic hardware commercialization acceleration. Quarterly review of FDA 510(k) clearance timelines, hyperscaler reserved capacity pricing, and notified body certification queue depth is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
NLP in Healthcare and Life Sciences Market
Artificial Intelligence (AI)
AI Platform Market
Artificial Intelligence (AI)
Europe Synthetic Data Generation Market
Artificial Intelligence (AI)
Global Mobile Artificial Intelligence Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in BFSI Market
Artificial Intelligence (AI)
Robotic Vision Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Oil and Gas Market
Artificial Intelligence (AI)
Global AI Governance Market
Artificial Intelligence (AI)
Europe Artificial Intelligence Market
Artificial Intelligence (AI)
US Artificial Intelligence (AI) Market
Artificial Intelligence (AI)
Machine Learning in Pharmaceutical Industry Market
Artificial Intelligence (AI)
Cloud Artificial Intelligence Market
Artificial Intelligence (AI)
Global Cognitive Computing Technology Market
Artificial Intelligence (AI)
Legal AI Software Market
Artificial Intelligence (AI)
Artificial Intelligence in Supply Chain Management Market
Artificial Intelligence (AI)
AI Recruitment Market