
 Autonomous Agents Market | 2026-2036
Autonomous Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Autonomous Agents Market Analysis
Multi-source AI model procurement is expanding as enterprises reduce dependency on single-vendor LLM stacks. NVIDIA Corporation leverages its GPU infrastructure to dominate training workloads for autonomous agent development. Microsoft anchors enterprise adoption through Azure OpenAI integrations that embed agentic capabilities into productivity suites. Google competes on foundation model breadth, sustaining research pipelines that feed specialized agent architectures.
Autonomous agents are software entities that perceive environments through sensor fusion or API interfaces, process decisions via neural networks or symbolic reasoning engines, and execute actions without continuous human intervention to achieve defined objectives. Cloud-based deployment leads segment economics by amortizing inference costs across tenant workloads, while edge computing configurations are capturing manufacturing and automotive latency-sensitive applications where millisecond response thresholds are non-negotiable. Reinforcement learning operating modes command premium engineering investment as they enable agents to optimize behavior through environmental feedback loops rather than static programming.
The EU AI Act, FDA software-as-medical-device guidance, and NHTSA autonomous vehicle testing protocols collectively impose compliance architectures that determine market access trajectories. These frameworks shape product development roadmaps by mandating explainability, human oversight, and safety validation before commercial deployment. Stakeholders must monitor regulatory divergence between jurisdictions to avoid fragmentation of agent certification pathways that would multiply compliance overhead.
Market Dynamics
Foundation model commoditization is compressing competitive moats and forcing autonomous agent developers to differentiate through vertical integration and proprietary data pipelines rather than raw model performance.
Growth Catalysts
- EU AI Act compliance mandates:Enterprises across financial services and healthcare are accelerating agent procurement to meet risk classification deadlines, creating immediate demand for certified autonomous systems.
- Edge computing infrastructure expansion:Manufacturing facilities in Germany and automotive plants in Japan are deploying latency-sensitive agents for real-time quality control and predictive maintenance workflows.
- API-first architecture proliferation:Software vendors are exposing agentic capabilities through standardized interfaces, lowering integration barriers for mid-market enterprises seeking automation without custom development.
Market Restraints
- GPU supply concentration:Training and inference workloads depend on semiconductor fabrication capacity concentrated in Taiwan and South Korea, creating input cost volatility and allocation constraints.
- Explainability requirements under EU AI Act:High-risk autonomous systems must provide interpretable decision trails, imposing engineering overhead that extends development timelines and raises compliance costs.
- Symbolic reasoning substitutes:Rule-based automation platforms retain cost advantages for deterministic workflows, limiting agent penetration in regulated industries with low tolerance for probabilistic outputs.
Strategic Opportunities
- India's PLI scheme for AI:Domestic manufacturing incentives are attracting agent developers to establish localized training infrastructure and capture public sector procurement opportunities.
- Convergence of computer vision and LLM architectures:Multimodal agents capable of processing visual, textual, and sensor inputs are opening robotics and drone applications previously requiring separate specialized systems.
- Outcome-based pricing in enterprise SaaS:Agent vendors are experimenting with performance-linked contracts where fees scale with measurable productivity gains, displacing traditional per-seat licensing.
Industry Challenges
- Reinforcement learning engineering scarcity:Talent capable of designing reward functions and training environments for agent optimization commands premium compensation, constraining development velocity.
- Legacy system integration complexity:Enterprise IT environments with decades of accumulated technical debt require extensive API middleware development before agents can access operational data streams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autonomous Agents Market |
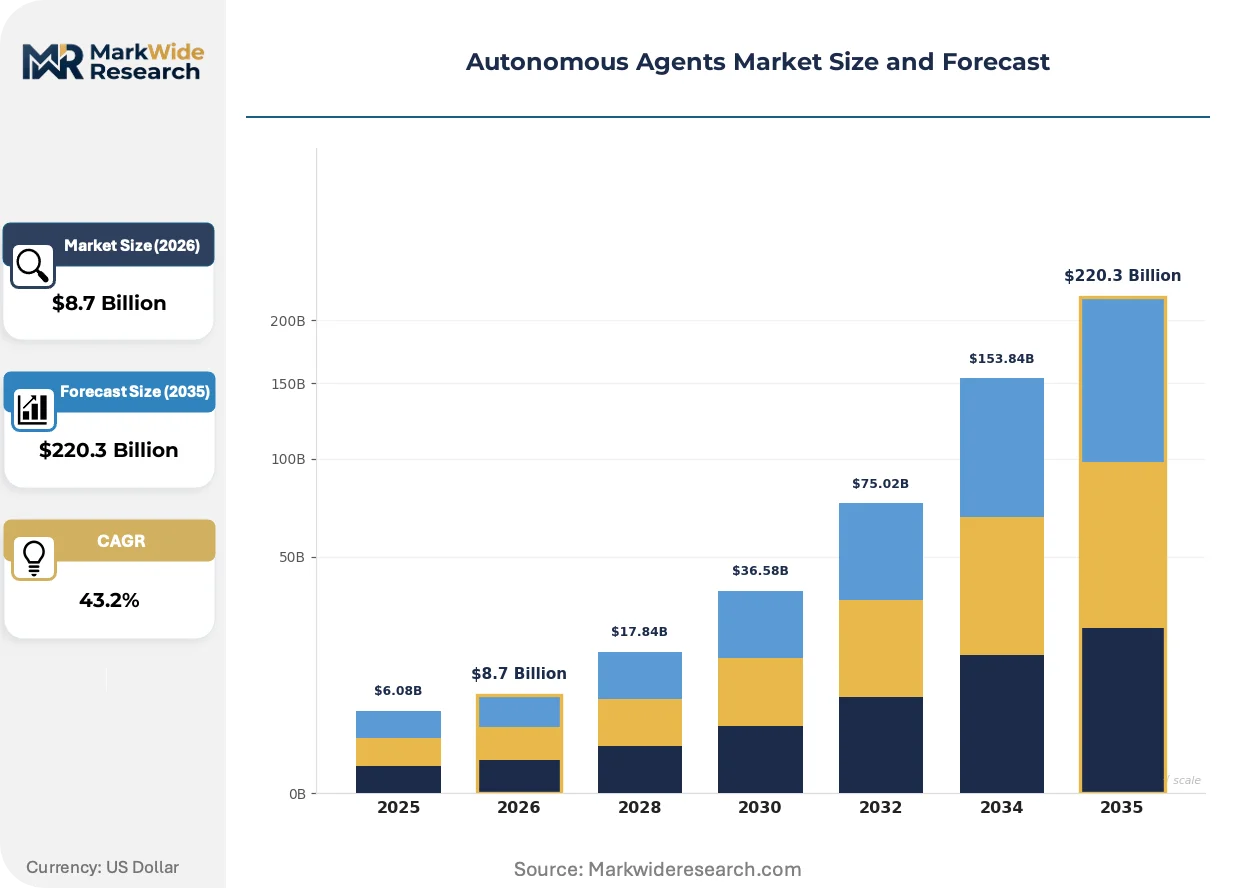
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $220.3 Billion |
| CAGR (2026 – 2036) | 43.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Virtual Assistants, Chatbots, Self-Driving Vehicles, Robotic Process Automation Deployment: Cloud-Based, On-Premises, Hybrid, Edge Computing End User: Retail, Healthcare, Manufacturing, Financial Services Operating Mode: Supervised Learning, Reinforcement Learning, Rule-Based Systems, Multi-Agent Systems |
| Companies Covered | IBM Corporation, Oracle, SAP, Amazon Web Services Inc., Microsoft, Google, NVIDIA Corporation, Salesforce, Intel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autonomous Agents Market Emerging Trajectories
Agent orchestration frameworks are consolidating previously fragmented toolchains, enabling multi-agent collaboration and reducing the engineering burden for complex workflow automation.
Multimodal foundation models are unifying perception, reasoning, and action generation within single architectures. Automotive manufacturers in Germany are piloting these systems for in-vehicle assistants that interpret driver gestures, voice commands, and dashboard alerts simultaneously. This convergence is unifying sensor processing and decision pipelines that previously required separate neural networks, compressing hardware requirements and latency budgets.
The EU AI Act's risk-based classification system is mandating conformity assessments for autonomous agents deployed in critical infrastructure. Financial institutions in France and healthcare providers in the Netherlands must document training data provenance and establish human oversight protocols before market authorization. High-risk applications are responding by embedding explainability modules and kill-switch mechanisms directly into agent architectures.
Enterprise buyers are consolidating vendor relationships around integrated platform providers rather than assembling point solutions. Mid-market companies in the United States are abandoning best-of-breed procurement strategies in favor of unified suites where agents interoperate natively with productivity and CRM tools. This concentration is most visible in professional services, where law firms and consultancies prioritize seamless handoffs between research agents and document generation systems over specialized performance metrics.
Autonomous Agents Market Segmentation
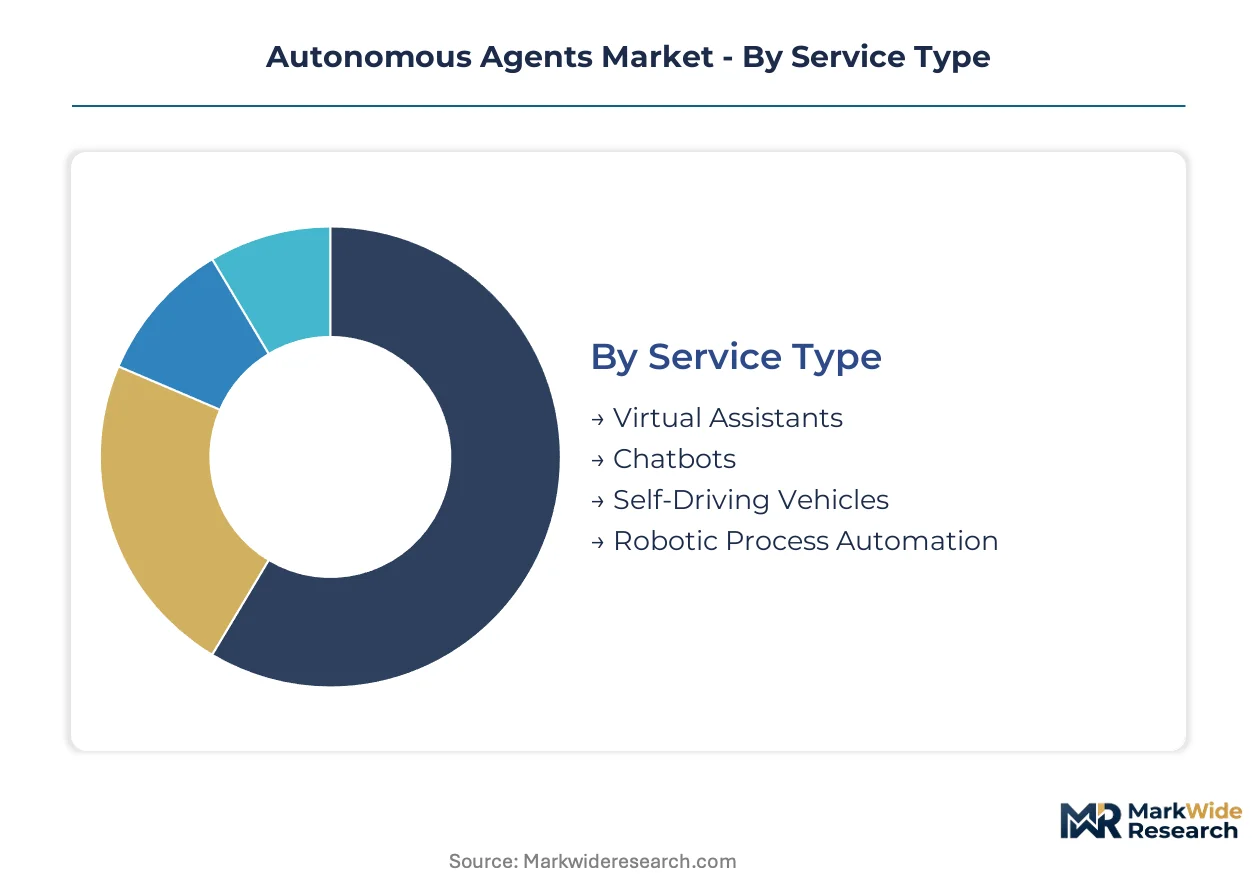
Segmentation in autonomous agents determines architectural trade-offs between latency, compliance burden, and operational autonomy. Deployment choices directly constrain which operating modes and service types become technically viable for specific end users.
Service Type:
Supply concentration in GPU infrastructure and foundation model training favors service types with amortizable inference costs across large user bases.
- Virtual Assistants:Natural language interfaces orchestrating calendar management, information retrieval, and cross-application task execution through API integrations. Financial services firms in the United States deploy these for client onboarding workflows where conversational fluidity reduces abandonment rates.
- Chatbots:Text-based interaction systems handling customer service triage, FAQ resolution, and transactional handoffs with deterministic escalation protocols. Retail operations in Germany leverage these for 24/7 order support where labor arbitrage justifies automation investment.
- Self-Driving Vehicles:Embodied agents processing LiDAR, camera, and radar inputs for navigation decisions in dynamic traffic environments.
- Robotic Process Automation:Software agents executing repetitive data entry, reconciliation, and report generation tasks within structured enterprise systems.
Virtual assistants absorb the bulk of installed capacity; self-driving vehicles are expanding most quickly.
Deployment:
Cost tier stratification separates enterprises with capital-intensive latency requirements from those prioritizing operational expenditure flexibility.
- Cloud-Based:Centralized inference infrastructure delivering elastic compute scaling through multi-tenant architectures. Healthcare providers in the Netherlands adopt these for diagnostic imaging agents where regulatory compliance costs favor shared security audits.
- Edge Computing:Distributed processing nodes positioned proximal to data sources, eliminating round-trip latency to centralized data centers. Automotive manufacturers in Japan deploy these for in-vehicle perception systems where millisecond braking decisions preclude cloud dependency.
- On-Premises:Dedicated hardware installations within organizational facilities, maintaining complete data sovereignty and network isolation.
- Hybrid:Architectures partitioning workloads between cloud and local infrastructure based on sensitivity classification and latency thresholds.
Cloud-based deployments capture the majority of new procurement; edge computing configurations are climbing the fastest.
End User:
Volume concentration varies sharply by sector maturity, with financial services and manufacturing leading measurable ROI documentation.
- Financial Services:Institutions deploying algorithmic trading agents, fraud detection systems, and compliance monitoring tools with real-time transaction analysis. Banks in France integrate these under EU AI Act high-risk system requirements with mandatory human oversight protocols.
- Manufacturing:Facilities implementing predictive maintenance agents, quality control vision systems, and supply chain optimization engines. Plants in Germany combine these with edge infrastructure for zero-defect production targets.
- Healthcare:Providers utilizing clinical decision support agents, patient scheduling optimization, and remote monitoring systems.
- Retail:Operations deploying inventory management agents, dynamic pricing engines, and personalized recommendation systems.
Financial services absorbs the bulk of installed capacity; manufacturing is gaining share fastest.
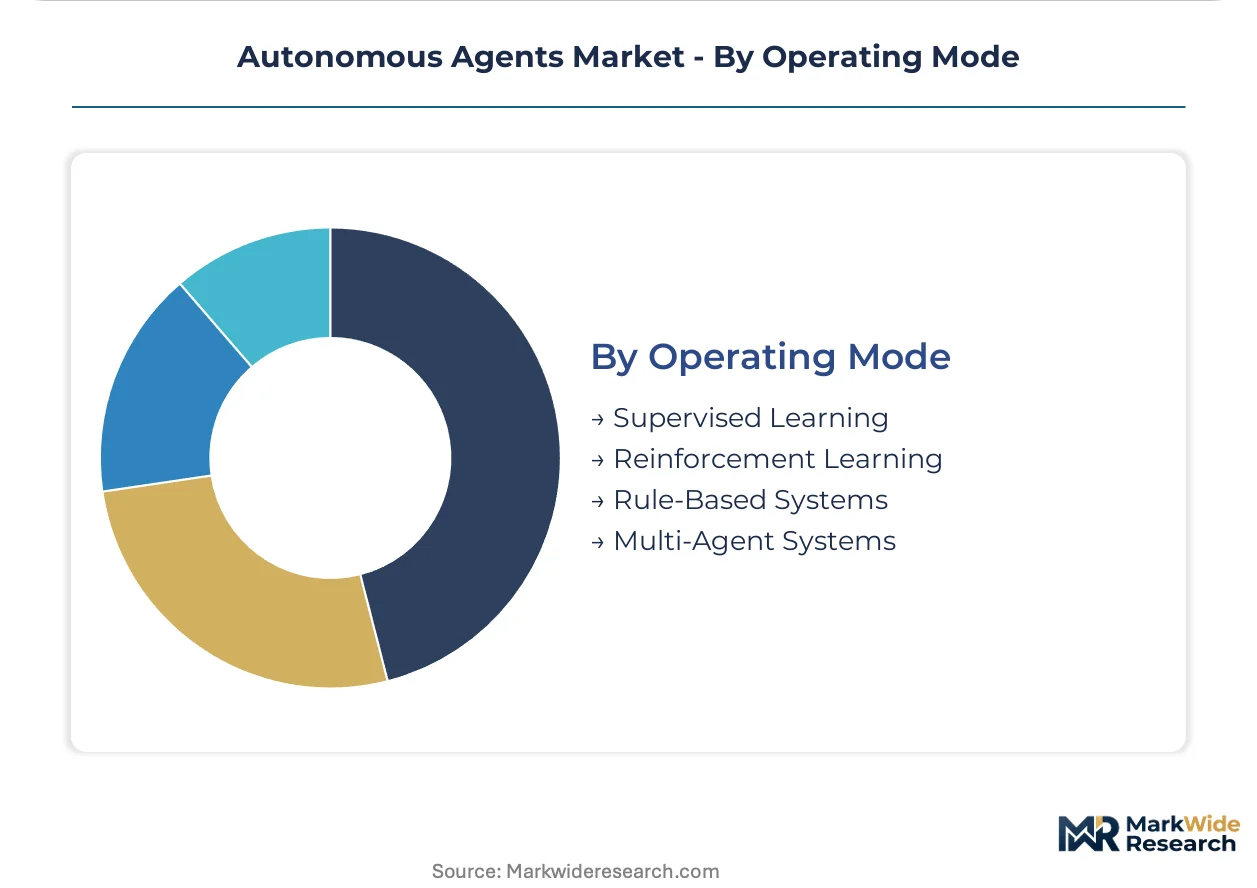
Operating Mode:
Margin structures diverge based on engineering intensity, with reinforcement learning commanding premium development investment.
- Reinforcement Learning:Agents optimizing behavior through environmental feedback rather than static programming, requiring sophisticated reward function design and simulation infrastructure. Robotics developers in the United States leverage these for warehouse automation where task variability exceeds rule-based system capabilities.
- Multi-Agent Systems:Coordinated populations of specialized agents negotiating task allocation and information sharing to achieve collective objectives. Logistics platforms in Singapore deploy these for dynamic fleet routing where decentralized decision-making outperforms centralized optimization.
- Supervised Learning:Agents trained on labeled datasets to replicate demonstrated behaviors within bounded input distributions.
- Rule-Based Systems:Deterministic logic engines executing predefined decision trees with complete interpretability and audit trails.
Supervised learning absorbs the bulk of installed capacity; reinforcement learning is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise AI procurement concentrates in the United States, where defense budgets and financial services automation drive deployment velocity. Regulatory fragmentation across jurisdictions is reshaping how developers architect compliance-ready systems.
United States
Defense procurement through DARPA and NSA accelerates classified autonomous agent development for signals intelligence. The NHTSA autonomous vehicle testing protocols mandate extensive safety validation before commercial deployment. Silicon Valley clusters host the bulk of reinforcement learning engineering talent, with OpenAI and Anthropic anchoring frontier model research pipelines.
Germany
Automotive manufacturers deploy edge-computing agents for real-time quality control in Stuttgart and Munich production facilities. The EU AI Act's high-risk system classification requires conformity assessments for industrial automation agents. The KBA coordinates type-approval processes for self-driving vehicle systems seeking European market access.
Japan
METI funding programs support multimodal agent development for manufacturing and eldercare applications. The country's national pharmaceutical regulator evaluates software-as-medical-device agents under revised PMDA guidance. Nagoya's automotive corridor pilots in-vehicle assistants combining computer vision and natural language processing.
India
The PLI scheme for AI attracts agent developers to establish localized training infrastructure in Bengaluru and Hyderabad. SEBI mandates algorithmic trading audit trails that shape how financial services agents document decision logic. Mumbai's banking sector procures compliance-monitoring agents to meet RBI operational risk requirements.
Singapore
Logistics platforms deploy multi-agent systems for dynamic fleet routing at the Port of Singapore. The Monetary Authority of Singapore's AI governance framework requires explainability modules for financial services agents. The city-state's sovereign wealth fund channels capital toward Southeast Asian agent startups seeking regional expansion.
Autonomous Agents Market Vendor Landscape
Strategic partnerships dominate the current landscape as hyperscalers embed agentic capabilities into enterprise productivity suites. The vendor base stratifies into three tiers: cloud infrastructure providers with captive GPU supply, enterprise software incumbents with distribution reach, and specialized agent orchestration startups. Two strategic archetypes prevail — vertically integrated stack owners and API-first platform enablers. Competitive moves center on foundation model licensing deals and edge infrastructure partnerships.
Within the hyperscaler tier, NVIDIA Corporation, Microsoft, and Amazon Web Services Inc. occupy positions that exemplify divergent paths to market influence. NVIDIA leverages its Santa Clara-based semiconductor operations to anchor training workload dominance. Microsoft's Redmond headquarters coordinates Azure OpenAI integrations that embed agents across Office productivity suites. Amazon Web Services Inc. represents the cloud-native archetype, exposing agentic capabilities through standardized API interfaces that lower integration barriers for mid-market procurement.
| Leading Market Players |
|---|
| IBM Corporation |
| Oracle |
| SAP |
| Amazon Web Services Inc. |
| Microsoft |
| NVIDIA Corporation |
| Salesforce |
| Intel |
| Others |
Supply Flow & Price Mechanics
Performance-grade divergence between high-risk certified agents and general-purpose automation tools manifests in both pricing stratification and supply chain sourcing protocols. Premium tiers command substantial engineering investment to satisfy EU AI Act conformity assessments, while commodity agents compete on inference cost amortization through multi-tenant cloud infrastructure. This bifurcation concentrates procurement decisions around regulatory exposure rather than raw capability metrics.
Pricing Analysis
Volume concentration in supervised learning deployments compresses margins at the base tier, while reinforcement learning configurations retain pricing power through engineering scarcity. SaaS-tiered subscription models dominate enterprise procurement, with differentiation anchored in certification grade and explainability module depth. Cost compression in cloud-based inference is intensifying because hyperscaler competition erodes per-token economics. Mid-market enterprises exhibit highest price sensitivity, whereas financial institutions under regulatory scrutiny prioritize compliance-grade agents regardless of premium positioning.
Supply Chain Analysis
Dual-sourcing requirements for GPU infrastructure mandate multi-supplier qualification across NVIDIA, AMD, and emerging cloud TPU providers to mitigate allocation risk. Semiconductor fabrication concentrates in Taiwan and South Korea, with advanced packaging operations anchored in the United States. Critical inputs span high-bandwidth memory modules, specialized AI accelerators, and proprietary foundation model licenses. Single-source vulnerability in TSMC's leading-edge node capacity threatens training workload scheduling. Distribution runs through hyperscaler marketplaces and direct enterprise licensing channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
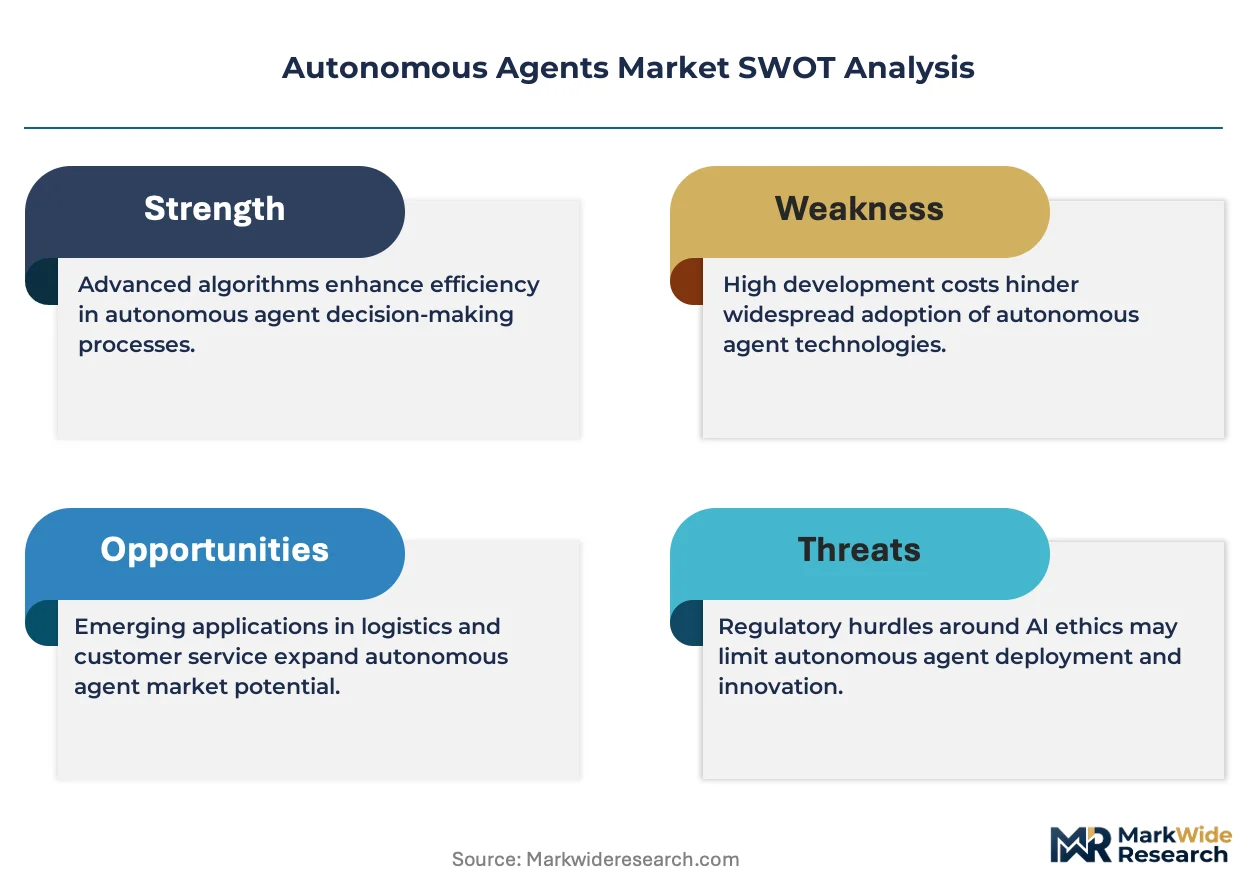
The autonomous agents market operates as a cost-of-compliance story where EU AI Act certification requirements erect barrier-to-entry moats favoring incumbents with established conformity assessment infrastructure.
For Market Incumbents: Acquire specialized reinforcement learning engineering teams to consolidate scarce talent pools before compensation inflation erodes project margins. Defensive positioning requires embedding kill-switch architectures and explainability modules directly into agent foundations to preempt regulatory retrofit costs. Threat substitution from rule-based automation platforms persists in deterministic workflow segments where probabilistic outputs face institutional resistance. For New Entrants and Emerging Players: EU AI Act compliance mandates in France and the Netherlands open a window for boutique conformity assessment services targeting mid-tier financial institutions lacking in-house regulatory expertise. White-space concentration appears in edge-computing agent configurations for German manufacturing quality control, where latency requirements exclude cloud-native incumbents. Go-to-market execution should anchor in API-first orchestration platforms that abstract foundation model complexity for systems integrators. For Investors and Strategic Acquirers: Exit pathways concentrate in hyperscaler acquisition of vertical orchestration specialists with proven regulatory certification track records. Long-term viability favors developers with captive training infrastructure and established data pipeline partnerships rather than pure software plays. Signal to monitor: divergence in FDA software-as-medical-device approval timelines for clinical decision support agents, which would indicate regulatory pathway maturation for healthcare vertical expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Certification Investment | EU AI Act conformity assessments create defensible positioning in high-risk system categories. |
| Edge Infrastructure Partnership | Automotive manufacturers in Japan demand sub-10ms latency for in-vehicle perception agents. |
| Foundation Model Licensing Agreement | Multi-source procurement reduces dependency concentration on single-vendor LLM stacks. |
| Vertical Orchestration Platform Launch | Professional services firms prioritize seamless handoffs between research and document generation agents. |
| Reinforcement Learning Talent Acquisition | Scarcity in reward function design constrains development velocity for warehouse automation robotics. |
Methodological Framework
Independent corroboration across primary interviews with AI platform engineers, enterprise IT procurement officers, regulatory compliance leads, and foundation model researchers underwrites the qualitative findings. Secondary validation draws from SEC filings of hyperscaler infrastructure providers, EU AI Act implementation guidance documents, NHTSA autonomous vehicle testing protocols, and FDA software-as-medical-device guidance releases. Bottom-up segment sizing triangulates against top-down macroeconomic anchoring across the analysis window.
Comparable-period anchoring to historical deployment trajectories in financial services automation established baseline adoption curves for the projection horizon. The analytical framework models segmentation across deployment architecture, operating mode complexity, end-use industry regulatory exposure, and geographic procurement concentration. CAGRs derive from logistic diffusion curves fitted to enterprise budget allocation patterns and infrastructure capacity expansion timelines. Key inputs include GPU supply allocation forecasts and foundation model commoditization velocity assumptions.
The model assumes a particular technology adoption path; alternative pathways for multimodal foundation model convergence would alter the outlook if unified architectures displace specialized agent stacks faster than projected. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and hyperscaler pricing discipline. Deviation in Taiwan semiconductor fabrication capacity utilization would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Global Artificial Intelligence in E-Commerce Market
Artificial Intelligence (AI)
AI Mirror Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) Governance Market
Artificial Intelligence (AI)
Latin America Artificial Intelligence Market
Artificial Intelligence (AI)
AI in Life Sciences Market
Artificial Intelligence (AI)
Cloud Computing Artificial Intelligence (AI) Market
Artificial Intelligence (AI)
Global Natural Language Generation (NLG) Market
Artificial Intelligence (AI)
Global Cognitive Services Market
Artificial Intelligence (AI)
Cloud Artificial Intelligence Market
Artificial Intelligence (AI)
Global Cognitive Automation Market
Artificial Intelligence (AI)
Emotion Detection and Recognition (EDR) Market
Artificial Intelligence (AI)
Global Federated Learning Solutions Market
Artificial Intelligence (AI)
Global Artificial Intelligence Chip Market
Artificial Intelligence (AI)
Artificial Intelligence Platform Market
Artificial Intelligence (AI)
Model Validation and Automation Market
Artificial Intelligence (AI)
Legal AI Market