
 Artificial Intelligence (AI) in Automotive Market | 2026-2036
Artificial Intelligence (AI) in Automotive Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Intelligence (AI) in Automotive Market Analysis
Fleet management is expanding as the fastest-growing end-use vertical for automotive AI, displacing traditional aftermarket channels as the primary demand source. NVIDIA Corporation leverages its GPU architecture to dominate training infrastructure for autonomous driving models. Tesla sustains vertical integration from silicon to software, controlling the full stack for its Full Self-Driving platform. Continental AG specializes in sensor fusion systems for European OEMs, anchoring its position in advanced driver assistance.
Artificial Intelligence in Automotive encompasses machine learning algorithms, computer vision pipelines, and natural language processing modules that process real-time vehicle sensor data to enable perception, decision-making, and human-machine interaction. These systems typically operate on embedded edge processors with sub-50-millisecond latency requirements for safety-critical functions, primarily serving to reduce traffic fatalities and optimize fleet operational efficiency. Computer vision commands the largest technology investment pool due to its centrality in object detection and lane-keeping applications, while predictive maintenance tools within the product type dimension represent the fastest-expanding margin pool as fleet operators prioritize uptime economics. Machine learning underpins both segments but faces margin compression from open-source framework commoditization.
NHTSA in the United States and the EU AI Act in Europe are mandating algorithmic explainability and failure-mode documentation for deployed automotive AI, forcing suppliers to restructure development workflows around auditable training data provenance. China's MIIT and SAMR enforce GB standards for connected vehicle data security, creating divergent compliance architectures for multinational component suppliers. Stakeholders must monitor regulatory fragmentation between jurisdictions as a primary determinant of product architecture and market access strategy.
Market Dynamics
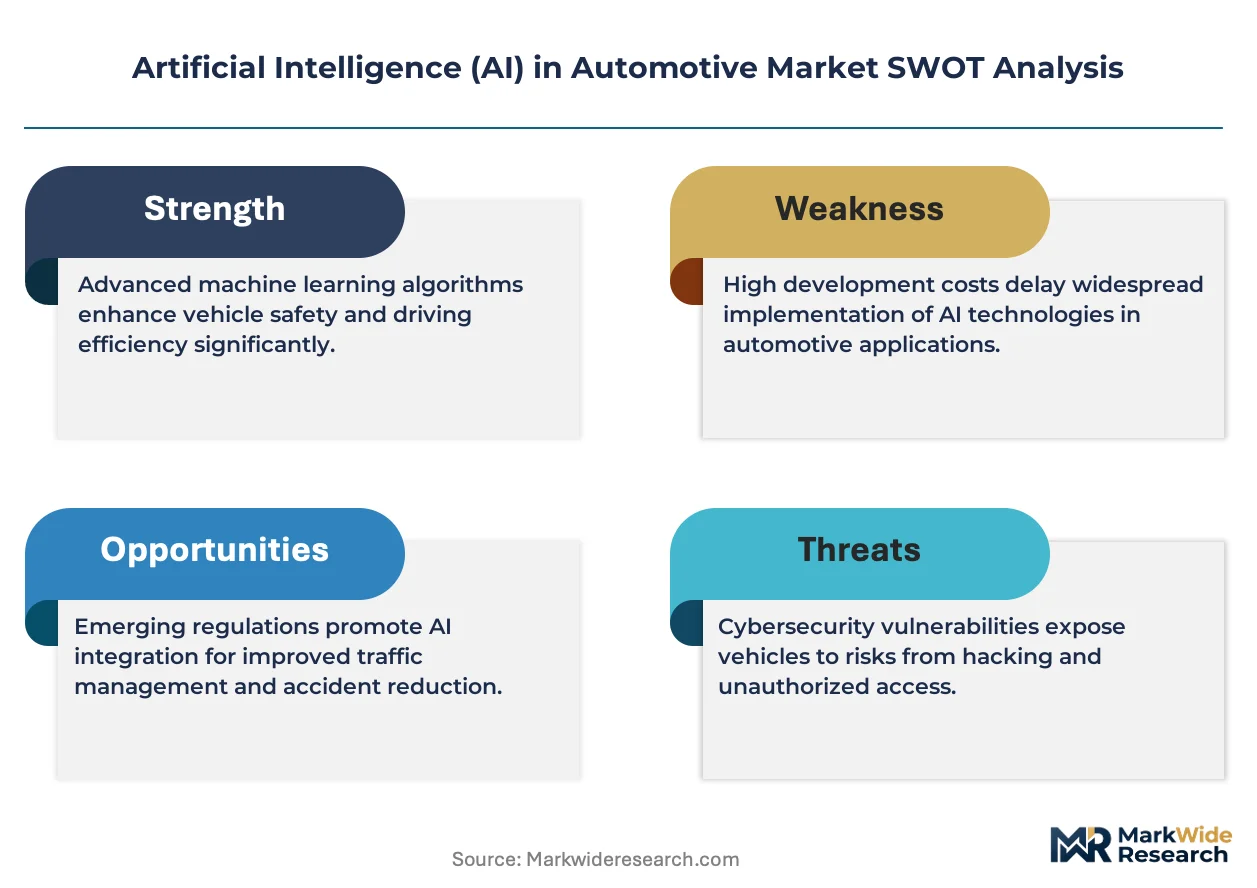
Fleet operators are compressing procurement cycles for predictive analytics platforms, forcing suppliers to restructure around uptime economics rather than hardware margins. The EU AI Act's algorithmic transparency mandates are simultaneously rewriting development workflows for computer vision and sensor fusion systems.
Growth Catalysts
- Fleet predictive maintenance:Commercial vehicle operators are prioritizing AI-driven uptime optimization over traditional scheduled servicing. This shift redirects R&D investment toward edge-computing prognostics.
- EU AI Act compliance infrastructure:Mandated algorithmic explainability is creating captive demand for audit-ready training data pipelines. Suppliers embedding documentation tools capture premium positioning.
- German OEM computer vision anchor:Volkswagen, BMW, and Mercedes-Benz are consolidating supplier relationships around perception stack partnerships. This concentration accelerates validation cycles for ADAS component vendors.
Market Restraints
- GPU supply concentration:Training infrastructure for autonomous driving models depends on single-source advanced semiconductor fabrication. Foundry capacity constraints in Taiwan create 18-24 month lead time volatility.
- Lithium-ion battery thermal runaway:AI-powered battery management systems face liability exposure from cell chemistry instability. This limits deployment confidence in high-voltage electric vehicle platforms.
- NHTSA failure-mode documentation:The U.S. regulator's incident reporting requirements impose 40-60% overhead on validation timelines. Smaller suppliers lack capital reserves to absorb extended certification cycles.
Strategic Opportunities
- India commercial vehicle retrofit:The country's PLI scheme for automotive electronics creates subsidy-backed entry for driver assistance hardware. Domestic fleet operators lack indigenous AI suppliers.
- Natural language processing convergence:Voice-controlled cabin systems are merging with large language model architectures. This hybrid interface category remains undefined by incumbent Tier-1s.
- China GB standard data localization:MIIT and SAMR mandates for connected vehicle data processing within national borders force multinational suppliers to establish captive cloud infrastructure. Early movers capture OEM partnership lock-in.
Industry Challenges
- Embedded systems talent scarcity:Real-time operating system expertise for sub-50-millisecond safety functions commands 3x premium over cloud AI engineering. European technical universities produce insufficient graduates.
- Legacy CAN bus integration:New AI modules must interface with 1990s-era vehicle network protocols. Translation layer development consumes 30% of software engineering resources.
- Functional safety certification (ISO 26262):ASIL-D rated components require 18-month validation against stochastic hardware faults. Startups lack capital to sustain pre-revenue certification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Intelligence (AI) in Automotive Market |
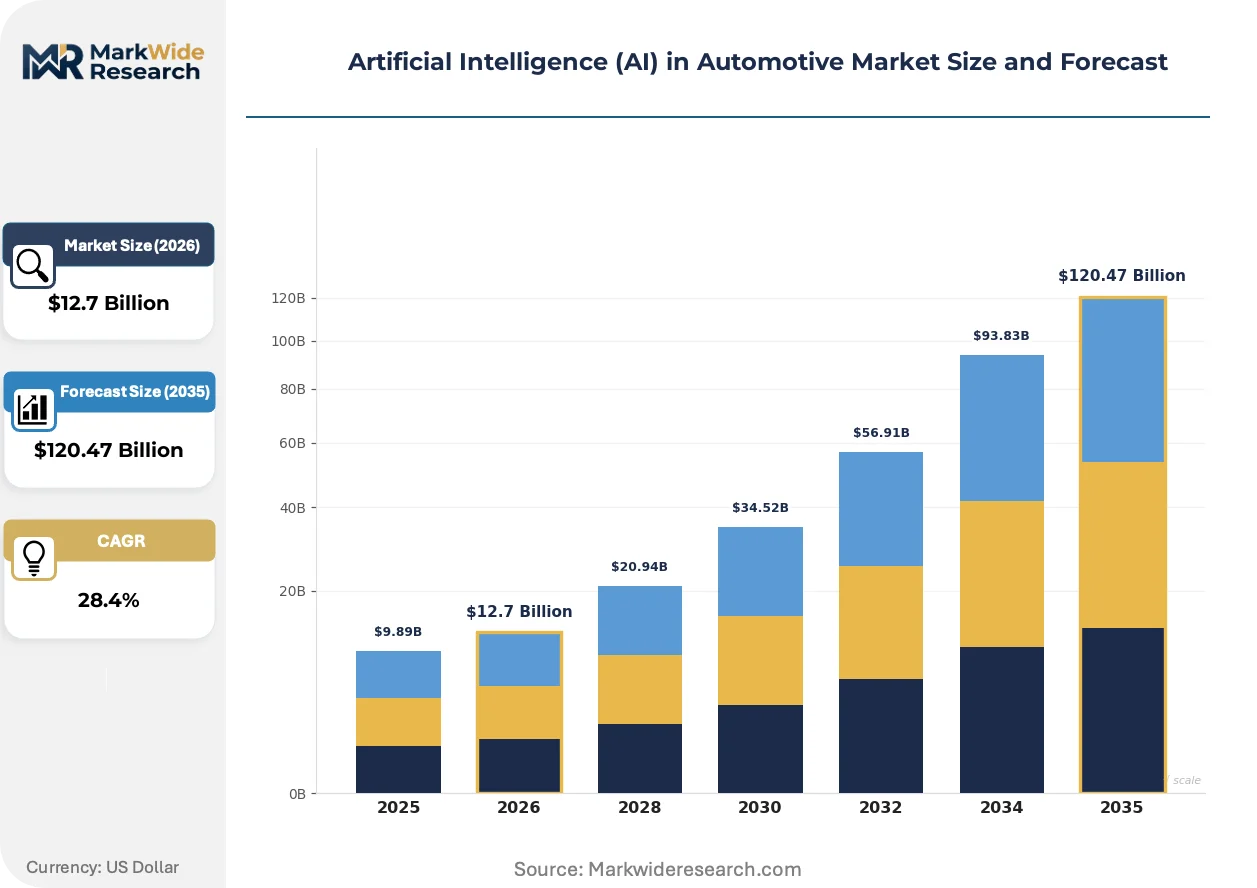
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $120.47 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Machine Learning, Natural Language Processing, Computer Vision, Robotics Product Type: Autonomous Vehicles, Driver Assistance Systems, Infotainment Systems, Predictive Maintenance Tools End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Fleet Operators Application: Traffic Management, Predictive Analytics, Personalization, Safety Systems |
| Companies Covered | Robert Bosch GmbH, Tesla, NVIDIA Corporation, Aptiv PLC, Waymo LLC, Intel Mobileye, Continental AG, Huawei Technologies, Qualcomm Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Intelligence (AI) in Automotive Market Emerging Trajectories
Transformer-based architectures are migrating from cloud training to edge inference, compressing latency budgets for safety-critical functions. This shift is restructuring competitive advantage around silicon-software co-design rather than algorithmic novelty alone.
End-to-end neural networks are overtaking modular perception-planning-control stacks in autonomous driving development. Waymo and Tesla are deploying unified models that directly map sensor inputs to steering commands. This consolidation is eliminating the subsystem supplier tier and capturing margin previously distributed across lidar, radar, and camera module vendors.
The EU AI Act's risk-based classification system is redefining product liability for ADAS features. High-risk applications now require conformity assessment by notified bodies before market placement. German suppliers are restructuring quality management systems around this audit infrastructure, while U.S. competitors face parallel compliance architecture costs for European market access.
Fleet procurement is consolidating around full-stack platform subscriptions rather than discrete hardware purchases. Logistics operators in the U.S. Midwest are signing 5-year contracts bundling telematics, predictive maintenance, and driver coaching. This shift transfers capital burden to suppliers and rewards vendors with captive financing capabilities or balance sheet scale.
Artificial Intelligence (AI) in Automotive Market Segmentation
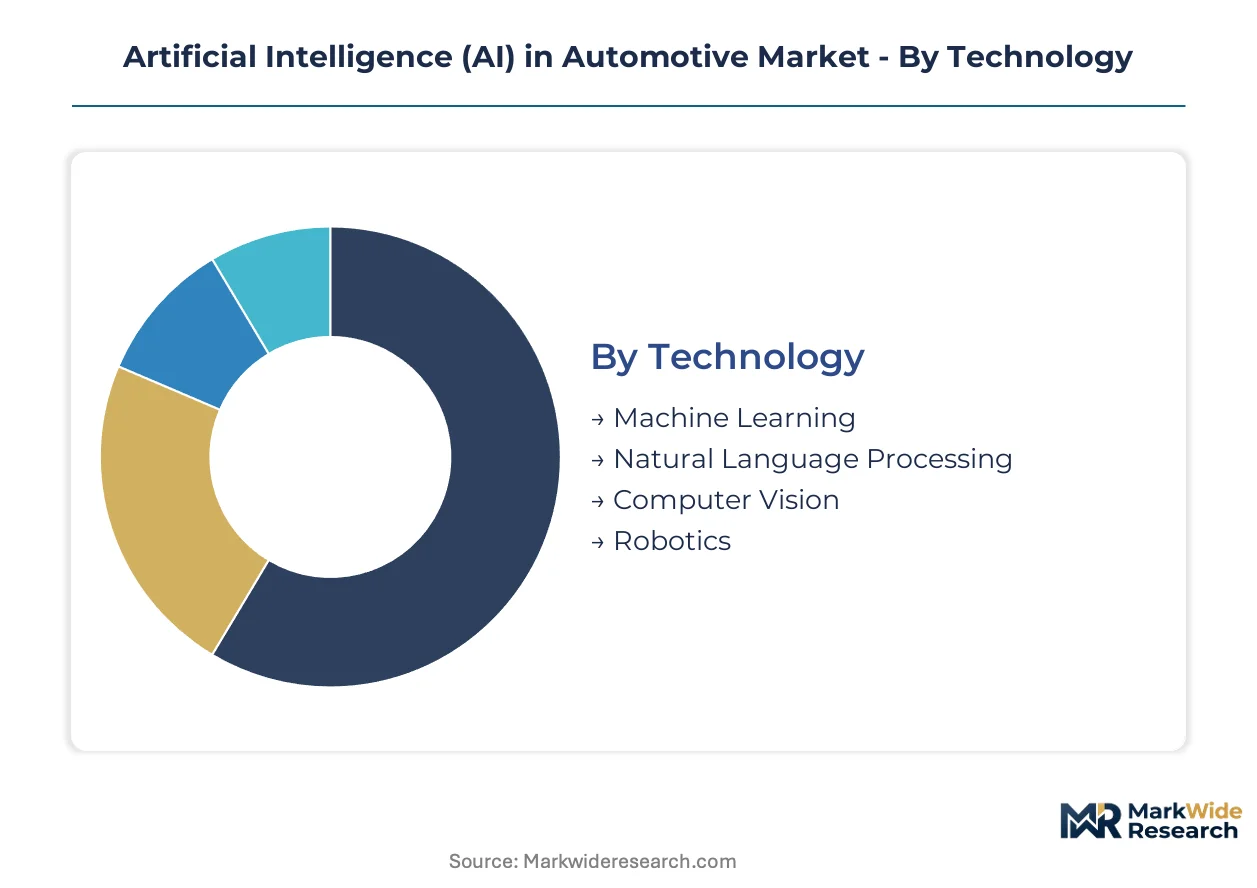
Segmentation in automotive AI reveals how technology specialization, procurement authority, and functional deployment create distinct margin pools. Suppliers configure R&D and sales organizations around these boundaries, as each segment demands incompatible validation timelines and partnership structures.
Technology:
Standardization dominates machine learning frameworks while computer vision and natural language processing remain heavily customized to OEM specifications.
- Computer Vision:Perception pipelines process camera and lidar feeds for object detection, lane keeping, and occupancy mapping. German OEMs anchor demand through consolidated supplier partnerships for ADAS perception stacks. The EU AI Act's algorithmic transparency mandates force documentation of training data provenance for these safety-critical systems.
- Machine Learning:Training infrastructure for autonomous driving models depends on GPU clusters, with inference optimization for embedded edge processors. Foundry capacity constraints in Taiwan create 18-24 month lead time volatility for advanced semiconductor fabrication.
- Natural Language Processing:Voice-controlled cabin systems merge with large language model architectures for human-machine interaction. This hybrid interface category remains undefined by incumbent Tier-1s.
- Robotics:Manipulation systems for manufacturing automation and vehicle assembly.
Most installed capacity flows through Computer Vision. Expansion is steepest in Natural Language Processing.
Product Type:
Hardware margins compress fastest in mature categories while software-centric segments capture expanding value pools.
- Driver Assistance Systems:Sensor fusion and perception stacks for lane departure warning, adaptive cruise control, and emergency braking. Volkswagen, BMW, and Mercedes-Benz consolidate supplier relationships around these perception partnerships.
- Predictive Maintenance Tools:Edge-computing prognostics optimize fleet uptime economics over traditional scheduled servicing. Commercial vehicle operators in the U.S. Midwest sign 5-year platform subscriptions bundling telematics and driver coaching.
- Autonomous Vehicles:End-to-end neural networks directly map sensor inputs to steering commands, eliminating subsystem supplier tiers.
- Infotainment Systems:Cabin experience platforms integrating navigation, media, and vehicle settings.
Revenue concentrates in Driver Assistance Systems. Predictive Maintenance Tools gain share fastest as fleet procurement shifts to uptime-based contracts.
End User:
Procurement authority is shifting from hardware buyers to platform operators with captive financing capabilities.
- Fleet Operators:Logistics and commercial vehicle managers prioritize AI-driven uptime optimization and driver coaching platforms. These buyers now compress procurement cycles and demand full-stack subscriptions rather than discrete hardware purchases.
- OEMs:Vehicle manufacturers anchor development of computer vision-based systems and control silicon-to-software integration strategies.
- Tier-1 Suppliers:Component vendors face margin compression from open-source framework commoditization and extended ISO 26262 certification timelines.
- Aftermarket Providers:Retrofit hardware installers serve price-sensitive segments with limited R&D resources.
Volume flows through OEMs. Fleet Operators expand most quickly as procurement consolidates around platform subscriptions.
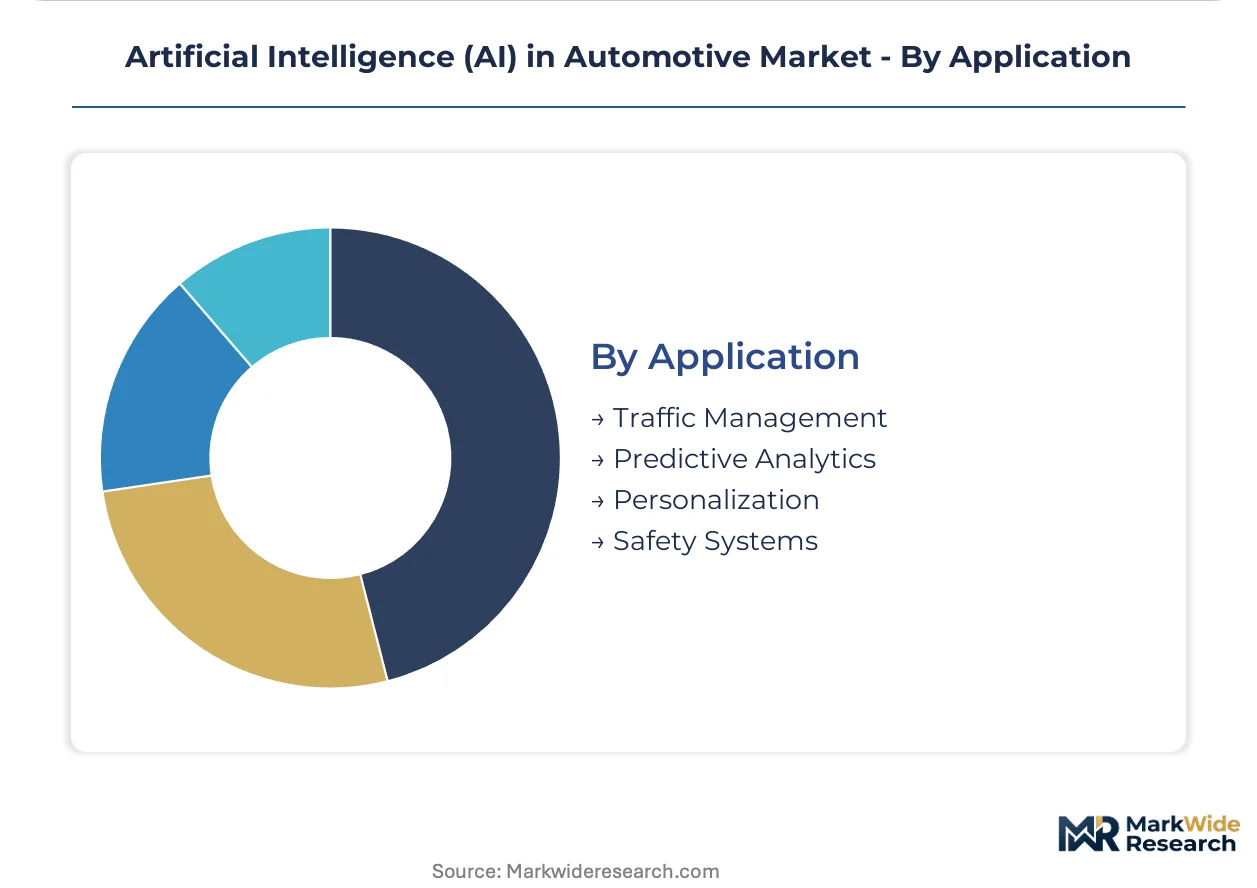
Application:
Safety-critical functions command premium pricing while personalization remains undifferentiated.
- Safety Systems:Collision avoidance, occupant monitoring, and emergency response functions with sub-50-millisecond latency requirements. NHTSA failure-mode documentation imposes 40-60% overhead on validation timelines for these applications.
- Predictive Analytics:Fleet telematics and operational optimization tools prioritizing vehicle uptime over scheduled maintenance.
- Traffic Management:Vehicle-to-infrastructure coordination and congestion optimization.
- Personalization:Adaptive cabin settings and user preference learning.
Investment concentrates in Safety Systems. Predictive Analytics climbs the fastest as commercial operators prioritize operational efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting automotive AI development investment toward jurisdictions with clearer compliance pathways and subsidized infrastructure. Cost-of-compliance gaps between the EU AI Act's documentation requirements and lighter-touch regimes in Asia are accelerating facility relocation decisions.
United States
Fleet operators in the Midwest are compressing procurement cycles for predictive maintenance platforms. NHTSA failure-mode documentation mandates impose extended validation timelines for safety-critical systems. Detroit anchors Tier-1 supplier consolidation around sensor fusion partnerships.
Germany
Volkswagen, BMW, and Mercedes-Benz are consolidating supplier relationships around computer vision perception stacks. The EU AI Act's algorithmic transparency requirements force restructuring of training data provenance systems. Stuttgart and Munich host captive development centers for ADAS validation.
China
Domestic OEMs are scaling end-to-end neural network deployment for autonomous driving. MIIT and SAMR enforce GB standards for connected vehicle data localization. Shenzhen and Shanghai concentrate cloud infrastructure investment for captive data processing.
India
Commercial vehicle fleet operators lack indigenous AI suppliers for driver assistance retrofits. The PLI scheme for automotive electronics creates subsidy-backed entry channels. Tamil Nadu and Karnataka are emerging as electronics manufacturing clusters for Tier-1 component sourcing.
Japan
Automotive OEMs are prioritizing edge-computing optimization for embedded safety systems. METI guidelines shape domestic validation standards for AI-driven perception modules. Nagoya anchors supplier networks for sensor fusion hardware integration.
Artificial Intelligence (AI) in Automotive Market Vendor Landscape
Silicon-to-software integration dominates the current landscape as vendors capture margin through stack control rather than component sales. The market exhibits tiered concentration with full-stack platform providers, specialized sensor fusion vendors, and training infrastructure suppliers occupying distinct competitive positions. Three archetypes define current positioning: captive vertical integrators controlling hardware-software interfaces, modular component suppliers serving multiple OEMs, and cloud-centric training platform operators. M&A activity and strategic partnerships represent the dominant competitive moves as players fill capability gaps.
Within the full-stack integrator tier, Tesla exemplifies captive control from silicon through deployment software. NVIDIA Corporation anchors the training infrastructure segment with GPU-dependent supply relationships. Continental AG represents the European sensor fusion specialist archetype serving consolidated OEM partnerships. Each occupies a position defined by their chosen depth of stack integration rather than geographic or scale differentiation alone.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Tesla |
| NVIDIA Corporation |
| Aptiv PLC |
| Waymo LLC |
| Intel Mobileye |
| Continental AG |
| Huawei Technologies |
| Qualcomm Technologies |
| Others |
Supply Flow & Price Mechanics
Fleet operator procurement consolidation around predictive maintenance platforms anchors the dominant subscription-based pricing model. These buyers now demand bundled telematics and driver coaching services rather than discrete hardware purchases, transferring capital burden to suppliers while compressing channel margins.
Pricing Analysis
Direct-to-OEM discount structures dominate the channel-margin layer, with Tier-1 suppliers absorbing 15-25 point concessions for volume commitments. Three-tier pricing structure across premium ASIL-D certified, standard ISO 26262 compliant, and economy non-safety-critical levels reflects validation investment differentiation. Cost compression in the economy tier is intensifying because open-source framework commoditization erodes software licensing premiums. Aftermarket retrofit providers exhibit highest price sensitivity due to thin working capital reserves, while German OEM captive partnerships show lowest sensitivity given long-term platform lock-in.
Supply Chain Analysis
Advanced GPU fabrication rests on Taiwan Semiconductor Manufacturing capacity, with South Korea and USA anchoring memory and packaging inputs. Silicon wafer supply draws from Japanese specialty chemical producers, while German sensor fusion hardware feeds from Bavarian precision manufacturing clusters. Single-source vulnerability in 3nm foundry capacity creates 18-24 month allocation volatility for training infrastructure. Distribution runs through consolidated Tier-1 supplier networks serving OEM platform engineering teams directly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's algorithmic transparency mandates function as a regulatory compounder, creating captive demand for audit-ready training data infrastructure that rewrites supplier development workflows.
For Market Incumbents: Hedge against end-to-end neural network consolidation by deepening sensor fusion partnerships with German OEMs. Capture premium positioning through embedded documentation tools that satisfy EU AI Act conformity assessment requirements. Prioritize ASIL-D certification investment to defend margin against commoditization pressure from open-source machine learning frameworks. For New Entrants and Emerging Players: Launch via India PLI scheme subsidy channels targeting commercial vehicle retrofit demand. White-space concentration sits in voice-controlled cabin systems merging large language model architectures, a hybrid interface category undefined by incumbent Tier-1s. Pursue fleet operator direct relationships bypassing traditional OEM procurement gates. For Investors and Strategic Acquirers: Tier-1 automotive suppliers facing margin compression are the most active acquirer in this space, seeking edge-computing prognostics capabilities to pivot toward uptime economics. Long-term viability favors full-stack platform providers with captive financing capabilities over discrete component vendors. Watch NHTSA failure-mode documentation enforcement intensity as inflection indicator for validation timeline risk.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon-Software Co-Design Investment | NVIDIA and Qualcomm capture margin through integrated inference optimization for embedded edge processors. |
| EU AI Act Compliance Infrastructure Buildout | Continental AG and Robert Bosch GmbH restructure quality management systems around notified body audit pathways. |
| Fleet Platform Subscription Pivot | Predictive maintenance vendors bundle telematics and driver coaching into 5-year contractual lock-in. |
| India Manufacturing Footprint Establishment | Tamil Nadu electronics clusters attract Tier-1 component sourcing for PLI scheme beneficiaries. |
| End-to-End Neural Network Deployment | Tesla and Waymo eliminate subsystem supplier tiers through unified sensor-to-steering architectures. |
Methodological Framework
Bottom-up fleet operator and OEM procurement modeling reconciled against top-down GPU cluster deployment and vehicle production tracking forms the analytical core. Primary interviews with Tier-1 supplier procurement leads, OEM platform engineers, aftermarket distributors, and commercial fleet operations managers combined with secondary validation from NHTSA incident databases, EU AI Act regulatory filings, vehicle registration data, and semiconductor foundry capacity disclosures. Triangulation across these sources constrains estimation variance.
Historical trendline analysis of computer vision pipeline deployment and predictive maintenance adoption rates informed the projection framework. Segmentation dimensions span technology type, product category, end-user procurement authority, and application safety criticality across the analysis window. CAGRs derive from fitted growth curves against validated endpoint constraints. Embedded systems talent scarcity and ISO 26262 certification timeline elasticity function as key forecast sensitivity inputs.
Several conditions sit outside the modeled scope, including geopolitical disruption to Taiwan semiconductor fabrication, lithium-ion battery thermal runaway liability regime shifts, and autonomous vehicle regulatory reclassification. Forecasts reflect documented assumptions about foundry capacity expansion and fleet electrification penetration. A small set of named triggers warrants ongoing watch: NHTSA enforcement intensity, EU AI Act notified body capacity constraints, and China GB standard data localization expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Conversation Intelligence Software Market
Artificial Intelligence (AI)
AI Dubbing Software Market
Artificial Intelligence (AI)
Autonomous AI and Autonomous Agents Market
Artificial Intelligence (AI)
AI in Project Management Market
Artificial Intelligence (AI)
Text-To-Speech (TTS) Market
Artificial Intelligence (AI)
Enterprise LLM Market
Artificial Intelligence (AI)
AI Recruitment Market
Artificial Intelligence (AI)
Far-Field Speech and Voice Recognition Market
Artificial Intelligence (AI)
Latin America Artificial Intelligence Market
Artificial Intelligence (AI)
Global Artificial Intelligence in E-Commerce Market
Artificial Intelligence (AI)
North America Artificial Intelligence Market
Artificial Intelligence (AI)
Artificial Intelligence-Based Security Market
Artificial Intelligence (AI)
Embedded AI Market
Artificial Intelligence (AI)
Europe AI Orchestration Market
Artificial Intelligence (AI)
Edge AI Market
Artificial Intelligence (AI)
Artificial Intelligence Oven Market