
 Automotive Gesture Recognition Market | 2026-2036
Automotive Gesture Recognition Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Gesture Recognition Market Analysis
Asset-light semiconductor licensing models are reshaping competitive entry in automotive gesture recognition. Qualcomm Incorporated leverages its Snapdragon cockpit platforms to anchor software-defined vehicle architectures. NVIDIA Corporation specializes in AI-driven gesture inference at the edge, sustaining premium positioning among autonomous driving stacks. Continental AG dominates sensor integration, controlling supply relationships with European OEMs seeking bundled haptic-gesture modules.
Automotive gesture recognition encompasses contactless human-machine interface technologies that interpret hand movements, body posture, or eye gaze through infrared, optical, or capacitive sensing arrays operating at wavelengths between 850 and 940 nanometers. These systems reduce manual distraction by enabling drivers to adjust infotainment, climate, or navigation functions without physical contact. Camera-based architectures lead current revenue pools due to their compatibility with existing driver-monitoring hardware, while ultrasonic technologies represent the fastest-expanding segment as Tier-1 suppliers seek lower-cost alternatives for mid-range vehicle platforms. Optical sensing captures concentrated margin pools in premium segments where multi-modal fusion with voice recognition commands price premiums.
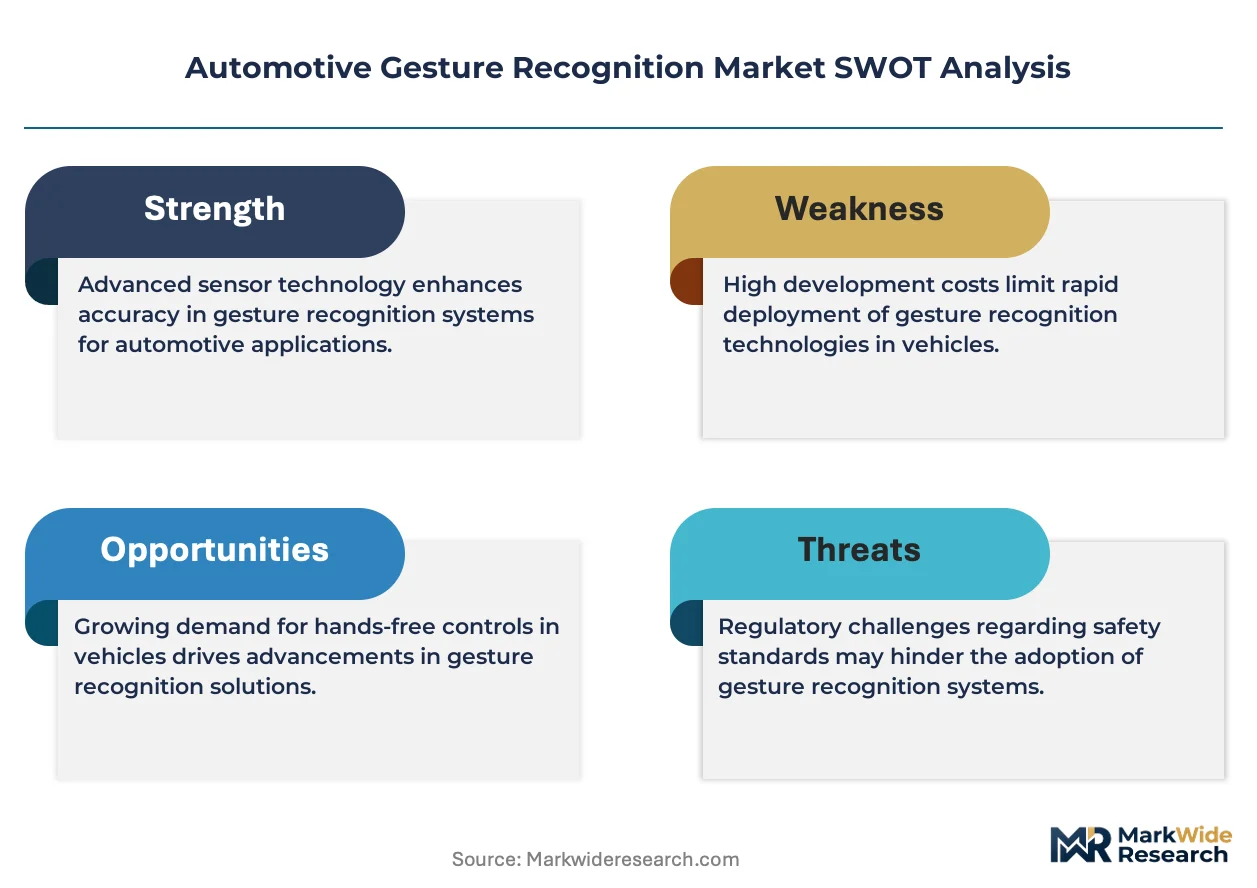
NHTSA distraction guidelines, UNECE WP.29 regulations, and the EU AI Act collectively mandate validated reliability thresholds for in-cabin gesture systems before type approval. These frameworks compel OEMs and Tier-1 Suppliers to document functional safety cases and algorithmic transparency for gesture interpretation models. Stakeholders must monitor evolving harmonization between regional certification regimes to avoid fragmented compliance costs that could constrain platform standardization.
Market Dynamics
Software-defined vehicle architectures are compressing hardware refresh cycles while mandating modular gesture interfaces that can update through over-the-air delivery. This structural shift forces Tier-1 suppliers to decouple sensor hardware from inference software, fragmenting traditional bundled procurement relationships.
Growth Catalysts
- EU AI Act certification mandates:European OEMs must validate algorithmic transparency for in-cabin sensing systems, creating pull for pre-certified gesture recognition modules that accelerate type approval timelines.
- Mid-range platform expansion:Ultrasonic gesture arrays are penetrating volume vehicle segments as cost-sensitive manufacturers seek touchless alternatives to capacitive touchscreens.
- Driver distraction liability frameworks:NHTSA guidelines in the United States and UNECE WP.29 regulations are hardening enforcement against manual interface interactions during vehicle operation.
Market Restraints
- Sensor fusion complexity:Multi-modal systems combining infrared, optical, and capacitive arrays require specialized calibration expertise that concentrates among German and Japanese Tier-1 suppliers.
- Silicon supply concentration:Edge AI inference chips for gesture processing depend on Taiwan semiconductor fabrication capacity, exposing OEMs to geopolitical supply disruption.
- Capacitive touchscreen substitution:Mature haptic feedback technologies in premium vehicles limit price premiums available to camera-based gesture alternatives.
Strategic Opportunities
- Commercial vehicle underpenetration:Fleet operators in long-haul trucking segments remain unserved by gesture interfaces designed around passenger car cabin geometries.
- Voice-gesture convergence:Multi-modal control stacks that fuse natural language processing with hand tracking are commanding integration partnerships between cockpit software providers and AI semiconductor vendors.
- India automotive safety mandates:The country's Bureau of Indian Standards is evaluating cabin monitoring requirements that would import EU-equivalent certification standards for new vehicle categories.
Industry Challenges
- Functional safety engineering scarcity:ISO 26262 ASIL certification expertise for gesture inference algorithms concentrates among a limited pool of automotive software engineers in Stuttgart and Tokyo.
- Legacy bus architecture integration:Established CAN and LIN networks in running vehicle platforms resist real-time gesture data throughput without gateway hardware retrofits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Gesture Recognition Market |
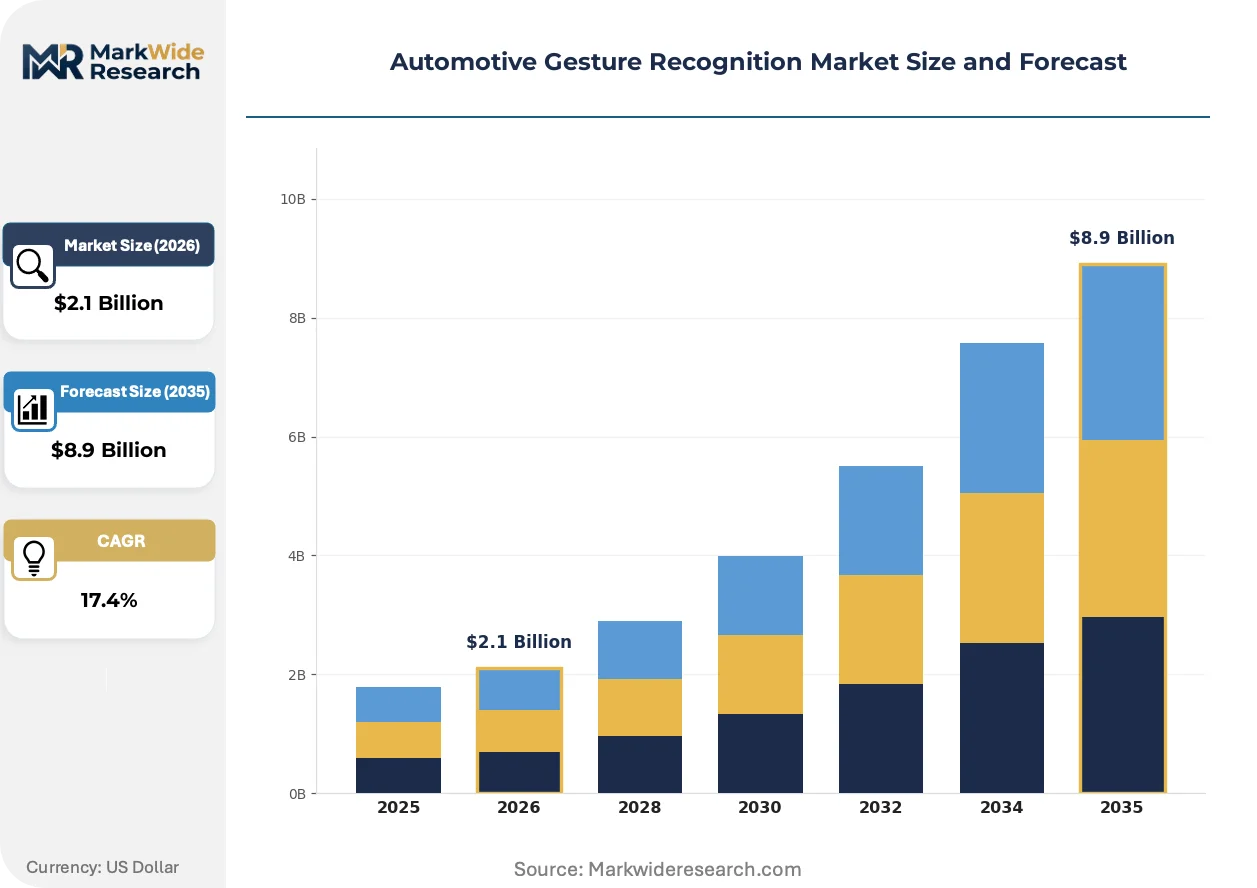
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $8.9 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Camera-Based, Touchless Sensors, Steering Wheel Controls, Voice Recognition Technology: Infrared, Ultrasonic, Capacitive, Optical End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Application: Infotainment, Driver Monitoring, Vehicle Control, Safety Features |
| Companies Covered | Continental AG, Robert Bosch GmbH, Synaptics Incorporated, Visteon Corporation, NXP Semiconductors, Qualcomm Incorporated, Harman International Industries, Valeo, NVIDIA Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Gesture Recognition Market Emerging Trajectories
Edge AI inference is migrating gesture processing from centralized cockpit controllers to dedicated sensor modules, compressing latency while fragmenting software architecture decisions across OEM engineering teams.
Time-of-flight depth cameras with 940 nanometer wavelength operation are rendering obsolete single-plane infrared arrays that struggle with variable cabin lighting conditions. Premium German OEMs are adopting these modules across flagship electric vehicle lines. The technology is rendering obsolete legacy two-dimensional hand tracking that fails under direct sunlight exposure through panoramic glass roofs.
UNECE WP.29 regulations on driver monitoring systems are mandating standardized performance thresholds for gaze and gesture detection accuracy. European type approval authorities now require documented failure-mode analysis for all in-cabin sensing algorithms. Volume manufacturers are responding by pre-integrating certified sensor modules rather than developing proprietary gesture stacks.
Fleet procurement managers are bundling gesture interface specifications into multi-year cockpit platform contracts, displacing discrete component sourcing. Tier-1 suppliers are responding with subscription-based software licensing that decouples hardware from feature activation. This shift is most visible in United States commercial vehicle segments where total-cost-of-ownership calculations dominate specification decisions.
Automotive Gesture Recognition Market Segmentation
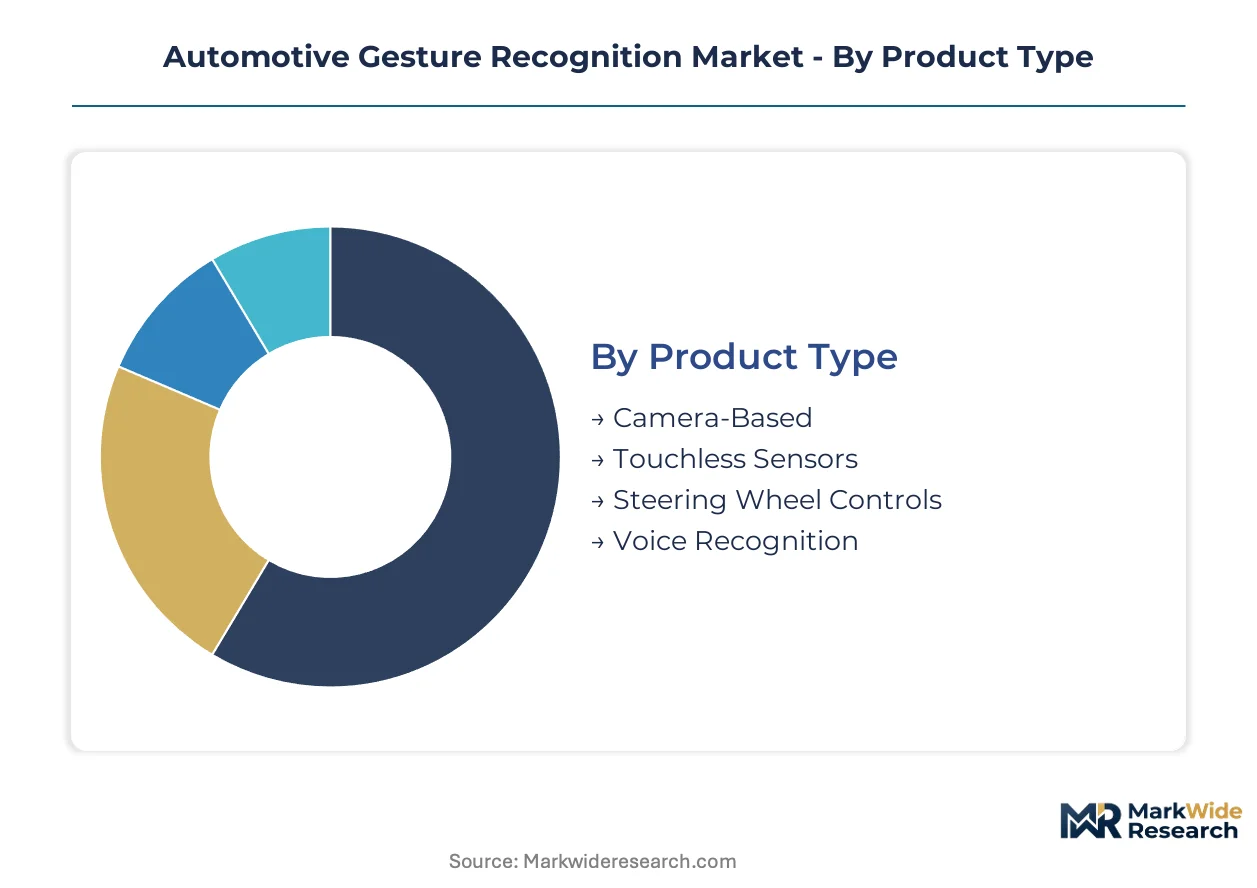
Gesture recognition systems fragment across hardware form factors, sensing modalities, supply chain tiers, and in-cabin use cases. Each dimension carries distinct certification requirements and margin structures that shape procurement decisions.
Product Type:
Mature hardware formats dominate current revenue pools while emerging contactless interfaces gain traction in next-generation cockpit designs.
- Camera-Based:These systems deploy infrared or time-of-flight depth sensors operating at 850-940 nanometer wavelengths to track hand position and motion vectors. German and Japanese OEMs concentrate procurement for flagship electric vehicle lines where panoramic glass roofs demand robust performance under variable lighting.
- Touchless Sensors:Ultrasonic and capacitive proximity arrays detect presence and coarse gestures without optical components. Mid-range vehicle platforms in the United States are adopting these modules as cost-effective alternatives to camera systems for basic climate and volume control functions.
- Steering Wheel Controls:Integrated haptic-gesture pads embedded in rim surfaces enable thumb-based command inputs.
- Voice Recognition:Natural language processing stacks fused with gesture confirmation signals form multi-modal control architectures.
Camera-Based retains volume leadership; Touchless Sensors holds the steepest expansion curve.
Technology:
Cost tier differentiation separates premium multi-modal fusion from single-technology implementations in volume segments.
- Infrared:Near-infrared LED arrays paired with CMOS imagers constitute the established baseline for hand tracking, offering proven performance in low-light cabin conditions. European Tier-1 suppliers control calibration expertise for these systems.
- Ultrasonic:Piezoelectric transducer grids emit high-frequency pulses to detect hand position through time-of-flight measurement. South Korean and Chinese component manufacturers are scaling production for entry-level vehicle categories.
- Capacitive:Electric field disruption sensors enable proximity detection without line-of-sight requirements.
- Optical:Visible-spectrum and structured-light cameras support gaze tracking and facial recognition integration.
Infrared maintains installed-base dominance; Ultrasonic climbs the fastest on unit economics.
End User:
Supply concentration varies sharply between vertically integrated OEM programs and distributed aftermarket channels.
- OEMs:Premium passenger vehicle manufacturers in Germany, Japan, and the United States specify gesture modules at platform design stage, locking in multi-year supply agreements with certified Tier-1 partners.
- Tier-1 Suppliers:Continental AG and comparable integrators bundle sensor hardware with functional safety certification, capturing margin pools from OEMs seeking accelerated type approval.
- Aftermarket Providers:Retrofit kit distributors target vehicle owners seeking cabin technology upgrades without factory installation.
- Vehicle Assemblers:Contract manufacturing operations for emerging EV brands procure pre-integrated cockpit modules containing gesture capability.
OEMs command specification authority; Tier-1 Suppliers capture certification-value capture.
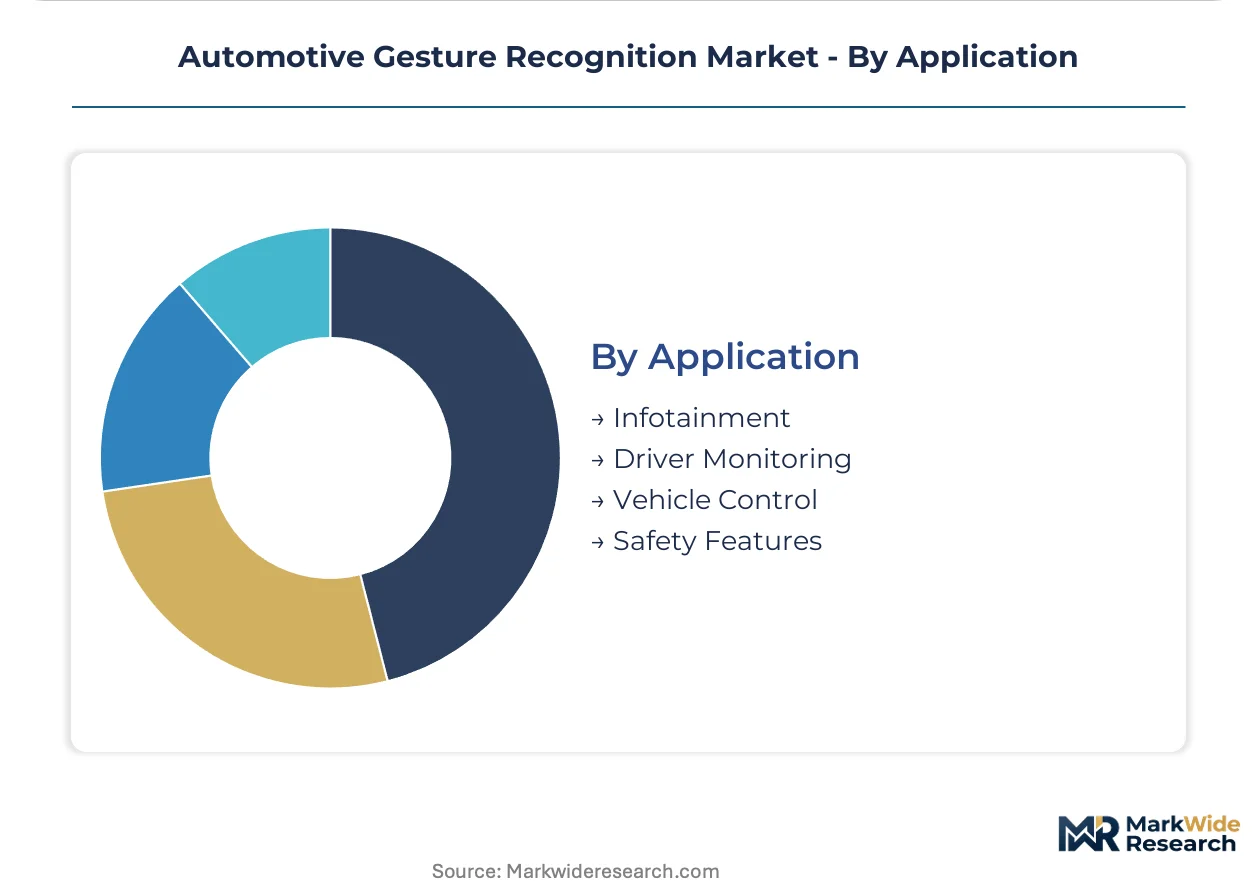
Application:
Regulatory mandates are displacing discretionary infotainment adoption toward mandated driver monitoring functions.
- Infotainment:Media selection, navigation input, and menu browsing constitute the original commercial use case, now mature in premium segments. NHTSA distraction guidelines are constraining expansion as regulators scrutinize cognitive load.
- Driver Monitoring:Gaze tracking and drowsiness detection systems are becoming mandatory under UNECE WP.29 regulations and EU AI Act certification requirements, forcing standardization across European vehicle categories.
- Vehicle Control:Climate adjustment, sunroof operation, and lighting commands via gesture reduce manual distraction.
- Safety Features:Emergency gesture recognition for hazard activation and occupant status verification.
Infotainment retains revenue scale; Driver Monitoring gains share fastest on regulatory compulsion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in automotive gesture recognition components favor established manufacturing clusters in Germany, Japan, and South Korea, while the United States and China balance domestic assembly capacity with selective technology licensing inflows.
Germany
Premium electric vehicle platforms from BMW and Mercedes-Benz drive specification demand for time-of-flight camera modules. The EU AI Act mandates algorithmic transparency documentation for all in-cabin sensing systems seeking type approval. Stuttgart engineering consultancies concentrate ISO 26262 functional safety certification expertise for gesture inference software.
United States
NHTSA distraction guidelines compel Detroit automakers to integrate touchless interfaces that reduce manual screen interaction during vehicle operation. Federal Motor Vehicle Safety Standards require documented failure-mode analysis for driver monitoring systems. Michigan-based Tier-1 suppliers coordinate sensor fusion calibration with Silicon Valley edge AI semiconductor vendors.
Japan
Tokyo and Nagoya manufacturing corridors anchor infrared sensor production for hand-tracking modules integrated into Toyota and Honda flagship lines. METI industrial standards harmonize with UNECE WP.29 regulations on driver monitoring performance thresholds. Osaka-based component houses specialize in capacitive proximity arrays for climate control applications.
South Korea
Hyundai Motor Group's Genesis luxury division sources multi-modal gesture systems from domestic Tier-1 integrators. The country's national automotive safety regulator evaluates cabin monitoring requirements aligned with European certification frameworks. Seoul semiconductor foundries fabricate CMOS imagers operating at 940 nanometer wavelengths for depth-sensing applications.
China
Ningbo and Shenzhen electronics clusters manufacture ultrasonic gesture arrays for entry-level domestic EV brands. MIIT technical standards for intelligent vehicle systems incorporate gesture recognition performance benchmarks. Yangtze River Delta assembly plants export touchless sensor modules to Southeast Asian vehicle assemblers.
Automotive Gesture Recognition Market Vendor Landscape
On the supply side, the industry is consolidating around three strategic layers: semiconductor vendors providing edge AI inference silicon, Tier-1 integrators bundling sensor hardware with functional safety certification, and cockpit software specialists enabling multi-modal fusion architectures. Dominant competitive moves include strategic partnerships between chip designers and automotive OEMs for platform-exclusive gesture stacks, plus geographic expansion through licensing arrangements that bypass direct manufacturing investment.
Among European-headquartered integrators, Continental AG and Robert Bosch GmbH exemplify the bundled hardware-certification archetype that captures margin pools from OEMs seeking accelerated regulatory approval. NVIDIA Corporation and Qualcomm Incorporated occupy positions at the semiconductor tier, supplying inference engines for software-defined vehicle architectures without direct sensor manufacturing exposure. Synaptics Incorporated represents the specialist tier focused on touchless interface intellectual property rather than full-system integration.
| Leading Market Players |
|---|
| Continental AG |
| Robert Bosch GmbH |
| Synaptics Incorporated |
| Visteon Corporation |
| NXP Semiconductors |
| Qualcomm Incorporated |
| Harman International Industries |
| Valeo |
| NVIDIA Corporation |
| Others |
Supply Flow & Price Mechanics
Rotterdam-to-Hamburg freight corridors transmit cost volatility from Taiwan semiconductor foundries into European Tier-1 supplier pricing, compressing margins on camera-based gesture modules while amplifying price differentiation between ISO 26262-certified and uncertified sensor tiers.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Certification grade under ISO 26262 ASIL-D and volume scale constitute the primary differentiation drivers. Pricing pressure stems from ultrasonic alternatives penetrating mid-range platforms. Fleet procurement managers exhibit highest price sensitivity; luxury German OEMs demonstrate lowest.
Supply Chain Analysis
Taiwan Semiconductor Manufacturing Company and Seoul-based foundries hold concentrated capacity for edge AI inference chips. Taiwan, South Korea, and Germany anchor component supply. CMOS imagers, piezoelectric transducers, and near-infrared LED arrays constitute critical inputs. Single-source vulnerability in Taiwan fabrication capacity poses structural risk. Distribution runs through Tier-1 integrators bundling hardware with functional safety certification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive gesture recognition is approaching a platform-economics inflection where software-defined vehicle architectures decouple sensor hardware from feature activation, rewarding ecosystem orchestrators over component specialists.
For Market Incumbents: Insulate certification-value capture by deepening backward integration into 940-nanometer CMOS imager supply and securing exclusive platform engineering relationships with German luxury OEMs. Threat from ultrasonic cost-down alternatives demands accelerated ASIL-D pre-certification investment. Channel control through subscription-based software licensing represents the critical defensive lever. For New Entrants and Emerging Players: Long-haul commercial vehicle cabins in North American fleet segments represent the most penetrable entry point given unserved geometries and total-cost-of-ownership procurement dominance. India automotive safety mandate preparation offers secondary white-space as BIS evaluates EU-equivalent standards. Go-to-market through fleet management software partnerships bypasses entrenched Tier-1 supply relationships. For Investors and Strategic Acquirers: Edge AI inference software specialists with pre-certified automotive stacks command scarcity premiums in acquisition markets. Long-term viability hinges on software-defined vehicle architecture migration sustaining recurring revenue models. Watch for OTA feature activation penetration rates in flagship electric vehicle lines as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces sensor fusion calibration costs across BMW and Mercedes-Benz electric vehicle programs. |
| Software-Defined Vehicle Investment | Enables over-the-air gesture feature activation decoupled from hardware procurement cycles. |
| Battery Supply Agreement | Secures stable CMOS imager allocation from Yangtze River Delta fabrication clusters. |
| Geographic Manufacturing Footprint | Localizes ultrasonic transducer production in Ningbo for Southeast Asian EV assemblers. |
| Charging Infrastructure Partnership | Integrates gesture control into fleet depot management systems for commercial vehicle operators. |
Methodological Framework
A standing panel of Tier-1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and dealership operations specialists provided ongoing calibration across the analysis window. Primary interview insights combined with secondary validation from vehicle production databases, IHS Markit registration data, SEC filings, and customs records. Bottom-up sensor unit economics and top-down cockpit content forecasts underwent rigorous triangulation.
Scenario-bracketing framed analytical approach across the projection horizon, modeling vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster dimensions. CAGRs derived from segmented unit-volume trajectories and average selling price curves. Edge AI semiconductor capex disclosures and UNECE WP.29 regulatory timeline assumptions informed forecast sensitivity bands.
Practitioners should monitor Taiwan semiconductor capacity utilization, EU AI Act enforcement consistency, and ultrasonic sensor cost curves for early signals of forecast revision. Assumptions underlying volume projections remain contingent on harmonized certification standards across regional regimes. Quarterly review of flagship electric vehicle gesture content specifications and fleet procurement contract terms is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Artificial Intelligence in Workspace Market
Artificial Intelligence (AI)
Federated Learning Market
Artificial Intelligence (AI)
AI Task Manager App Market
Artificial Intelligence (AI)
Global Insight Engines Market
Artificial Intelligence (AI)
Artificial Intelligence for IT Operations (Aiops) Market
Artificial Intelligence (AI)
Reinforcement Learning Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Sports Market
Artificial Intelligence (AI)
Global Ambient Intelligence Market
Artificial Intelligence (AI)
AI in Medical Writing Market
Artificial Intelligence (AI)
Commercial Artificial Intelligence Market
Artificial Intelligence (AI)
Edge AI Hardware Market
Artificial Intelligence (AI)
North America Chatbot Market
Artificial Intelligence (AI)
AI-Ready Enterprise Knowledge Graph Market
Artificial Intelligence (AI)
Global Cloud Telecommunication AI Market
Artificial Intelligence (AI)
AI As a Service (Aiaas) Market
Artificial Intelligence (AI)
Global Voice Assistant Application Market