
 Global Ambient Intelligence Market | 2026-2036
Global Ambient Intelligence Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ambient Intelligence Market Foresight
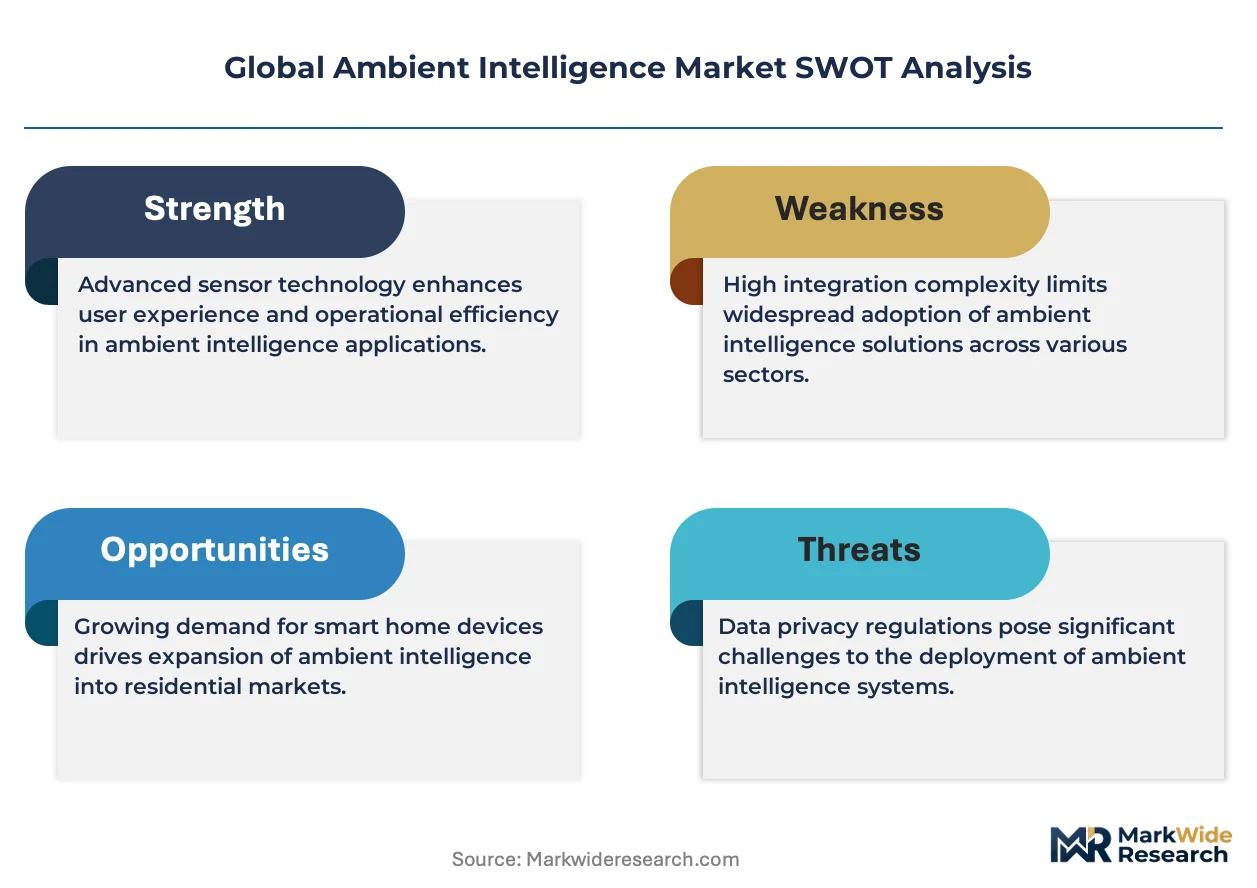
Platform unbundling into modular sensor-as-a-service offerings is realigning procurement patterns across enterprise buyers. Siemens AG leverages its building automation heritage to anchor large-scale deployments in European commercial real estate. Honeywell International Inc. competes through R&D intensity in edge analytics hardware. Microsoft Corporation extends cloud-native AI orchestration layers that integrate disparate sensor networks.
Ambient intelligence denotes environments where embedded sensor arrays, context-aware algorithms, and adaptive interfaces operate invisibly to anticipate human needs without explicit commands, typically processing data through sub-100ms latency thresholds to enable real-time environmental responsiveness. The technology dimension shows context-aware computing and pervasive sensors capturing dominant deployment share as foundational layers, while machine learning applications command premium margins through predictive personalization. Application-side growth concentrates in adaptive workspaces and intelligent transportation, where operational efficiency gains justify capital outlays.
The EU AI Act and GDPR impose strict algorithmic transparency and data minimization requirements on sensor networks processing biometric or behavioral data. The FCC in the United States governs spectrum allocation for low-power wide-area sensor communications, directly constraining device density in smart building deployments. China's SAMR and MIIT enforce GB standards for networked device interoperability and cybersecurity certification. Stakeholders must monitor regulatory divergence across these jurisdictions to determine whether to architect single compliant platforms or regionally differentiated technology stacks.
Market Dynamics
Platform unbundling into modular sensor-as-a-service offerings is fundamentally restructuring procurement economics across enterprise buyers, forcing incumbents to abandon integrated hardware-software bundles in favor of API-first architectures that reduce upfront capital barriers.
Growth Catalysts
- EU AI Act algorithmic transparency mandates:The regulation's risk-based classification system for biometric processing is accelerating enterprise investment in explainable sensor analytics to preempt compliance penalties.
- China's metropolitan technology corridors:Municipal authorities in Shenzhen, Shanghai, and Hangzhou fund intelligent infrastructure at scale, creating concentrated demand pools for integrated building automation systems.
- Edge analytics hardware maturation:Sub-50 millisecond inference latency on ARM-based neural processing units enables real-time environmental responsiveness without cloud dependency.
Market Restraints
- GDPR data minimization requirements:The regulation's purpose limitation principle constrains behavioral data retention periods, compressing training dataset availability for predictive personalization models.
- Rare earth element supply concentration:Neodymium and dysprosium processing dominance in China's Jiangxi and Inner Mongolia provinces creates geopolitical exposure for sensor magnet supply chains.
- Millimeter-wave spectrum fragmentation:Inconsistent national allocations for 60 GHz unlicensed bands force hardware variants that fragment manufacturing scale economies.
Strategic Opportunities
- India's smart cities mission:The Ministry of Housing and Urban Affairs' AMRUT 2.0 scheme funds intelligent street lighting and waste management systems in 100 urban agglomerations.
- Fusion of spatial computing with ambient sensing:Apple Vision Pro and Meta Quest ecosystem penetration creates demand for room-scale sensor mesh calibration services.
- Outcome-based facility management contracts:Energy service companies in Germany now guarantee kilowatt-hour reductions through sensor-driven HVAC optimization, shifting revenue models from hardware to performance.
Industry Challenges
- Embedded systems security certification:IEC 62443-4-2 component-level compliance timelines extend 14-18 months, delaying product launches for industrial automation vendors.
- Interoperability protocol fragmentation:Matter, Zigbee, Z-Wave, and proprietary mesh networks coexist without dominant standard, forcing multi-protocol gateway complexity.
- Cross-functional talent scarcity:The intersection of RF engineering, machine learning operations, and building systems expertise remains underdeveloped in technical education pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ambient Intelligence Market |
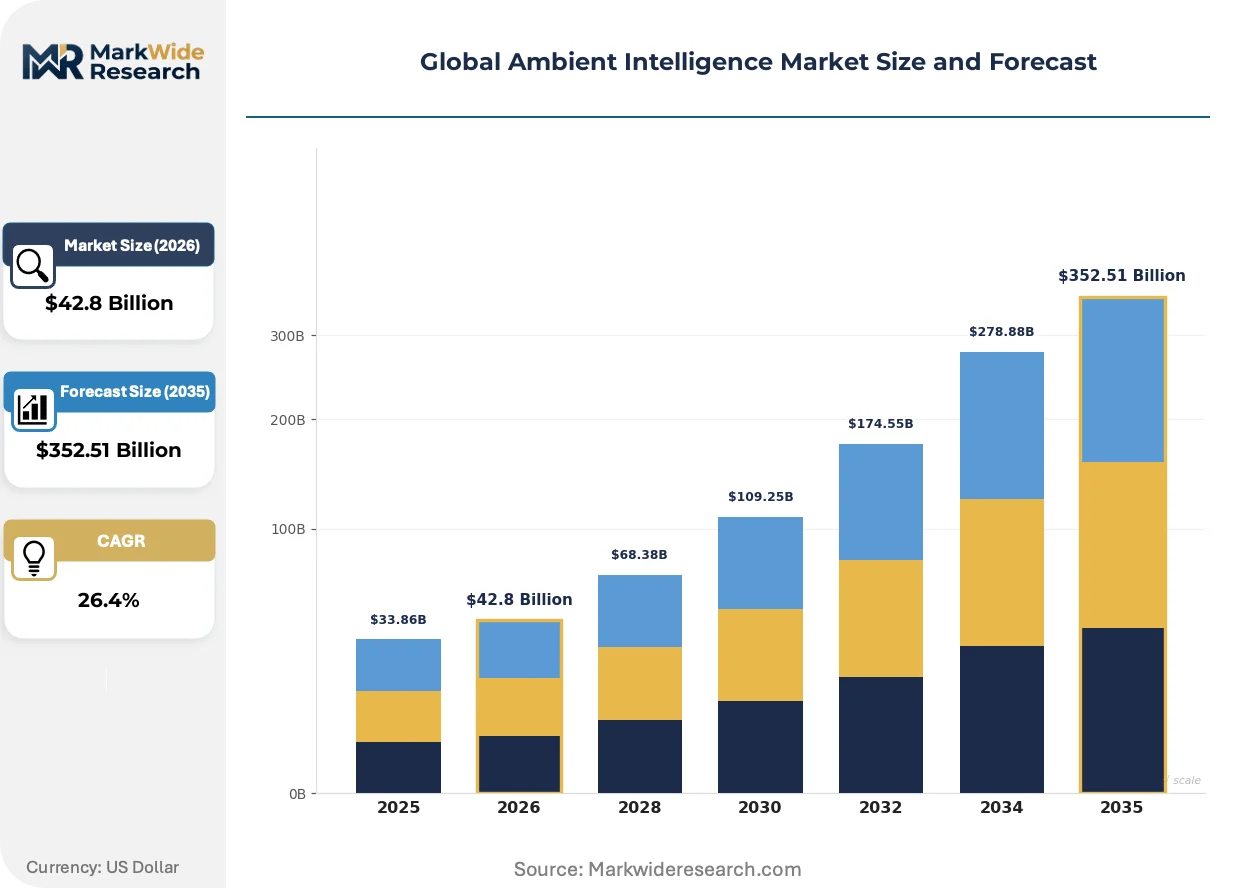
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $352.51 Billion |
| CAGR (2026 – 2036) | 26.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Context-Aware Computing, Pervasive Sensors, Natural Language Processing, Machine Learning, Ubiquitous Computing Application: Smart Homes, Personalized Retail, Adaptive Workspaces, Public Safety Systems, Intelligent Transportation End User: Consumer Electronics, Retail Chains, Corporate Offices, Municipal Authorities, Hospitality Venues Deployment: Cloud-Based Systems, Edge Computing, On-Premises Solutions, Hybrid Platforms, Fog Computing |
| Companies Covered | Siemens AG, Honeywell International Inc., Johnson Controls, Schneider Electric SE, Infosys Limited, ABB Ltd., Amazon.com Inc., Intel Corporation, Microsoft Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ambient Intelligence Market Shifts & Advancements
Federated learning architectures and on-device model compression are redistributing computational intelligence away from centralized cloud infrastructure, enabling privacy-preserving personalization while reducing bandwidth costs for dense sensor deployments.
Edge-native transformer models optimized for microcontroller memory constraints are decentralizing inference workloads previously requiring GPU clusters. Facility operators in Singapore and Dubai commercial towers deploy these models for occupancy prediction without transmitting raw video feeds. The shift compresses data egress costs by 60-80% while satisfying GDPR and UAE data sovereignty requirements.
The EU AI Act's high-risk system registration obligations are forcing sensor vendors to implement algorithmic change logging and human oversight interfaces by default. Industrial automation suppliers serving European manufacturing now embed model cards and bias testing documentation directly into device firmware. Medical-grade ambient monitoring systems face the strictest conformity assessment timelines, with notified body queues extending 12-16 months.
Enterprise real estate teams are consolidating vendor relationships around full-stack platform providers rather than point-solution sensor suppliers. JLL and CBRE procurement frameworks now prioritize single-contract accountability for hardware, software, and ongoing optimization services. This concentration is most visible in London and New York Class A office repositioning projects, where landlords bundle tenant experience apps with underlying sensor infrastructure under unified service level agreements.
Global Ambient Intelligence Market Segmentation
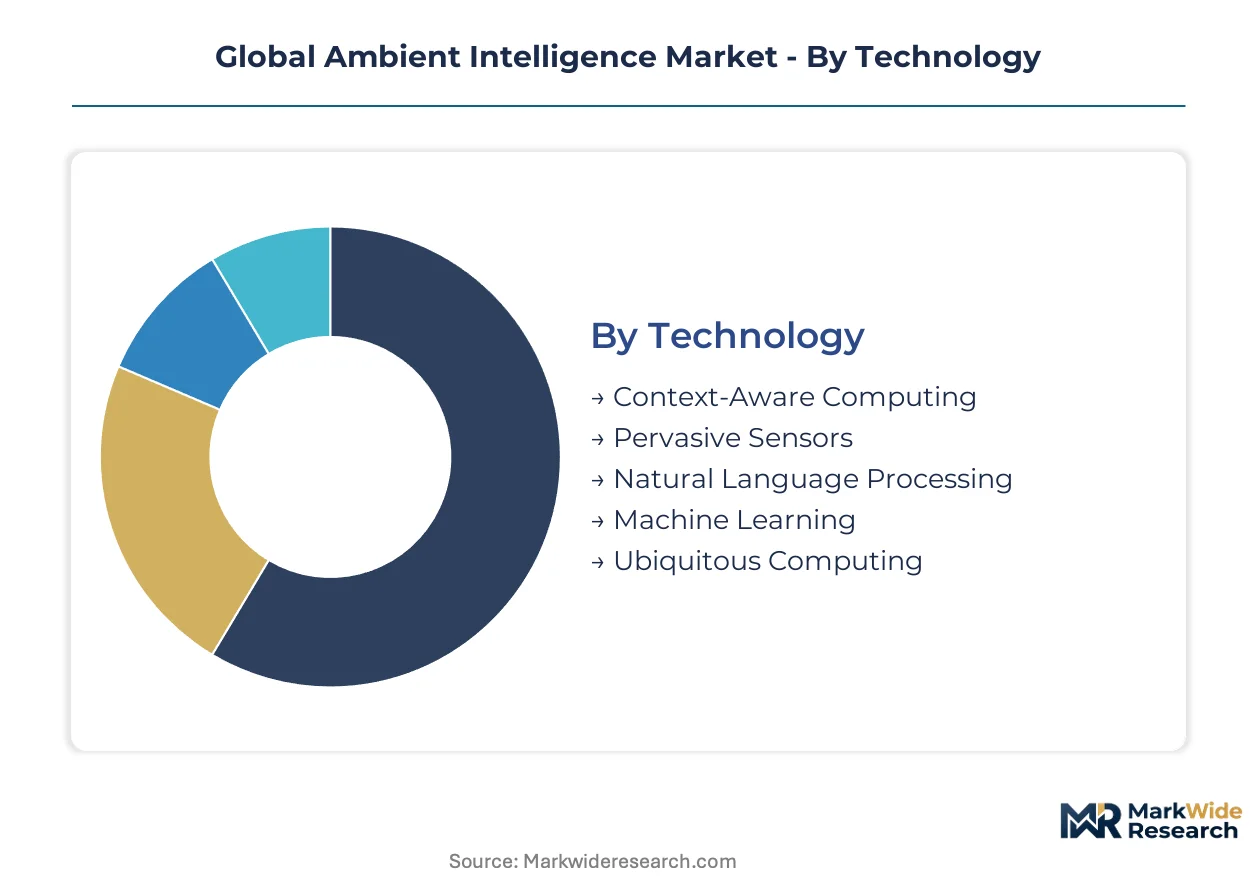
Segmentation in ambient intelligence reveals how procurement economics split between foundational infrastructure and premium intelligence layers. Technology choices determine latency performance and regulatory exposure. Application focus shapes whether deployments prioritize operational efficiency or experiential personalization.
Technology:
Volume concentrates in sensing hardware while premium margins accrue to algorithmic intelligence layers.
- Context-Aware Computing:Middleware systems fuse multi-sensor inputs into situational understanding using probabilistic reasoning engines. Demand clusters in German smart home deployments where GDPR compliance requires on-premise inference. Siemens AG anchors European commercial real estate with building automation heritage.
- Pervasive Sensors:Distributed MEMS arrays capture environmental, biometric, and positional data through low-power wide-area protocols. China's metropolitan technology corridors fund dense deployments in Shenzhen and Shanghai municipal infrastructure.
- Natural Language Processing:Voice interfaces enable command-free environmental control through acoustic scene analysis.
- Machine Learning:Predictive models anticipate occupancy patterns and energy loads from historical behavioral data.
- Ubiquitous Computing:Invisible processing substrates embed computation into architectural surfaces and furnishings.
Today's leader: Pervasive Sensors. Tomorrow's challenger: Machine Learning.
Application:
Cost tier separation runs between capital-intensive infrastructure retrofits and software-layer experience upgrades.
- Smart Homes:Residential deployments integrate climate, lighting, and security systems through unified control planes. Germany's residential complexes accelerate uptake driven by EU AI Act algorithmic transparency requirements for biometric processing.
- Intelligent Transportation:Traffic flow optimization and predictive maintenance systems reduce congestion and operational downtime. Municipal authorities in Hangzhou fund integrated building automation systems at scale.
- Adaptive Workspaces:Occupancy-responsive HVAC and lighting configurations reduce energy intensity per square meter.
- Personalized Retail:In-store behavioral analytics tailor merchandise placement and promotional timing.
- Public Safety Systems:Emergency response acceleration through automated threat detection and resource dispatch.
Smart Homes dominate current procurement volumes; Intelligent Transportation offers the steepest expansion trajectory as municipal infrastructure budgets recover.
End User:
Customer type determines whether deployments prioritize consumer convenience or enterprise return-on-investment metrics.
- Municipal Authorities:City-scale deployments fund intelligent street lighting and waste management through performance guarantees. India's Ministry of Housing and Urban Affairs AMRUT 2.0 scheme targets 100 urban agglomerations.
- Corporate Offices:Class A landlords bundle tenant experience applications with sensor infrastructure under unified service level agreements. JLL and CBRE procurement frameworks in London and New York prioritize single-contract accountability.
- Consumer Electronics:Mass-market voice assistants and home automation hubs drive volume scale.
- Retail Chains:Footfall analytics and inventory optimization justify capital outlays through measurable conversion improvements.
- Hospitality Venues:Guest experience personalization through ambient room configuration and predictive service delivery.
Municipal Authorities anchor infrastructure-scale procurement. Corporate Offices represent the fastest-climbing customer segment as hybrid work models demand spatial optimization.
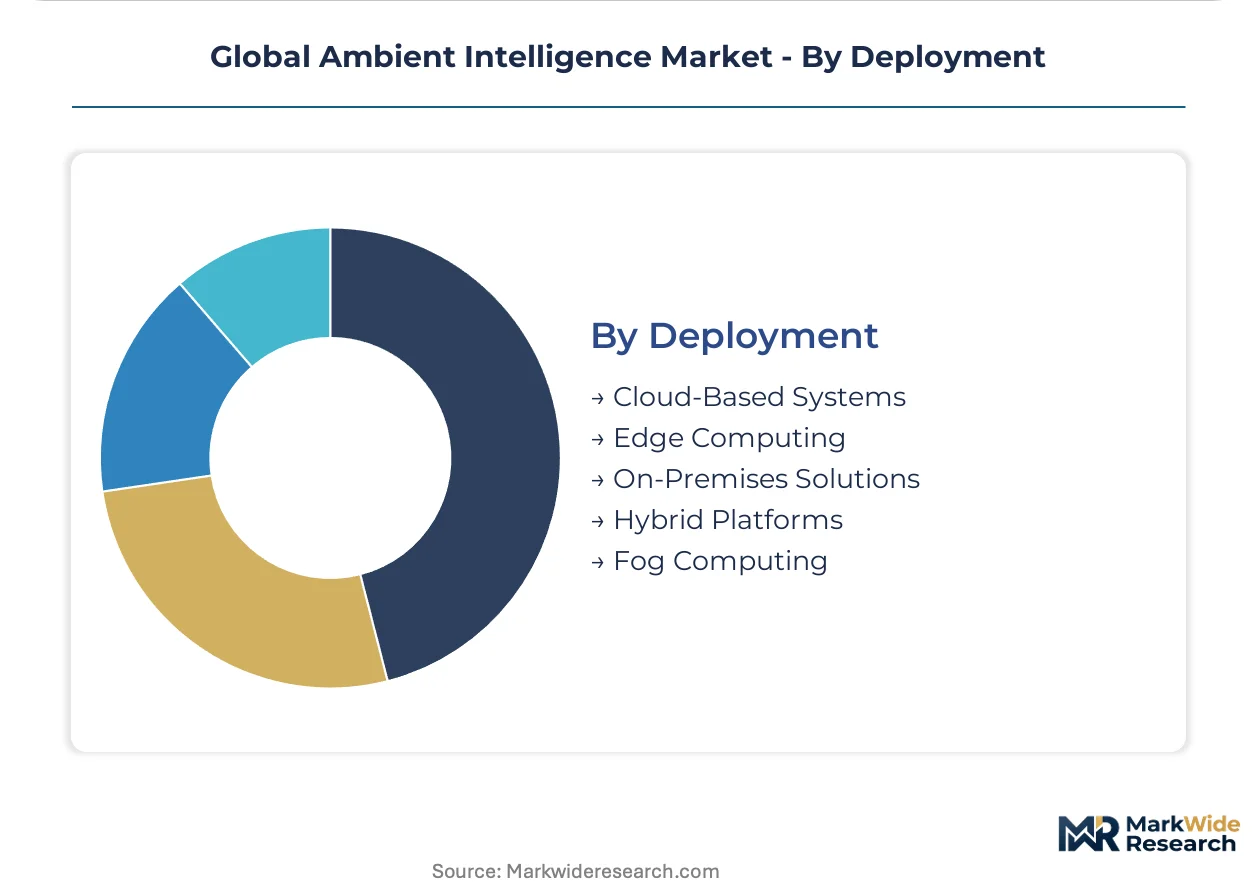
Deployment:
Supply concentration in edge hardware manufacturing creates margin pressure on cloud-native orchestration providers.
- Edge Computing:Sub-50 millisecond inference on ARM-based neural processing units enables real-time responsiveness without cloud dependency. Facility operators in Singapore and Dubai commercial towers deploy occupancy prediction without transmitting raw video feeds.
- Hybrid Platforms:Workload splitting between local inference and cloud training balances latency against model complexity. Microsoft's cloud-native AI orchestration layers integrate disparate sensor networks across enterprise estates.
- Cloud-Based Systems:Centralized model training and fleet management reduce per-device computational requirements.
- On-Premises Solutions:Air-gapped deployments satisfy data sovereignty requirements in regulated industries.
- Fog Computing:Hierarchical processing architectures distribute intelligence across gateway, edge, and cloud tiers.
Edge Computing commands premium pricing for latency-critical applications. Hybrid Platforms are gaining share fastest as procurement teams seek architectural flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ambient intelligence originated in European research laboratories during the late 1990s, with Philips Research in the Netherlands and Fraunhofer Institutes in Germany pioneering the conceptual foundations of context-aware environments before commercial deployment.
United States
Enterprise real estate modernization and federal smart building mandates drive procurement across Class A office portfolios. The FCC governs spectrum allocation for low-power wide-area sensor communications, constraining device density in commercial deployments. Silicon Valley and Boston metropolitan clusters anchor R&D concentration for edge analytics hardware.
Germany
Residential complex retrofits and industrial facility automation absorb substantial sensor infrastructure investment. The EU AI Act's risk-based classification system for biometric processing accelerates enterprise spending on explainable analytics. Siemens AG leverages its building automation heritage to anchor large-scale deployments across North Rhine-Westphalia commercial zones.
China
Municipal authorities in Shenzhen, Shanghai, and Hangzhou fund intelligent infrastructure at scale, creating concentrated demand pools. SAMR and MIIT enforce GB standards for networked device interoperability and cybersecurity certification. The Yangtze River Delta and Pearl River Delta technology corridors concentrate manufacturing scale for sensor hardware exports.
India
The Ministry of Housing and Urban Affairs' AMRUT 2.0 scheme targets intelligent street lighting and waste management across 100 urban agglomerations. BIS certification requirements for electronic product safety shape procurement specifications for municipal tenders. Karnataka and Maharashtra state governments pilot integrated building automation in Bangalore and Mumbai commercial districts.
Singapore
Smart nation infrastructure programs and tropical climate optimization requirements sustain premium deployment rates. The IMDA governs data sovereignty requirements for sensor networks processing personal information. Facility operators in Marina Bay and Raffles Place commercial towers deploy edge-native occupancy prediction without transmitting raw video feeds.
Global Ambient Intelligence Market Competitive Landscape
The competitive structure tilts toward diversified industrial conglomerates with building automation heritage. Market concentration remains moderate, with hardware-software integration capabilities separating tier-one providers from component specialists. Two strategic archetypes dominate: legacy automation vendors leveraging installed base relationships, and cloud-native orchestration platforms integrating disparate sensor networks. Dominant competitive moves include API-first architectural pivots and outcome-based facility management contracting.
Within the diversified industrial tier, Siemens AG and Honeywell International Inc. exemplify archetypes anchored in building automation heritage and R&D intensity in edge analytics hardware respectively. Microsoft Corporation occupies a position on the cloud-native orchestration vector, extending AI layers that integrate sensor networks across enterprise estates. Schneider Electric SE and ABB Ltd. sit within the European automation specialist cluster, while Intel Corporation and Amazon.com Inc. represent technology platform extensions into ambient intelligence infrastructure.
| Leading Market Players |
|---|
| Siemens AG |
| Honeywell International Inc. |
| Johnson Controls |
| Schneider Electric SE |
| Infosys Limited |
| ABB Ltd. |
| Amazon.com Inc. |
| Intel Corporation |
| Microsoft Corporation |
| Others |
Supply & Pricing Matrix
Enterprise procurement consolidation around full-stack platform providers is compressing margins for point-solution sensor vendors and forcing supply chain reconfiguration toward vertically integrated manufacturing footprints that can absorb pricing pressure through captive component sourcing.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies the market by certification grade and after-sales service bundling. Premium tiers command substantial markups for IEC 62443-4-2 compliant industrial systems with embedded cybersecurity warranties. Cost compression in the standard tier intensifies as Chinese MEMS manufacturers expand wafer capacity. Municipal authorities exhibit highest price sensitivity due to public tender transparency requirements, while corporate offices prioritize total cost of ownership over unit pricing.
Supply Chain Analysis
Freight cost volatility from Asia-Pacific manufacturing hubs to European and North American deployment sites is reshaping regional sourcing strategies for time-sensitive building automation projects. Sensor hardware production concentrates in China, Taiwan, and South Korea, with rare earth magnet processing anchored in China's Jiangxi province. The supply chain draws from neodymium, dysprosium, and silicon wafer feedstocks. Single-source vulnerability in advanced neural processing unit fabrication creates exposure for edge analytics vendors. Distribution runs through authorized system integrators and direct OEM relationships with large facility operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Ambient Intelligence Market functions as a stable compounder underpinned by regulatory mandates for building energy efficiency that guarantee replacement demand regardless of macroeconomic cycles.
For Market Incumbents: Extend platform unbundling into modular sensor-as-a-service architectures to preempt cloud-native orchestration challengers. Deepen backward integration into ARM-based neural processing unit design to secure sub-50 millisecond inference latency advantages. Fortify certification pipelines for EU AI Act high-risk system registration before notified body queues lengthen further. For New Entrants and Emerging Players: Capture India's AMRUT 2.0 municipal infrastructure tenders where incumbent presence remains thin and technical specifications favor adaptable API-first solutions. Penetrate the adaptive workspace segment through outcome-based energy performance contracting that shifts buyer risk profiles. Deploy through local system integrator partnerships rather than direct enterprise sales to bypass established vendor relationships. For Investors and Strategic Acquirers: Asymmetric upside sits with edge-native AI software specialists possessing federated learning IP and on-device model compression capabilities. The five-to-ten year viability window favors acquisition targets with demonstrated deployments in Singapore and Dubai commercial towers where data sovereignty requirements create defensive moats. Monitor notified body queue lengths for EU AI Act medical-grade conformity assessments as an inflection indicator for regulatory-driven consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Architecture Pivot | Reduces upfront capital barriers for enterprise buyers and displaces bundled hardware-software incumbents. |
| Outcome-Based Facility Management Contracting | Shifts revenue models from hardware sales to performance guarantees in German energy service markets. |
| Edge-Native Transformer Model Development | Enables GDPR-compliant occupancy prediction in Singapore commercial towers without cloud data transmission. |
| Federated Learning Platform Deployment | Preserves privacy while reducing bandwidth costs for dense municipal sensor networks in Shenzhen. |
| IEC 62443-4-2 Certification Acceleration | Shortens 14-18 month compliance timelines that currently delay industrial automation product launches. |
Research Methodology
Multiple input streams — structured interviews with building automation executives, facility management procurement leads, and edge hardware engineering directors, alongside regulatory filing analysis and customs trade data — were reconciled through bottom-up and top-down triangulation. Primary fieldwork encompassed discussions with Siemens AG and Honeywell International Inc. product strategists, Microsoft Corporation cloud platform architects, and municipal technology officers in Shenzhen, Shanghai, and Hangzhou. Secondary validation drew from EU AI Act implementation guidance, FCC spectrum allocation dockets, SAMR GB standard publications, and SEC 10-K disclosures from diversified industrial conglomerates.
Data-stream reconciliation across technology segmentation, application verticals, deployment architectures, and geographic regulatory clusters shaped the analytical framework over the projection horizon. CAGRs were derived from installed base growth modeling, replacement cycle analysis, and penetration rate assumptions across residential, commercial, and municipal end-use categories. Forecast inputs incorporated edge analytics hardware maturation curves, EU AI Act compliance cost burdens, and China's intelligent infrastructure budget allocations.
Regulatory implementation delays, rare earth supply disruptions, and interoperability protocol fragmentation are the dominant revision risks that could compress or extend growth trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
AI As a Service (Aiaas) Market
Artificial Intelligence (AI)
AI Content Creation Tool Market
Artificial Intelligence (AI)
AI in Robotics Market
Artificial Intelligence (AI)
Supermarket AI-Powered Checkout Market
Artificial Intelligence (AI)
Embedded AI Market
Artificial Intelligence (AI)
Autonomous AI and Autonomous Agents Market
Artificial Intelligence (AI)
Global Artificial Intelligence in Life Science Market
Artificial Intelligence (AI)
Cognitive Collaboration Market
Artificial Intelligence (AI)
Global Voice Cloning Market
Artificial Intelligence (AI)
AI Virtual Assistants Market
Artificial Intelligence (AI)
Enterprise Generative AI Market
Artificial Intelligence (AI)
No-Code AI Platform Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) Governance Market
Artificial Intelligence (AI)
Industrial AI Software Market
Artificial Intelligence (AI)
Intelligent Assistant Embedded Consumer Devices Market
Artificial Intelligence (AI)
North America Conversational AI Market