
 North America Conversational AI Market | 2026-2036
North America Conversational AI Market Size, Share, and Industry Trends Forecast 2026-2036
North America Conversational AI Market Analytics
Platform licensing revenue is narrowing as enterprise buyers shift spending toward outcome-based managed services and custom model fine-tuning. Microsoft leverages its Azure cloud infrastructure to anchor large-scale government and healthcare contracts across the United States and Canada. Google competes through deep integration of its natural language models into contact-center software and productivity suites. IBM sustains relevance with Watson-powered virtual agents targeting regulated industries requiring auditable AI decision paths.
Conversational AI encompasses software systems that process human language through natural language processing, machine learning, and speech recognition to enable automated dialogue across text and voice channels. These systems typically operate with sub-second response latency and deploy transformer-based neural architectures trained on billions of parameters to interpret intent, manage context, and generate coherent replies for customer service, internal operations, and consumer applications. Natural language processing leads technology investment as enterprises prioritize multilingual intent classification and sentiment analysis capabilities. Cloud-based deployment dominates structural spend, though hybrid configurations gain traction among financial services and healthcare entities managing sensitive data under strict residency requirements. Virtual assistants and chatbots capture the largest application share, while voice assistants grow fastest as automotive and smart-home integrations proliferate.
The U.S. Food and Drug Administration scrutinizes clinical conversational AI under software-as-medical-device frameworks, lengthening validation cycles but creating compliance barriers for unvalidated entrants. Health Insurance Portability and Accountability Act requirements constrain cloud data architectures, pushing healthcare providers toward hybrid deployments with on-premise components. The Federal Communications Commission monitors robocall and consumer protection boundaries for outbound voice applications, shaping permissible use cases. Stakeholders must weigh regulatory fragmentation between U.S. federal standards and provincial health privacy laws in Canada when architecting cross-border deployment strategies.
Market Dynamics
Enterprise procurement of conversational AI is pivoting from perpetual software licenses toward consumption-based cloud services and managed outcome contracts, compressing vendor revenue recognition cycles while expanding total addressable spend per account.
Growth Catalysts
- FDA Software-as-Medical-Device Framework:Finalized guidance on AI-enabled clinical tools is clarifying validation pathways for healthcare providers deploying diagnostic chatbots and triage assistants across U.S. hospital networks.
- Hybrid Cloud Architectures:Financial services and healthcare entities in the U.S. Northeast corridor are accelerating on-premise edge deployments to satisfy HIPAA data residency requirements without sacrificing model performance.
- Contact-Center Modernization:Large U.S. insurers and telecommunications carriers are replacing interactive voice response systems with neural voice agents capable of handling complex policy inquiries and claims intake.
Market Restraints
- GPU Compute Cost Volatility:Training and inference workloads for transformer models remain exposed to Nvidia data-center chip pricing and cloud provider reservation economics, squeezing gross margins for mid-scale platform vendors.
- Cross-Border Data Fragmentation:Health Canada provincial privacy laws and U.S. HIPAA requirements create architectural incompatibility for unified North American deployments, forcing redundant infrastructure investments.
- Substitution by Low-Code Automation:Robotic process automation platforms with basic natural language capabilities are capturing simpler use cases in administrative workflows, capping conversational AI expansion in back-office segments.
Strategic Opportunities
- Canadian Provincial Health Networks:Quebec and Ontario hospital systems lag U.S. penetration rates for patient-facing virtual assistants, presenting first-mover expansion potential for bilingual English-French models.
- Automotive Voice Integration:Detroit-based OEMs and Canadian suppliers are embedding conversational interfaces into infotainment and driver-assistance systems, opening a hardware-coupled revenue stream distinct from enterprise software.
- State-Level Medicaid Modernization:CMS innovation waivers in California, New York, and Texas are funding beneficiary self-service portals, creating procurement pipelines for eligibility and benefits chatbots.
Industry Challenges
- Conversational AI Engineer Scarcity:Enterprises in Boston and Toronto clusters report acute shortages of specialists capable of fine-tuning large language models for domain-specific retrieval-augmented generation pipelines.
- Legacy System Integration Complexity:Mainframe-dependent U.S. insurers and Canadian banks face protracted API harmonization timelines when connecting modern dialogue systems to decades-old policy administration platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Conversational AI Market |
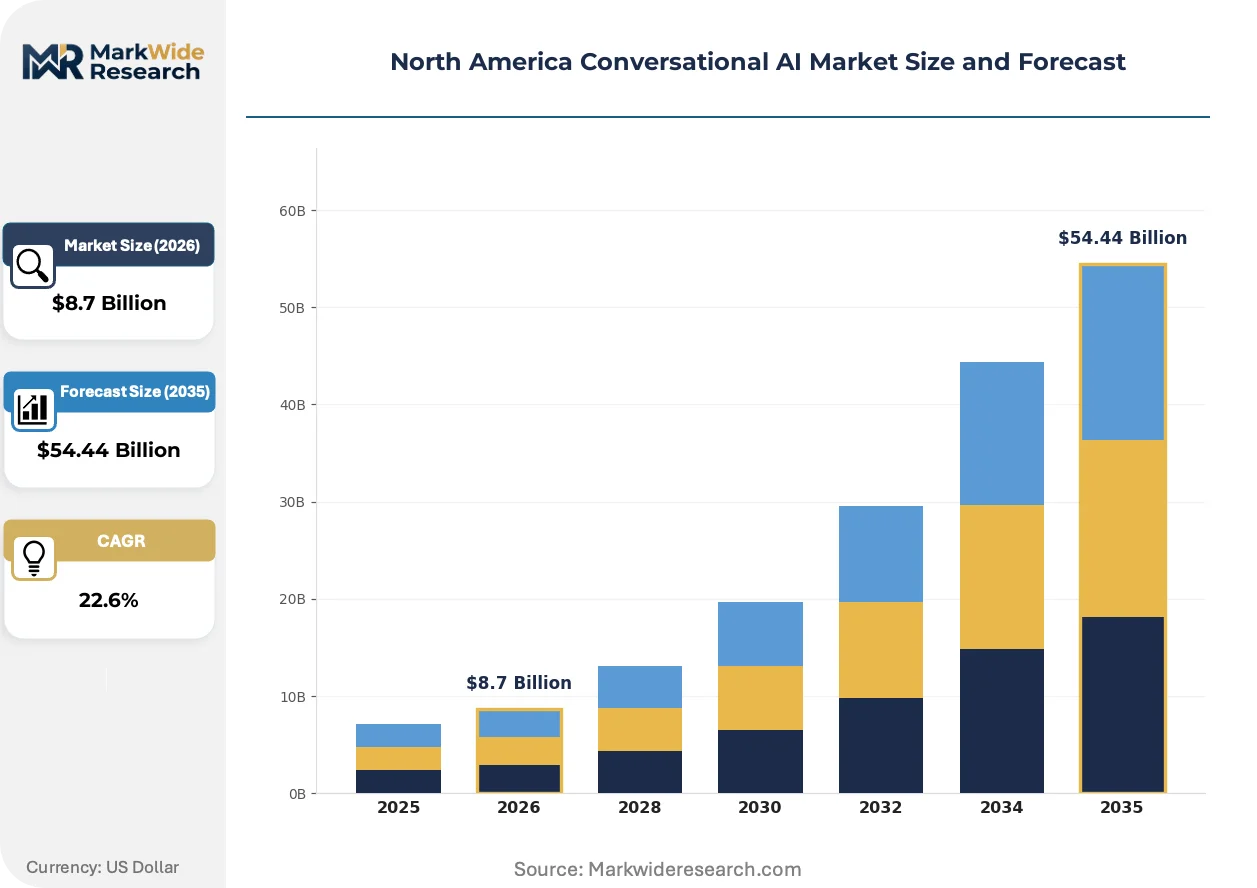
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $54.44 Billion |
| CAGR (2026 – 2036) | 22.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Natural Language Processing, Machine Learning, Speech Recognition, Text-to-Speech Deployment: Cloud-based, On-premise, Hybrid, Multi-tenant End User: Retail, Healthcare, BFSI, Telecom Application: Chatbots, Virtual Assistants, Customer Support, Voice Assistants |
| Companies Covered | Microsoft, Google, IBM, Amazon Web Services, OpenAI, Nuance Communications, Oracle, Salesforce, Kore.ai, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Conversational AI Market Evolving Landscape
Transformer-based architectures are compressing development timelines for domain-specific dialogue systems while regulatory pressure on algorithmic accountability is reshaping vendor product roadmaps across healthcare and financial services.
Retrieval-augmented generation is collapsing the cost structure for enterprise knowledge-base deployment. Healthcare systems in Minnesota and Pennsylvania are adopting RAG pipelines to ground clinical chatbot responses in institutional electronic health record content without retraining foundation models. This architecture is collapsing the traditional trade-off between model accuracy and hallucination risk that constrained earlier conversational AI rollouts in regulated settings.
The FDA's evolving enforcement posture on machine learning-enabled medical devices is extending premarket submission requirements for clinical conversational tools. Developers targeting diagnostic or treatment recommendation use cases now face 510(k) or De Novo pathways previously reserved for hardware devices. U.S. digital health startups are responding by bifurcating product strategies between regulated clinical applications and administrative workflow automation that falls outside device jurisdiction.
Enterprise buyers are consolidating vendor relationships around integrated platform stacks rather than point solutions for chat, voice, and analytics. Procurement teams at Fortune 500 manufacturers and retailers are awarding multi-year contracts to cloud providers offering unified natural language services spanning contact centers, internal help desks, and developer tools. This concentration is most pronounced in the Chicago and Atlanta metropolitan areas, where mid-market enterprises are skipping best-of-breed experimentation in favor of single-source Azure or Google Cloud commitments.
North America Conversational AI Market Segmentation
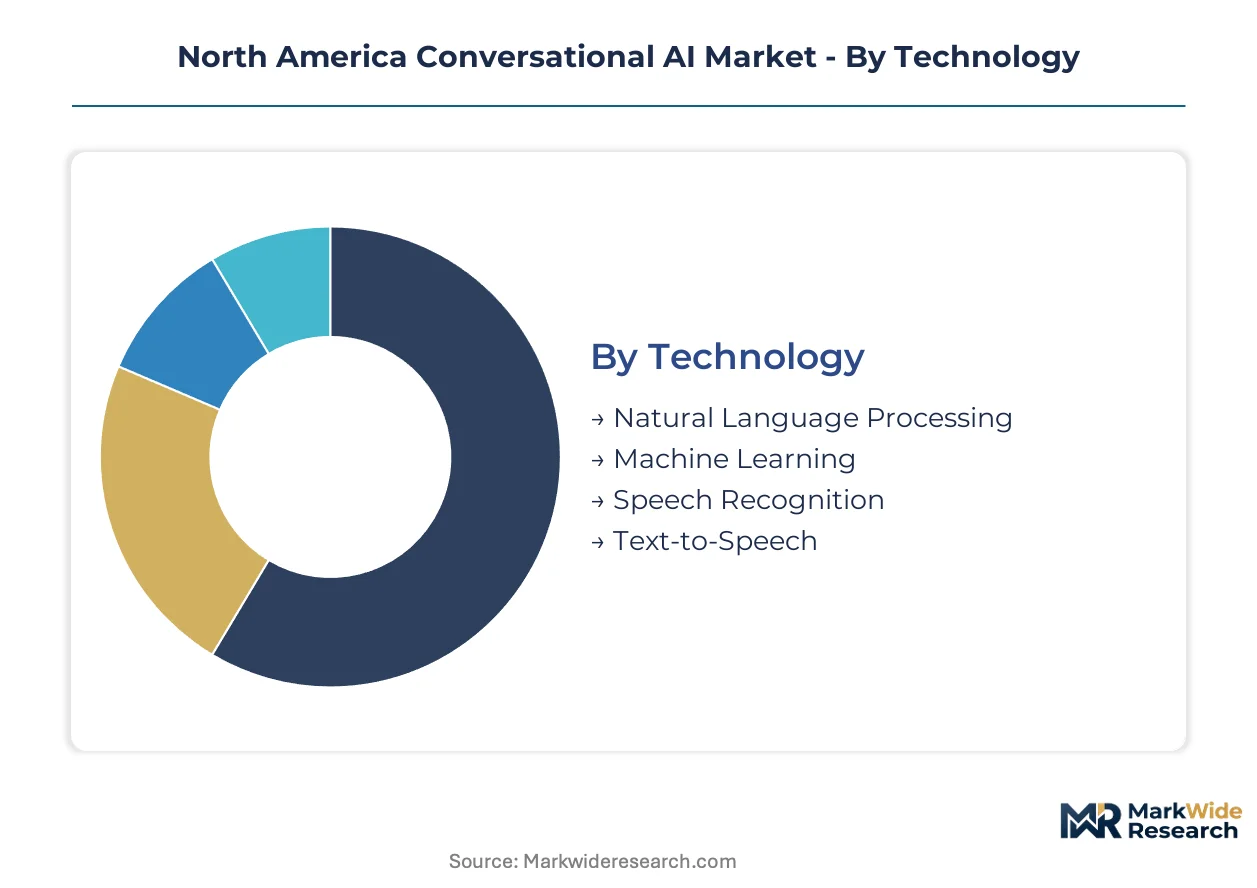
Segmentation reveals how conversational AI procurement patterns diverge across technical architectures, regulatory environments, and customer sophistication levels. Buyers in regulated industries prioritize deployment flexibility and audit trails over raw performance metrics, reshaping vendor competitive priorities across the United States and Canada.
Technology:
After-sales service intensity varies sharply across technology layers, with natural language processing demanding continuous model retraining and speech recognition requiring acoustic calibration support.
- Natural Language Processing:Transformer-based architectures process intent classification and entity extraction across multilingual corpora. Healthcare systems in Minnesota and Pennsylvania deploy NLP pipelines for clinical documentation, constrained by FDA software-as-medical-device validation timelines.
- Machine Learning:Supervised and reinforcement learning techniques optimize dialogue policy and response ranking. Financial services firms in the U.S. Northeast corridor invest heavily here for fraud detection and compliance monitoring applications.
- Speech Recognition:Acoustic models convert spoken input to structured text with sub-second latency. Automotive OEMs in Detroit integrate these systems for hands-free infotainment control.
- Text-to-Speech:Neural vocoders generate natural-sounding voice output from text prompts. Contact-center modernization drives demand among large U.S. insurers replacing legacy interactive voice response systems.
By volume, Natural Language Processing leads. By growth pace, Speech Recognition is climbing the fastest.
Deployment:
Cost tier segmentation separates enterprise buyers with dedicated infrastructure budgets from mid-market adopters prioritizing operational expenditure predictability.
- Cloud-based:Fully managed services eliminate capital expenditure for compute infrastructure. Retail chains and telecom carriers favor this model for seasonal demand elasticity.
- On-premise:Dedicated hardware installations satisfy data residency mandates. Canadian provincial health networks and U.S. Department of Defense contractors require these configurations.
- Hybrid:Sensitive data processing occurs at the edge while model training leverages cloud scale. HIPAA-constrained healthcare providers in Boston and New York City accelerate adoption here.
- Multi-tenant:Shared infrastructure partitions resources across client organizations. Cost-sensitive state Medicaid agencies in California and Texas utilize this architecture for beneficiary self-service portals.
Cloud-based deployments dominate current spend. Hybrid configurations are expanding most quickly as regulatory fragmentation intensifies.
End User:
Application maturity diverges across verticals, with early adopters now optimizing for domain-specific accuracy while laggards complete initial pilot phases.
- Retail:E-commerce chatbots handle product discovery and order tracking. Major U.S. retailers deploy these for 24/7 customer engagement without human agent scaling.
- Healthcare:Patient triage, appointment scheduling, and clinical documentation assistance. FDA scrutiny of diagnostic applications lengthens validation cycles for developers targeting clinical decision support.
- BFSI:Claims intake, policy inquiry, and fraud alert systems. Large insurers replace interactive voice response with neural voice agents capable of complex policy interpretation.
- Telecom:Billing dispute resolution and service provisioning. Canadian carriers and U.S. regional operators modernize contact centers to reduce churn.
Healthcare generates the highest solution customization revenue. Retail shows the steepest expansion trajectory in deployment volume.
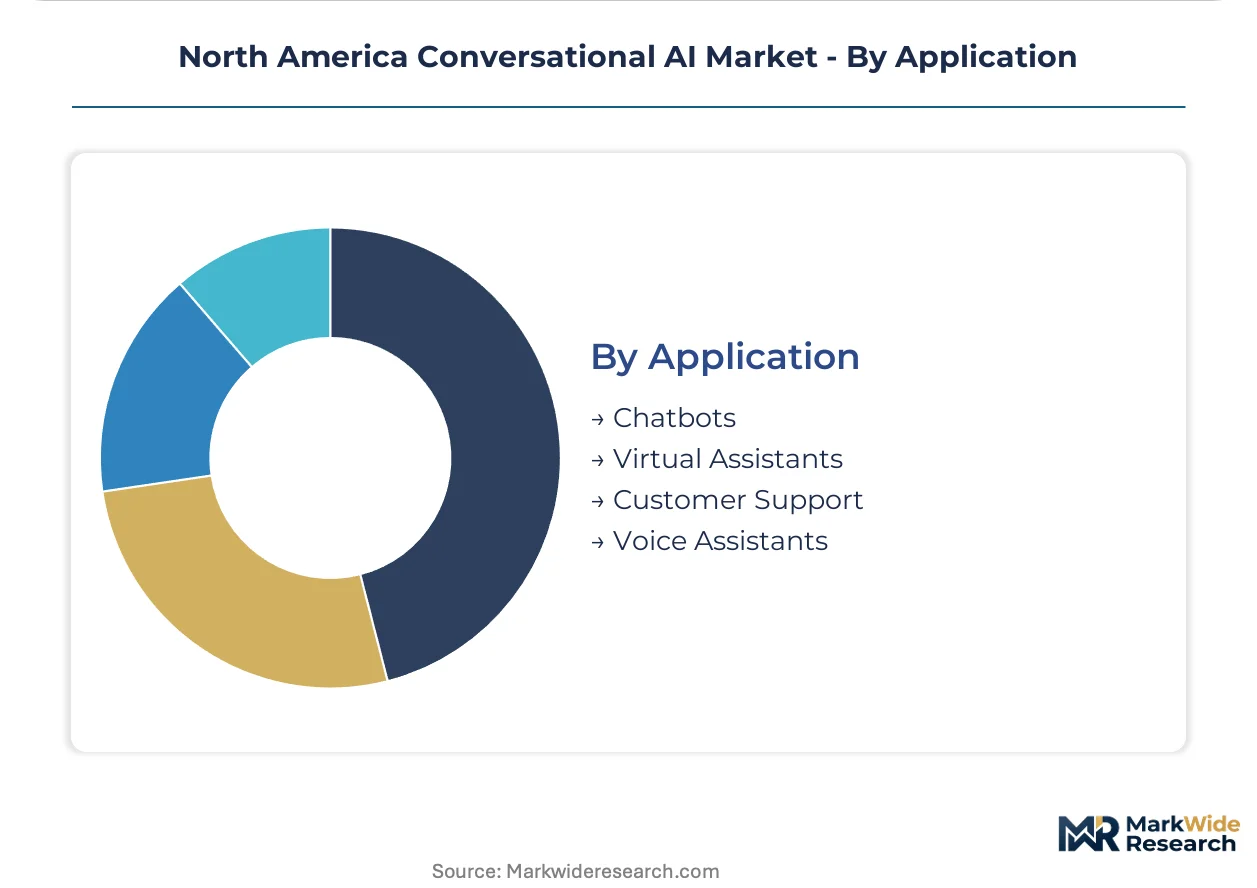
Application:
Customer type segmentation separates enterprise buyers seeking integrated platform stacks from point-solution adopters addressing specific workflow pain points.
- Chatbots:Text-based interfaces embedded in websites and messaging platforms. These capture the largest current deployment base across administrative workflows.
- Virtual Assistants:Context-aware agents managing multi-turn conversations with memory and personalization. Quebec and Ontario hospital systems lag U.S. penetration, presenting first-mover expansion potential for bilingual English-French models.
- Customer Support:Automated resolution of tier-1 inquiries with seamless human escalation. Fortune 500 manufacturers in Chicago and Atlanta consolidate around unified natural language services.
- Voice Assistants:Speech-driven interfaces for hands-free operation. Detroit-based OEMs and Canadian automotive suppliers embed these into infotainment systems, opening hardware-coupled revenue streams.
Chatbots lead by installed base. Voice Assistants are gaining share fastest through automotive and smart-home integration proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States buyers demonstrate the lowest price elasticity for HIPAA-compliant hybrid deployments, while Canadian provincial health networks and Mexican contact-center operators remain acutely sensitive to per-seat licensing costs. This demand-elasticity contrast shapes vendor go-to-market strategies across the continent.
United States
Hospital networks in Minnesota and Pennsylvania deploy retrieval-augmented generation pipelines for clinical documentation grounded in electronic health records. FDA software-as-medical-device frameworks extend validation timelines for diagnostic chatbots. Boston and New York City anchor enterprise adoption clusters where Fortune 500 manufacturers consolidate around unified Azure and Google Cloud natural language stacks.
Canada
Quebec and Ontario hospital systems lag U.S. penetration rates for patient-facing virtual assistants, creating first-mover expansion potential for bilingual English-French models. Health Canada provincial privacy laws and U.S. HIPAA requirements generate architectural incompatibility for unified North American deployments. Toronto's AI research corridor attracts specialist talent for fine-tuning large language models, though acute shortages persist.
Mexico
Contact-center modernization drives neural voice agent adoption among nearshore business process outsourcing operators serving U.S. insurers and telecommunications carriers. Mexico's federal data protection framework governs cross-border data flows for cloud-based conversational AI services. Mexico City and Monterrey metropolitan areas concentrate deployment activity for Spanish-English bilingual customer support applications.
California
CMS innovation waivers fund Medicaid beneficiary self-service portals, creating procurement pipelines for eligibility and benefits chatbots. State-level privacy regulations supplement federal HIPAA constraints on healthcare data architectures. San Francisco Bay Area technology clusters drive automotive voice integration development for Detroit-based OEMs and smart-home device manufacturers.
Texas
State Medicaid modernization programs deploy conversational interfaces for beneficiary enrollment and claims status inquiry. Texas Medical Board guidelines intersect with FDA frameworks for clinical decision support tools. Dallas-Fort Worth and Houston metropolitan areas concentrate healthcare system procurement activity alongside energy sector internal help desk automation.
North America Conversational AI Market Competitive Landscape
Capability concentration sits with hyperscale cloud providers possessing transformer training infrastructure; scale advantage sits with enterprise software incumbents wielding installed base relationships. The market structure bifurcates between infrastructure-anchored platforms and application-layer specialists. Three archetypes dominate: hyperscale cloud-native stacks, legacy enterprise software extenders, and vertical-focused conversational AI pure-plays. Competitive moves center on multi-year managed outcome contracts and hybrid deployment certifications for regulated industries.
Within the hyperscale tier, Microsoft and Google exemplify infrastructure-anchored positioning through Azure and cloud-native natural language service integration. IBM occupies a distinct archetype as a legacy enterprise software extender with Watson-powered virtual agents targeting auditable AI decision paths in regulated settings. These three entities represent the dominant competitive anchors shaping procurement consolidation patterns across U.S. and Canadian enterprise buyers.
| Leading Market Players |
|---|
| Microsoft |
| IBM |
| Amazon Web Services |
| OpenAI |
| Nuance Communications |
| Oracle |
| Salesforce |
| Kore.ai |
| Others |
Value Network & Pricing Analysis
The I-95 freight corridor linking Boston and New York City carries premium GPU server clusters and specialized AI training hardware, with its congestion surcharges feeding directly into deployment cost differentials between hybrid-edge configurations and pure cloud alternatives. This logistics bottleneck amplifies pricing power for domestic edge-compute providers while compressing margins for vendors dependent on just-in-time Nvidia chip deliveries from West Coast distribution hubs.
Pricing Analysis
Managed service and custom fine-tuning revenue layers now exceed perpetual license lifetime value across enterprise accounts. Three-tier pricing structure across premium, standard, and economy levels separates HIPAA-validated healthcare deployments from administrative workflow automation and basic chatbot implementations. Cost compression in the mid-market tier is intensifying because robotic process automation platforms capture simpler use cases with lower price points. State Medicaid agencies exhibit highest price sensitivity, while U.S. Northeast hospital networks anchored in Boston and New York City demonstrate lowest elasticity for compliance-certified hybrid deployments.
Supply Chain Analysis
Upstream GPU and specialized AI accelerator supply draws from Taiwan, South Korea, and the United States, with Nvidia data-center chips commanding allocation priority through cloud provider reservation contracts. Transformer training infrastructure rests on high-bandwidth memory modules, advanced packaging substrates, and liquid cooling systems. Single-source vulnerability concentrates in leading-edge semiconductor fabrication, where geopolitical export controls threaten supply continuity for training clusters. Distribution runs through hyperscale cloud marketplaces and direct OEM relationships with hospital networks and financial services entities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Outcome-based managed services and recurring fine-tuning contracts are expanding faster than perpetual platform licenses, redefining this market as a service-attach opportunity where vendor stickiness depends on continuous model optimization rather than upfront software acquisition.
For Market Incumbents: Entrench hybrid deployment certifications for HIPAA-constrained healthcare providers and financial services entities, locking in multi-year managed outcome contracts before emerging pure-play specialists achieve regulatory validation. Deepen backward integration into edge compute infrastructure to defend against GPU cost volatility squeezing gross margins. Prioritize bilingual English-French model development to preempt new entrant expansion into Quebec and Ontario hospital systems.
For New Entrants and Emerging Players: Pursue Canadian provincial health networks as the most penetrable geography, where patient-facing virtual assistant deployment lags U.S. penetration rates by several years. Target automotive voice integration partnerships with Detroit-based OEMs and Canadian suppliers as a hardware-coupled revenue stream distinct from saturated enterprise software competition. Lead with retrieval-augmented generation expertise as the differentiated go-to-market angle for clinical documentation applications.
For Investors and Strategic Acquirers: Conversational AI pure-plays with vertical-specific regulatory certifications and established hospital system relationships represent the priority acquisition archetype for platform consolidation strategies. Long-term viability hinges on successful pivot from license revenue to consumption-based services across the projection horizon. Monitor FDA 510(k) submission volumes for diagnostic chatbot applications as the inflection signal indicating which developers will capture regulated clinical decision support market share.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Deployment Certification | HIPAA-validated edge configurations unlock multi-year hospital network contracts in Boston and New York City clusters. |
| Bilingual Model Development | English-French capabilities capture first-mover advantage in Quebec and Ontario provincial health systems. |
| Retrieval-Augmented Generation Pipeline | RAG architectures collapse hallucination risk for clinical applications under FDA software-as-medical-device scrutiny. |
| Automotive Voice Integration Partnership | Hardware-coupled revenue streams with Detroit OEMs diversify beyond enterprise software price competition. |
| Managed Outcome Contract Structure | Consumption-based pricing aligns vendor incentives with client operational metrics across Medicaid modernization programs. |
Research Methodology
Desk research of hyperscaler capex disclosures, FDA 510(k) submission databases, and hospital procurement records preceded structured interviews with CTOs at Fortune 500 manufacturers, biomedical engineers at Minnesota and Pennsylvania health systems, and platform engineers at contact-center modernization vendors. Primary fieldwork with healthcare IT procurement committees and financial services compliance officers combined with secondary validation against CMS innovation waiver documentation and provincial health network tender records. Bottom-up deployment volume estimates triangulated against top-down cloud services revenue segmentation.
Assumptions held fixed include current FDA software-as-medical-device enforcement posture and prevailing HIPAA data residency requirements, while GPU pricing trajectories and provincial privacy law harmonization timelines were varied across sensitivity scenarios. The analytical framework modeled deployment mode, organization size, vertical regulatory intensity, integration complexity, and regional adoption pattern across the projection horizon. CAGRs derived from logistic diffusion curves fitted to historical cloud migration patterns and healthcare AI adoption benchmarks, with transformer training cost curves and contact-center automation substitution rates as key forecast inputs.
Sensitivities concentrate around FDA guidance evolution on diagnostic chatbot classification and cross-border data architecture compatibility between U.S. and Canadian health privacy regimes. Forecasts reflect these documented assumptions without claiming certainty on regulatory timelines or geopolitical semiconductor access conditions. Cross-checking against hyperscaler earnings call commentary on healthcare vertical growth rates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Digital Intelligence Technology Market
Artificial Intelligence (AI)
Japan Edge AI Market
Artificial Intelligence (AI)
AI Voice Cloning Market
Artificial Intelligence (AI)
Global Cloud Telecommunication AI Market
Artificial Intelligence (AI)
Global AI in Telecommunication Market
Artificial Intelligence (AI)
Global Cognitive Automation Market
Artificial Intelligence (AI)
Artificial Intelligence in Transportation Market
Artificial Intelligence (AI)
Conversation Intelligence Software Market
Artificial Intelligence (AI)
Deep Learning Market
Artificial Intelligence (AI)
Agentic AI Market
Artificial Intelligence (AI)
Intelligent Virtual Assistant Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) Assisted Robots Market
Artificial Intelligence (AI)
Global Cognitive Computing Technology Market
Artificial Intelligence (AI)
Brain-Computer Interface System Market
Artificial Intelligence (AI)
Far-Field Speech and Voice Recognition Market
Artificial Intelligence (AI)
Artificial Intelligence Chatbots Market