
 Edge AI Software Market | 2026-2036
Edge AI Software Market Size, Share, and Industry Trends Forecast 2026-2036
Edge AI Software Market Intelligence
A transition from purely cloud-based AI processing to hybrid on-premise deployments is recalibrating the competitive landscape. This shift prioritizes software that can function efficiently on resource-constrained hardware. Microsoft leverages its Azure IoT Edge platform to extend cloud intelligence to edge devices. NVIDIA dominates the hardware-software stack with its CUDA and TensorRT libraries for accelerated inference, while Intel competes through its OpenVINO toolkit, optimizing deep learning models for its own processors.
Edge AI software encompasses algorithms and platforms designed to execute machine learning models directly on endpoint devices, such as sensors, cameras, and gateways. This architecture minimizes latency by processing data locally, enabling real-time automated responses without reliance on a central cloud server. Among solution types, Computer Vision leads in adoption, integral to applications like security surveillance. The Autonomous Vehicles use case represents the fastest-growing segment, requiring sophisticated predictive analytics and sensor fusion capabilities.
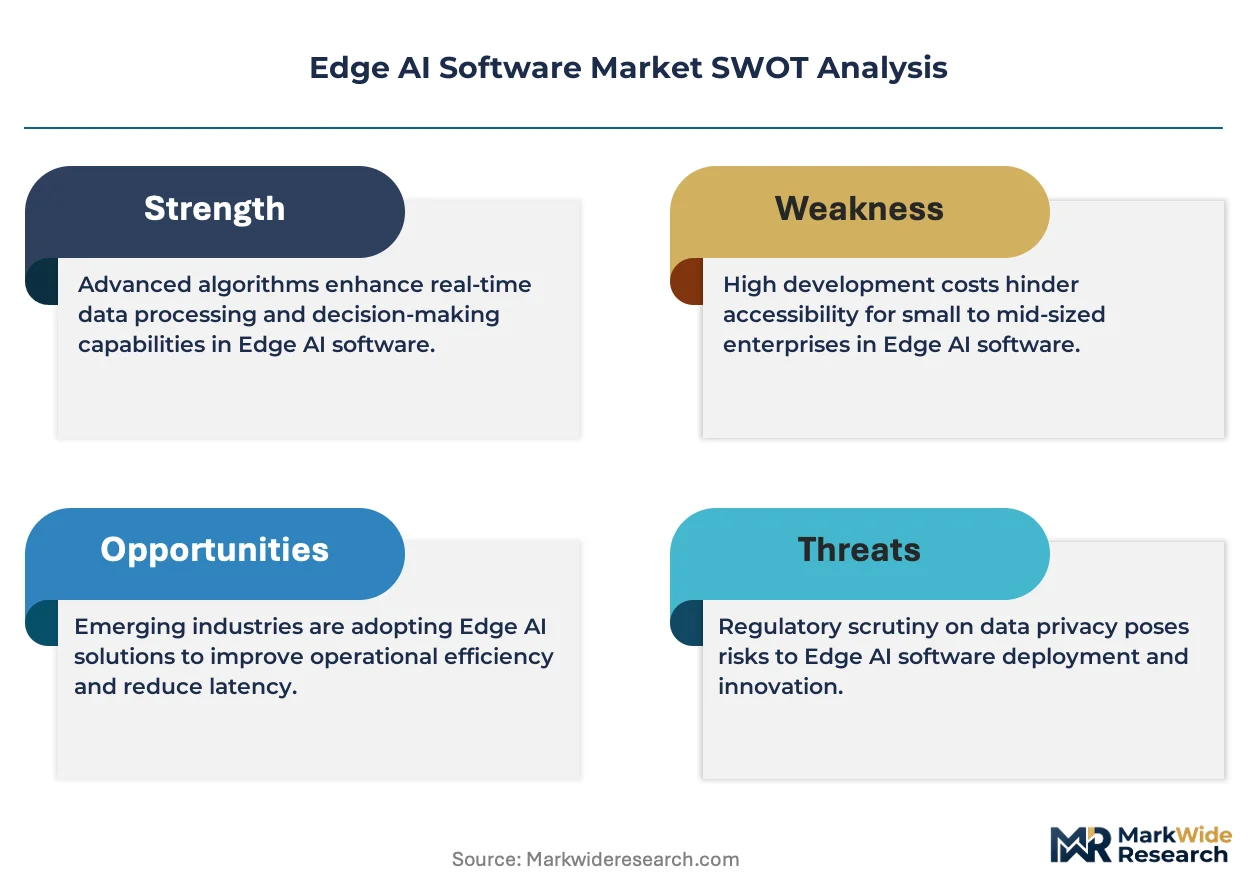
Data governance frameworks like the EU's GDPR and the upcoming EU AI Act impose strict requirements on data privacy and algorithmic transparency. Concurrently, standards bodies such as ISO/IEC are developing guidelines for AI trustworthiness and quality management, influencing product development roadmaps. Vendor success will depend on creating software that is not only powerful but also compliant and adaptable to a fragmented global regulatory environment.
Market Dynamics
The transition from cloud-centric AI to hybrid on-premise deployments is the dominant force recalibrating the market. This shift prioritizes software optimized for resource-constrained hardware, directly impacting algorithm design and hardware-software co-development strategies across the ecosystem.
Growth Catalysts
- Industry 4.0 Adoption:Smart Manufacturing's demand for real-time quality control and predictive maintenance on the factory floor drives adoption of edge computer vision and analytics platforms.
- 5G Network Expansion:The rollout of 5G infrastructure provides the high-bandwidth, low-latency connectivity essential for distributed edge AI systems, particularly in smart city and connected vehicle applications.
- Data Sovereignty Mandates:Regulations like GDPR in Europe and similar data residency laws in countries like India encourage local processing, making edge AI a compliance-friendly architecture.
Market Restraints
- Hardware and Software Fragmentation:A diverse landscape of processors, from CPUs to GPUs and specialized ASICs, complicates software development, requiring extensive optimization for different hardware targets.
- High Initial Development Costs:Creating and optimizing AI models for resource-constrained edge devices demands specialized expertise and significant investment in development and testing cycles, raising barriers to entry.
- Regulatory Compliance Complexity:Navigating the stringent requirements of frameworks like the EU AI Act for high-risk systems introduces significant compliance overhead and development delays for vendors.
Strategic Opportunities
- On-Device Healthcare Analytics:Developing AI software for medical wearables and diagnostic equipment offers opportunities for real-time patient monitoring and personalized health alerts, a largely untapped area.
- Smart Factory Upgrades in Southeast Asia:Governments in countries like Vietnam and Thailand are promoting manufacturing modernization, creating an opportunity for edge AI solutions in automated quality inspection and robotics.
- AI and Blockchain Convergence:Integrating edge AI with blockchain can create secure, auditable, and decentralized AI systems for applications in supply chain management and financial services.
Industry Challenges
- Specialized Talent Scarcity:A shortage of engineers skilled in both embedded systems and machine learning optimization, such as with TensorRT or OpenVINO, constrains product development and deployment.
- Legacy System Integration:Integrating modern edge AI platforms with existing operational technology and IT infrastructure in industrial environments presents significant technical and security challenges.
- Lack of Standardization:The absence of universal standards for edge device management, data formats, and model interoperability hinders scalability and creates vendor lock-in concerns for customers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Edge AI Software Market |
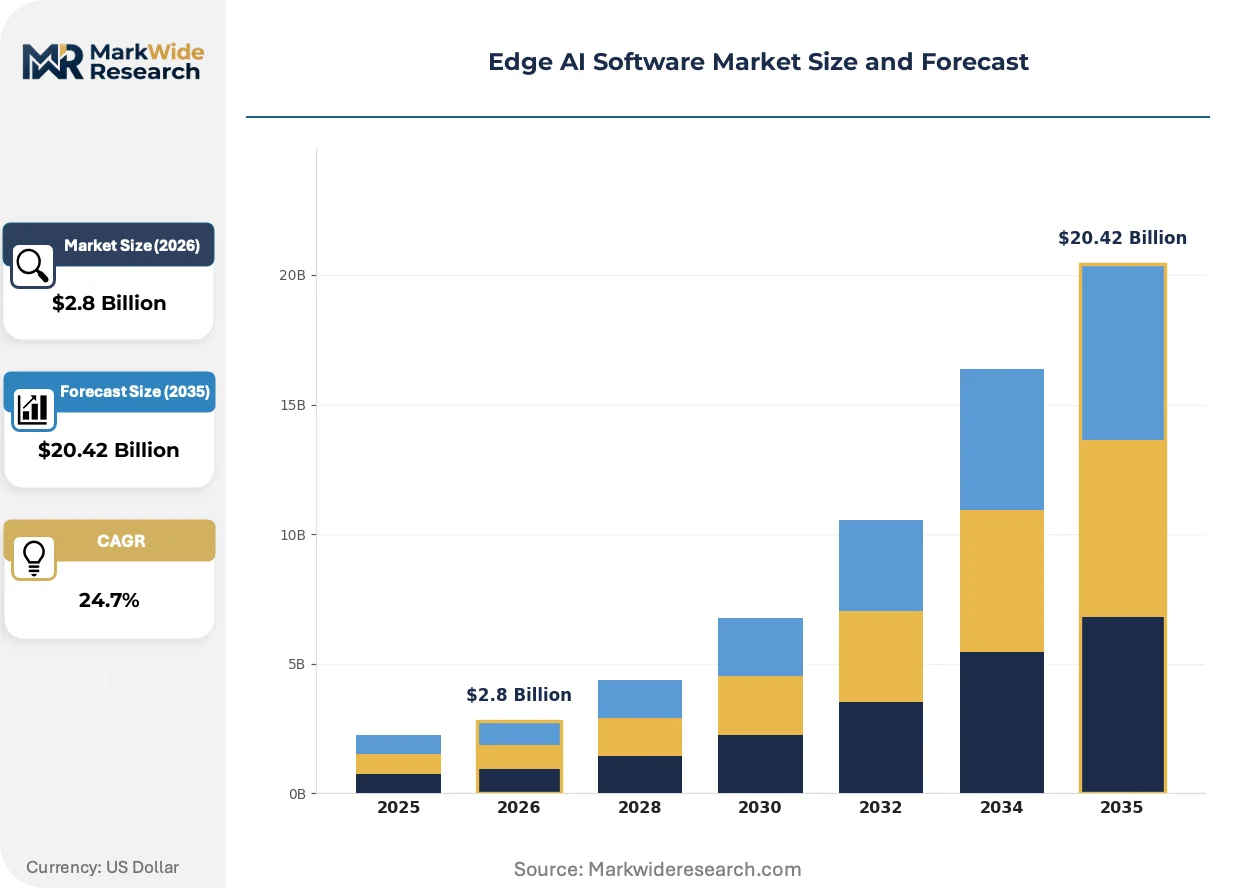
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $20.42 Billion |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: On-Premise, Cloud-Integrated, Hybrid, Embedded, Standalone Solution Type: Computer Vision, Natural Language Processing, Predictive Analytics, Anomaly Detection, Speech Recognition Use Case: Smart Manufacturing, Autonomous Vehicles, Security Surveillance, Retail Analytics, Smart Agriculture End User Industry: Information Technology, Transportation, Government Agencies, Consumer Electronics, Telecommunications |
| Companies Covered | Qualcomm, Google, Intel, Amazon, Microsoft, NVIDIA, Arm, IBM, AMD, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Edge AI Software Market Strategic Shifts & Innovations
A fundamental shift toward decentralized intelligence is redefining software architecture. Concurrently, emerging governance frameworks are formalizing rules for algorithmic transparency and data privacy, influencing product design across all end-use sectors.
Federated learning is an AI training technique that updates a shared model using data from multiple edge devices without centralizing the raw data. The healthcare and consumer electronics sectors are adopting this approach to protect user privacy. This methodology is decentralizing model training, reducing reliance on cloud-based datasets and enhancing data security.
The EU AI Act establishes a risk-based system, imposing strict obligations on providers of high-risk AI, including systems in critical infrastructure. This legislation mandates comprehensive risk assessments and human oversight capabilities. Software vendors targeting Europe are embedding 'trust by design' principles into their development lifecycle to ensure compliance.
Enterprise customers are moving from perpetual software licenses toward flexible, consumption-based pricing models for AI. This change disrupts traditional sales, favoring vendors who offer modular, API-driven services that can scale with usage. The shift is most visible in industrial IoT, where companies deploy models for tasks like predictive maintenance and pay per inference.
Edge AI Software Market Segmentation
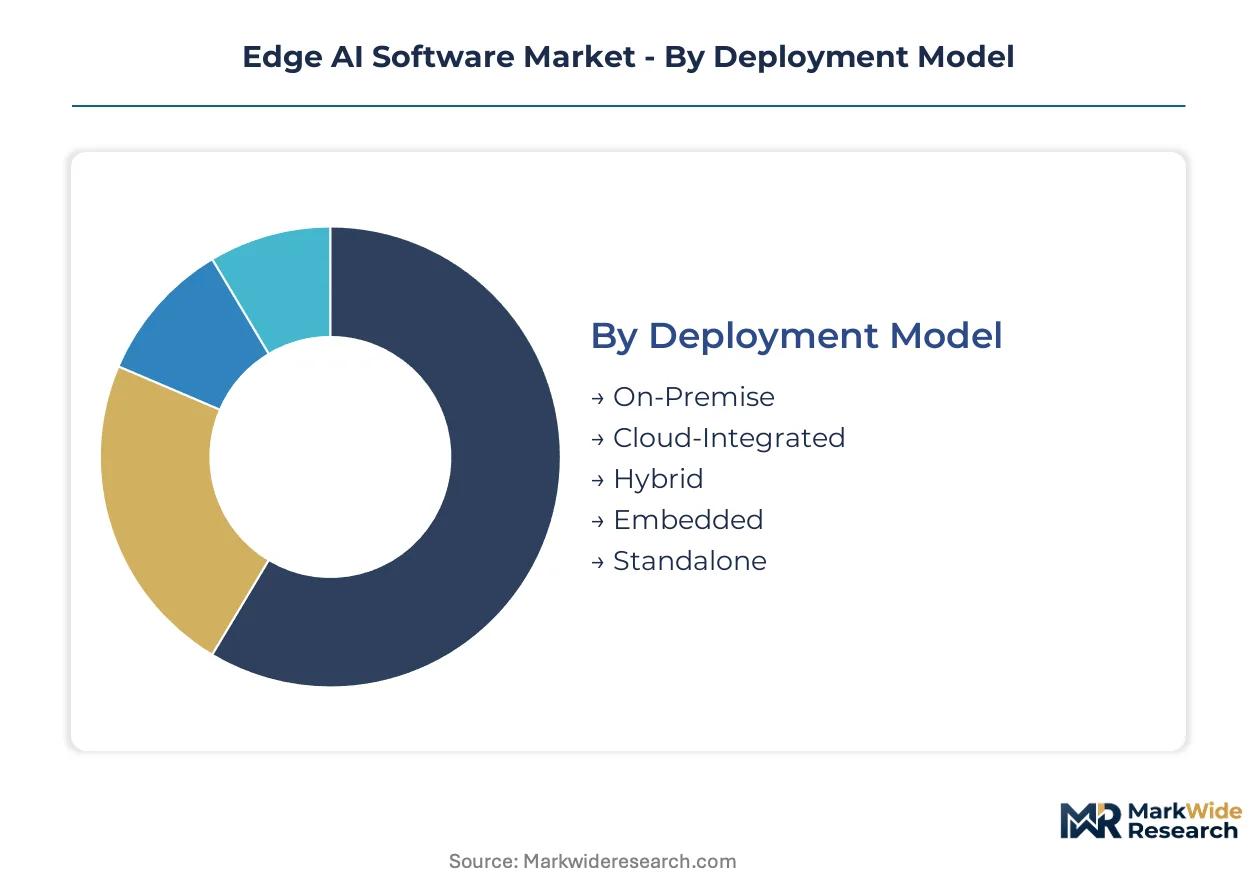
The Edge AI Software Market exhibits diverse operational and technological configurations, necessitating a granular segmentation to understand its varied adoption patterns. Analyzing these segments reveals how different deployment models, solution types, use cases, and end-user industries are shaping the competitive landscape.
Deployment Model:
The market for edge AI software differentiates significantly based on the integration depth, ranging from standalone applications to deeply embedded systems.
- Hybrid:This model combines local edge processing with cloud-based services for data storage, model retraining, and complex analytics. Demand concentrates in Smart Manufacturing, where real-time factory floor data requires immediate action, while long-term trends benefit from cloud insights.
- Embedded:Edge AI software is integrated directly into hardware devices, such as microcontrollers or specialized AI chips, for highly resource-constrained environments. This segment is critical for Autonomous Vehicles, enabling low-latency decision-making and enhancing safety without external network reliance.
- On-Premise:Software is deployed entirely within a local enterprise network, providing full control over data and processing without external cloud dependencies.
- Cloud-Integrated:This model primarily relies on cloud infrastructure but extends specific AI functionalities to edge devices for local data collection and pre-processing.
- Standalone:Edge AI applications operate independently on devices, performing all processing locally without requiring persistent cloud connectivity or integration into larger systems.
Hybrid deployment leads volumes today; Embedded solutions are gaining share fastest.
Solution Type:
Edge AI software offers distinct functional capabilities, each addressing specific operational challenges across various industries.
- Computer Vision:These solutions process visual data from cameras and sensors for tasks like object detection, facial recognition, and quality inspection. Demand concentrates in security surveillance, where real-time threat detection and anomaly identification are paramount for public safety.
- Predictive Analytics:Algorithms analyze historical and real-time data to forecast future outcomes, anticipate failures, or optimize operational performance. This capability is crucial for Autonomous Vehicles, enabling proactive decision-making and route optimization based on sensor fusion.
- Natural Language Processing:Edge-based NLP enables local processing of human language for tasks such as voice commands, sentiment analysis, and text summarization without cloud roundtrips.
- Anomaly Detection:These solutions identify unusual patterns or outliers in data streams, signaling potential issues or deviations from normal behavior.
- Speech Recognition:Software converts spoken language into text or commands directly on edge devices, supporting voice assistants and hands-free operation in various applications.
Computer Vision solutions currently dominate; Predictive Analytics applications are expanding most quickly.
Use Case:
The application of edge AI software varies significantly across different operational scenarios, each driven by unique industry demands and performance requirements.
- Smart Manufacturing:Edge AI enhances factory operations through real-time quality control, predictive maintenance, and robotic automation directly on the production line. This segment is critical for Industry 4.0 adoption, ensuring operational continuity and optimizing resource utilization.
- Autonomous Vehicles:Edge AI enables self-driving capabilities through sensor fusion, perception, and real-time decision-making on board the vehicle. This use case requires ultra-low latency processing and robust safety features, directly impacting passenger and pedestrian safety.
- Security Surveillance:Edge AI processes video feeds locally to detect intrusions, identify suspicious activities, and manage access control in real time.
- Retail Analytics:These solutions analyze customer behavior, optimize store layouts, and manage inventory at the point of sale.
- Smart Agriculture:Edge AI assists in crop monitoring, livestock management, and precision farming by processing data from sensors and drones locally.
Smart Manufacturing drives significant operational efficiencies; Autonomous Vehicles presents the steepest expansion trajectory.
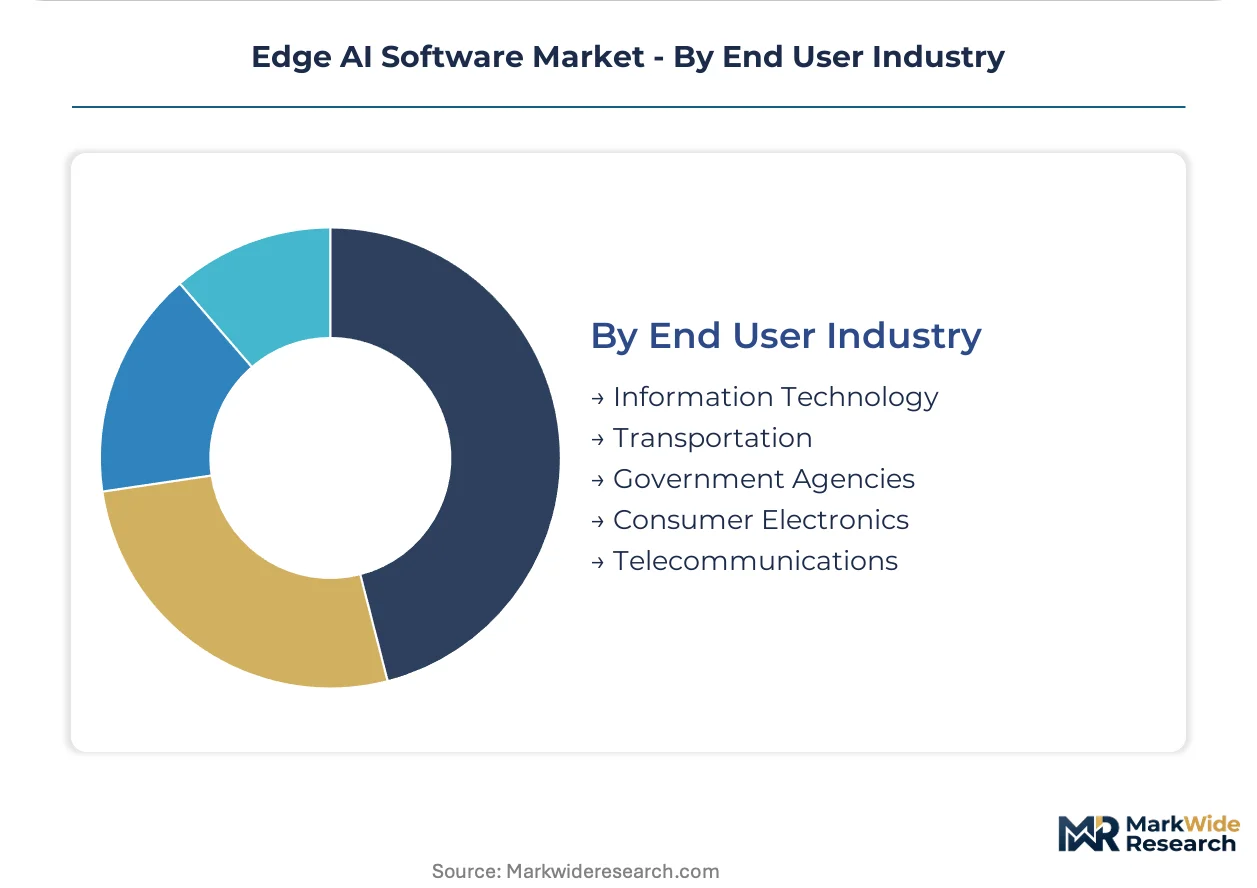
End User Industry:
Edge AI software finds adoption across a broad spectrum of industries, each leveraging its capabilities to address specific business challenges and opportunities.
- Transportation:This sector utilizes edge AI for autonomous driving systems, traffic management, and logistics optimization, particularly in connected vehicle ecosystems. Demand concentrates in the United States, driven by significant investments in automotive research and development.
- Information Technology:Edge AI solutions are deployed within IT infrastructure for network optimization, cybersecurity, and data processing at the network's periphery. This industry forms a foundational market, enabling the widespread adoption of edge computing across other sectors.
- Government Agencies:Public sector entities leverage edge AI for smart city initiatives, public safety, and infrastructure monitoring.
- Consumer Electronics:Edge AI integrates into devices like smartphones, smart home appliances, and wearables for personalized experiences and enhanced privacy.
- Telecommunications:Telcos deploy edge AI for network optimization, intelligent resource allocation, and enhanced customer experience at the cell tower or local exchange.
Transportation represents a foundational market; Consumer Electronics is climbing the fastest in adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States' advanced semiconductor and automotive industries drive significant demand for edge AI software. This robust demand is supported by substantial investments in technological innovation. Regulatory frameworks across various nations further shape deployment strategies and market penetration.
United States
The United States, with its advanced semiconductor and automotive industries, generates substantial demand for edge AI solutions. The Inflation Reduction Act (IRA) encourages domestic manufacturing and technology adoption, impacting edge AI deployment in industrial settings. Silicon Valley continues as a hub for AI innovation, fostering new startups and research in edge computing.
Germany
German Smart Manufacturing initiatives and its strong automotive sector create significant demand for real-time edge analytics. The EU AI Act establishes stringent governance standards, influencing product design for European deployment. Bavaria, a center for automotive and industrial technology, sees extensive integration of edge AI into production lines.
China
China's rapid 5G network expansion and extensive Smart Manufacturing adoption fuel a strong demand for distributed edge AI systems. The Ministry of Industry and Information Technology (MIIT) promotes industrial digitalization, accelerating edge AI implementation across sectors. The Yangtze River Delta region, a major manufacturing hub, integrates edge AI for operational efficiency.
Japan
Japan's focus on industrial automation and autonomous vehicle development drives demand for high-performance edge AI processing. The Ministry of Economy, Trade and Industry (METI) supports AI research and development, fostering innovation in embedded systems. Kanto, including Tokyo, remains a key region for advanced robotics and AI integration in various industries.
South Korea
South Korea's leadership in 5G infrastructure and consumer electronics generates substantial demand for on-device AI capabilities. The national AI strategy aims to accelerate technological advancement and widespread adoption across industries. The Seoul Capital Area is a focal point for R&D, incubating innovative edge AI applications in smart devices.
Edge AI Software Market Key Industry Players
Global majors compete with regional champions across the hardware and software stack for edge AI solutions. The market exhibits a tiered structure, with established technology giants and specialized startups vying for market share. Strategic archetypes include integrated platform providers, dedicated hardware accelerators, and niche software optimizers. Dominant competitive moves involve strategic partnerships and portfolio diversification to address fragmented customer needs.
Integrated platform providers like Microsoft, with its Azure IoT Edge, exemplify the archetype of extending cloud intelligence to edge devices. NVIDIA, a US-based corporation, anchors the hardware-software stack with its CUDA and TensorRT libraries, representing the specialized accelerator archetype. Intel, another prominent US-based technology company, occupies a position as a hardware-centric competitor through its OpenVINO toolkit for optimizing deep learning models.
| Leading Market Players |
|---|
| Qualcomm |
| Intel |
| Amazon |
| Microsoft |
| NVIDIA |
| Arm |
| IBM |
| AMD |
| Others |
Cost & Logistics Intelligence
Divergence between high-performance embedded solutions and flexible hybrid deployments shapes both pricing strategies and supply chain configurations. Specialized AI software commanding premium value-based pricing relies on concentrated, high-tech component supply chains, while broader hybrid offerings often adopt subscription models with more diversified hardware sourcing.
Pricing Analysis
Input cost pass-through for specialized hardware components directly influences edge AI software pricing for embedded systems. The dominant pricing model favors subscription or value-based licensing, particularly for advanced analytics and computer vision solutions. Price differentiation stems from customization level for specific industrial applications and guaranteed performance tiers. Pricing softness in commoditized hybrid solutions arises from increased competition and open-source alternatives. Small and medium-sized enterprises often exhibit higher price sensitivity compared to large automotive OEMs or critical infrastructure operators.
Supply Chain Analysis
Specialized AI chip supply, including GPUs and ASICs, relies heavily on manufacturing hubs in the United States, Taiwan, and South Korea. Raw material dependencies include rare earth elements for advanced semiconductors and specialized embedded system components. Hardware fragmentation across diverse processor architectures represents a structural supply chain risk, complicating software optimization efforts. Distribution runs through a combination of direct sales to large enterprises and channel partnerships with system integrators for broader market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with the EU AI Act establishing stringent governance standards that drive demand for compliant software solutions.
For Market Incumbents:
Acquire specialized AI talent in embedded systems and machine learning optimization to counter talent scarcity. Consolidate market share through strategic partnerships with hardware manufacturers, ensuring software-hardware co-development. Address the threat of specialized startups by integrating cutting-edge compliance features, such as those mandated by the EU AI Act, into core offerings. Invest in R&D for resource-efficient algorithms to reduce hardware dependency and broaden deployment possibilities.
For New Entrants and Emerging Players:
System integrators represent a critical channel for penetrating the fragmented industrial IoT market. Target on-device healthcare analytics as a white-space opportunity, leveraging privacy-preserving federated learning approaches. Focus on smart factory upgrades in Southeast Asia, offering modular, API-driven services for quality inspection and predictive maintenance. A go-to-market angle emphasizing rapid deployment and demonstrable ROI in niche applications can gain traction.
For Investors and Strategic Acquirers:
Consolidation pressure builds where hardware fragmentation meets specialized software needs, creating opportunities for targeted acquisitions. The long-term viability of edge AI software is anchored in its ability to enable real-time decision-making and ensure data sovereignty. Identify acquisition targets that are specialized software optimizers or embedded AI solution providers with strong intellectual property. The rapid adoption of new data residency laws or industry-specific compliance standards serves as a key signal to watch for inflection points.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop Edge-Native AI Platforms | This initiative enables efficient processing directly on endpoint devices, reducing latency for critical applications. |
| Invest in Hardware-Software Co-development | This strategy optimizes AI models for diverse edge processors, enhancing performance and energy efficiency. |
| Form Strategic Cloud-Edge Partnerships | These alliances extend cloud intelligence to edge devices, creating seamless hybrid AI environments for enterprises. |
| Acquire Niche Algorithm Developers | This move integrates specialized AI capabilities, addressing specific industry challenges like predictive maintenance. |
| Expand into Emerging Manufacturing Hubs | This geographic expansion captures demand from industrial digitalization initiatives in regions like Southeast Asia. |
Research Approach
Multiple input streams — primary interviews with industry stakeholders, secondary market intelligence, and econometric modeling — were reconciled to construct a comprehensive market view. This involved engaging CTOs at manufacturing firms, automotive R&D leads, AI platform engineers, and regulatory compliance officers. Secondary validation drew from SEC filings of leading technology companies, industry association reports, and government technology policy documents.
Data stream reconciliation informed the analytical framework, which segmented the market by deployment model, solution type, use case, end-user industry, and regional adoption pattern. Volume and value outputs across the analysis window reflect a triangulated approach, integrating historical trends with projected technological advancements. Compound annual growth rates were derived from a blend of quantitative analysis and qualitative insights into 5G rollout rates and semiconductor manufacturing capacity.
Revisions become necessary when unforeseen regulatory shifts or rapid hardware obsolescence materialize. Forecasts reflect assumptions documented at the time of publication regarding technological trajectories and market acceptance. Global talent migration and evolving cybersecurity threats represent specific risk factors. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Artificial Intelligence in Telecommunication Market
Artificial Intelligence (AI)
CLV and Churn Prediction AI Market
Artificial Intelligence (AI)
Enterprise LLM Market
Artificial Intelligence (AI)
Brain Computer Interface Market
Artificial Intelligence (AI)
Multimodal AI Market
Artificial Intelligence (AI)
Model Validation and Automation Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) Software Market
Artificial Intelligence (AI)
Semantic Web Market
Artificial Intelligence (AI)
Global Artificial Intelligence in Stadium Market
Artificial Intelligence (AI)
Cloud Artificial Intelligence Market
Artificial Intelligence (AI)
Explainable AI Market
Artificial Intelligence (AI)
Intelligent Assistant Embedded Consumer Devices Market
Artificial Intelligence (AI)
Cognitive Collaboration Market
Artificial Intelligence (AI)
Global Cognitive Operations Market
Artificial Intelligence (AI)
AI in Fashion Market
Artificial Intelligence (AI)
Neural Network Market