
 Intelligent Assistant Embedded Consumer Devices Market | 2026-2036
Intelligent Assistant Embedded Consumer Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Intelligent Assistant Embedded Consumer Devices Market Outlook
Asian semiconductor foundries is consolidating output for voice-processing chipsets destined for consumer electronics. Amazon leverages its Alexa ecosystem to anchor smart speaker distribution across North American retail channels. Google LLC competes through deep integration of its assistant into Android-powered televisions and automotive interfaces. Apple Inc. differentiates by controlling proprietary silicon and on-device inference for privacy-centric users.
Intelligent assistant embedded consumer devices combine microphone arrays, natural language processors, and wireless connectivity modules to execute voice-activated commands without continuous cloud dependency. These systems typically operate on ARM-based architectures with wake-word detection consuming under 500 milliwatts in standby mode, serving residential automation and hands-free computing needs. Smart speakers dominate shipment volumes while edge computing integration captures the fastest expansion as latency-sensitive applications multiply. Wearable technology concentrates margin pools where health monitoring functionality commands premium positioning.
The EU AI Act imposes risk-classification obligations on conversational AI deployed in European households, compelling manufacturers to document training data provenance. The FCC in the United States governs spectrum allocation for Wi-Fi and Bluetooth protocols that carry voice traffic between devices and routers. China's SAMR enforces algorithmic recommendation provisions affecting how intelligent assistants surface content to users. Stakeholders must monitor diverging compliance timelines across jurisdictions to avoid market access fragmentation.
Market Dynamics
Edge computing deployment is compressing latency requirements for voice-activated systems, forcing manufacturers to relocate inference workloads from cloud data centers to ARM-based silicon within the device enclosure. This architectural migration is redistributing value capture toward semiconductor foundries and away from hyperscale cloud operators.
Growth Catalysts
- EU AI Act compliance mandates:Risk-classification obligations for conversational AI deployed in European households are compelling manufacturers to document training data provenance, creating certified-product premiums for compliant vendors.
- Smart home automation clusters:Residential users in Germany, France, and the United Kingdom are accelerating adoption of integrated voice-controlled lighting, climate, and security systems.
- Wake-word detection efficiency gains:Sub-500 milliwatt standby consumption on microphone array chipsets is enabling always-on operation in battery-powered wearables without daily recharging cycles.
Market Restraints
- Silicon supply concentration:Voice-processing chipset output is consolidating among Asian semiconductor foundries, creating single-source vulnerability for OEMs dependent on specific 12-inch wafer capacities.
- Algorithmic transparency costs:The EU AI Act's documentation requirements impose fixed compliance burdens that disproportionately burden low-volume manufacturers serving niche European segments.
- Wireless protocol fragmentation:Divergent spectrum allocation rules between the FCC in the United States and China's SAMR complicate SKU rationalization for globally distributed product lines.
Strategic Opportunities
- Health monitoring wearables convergence:Premium positioning in wrist-worn devices combining voice assistance with biometric sensing commands margin pools unavailable to standalone smart speakers.
- Automotive interface integration:Android-powered infotainment systems are creating embedded assistant opportunities in vehicle cabins where hands-free operation is safety-mandated.
- Shenzhen electronics ecosystem proximity:Edge computing hardware developers co-located with component markets can compress prototyping cycles for latency-sensitive applications.
Industry Challenges
- Natural language processing talent scarcity:On-device inference optimization requires specialized firmware engineers familiar with quantized neural network deployment, a skill set concentrated among competing employers in Seoul and Austin.
- Cross-jurisdiction certification timelines:Staggered implementation dates for the EU AI Act, FCC equipment authorization, and China's SAMR algorithmic recommendation provisions fragment product launch synchronization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intelligent Assistant Embedded Consumer Devices Market |
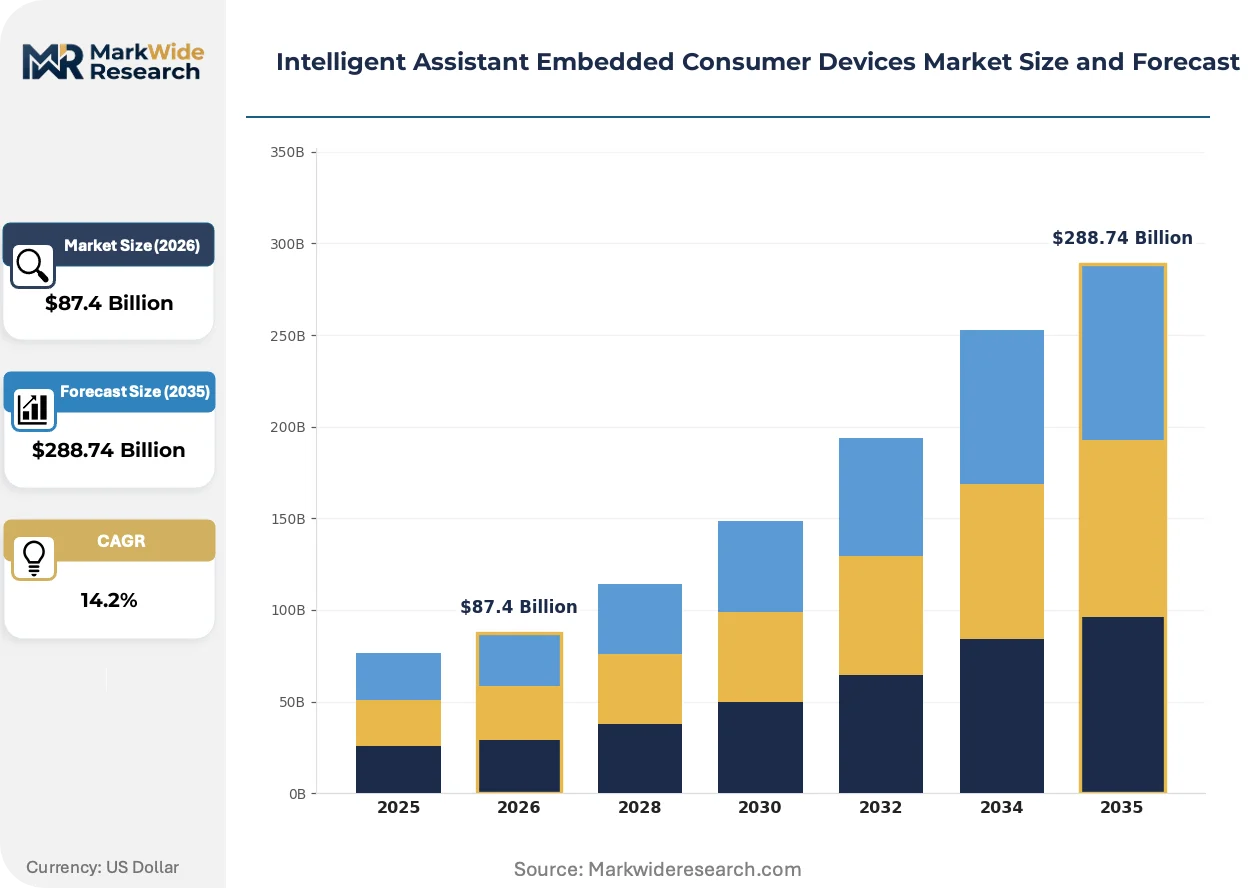
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $288.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Smart Speakers, Wearable Technology, Smart Displays, Home Appliances Integration Level: Cloud-Based, On-Premises, Hybrid, Edge Computing End User: Residential Users, Businesses, Educational Institutions, Healthcare Providers Functionality: Voice Control, Smart Home Automation, Health Monitoring, Personal Assistance |
| Companies Covered | Amazon, Google LLC, Apple Inc., Samsung Electronics Co., Ltd., Microsoft Corporation, LG Electronics Inc., Sony Corporation, Intel Corporation, Huawei Technologies Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intelligent Assistant Embedded Consumer Devices Market Strategic Shifts
Architectural decisions around inference location are reshaping competitive boundaries between cloud-native assistant providers and silicon-integrated device manufacturers. The technical trajectory favors vendors controlling both ends of this stack.
On-device natural language processing is consolidating execution of voice commands within the device enclosure rather than transmitting audio streams to remote servers. Smart speaker manufacturers in North American retail channels are adopting this architecture to reduce subscription dependency. The shift is consolidating value capture toward semiconductor vendors and compressing margins for pure-play cloud service operators.
The EU AI Act's risk-classification framework is tightening algorithmic transparency requirements for voice-enabled systems entering European households. Manufacturers must now document training data provenance and model decision pathways before CE marking approval. Smart home automation vendors serving Germany, France, and the United Kingdom are responding by establishing dedicated compliance functions and pre-certifying silicon platforms.
Residential buyers are rotating procurement preferences toward privacy-centric configurations where wake-word detection and command processing occur without continuous cloud connectivity. Smart speaker distribution through North American retail channels is fragmenting between connected and edge-isolated product tiers. This bifurcation is most visible among premium residential segments in Germany and the United Kingdom where GDPR awareness intersects with disposable income thresholds.
Intelligent Assistant Embedded Consumer Devices Market Segmentation
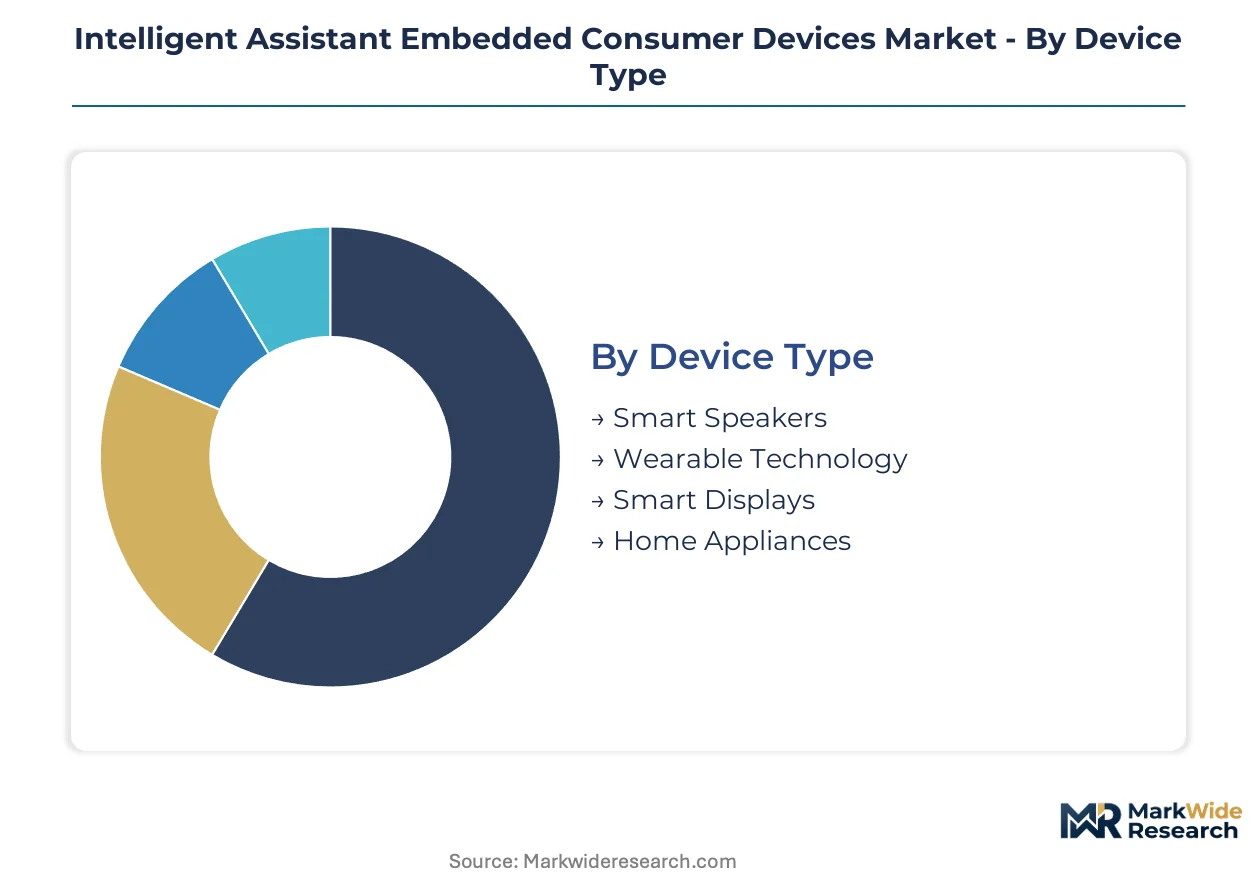
Intelligent assistant embedded consumer devices fragment across four intersecting dimensions that determine silicon requirements, compliance obligations, and margin architecture. Device type and integration level govern hardware BOM composition, while end user and functionality shape firmware complexity and certification pathways.
Device Type:
Standardization dominates at the high-volume end of this spectrum, with customization concentrating in health-integrated form factors where sensor fusion demands proprietary acoustic tuning.
- Smart Speakers:Cylindrical or spherical enclosures housing microphone arrays with far-field voice capture and Wi-Fi/Bluetooth connectivity modules. Demand clusters in Germany, France, and the United Kingdom where residential automation adoption is accelerating. Wake-word detection efficiency gains below 500 milliwatts enable always-on operation without thermal management complexity.
- Wearable Technology:Wrist-worn or ear-worn devices combining voice assistance with biometric sensing capabilities. Health monitoring functionality commands premium positioning unavailable to standalone smart speakers, with margin pools concentrating where FDA or EU MDR clearance intersects with consumer electronics distribution. Battery constraints drive sub-threshold silicon selection.
- Smart Displays:Screen-integrated assistants with visual feedback for video calling and content browsing.
- Home Appliances:Refrigerators, ovens, and washing machines with embedded voice interfaces for hands-free operation.
Leading the category by volume: Smart Speakers. Expanding most quickly: Wearable Technology.
Integration Level:
Cost tier stratification separates royalty-bearing cloud dependencies from capital-intensive edge silicon investments, with hybrid architectures occupying the mid-tier optimization zone.
- Cloud-Based:Audio streams transmit to remote servers for natural language processing and command execution. Hyperscale operators capture recurring value while OEMs absorb connectivity BOM costs and subscription dependency risks.
- Edge Computing:ARM-based silicon executes wake-word detection and command inference within the device enclosure. Shenzhen, Seoul, and Austin concentrate hardware development where latency-sensitive applications demand sub-100 millisecond response times. This architectural migration redistributes value capture toward semiconductor foundries.
- On-Premises:Local server infrastructure processes voice commands without external connectivity.
- Hybrid:Edge wake-word detection triggers cloud processing for complex queries only.
Dominant by deployment scale: Cloud-Based. Gaining share fastest: Edge Computing.
End User:
Application context determines acoustic environment complexity, with residential settings demanding noise robustness and healthcare environments requiring HIPAA or GDPR-aligned data handling.
- Residential Users:Household deployments across single-family and multi-unit dwellings. Germany, France, and the United Kingdom show accelerating procurement of integrated lighting, climate, and security systems with unified voice control.
- Healthcare Providers:Clinical and home-care settings where hands-free operation reduces contamination risks. EU AI Act risk-classification obligations impose documentation requirements for training data provenance before CE marking approval.
- Businesses:Corporate environments with multi-user voice profiles and access control integration.
- Educational Institutions:Classroom and campus deployments for administrative assistance and accessibility support.
Largest addressable base: Residential Users. Steepest compliance-driven expansion: Healthcare Providers.
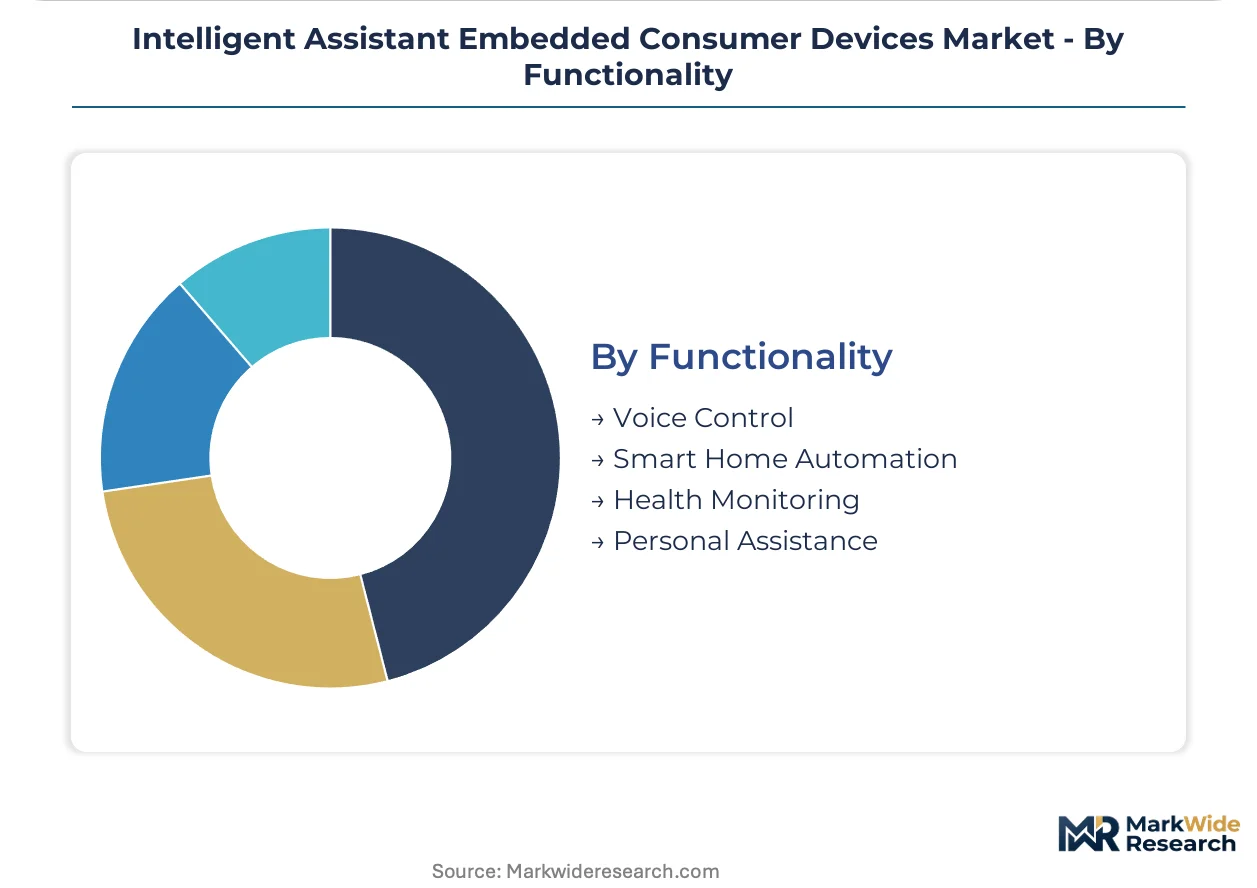
Functionality:
Maturity gradients separate commodity voice control from emergent health monitoring, where regulatory clearance creates defendable margin structures.
- Smart Home Automation:Unified control of lighting, HVAC, security, and entertainment systems through voice commands. Residential buyers in Germany and the United Kingdom rotate procurement toward privacy-centric configurations with edge-isolated processing tiers.
- Health Monitoring:Biometric sensing combined with voice assistance for wellness tracking and emergency response. FDA and EU MDR pathways create certification premiums that commodity functionality cannot replicate.
- Voice Control:Basic command execution for media playback, information retrieval, and device operation.
- Personal Assistance:Calendar management, messaging, and productivity task execution.
Widest installed base: Smart Home Automation. Climbing the fastest: Health Monitoring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon wafer fabrication capacity in Taiwan and South Korea anchors supply-side positioning for voice-processing chipsets, while demand-side procurement clusters concentrate in North American and European residential automation markets.
United States
FCC spectrum allocation for Wi-Fi and Bluetooth protocols shapes device connectivity architecture, with Austin and Seattle hosting edge computing development clusters where latency-sensitive inference workloads concentrate. Residential buyers through North American retail channels rotate toward privacy-centric smart speaker configurations with on-device processing tiers.
Germany
EU AI Act risk-classification obligations for conversational AI compel manufacturers to document training data provenance before CE marking approval, creating compliance premiums for certified vendors. Munich and Berlin anchor smart home automation adoption clusters where integrated voice-controlled lighting and climate systems penetrate premium residential segments.
China
SAMR algorithmic recommendation provisions govern how intelligent assistants surface content to users, with Shenzhen's electronics ecosystem compressing prototyping cycles for edge computing hardware developers. Domestic OEMs leverage proximity to Asian semiconductor foundries for voice-processing chipset procurement.
United Kingdom
GDPR-aligned data handling requirements intersect with disposable income thresholds to fragment smart speaker distribution between connected and edge-isolated product tiers. London and Manchester residential buyers demonstrate accelerating procurement of unified voice-controlled security and entertainment systems.
South Korea
Seoul concentrates specialized firmware engineering talent for quantized neural network deployment, with Samsung Electronics anchoring domestic smart display and wearable technology production. Government-backed AI semiconductor initiatives reinforce local edge computing silicon development.
Intelligent Assistant Embedded Consumer Devices Market Competitive Environment
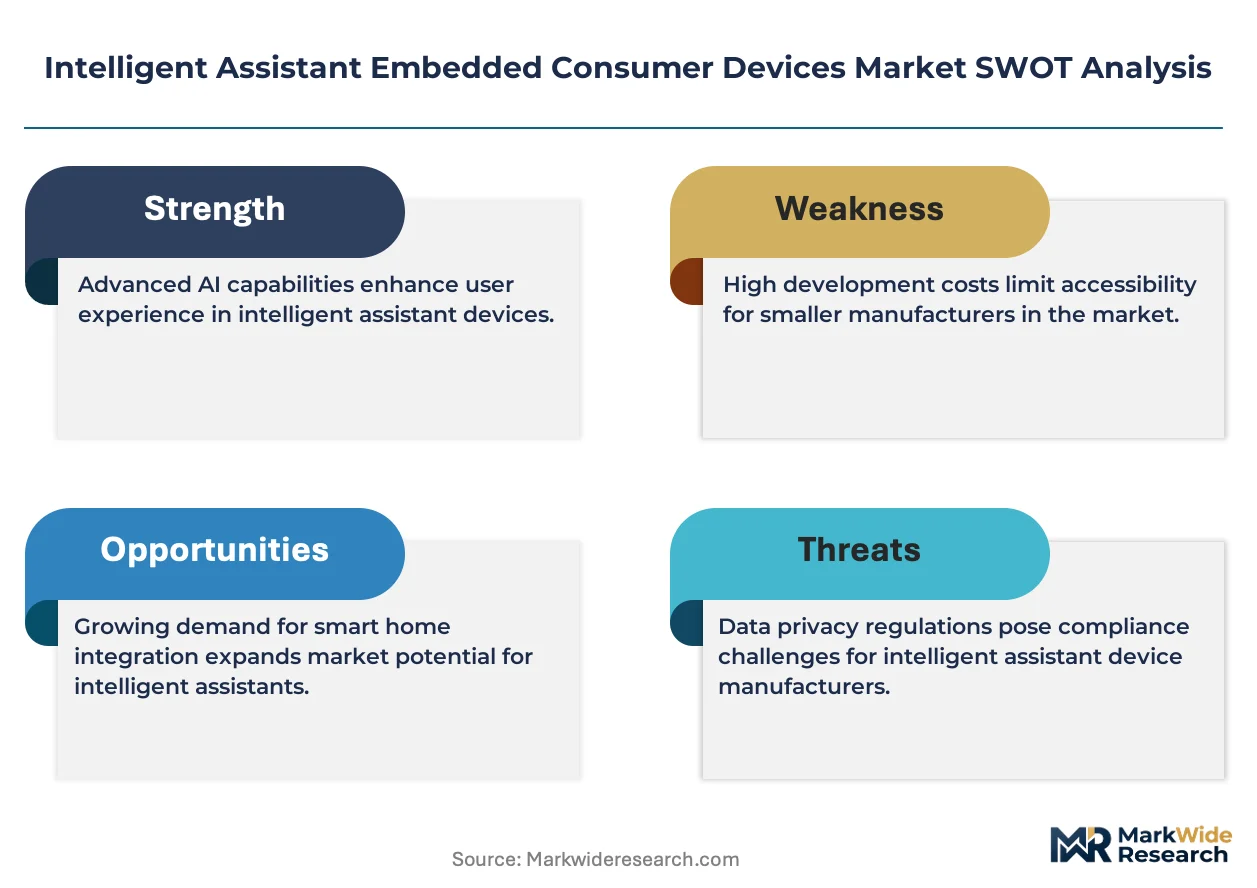
Established producers occupy the standard tier; emerging entrants pursue health-integrated wearable form factors and automotive cabin interfaces. The vendor base stratifies across three maturity tiers: hyperscale cloud operators with assistant ecosystems, consumer electronics OEMs with silicon integration capabilities, and semiconductor foundries capturing value from edge computing migration. Competitive positioning depends on M&A activity targeting voice-processing IP and strategic partnerships between automotive Tier 1s and assistant platform providers.
Within the hyperscale ecosystem tier, Amazon and Google LLC exemplify platform-centric positioning through retail channel anchoring and Android integration vectors respectively. Apple Inc. occupies a differentiated position through proprietary silicon control and on-device inference architecture. Samsung Electronics Co., Ltd. represents the diversified electronics conglomerate archetype spanning smart displays, wearables, and home appliances with embedded voice interfaces.
| Leading Market Players |
|---|
| Amazon |
| Google LLC |
| Apple Inc. |
| Samsung Electronics Co., Ltd. |
| Microsoft Corporation |
| LG Electronics Inc. |
| Sony Corporation |
| Intel Corporation |
| Huawei Technologies Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Residential procurement preferences for privacy-centric configurations in Germany and the United Kingdom are compelling manufacturers to source edge-capable silicon from Taiwan and South Korea, compressing margins on cloud-dependent product tiers while inflating premiums for on-device inference architectures.
Pricing Analysis
Warranty and service bundling separates premium voice-enabled devices from economy tiers, with extended EU AI Act compliance documentation and on-device processing warranties commanding 15-25% uplifts over standard cloud-connected units. Price differentiation rests on CE marking tier and wake-word detection efficiency grade, with sub-500 milliwatt standby certification attracting residential buyers in France and Germany. Pricing pressure stems from Asian foundry consolidation in 12-inch wafer capacity for ARM-based voice processors. Healthcare providers demonstrate lowest price sensitivity due to FDA and EU MDR clearance requirements, while mass-market smart speaker buyers in North American retail channels exhibit highest elasticity.
Supply Chain Analysis
Freight cost volatility from Asian semiconductor hubs to European assembly plants is compressing landed costs for voice-processing chipsets, with air freight premiums for prototype iterations offset by ocean freight economies on volume production. Supply concentrates in Taiwan, South Korea, and China for microphone array modules, natural language processing ASICs, and wireless connectivity components. Raw material dependencies include 12-inch silicon wafers, rare-earth magnets for speaker drivers, and lithium-polymer cells for wearable form factors. Single-source vulnerability in TSMC and Samsung Foundry capacity allocation represents the dominant structural risk. Distribution runs through Shenzhen electronics markets for component sourcing, then consolidates through regional distribution centers serving German, UK, and US retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The intelligent assistant embedded consumer devices market is executing a architectural transition from cloud-native inference to edge-computing silicon, with on-device natural language processing displacing subscription-dependent voice services as the dominant technical trajectory.
For Market Incumbents: To counter margin compression from hyperscale cloud operators, Amazon and Google LLC must deepen backward integration into ARM-based silicon design while establishing captive foundry relationships in Taiwan and South Korea. Certification investment in EU AI Act pre-approved hardware platforms creates defendable positioning in German and UK residential segments where compliance premiums persist.
For New Entrants and Emerging Players: Specialized firmware for quantized neural network deployment on battery-constrained wearables offers the most penetrable white-space target, with health monitoring functionality in wrist-worn devices commanding margin pools unavailable to commodity smart speakers. FDA and EU MDR clearance pathways provide the strongest go-to-market angle against established consumer electronics OEMs.
For Investors and Strategic Acquirers: The window for entry favors voice-processing IP specialists with on-device inference optimization capabilities and established relationships with Seoul or Austin engineering talent pools. Long-term viability hinges on controlling both silicon architecture and assistant software layers. Watch for inflection signals in automotive Tier 1 partnerships for cabin-embedded assistants, where safety-mandated hands-free operation is accelerating procurement timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge Computing Silicon Acquisition | Captures value migration from hyperscale cloud operators to semiconductor foundries in Taiwan and South Korea. |
| EU AI Act Pre-Certification Program | Establishes compliance premiums in German and UK residential automation markets before staggered implementation deadlines. |
| Health Monitoring Wearable Launch | Accesses FDA and EU MDR margin pools through biometric sensing integration in wrist-worn voice assistants. |
| Automotive Tier 1 Partnership | Secures safety-mandated positioning in vehicle cabin interfaces through Android-powered infotainment integration. |
| Shenzhen Ecosystem Proximity Investment | Compresses prototyping cycles for latency-sensitive edge computing hardware developers near component markets. |
Study Parameters
Independent corroboration across primary interviews with smart home automation vendors, semiconductor foundry procurement managers, EU regulatory affairs consultants, and North American retail channel buyers underwrites the qualitative findings in this analysis. Secondary validation draws from FCC equipment authorization databases, EU AI Act implementation guidance, SAMR algorithmic recommendation provisions, SEC filings of hyperscale cloud operators, and customs records of voice-processing chipset trade flows. Bottom-up shipment estimates by device type and integration level triangulate against top-down market sizing by regional procurement clusters.
Rate-of-change decomposition separates volume expansion from value migration effects across the analysis window, with CAGRs derived from segmented growth trajectories by device type, integration level, end user, and functionality. The analytical framework models smart speaker, wearable technology, smart display, and home appliance form factors against cloud-based, edge computing, hybrid, and on-premises architectures. Input assumptions include ARM-based silicon adoption curves, EU AI Act compliance cost pass-through rates, and healthcare provider procurement timelines for HIPAA-aligned voice systems.
Several conditions sit outside the modeled scope, including unforeseen tariff escalations on Chinese-manufactured components, abrupt foundry capacity reallocations to automotive or AI training chipsets, and accelerated regulatory fragmentation beyond the EU AI Act, FCC, and SAMR frameworks already incorporated. Forecasts reflect assumptions about edge computing latency requirements and residential privacy preferences that may shift with technological or cultural developments. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Cognitive Collaboration Market
Artificial Intelligence (AI)
Japan Edge AI Market
Artificial Intelligence (AI)
Global Cognitive Computing Technology Market
Artificial Intelligence (AI)
Artificial Intelligence in Robots Market
Artificial Intelligence (AI)
Global AI Training Dataset Market
Artificial Intelligence (AI)
Artificial Intelligence and Machine Learning Market
Artificial Intelligence (AI)
Intelligent Virtual Assistant Market
Artificial Intelligence (AI)
Voice Assistance Application Market
Artificial Intelligence (AI)
AI in Fashion Market
Artificial Intelligence (AI)
CLV and Churn Prediction AI Market
Artificial Intelligence (AI)
AI in Life Sciences Market
Artificial Intelligence (AI)
Global Natural Language Generation (NLG) Market
Artificial Intelligence (AI)
Brain-Computer Interface System Market
Artificial Intelligence (AI)
Global Mobile Artificial Intelligence Market
Artificial Intelligence (AI)
Global Enterprise Artificial Intelligence Market
Artificial Intelligence (AI)
Aiops Market