
 Artificial Intelligence in Workspace Market | 2026-2036
Artificial Intelligence in Workspace Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Intelligence in Workspace Market Analysis
Generative AI integration into enterprise software is reshaping how knowledge workers interact with productivity tools. Microsoft leverages its Copilot architecture across Office 365 and Teams to anchor enterprise adoption. Nvidia sustains dominance in AI training infrastructure that powers backend workspace intelligence. Google competes through deep integration of Gemini into Workspace applications.
Artificial Intelligence in Workspace encompasses machine learning models, natural language processing engines, and robotic process automation tools deployed to augment human productivity in professional environments. These systems process unstructured data, generate content, and automate repetitive cognitive tasks through cloud-based inference APIs and on-premise model serving. Natural language processing leads technology adoption due to its direct applicability in document generation and conversational interfaces. Workflow automation applications capture expanding margin pools as enterprises seek measurable efficiency gains. Cloud-based deployment dominates new implementations, though hybrid configurations persist in regulated industries.
The EU AI Act imposes risk-tiered compliance obligations on automated workplace systems, while the US lacks unified federal AI legislation and relies on sectoral FDA, FCC, and NHTSA guidance. ISO standards for AI management systems are gaining traction as procurement benchmarks across multinational corporations. Enterprises must evaluate whether their AI workspace vendors maintain auditable model governance before committing to multi-year platform contracts.
Market Dynamics
Enterprise IT departments are consolidating vendor relationships around platforms that embed generative AI natively, compressing procurement cycles from multi-year evaluations to accelerated pilot-to-production timelines as competitive pressure mounts.
Growth Catalysts
- EU AI Act transparency mandates:Risk-tiered classification of automated workplace systems is forcing enterprises to upgrade legacy workflow tools, creating replacement demand for auditable AI platforms across financial services and healthcare corridors in Germany, France, and the Netherlands.
- Natural language processing engines:Document generation and conversational interfaces are reducing administrative task time by measurable increments, with legal, consulting, and research-intensive sectors deploying these tools at scale.
- Cloud inference API expansion:On-demand model serving is lowering barriers to AI workspace adoption for mid-market enterprises previously excluded by infrastructure capital requirements.
Market Restraints
- GPU supply concentration:Training infrastructure for large language models remains dependent on a narrow supplier base, creating procurement bottlenecks and pricing volatility for enterprises building custom AI workspace solutions.
- Data residency requirements:Cross-border data transfer restrictions under GDPR and emerging national privacy frameworks are fragmenting cloud deployment architectures and inflating compliance overhead.
- Technical debt in legacy systems:Decades-old enterprise resource planning and document management platforms resist API-level integration with modern AI agents, forcing expensive middleware development.
Strategic Opportunities
- Regulatory tailwind from ISO 42001:The emerging AI management systems standard is becoming a procurement benchmark for multinational corporations, creating first-mover advantage for vendors achieving early certification.
- Workflow automation in regulated industries:Insurance claims processing and pharmaceutical regulatory submission workflows remain underpenetrated by intelligent automation, offering expansion vectors for specialized platform providers.
- Edge deployment configurations:Hybrid architectures combining cloud training with on-premise inference are opening public sector and defense contracts previously inaccessible to pure-cloud vendors.
Industry Challenges
- Prompt engineering talent scarcity:The specialized skill set required to optimize large language model outputs for enterprise workflows commands premium compensation, constraining implementation velocity.
- Model governance audit complexity:Multi-year platform contracts now require demonstrable bias testing, version control, and explainability documentation that most vendors lack operational maturity to deliver.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Intelligence in Workspace Market |
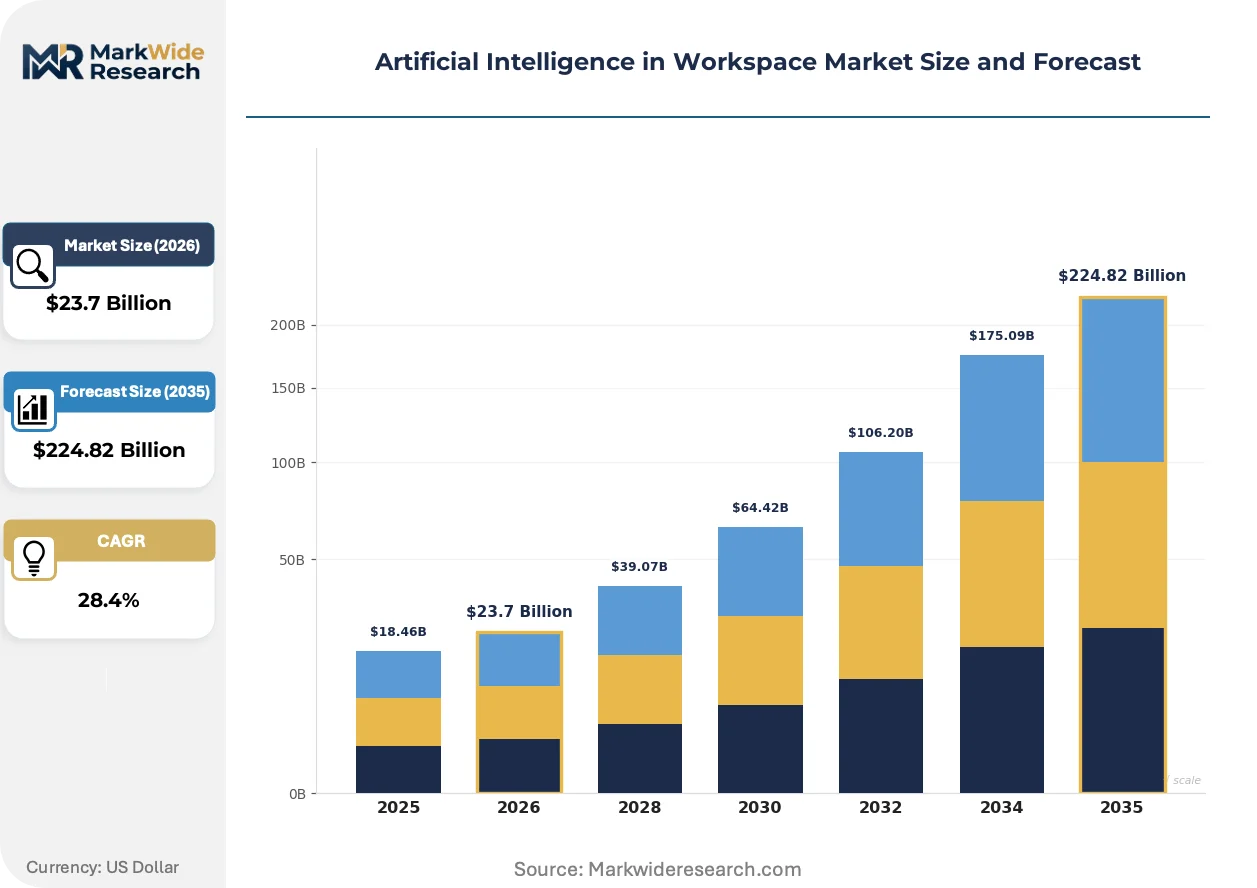
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $224.82 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Machine Learning, Natural Language Processing, Robotic Process Automation, Computer Vision Application: Virtual Assistants, Workflow Automation, Data Analysis, Predictive Analytics End User: IT Departments, HR Teams, Marketing Firms, Customer Service Deployment: On-Premise, Cloud-Based, Hybrid, Managed Services |
| Companies Covered | Microsoft, Amazon Web Services, Nvidia, IBM, Google, Samsung, Atlassian, Notion, Palantir, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Intelligence in Workspace Market Emerging Trajectories
Generative AI capabilities are migrating from standalone applications into the fabric of everyday productivity software, altering how knowledge workers interact with information and compressing the gap between intent and output.
Retrieval-augmented generation architectures are hybridizing document search with synthetic content creation, enabling enterprise knowledge bases to answer complex queries with cited source material. Legal departments and research functions are adopting these systems fastest, replacing manual literature review with automated synthesis. The technology is hybridizing traditional enterprise search markets with generative content markets, collapsing what were previously distinct software procurement categories.
The EU AI Act's risk-based compliance framework is reshaping vendor product roadmaps, with high-risk workplace automation systems now requiring human oversight mechanisms and algorithmic impact assessments. Platform providers are restructuring model documentation and audit trails to satisfy conformity assessment requirements. Financial services deployments across Frankfurt, Paris, and Amsterdam are experiencing the most acute compliance timeline pressure, with procurement teams demanding pre-certified solutions.
Enterprise buyers are consolidating vendor relationships around integrated suites rather than best-of-breed point solutions, privileging platforms that embed AI across email, documents, meetings, and project management. Channel partners and systems integrators are repositioning around implementation and change management services as product differentiation narrows. This concentration pattern is most pronounced in United States technology corridors and London financial services clusters, where procurement teams prioritize interoperability over specialized functionality.
Artificial Intelligence in Workspace Market Segmentation
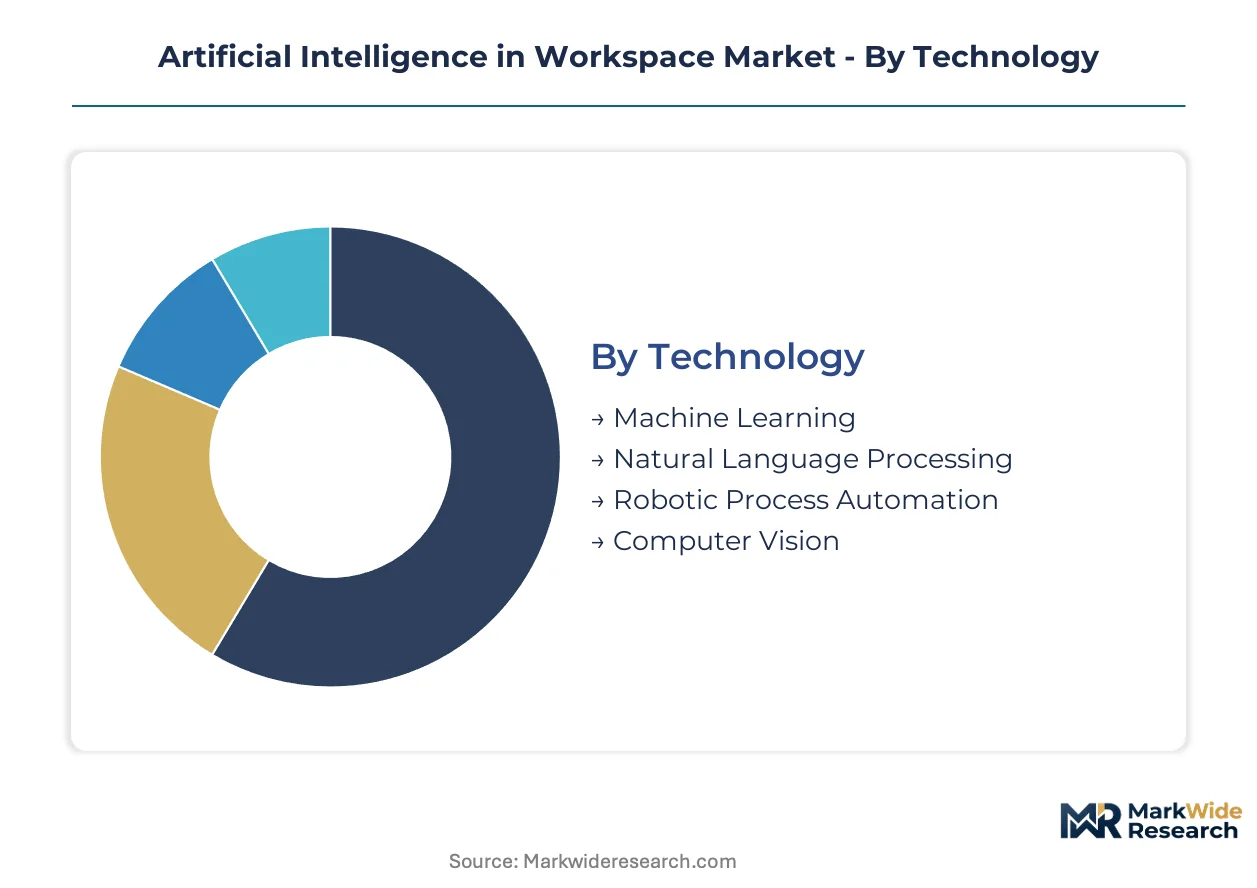
Workspace AI segmentation reveals distinct procurement patterns across technology maturity and deployment risk tolerance. Enterprise buyers prioritize segments offering measurable productivity gains against compliance-verifiable infrastructure.
Technology:
Mature capabilities dominate current deployments while emerging modalities capture experimental budgets.
- Machine Learning:Statistical pattern recognition algorithms power predictive workload scheduling and resource optimization across enterprise infrastructure. Financial services corridors in the United States and Germany deploy these systems for fraud detection and capacity planning, constrained by model interpretability requirements under the EU AI Act.
- Natural Language Processing:Transformer-based architectures enable document synthesis, email triage, and conversational interfaces in productivity suites. Legal departments and consulting firms in London and New York drive procurement volumes, motivated by measurable reductions in administrative review time.
- Robotic Process Automation:Rule-based task automation handles structured data workflows with deterministic outputs.
- Computer Vision:Image recognition systems process document scans, video conferencing analytics, and physical workspace monitoring.
Natural Language Processing handles the majority of throughput; Computer Vision is the fastest mover on share.
Application:
Cost tier stratification separates proof-of-concept pilots from scaled production deployments.
- Workflow Automation:Intelligent process orchestration connects disparate enterprise systems through API-based task chaining. Insurance claims processing and pharmaceutical regulatory submissions in the United States and Switzerland show concentrated demand, driven by quantifiable cost-per-transaction reductions.
- Virtual Assistants:Conversational agents handle meeting scheduling, information retrieval, and routine inquiry resolution. Technology sector adoption concentrates in San Francisco and Seattle clusters, where engineering teams prioritize uninterrupted deep-work periods.
- Data Analysis:Automated insight generation from structured business intelligence datasets.
- Predictive Analytics:Forecasting models project resource needs, customer behavior, and operational risks.
Workflow Automation commands the largest implementation spend; Predictive Analytics is climbing the fastest on enterprise priority lists.
End User:
Customer type determines feature requirements and security posture specifications.
- IT Departments:Infrastructure teams deploy AI for ticket classification, anomaly detection, and automated remediation scripts. German automotive manufacturers and Dutch financial institutions mandate ISO 42001-aligned governance in procurement specifications.
- HR Teams:Talent acquisition and employee engagement platforms leverage AI for candidate screening and sentiment analysis. Regulatory scrutiny under GDPR and emerging algorithmic management laws in France and Spain constrains deployment velocity.
- Marketing Firms:Content generation and campaign optimization tools target creative production workflows.
- Customer Service:Support automation and quality assurance systems manage inquiry routing and response coaching.
IT Departments absorb the deepest technology investment; HR Teams are gaining share fastest as compliance frameworks mature.
Deployment:
Geography dictates architecture choices through data residency and latency requirements.
- Cloud-Based:Scalable inference APIs eliminate capital expenditure for model training infrastructure. Mid-market enterprises across the United Kingdom and Netherlands favor this model, enabled by expanding regional cloud availability zones.
- Hybrid:Split architectures train models in cloud environments while serving predictions from on-premise infrastructure. Defense contractors and public sector agencies in the United States and Germany require this configuration for classified or sensitive data handling.
- On-Premise:Fully captive infrastructure serves highly regulated workloads with complete data sovereignty.
- Managed Services:Third-party operators handle model operations, updates, and compliance documentation.
Cloud-Based deployment carries the dominant transaction volume; Hybrid configurations are expanding most quickly on contract value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based AI workspace vendors export inference infrastructure and productivity platforms to enterprise buyers across Germany, Japan, and the United Kingdom, establishing transatlantic and transpacific trade corridors that concentrate deployment spend in financial services and technology clusters.
United States
Enterprise procurement teams in San Francisco and New York Metro prioritize generative AI integration across Office 365 and collaboration suites. The FDA and FCC maintain sectoral guidance on automated decision systems without unified federal AI legislation. Technology corridors in Seattle and Austin host the densest concentration of pilot-to-production deployments for intelligent workflow platforms.
Germany
Automotive manufacturers and financial institutions in Frankfurt and Munich mandate ISO 42001-aligned governance specifications for AI workspace procurement. The EU AI Act imposes risk-tiered compliance obligations on automated workplace systems with acute timeline pressure for high-risk classifications. Industrial clusters in Stuttgart and Wolfsburg deploy predictive workload scheduling for manufacturing optimization.
United Kingdom
Legal departments and consulting firms in London drive natural language processing adoption for document synthesis and administrative review reduction. GDPR cross-border data transfer restrictions fragment cloud deployment architectures and inflate compliance overhead. The technology corridor between London and Cambridge concentrates retrieval-augmented generation deployments for enterprise knowledge bases.
Japan
Enterprise buyers in Tokyo and Osaka prioritize uninterrupted deep-work periods through virtual assistant deployment for meeting scheduling and information retrieval. METI promotes AI management system standards that align with emerging ISO frameworks. Manufacturing headquarters in Nagoya integrate computer vision systems for document processing and quality assurance workflows.
Netherlands
Mid-market enterprises in Amsterdam and Rotterdam favor cloud-based inference APIs enabled by expanding regional cloud availability zones. The EU AI Act's transparency mandates create replacement demand for auditable AI platforms across financial services corridors. The Eindhoven technology cluster hosts specialized providers targeting pharmaceutical regulatory submission automation.
Artificial Intelligence in Workspace Market Vendor Landscape
Channel-controlling players compete with product-specialist players for procurement relationships in enterprise IT departments. The vendor base concentrates around integrated productivity suites that embed generative AI natively, compressing evaluation cycles from multi-year assessments to accelerated pilots. Two strategic archetypes dominate: hyperscale cloud providers with training infrastructure dominance, and specialized workflow platforms with deep vertical integration. Competitive moves center on strategic partnerships for model access and geographic expansion through regional cloud availability zones.
Within the hyperscale infrastructure tier, Microsoft and Amazon Web Services occupy positions that exemplify channel control through embedded distribution in existing enterprise software contracts. Nvidia anchors the training hardware layer that powers backend workspace intelligence across vendor ecosystems. These three entities represent the concentration of technical capability and procurement leverage that shapes competitive dynamics for mid-market and specialized players.
| Leading Market Players |
|---|
| Microsoft |
| Amazon Web Services |
| Nvidia |
| IBM |
| Samsung |
| Atlassian |
| Notion |
| Palantir |
| Others |
Supply Flow & Price Mechanics
Overcapacity in cloud inference infrastructure across the United States and Western Europe is compressing per-token pricing for natural language processing services while forcing hyperscale providers to bundle compute credits with productivity suite subscriptions. This utilization dynamic rewards buyers with scale commitments while squeezing specialized middleware vendors unable to match bundled economics.
Pricing Analysis
Technology-generation pricing gaps separate legacy rule-based automation from transformer-based generative systems and emerging multimodal architectures. Subscription-tiered SaaS models dominate enterprise procurement, with ISO 42001 certification tier and inference volume scale serving as the primary price differentiation drivers. Cost compression in mid-market workflow automation is intensifying because cloud API commoditization erodes proprietary model premiums. Mid-market enterprises exhibit the highest price sensitivity, while defense contractors and pharmaceutical regulatory teams absorb premium pricing for hybrid deployment configurations.
Supply Chain Analysis
Contract-manufacturing concentration for AI training hardware rests with Taiwan Semiconductor Manufacturing Company and Samsung Foundry for advanced process nodes, with assembly and testing concentrated in Malaysia and Vietnam. Raw material dependencies span high-bandwidth memory from South Korea, advanced packaging substrates from Japan, and rare earth elements for magnetics from China. Single-source vulnerability in EUV lithography equipment creates structural supply chain risk. Distribution runs through hyperscale cloud marketplaces and direct enterprise sales teams with regional systems integrator overlays.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from open-source model ecosystems that erode proprietary API pricing power and commoditize core natural language processing capabilities.
For Market Incumbents: Pre-empt open-source displacement by embedding inference capabilities directly into existing productivity suite contracts, removing standalone procurement friction. Accelerate ISO 42001 certification timelines to capture replacement demand from EU AI Act compliance deadlines. Channel control through pre-installed software distribution remains the critical defensive lever against API-only challengers.
For New Entrants and Emerging Players: Build out specialized retrieval-augmented generation platforms targeting pharmaceutical regulatory submission workflows in Switzerland and the Netherlands, segments where incumbent suites lack vertical depth. Insurance claims processing automation offers comparable white-space opportunity with measurable ROI documentation requirements. Go-to-market execution should route through boutique systems integrators with existing payer relationships rather than direct enterprise sales.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across pure-software AI workspace layers as cloud infrastructure commoditizes training and inference. Long-term viability favors asset-light platform providers with recurring revenue concentration and vertical workflow moats. Acquisition targets should demonstrate existing ISO 42001 alignment or EU AI Act pre-certification. The signal to watch is hyperscaler bundling intensity—accelerated credit giveaways indicate pricing pressure that compresses standalone vendor margins.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 42001 Certification Acceleration | Pre-certification captures EU AI Act replacement demand across Frankfurt and Paris financial corridors. |
| Retrieval-Augmented Generation Platform Launch | Vertical specialization in legal document synthesis defends against generalist suite commoditization. |
| Hybrid Deployment Architecture Expansion | On-premise inference capabilities unlock public sector contracts with data sovereignty requirements. |
| Strategic Partnership with Hyperscaler | Model access agreements through AWS or Azure reduce training infrastructure capital requirements. |
| Acquisition of Workflow Automation Specialist | Vertical integration into pharmaceutical regulatory submissions deepens moat in underpenetrated segment. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of hyperscaler capex disclosures, SEC 10-K filings, EU regulatory impact assessments, and ISO standard development documentation. Primary interviews engaged enterprise IT procurement officers, platform engineering leads, channel partner executives, and compliance officers at financial services institutions. Secondary validation drew from FDA sectoral guidance, EU AI Act implementation timelines, and cloud availability zone expansion announcements. Bottom-up deployment estimates triangulated against top-down infrastructure spending analysis.
Forecast inputs span technology generation adoption curves, regulatory compliance timeline pressures, and cloud infrastructure capacity expansion patterns across the projection horizon. Segmentation modeling incorporated deployment architecture, organization size tier, vertical industry, integration complexity level, and regional regulatory cluster. CAGRs were derived from fitted adoption curves against infrastructure scaling constraints. Industry-specific inputs included GPU supply availability and EU AI Act enforcement trajectory.
Stress conditions across GPU supply disruption, EU AI Act enforcement acceleration, and open-source model capability advancement were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about infrastructure scaling and regulatory implementation pacing. Quarterly review of hyperscaler capex guidance and EU member state enforcement actions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Japan Edge AI Market
Artificial Intelligence (AI)
Computer Vision Market
Artificial Intelligence (AI)
Global AI Training Dataset Market
Artificial Intelligence (AI)
Emotion AI Software Market
Artificial Intelligence (AI)
MENA Artificial Intelligence Market
Artificial Intelligence (AI)
Far-Field Speech and Voice Recognition Market
Artificial Intelligence (AI)
GCC Artificial Intelligence Market
Artificial Intelligence (AI)
Global AI in Telecommunication Market
Artificial Intelligence (AI)
AI Mirror Market
Artificial Intelligence (AI)
Semantic Web Market
Artificial Intelligence (AI)
AI Demand Forecasting Software Market
Artificial Intelligence (AI)
Context Aware Computing Market
Artificial Intelligence (AI)
Global Natural Language Generation (NLG) Market
Artificial Intelligence (AI)
Artificial Intelligence in Supply Chain Management Market
Artificial Intelligence (AI)
Cloud Computing Artificial Intelligence (AI) Market
Artificial Intelligence (AI)
Global Deep Learning Neural Networks (Dnns) Market