
 Armored Vehicle Navigation Systems Market | 2026-2036
Armored Vehicle Navigation Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Armored Vehicle Navigation Systems Market Outlook
The gap between premium multi-sensor navigation suites and commodity GPS receivers is consolidating around anti-jamming resilience and battlefield survivability specifications. BAE Systems plc leverages deep integration with UK and US defense platforms to sustain long-term program capture. Safran SA anchors European sovereign navigation capabilities through its hybrid INS-GPS architectures for armored vehicles.
Armored vehicle navigation systems integrate inertial measurement units, satellite receivers, and terrain-mapping sensors to deliver continuous position data in GPS-contested environments; these systems typically achieve accuracy within ten meters circular error probable even during electronic warfare conditions. INS product types command the highest engineering margins due to their role in denied-navigation scenarios, while Lidar segments are gaining traction for obstacle detection in autonomous ground vehicle trials. Military end users dominate installed base volumes, though private security operators are emerging as a discrete demand channel for retrofit-grade portable installations.
FAA certification standards for embedded avionics-grade components and NATO STANAG interoperability protocols shape supplier qualification requirements across allied defense markets. The US Department of Defense's PNT resiliency directives and EU defense fund localization mandates are tightening supply chain access for non-domestic component vendors. Stakeholders must monitor evolving electronic warfare threats and corresponding jamming spectrum allocations to align R&D roadmaps with operational doctrine shifts.
Market Dynamics
Electronic warfare threats against GPS infrastructure are forcing defense procurement agencies to restructure navigation system specifications around multi-sensor resilience architectures rather than single-source satellite dependency.
Growth Catalysts
- NATO STANAG interoperability mandates:Allied defense ministries are standardizing navigation interface protocols to enable cross-border equipment integration during joint operations.
- Autonomous ground vehicle programs:Unmanned combat vehicle development pipelines in the United States and Germany are accelerating demand for terrain-mapping Lidar fused with inertial navigation.
- GPS-denied warfare doctrine:Military strategists are rewriting operational requirements to prioritize continuous positioning capability under active electronic attack conditions.
Market Restraints
- Precision gyroscope supply concentration:Ring laser gyro and fiber-optic gyro component manufacturing clusters heavily in specialized defense-industrial zones, creating single-source vulnerability.
- FAA certification timeline friction:Avionics-grade component qualification for embedded navigation systems extends development cycles by 18-36 months.
- High-purity rare earth magnet dependencies:Neodymium and dysprosium inputs for inertial measurement unit cores face price volatility from concentrated upstream mining operations.
Strategic Opportunities
- Retrofit-grade portable installations:Private security contractors operating in contested zones represent an emerging channel for modular navigation suites requiring minimal platform integration.
- INS-Lidar convergence:Hybrid architectures combining inertial navigation with three-dimensional terrain mapping are opening autonomous obstacle-avoidance applications beyond traditional military end uses.
- EU defense fund localization incentives:European sovereign capability mandates are creating procurement preferences for navigation systems with domestic component sourcing above defined thresholds.
Industry Challenges
- Inertial sensor calibration expertise scarcity:Specialized technicians capable of maintaining ring laser gyro alignment tolerances remain concentrated within defense contractor workforces.
- Multi-sensor fusion algorithm validation:Software certification for safety-critical navigation outputs requires extensive field testing against electronic warfare threat libraries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Armored Vehicle Navigation Systems Market |
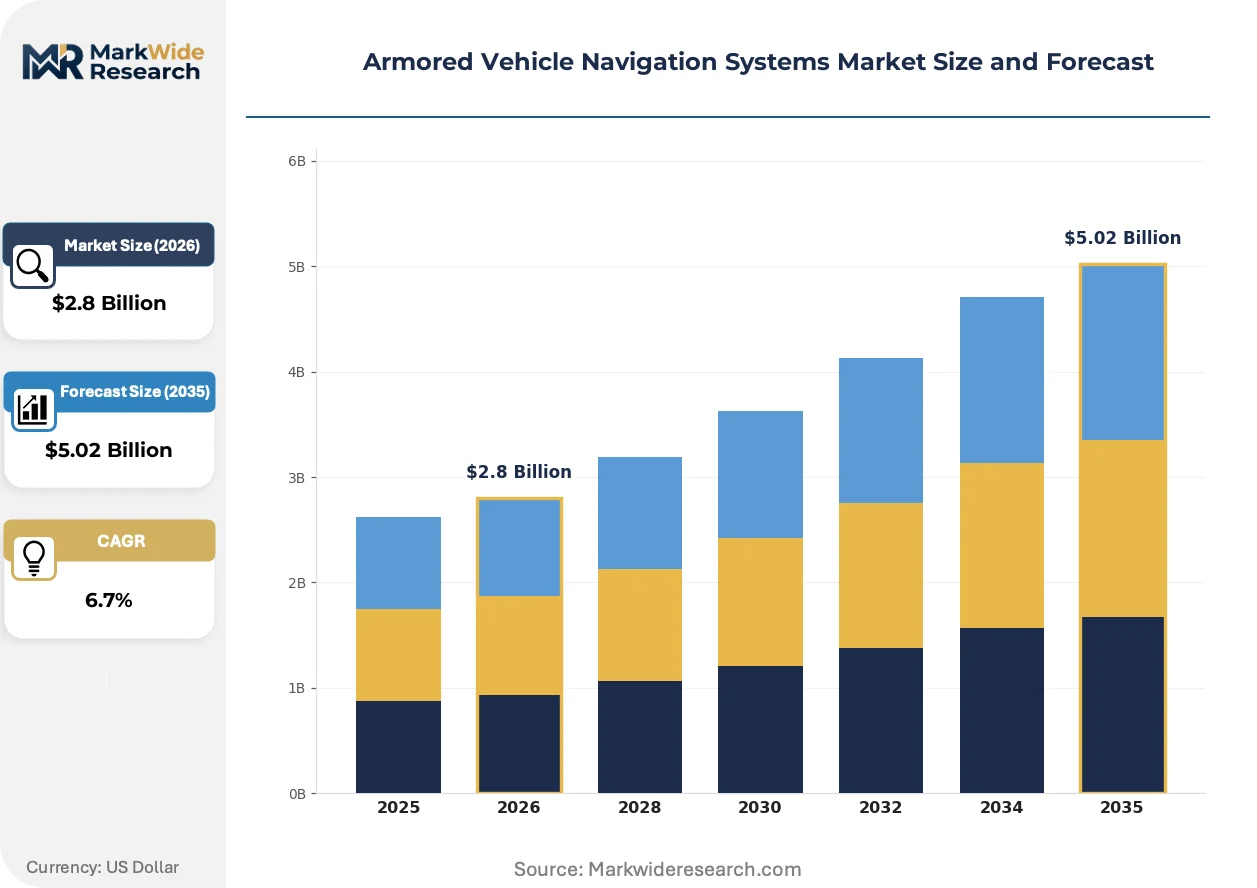
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: GPS, INS, Lidar, Radar Technology: Wireless, Wired, Hybrid, Cloud-based End User: Military, Government, Private Security, Emergency Services Installation Type: Fixed, Mobile, Portable, Integrated |
| Companies Covered | Honeywell International Inc., KVH Industries Inc., BAE Systems plc, RTX Corporation, Safran SA, Thales Group, Northrop Grumman Corporation, Elbit Systems Ltd., Hertz Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Armored Vehicle Navigation Systems Market Strategic Shifts
Navigation system architectures are migrating from federated single-sensor designs toward tightly integrated multi-physics sensor clusters that maintain positioning integrity through active denial environments.
Multi-constellation satellite receivers augmented with anti-jam antenna electronics are absorbing procurement priority across NATO member defense modernization programs. Ground combat vehicle upgrade contracts in the United States and United Kingdom are specifying these enhanced receivers as baseline requirements. The technology is absorbing engineering resources previously allocated to standalone inertial navigation subsystem development.
The US Department of Defense's PNT resiliency directives are mandating redundant positioning sources for all mission-critical ground platforms. These requirements are compressing supplier qualification timelines and elevating anti-spoofing cryptographic standards. Ground vehicle programs are responding by dual-sourcing inertial and celestial navigation backup modalities.
Defense acquisition offices are consolidating navigation system procurement under platform-level integration contracts rather than component-level purchases. Prime contractors are absorbing subsystem vendor relationships through selective sourcing agreements. This pattern is most visible in United States Army ground combat vehicle modernization streams where navigation suites are now specified as integrated mission equipment packages.
Armored Vehicle Navigation Systems Market Segmentation
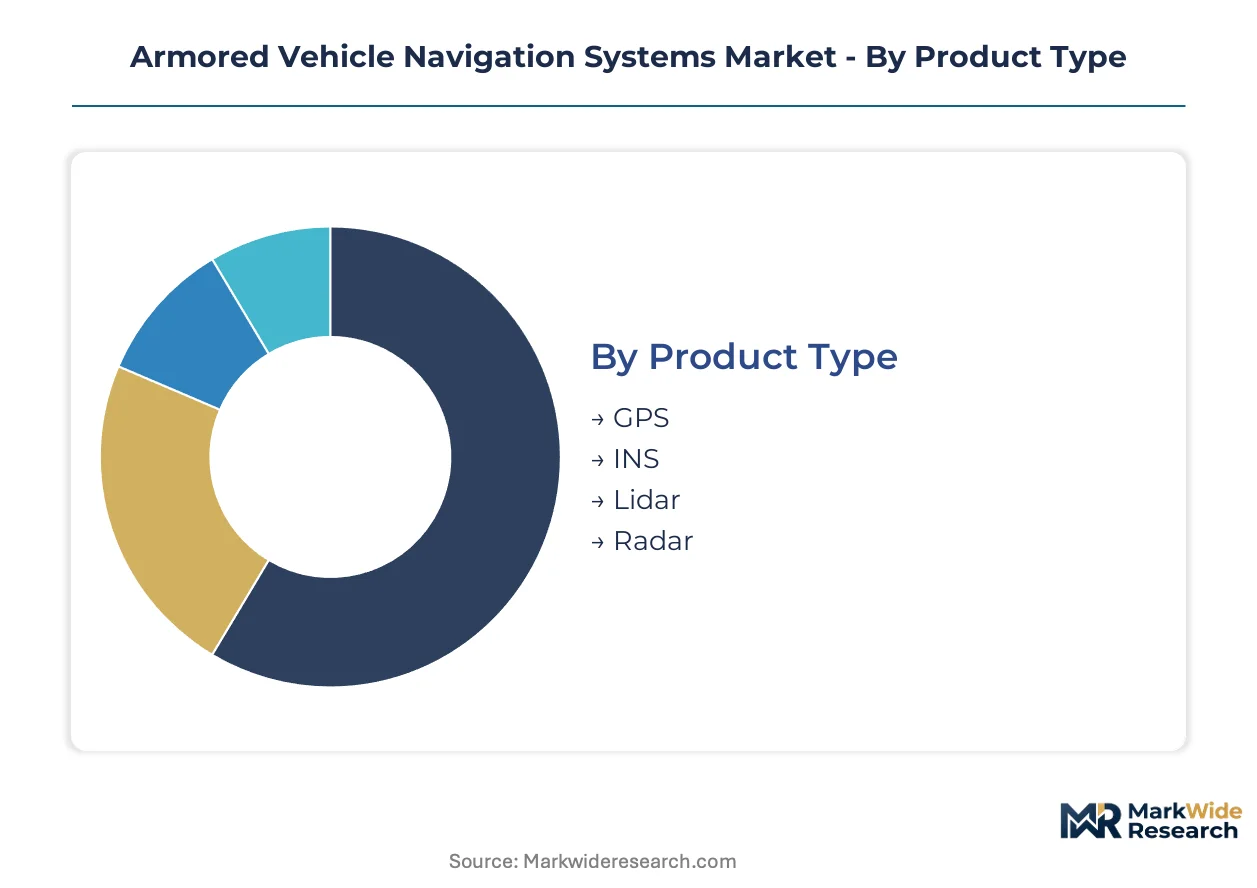
Navigation system procurement decisions in armored vehicles hinge on mission profile, electronic warfare exposure, and platform integration depth. Segment boundaries are blurring as multi-sensor fusion becomes standard, yet discrete categories persist in contract specifications and budget line items.
Product Type:
Defense procurement offices weight anti-jam resilience and denied-environment performance above unit cost when evaluating navigation suites.
- INS:Ring laser and fiber-optic gyro configurations deliver continuous positioning without external signals. United States Army ground combat vehicle retrofits specify INS as mandatory backup for GPS-denied operations.
- GPS:Multi-constellation receivers with anti-jam antenna electronics dominate volume shipments. NATO STANAG interoperability protocols are standardizing receiver interface specifications across allied procurement programs.
- Lidar:Three-dimensional terrain mapping for autonomous obstacle avoidance. German unmanned ground vehicle trials are expanding demand for Lidar-INS fused architectures.
- Radar:Ground-penetrating and foliage-penetrating variants for all-weather navigation. Specialized applications in counter-IED route clearance missions.
Volume sits with GPS; growth tilts toward INS.
Technology:
Platform integration constraints and data security requirements segment procurement between hardened wired backbones and modular wireless upgrades.
- Wired:Shielded copper and fiber-optic datalinks resistant to electromagnetic interference. Fixed installations in main battle tanks prioritize signal integrity over reconfiguration flexibility.
- Hybrid:Wired backbone with wireless edge nodes for sensor augmentation. United Kingdom armored vehicle modernization programs specify hybrid architectures to balance survivability with upgrade paths.
- Wireless:Mesh networking for rapid reconfiguration in expeditionary deployments. Private security contractors favor wireless portable kits for vehicle-agnostic installation.
- Cloud-based:Distributed processing for terrain database updates and mission planning. Limited operational deployment due to contested spectrum vulnerabilities.
Hybrid architectures command the premium tier; wired systems retain the installed base majority.
End User:
Budget authority and operational doctrine divergence create distinct specification profiles across buyer categories.
- Military:Multi-sensor resilience architectures with cryptographic anti-spoofing. United States Department of Defense PNT resiliency directives mandate redundant positioning sources for all mission-critical ground platforms.
- Private Security:Modular retrofit-grade suites requiring minimal platform integration. Contested-zone operators in the Middle East and Africa are absorbing portable navigation system shipments.
- Government:Border patrol and customs enforcement vehicles with intermediate ruggedization requirements. Procurement concentrated through federal fleet modernization programs.
- Emergency Services:Urban search-and-rescue and disaster response vehicles. Cost constraints limit adoption to high-value specialized platforms.
Military buyers anchor revenue; private security is expanding most quickly.
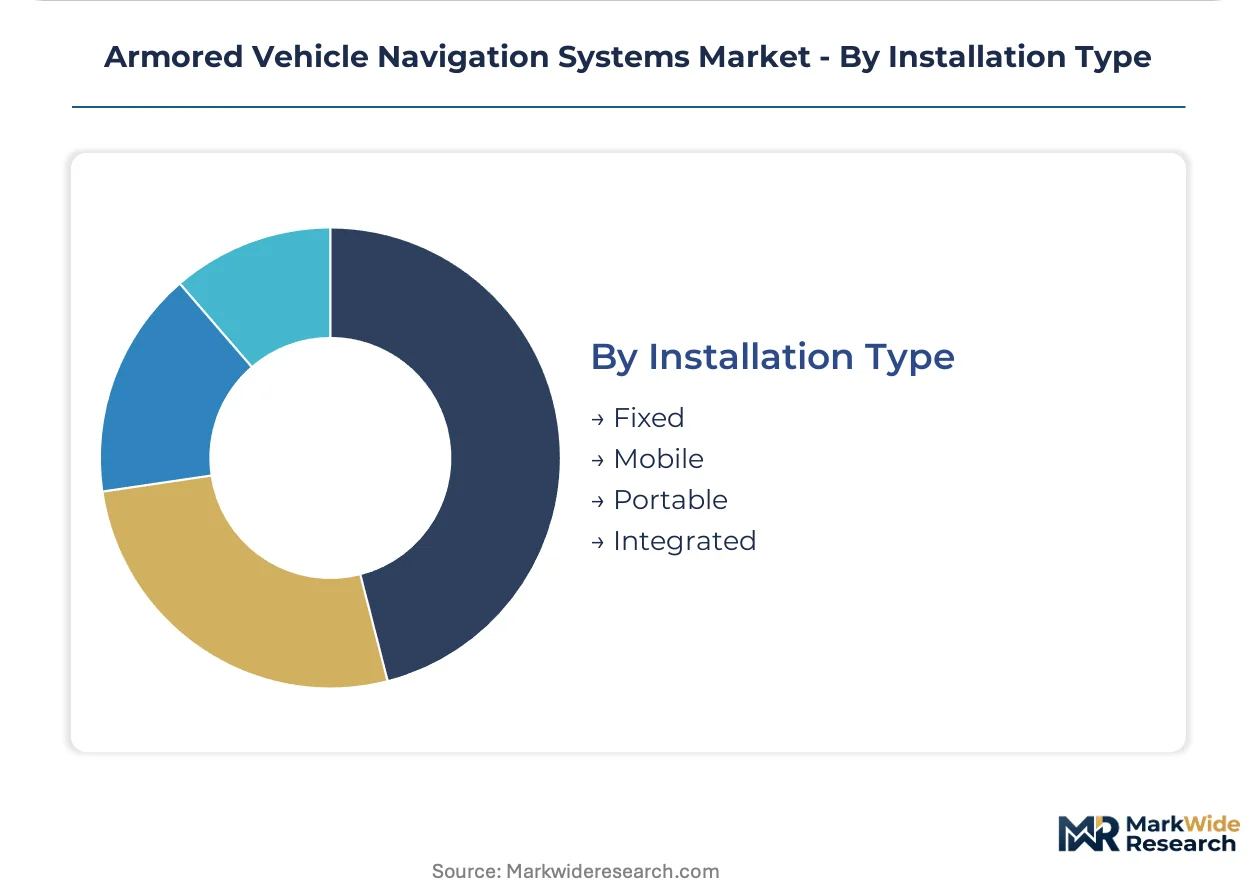
Installation Type:
Platform life cycle stage and mission flexibility requirements determine integration depth preferences.
- Integrated:Factory-installed multi-sensor clusters with dedicated vehicle bus interfaces. New-production armored vehicles in the United States and Germany specify integrated navigation as standard mission equipment.
- Fixed:Permanent mounting with hardwired power and data connections. Upgrade programs for legacy vehicle fleets favor fixed installations to minimize recurring integration costs.
- Portable:Rapid-deployment kits for vehicle-agnostic use. Private security and special operations units prioritize portability for cross-platform flexibility.
- Mobile:Semi-permanent mounting allowing inter-vehicle transfer. Expeditionary logistics units specify mobile installations for fleet management efficiency.
Integrated systems dominate new procurement; portable configurations are gaining share fastest in the retrofit channel.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aberdeen Proving Ground anchors North American defense navigation R&D, hosting the US Army's ground vehicle integration laboratories where multi-sensor fusion architectures undergo field validation.
United States
Pentagon PNT resiliency directives and Army ground combat vehicle modernization pipelines drive multi-sensor suite procurement. FAA certification standards for avionics-grade components extend supplier qualification timelines. The Michigan defense corridor around Detroit hosts prime contractor integration facilities for factory-installed navigation clusters.
Germany
Bundeswehr unmanned ground vehicle trials and NATO STANAG interoperability mandates accelerate INS-Lidar fusion adoption. KBA automotive-grade certification requirements influence military navigation system ruggedization standards. The Bavarian aerospace cluster around Munich concentrates fiber-optic gyro component engineering talent.
United Kingdom
Ministry of Defence armored vehicle upgrade programs specify hybrid wired-wireless architectures for reconfiguration flexibility. UK defense export control regulations shape technology transfer protocols for navigation subsystems. The South West England cluster around Bristol houses BAE Systems navigation integration facilities.
Israel
Israel Defense Forces GPS-denied warfare doctrine prioritizes redundant inertial backup modalities for ground platforms. Israeli Ministry of Defense localization mandates restrict foreign component access in sensitive navigation systems. The Tel Aviv metropolitan corridor concentrates algorithm development for multi-sensor fusion software.
France
Direction Générale de l'Armement procurement incentives favor domestic hybrid INS-GPS architectures for armored vehicles. EU defense fund localization thresholds create procurement preferences for European-sourced navigation components. The Paris-Saclay technology cluster hosts Safran's inertial navigation R&D facilities.
Armored Vehicle Navigation Systems Market Competitive Environment
Premium-margin players sit above commodity-margin players across anti-jam resilience and battlefield survivability specifications. The vendor base organizes into three tiers: integrated platform primes absorbing subsystem vendors, specialized inertial sensor houses, and modular retrofit kit suppliers. Consolidation pressure intensifies as defense acquisition offices shift from component-level to platform-level procurement contracts. Prime contractors deploy selective sourcing agreements to capture long-term program revenue streams.
Within the integrated platform tier, BAE Systems plc and RTX Corporation exemplify prime contractor archetypes leveraging deep defense platform relationships. Safran SA and Thales Group anchor European sovereign navigation capabilities through hybrid architecture specialization. Honeywell International Inc. occupies a position spanning commercial avionics heritage and military navigation applications.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| KVH Industries Inc. |
| BAE Systems plc |
| RTX Corporation |
| Safran SA |
| Thales Group |
| Northrop Grumman Corporation |
| Elbit Systems Ltd. |
| Hertz Systems |
| Others |
Value Chain & Pricing Dynamics
Captive in-house production of ring laser gyro and fiber-optic gyro components by prime contractors like BAE Systems and RTX Corporation anchors supply positions while supporting premium pricing power for integrated navigation suites. This vertical control over critical inertial sensor manufacturing insulates these vendors from rare earth magnet price volatility and concentrates margin capture at the platform level.
Pricing Analysis
Outcome-based pricing tied to mission-readiness uptime and GPS-denied navigation assurance anchors contract values for military procurement. Three-tier pricing structure across premium multi-sensor resilience suites, standard anti-jam GPS configurations, and economy-grade portable retrofit kits reflects certification grade and battlefield survivability specifications. Cost compression in the portable retrofit tier is intensifying because private security contractors prioritize vehicle-agnostic flexibility over integrated performance. Military end users demonstrate lowest price sensitivity due to operational doctrine mandates, while emergency services buyers face budget constraints limiting adoption.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale defense procurement demand from United States Army and Bundeswehr modernization programs, bypassing distribution intermediaries for integrated platform contracts. Manufacturing concentrates in the United States, Germany, and France for precision gyroscope fabrication, while rare earth magnet sourcing draws from concentrated upstream mining operations in China and Australia. Single-source vulnerability in high-purity neodymium and dysprosium inputs creates supply chain risk for inertial measurement unit production. Distribution runs through prime contractor integration facilities for factory-installed systems, with modular kit suppliers serving private security retrofit demand via specialized defense distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized inertial sensor calibration expertise scarcity props pricing for maintenance and upgrade services, constraining capacity expansion across NATO defense industrial bases. This bottleneck sustains margin premiums for incumbent vendors with captive technician workforces.
For Market Incumbents: Lock in long-term platform integration contracts with United States Army and UK Ministry of Defence to defend against emerging modular retrofit competitors. Deepen backward integration into fiber-optic gyro component manufacturing to reduce rare earth magnet supply exposure. Capture recurring revenue through selective sourcing agreements that absorb subsystem vendor relationships and control navigation suite specification authority. For New Entrants and Emerging Players: Begin with private security contractor demand in Middle East and African contested zones, where portable navigation kit requirements favor rapid-deployment flexibility over integrated performance. Target modular retrofit-grade architectures requiring minimal vehicle bus integration as the most penetrable entry segment. Pursue wireless mesh networking form factors as a differentiated go-to-market angle for expeditionary logistics and special operations units. For Investors and Strategic Acquirers: Exit pathways concentrate in prime contractor acquisition of specialized inertial sensor houses to secure calibration expertise and ring laser gyro manufacturing capacity. Long-term viability favors vendors with NATO STANAG certification credentials and established defense platform integration relationships. Monitor Bundeswehr unmanned ground vehicle trial outcomes as an inflection indicator for INS-Lidar fusion architecture adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Sensor Fusion Architecture Development | BAE Systems and Safran SA anchor European sovereign navigation capabilities through hybrid INS-GPS integration. |
| Anti-Jam Antenna Electronics Integration | United States Army ground combat vehicle retrofits specify enhanced receivers as baseline mission requirements. |
| Portable Retrofit Kit Expansion | Private security contractors in contested zones absorb modular navigation suites for vehicle-agnostic deployment. |
| Rare Earth Magnet Supply Securement | Neodymium and dysprosium price volatility from concentrated mining operations threatens IMU production economics. |
| Calibration Expertise Workforce Development | Ring laser gyro alignment technician scarcity limits maintenance capacity across NATO defense industrial bases. |
Study Parameters
Defense procurement databases, NATO STANAG interoperability protocol documentation, and United States Department of Defense PNT resiliency directive filings formed the secondary backbone for market sizing and technology trend identification. Primary interviews with ground vehicle platform engineers, inertial navigation system procurement officers at defense ministries, aftermarket service heads at prime contractors, and private security contractor operations directors validated demand assumptions and pricing dynamics. Bottom-up triangulation across product type shipments and top-down cross-check against defense budget line items ensured segmentation accuracy.
Historical trendline analysis of military navigation system procurement across the analysis window established baseline growth patterns for projection modeling. The analytical framework segmented volume and value outputs by product type, technology architecture, end user category, and installation depth, with regional production cluster and regulatory framework as additional dimensions. CAGRs were derived through regression analysis of defense modernization pipeline commitments and autonomous vehicle program development timelines. Electronic warfare threat evolution and corresponding jamming spectrum allocations served as critical forecast inputs for GPS-denied capability demand.
Underlying measurement precision varies by segment; integrated multi-sensor suites and military end user procurement carry tighter precision than portable retrofit configurations and private security demand. Forecasts reflect assumptions around NATO defense spending continuity, rare earth supply chain stability, and FAA certification timeline consistency for avionics-grade components. Periodic stress-testing of base assumptions is recommended given electronic warfare doctrine evolution and EU defense fund localization mandate implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Armored Vehicles
Middle-East and Africa Armored Vehicles Market
Armored Vehicles
Armored Vehicle Fire Suppression Systems Market
Armored Vehicles
Armored Vehicles Upgrade and Retrofit Market
Armored Vehicles
Asia-Pacific Armored Fighting Vehicles Market
Armored Vehicles
Europe Armored Fighting Vehicles Market
Armored Vehicles
US Armored Vehicle Market
Armored Vehicles
Armored Vehicle Procurement and Upgrade Market
Armored Vehicles
Armored Personnel Carrier Market
Armored Vehicles
Boom Arms Market
Armored Vehicles
Armored Fighting Vehicles Market
Armored Vehicles
Armoured Personnel Carrier (APC) Market
Armored Vehicles
Armored Vehicles Market
Armored Vehicles
Armor Protection Systems Market
Armored Vehicles
Global Ceramic Armor Market
Armored Vehicles
Military Armored Car Market
Armored Vehicles
North America Armored Fighting Vehicles Market