
 US Armored Vehicle Market | 2026-2036
US Armored Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
US Armored Vehicle Market Insights
Performance-based logistics contracting is shifting how armored vehicle capabilities reach operators. General Dynamics Land Systems leverages its integrated supply chain to sustain long-term fleet readiness contracts. BAE Systems anchors its position through specialized survivability engineering for ground combat platforms. Oshkosh Defense competes aggressively in tactical wheeled vehicle segments with modular payload architectures.
US armored vehicles integrate steel-ceramic composite armor, V-hull blast-deflecting geometries, and 600-horsepower turbocharged diesel powertrains to protect crews against kinetic and improvised explosive threats across contested operational environments. Combat vehicles dominate procurement budgets as the Army pursues Optionally Manned Fighting Vehicle replacements, while mine-resistant platforms retain priority in counter-IED force protection missions. Transportation vehicles occupy stable demand channels through medium and heavy tactical truck refresh cycles.
FAA coordination governs air-transportability certification for rapid-deployment armored units, while NHTSA commercial truck safety standards influence tactical wheeled vehicle braking and lighting systems. The Department of Defense MIL-STD-461 electromagnetic interference requirements shape electronics hardening investments across all platforms. Stakeholders must track how Army Futures Command requirements for optionally manned and electric-drive prototypes reshape supplier qualification criteria.
Market Dynamics
Army Futures Command requirements for optionally manned and electric-drive prototypes are restructuring supplier qualification criteria, forcing defense contractors to retool engineering capabilities around software-defined architectures and modular powertrain systems.
Growth Catalysts
- MIL-STD-810H Environmental Testing:The Department of Defense standard mandates survivability against extreme temperatures, vibration, and humidity, accelerating platform hardening investments across all vehicle categories.
- Counter-IED Force Protection Missions:Mine-resistant ambush-protected platforms retain procurement priority as asymmetric threats persist in contested operational theaters, sustaining demand for blast-deflecting hull geometries.
- Steel-Ceramic Composite Armor:Advanced material layering delivers superior kinetic protection at reduced weight compared to homogeneous steel, enabling air-transportability without sacrificing crew survivability.
Market Restraints
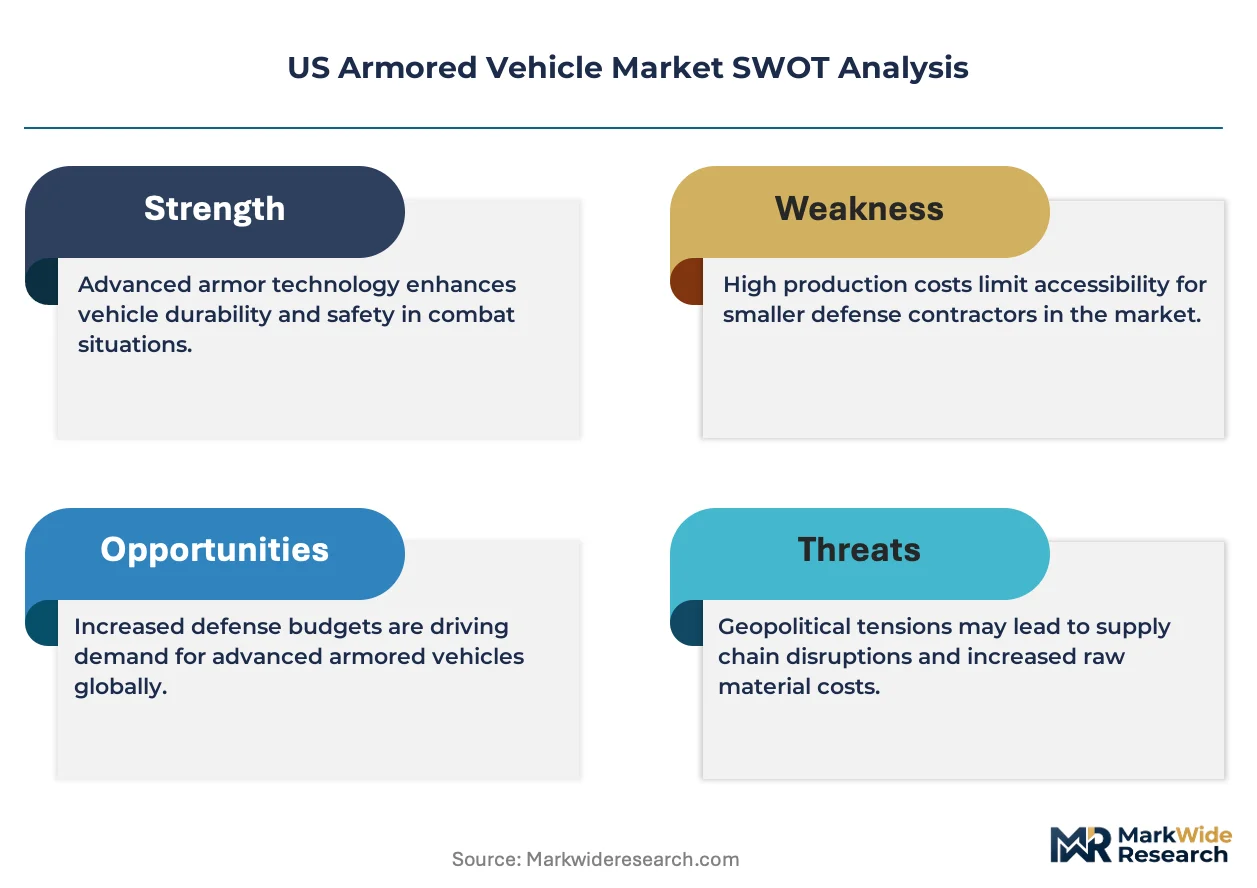
- Titanium and Rare Earth Input Volatility:Armor-grade titanium plate and neodymium magnet supplies face price instability, compressing margins on electric-drive prototype development programs.
- Single-Source Powertrain Dependency:Heavy-duty turbocharged diesel engine production concentrates among three domestic manufacturers, creating vulnerability in surge procurement scenarios.
- Electromagnetic Hardening Complexity:MIL-STD-461 compliance for electronics shielding adds non-recurring engineering costs that smaller subsystem vendors struggle to absorb.
Strategic Opportunities
- Texas Defense Manufacturing Corridor:Army Futures Command headquarters in Austin anchors a supplier ecosystem spanning El Paso armored vehicle final assembly and Houston-area composite materials production.
- Performance-Based Logistics Contracts:Long-term fleet readiness agreements shift revenue from transactional spare parts to availability guarantees, locking in decade-long supplier relationships.
- Hybrid-Electric Drive Convergence:Integration of lithium-ion battery packs with 600-horsepower diesel architectures enables silent watch capability and reduced thermal signature for reconnaissance variants.
Industry Challenges
- Embedded Software Talent Scarcity:Vehicle control systems require cybersecurity-cleared programmers proficient in real-time operating systems, a skill set concentrated among civilian technology firms with limited defense clearance pipelines.
- FAA Air-Transportability Certification Timelines:Rapid-deployment requirements demand concurrent engineering with federal aviation regulators, compressing development schedules for C-17 and C-5 transport compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Armored Vehicle Market |
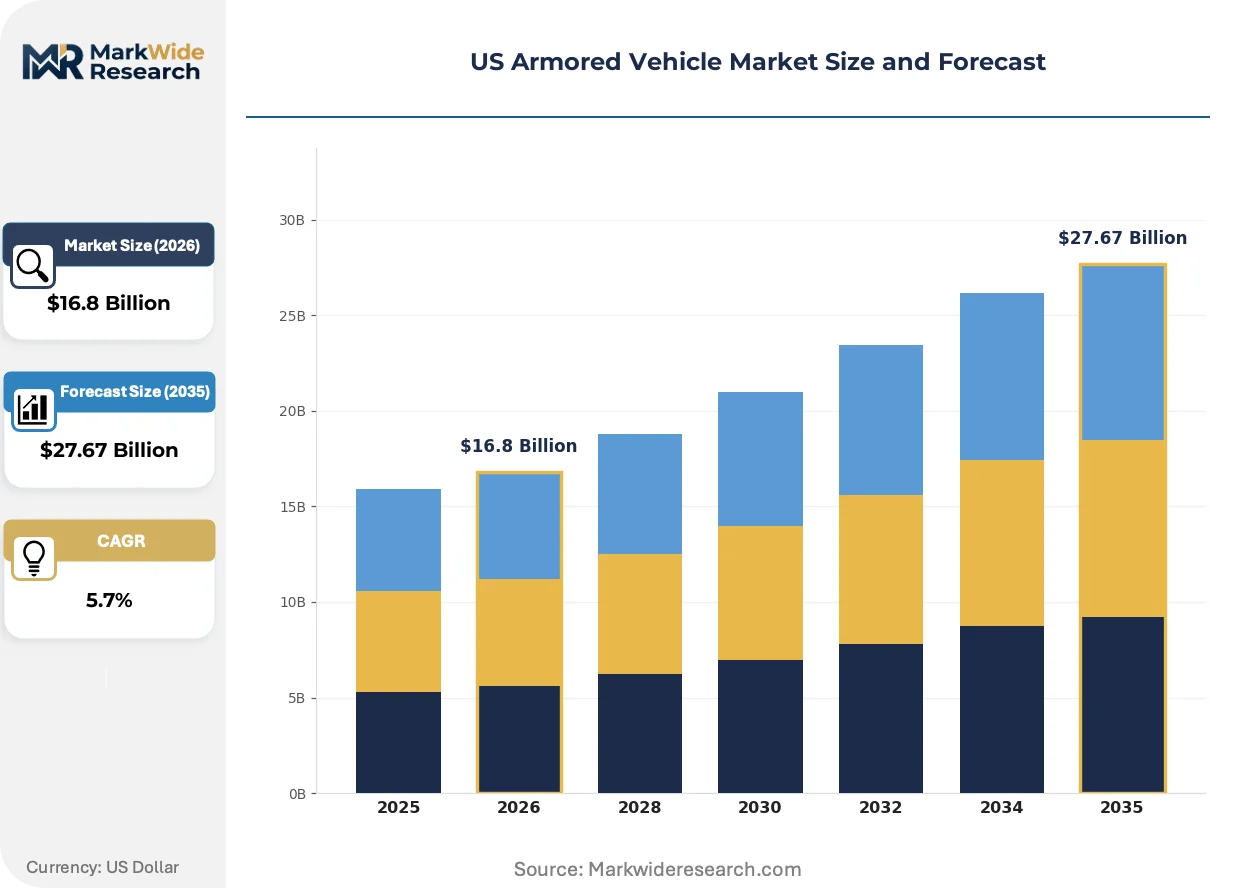
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $27.67 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Combat Vehicles, Transportation Vehicles, Reconnaissance Vehicles, Support Vehicles End User: Military, Law Enforcement, Private Security, Government Agencies Technology: Ballistic Protection, Electromagnetic Protection, Mine-Resistant, Hybrid Technology Application: Surveillance, Combat Operations, Peacekeeping Missions, Civil Disturbance Management |
| Companies Covered | General Dynamics Land Systems, Oshkosh Defense, BAE Systems, Lockheed Martin, Navistar Defense, Textron Systems, AM General, Lenco Industries, Northrop Grumman, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Armored Vehicle Market Trends and Innovations
Software-defined vehicle architectures are displacing hardware-centric platform designs, enabling over-the-air capability upgrades and reducing physical modification costs across multi-decade fleet lifecycles.
Modular open systems architecture is consolidating proprietary subsystem integration around standardized data buses and power interfaces. Army program offices now mandate non-proprietary middleware for all new vehicle competitions, compressing vendor lock-in advantages that historically protected incumbent suppliers. This standardization is consolidating competitive differentiation around software integration speed rather than hardware exclusivity.
NHTSA commercial truck safety standards are extending into tactical wheeled vehicle braking and lighting system requirements. The regulatory convergence forces defense contractors to dual-certify platforms for both military and limited civilian highway operation, adding validation costs but enabling domestic training and logistics flexibility. Medium tactical truck segments face the steepest compliance burden under this framework.
Army acquisition commands are bundling sensor payload integration with base vehicle procurement rather than treating them as separate line items. This behavior compresses traditional prime-subcontractor boundaries, requiring chassis manufacturers to absorb electro-optical and signals intelligence system liability. The shift is most visible in armored reconnaissance vehicle competitions where sensor suite performance dominates source selection criteria.
US Armored Vehicle Market Segmentation
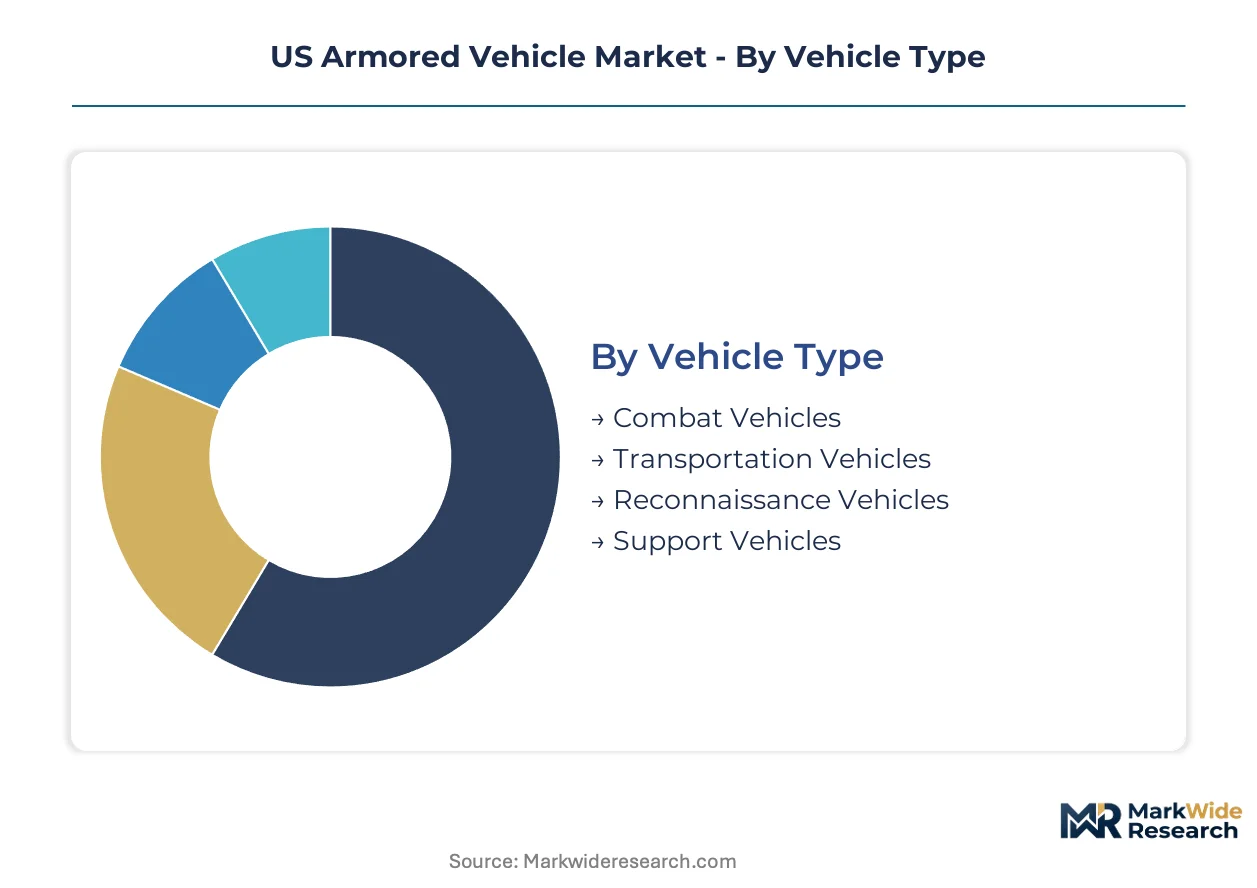
Segmentation in the US armored vehicle market reveals how procurement priorities split across mission requirements and threat environments. Defense contractors configure platform architectures differently for kinetic combat versus stability operations, with technology choices directly determining unit economics and supplier qualification pathways.
Vehicle Type:
Capital intensity varies sharply across vehicle categories, with combat platforms demanding the heaviest upfront engineering investment in armor integration and weapons system hardening.
- Combat Vehicles:Steel-ceramic composite armor and 600-horsepower turbocharged diesel powertrains define these platforms. Army Futures Command in Austin, Texas, directs Optionally Manned Fighting Vehicle development, concentrating procurement decisions in the state while mandating software-defined architectures for next-generation fleet replacements.
- Transportation Vehicles:Medium and heavy tactical trucks with modular payload systems sustain logistics networks. NHTSA braking and lighting standards apply to these platforms, requiring dual-certification that adds validation costs but enables domestic highway operation for training and rapid deployment.
- Reconnaissance Vehicles:Sensor-integrated platforms with reduced thermal signatures.
- Support Vehicles:Maintenance and recovery variants with specialized crane and winch configurations.
Most installed capacity flows through Transportation Vehicles. Expansion is steepest in Combat Vehicles.
End User:
Customer concentration shapes contracting mechanisms, with volume buyers commanding performance-based logistics agreements that lock in decade-long supplier relationships.
- Military:The Department of Defense dominates procurement through Army Futures Command modernization programs. MIL-STD-810H environmental testing and MIL-STD-461 electromagnetic hardening requirements filter vendor participation, compressing the qualified supplier base for major platform competitions.
- Law Enforcement:State and municipal agencies acquire mine-resistant platforms for counter-IED and civil disturbance scenarios. Procurement concentrates in Texas border counties and southwestern jurisdictions facing asymmetric threat environments, with funding flowing through Department of Homeland Security grant programs.
- Private Security:Corporate and diplomatic protection services.
- Government Agencies:Federal civilian departments with protective mission requirements.
Military contracts absorb the majority of production capacity. Law Enforcement represents the fastest-growing customer segment as domestic security priorities shift.
Technology:
Technology selection determines supply chain exposure, with rare earth and titanium inputs creating margin vulnerability for advanced protection systems.
- Ballistic Protection:Steel-ceramic composite layering delivers kinetic threat survivability at reduced weight versus homogeneous steel. Texas-based composite materials producers in the Houston corridor supply armor components, anchoring a regional manufacturing cluster that supports final assembly operations in El Paso.
- Mine-Resistant:V-hull blast-deflecting geometries protect crews against improvised explosive devices. Counter-IED force protection missions sustain demand for these platforms across contested operational theaters, with procurement priority reflecting persistent asymmetric threat environments.
- Electromagnetic Protection:MIL-STD-461 compliance for electronics shielding.
- Hybrid Technology:Lithium-ion battery integration with diesel architectures for silent watch capability.
Ballistic Protection systems occupy the largest installed base. Hybrid Technology is climbing the fastest as electric-drive prototypes advance through Army evaluation.
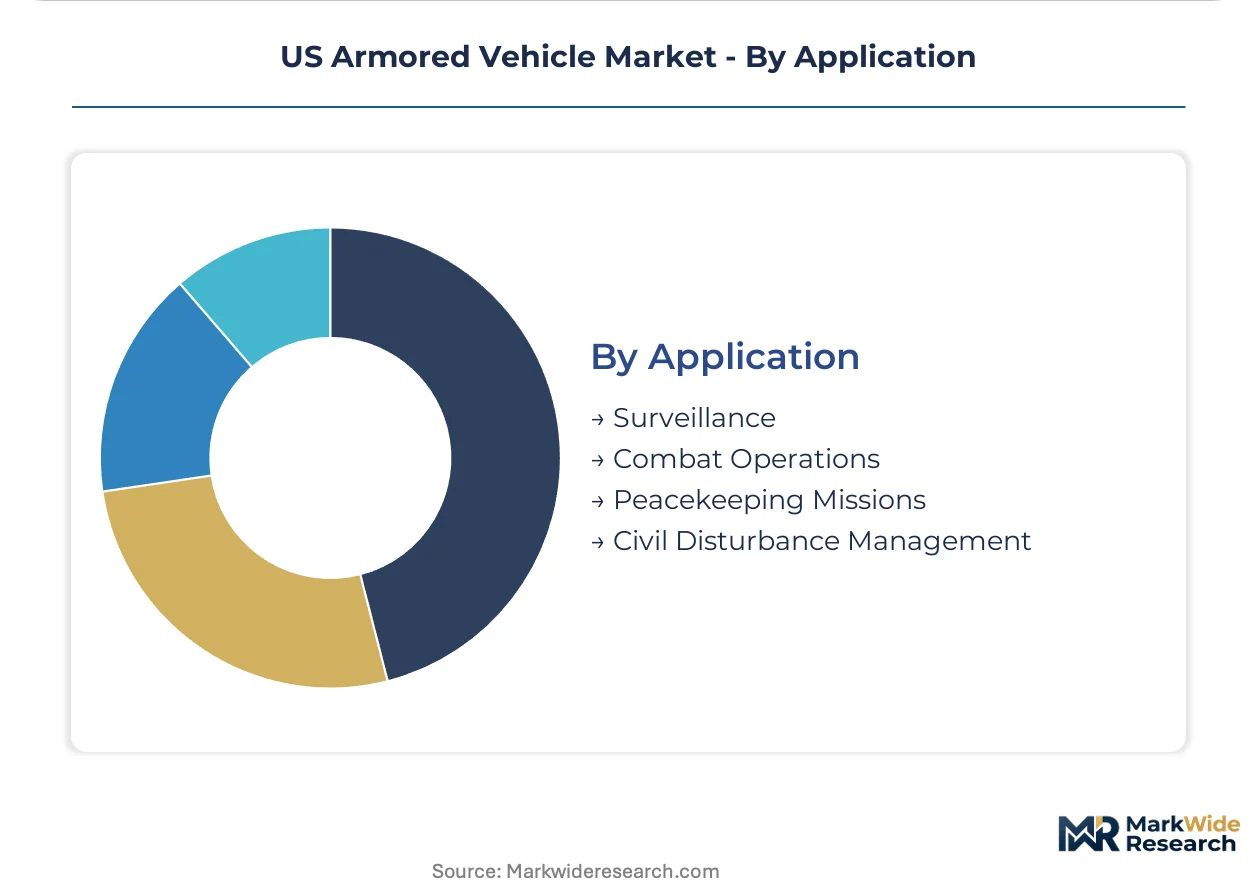
Application:
Mission type dictates platform configuration, with surveillance applications driving sensor integration requirements that blur traditional prime-subcontractor boundaries.
- Combat Operations:Full-spectrum warfare platforms integrating active protection systems and networked lethality. Army procurement bundles sensor payloads with base vehicle contracts, requiring chassis manufacturers to absorb electro-optical system liability and compressing traditional supplier boundaries.
- Surveillance:Reconnaissance variants with signals intelligence and electro-optical suites. FAA air-transportability certification governs rapid-deployment requirements for these units, demanding concurrent engineering with federal regulators that compresses C-17 and C-5 compatibility development schedules.
- Peacekeeping Missions:Stability operations with reduced weapons configurations.
- Civil Disturbance Management:Law enforcement and National Guard riot control platforms.
Combat Operations absorbs the majority of platform investment. Surveillance is gaining share fastest as sensor-centric warfare reshapes requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada maintains mine-resistant platform production for coalition force commitments, while Mexico concentrates on armored personnel carriers for domestic security operations. Both nations reference US MIL-STD specifications for interoperability, though procurement volumes diverge sharply.
Texas
Army Futures Command headquarters in Austin drives next-generation vehicle requirements for Optionally Manned Fighting Vehicle programs. MIL-STD-810H environmental testing standards filter vendor participation for major platform competitions. The El Paso-Houston corridor anchors final assembly operations and composite materials production for steel-ceramic armor systems.
Michigan
Automotive manufacturing infrastructure supports armored vehicle powertrain and chassis component supply. NHTSA commercial truck safety standards influence tactical wheeled vehicle braking system designs for dual military-civilian certification. Detroit-area engineering talent pools feed embedded software development for vehicle control architectures.
Virginia
Department of Defense procurement commands in Arlington shape contract specifications for electromagnetic hardening requirements under MIL-STD-461. Northern Virginia cybersecurity firms supply cleared personnel for software-defined vehicle development. The Pentagon's proximity accelerates requirements feedback loops between operators and contractors.
Wisconsin
Tactical wheeled vehicle manufacturing concentrates around Oshkosh for medium and heavy truck platforms. FAA air-transportability certification coordination occurs through concurrent engineering with federal regulators. Regional supply chains support modular payload architectures for rapid reconfiguration between mission profiles.
California
Silicon Valley technology firms contribute sensor integration and autonomous navigation capabilities for reconnaissance variants. Defense contractors absorb electro-optical system liability under bundled procurement structures. Southern California aerospace clusters support C-17 and C-5 transport compatibility engineering for rapid-deployment units.
US Armored Vehicle Market Competitive Landscape
Top-tier vendors anchor prime contracting positions for major platform competitions, while mid-tier specialists concentrate on subsystem integration and survivability engineering. The market structure reflects consolidated final assembly capacity alongside fragmented component supply. Three archetypes dominate: diversified defense conglomerates with integrated supply chains, specialized ground combat platform engineers, and tactical wheeled vehicle modular architects. Competitive moves center on performance-based logistics contracting for decade-long fleet readiness agreements and retooling around software-defined architectures for electric-drive prototypes.
Within the diversified defense conglomerate tier, General Dynamics Land Systems and Lockheed Martin occupy positions defined by integrated supply chain control and broad platform portfolios. BAE Systems exemplifies the specialized survivability engineering archetype, anchoring competitive differentiation around hardened ground combat systems. Oshkosh Defense sits within the tactical wheeled vehicle segment, representing modular payload architecture capabilities for medium and heavy truck refresh cycles. These three company structures illustrate how vendor positioning aligns with Army Futures Command procurement priorities.
| Leading Market Players |
|---|
| General Dynamics Land Systems |
| Oshkosh Defense |
| BAE Systems |
| Lockheed Martin |
| Navistar Defense |
| Textron Systems |
| AM General |
| Lenco Industries |
| Northrop Grumman |
| Others |
Pricing and Supply Chain Analysis
Army Futures Command requirements for optionally manned and electric-drive prototypes are forcing defense contractors to absorb non-recurring engineering costs for software-defined architectures, compressing margins on fixed-price development contracts while concentrating pricing power among titanium and rare-earth suppliers with qualified defense production capacity.
Pricing Analysis
Capacity additions in Texas are reshaping price floors for steel-ceramic composite armor systems as Houston-area composite materials producers expand output to serve El Paso final assembly operations. Three-tier pricing structure across MIL-STD-810H certified, commercially adapted, and law enforcement variants separates defense-grade platforms from domestic security procurement. Cost compression in electric-drive prototype development is intensifying because titanium plate and neodymium magnet supplies face price instability. Law enforcement agencies exhibit highest price sensitivity due to Department of Homeland Security grant funding constraints, while military buyers prioritize performance guarantees over unit cost.
Supply Chain Analysis
Direct-to-Army contracting channels handle major platform competitions, with prime contractors managing tiered subcontractor networks for survivability engineering and powertrain integration. Geographic supply concentration centers on the United States for final assembly and heavy-duty diesel engines, with titanium feedstock drawing from domestic and allied sources. Armor-grade titanium plate, neodymium magnets for electric drives, and lithium-ion battery cells constitute critical input dependencies. Single-source powertrain vulnerability among three domestic engine manufacturers creates surge procurement risk. Distribution runs through performance-based logistics contracts that lock in decade-long supplier relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MIL-STD-810H environmental testing mandates function as a regulatory compounder, elevating survivability requirements that sustain platform hardening investments across all vehicle categories and filtering vendor participation for major competitions.
For Market Incumbents: Extend performance-based logistics contracting advantages by deepening software integration capabilities around optionally manned architectures. Absorb electro-optical system liability under bundled procurement structures to compress prime-subcontractor boundaries. Anchor competitive differentiation in Army Futures Command qualification pathways before electric-drive prototype supplier criteria solidify.
For New Entrants and Emerging Players: Begin with law enforcement mine-resistant platform segments in Texas border counties and southwestern jurisdictions where Department of Homeland Security grant funding sustains procurement momentum. Target civil disturbance management variants as the most penetrable application where National Guard requirements overlap with municipal security priorities. Pursue NHTSA dual-certification pathways to enable domestic highway operation for training flexibility.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized survivability engineering firms holding MIL-STD-461 electromagnetic hardening capabilities and cleared software talent pipelines. Long-term viability rests on positioning for decade-long fleet readiness agreements rather than transactional spare parts revenue. Watch Army Futures Command prototype downselect decisions as the inflection indicator for supplier qualification consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Performance-Based Logistics Contract Expansion | Locks in decade-long supplier relationships with Army and Marine Corps fleet readiness programs. |
| Software-Defined Vehicle Architecture Investment | Enables over-the-air capability upgrades for Optionally Manned Fighting Vehicle competitions. |
| Texas Defense Manufacturing Corridor Presence | Positions suppliers within Army Futures Command requirement development and El Paso final assembly. |
| Hybrid-Electric Drive Prototype Development | Addresses silent watch capability requirements for reconnaissance variants under Army evaluation. |
| MIL-STD-461 Electromagnetic Hardening Certification | Filters vendor participation for electronics shielding compliance across all platform categories. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with Army program office acquisition leads, defense contractor platform engineers, composite materials procurement managers, and performance-based logistics contract administrators with secondary validation. Defense budget justification documents, MIL-STD specification filings, FAA air-transportability certification records, and NHTSA commercial truck safety standard dockets anchored secondary source triangulation. Bottom-up platform production estimates and top-down defense procurement budget allocations were cross-referenced for convergence.
Historical reference periods spanning defense modernization cycles anchored the forecast window, with analytical frameworks modeling vehicle type, end user, technology, and application dimensions across the projection horizon. CAGRs were derived from procurement budget trajectory analysis and platform replacement schedule alignment. Army Futures Command prototype development timelines and electric-drive technology maturation curves served as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including classified program budgets, emergency supplemental appropriations for contingency operations, and rapid technology insertions outside standard acquisition pathways. Forecasts reflect assumptions about sustained defense modernization funding and titanium supply chain stability. Periodic stress-testing of base assumptions is recommended given electromagnetic hardening complexity and embedded software talent scarcity risks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Armored Vehicles
Armored Vehicle Fire Suppression Systems Market
Armored Vehicles
Military Armored Car Market
Armored Vehicles
Armored Vehicles Upgrade and Retrofit Market
Armored Vehicles
Armored Fighting Vehicles Market
Armored Vehicles
Armor Protection Systems Market
Armored Vehicles
Armored Vehicles Market
Armored Vehicles
Asia-Pacific Armored Fighting Vehicles Market
Armored Vehicles
Armored Personnel Carrier Market
Armored Vehicles
Middle-East and Africa Armored Vehicles Market
Armored Vehicles
Armored Vehicle Procurement and Upgrade Market
Armored Vehicles
Boom Arms Market
Armored Vehicles
Armored Vehicle Navigation Systems Market
Armored Vehicles
Armoured Personnel Carrier (APC) Market
Armored Vehicles
Global Ceramic Armor Market
Armored Vehicles
Europe Armored Fighting Vehicles Market
Armored Vehicles
North America Armored Fighting Vehicles Market