
 Armored Vehicles Market | 2026-2036
Armored Vehicles Market Size, Share, and Industry Trends Forecast 2026-2036
Armored Vehicles Market Intelligence
Defense leasing and government-backed project finance is reconfiguring capital deployment across the armored vehicle sector, enabling smaller sovereign buyers to access heavy platforms without upfront procurement burdens. Oshkosh Corporation leverages its established position in tactical wheeled vehicles to sustain North American supply commitments. Rheinmetall AG anchors European land-systems manufacturing through integrated propulsion and armor development. BAE Systems differentiates via naval-to-land technology transfer and long-term through-life support contracts.
Armored vehicles are ground mobility platforms engineered with hardened steel or composite armor arrays, typically rated to STANAG 4569 ballistic and blast protection levels, designed to transport personnel and materiel through contested environments. Combat vehicles occupy the highest value tier due to turret integration and active protection system complexity, while cash-in-transit vehicles represent a mature, price-competitive segment driven by private banking logistics. Personnel carriers compete on modular armor packages and rapid reconfiguration capacity for peacekeeping versus combat roles.
NATO standardization agreements, EU defense procurement directives, and national military certification regimes collectively shape product specifications and cross-border market access for platform suppliers. The US Department of Defense's Modular Open Systems Approach mandates interoperability standards that ripple through allied supply chains. Stakeholders must monitor how sovereign industrial-base policies reshape teaming requirements and technology-transfer rules for multinational programs.
Market Dynamics
Defense leasing structures and modular open systems architectures are compressing traditional procurement cycles while fragmenting platform ownership models across NATO-aligned forces.
Growth Catalysts
- EU AI Act procurement frameworks:Stricter ballistic certification requirements under these protocols are forcing technology refresh cycles that displace legacy platforms.
- Active protection systems:Integration of radar-guided interceptors and hard-kill mechanisms is elevating platform survivability standards for mechanized infantry units.
- German production clusters:Concentrated armor and propulsion manufacturing around Munich and Kassel anchors continental supply security for allied replenishment programs.
Market Restraints
- Specialized steel alloy volatility:Quenched and tempered armor plate pricing fluctuates with energy-intensive smelting costs concentrated in Central European foundries.
- Single-source turret integration:Complex electro-optical fire control systems rely on a narrow supplier base in Bavaria and Lower Saxony, creating concentration exposure.
- REACH chemical restrictions:Legacy composite armor resins face phase-out timelines that compress qualified material alternatives.
Strategic Opportunities
- Polish fleet recapitalization:Accelerated NATO burden-sharing commitments are opening long-term vehicle co-production arrangements with domestic industrial participation requirements.
- Hybrid-electric propulsion:Convergence of diesel-electric drives with silent-running tactical modes addresses acoustic signature reduction for reconnaissance variants.
- Through-life support unbundling:Performance-based logistics contracts separate platform ownership from maintenance obligation, enabling sovereign fleet outsourcing.
Industry Challenges
- Systems integration engineering:Retrofitting legacy hulls with digital battle management architectures demands scarce software-hardware co-design expertise.
- STANAG 4569 certification timelines:Multi-threat ballistic and blast validation protocols extend development cycles for new armor configurations.
- Cross-border technology transfer:National industrial-base policies restrict component sourcing for multinational programs, fragmenting supply rationalization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Armored Vehicles Market |
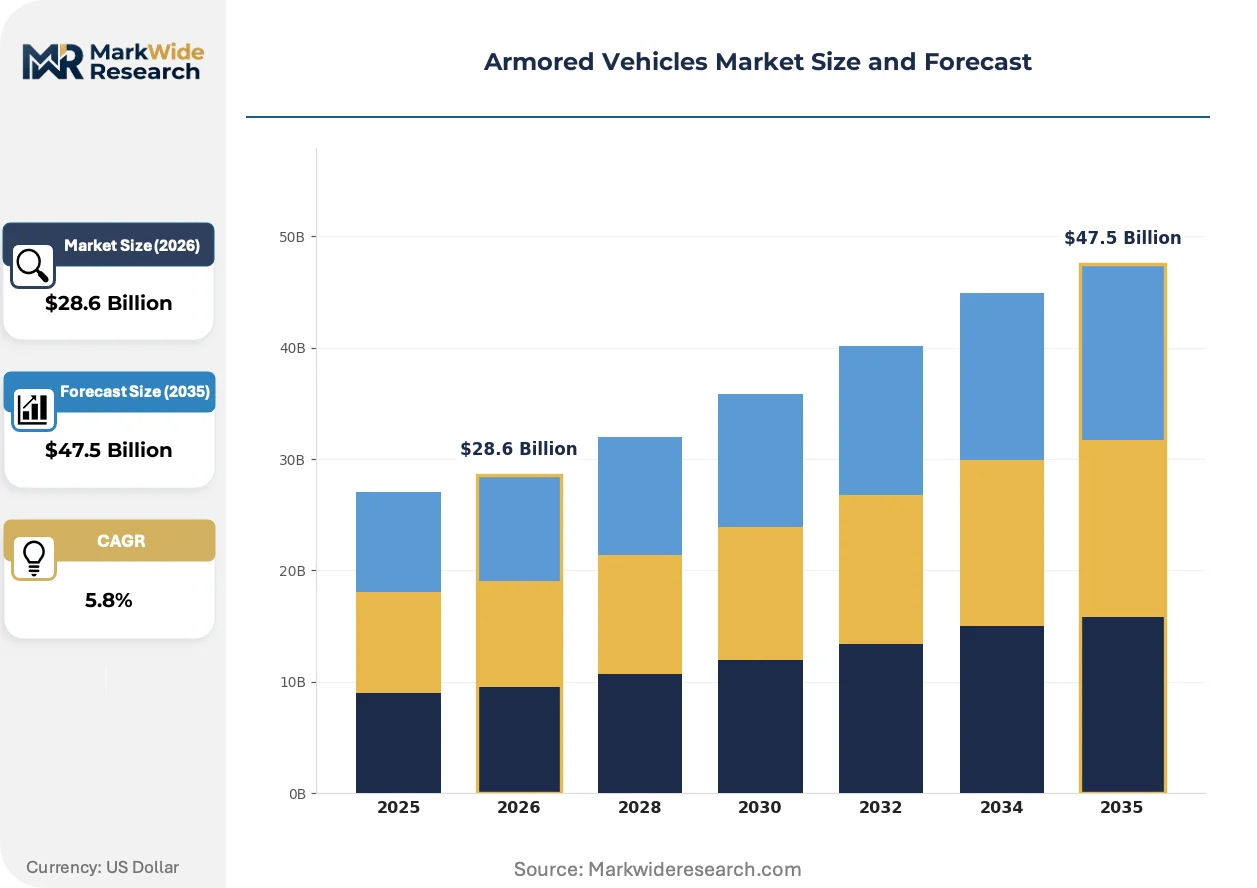
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $47.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Combat Vehicles, Personnel Carriers, Tactical Vehicles, Cash-in-Transit Vehicles End User: Defense Forces, Law Enforcement, Private Security, Government Agencies Technology: Ballistic Protection, Mine Resistance, Blast Protection, Surveillance Capabilities Deployment: On-road, Off-road, Urban, Military Operations |
| Companies Covered | Oshkosh Corporation, Krauss-Maffei Wegmann, General Dynamics Corporation, Textron Inc., International Armored Group, BAE Systems, Hanwha Defense, Lockheed Martin Corporation, Rheinmetall AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Armored Vehicles Market Strategic Shifts & Innovations
Digital engineering workflows and sovereign data sovereignty requirements are restructuring how armored vehicle specifications migrate from design to field deployment.
Active protection systems are virtualizing traditional armor mass-through-protection tradeoffs by intercepting threats before hull contact. Mechanized infantry commands in Central and Eastern Europe are accelerating adoption of radar-guided hard-kill interceptors. This architecture is virtualizing the competitive calculus between passive composite arrays and sensor-driven defensive suites.
EU defense procurement directives are mandating cross-border industrial participation quotas for platform awards above specified contract values. These rules fragment sole-source awards and compel consortium structures that dilute prime contractor margin control. Combat vehicle programs in the Nordic-Baltic corridor face the most acute compliance complexity.
Leasing structures are displacing capital acquisition for mid-tier sovereign buyers seeking fleet access without balance-sheet commitment. Defense ministries in Southeastern Europe are piloting government-backed project finance vehicles that transfer residual value risk to export credit agencies. This model concentrates most visibly where NATO interoperability requirements outpace domestic fiscal capacity.
Armored Vehicles Market Segmentation
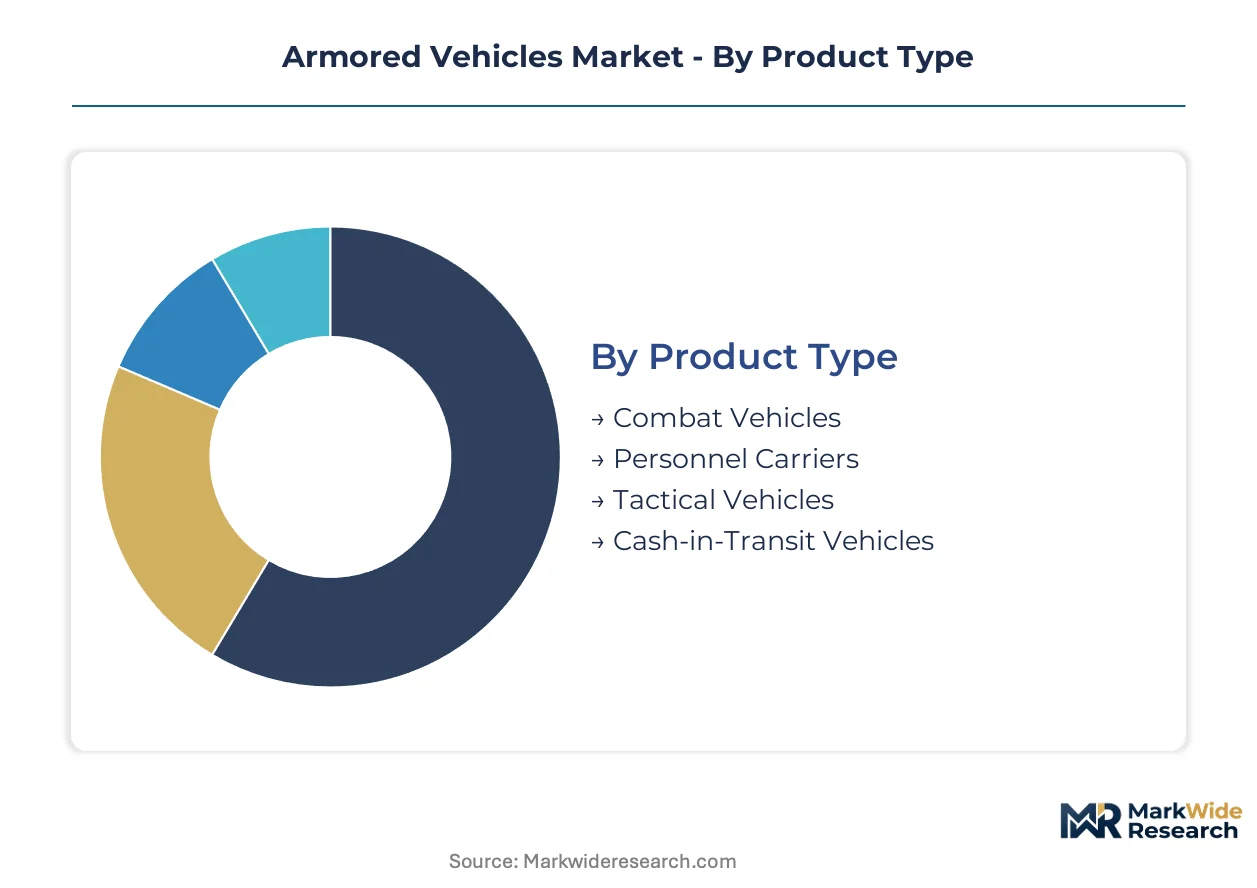
Segmentation in armored vehicles separates platforms by survivability tier, procurement authority, and mission profile. Each dimension carries distinct certification burdens and replacement cadences that reshape supplier priorities and fleet planning horizons.
Product Type:
Combat vehicles cycle slowest due to turret integration complexity and STANAG validation timelines, while cash-in-transit platforms refresh fastest on private-sector depreciation schedules.
- Combat Vehicles:Heavy platforms integrate active protection systems, large-caliber turrets, and digital battle management architectures. Demand concentrates in NATO mechanized infantry modernization programs where survivability against anti-tank guided missiles drives specification inflation.
- Personnel Carriers:Modular hulls accommodate rapid armor package swaps between peacekeeping patrol configurations and high-threat combat loads. Polish and Romanian defense ministries prioritize these for NATO interoperability compliance without full combat vehicle procurement costs.
- Tactical Vehicles:Light and medium trucks with add-on armor kits serve reconnaissance and logistics roles.
- Cash-in-Transit Vehicles:Commercial armored vans for banking logistics operate on 5-7 year replacement cycles.
Personnel carriers anchor the volume base while combat vehicles gain share at the steepest rate.
End User:
Defense procurement dominates capital deployment, yet private security and law enforcement segments operate on compressed decision timelines with fewer interoperability constraints.
- Defense Forces:National military services specify STANAG 4569 protection levels and mandate modular open systems architectures for fleet commonality. German, Polish, and Czech ministries currently drive the largest platform awards through NATO burden-sharing frameworks.
- Law Enforcement:Police tactical units require urban-optimized armor with lower ballistic ratings than military specifications. Acquisition concentrates in municipal budget cycles with faster approval pathways than defense procurement.
- Private Security:Commercial operators serving extractive industries and diplomatic protection purchase cash-in-transit and light tactical platforms.
- Government Agencies:Border patrol, coast guard, and correctional services acquire specialized variants with intermediate protection levels.
Defense forces absorb the majority of platform value while law enforcement expands most quickly.
Technology:
Technology segmentation tracks protection mechanism maturity, with passive armor representing installed base dominance and active systems capturing incremental investment share.
- Ballistic Protection:Hardened steel and composite arrays rated to STANAG 4569 Level 4-6 form the baseline protection standard. Demand clusters in Central European production corridors where quenched and tempered plate supply concentrates.
- Mine Resistance:V-hull geometries and blast-absorbing seating systems address underbody threat vectors. African and Middle Eastern export markets prioritize these configurations for asymmetric conflict environments.
- Blast Protection:Spall liners and structural reinforcement against improvised explosive devices.
- Surveillance Capabilities:Electro-optical suites and remote weapon stations.
Ballistic protection commands the largest installed base while mine resistance climbs the fastest.
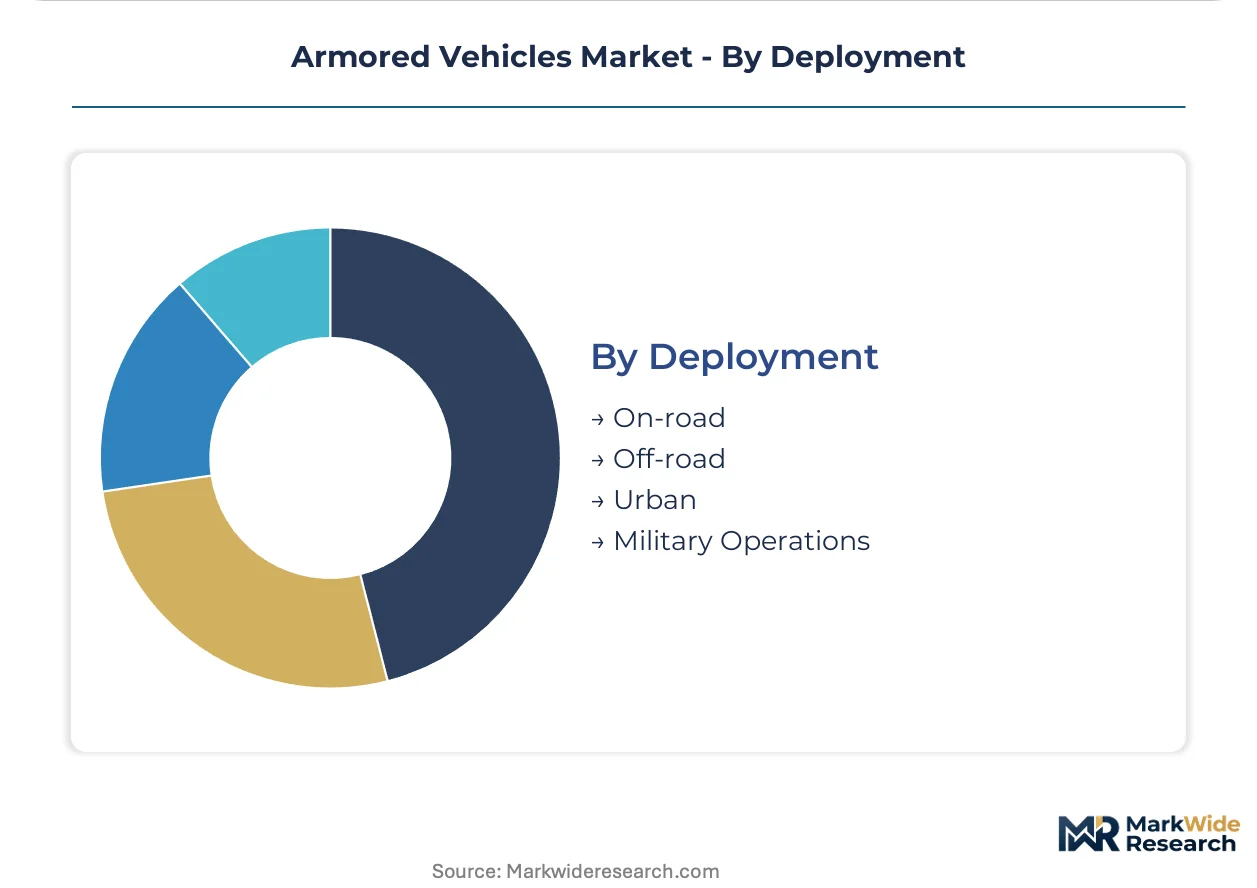
Deployment:
Deployment mode determines mobility architecture tradeoffs between speed, protection weight, and terrain accessibility.
- On-road:Cash-in-transit and diplomatic security vehicles optimize for highway speed with discrete armor profiles. Urban deployment in European capitals drives demand for reduced visual signatures.
- Off-road:Military logistics and reconnaissance platforms require independent suspension and high-power density for cross-country mobility. Nordic-Baltic procurement emphasizes these capabilities for forest and tundra operations.
- Urban:Narrow-street maneuverability and crowd-control configurations.
- Military Operations:Full-spectrum combat deployment with integrated command and control.
Off-road configurations anchor the military procurement base while urban deployment gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers extract pricing premiums from NATO standardization requirements while Polish buyers leverage co-production mandates to compress acquisition costs. This asymmetry shapes procurement patterns across the continent.
Germany
Bundeswehr fleet modernization and NATO burden-sharing commitments drive mechanized infantry vehicle demand. The EU AI Act procurement frameworks enforce stricter ballistic certification timelines that accelerate platform replacement. Munich and Kassel anchor concentrated armor and propulsion manufacturing clusters serving allied replenishment programs.
Poland
Accelerated NATO interoperability compliance and eastern flank deterrence posture fuel personnel carrier procurement. National industrial-base policies mandate domestic co-production quotas for foreign platform awards. Poznan and Warsaw host emerging vehicle assembly operations integrated with German supply chains.
United States
Modular Open Systems Approach mandates reshape tactical wheeled vehicle specifications across allied forces. The Department of Defense procurement protocols prioritize interoperability standards that ripple through NATO supply chains. Oshkosh, Wisconsin and Sterling Heights, Michigan concentrate tactical vehicle engineering and manufacturing capacity.
United Kingdom
Naval-to-land technology transfer programs and long-term through-life support contracts differentiate platform offerings. Ministry of Defence certification regimes enforce STANAG 4569 validation for mechanized units. Telford and Newcastle anchor armored systems integration and maintenance operations.
South Korea
Export-oriented defense industrial expansion targets NATO-aligned markets for wheeled and tracked platforms. Hanwha Defense leverages domestic shipbuilding-to-land-systems capabilities for integrated propulsion development. Changwon and Seoul concentrate electro-optical fire control and active protection system engineering.
Armored Vehicles Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in armor plate, turret mechanisms, and electro-optical suites. The vendor base stratifies between full-spectrum combat vehicle primes and modular subsystem suppliers. Three archetypes dominate: continental European land-systems houses with captive armor foundries, Anglo-American primes with naval-aerospace crossovers, and Korean conglomerates with shipbuilding-to-ground diversification. Competitive moves concentrate on consortium formation for EU procurement compliance and performance-based logistics contract capture.
Within the European land-systems tier, Krauss-Maffei Wegmann and Rheinmetall AG exemplify integrated propulsion-to-platform manufacturers with Munich and Kassel production gravity. Oshkosh Corporation occupies a position among North American tactical wheeled vehicle specialists serving modular open systems mandates. BAE Systems represents the naval-to-land technology transfer archetype with through-life support contract structures.
| Leading Market Players |
|---|
| Oshkosh Corporation |
| Krauss-Maffei Wegmann |
| General Dynamics Corporation |
| Textron Inc. |
| International Armored Group |
| BAE Systems |
| Hanwha Defense |
| Lockheed Martin Corporation |
| Rheinmetall AG |
| Others |
Cost & Logistics Intelligence
Undercapacity in Central European armor plate foundries is compressing supplier margins while elevating pricing leverage for integrated manufacturers with captive steel capacity. This utilization squeeze feeds directly into platform pricing postures, with hull fabricators passing through alloy cost volatility while turret integrators extract premiums from scarce electro-optical fire control availability.
Pricing Analysis
Configured-to-order pricing for combat vehicles with integrated active protection systems commands a 40-60% premium over standard personnel carrier configurations. Three-tier pricing structure across premium, standard, and economy levels reflects STANAG 4569 certification grade, with Level 6 ballistic validation adding substantial cost. Pricing pressure stems from Polish co-production mandates requiring technology transfer concessions that compress prime contractor margins. Defense ministries exhibit lowest price sensitivity for active protection system integration, while municipal law enforcement procurement shows highest sensitivity to armor package upgrades.
Supply Chain Analysis
Export-control regimes under EU dual-use regulations and US ITAR restrictions limit electro-optical fire control system flows to non-NATO buyers. Geographic supply concentration centers on Germany, South Korea, and the United States for complete platform integration. Raw material dependencies draw from Swedish specialty steel, Turkish boron carbide ceramics, and Japanese precision optics. Single-source vulnerability concentrates in Bavarian turret mechanism suppliers. Distribution runs through government-to-government foreign military sales channels and direct commercial sales with offset agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as NATO burden-sharing commitments fragment large platform awards into consortium-structured competitions, creating niches for subsystem specialists and co-production partners.
For Market Incumbents: Entrench position through backward integration into quenched and tempered armor plate production, securing supply against Central European foundry volatility. Acquire electro-optical fire control engineering capacity in South Korea to diversify beyond Bavarian single-source exposure. Lock in long-term through-life support contracts with Polish and Romanian ministries before co-production mandates mature.
For New Entrants and Emerging Players: Build out active protection system retrofit capabilities for legacy hull fleets in Southeastern Europe, where NATO interoperability requirements outpace replacement budgets. Target Polish domestic assembly partnerships as the most penetrable entry vector. Pursue performance-based logistics contracts that separate platform ownership from maintenance obligation.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across active protection system engineering, favoring specialized component suppliers over full-platform integrators. Long-term viability through the decade ahead rests on software-hardware co-design expertise for digital battle management architectures. Acquisition target archetype: mid-cap electro-optical fire control developers with ITAR-free product variants. Signal to watch: Polish industrial participation quota enforcement in upcoming mechanized infantry awards.
| Strategic Initiative | Industry Significance |
|---|---|
| Active Protection System Integration | Virtualizes armor mass-through-protection tradeoffs for mechanized infantry survivability. |
| Co-Production Partnership Formation | Satisfies Polish and Romanian domestic content mandates while accessing NATO-aligned demand. |
| Hybrid-Electric Propulsion Development | Addresses acoustic signature reduction for Nordic-Baltic reconnaissance requirements. |
| Performance-Based Logistics Contracting | Unbundles platform ownership from maintenance obligation for sovereign fleet outsourcing. |
| Digital Battle Management Architecture | Enables Modular Open Systems Approach compliance for US and allied procurement. |
Research Approach
A standing panel of Bundeswehr procurement officers, Polish defense ministry industrial participation directors, Rheinmetall AG platform engineers, and NATO standardization office technical leads provided ongoing calibration. Primary interviews with these stakeholders combined with secondary validation from EU defense procurement directive filings, US DoD budget justification documents, STANAG 4569 certification records, and national military equipment registers. Bottom-up platform delivery forecasts triangulated against top-down NATO burden-sharing commitment allocations.
Scenario-bracketing framed low, baseline, and high cases across the projection horizon, with segmentation dimensions spanning protection tier, procurement authority, mission profile, and technology maturity. CAGRs derived from fitted growth curves anchored to announced fleet modernization timelines and validated against historical replacement cadences. Industry-specific forecast inputs included active protection system adoption curves and hybrid-electric propulsion development milestones.
Stress conditions across alloy price volatility, REACH chemical restriction phase-out timelines, and cross-border technology transfer policy shifts were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding NATO interoperability compliance trajectories and EU AI Act procurement framework implementation. Material shifts in German industrial-base policy or Polish co-production quota enforcement would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Armored Vehicles
US Armored Vehicle Market
Armored Vehicles
Armored Fighting Vehicles Market
Armored Vehicles
Boom Arms Market
Armored Vehicles
Armor Protection Systems Market
Armored Vehicles
Armored Vehicles Upgrade and Retrofit Market
Armored Vehicles
Europe Armored Fighting Vehicles Market
Armored Vehicles
Armoured Personnel Carrier (APC) Market
Armored Vehicles
Global Ceramic Armor Market
Armored Vehicles
Military Armored Car Market
Armored Vehicles
Armored Vehicle Fire Suppression Systems Market
Armored Vehicles
Asia-Pacific Armored Fighting Vehicles Market
Armored Vehicles
North America Armored Fighting Vehicles Market
Armored Vehicles
Armored Vehicle Procurement and Upgrade Market
Armored Vehicles
Armored Vehicle Navigation Systems Market
Armored Vehicles
Middle-East and Africa Armored Vehicles Market
Armored Vehicles
Armored Personnel Carrier Market