
 Global Ceramic Armor Market | 2026-2036
Global Ceramic Armor Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ceramic Armor Market Foresight
Premium boron carbide solutions is decoupling from commodity alumina plates on a cost-per-stopped-threat basis. CoorsTek Inc. leverages its vertically integrated ceramic powder production to sustain margin control across military contracts. CeramTec GmbH anchors European supply chains through specialized silicon carbide manufacturing in Germany. BAE Systems competes on system-level integration, bundling ceramic strike faces with composite backings for vehicle platforms.
Ceramic armor comprises hard ceramic tiles bonded to fiber-reinforced composite backings, engineered to shatter and dissipate kinetic energy from ballistic projectiles at areal densities below metallic alternatives. Alumina dominates procurement volumes due to established supply chains and lower raw material costs, while boron carbide commands premium positioning for next-generation military protection where weight reduction is critical. Silicon Carbide occupies the middle tier, balancing performance against cost in law enforcement defense and security vehicles where threat levels vary. Personal body armor represents a mature segment with standardized NIJ certification requirements, whereas protective barriers for secure facilities show expanding specification diversity.
NIJ standards in the United States, NATO STANAG agreements across European defense forces, and South Korea's DAPA acquisition frameworks collectively shape product certification pathways and cross-border market access. The EU Green Deal's embedded carbon reporting through CSRD is beginning to influence raw material sourcing decisions for European manufacturers. Stakeholders must monitor how next-generation threat disclosures from military laboratories redirect R&D spending toward multi-hit capable ceramic matrix composites.
Market Dynamics
NIJ ballistic standard upgrades and NATO STANAG threat disclosures are forcing simultaneous material transitions across soldier protection and vehicle armor programs, compressing supplier qualification timelines while fragmenting procurement specifications.
Growth Catalysts
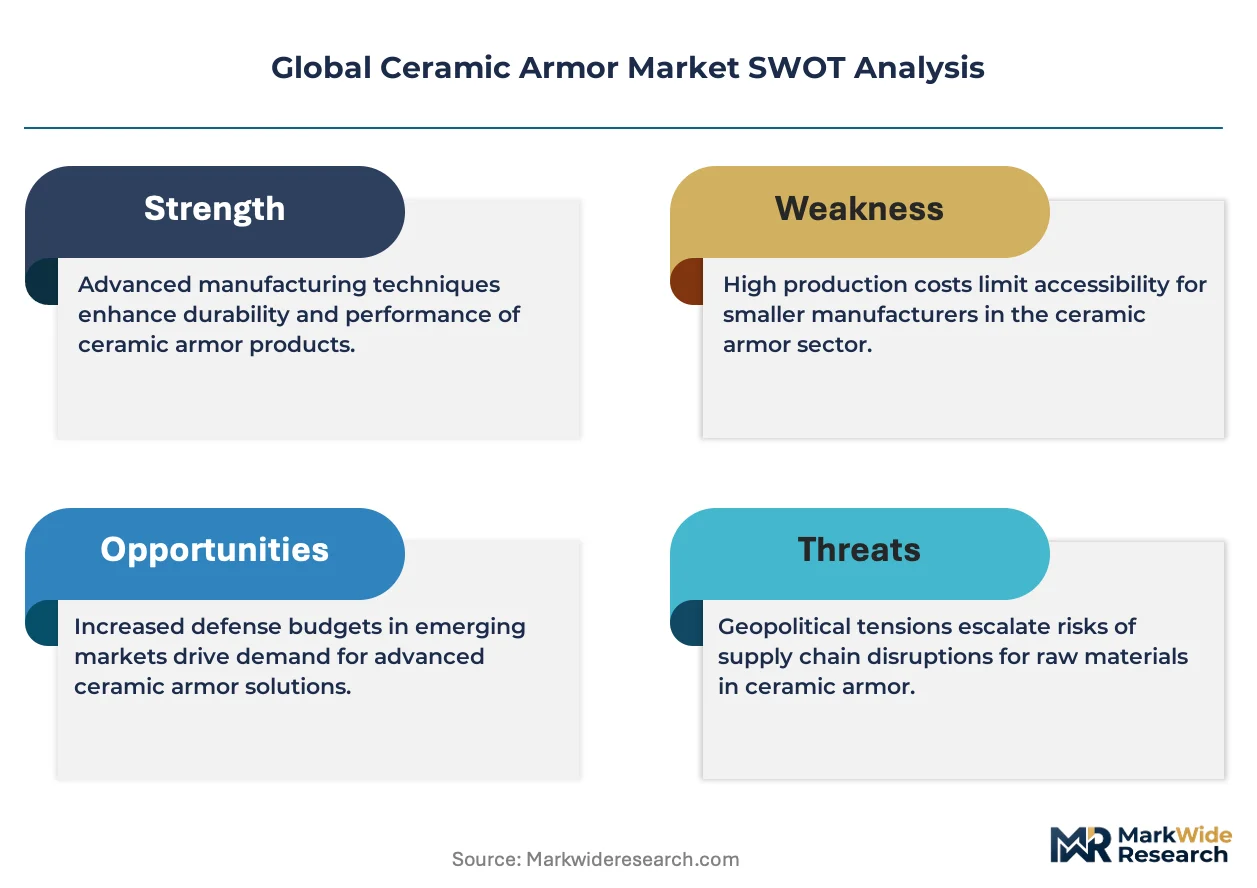
- Armor-piercing threat disclosures:Military laboratories in the United States and Germany are releasing updated penetration profiles that mandate ceramic matrix composite upgrades for next-generation plates.
- CSRD embedded carbon reporting:The EU Green Deal's supply chain transparency requirements are accelerating boron carbide sourcing audits among European defense contractors seeking contract eligibility.
- Soldier survivability prioritization:Defense budget reallocations in South Korea under DAPA frameworks are expanding personal body armor procurement volumes for frontline units.
Market Restraints
- Raw material concentration:Boron carbide precursor supply concentrates in limited geographic clusters, exposing armor manufacturers to price volatility and allocation constraints.
- Multi-hit performance ceiling:Monolithic ceramic tiles face inherent structural limitations against sequential impacts, restricting their deployment in vehicle hull applications without composite backing redundancy.
- REACH substance restrictions:ECHA scrutiny of certain ceramic processing aids is complicating formulation continuity for silicon carbide manufacturers serving European law enforcement.
Strategic Opportunities
- India defense indigenization:The country's PLI scheme for strategic materials is opening localized ceramic powder production partnerships for foreign armor system integrators.
- Secure facility barriers:Embassy and critical infrastructure protection specifications are diversifying beyond standard NIJ levels, creating demand for custom ceramic composite configurations.
- Multi-material convergence:Integration of silicon carbide strike faces with ultra-high molecular weight polyethylene backings is enabling weight-optimized solutions for maritime security forces.
Industry Challenges
- Ballistic test engineer scarcity:Specialized talent capable of interpreting NIJ and STANAG protocols simultaneously is concentrated among a handful of defense contractors, constraining R&D velocity.
- Qualification timeline compression:Accelerated threat disclosure cycles are compressing the traditional 18-24 month ceramic plate certification process, forcing manufacturers to parallelize testing and production scale-up.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ceramic Armor Market |
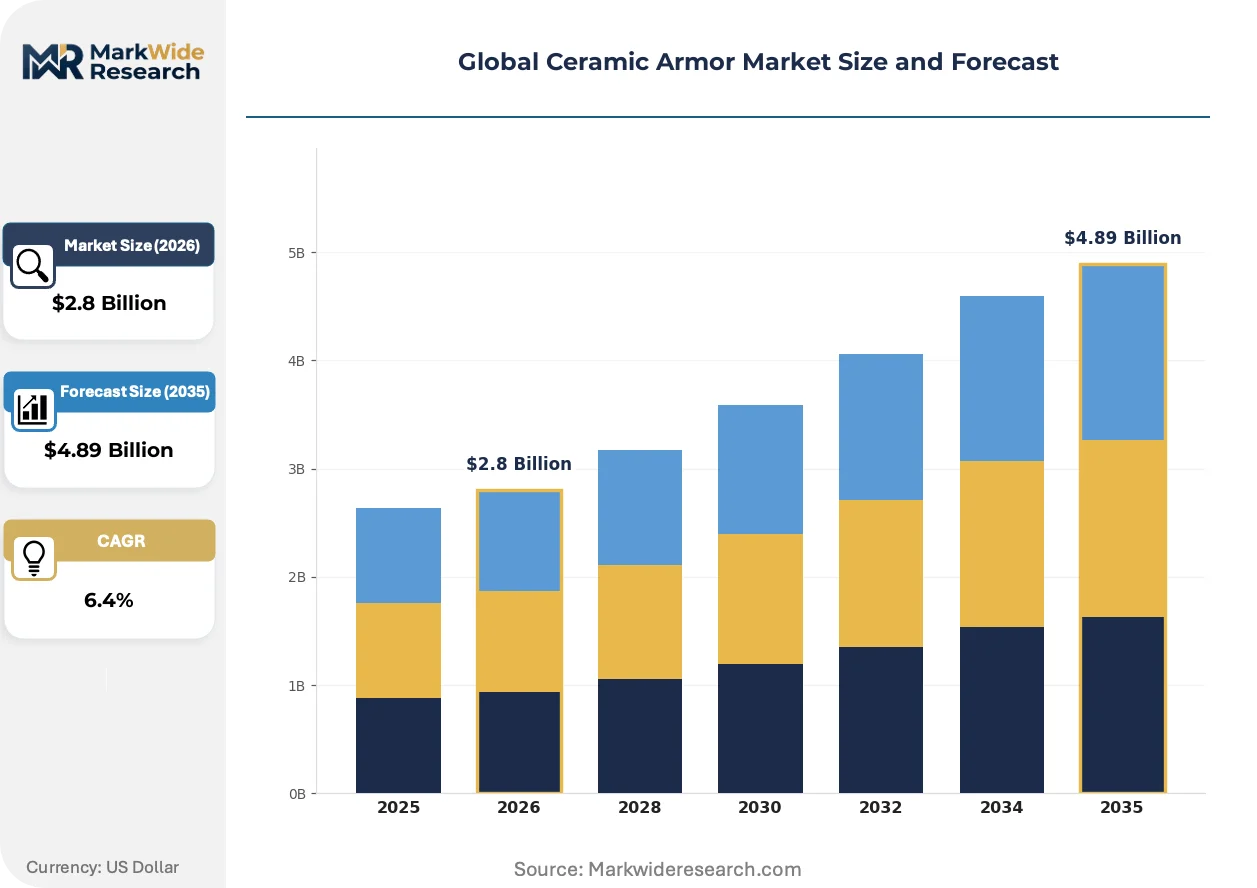
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alumina, Silicon Carbide, Boron Carbide, Zirconia, Titanium Diboride Application: Military Protection, Law Enforcement Defense, Security Vehicles, Personal Body Armor, Protective Barriers End User: Defense Forces, Police Agencies, Private Security Firms, Vehicle Manufacturers, Homeland Security Deployment: Field Operations, Tactical Missions, Secure Facilities, Training Exercises, Disaster Response |
| Companies Covered | ArmorWorks Enterprises, Safariland, CoorsTek Inc., Koninklijke DSM, Compagnie de Saint-Gobain, 3M Company, Integris Composites, BAE Systems, CeramTec GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ceramic Armor Market Shifts & Advancements
Material science advances and procurement digitization are converging to reshape how ceramic armor specifications are developed, tested, and contracted across military and security end-uses.
Silicon carbide-boron carbide hybrid strike faces are unifying the weight advantages of premium ceramics with the cost structure of mid-tier alternatives. Vehicle platform integrators in Germany and South Korea are adopting these configurations for crew compartment protection where areal density constraints compete with budget ceilings. This unification is compressing the traditional three-tier material hierarchy into a more fluid performance-cost continuum.
CSRD supply chain disclosure mandates are forcing European manufacturers to document carbon intensity across boron carbide precursor mining and processing stages. Defense contractors serving NATO-aligned forces must now embed emissions tracking into ceramic powder qualification protocols. German and French armor producers are responding by consolidating supplier audits and shortening qualification lists to reduce reporting complexity.
Competitive bidding platforms are displacing sole-source negotiations for standardized law enforcement plate contracts in the United States. Municipal procurement departments are aggregating demand through cooperative purchasing agreements, compressing price discovery cycles from quarters to weeks. This channel shift is most visible in state-level corrections and federal protective service programs where NIJ Level IIIA and Level IV specifications dominate volume.
Global Ceramic Armor Market Segmentation
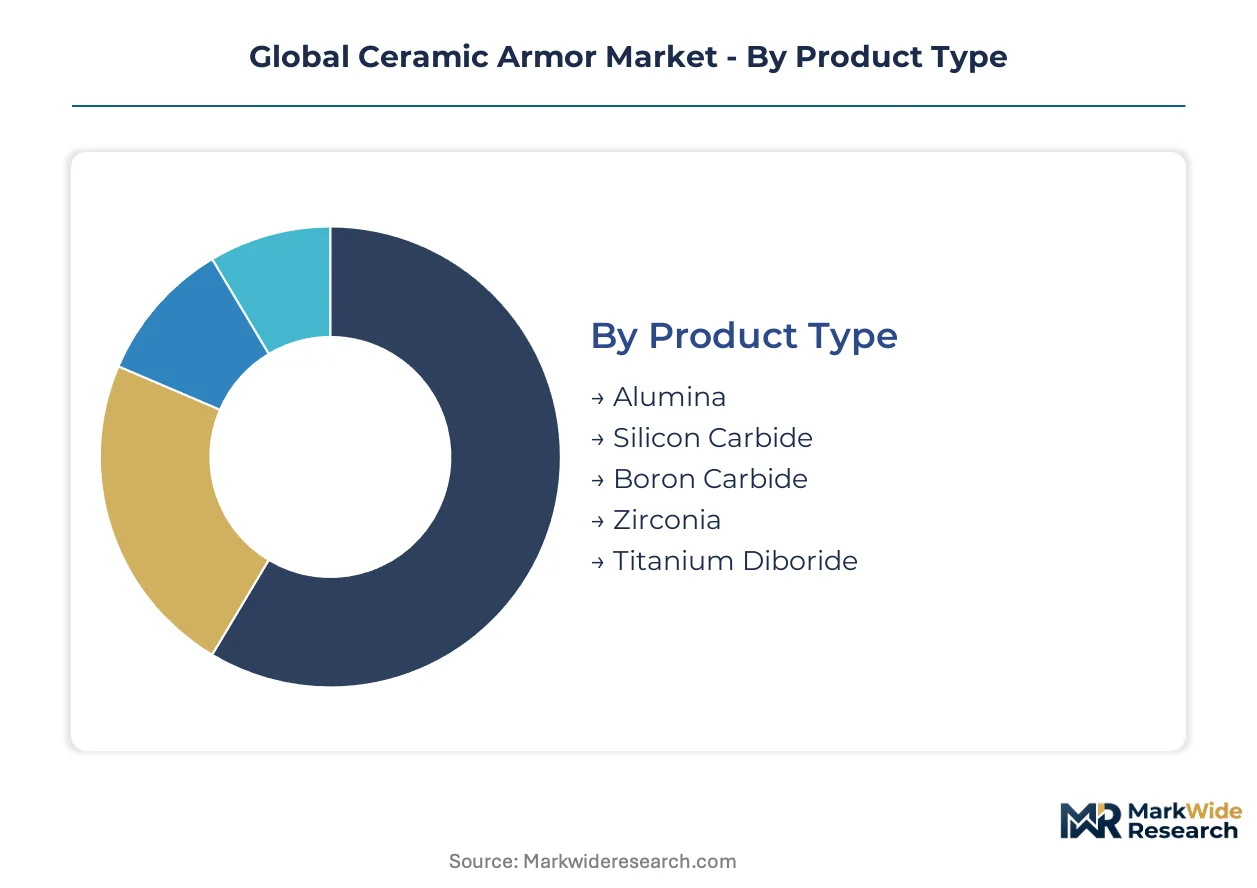
Ceramic armor procurement decisions cascade through four interconnected dimensions: material chemistry determines ballistic performance ceilings, application context dictates weight and multi-hit requirements, end-user category shapes certification pathways, and deployment scenario influences durability specifications against environmental stressors.
Product Type:
Cost-performance positioning separates commodity ceramics from premium formulations, with procurement officers trading areal density against budget constraints across threat profiles.
- Alumina:Aluminum oxide ceramic dominates procurement volumes through established powder supply chains and favorable raw material economics. United States defense contractors specify alumina for vehicle hull applications where areal density tolerance accommodates heavier strike faces against cost ceilings.
- Silicon Carbide:Intermediate density and fracture toughness position silicon carbide as the preferred compromise for law enforcement defense and security vehicles across Germany and South Korea. NATO STANAG threat disclosures are accelerating silicon carbide adoption in crew compartment protection where weight reduction carries tactical value without boron carbide cost premiums.
- Boron Carbide:Lowest theoretical density among technical ceramics commands premium positioning for dismounted soldier protection where every gram determines mobility. CSRD embedded carbon reporting is complicating European sourcing of boron carbide precursors.
- Zirconia:Transformation toughening mechanisms deliver exceptional fracture resistance for multi-hit scenarios in secure facility barriers.
- Titanium Diboride:Extreme hardness against armor-piercing threats finds niche application in specialized military protection programs.
Alumina leads on scale; boron carbide leads on momentum.
Application:
Threat velocity and impact frequency differentiate specification requirements, with vehicle platforms tolerating higher areal densities than dismounted personnel systems.
- Military Protection:Soldier survivability prioritization across NATO-aligned forces is expanding procurement volumes for next-generation ceramic matrix composite plates. United States and German military laboratories are releasing updated penetration profiles that mandate material upgrades for next-generation soldier protection.
- Personal Body Armor:Standardized NIJ certification requirements create procurement efficiency for law enforcement defense, though municipal cooperative purchasing agreements are compressing price discovery cycles from quarters to weeks.
- Security Vehicles:Crew compartment protection specifications in South Korea under DAPA frameworks are driving silicon carbide-boron carbide hybrid configurations.
- Law Enforcement Defense:State-level corrections and federal protective service programs dominate standardized plate volumes.
- Protective Barriers:Embassy and critical infrastructure protection specifications are diversifying beyond standard NIJ levels.
Military protection leads on scale; protective barriers lead on momentum.
End User:
Budget cycle timing and certification authority concentration shape supplier relationship strategies, with defense forces running multi-year programs against police agency spot purchasing.
- Defense Forces:NATO STANAG and NIJ ballistic standard upgrades are forcing simultaneous material transitions across soldier protection and vehicle armor programs, compressing supplier qualification timelines.
- Police Agencies:Municipal procurement digitization through cooperative purchasing agreements is displacing sole-source negotiations for standardized law enforcement plate contracts.
- Vehicle Manufacturers:System-level integration requirements favor suppliers bundling ceramic strike faces with composite backings.
- Private Security Firms:Commercial threat assessments drive custom ceramic composite configurations outside standard certification pathways.
- Homeland Security:Federal protective service programs aggregate demand for NIJ Level IIIA and Level IV specifications.
Defense forces lead on scale; private security firms lead on momentum.
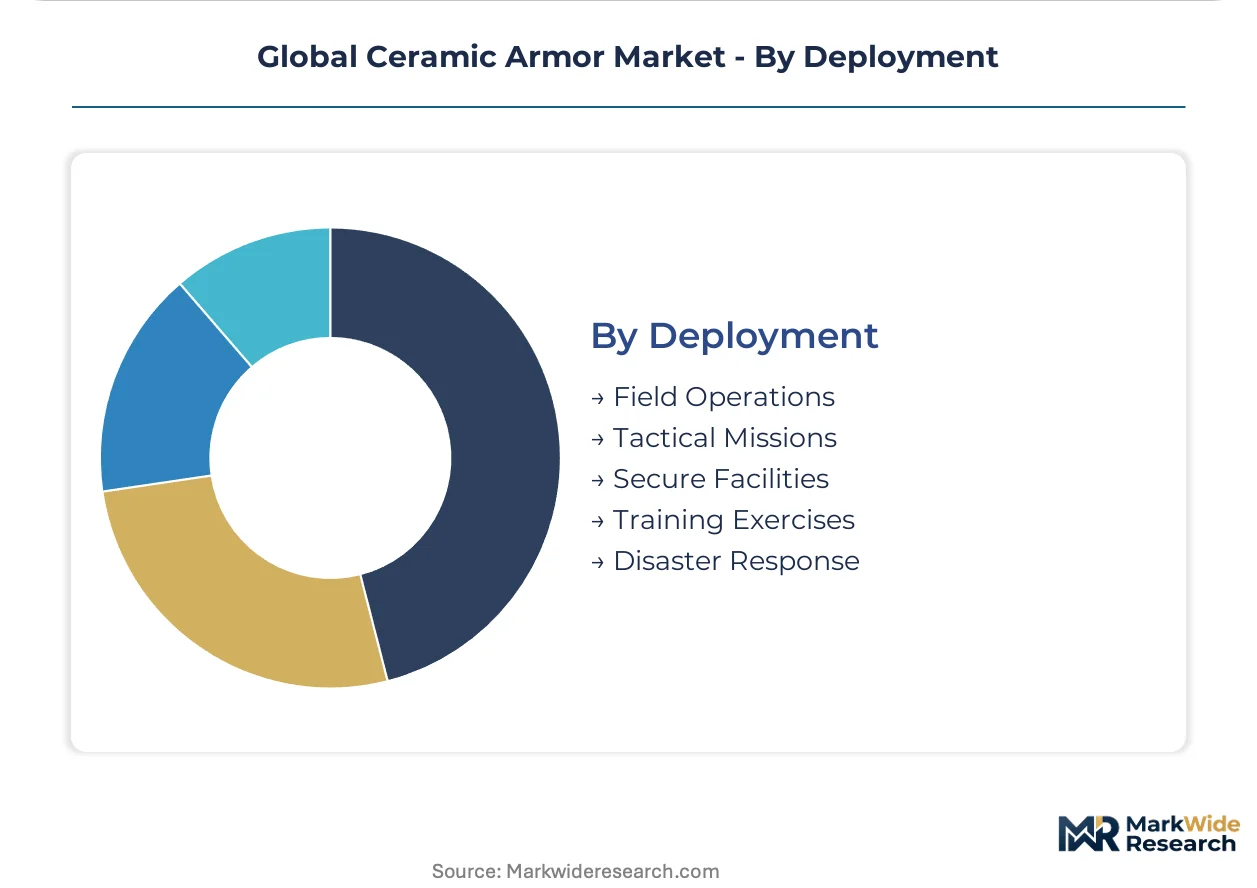
Deployment:
Environmental exposure duration and impact probability determine durability specifications against thermal cycling and moisture ingress.
- Field Operations:Extended environmental exposure demands ceramic matrix composite backing redundancy against moisture degradation and thermal shock.
- Tactical Missions:Short-duration high-intensity scenarios prioritize weight minimization over multi-hit durability.
- Secure Facilities:Static installation enables heavier ceramic configurations optimized for repeated impact resistance.
- Training Exercises:High-cycle usage patterns favor replaceable tile architectures over monolithic plate designs.
- Disaster Response:Unpredictable threat environments require flexible ceramic armor configurations spanning fragmentation and ballistic protection.
Field operations leads on scale; secure facilities leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized ballistic test engineers concentrate in defense contractor clusters across the United States, Germany, and South Korea, anchoring procurement specification development and supplier qualification timelines for ceramic armor programs.
United States
NIJ ballistic standard upgrades drive material transitions across soldier protection and vehicle armor programs. Defense contractors in Michigan and Texas compress supplier qualification timelines while fragmenting procurement specifications. The Army Research Laboratory in Maryland releases updated penetration profiles that mandate ceramic matrix composite upgrades.
Germany
NATO STANAG threat disclosures accelerate silicon carbide adoption in crew compartment protection. The EU Green Deal's CSRD embedded carbon reporting forces boron carbide sourcing audits among defense contractors seeking contract eligibility. CeramTec GmbH anchors European supply chains through specialized manufacturing in Plochingen.
South Korea
DAPA acquisition frameworks expand personal body armor procurement volumes for frontline units. Defense budget reallocations prioritize soldier survivability in procurement decisions. Hyundai Rotem and Hanwha Aerospace drive silicon carbide-boron carbide hybrid configurations for vehicle platforms in Changwon.
India
The PLI scheme for strategic materials opens localized ceramic powder production partnerships for foreign armor system integrators. Defense indigenization mandates redirect procurement toward domestic manufacturing capabilities. Bharat Forge and Tata Advanced Systems cluster ceramic armor development in Pune and Hyderabad.
United Kingdom
BAE Systems competes on system-level integration, bundling ceramic strike faces with composite backings for vehicle platforms. Ministry of Defence procurement frameworks emphasize multi-hit capable ceramic matrix composites. Defense contractors in Bristol and Glasgow specialize in next-generation threat response configurations.
Global Ceramic Armor Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the ceramic armor value chain, creating a tiered market structure where powder synthesis capabilities separate integrated manufacturers from assembly-focused players. The vendor base fragments across three strategic archetypes: vertically integrated ceramic powder producers, system-level armor integrators, and specialized composite backing suppliers. Consolidation pressure concentrates among mid-tier silicon carbide manufacturers seeking scale against boron carbide premium positioning. Dominant competitive moves include backward integration into precursor mining and strategic partnerships with defense contractors for multi-year program qualification.
Within the integrated ceramic powder tier, CoorsTek Inc. and CeramTec GmbH exemplify geographic anchoring strategies that control supply chain exposure. Among system-level integrators, BAE Systems occupies a position representing bundled strike-face-and-backing configurations for vehicle platforms. These three companies illustrate how competitive positioning depends on whether players control upstream powder production or downstream system integration, with the middle ground of silicon carbide specialization facing margin compression from both directions.
| Leading Market Players |
|---|
| ArmorWorks Enterprises |
| Safariland |
| CoorsTek Inc. |
| Koninklijke DSM |
| Compagnie de Saint-Gobain |
| 3M Company |
| Integris Composites |
| BAE Systems |
| CeramTec GmbH |
| Others |
Supply & Pricing Matrix
NIJ Level IV certification mandates from United States defense procurement are compressing supplier qualification timelines and forcing armor manufacturers to absorb higher boron carbide precursor costs or sacrifice margin on alumina alternatives. This demand-side specification tightening cascades into supply chain restructuring as European contractors face simultaneous CSRD carbon reporting obligations.
Pricing Analysis
Bundled strike-face-and-backing configurations command premium positioning against unbundled ceramic tile sales. Three-tier pricing structure across premium, standard, and economy levels stratifies by areal density performance and NIJ certification grade. Cost compression in law enforcement procurement is intensifying because municipal cooperative purchasing agreements aggregate demand and compress price discovery cycles. Police agencies exhibit highest price sensitivity; defense forces running multi-year STANAG programs demonstrate lowest.
Supply Chain Analysis
Boron carbide precursor supply rests on limited geographic clusters in the United States and Germany, with silicon carbide powder production concentrating in South Korea and Japan. Critical inputs span specialty ceramic powders, fiber-reinforced composite backings, and multi-hit capable matrix formulations. Single-source vulnerability in boron carbide mining exposures creates allocation risk during defense procurement surges. Distribution runs through defense contractor prime relationships and municipal cooperative purchasing platforms for law enforcement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as soldier survivability prioritization across NATO-aligned forces sustains procurement volumes regardless of budget cycle fluctuations. Defense budget reallocations under DAPA frameworks and similar programs provide durable demand anchoring.
For Market Incumbents: To counter margin compression from municipal cooperative purchasing, deepen backward integration into ceramic powder production and consolidate supplier audits to reduce CSRD reporting complexity. Capture multi-year program qualification slots early as NIJ and STANAG disclosure cycles accelerate.
For New Entrants and Emerging Players: Launch via specialized composite backing partnerships targeting India's PLI scheme for strategic materials localization. Private security firms and embassy barrier specifications offer the most penetrable segments outside standardized certification pathways. Lead with custom ceramic composite configurations for critical infrastructure protection.
For Investors and Strategic Acquirers: Asymmetric upside sits with silicon carbide-boron carbide hybrid specialists bridging premium and mid-tier positioning. Long-term viability centers on captive powder production and defense contractor relationships. Watch for next-generation threat disclosures from United States and German military laboratories as inflection indicators redirecting R&D spending.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Powder Production | CoorsTek and CeramTec sustain margin control through captive boron carbide and silicon carbide supply. |
| Multi-year Defense Program Qualification | BAE Systems secures vehicle platform bundling contracts under NATO STANAG disclosure timelines. |
| CSRD Supply Chain Audit Consolidation | German and French armor producers reduce reporting complexity by shortening qualified supplier lists. |
| Silicon Carbide-Boron Carbide Hybrid Development | Hyundai Rotem and Hanwha Aerospace optimize crew compartment protection for South Korean DAPA frameworks. |
| Localized Production Partnership under PLI Scheme | Foreign integrators access India's defense indigenization mandates through Bharat Forge and Tata Advanced Systems clusters. |
Research Methodology
Coverage spans the United States, Germany, South Korea, India, and the United Kingdom, with primary inputs from each defense procurement cluster. The analysis combines interviews with ceramic armor program managers, ballistic test engineers, defense contractor procurement leads, and composite materials R&D directors with secondary validation from NIJ certification databases, NATO STANAG disclosure documents, DAPA acquisition frameworks, and EU CSRD regulatory filings. Bottom-up segmentation modeling triangulates against top-down defense budget allocation analysis.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions include material chemistry tier, application context, end-user procurement authority, and deployment scenario durability requirements. CAGRs derive from defense budget trajectory analysis, threat disclosure cycle timing, and ceramic powder capacity expansion announcements. Industry-specific inputs capture NIJ standard upgrade implementation schedules and REACH substance restriction timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated threat disclosure cycles or boron carbide supply disruptions. Forecasts reflect assumptions about defense budget continuity, certification pathway stability, and raw material sourcing geography. A small set of named triggers warrants ongoing watch: next-generation armor-piercing threat disclosures, ECHA processing aid restrictions, and India's PLI scheme implementation pace.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Armored Vehicles
Armoured Personnel Carrier (APC) Market
Armored Vehicles
Armored Vehicle Navigation Systems Market
Armored Vehicles
Military Armored Car Market
Armored Vehicles
Armored Vehicles Market
Armored Vehicles
US Armored Vehicle Market
Armored Vehicles
Asia-Pacific Armored Fighting Vehicles Market
Armored Vehicles
Armored Personnel Carrier Market
Armored Vehicles
North America Armored Fighting Vehicles Market
Armored Vehicles
Armored Vehicle Procurement and Upgrade Market
Armored Vehicles
Armor Protection Systems Market
Armored Vehicles
Armored Fighting Vehicles Market
Armored Vehicles
Armored Vehicles Upgrade and Retrofit Market
Armored Vehicles
Armored Vehicle Fire Suppression Systems Market
Armored Vehicles
Middle-East and Africa Armored Vehicles Market
Armored Vehicles
Europe Armored Fighting Vehicles Market
Armored Vehicles
Boom Arms Market