
 Europe Armored Fighting Vehicles Market | 2026-2036
Europe Armored Fighting Vehicles Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Armored Fighting Vehicles Market Foresight
Platform lifecycle extension revenue is reshaping competitive economics across the Europe Armored Fighting Vehicles Market. Rheinmetall AG leverages its industrial base in Germany to dominate tracked vehicle refurbishment contracts. KNDS N.V. anchors Franco-Belgian supply chains through cross-border production integration. BAE Systems PLC sustains British Army support relationships via long-term availability contracts for Challenger platforms.
Armored fighting vehicles are tracked or wheeled combat platforms built from high-hardness steel, composite armor, and ceramic arrays, designed to transport personnel and deliver direct fire under ballistic and blast threats. Infantry fighting vehicles with 30-40mm autocannon turrets represent the mature volume segment, while active protection systems integration commands premium positioning as threat profiles evolve. Hybrid power technology segments are gaining structural attention as military operators confront fuel logistics constraints in dispersed operations.
EU Green Deal procurement standards and the F-Gas Regulation constrain powertrain and cooling system specifications, while CE marking and NATO STANAG ballistic certification define minimum platform interoperability. The European Defence Agency coordinates joint capability development, pressuring national programs toward common technical architectures. Stakeholders must weigh sovereign production retention against cross-border consortium economics as framework nations consolidate spending authority.
Market Dynamics
NATO's eastern flank expansion is compressing procurement cycles as Poland and the Baltic states accelerate territorial defense investments ahead of platform obsolescence deadlines.
Growth Catalysts
- Eastern European Territorial Defense:Poland's mechanized brigade modernization and Baltic mechanized infantry procurement are pulling tracked vehicle volumes upward.
- EU Green Deal Defense Procurement Standards:Sustainability-linked tender scoring is creating qualification advantages for suppliers with low-carbon production footprints.
- Active Protection System Maturation:Hard-kill and soft-kill APS integration is extending platform survivability against shaped-charge and kinetic energy threats.
Market Restraints
- High-Hardness Steel Supply Concentration:European armor plate production concentrates in German and Swedish mills, creating input bottlenecks during surge demand.
- F-Gas Regulation Cooling System Constraints:Refrigerant restrictions limit thermal management options for enclosed fighting compartments.
- Skilled Welder Shortage:Certified armored vehicle welders are aging out faster than apprenticeship pipelines replenish across Central European industrial bases.
Strategic Opportunities
- Romanian and Bulgarian Fleet Gaps:These NATO members operate Soviet-era platforms nearing end-of-life with limited domestic replacement capacity.
- Hybrid Powertrain Convergence:Battery-electric and fuel-cell auxiliary systems are opening silent-watch and reduced-thermal-signature operational modes.
- Long-Term Availability Contracting:British and French defense ministries are shifting from capital purchase to through-life support models.
Industry Challenges
- NATO STANAG Certification Timelines:Ballistic and blast protection validation cycles extend 18-24 months, compressing platform delivery windows.
- Legacy Platform Integration Complexity:Digital architecture retrofits into 1980s-era chassis strain electrical power budgets and cooling capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Armored Fighting Vehicles Market |
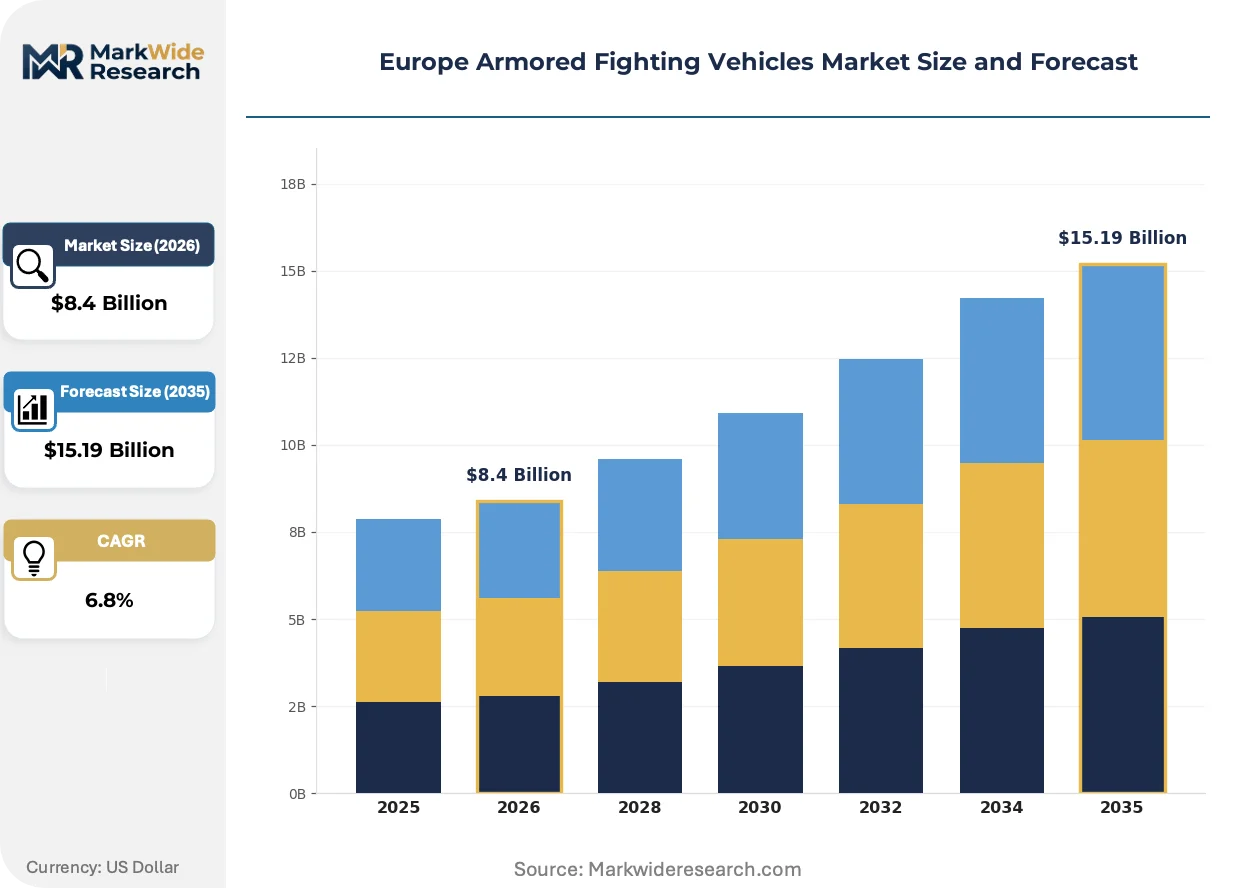
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Main Battle Tanks, Infantry Fighting Vehicles, Armored Personnel Carriers, Self-Propelled Artillery Technology: Hybrid Power, Counter-IED Systems, Active Protection Systems, Communication Systems End User: Defense Forces, Private Security Contractors, Government Agencies, NATO Forces Installation: On-Site Maintenance, Off-Site Maintenance, Factory Integration, Field Deployment |
| Companies Covered | KNDS N.V., Krauss-Maffei Wegmann, BAE Systems PLC, Oshkosh Corporation, Patria, Rheinmetall AG, Iveco Defence Vehicles, ARQUUS Defense, General Dynamics Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Armored Fighting Vehicles Market Shifts & Advancements
Battlefield digitization is compressing sensor-to-shooter timelines while sustainability mandates reshape powertrain development priorities across European defense industrial bases.
Artificial intelligence-enabled threat detection is digitizing crew situational awareness. Sensor fusion algorithms process thermal, radar, and acoustic inputs to classify targets and prioritize engagement sequences. French and German mechanized units are fielding these capabilities in reconnaissance variants ahead of main battle tank integration.
The EU F-Gas Regulation is constraining refrigerant choices for vehicle environmental control systems. Defense contractors are retrofitting cooling loops with lower-global-warming-potential alternatives or abandoning vapor-compression architectures for liquid-cooled thermal management. Infantry fighting vehicles with sealed NBC protection are experiencing the tightest specification pressure.
Consolidated framework contracting is concentrating buyer power. National defense ministries are pooling procurement authority through the European Defence Agency's joint capability development mechanisms. Suppliers now face single-negotiation entry points for multi-country vehicle fleets, compressing margin structures while extending contract durations.
Europe Armored Fighting Vehicles Market Segmentation
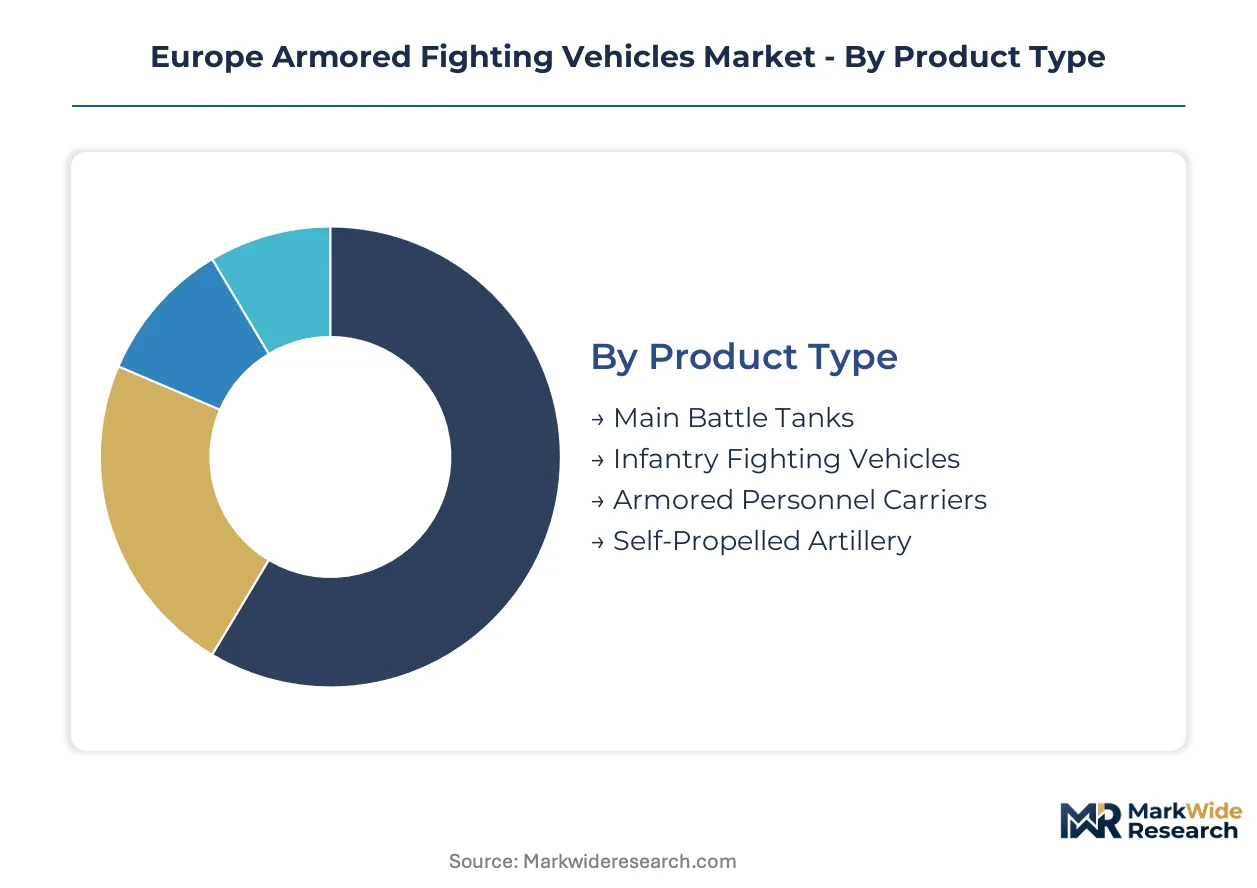
Segmentation in armored fighting vehicles separates procurement cycles measured in decades from upgrade pathways cycling every 5-7 years. Understanding these velocity differences helps suppliers align R&D portfolios with actual revenue timing.
Product Type:
Tracked platforms exhibit the widest lifecycle variance, with main battle tanks enduring 30-40 year service spans while lighter wheeled variants turn over faster in expeditionary roles.
- Main Battle Tanks:Heavy tracked platforms integrating 120-140mm smoothbore guns with composite armor arrays and turbine or diesel powerpacks. Poland and Germany are concentrating procurement authority around next-generation replacements as Leopard 2 and T-72 derivatives age out.
- Infantry Fighting Vehicles:Tracked or wheeled platforms carrying 6-8 dismounts with 25-40mm autocannon turrets and missile integration hardpoints. Baltic states are accelerating mechanized infantry procurement under NATO's enhanced forward presence framework.
- Armored Personnel Carriers:Protected mobility platforms optimized for troop transport with lighter armament and modular armor kits. Romanian and Bulgarian fleet gaps are pulling Eastern European demand.
- Self-Propelled Artillery:Tracked chassis mounting 155mm howitzers with automated loading and fire control systems. NATO STANAG 4439 ammunition compatibility requirements are shaping procurement specifications.
Infantry fighting vehicles anchor the volume base while active protection system integration in main battle tanks gains share at the steepest rate.
Technology:
Cost tiers separate mature mechanical systems from digitally intensive subsystems commanding premium pricing and shorter obsolescence windows.
- Hybrid Power:Battery-electric and fuel-cell auxiliary systems enabling silent-watch operations and reduced thermal signatures. German industrial bases are piloting series-hybrid architectures for reconnaissance variants.
- Counter-IED Systems:Electronic jamming and signature reduction technologies protecting against roadside explosive threats. French expeditionary forces are mandating these for wheeled vehicle deployments.
- Active Protection Systems:Hard-kill interceptors and soft-kill decoys defeating anti-tank guided missiles and rocket-propelled grenades. Polish territorial defense investments are prioritizing APS retrofit programs.
- Communication Systems:Software-defined radios and tactical data links enabling network-centric warfare. EU Green Deal procurement standards are constraining power and thermal budgets for these digital architectures.
Communication systems anchor installed base revenue while hybrid power expands most quickly as fuel logistics constraints intensify.
End User:
Customer type determines specification authority, with sovereign defense ministries retaining design control while pooled procurement concentrates buyer leverage.
- Defense Forces:National armies defining platform requirements through domestic industrial participation mandates. Polish mechanized brigade modernization exemplifies sovereign procurement authority.
- NATO Forces:Allied command structures coordinating multi-national fleet standardization through framework nation concepts. Baltic states are pooling requirements under enhanced forward presence mechanisms.
- Government Agencies:Border security and internal security forces operating lighter protected mobility platforms. EU Green Deal sustainability scoring is altering qualification thresholds.
- Private Security Contractors:Commercial operators acquiring surplus or downgraded platforms for site protection and convoy escort. Romanian and Bulgarian secondary markets are supplying these channels.
Defense forces anchor procurement volume while NATO forces are climbing the fastest as collective defense spending accelerates.
Installation:
Supply concentration varies sharply, with factory integration capturing high-value integration work while distributed maintenance networks strain skilled labor availability.
- Factory Integration:Original manufacturing and major variant production at prime contractor facilities. German and Swedish armor plate mills are constraining surge capacity for hull fabrication.
- Field Deployment:Forward-based assembly and operational configuration in theater. NATO's eastern flank expansion is compressing deployment timelines.
- On-Site Maintenance:Unit-level repair and component replacement at military installations. Certified armored vehicle welder shortages across Central Europe are limiting throughput.
- Off-Site Maintenance:Depot-level overhaul and lifecycle extension at specialized facilities. British long-term availability contracts are shifting revenue toward through-life support models.
Factory integration captures value concentration while on-site maintenance faces the steepest expansion constraints from skilled labor scarcity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across Europe diverge sharply between NATO's eastern flank states pursuing territorial defense modernization and western European forces emphasizing expeditionary sustainability requirements under EU Green Deal procurement standards.
Germany
Berlin's framework nation role for NATO's enhanced forward presence drives main battle tank and infantry fighting vehicle procurement coordination. The KBA and federal procurement office enforce EU Green Deal sustainability scoring on defense tenders. Rheinmetall AG anchors tracked vehicle production from its Düsseldorf industrial base, supplying hull armor from German high-hardness steel mills.
Poland
Warsaw's mechanized brigade modernization program represents Europe's largest tracked vehicle procurement pipeline. The Polish Ministry of Defence applies NATO STANAG certification requirements while prioritizing active protection system integration. Poznań and Świętoszów host final assembly and testing facilities for territorial defense platforms.
France
Paris maintains sovereign design control through cross-border KNDS N.V. production integration with Belgium. The ANSM and DGA coordinate CE marking and military qualification standards for armored platforms. Roanne and Bourges concentrate final integration work for expeditionary wheeled vehicle variants.
United Kingdom
London's shift toward long-term availability contracts restructures revenue timing for British Army platform support. The Ministry of Defence applies NATO STANAG 4439 ammunition compatibility mandates. Newcastle and Telford sustain Challenger platform overhaul capacity through BAE Systems PLC depot relationships.
Romania
Bucharest's Soviet-era fleet obsolescence creates replacement demand without domestic manufacturing capacity. The national defense procurement agency aligns specifications with NATO interoperability requirements. Craiova and Bucharest host maintenance facilities dependent on foreign prime contractor technical support.
Europe Armored Fighting Vehicles Market Competitive Landscape
Capability concentration sits with prime contractors commanding ballistic certification authority and armor supply relationships; scale advantage sits with diversified industrial conglomerates integrating cross-border production networks. The vendor base organizes around three archetypes: sovereign production champions retaining domestic hull fabrication, transnational consortium players pooling design authority across borders, and systems integrators specializing in electronics and active protection retrofit. Consolidation pressures intensify through framework nation contracting and European Defence Agency joint capability development mechanisms.
Among German-based industrial champions, Rheinmetall AG exemplifies sovereign production retention through captive armor plate supply and tracked vehicle refurbishment dominance. KNDS N.V. represents the transnational consortium model, anchoring Franco-Belgian supply chain integration. BAE Systems PLC occupies a position as a systems integrator sustaining British Army platform support through availability-based contracting rather than capital sale economics.
| Leading Market Players |
|---|
| KNDS N.V. |
| Krauss-Maffei Wegmann |
| BAE Systems PLC |
| Oshkosh Corporation |
| Patria |
| Rheinmetall AG |
| Iveco Defence Vehicles |
| ARQUUS Defense |
| General Dynamics Corporation |
| Others |
Supply & Pricing Matrix
Undercapacity at German and Swedish high-hardness steel mills is compressing hull fabrication throughput and amplifying pricing power for armor plate suppliers serving NATO eastern flank procurement surges. This utilization squeeze feeds forward into prime contractor bidding postures and ministry tender scoring weights.
Pricing Analysis
Long-term availability contracts dominate British and French defense procurement, displacing capital sale economics and restructuring revenue timing toward through-life service streams. Price differentiation hinges on NATO STANAG certification tier and active protection system integration depth, with premium positioning commanding extended performance guarantees. Cost compression in base vehicle tiers is intensifying as framework nation contracting pools buyer leverage across multi-country fleets. Government agencies and border security forces exhibit the sharpest price sensitivity, while sovereign defense ministries prioritize capability assurance over unit economics.
Supply Chain Analysis
Tariff exposure between European armor plate mills and Polish final assembly facilities dominates supply chain risk calculus for eastern flank modernization programs. Geographic supply concentration centers on Germany and Sweden for high-hardness steel, France and Belgium for turret integration, and the United Kingdom for powerpack refurbishment. Raw material dependencies encompass chromium alloys, ceramic armor arrays, and rare-earth elements for electro-optical subsystems. Single-source vulnerability in certified armored vehicle welding labor constrains surge capacity. Distribution runs through prime contractor depot networks and NATO maintenance and repair organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
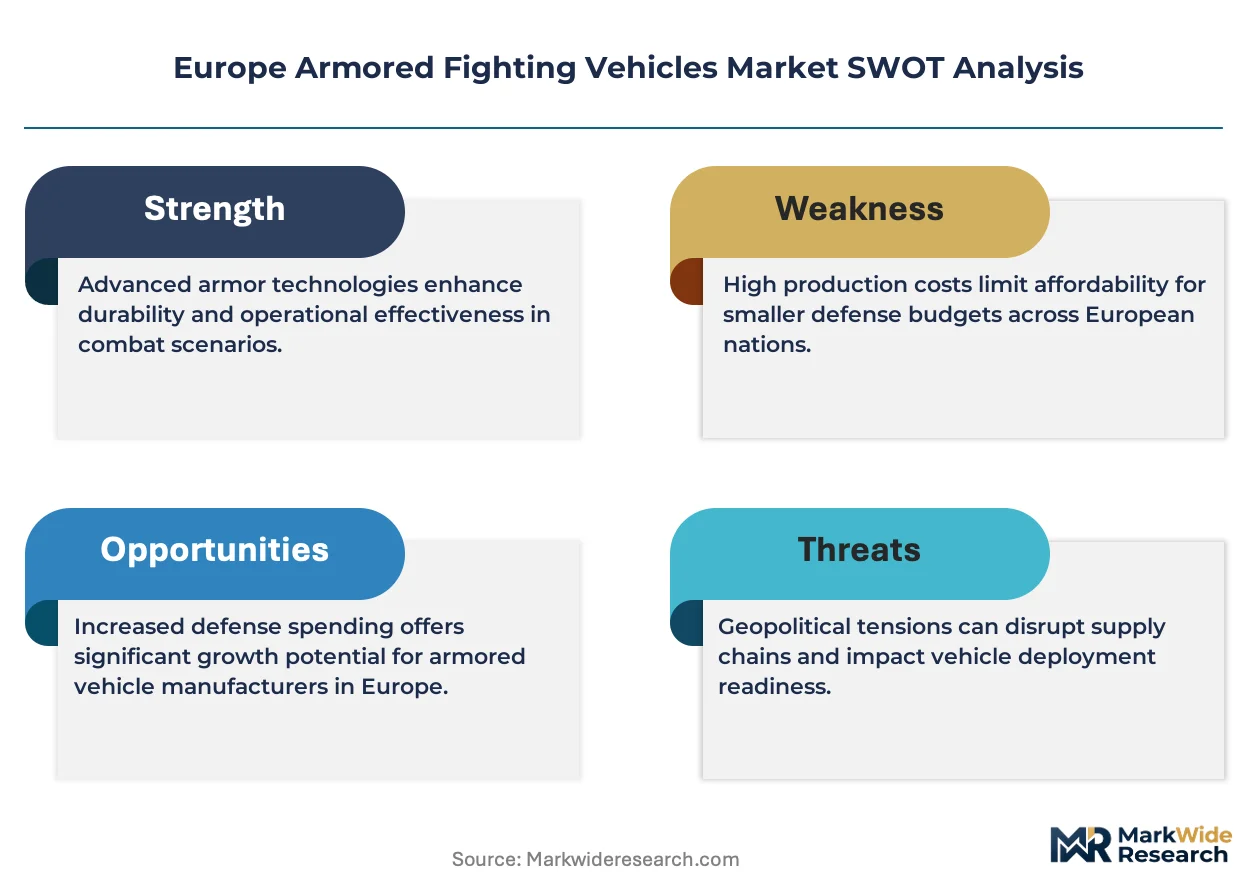
Certified armored vehicle welder attrition outpaces Central European apprenticeship pipelines, creating a structural chokepoint that determines which suppliers can execute surge contracts. This skill scarcity reshapes competitive boundaries and consolidation incentives across the European defense industrial base.
For Market Incumbents: Entrench ballistic certification authority through captive armor plate supply relationships and NATO STANAG validation infrastructure. Deepen upstream control over high-hardness steel milling capacity in Germany and Sweden to defend against emerging consortium bids. Prioritize active protection system integration R&D as the primary margin expansion lever against commoditized base vehicle competition. For New Entrants and Emerging Players: Establish a beachhead in Romanian and Bulgarian fleet replacement programs where Soviet-era platform obsolescence outruns domestic manufacturing capacity. Target active protection system retrofit and digital architecture upgrade segments rather than clean-sheet hull fabrication. Pursue subcontractor relationships with KNDS N.V. or Rheinmetall AG as the fastest path to NATO qualification credibility. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among depot-level maintenance specialists holding long-term availability contracts with British and French defense ministries. Long-term viability favors suppliers with captive armor supply and certified welding pipelines across the projection horizon. Acquisition targets should demonstrate framework nation contracting access and hybrid powertrain development portfolios. Watch Polish mechanized brigade procurement award timing as the signal for eastern flank demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Active Protection System Integration | Hard-kill and soft-kill APS retrofit extends platform survivability against shaped-charge threats for Polish territorial defense investments. |
| Hybrid Powertrain Development | Battery-electric auxiliary systems enable silent-watch operations while satisfying EU Green Deal procurement sustainability scoring requirements. |
| Long-term Availability Contracting | Through-life support models shift revenue timing and lock out competitors from British Army Challenger platform maintenance access. |
| Cross-border Production Integration | Franco-Belgian supply chain consolidation through KNDS N.V. pools design authority and compresses competitor margin structures. |
| Certified Welder Pipeline Investment | Central European apprenticeship programs address skilled labor scarcity constraining on-site maintenance throughput for NATO eastern flank deployments. |
Research Methodology
Desk research of NATO procurement databases, EU defense industrial policy filings, and national ministry tender announcements preceded structured interviews with platform program managers, armor systems engineers, defense procurement officers, and depot maintenance directors. Secondary validation drew from European Defence Agency capability development reports, STANAG certification registries, and customs trade data on high-hardness steel shipments. Bottom-up platform delivery forecasts were triangulated against top-down defense spending projections across the analysis window.
Assumption sets held NATO eastern flank threat perceptions and EU Green Deal procurement standards fixed while varying Polish mechanized brigade modernization pacing and German steel mill capacity utilization rates. Segmentation dimensions modeled encompass platform type, technology tier, end-user category, and installation mode alongside hybrid powertrain adoption curves. CAGRs were derived from regression analysis of historical procurement cycles and policy-driven demand step-changes. Industry-specific inputs included F-Gas Regulation compliance cost trajectories and active protection system fielding timelines.
Stress conditions across armor plate supply bottlenecks, skilled welder attrition rates, and NATO STANAG certification backlogs were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding framework nation contracting consolidation and sustainability-linked tender scoring evolution. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Armored Vehicles
Armored Vehicle Fire Suppression Systems Market
Armored Vehicles
US Armored Vehicle Market
Armored Vehicles
Asia-Pacific Armored Fighting Vehicles Market
Armored Vehicles
Global Ceramic Armor Market
Armored Vehicles
Armored Personnel Carrier Market
Armored Vehicles
North America Armored Fighting Vehicles Market
Armored Vehicles
Boom Arms Market
Armored Vehicles
Armored Vehicles Upgrade and Retrofit Market
Armored Vehicles
Armored Vehicle Navigation Systems Market
Armored Vehicles
Military Armored Car Market
Armored Vehicles
Armored Fighting Vehicles Market
Armored Vehicles
Armoured Personnel Carrier (APC) Market
Armored Vehicles
Middle-East and Africa Armored Vehicles Market
Armored Vehicles
Armored Vehicle Procurement and Upgrade Market
Armored Vehicles
Armor Protection Systems Market
Armored Vehicles
Armored Vehicles Market