
 India Combat Vehicle Systems Market | 2026-2036
India Combat Vehicle Systems Market Size, Share, and Industry Trends Forecast 2026-2036
India Combat Vehicle Systems Market Insights
Tamil Nadu is reshaping India's combat vehicle manufacturing geography through the Chennai-Coimbatore-Salem defence industrial corridor. Larsen & Toubro Defence anchors heavy fabrication and armored hull production at its Hazira and Sri City facilities. Tata Advanced Systems leverages its aerospace-electronics heritage to compete in turret systems and sensor integration. Bharat Forge Defence specializes in artillery and armored vehicle subsystems through its Pune and Satara forging complexes.
Combat vehicle systems encompass the integrated mechanical, electronic, and protective subsystems that enable armored platforms to execute ground warfare missions, including powerpacks rated for desert and high-altitude operation, composite armor packages, fire-control computers, and battlefield management terminals. Infantry Fighting Vehicles and Active Protection Systems represent the fastest-expanding demand pools, with the former driven by the Indian Army's requirement for tracked and wheeled platforms under 25-tonne class, and the latter attracting margin concentration as hard-kill and soft-kill countermeasures displace passive armor add-ons. Tanks retain the largest absolute value share but face elongated procurement cycles under the Defence Acquisition Procedure's higher-value clearance thresholds.
BIS certification requirements and CEA electrical safety standards shape subsystem qualification timelines for domestic suppliers, while the Ordnance Factory Board's corporatization into seven defence public sector undertakings restructures procurement interfaces. The PLI scheme for specialty steel and high-performance alloys tightens upstream material access, forcing private integrators to deepen vendor development programs. Stakeholders must monitor how the Defence Acquisition Procedure's iDEX and Make-II categories redirect prototype-to-production funding toward non-traditional entrants.
Market Dynamics
The Defence Acquisition Procedure's iDEX and Make-II funding categories are redirecting prototype-to-production flows toward non-traditional entrants, fragmenting incumbent supplier relationships while accelerating domestic subsystem qualification timelines under BIS certification mandates.
Growth Catalysts
- Active Protection Systems demand:Hard-kill and soft-kill countermeasures displace passive armor add-ons across mechanized infantry platforms, concentrating margins in electronic warfare and sensor fusion subsystems.
- PLI scheme for specialty steel:The production-linked incentive tightens upstream material access for high-performance alloys, forcing integrators to deepen vendor development programs and captive forging investments.
- Tamil Nadu industrial corridor concentration:The Chennai-Coimbatore-Salem defence corridor aggregates foundry, electronics, and systems integration capacity, shortening subsystem logistics loops for armored hull and turret manufacturers.
Market Restraints
- Specialty steel input volatility:High-performance alloy prices fluctuate with nickel and chromium supply disruptions, compressing fabrication margins for hull and chassis producers.
- Ordnance Factory Board procurement interface:The corporatization into seven defence public sector undertakings creates transitional friction in long-term supply agreements and technical collaboration protocols.
- Passive armor substitution ceiling:Composite and reactive armor packages face weight constraints under 25-tonne platform specifications, limiting protection upgrades without powerpack displacement.
Strategic Opportunities
- Gujarat defence corridor expansion:The Ahmedabad-Vadodara cluster offers underutilized heavy fabrication capacity for powerpack and transmission system localization.
- Fire-control computer convergence:Artificial intelligence-enabled target recognition is hybridizing with existing ballistic calculation architectures, opening retrofit markets for legacy platform fleets.
- CEA electrical safety standard adoption:Compliance mandates for battlefield management terminals create first-mover advantage for domestic electronics integrators with certified production lines.
Industry Challenges
- Systems integration talent scarcity:Embedded software engineers with military-grade security clearance and real-time operating system experience command premium compensation, constraining program staffing.
- BIS certification timeline compression:Subsystem qualification cycles for composite armor and fire-control electronics extend 18-24 months, delaying platform integration milestones.
- Legacy platform interoperability:Battlefield management terminals must interface with Soviet-era communication protocols still operational in frontline armored units, complicating hardware-software stack design.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Combat Vehicle Systems Market |
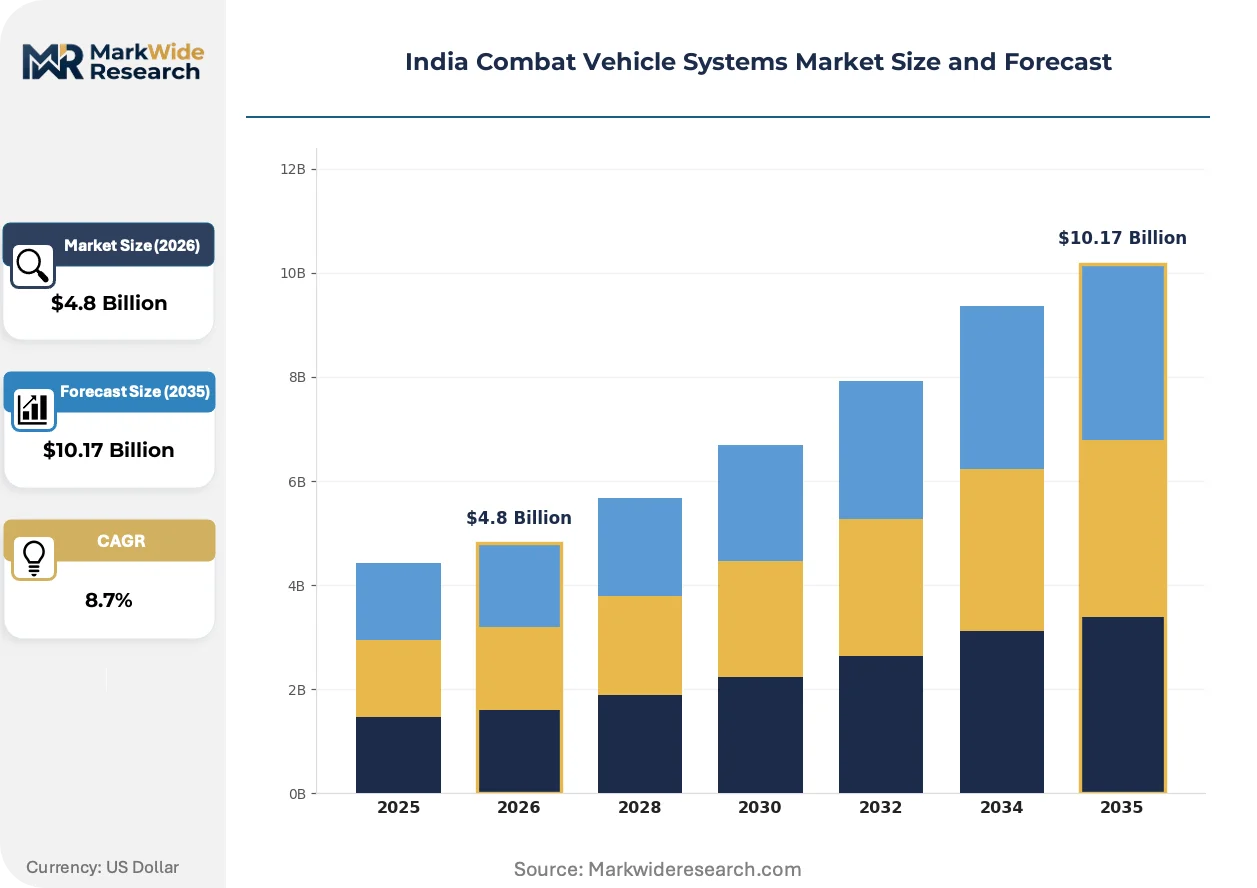
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tanks, Armored Personnel Carriers, Infantry Fighting Vehicles, Reconnaissance Vehicles Technology: Active Protection Systems, C4ISR, Hybrid Technology, Autonomous Systems End User: Military, Paramilitary Forces, Defense Contractors, Government Agencies Application: Ground Operations, Surveillance, Combat Support, Logistics |
| Companies Covered | Larsen & Toubro Defence, Tata Advanced Systems, Bharat Electronics Limited, Mahindra Defence Systems, Bharat Forge Defence, Ashok Leyland Defence, Kalyani Strategic Systems, Alpha Design Technologies, Ordnance Factory Board, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Combat Vehicle Systems Market Trends and Innovations
Active protection technologies and indigenous electronics qualification are compressing procurement cycles while elevating software-defined functionality in traditionally hardware-centric armored platforms.
Active Protection Systems is hybridizing kinetic interceptors with directed-energy countermeasures to defeat tandem-charge anti-tank munitions. The Indian Army's mechanized infantry directorate prioritizes these platforms for high-altitude and desert deployment zones. This convergence is collapsing the traditional separation between armor and electronic warfare procurement categories.
The PLI scheme for specialty steel and high-performance alloys mandates minimum domestic value addition thresholds for alloy melting and forging operations. Defence public sector undertakings must now source billet and bar stock from certified domestic melt shops, restructuring tier-2 supplier bases. Gujarat and Tamil Nadu foundries capture disproportionate qualification volume under this geographic concentration.
Buyer concentration within the Army's Directorate of Mechanized Forces compresses negotiation cycles and elevates technical specification influence. Single-source negotiations for Infantry Fighting Vehicle programs displace competitive bidding for subsystems above threshold values. This shift concentrates risk with prime integrators while accelerating design-to-field timelines for urgent operational requirements.
India Combat Vehicle Systems Market Segmentation
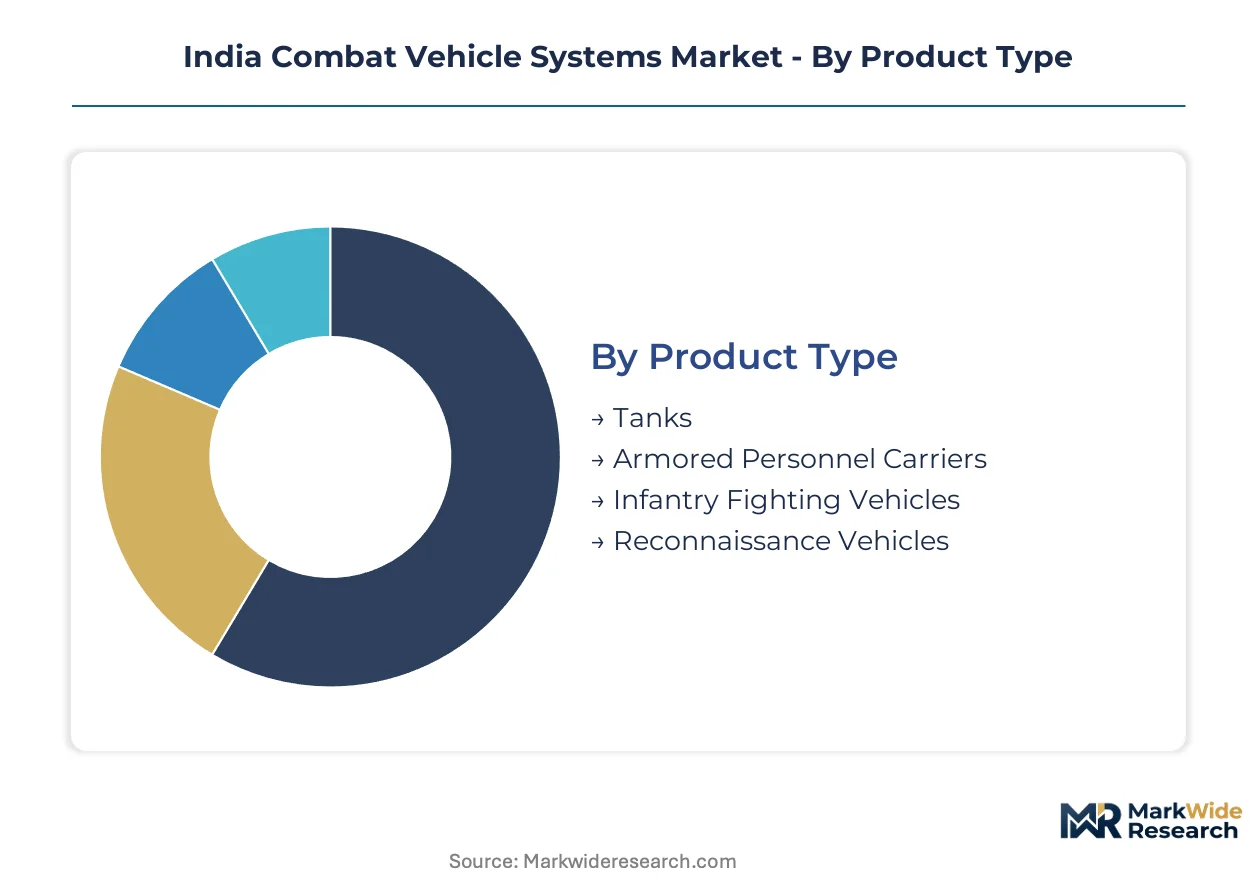
Combat vehicle systems procurement in India fragments across platform generations, mission profiles, and indigenization mandates. The Indian Army's mechanized modernization drives demand concentration in tracked and wheeled platforms under 25-tonne specifications, while Defence Acquisition Procedure reforms redirect contract flows toward domestic subsystem integrators.
Product Type:
Platform weight classes and armor configurations span desert, high-altitude, and urban warfare use-case spectrums.
- Tanks:Main battle platforms with composite and reactive armor packages rated for frontal arc protection against tandem-charge munitions. Procurement concentrates under the Army's Directorate of Mechanized Forces, though elongated clearance timelines under higher-value Defence Acquisition Procedure thresholds constrain program velocity.
- Infantry Fighting Vehicles:Tracked and wheeled configurations under 25-tonne class with integrated turret systems and dismount capacity. Tamil Nadu and Gujarat defence corridors capture hull and powerpack fabrication demand driven by the Army's urgent operational requirements for high-altitude deployment zones.
- Armored Personnel Carriers:Protected mobility platforms for troop transport and medical evacuation roles. BIS certification timelines for ballistic-grade steel hulls extend subsystem qualification cycles for private integrators competing with defence public sector undertakings.
- Reconnaissance Vehicles:Light armored platforms with sensor mast integration for forward observation missions. CEA electrical safety standards for battlefield management terminals shape electronics supplier selection in this category.
Established volume favors Tanks; emerging adoption favors Infantry Fighting Vehicles.
Technology:
Cost tiers separate legacy mechanical systems from software-defined electronic warfare architectures requiring cleared engineering talent.
- Active Protection Systems:Hard-kill interceptors and soft-kill countermeasures displacing passive armor add-ons across mechanized platforms. Demand concentrates in electronic warfare and sensor fusion subsystems as the Army prioritizes protection-to-weight ratios for high-altitude operations.
- C4ISR:Command, control, communications, computers, intelligence, surveillance and reconnaissance integration for networked ground warfare. The PLI scheme for specialty steel and high-performance alloys tightens upstream access for chassis producers while software stacks face systems integration talent scarcity.
- Hybrid Technology:Powerpack architectures combining diesel prime movers with electric traction motors for silent watch and reduced thermal signature. BIS certification for high-voltage electrical systems extends prototype-to-production timelines.
- Autonomous Systems:Unmanned ground vehicle platforms and remote turret operation for crewed-uncrewed teaming. DGFT export control classifications for dual-use navigation and AI components constrain subsystem sourcing.
Margin concentration sits with Active Protection Systems; qualification complexity peaks with Autonomous Systems.
End User:
Customer type determines specification authority, funding source, and indigenization mandate intensity.
- Military:The Indian Army's mechanized infantry directorate dominates platform procurement with single-source negotiation authority for urgent operational requirements. Defence Acquisition Procedure iDEX and Make-II categories redirect prototype funding toward non-traditional subsystem entrants.
- Paramilitary Forces:Internal security and border patrol applications drive demand for lighter, road-mobile armored platforms with reduced logistics footprints. Procurement operates under separate budgetary lines with faster clearance thresholds.
- Defense Contractors:Prime integrators and tier-1 suppliers competing for subsystem contracts under corporatized defence public sector undertaking procurement interfaces. Vendor development programs deepen as PLI scheme domestic value addition mandates tighten material access.
- Government Agencies:Research and development funding through DRDO and iDEX for technology demonstration platforms. Make-II category projects elevate non-traditional entrants in fire-control computer and sensor fusion domains.
Procurement volume concentrates with Military; contract velocity favors Paramilitary Forces.
Application:
Mission profile dictates platform mobility, protection level, and electronics payload requirements.
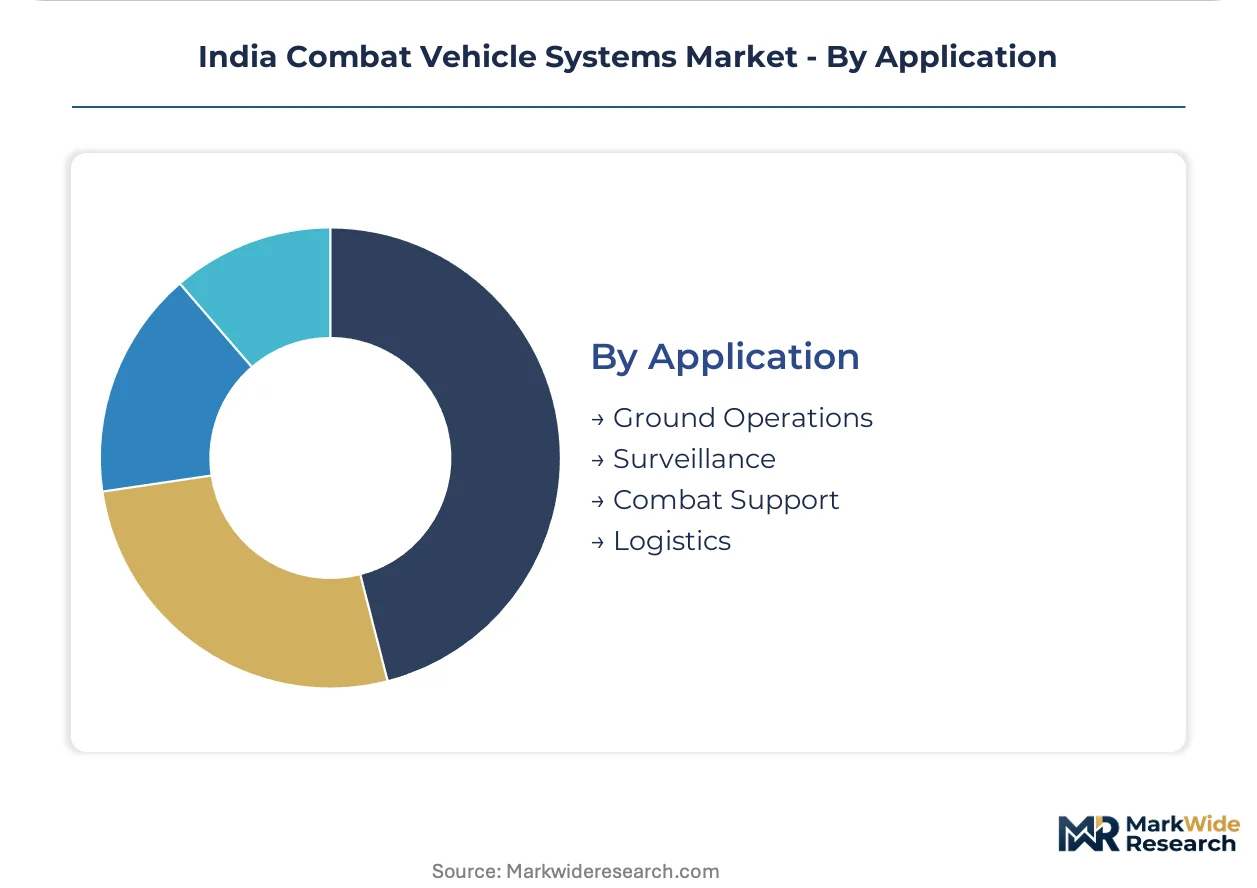
- Ground Operations:Direct fire and maneuver warfare platforms with highest armor and powerpack specifications. The 25-tonne weight ceiling for air-portable deployment constrains protection upgrades without powerpack displacement.
- Surveillance:Sensor-rich platforms with mast-mounted electro-optical and radar systems for persistent area monitoring. CEA electrical safety compliance creates first-mover advantage for certified domestic electronics integrators.
- Combat Support:Engineering vehicles, recovery platforms, and ammunition carriers operating behind forward edge of battle areas. Ordnance Factory Board corporatization creates transitional friction in long-term supply agreements for specialized chassis.
- Logistics:Protected cargo and fuel transport platforms with reduced armor requirements. Gujarat defence corridor foundries capture disproportionate hull fabrication volume for this application tier.
Platform complexity peaks with Ground Operations; production scale concentrates with Logistics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foundry capacity and electronics integration clusters concentrate in Gujarat and Tamil Nadu, where defence industrial corridors aggregate subsystem suppliers for armored hull and turret manufacturers. The Ordnance Factory Board's corporatization into seven defence public sector undertakings redistributes procurement interfaces across state-level production facilities.
Gujarat
Ahmedabad-Vadodara corridor anchors heavy fabrication for powerpack and transmission systems under the state's defence manufacturing policy. PLI scheme incentives for specialty steel draw forging investments into the region. Hazira-based facilities capture armored hull production volume for mechanized infantry platforms.
Tamil Nadu
Chennai-Coimbatore-Salem corridor concentrates foundry, electronics, and systems integration capacity for turret and sensor manufacturers. CEA electrical safety standards shape battlefield management terminal qualification timelines for domestic integrators. Sri City facilities shorten logistics loops between hull fabrication and electronics payload integration.
Maharashtra
Pune and Satara forging complexes specialize in artillery and armored vehicle subsystems for prime integrators. BIS certification requirements for composite armor packages extend qualification cycles for tier-2 suppliers. The state's automotive component ecosystem feeds powerpack and transmission vendor development programs.
Karnataka
Bengaluru's aerospace-electronics heritage supports fire-control computer and sensor fusion subsystem development. iDEX and Make-II funding categories redirect prototype-to-production flows toward non-traditional entrants in the state. DGFT export control classifications for dual-use navigation components constrain sourcing for autonomous systems developers.
Haryana
Delhi-NCR proximity enables systems integration talent access for embedded software engineers with security clearance. The Army's Directorate of Mechanized Forces maintains procurement specification authority from nearby headquarters. Ordnance Factory Board transitional friction affects long-term supply agreements for specialized chassis producers in the region.
India Combat Vehicle Systems Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in forging, electronics, and armor subsystems. The supplier base fragments across defence public sector undertakings, diversified industrial conglomerates, and emerging tier-2 specialists. Three archetypes dominate: prime integrators with captive fabrication, component specialists with BIS-certified production lines, and technology entrants leveraging iDEX funding pathways. Competitive moves concentrate on vendor development program expansion and captive forging investments under PLI scheme mandates.
Among diversified industrial conglomerates, Larsen & Toubro Defence and Tata Advanced Systems occupy positions spanning heavy fabrication through electronics integration. Bharat Forge Defence exemplifies the component specialist archetype with forging-focused positioning. These three anchors represent distinct competitive vectors: systems integration breadth, aerospace-electronics heritage, and metallurgical specialization respectively.
| Leading Market Players |
|---|
| Larsen & Toubro Defence |
| Tata Advanced Systems |
| Bharat Electronics Limited |
| Mahindra Defence Systems |
| Bharat Forge Defence |
| Ashok Leyland Defence |
| Kalyani Strategic Systems |
| Alpha Design Technologies |
| Ordnance Factory Board |
| Others |
Pricing and Supply Chain Analysis
Specialty steel melt shops concentrated in Gujarat and Tamil Nadu defence corridors anchor margin distribution across hull fabrication, powerpack assembly, and electronics integration tiers. The PLI scheme's domestic value addition thresholds compress pricing flexibility for integrators while elevating returns for certified upstream suppliers.
Pricing Analysis
BIS certification dictates the pricing tier structure across subsystem categories. Three-tier pricing separates BIS-certified armor packages from standard-grade hull steel and uncertified commercial alternatives. Cost compression in powerpack assemblies intensifies because nickel and chromium price volatility feeds directly into high-performance alloy billet costs. Paramilitary procurement channels exhibit the highest price sensitivity due to faster clearance thresholds and constrained budgetary lines, while military urgent operational requirements tolerate premium positioning for qualified subsystems.
Supply Chain Analysis
Tariff exposure between India and alloy source markets dominates supply chain risk calculus for chromium and nickel inputs. Foundry capacity concentrates in India, South Korea, and Japan for specialized armor-grade steel production. The ecosystem draws from domestic billet melting, imported high-purity chromium, and captive forging operations for critical chassis components. Single-source vulnerability in high-voltage electrical systems for hybrid powerpacks constrains platform integration timelines. Distribution runs through defence public sector undertaking procurement interfaces and direct prime integrator contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Active Protection Systems threaten to displace traditional armor packages across mechanized platforms, forcing incumbents to defend subsystem relevance through electronics qualification and software-defined functionality.
For Market Incumbents: Pre-empt passive armor substitution by accelerating fire-control computer convergence with AI-enabled target recognition architectures. Deepen captive forging investments in Gujarat to secure PLI scheme compliance and insulate against specialty steel input volatility. Lock in long-term supply agreements with corporatized defence public sector undertakings before transitional procurement interfaces stabilize. For New Entrants and Emerging Players: iDEX-funded prototype-to-production pathways in fire-control electronics and sensor fusion represent the most penetrable entry point for non-traditional subsystem developers. Target battlefield management terminal qualification under CEA electrical safety standards to capture first-mover certification advantage. Pursue Make-II category projects that bypass competitive bidding thresholds for urgent operational requirements. For Investors and Strategic Acquirers: Capital is best deployed toward BIS-certified component specialists with captive metallurgical capacity and established defence public sector undertaking supply relationships. Long-term viability hinges on sustained indigenization mandate intensity and the Army's mechanized modernization program velocity. Monitor Defence Acquisition Procedure threshold adjustments as the primary inflection signal for contract flow redirection.| Strategic Initiative | Industry Significance |
|---|---|
| Active Protection System Integration | Hard-kill and soft-kill countermeasures displace passive armor across 25-tonne platforms under Army mechanized directives. |
| Captive Forging Investment | Gujarat and Tamil Nadu facilities secure PLI scheme compliance for high-performance alloy domestic value addition thresholds. |
| Fire-Control Computer Convergence | AI-enabled target recognition hybridization opens retrofit markets for legacy Soviet-era platform fleets. |
| BIS Certification Acceleration | Compressed 18-24 month qualification cycles for composite armor and electronics enable faster platform integration milestones. |
| Vendor Development Program Expansion | Tier-2 supplier base restructuring under corporatized defence public sector undertaking procurement interfaces tightens material access. |
Research Methodology
A standing panel of platform integration engineers, defence public sector undertaking procurement officers, BIS certification auditors, and Army Directorate of Mechanized Forces specification authorities provided ongoing calibration throughout the study. Primary fieldwork combined structured interviews with tier-1 subsystem suppliers and secondary validation through Defence Acquisition Procedure amendment records, PLI scheme administrative filings, CEA electrical safety standard documentation, and customs data on specialty steel alloy imports. Bottom-up segment sizing triangulated against top-down defence budget allocation analysis.
Scenario-bracketing around indigenization mandate intensity and mechanized modernization program velocity shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include platform weight class, protection system architecture, end-user procurement channel, and regional defence corridor concentration. CAGRs derived from subsystem qualification timeline compression, contract award velocity under iDEX and Make-II categories, and foundry capacity expansion trajectories. Industry-specific forecast inputs incorporated BIS certification backlog estimates and CEA electrical safety compliance adoption curves.
Practitioners should monitor PLI scheme threshold adjustments, Defence Acquisition Procedure category reclassifications, and active protection system field trial outcomes for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Vehicles
Indonesia Defense Market
Military Vehicles
Military Tank Container Market
Military Vehicles
Colombia Defense Market
Military Vehicles
Japan Defense Market
Military Vehicles
Riot Control Vehicle Market
Military Vehicles
Infantry Fighting Vehicle (IFV) Market
Military Vehicles
Robotic Combat Vehicle (RCV) Market
Military Vehicles
Military Unmanned Ground Vehicle Market
Military Vehicles
Global Military Vehicle Electrification Market
Military Vehicles
Middle East Military Vehicles Market
Military Vehicles
Military Trucks Market
Military Vehicles
Combat Support Vehicle Market
Military Vehicles
Amphibious Land Craft Market
Military Vehicles
Military Ground Robots Market
Military Vehicles
Taiwan Defense Market
Military Vehicles
Military Land Vehicles Market