
 Middle-East and Africa Armored Vehicles Market | 2026-2036
Middle-East and Africa Armored Vehicles Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Armored Vehicles Market Foresight
Law enforcement agencies and private security contractors are reorganizing procurement priorities across the Middle-East and Africa, shifting budget share from conventional military buyers toward internal security applications. NIMR Automotive leverages its UAE manufacturing base to dominate regional light armored vehicle exports. Streit Group sustains a broad product catalog spanning commercial armoring and tactical platforms for African peacekeeping missions. Paramount Group anchors its competitive position through integrated design-to-delivery capability for mine-resistant platforms.
Armored vehicles in the Middle-East and Africa encompass wheeled and tracked platforms engineered to withstand ballistic threats, improvised explosive devices, and harsh desert terrain, typically integrating steel or composite hulls with V-shaped undercarriages and blast-mitigating seating. These systems serve military combat operations, counter-insurgency patrols, VIP protection, and border surveillance across conflict-prone and high-threat environments. The light armored vehicle category leads volume demand due to versatility in urban counterterrorism and rapid deployment scenarios, while active protection systems represent the fastest-growing technology segment as operators prioritize survivability against anti-tank guided missiles. Ballistic armor remains the most mature technology dimension with established supply chains but thinning margins, whereas situational awareness systems concentrate margin pools through sensor fusion and software integration requirements.
Saudi Arabia's General Authority for Military Industries, the UAE's Tawazun Council, and Israel's Ministry of Defense shape procurement through local content mandates and offset requirements that redirect contract value toward domestic assembly. South Africa's National Conventional Arms Control Committee and Egypt's military production authorities impose export licensing frameworks that constrain technology transfer and cross-border sales. Stakeholders must monitor how Gulf sovereign defense industrial strategies reshape supplier qualification criteria and long-term partnership structures.
Market Dynamics
Active Protection Systems technology is bifurcating procurement strategies across Middle-East and Africa defense ministries, splitting budgets between legacy passive armor retrofits and next-generation integrated survivability suites that demand entirely new vehicle architectures and supplier relationships.
Growth Catalysts
- Border Security Modernization:Saudi Arabia, the UAE, and Israel are accelerating armored personnel carrier procurement to address intensified frontier surveillance requirements and cross-border threat vectors.
- Local Content Mandates:Tawazun Council offset requirements and SAMI joint venture structures redirect contract value toward domestic assembly lines, creating captive demand for regional manufacturing capacity.
- Counter-Insurgency Operations:Light armored vehicle demand concentrates in urban counterterrorism applications where rapid deployment and maneuverability outweigh heavy armor protection.
Market Restraints
- Steel and Composite Input Volatility:Ballistic-grade steel and ceramic composite prices fluctuate with energy costs, compressing margins on fixed-price government contracts.
- Technology Transfer Licensing:South Africa's National Conventional Arms Control Committee and Egypt's military production authorities impose export licensing frameworks that constrain cross-border component flows and intellectual property mobility.
- Active Protection System Complexity:Radar and electro-optical sensor integration demands specialized engineering talent scarce across the region, extending development timelines.
Strategic Opportunities
- East African Peacekeeping Infrastructure:African Union mission requirements in Somalia and the Sahel create demand for mine-resistant ambush-protected platforms with integrated medical evacuation configurations.
- VIP Protection Services:Commercial armoring for executive transport represents an underpenetrated segment as private security contractors expand fleet modernization programs.
- Situational Awareness Convergence:Sensor fusion software integrating thermal imaging, drone detection, and command-and-control interfaces commands premium positioning in procurement evaluations.
Industry Challenges
- Systems Integration Engineering:Retrofitting legacy vehicle hulls with Active Protection Systems requires extensive structural modification and power management reconfiguration.
- Certification Timeline Compression:Ballistic testing protocols and blast survivability validation extend qualification periods, delaying revenue recognition on development contracts.
- Supply Chain Reconfiguration:Local content mandates force prime contractors to qualify new sub-tier suppliers, introducing quality assurance risks and first-article inspection delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Armored Vehicles Market |
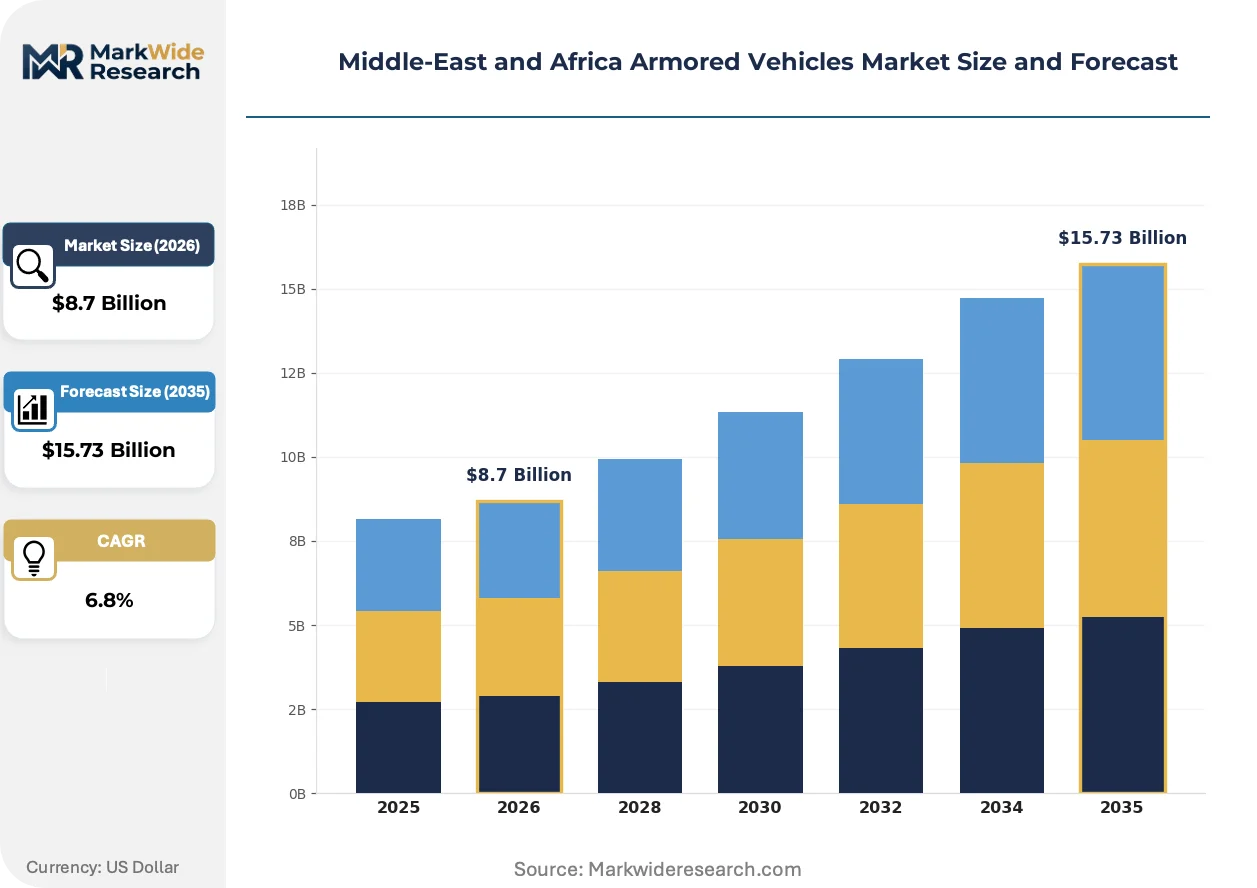
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Light Armored Vehicle, Main Battle Tank, Armored Personnel Carrier, Mine-Resistant Ambush Protected End User: Military, Law Enforcement, Security Agencies, Private Contractors Technology: Active Protection Systems, Situational Awareness Systems, Ballistic Armor, Communication Systems Distribution Channel: Direct Sales, Distributors, Online Sales, Others |
| Companies Covered | Mahindra Emirates Vehicle Armouring FZ-LLC, NIMR Automotive (EDGE Group PJSC), Streit Group, SAUDI ARABIAN MILITARY INDUSTRIES (SAMI), Paramount Group, Denel SOC Ltd, BAE Systems plc, Rheinmetall AG, Israel Aerospace Industries (IAI), Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Armored Vehicles Market Shifts & Advancements
Survivability technology is reshaping vehicle architecture decisions across Middle-East and Africa defense programs, with procurement authorities prioritizing integrated protection systems over incremental armor upgrades and demanding open-system standards for future sensor integration.
Active Protection Systems technology is bifurcating platform development pathways. These radar-directed countermeasure suites detect and neutralize incoming anti-tank guided missiles before impact. National military forces in Israel and the UAE are fielding these systems on new-build vehicles while deferring legacy fleet retrofits. This technology is bifurcating supplier ecosystems into integrated prime contractors capable of full-system delivery versus armor specialists confined to passive protection components.
Local content mandates issued by Saudi Arabia's General Authority for Military Industries and the UAE's Tawazun Council are restructuring qualification requirements. Foreign primes must now establish joint ventures or license production agreements to access major tenders. Main battle tank and armored personnel carrier programs are most affected, with Rheinmetall and SAMI partnerships establishing template structures for technology transfer compliance.
Contracting authorities are unbundling after-sales service from initial platform acquisition. Defense ministries now negotiate separate performance-based logistics agreements covering spare parts, depot maintenance, and obsolescence management. This pattern concentrates margin pools with integrators capable of multi-decade support commitments. Israel's Ministry of Defense and the UAE's military procurement directorates have pioneered this model in recent armored vehicle competitions.
Middle-East and Africa Armored Vehicles Market Segmentation
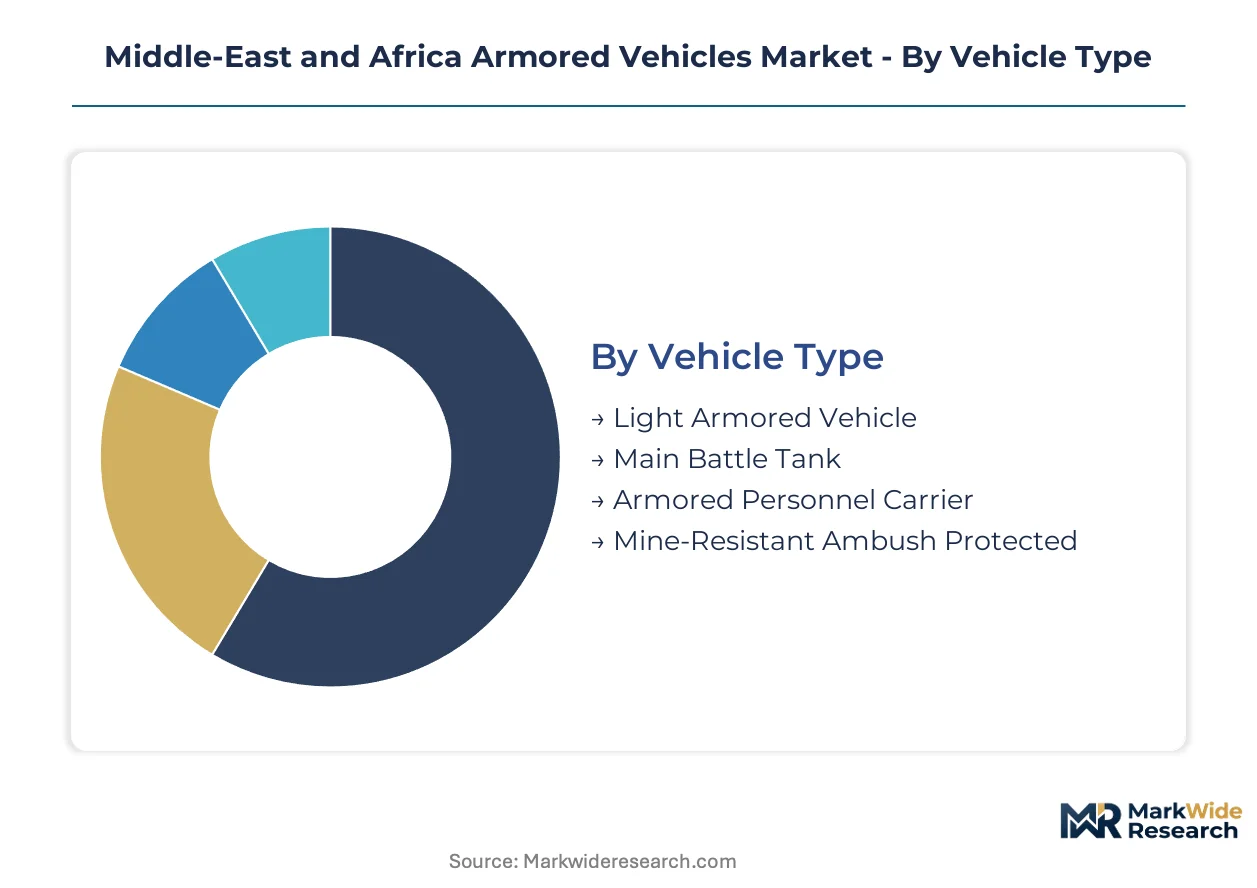
Segmentation in the Middle-East and Africa armored vehicles market reveals how procurement priorities diverge between heavy combat platforms and agile counter-insurgency systems. Understanding these splits exposes where defense budgets concentrate and which technology investments reshape fleet modernization timelines.
Vehicle Type:
Margin pools concentrate in platforms balancing survivability with rapid deployment capability, where integration complexity creates pricing power for systems integrators.
- Light Armored Vehicle:Wheeled platforms with modular armor packages dominate urban counterterrorism and rapid reaction missions. Saudi Arabia and the UAE prioritize these for border patrol and internal security, driving volume through Tawazun Council offset programs that mandate local assembly.
- Mine-Resistant Ambush Protected:V-shaped hulls with blast-deflecting geometries and suspended seating protect against improvised explosive devices in asymmetric warfare. East African peacekeeping missions in Somalia and the Sahel generate sustained demand for medical evacuation configurations.
- Main Battle Tank:Heavy tracked platforms with composite armor arrays serve conventional deterrence and armored breakthrough operations.
- Armored Personnel Carrier:Troop transport vehicles with medium protection levels support mechanized infantry deployment.
The dominant share belongs to Light Armored Vehicle, while Mine-Resistant Ambush Protected is closing the gap fastest.
End User:
Procurement authority fragmentation across national military hierarchies and internal security ministries creates distinct qualification pathways and contract structures.
- Military:National defense forces operate the largest fleet concentrations, with Israel's Ministry of Defense and Saudi Arabia's General Authority for Military Industries driving main battle tank and armored personnel carrier acquisitions through technology transfer mandates.
- Law Enforcement:Police tactical units and gendarmerie forces deploy light armored vehicles for riot control and high-risk warrant service, with Egypt's Interior Ministry expanding wheeled platform procurement.
- Security Agencies:Intelligence and presidential guard units require discreet armoring and advanced communication suites.
- Private Contractors:Executive protection firms and resource extraction security providers source commercial armoring for SUV and sedan conversions.
Military commands the largest budget allocation, though Law Enforcement is expanding procurement most aggressively.
Technology:
Revenue concentration shifts toward sensor integration and software-defined protection systems that require ongoing technical support contracts.
- Active Protection Systems:Radar-directed countermeasure suites intercept anti-tank guided missiles before hull impact. Israel and the UAE field these on new-build vehicles, bifurcating supplier ecosystems between integrated prime contractors and passive armor specialists.
- Situational Awareness Systems:Sensor fusion architectures integrating thermal imaging, drone detection, and command-and-control interfaces command premium positioning. These systems demand specialized engineering talent scarce across the region, extending development timelines.
- Ballistic Armor:Steel and ceramic composite arrays represent mature technology with established supply chains but compressing margins.
- Communication Systems:Secure voice and data networks enable networked warfare and blue-force tracking.
Ballistic Armor retains the largest installed base, yet Active Protection Systems is climbing the fastest as survivability priorities shift from passive to active defense.
Distribution Channel:
Contract value flows reflect sovereign procurement regulations that restrict intermediary participation in defense transactions.
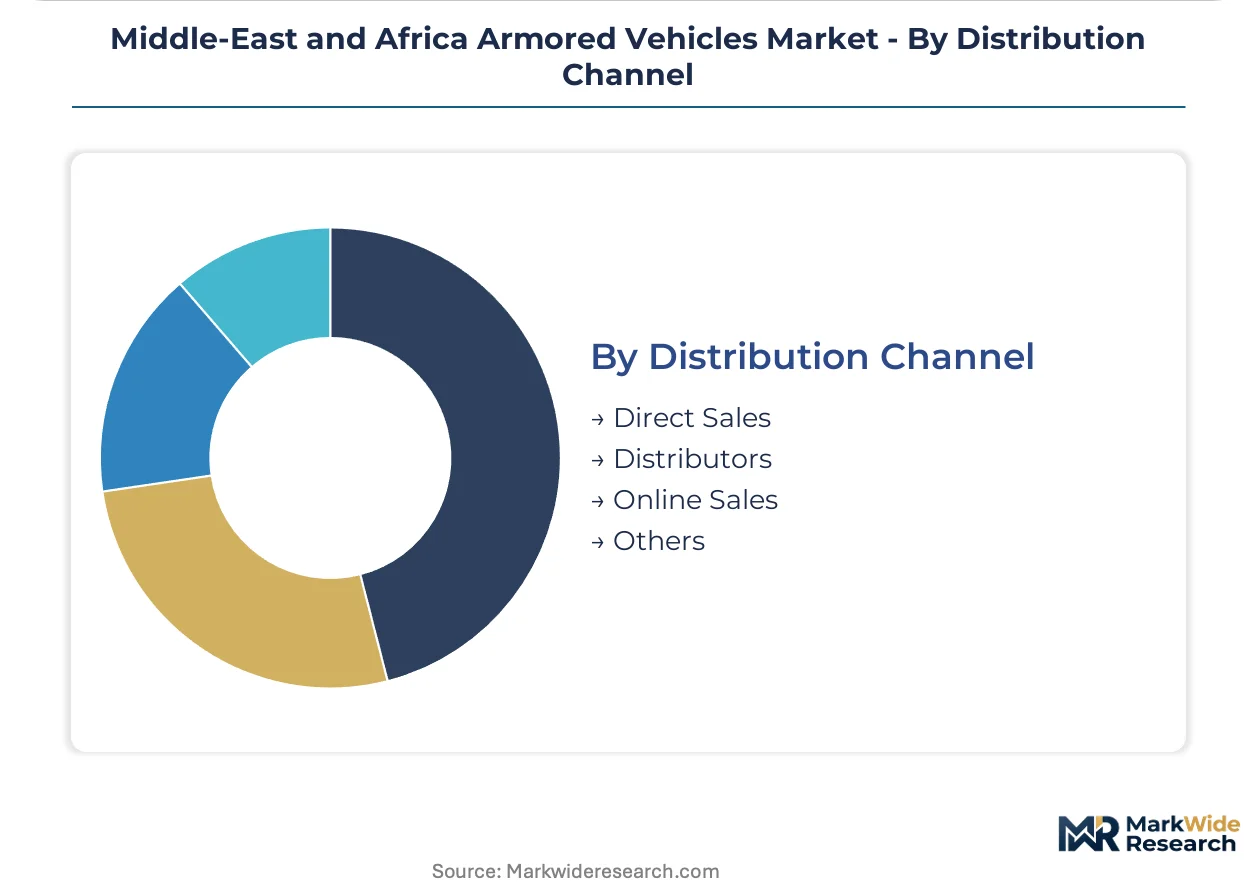
- Direct Sales:Prime contractors negotiate government-to-government agreements and foreign military sales channels, capturing full contract value without distributor margins. Saudi SAMI joint ventures and UAE Tawazun partnerships operate exclusively through this channel.
- Distributors:Authorized representatives facilitate spare parts and aftermarket service in markets with limited direct presence.
- Online Sales:Digital platforms support commercial armoring components and accessories.
- Others:Leasing arrangements and offset-driven joint ventures accommodate local content requirements.
Direct Sales dominates transaction value, while Distributors handle the widest geographic spread across fragmented African markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Red Sea corridor and Gulf maritime chokepoints armored vehicle logistics networks across the Middle-East and Africa. Saudi Arabia's King Abdullah Economic City port infrastructure and the UAE's Jebel Ali deep-water facilities enable heavy equipment transshipment to East African peacekeeping theaters.
Saudi Arabia
Border security modernization along the Yemeni frontier and Iraqi border drives armored personnel carrier demand. The General Authority for Military Industries enforces local content mandates requiring joint venture structures for foreign prime contractors. SAMI-Rheinmetall production lines in the King Salman Military Industries Complex near Riyadh manufacture main battle tank hulls under technology transfer agreements.
United Arab Emirates
Counter-insurgency patrol requirements in Yemen and internal security operations sustain light armored vehicle procurement. Tawazun Council offset requirements redirect contract value toward domestic assembly at NIMR Automotive facilities in Al Ain. EDGE Group's vertical integration strategy consolidates subsystem suppliers within Abu Dhabi's defense industrial zone.
Israel
Active Protection Systems fielding on new-build combat vehicles displaces passive armor retrofits across the legacy fleet. The Ministry of Defense procures through government-to-government channels that exclude distributor intermediaries. Israel Aerospace Industries and Rafael Advanced Defense Systems anchor the national defense cluster around Haifa's technology corridor.
South Africa
Mine-resistant platform exports to African Union peacekeeping missions generate sustained demand for blast-protected configurations. The National Conventional Arms Control Committee imposes export licensing frameworks that constrain cross-border component flows. Paramount Group's integrated design-to-delivery facility in Johannesburg supplies integrated survivability suites to East African operators.
Egypt
Mechanized infantry modernization programs sustain armored personnel carrier acquisitions for Sinai Peninsula operations. Military production authorities under the Ministry of Defense operate state-owned assembly lines that limit foreign prime contractor participation. The Cairo-Suez defense industrial corridor concentrates maintenance depot capacity for legacy Soviet-era fleet sustainment.
Middle-East and Africa Armored Vehicles Market Competitive Landscape
Concentration sits with sovereign-backed industrial groups and foreign prime contractors operating through mandated joint venture structures. The supplier ecosystem bifurcates between integrated system integrators capable of full-platform delivery and regional specialists confined to subsystem production or commercial armoring. Three archetypes dominate: state-owned defense industrial champions with captive domestic demand, European primes executing technology transfer compliance, and African specialists in mine-resistant platform integration. Competitive positioning depends on securing long-term performance-based logistics contracts and qualifying local assembly capacity under offset frameworks.
Within the sovereign-industrial champion tier, NIMR Automotive and SAMI exemplify the Gulf state model of defense localization. NIMR leverages its UAE manufacturing base to supply light armored vehicles across Tawazun Council-mandated procurement channels. SAMI represents Saudi Arabia's vertical integration ambition through Rheinmetall partnership structures. Paramount Group anchors the African specialist position with integrated mine-resistant platform capability.
| Leading Market Players |
|---|
| Mahindra Emirates Vehicle Armouring FZ-LLC |
| NIMR Automotive (EDGE Group PJSC) |
| Streit Group |
| SAUDI ARABIAN MILITARY INDUSTRIES (SAMI) |
| Paramount Group |
| Denel SOC Ltd |
| BAE Systems plc |
| Rheinmetall AG |
| Israel Aerospace Industries (IAI) |
| Others |
Supply & Pricing Matrix
Active Protection Systems displacement of passive armor configurations simultaneously redraws supply geography toward Israeli and Emirati sensor-integration clusters while compressing pricing power for legacy steel and composite suppliers locked into fixed-price government contracts. This substitution dynamic concentrates margin capture with systems integrators capable of radar and electro-optical fusion, leaving ballistic-grade material producers exposed to energy-cost volatility without pricing escalation clauses.
Pricing Analysis
Volume-discount tiering structures in Saudi SAMI and UAE Tawazun-mandated procurement channel contract value toward domestic assembly partners qualifying for offset credits. Three-tier pricing stratification separates integrated survivability suites with multi-decade performance-based logistics commitments from standard armored personnel carrier configurations and economy-grade retrofit packages for legacy fleet sustainment. Cost compression in ballistic armor tiers intensifies as ceramic composite and high-grade steel prices fluctuate with energy markets. Military end-users demonstrate lowest price sensitivity given technology transfer mandates, while private security contractors and African peacekeeping procurement authorities exhibit acute budget constraints.
Supply Chain Analysis
Strait of Hormuz transit underwrites heavy equipment logistics for armored vehicle hull transshipment from Saudi Arabia's King Abdullah Economic City and UAE's Jebel Ali facilities to East African theaters. Supply concentration centers on Germany for main battle tank powertrain systems, South Africa for mine-resistant platform engineering, and Israel for Active Protection Systems radar components. Ballistic-grade steel draws from European and Asian mills, ceramic composite armor feeds from specialized sintering facilities, and electro-optical sensors hinge on Israeli and Emirati integration houses. Single-source vulnerability concentrates in Active Protection Systems sensor fusion software where regional engineering talent scarcity extends qualification timelines. Distribution runs through government-to-government foreign military sales channels with distributor intermediaries excluded from prime contract value.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
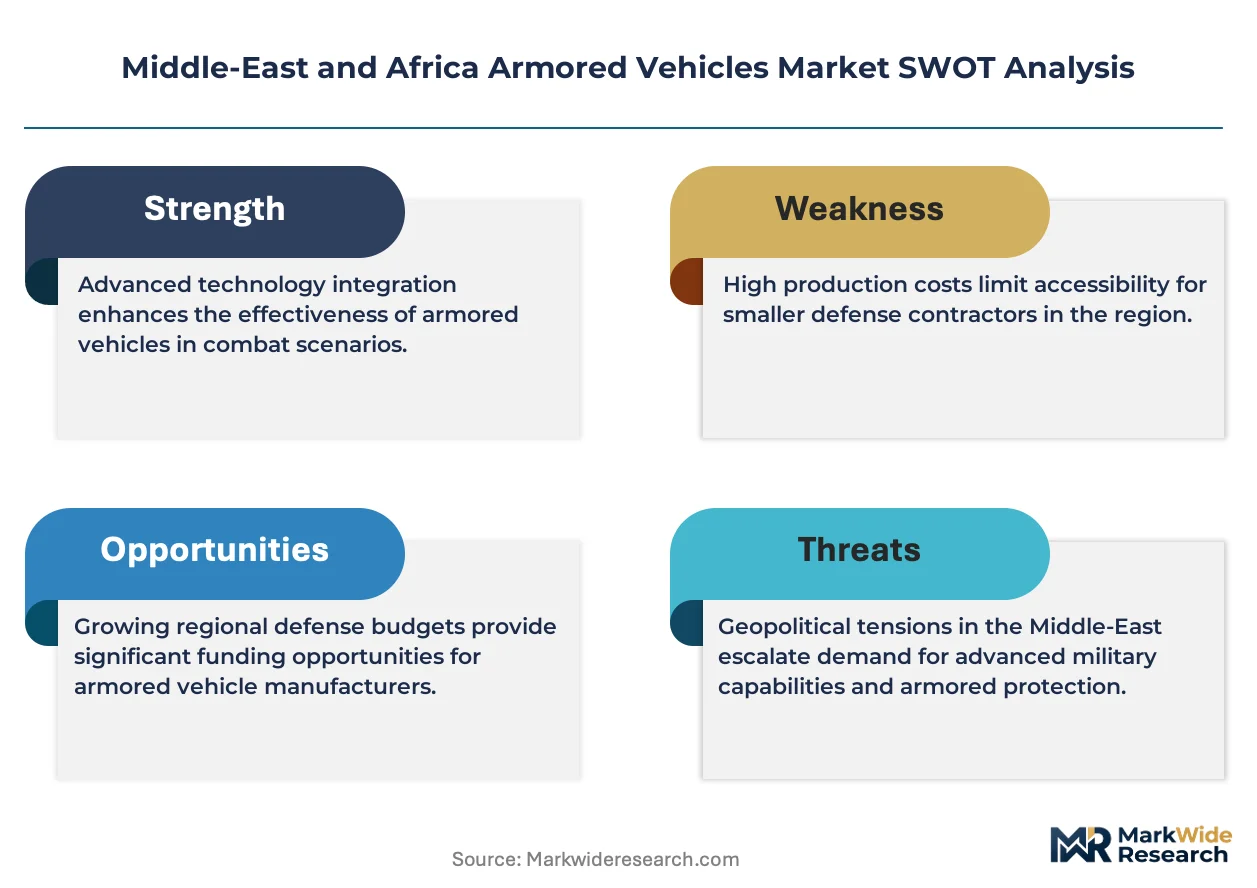
This market functions as a defensive-moat structure where regulatory entrenchment through local content mandates and offset requirements creates captive supplier relationships that resist displacement. Switching costs compound through multi-decade performance-based logistics agreements and joint venture equity structures that embed foreign primes within sovereign industrial ecosystems.
For Market Incumbents: Compound defensive positioning through backward integration into Active Protection Systems sensor production and captive supply of ballistic-grade composite materials. Rheinmetall-SAMI partnership structures demonstrate how technology transfer compliance creates multi-decade revenue visibility. Capacity addition in Saudi Arabia's King Salman Military Industries Complex and UAE's Al Ain defense zones captures Tawazun Council and General Authority for Military Industries procurement channels. Threat substitution from Israeli sensor-integration houses demands accelerated R&D in drone-detection fusion algorithms. For New Entrants and Emerging Players: Certification fast-track through African Union peacekeeping mission pre-qualification protocols offers the most penetrable entry vector for mine-resistant ambush-protected platform specialists. East African medical evacuation configurations represent white-space demand underserved by Gulf-centric production capacity. VIP protection services for executive transport fleets in Lagos, Nairobi, and Johannesburg provide commercial armoring revenue without sovereign procurement complexity. Go-to-market execution should anchor on paramilitary procurement officers and private security contractor fleet managers rather than defense ministry hierarchies. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed African defense specialists holding integrated design-to-delivery capability for blast-protected platforms. Five-to-ten year viability framing favors targets with established African Union mission supply relationships and performance-based logistics contract backlogs. Acquisition archetype prioritization centers on South African mine-resistant platform engineers with National Conventional Arms Control Committee export licensing compliance and East African depot maintenance networks. Inflection signal to monitor: Tawazun Council and SAMI joint venture restructuring that opens equity participation beyond Rheinmetall-template partnerships.| Strategic Initiative | Industry Significance |
|---|---|
| Active Protection Systems Integration | Israeli and Emirati radar-directed countermeasure deployment on new-build vehicles displaces legacy passive armor retrofits. |
| Joint Venture Localization | SAMI-Rheinmetall production lines in Riyadh satisfy General Authority for Military Industries technology transfer mandates. |
| Performance-Based Logistics Unbundling | Israel's Ministry of Defense and UAE military procurement directorates negotiate separate multi-decade support agreements. |
| African Peacekeeping Configuration Development | Paramount Group's integrated Johannesburg facility supplies medical evacuation variants to Somalia and Sahel missions. |
| Sensor Fusion Software Investment | Thermal imaging and drone detection integration commands premium positioning in procurement evaluations despite regional engineering scarcity. |
Research Methodology
Operator-level perspectives from defense procurement directors at Saudi Arabia's General Authority for Military Industries, UAE Tawazun Council offset program managers, Israeli Ministry of Defense platform engineers, and African Union mission logistics coordinators anchored the qualitative base. Primary interview coverage extended to NIMR Automotive production executives, Paramount Group design engineers, and South African National Conventional Arms Control Committee licensing officers. Secondary validation drew from customs and trade data tracking armored vehicle hull shipments through Red Sea corridor ports, SEC 10-K filings of European prime contractors, and foreign military sales disclosure databases. Bottom-up platform-level build-up and top-down defense budget allocation triangulation cross-verified volume estimates.
Sensitivity analysis across steel and ceramic composite price volatility scenarios, Active Protection Systems adoption rate variants, and local content mandate enforcement intensity shaped the analytical framework. Segmentation dimensions modeled encompass vehicle type, end-user hierarchy, technology tier, and distribution channel structure across the projection horizon. CAGRs derived from defense budget trajectory analysis and platform replacement cycle timing. Industry-specific forecast inputs included Tawazun Council offset credit valuation and African Union mission equipment refresh schedules.
Decision-makers should treat outputs as directional under assumptions of sustained border security modernization spending and continued local content mandate enforcement; material deviation in energy cost trajectories or regulatory relaxation would warrant model refresh. Forecasts reflect documented assumptions regarding technology transfer timeline feasibility and regional engineering talent availability. Practitioners should keep alternative scenarios live as Gulf sovereign defense industrial strategies and African peacekeeping mission mandates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Armored Vehicles
Armored Vehicles Upgrade and Retrofit Market
Armored Vehicles
Boom Arms Market
Armored Vehicles
Europe Armored Fighting Vehicles Market
Armored Vehicles
North America Armored Fighting Vehicles Market
Armored Vehicles
Armored Vehicle Procurement and Upgrade Market
Armored Vehicles
Armoured Personnel Carrier (APC) Market
Armored Vehicles
Armored Personnel Carrier Market
Armored Vehicles
Asia-Pacific Armored Fighting Vehicles Market
Armored Vehicles
Armored Fighting Vehicles Market
Armored Vehicles
Armored Vehicle Navigation Systems Market
Armored Vehicles
Armor Protection Systems Market
Armored Vehicles
Armored Vehicles Market
Armored Vehicles
Global Ceramic Armor Market
Armored Vehicles
Armored Vehicle Fire Suppression Systems Market
Armored Vehicles
Military Armored Car Market
Armored Vehicles
US Armored Vehicle Market