
 Armored Fighting Vehicles Market | 2026-2036
Armored Fighting Vehicles Market Size, Share, and Industry Trends Forecast 2026-2036
Armored Fighting Vehicles Market Analysis
STANAG 4569 certification for ballistic and mine protection is collapsing the supplier base as only a handful of platforms meet the latest Level 6 requirements. Rheinmetall AG leverages its in-house armor steel production to sustain vertical integration across the Lynx family. General Dynamics Corporation anchors North American land systems through its M1 Abrams upgrade pipeline and Stryker modernization programs. Hanwha Defense competes aggressively in the Asia-Pacific export market with its K21 and Redback offerings.
Armored fighting vehicles are tracked or wheeled combat platforms engineered to withstand ballistic, mine, and improvised explosive device threats while delivering direct fire, troop transport, or artillery support; hull construction typically employs rolled homogeneous armor, composite arrays, or ceramic-ERA layering to achieve specified protection levels against kinetic energy penetrators and shaped charges. Infantry fighting vehicles represent the fastest-growing product category as mechanized infantry doctrines prioritize dismountable fire teams protected under armor during assault maneuvers. Active Protection Systems command the steepest technology premium, with Rafael Trophy and Rheinmetall StrikeShield architectures displacing passive armor weight growth on next-generation platforms.
The U.S. Department of Defense, Germany's BAAINBw, and South Korea's DAPA collectively shape procurement standards through MIL-STD-810 environmental testing, ITAR export controls, and offset requirements that gate foreign market access. NATO STANAG interoperability mandates and the EU's developing Defense Industrial Readiness criteria further constrain non-aligned suppliers from contesting transatlantic tenders. Stakeholders must monitor how AUKUS technology-sharing protocols and NATO's new Force Structure Requirements reshape platform specifications before committing to long-cycle development bets.
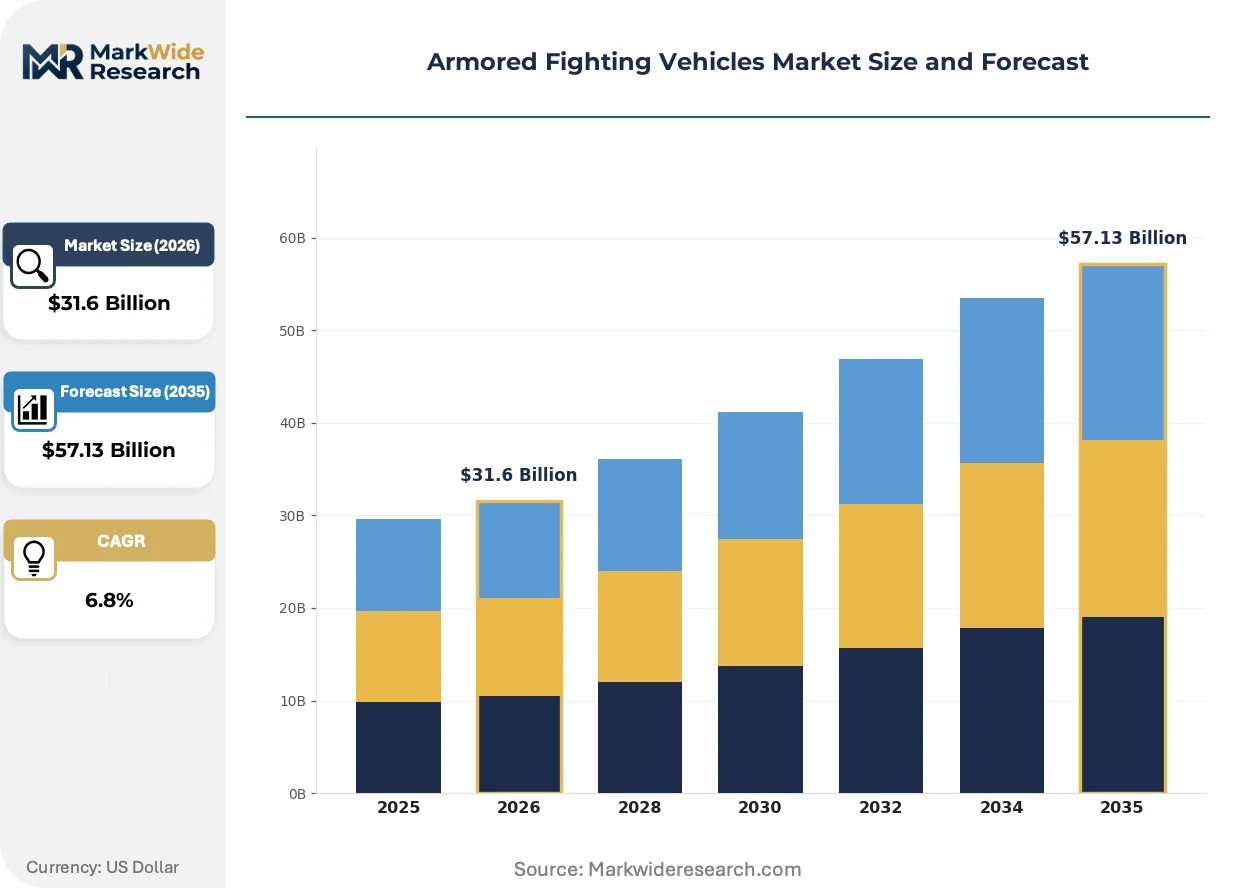
Market Dynamics
Active Protection Systems integration is compressing platform weight allowances and forcing armor manufacturers to re-engineer hull geometries around Rafael Trophy and Rheinmetall StrikeShield sensor-to-hard-kill architectures.
Growth Catalysts
- NATO STANAG 4569 Level 6 mandates:Ballistic certification requirements above 30mm armor-piercing protection are filtering procurement shortlists toward qualified hull suppliers.
- Mechanized infantry doctrinal revision:Dismountable fire team protection under armor during assault maneuvers is expanding IFV procurement pipelines.
- Rolled homogeneous armor substitution:Composite ceramic-ERA layering achieves equivalent protection at reduced areal density, enabling mobility upgrades.
Market Restraints
- High-strength armor steel supply concentration:German and South Korean integrated mills control premium quenched-and-tempered plate output, constraining hull fabrication capacity elsewhere.
- ITAR export control friction:U.S. State Department licensing timelines extend delivery schedules for non-NATO buyers.
- Active Protection System technical limitation:Urban clutter and top-attack munitions defeat current radar-based threat detection envelopes.
Strategic Opportunities
- Emerging European buyer pool:Poland and Romania are expanding mechanized brigade structures with NATO-interoperable platform requirements.
- Technology convergence of APS and directed energy:Hard-kill interceptors paired with 50kW laser dazzlers address saturation rocket attacks.
- EU Defense Industrial Readiness criteria:Cross-border consortium bidding preferences create entry paths for mid-tier armor integrators.
Industry Challenges
- Ballistic welder certification scarcity:Qualified technicians for high-hardness armor joining remain concentrated at Rheinmetall and Hyundai Rotem facilities.
- STANAG 4569 live-fire validation timelines:Full certification cycles for new hull designs extend development-to-contract intervals.
- Legacy platform electronics integration friction:M1 Abrams and Leopard 2 digital backbone upgrades compete for limited systems engineering bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Armored Fighting Vehicles Market |
| Market Size in 2026 | $31.6 Billion |
| Market Size in 2035 | $57.13 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tanks, Armored Personnel Carriers, Infantry Fighting Vehicles, Self-Propelled Guns Technology: Active Protection Systems, Night Vision, Navigation Systems, Communication Systems End User: Military, Government, Private Security, Defense Contractors Deployment: Onshore, Offshore, Urban Areas, Battlefields |
| Companies Covered | BAE Systems, General Dynamics Corporation, Rheinmetall AG, Oshkosh Corporation, Krauss-Maffei Wegmann, Hanwha Defense, Textron Inc., Leonardo S.p.A., Elbit Systems Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Armored Fighting Vehicles Market Emerging Trajectories
Unmanned turret architectures and reduced-crew concepts are compressing vehicle silhouettes while expanding sensor fusion requirements. Platform designers must balance armor mass against power generation for directed energy and electronic warfare subsystems.
Active Protection Systems is bifurcating the armor market into sensor-integrated platforms and legacy passive-only hulls. NATO procurement agencies now mandate hard-kill capability for new IFV tenders. This technological divide is excluding non-APS-integrated suppliers from contested European and Asia-Pacific competitions.
EU Defense Industrial Readiness criteria are mandating cross-border supply chain transparency for platforms qualifying as European. Member state procurement offices must document steel forging, electronics, and final assembly provenance. German BAAINBw and French DGA tenders now weight industrial dispersion scores alongside technical compliance.
Buyer concentration among NATO military procurement agencies is compressing vendor negotiation leverage. Three national customers—the U.S. Department of Defense, Germany's BAAINBw, and South Korea's DAPA—set specification baselines that cascade to aligned smaller forces. Platform developers now optimize for these anchor buyers rather than fragmented export markets.
Armored Fighting Vehicles Market Segmentation
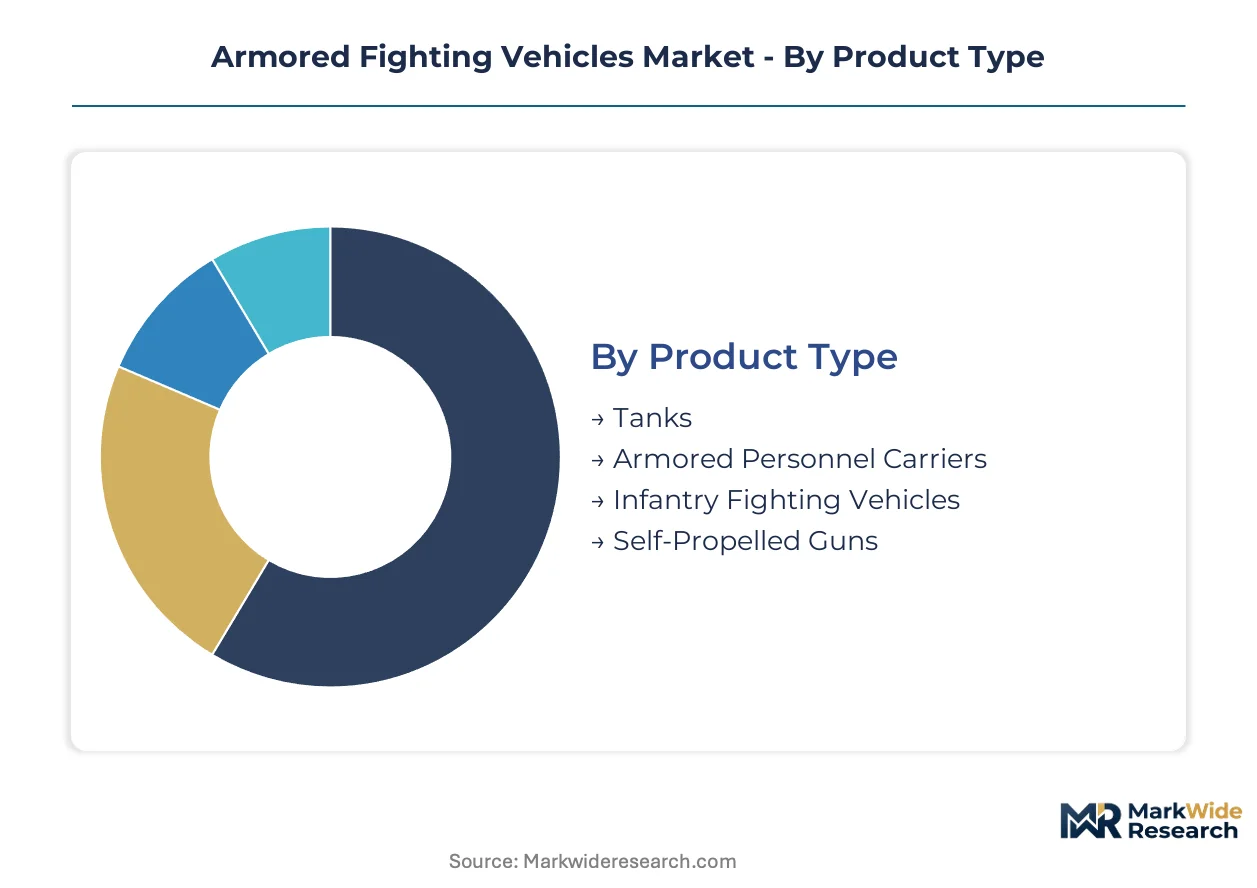
Platform specialization across the Armored Fighting Vehicles Market reflects divergent national doctrinal priorities and threat environment adaptations. Procurement patterns fragment sharply between heavy armor states pursuing main battle tank modernization and mechanized forces prioritizing protected mobility for infantry squads.
Product Type:
Domestic production concentrates in the United States, Germany, and South Korea, while export demand flows toward NATO-aligned Eastern European states and select Asia-Pacific partners.
- Tanks:Tracked platforms mounting 120mm or larger main guns with composite armor arrays and turbine or diesel powerpacks. The U.S. Army's M1 Abrams upgrade pipeline and Poland's acquisition of K2 Black Panther hulls anchor procurement volume. STANAG 4569 Level 6 mandates are extending development cycles for next-generation hull designs.
- Infantry Fighting Vehicles:Mechanized platforms carrying 6-9 dismountable troops under armor with 25-40mm autocannon armament. Germany's Puma and South Korea's Redback compete for Australia's LAND 400 Phase 3 tender. Mechanized infantry doctrinal revision across NATO is accelerating IFV procurement timelines.
- Armored Personnel Carriers:Wheeled or tracked troop transports with lighter armament and modular protection kits. Boxer 8x8 programs span Germany, the United Kingdom, and Lithuania.
- Self-Propelled Guns:Artillery platforms integrating 155mm howitzers with armored hulls and automated ammunition handling. K9 Thunder exports to Norway and Estonia demonstrate South Korean competitive positioning.
Tanks command the established base. The steepest expansion runs through Infantry Fighting Vehicles.
Technology:
Cost tiers separate sensor-integrated platforms commanding technology premiums from legacy passive-only hulls facing procurement exclusion.
- Active Protection Systems:Hard-kill interceptors and soft-kill countermeasures defending against anti-tank guided missiles and rocket-propelled grenades. Rafael Trophy systems equip Israeli Merkava and U.S. Abrams variants; Rheinmetall StrikeShield anchors European integration. Urban clutter and top-attack munitions impose detection envelope limitations constraining deployment confidence.
- Night Vision:Thermal imaging and image intensification systems enabling 24-hour operational tempo. Third-generation FLIR exports fall under ITAR licensing controls extending delivery schedules for non-NATO buyers.
- Navigation Systems:GPS-denied positioning through inertial measurement units and terrain-relative navigation. Military GPS M-code encryption upgrades are forcing platform electronics refresh cycles.
- Communication Systems:Software-defined radios and tactical data links enabling networked maneuver warfare. NATO Link-16 and national proprietary protocols create interoperability integration burdens.
Active Protection Systems absorb the steepest R&D investment. Night Vision maintains the broadest installed base across legacy fleet upgrades.
End User:
Customer concentration among state military procurement agencies compresses vendor negotiation leverage and specification autonomy.
- Military:National army and marine corps forces operating as primary platform acquirers. The U.S. Department of Defense, Germany's BAAINBw, and South Korea's DAPA set technical baselines cascading to aligned smaller forces.
- Government:Border security and internal security agencies requiring protected mobility for counter-insurgency and law enforcement missions. Romanian and Polish border guard mechanization programs illustrate non-military demand.
- Private Security:Corporate and NGO entities operating in high-threat environments. ITAR and national export controls severely constrain hull availability to this segment.
- Defense Contractors:System integrators and platform modifiers performing mid-life upgrades and technology insertion. Limited qualified ballistic welder certification concentrates upgrade capacity at Rheinmetall and Hyundai Rotem facilities.
Military end users dominate contract value. Government security agencies represent the fastest-climbing alternative demand channel.
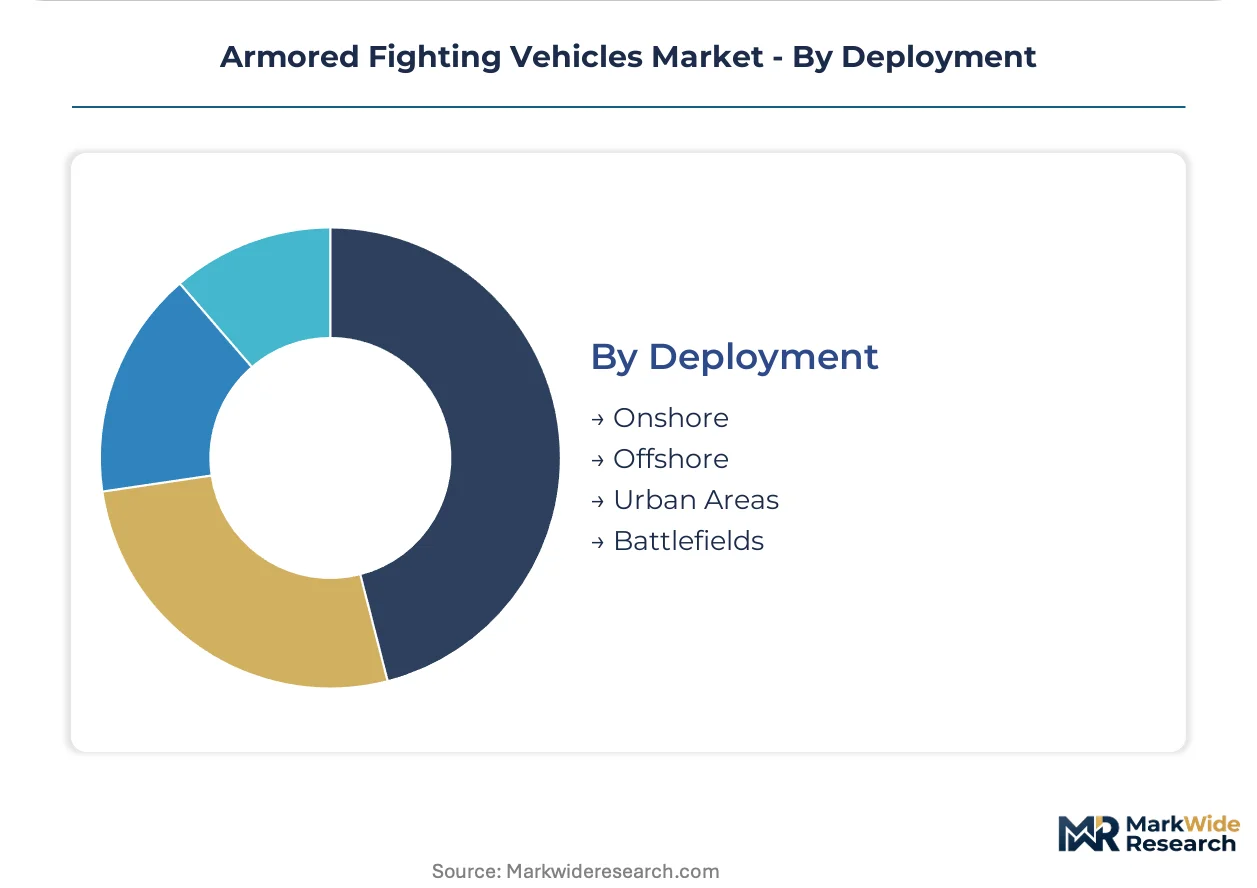
Deployment:
Application environments dictate divergent protection-mobility tradeoffs and signature management requirements.
- Urban Areas:Confined terrain demanding all-aspect protection against improvised explosive devices and elevated threats. Hull geometries adapt to radar-based APS sensor fields-of-view compromised by building clutter.
- Battlefields:Open maneuver warfare prioritizing long-range kinetic engagement and cross-country mobility. Main battle tank procurement concentrates here.
- Onshore:Continental operations with established logistics infrastructure and maintenance support networks. NATO European theater preparation drives demand.
- Offshore:Expeditionary and amphibious operations requiring corrosion-resistant hull treatments and saltwater fording capability. Marine corps and naval infantry specifications apply.
Battlefield deployment anchors historical procurement volume. Urban Areas configuration is gaining specification weight fastest as counter-insurgency doctrine persists.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government fleet modernization programs and evolving ballistic protection mandates are redirecting procurement budgets toward qualified hull suppliers. National security strategies in major defense economies prioritize STANAG 4569 certification and Active Protection Systems integration as baseline requirements for new platform acquisitions.
United States
The U.S. Army's M1 Abrams upgrade pipeline and Stryker modernization programs sustain domestic manufacturing capacity. Department of Defense MIL-STD-810 environmental testing standards filter vendor participation through rigorous qualification protocols. The Detroit Arsenal in Warren, Michigan anchors heavy armor production alongside GDLS facilities in Lima, Ohio.
Germany
BAAINBw procurement specifications for the Puma IFV and Lynx family establish European technical baselines for NATO interoperability. EU Defense Industrial Readiness criteria mandate cross-border supply chain documentation for platform qualification. Rheinmetall's Düsseldorf headquarters and Kassel production complex concentrate ballistic steel forging and final assembly expertise.
South Korea
DAPA export promotion drives K2 Black Panther and K9 Thunder sales to NATO-aligned Eastern European buyers. Offset requirements and technology transfer clauses structure foreign market access negotiations. Hyundai Rotem's Changwon plant and Hanwha Defense's facilities in Seoul and Daejeon integrate hull fabrication with electronics integration.
Poland
Mechanized brigade expansion and legacy Soviet-era platform replacement create sustained demand for NATO-interoperable hulls. National offset policies require local industrial participation in major procurement contracts. Huta Stalowa Wola and Polish Armaments Group facilities in Silesia develop co-production arrangements with foreign prime contractors.
Australia
LAND 400 Phase 3 tender evaluation for next-generation IFV capability drives specification alignment with Five Eyes partners. Defence Export Controls regulate technology transfer thresholds for subsystem integration. Victoria's defence industry precinct in Melbourne and Queensland's manufacturing corridor host platform modification and sustainment operations.
Armored Fighting Vehicles Market Vendor Landscape
Player mix skews toward vertically integrated defense conglomerates with captive armor steel production and in-house electronics integration. Market structure concentrates contract awards among three to five prime contractors qualified for STANAG 4569 Level 6 hull fabrication. Strategic archetypes include steel-integrated platform developers, electronics-lean system integrators, and state-backed export champions. Competitive dynamics center on M&A consolidation of niche APS specialists and capacity expansion for quenched-and-tempered plate output.
Among European integrated suppliers, Rheinmetall AG and Krauss-Maffei Wegmann occupy positions defined by backward integration into specialty steel production and long-cycle government relationships. General Dynamics Corporation anchors North American land systems through scale advantages in upgrade program execution. Hanwha Defense exemplifies the state-backed export champion archetype, leveraging domestic fleet procurement to amortize development costs before foreign sales campaigns.
| Leading Market Players |
|---|
| BAE Systems |
| General Dynamics Corporation |
| Rheinmetall AG |
| Oshkosh Corporation |
| Krauss-Maffei Wegmann |
| Hanwha Defense |
| Textron Inc. |
| Leonardo S.p.A. |
| Elbit Systems Ltd. |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between NATO procurement agencies and prime contractors lock in multi-year hull fabrication capacity at German and South Korean integrated mills, anchoring price visibility for quenched-and-tempered armor plate while constraining spot-market flexibility for non-aligned buyers.
Pricing Analysis
STANAG 4569 certification level creates the primary spread between platform tiers, with Level 6-qualified hulls commanding substantial premiums over Level 4 alternatives. Three-tier pricing structure across APS-integrated, night-vision-equipped, and baseline configurations reflects technology bundling strategies. Cost compression in legacy passive-only segments is intensifying because procurement agencies now mandate hard-kill protection for new tenders. Government military buyers exhibit the lowest price sensitivity due to offset requirements and national security framing, while private security contractors face effective exclusion from hull access.
Supply Chain Analysis
Port congestion on Baltic trade lanes and container availability constraints for oversized armor plate shipments are elevating inbound logistics costs for Eastern European assembly facilities. Geographic supply concentration centers on Germany, South Korea, and the United States for high-strength quenched-and-tempered steel, with captive forging capacity at Rheinmetall and Hyundai Rotem facilities. Raw material dependencies include nickel-bearing armor alloys, ceramic composite inserts, and rare earth elements for APS radar components. Single-source vulnerability for qualified ballistic welder certification concentrates hull fabrication risk. Distribution runs through government-to-government foreign military sale channels with ITAR licensing gates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment story where STANAG certification and ITAR compliance create switching costs that lock procurement agencies into established supplier relationships.
For Market Incumbents: Consolidate captive steel forging capacity through exclusive offtake arrangements with German and South Korean integrated mills, insulating against raw material access competition. Deepen backward integration into ceramic-ERA layering production to capture technology premiums currently flowing to subsystem suppliers. Emerging state-backed export champions from South Korea pose the primary entrant threat through aggressive offset packaging. For New Entrants and Emerging Players: Aftermarket APS retrofit and legacy platform electronics integration represent service-layer gaps where incumbents under-serve due to engineering bandwidth constraints. Border security agencies in Romania and Poland offer the most penetrable demand channel outside military procurement concentration. A go-to-market angle emphasizing rapid STANAG 4569 live-fire validation timelines can differentiate against prime contractor development cycles. For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier armor integrators with demonstrated cross-border consortium bidding capability under EU Defense Industrial Readiness criteria. Long-term viability rests on positioning for NATO Force Structure Requirements recalibration rather than fragmented export market optimization. The signal to watch is AUKUS technology-sharing protocol expansion into land systems, which would reshape platform specification baselines and supplier qualification thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| STANAG 4569 Level 6 Certification Investment | Qualifies hull suppliers for NATO IFV tenders excluding uncertified competitors. |
| Active Protection System Technology Licensing | Rafael Trophy and Rheinmetall StrikeShield architectures command integration premiums. |
| Cross-Border Consortium Formation | EU Defense Industrial Readiness criteria weight industrial dispersion scores in tender evaluation. |
| Quenched-and-Tempered Plate Capacity Expansion | German and South Korean mill constraints create supply access leverage for integrated producers. |
| Legacy Platform Digital Backbone Upgrade | M1 Abrams and Leopard 2 electronics refresh cycles compete for limited systems engineering bandwidth. |
Methodological Framework
A spread of perspectives from BAAINBw procurement officers, DAPA export promotion executives, Rheinmetall platform engineers, and Australian Defence materiel planners converged on the working assumptions governing fleet modernization timelines. Primary fieldwork with NATO standardization office technical leads and secondary validation through MIL-STD-810 documentation, EU Defense Industrial Readiness draft criteria, and foreign military sale congressional notifications anchored supply-side assessment. Bottom-up hull production capacity modeling and top-down defense budget appropriation analysis triangulated market sizing.
Segmentation dimensions modeled span platform type, protection technology tier, end-user agency classification, and deployment environment configuration across the projection horizon. Infantry fighting vehicle procurement acceleration and main battle tank modernization pipeline phasing informed product mix assumptions. CAGRs were derived from contract award velocity analysis and platform delivery schedule aggregation.
Underlying assumptions cover sustained NATO alliance commitment to STANAG interoperability, with deviation risk concentrated in AUKUS technology-sharing expansion and EU defense industrial policy fragmentation. Forecasts reflect these conditions; outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Armored Vehicles
Boom Arms Market
Armored Vehicles
Global Ceramic Armor Market
Armored Vehicles
Armored Vehicle Procurement and Upgrade Market
Armored Vehicles
Armored Vehicles Upgrade and Retrofit Market
Armored Vehicles
Armored Vehicles Market
Armored Vehicles
Military Armored Car Market
Armored Vehicles
Armored Vehicle Fire Suppression Systems Market
Armored Vehicles
North America Armored Fighting Vehicles Market
Armored Vehicles
Asia-Pacific Armored Fighting Vehicles Market
Armored Vehicles
Middle-East and Africa Armored Vehicles Market
Armored Vehicles
Armored Personnel Carrier Market
Armored Vehicles
Armoured Personnel Carrier (APC) Market
Armored Vehicles
US Armored Vehicle Market
Armored Vehicles
Europe Armored Fighting Vehicles Market
Armored Vehicles
Armor Protection Systems Market
Armored Vehicles
Armored Vehicle Navigation Systems Market