
 Armored Vehicles Upgrade and Retrofit Market | 2026-2036
Armored Vehicles Upgrade and Retrofit Market Size, Share, and Industry Trends Forecast 2026-2036
Armored Vehicles Upgrade and Retrofit Market Intelligence
STANAG 4569 ballistic protection certification is unwinding the competitive landscape, as only contractors with proven NATO qualification records secure multi-year upgrade contracts. Rheinmetall AG leverages its integrated armor foundry and electronics division to capture full-upgrade packages for main battle tanks. BAE Systems PLC sustains long-term service agreements with the British Army's Challenger fleet, anchoring recurring revenue through platform life extension programs. Elbit Systems Ltd competes on active protection system integration, differentiating through proprietary Trophy variants adapted for Western and legacy Soviet-era hulls.
Armored vehicles upgrade and retrofit encompasses the structural modification, subsystem replacement, and capability enhancement of existing military and security platforms beyond original design specifications, typically involving integration of composite armor panels rated to Level 4+ ballistic standards, digital battle management architectures, and powertrain overhauls to accommodate added weight. The primary purpose is to extend operational service life by 15-25 years while closing capability gaps against evolving anti-armor threats. Electronics and communication systems represent the fastest-expanding product category as network-centric warfare requirements drive demand for software-defined radios and battle management systems. Active protection technology commands premium margins due to limited qualified suppliers and the complexity of integrating radar-based interceptors without compromising vehicle mobility. Military end users dominate volume, though law enforcement segments in high-threat urban environments are emerging as a specialized growth corridor for lighter retrofit packages.
NATO standardization agreements, the U.S. Department of Defense MIL-STD-810 environmental testing protocols, and the EU's Defence and Security Procurement Directive collectively shape market access by mandating interoperability, electromagnetic compatibility, and cross-border contracting transparency. The U.S. Army's Ground Vehicle Systems Center enforces rigorous configuration control that limits vendor substitution mid-program, locking in incumbent suppliers through technical data package restrictions. Stakeholders must monitor how export control revisions under the U.S. International Traffic in Arms Regulations and the EU's evolving dual-use technology lists reshape component sourcing flexibility for platforms with foreign military sales lineage.
Market Dynamics
NATO fleet obsolescence is compressing upgrade timelines as legacy main battle tanks approach structural fatigue limits, forcing defense ministries to choose between life-extension investments and platform replacement costs.
Growth Catalysts
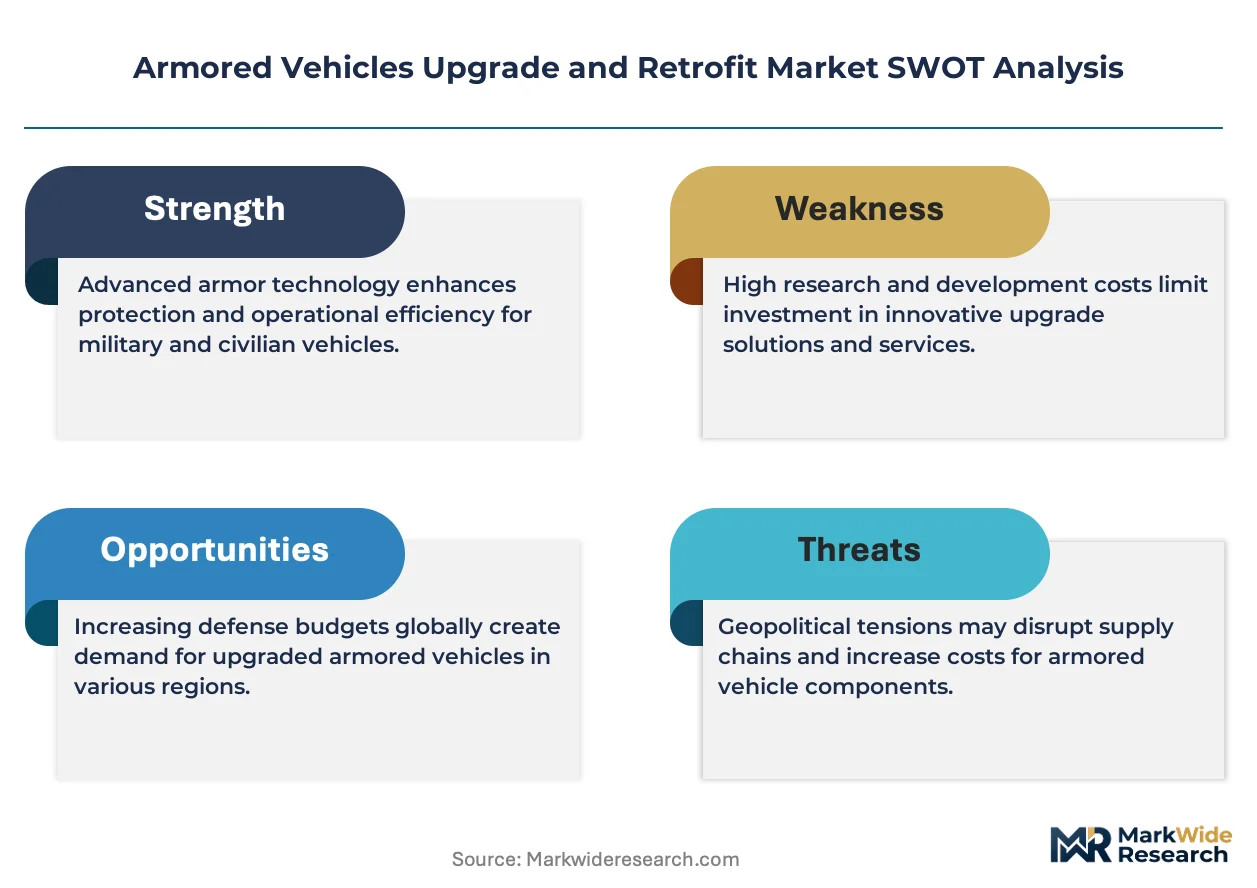
- STANAG 4569 ballistic certification:NATO standardization agreements are mandating unified protection levels across member fleets, creating mandatory retrofit demand for platforms lacking composite armor ratings.
- Active protection systems:Radar-based interceptor technology is displacing passive armor add-ons as the primary countermeasure against shaped-charge and kinetic energy threats in mechanized units.
- German industrial concentration:Krauss-Maffei Wegmann and Rheinmetall AG anchor continental upgrade capacity, drawing cross-border contracts from Poland, Czech Republic, and Nordic procurement agencies.
Market Restraints
- Titanium and ceramic armor input costs:Ballistic-grade composite panel materials face supply volatility from limited specialty foundry capacity concentrated in German and Austrian metallurgical clusters.
- Technical data package restrictions:U.S. Army Ground Vehicle Systems Center configuration control protocols lock incumbent suppliers into multi-year programs, blocking mid-contract vendor substitution.
- Platform heterogeneity:Soviet-era hull architectures in Eastern European inventories resist standardized Western subsystem integration without structural modification.
Strategic Opportunities
- Polish fleet modernization:Warsaw's accelerated Leopard 2 and PT-91 upgrade programs represent uncontracted volume for turret electronics and powertrain overhaul specialists.
- EU Defence and Security Procurement Directive:Cross-border contracting transparency mandates are opening national upgrade programs to qualified contractors from other member states.
- Software-defined radio convergence:Battle management system integration with legacy analog architectures creates white space for middleware developers bridging digital-analog interface gaps.
Industry Challenges
- Electromagnetic compatibility certification:Integrating active protection radar with existing vehicle electronics requires extensive MIL-STD-461 testing cycles that compress program margins.
- Legacy powertrain accommodation:Added armor weight demands engine and transmission upgrades that strain original hull structural margins, requiring extensive finite element analysis and physical prototyping.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Armored Vehicles Upgrade and Retrofit Market |
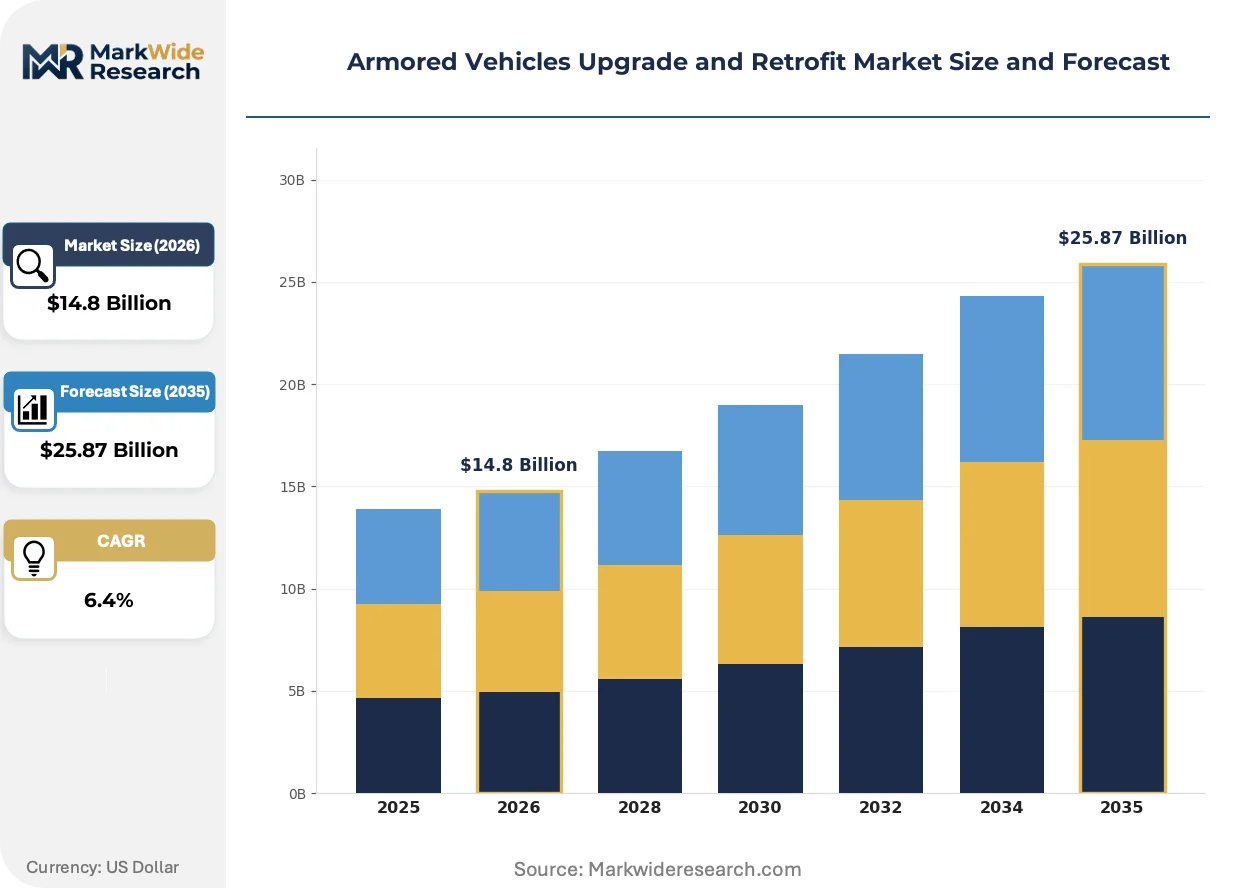
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.87 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Armor Kits, Electronics, Communication Systems, Weapon Systems Technology: Active Protection, Situational Awareness, Weapon Integration, Ballistic Resistance End User: Military, Law Enforcement, Private Security, Government Agencies Service Type: Maintenance, Customization, Installation, Consulting |
| Companies Covered | General Dynamics Corporation, BAE Systems PLC, Rheinmetall AG, Oshkosh Corporation, Thales Group, Elbit Systems Ltd, Textron Inc., Krauss-Maffei Wegmann, Lockheed Martin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Armored Vehicles Upgrade and Retrofit Market Strategic Shifts & Innovations
Digital architecture integration is displacing hardware-centric upgrade models as network-centric warfare requirements penetrate platform-level specifications. Software-defined capabilities now determine competitive positioning as much as ballistic protection ratings.
Modular armor kits are fragmenting the traditional monolithic upgrade contract structure. These swappable protection systems allow field-level threat calibration without depot-level overhaul, enabling mechanized units to reconfigure vehicles between high-intensity combat and stabilization missions. German Bundeswehr trials of rapidly exchangeable appliqué panels are compressing contractor margins on full-platform rebuilds while expanding recurring revenue from module refresh cycles.
The EU's evolving dual-use technology control lists are reshaping component sourcing flexibility for platforms with foreign military sales lineage. Export classification reviews for thermal imaging and encrypted communication subsystems are extending procurement lead times for integrators serving multiple national fleets. Contractors are responding by qualifying dual-source supply chains and pre-positioning strategic component inventories in member state territories.
Defense ministries are unbundling long-term service agreements from initial hardware procurement, treating platform availability as a purchased outcome rather than a capital asset. British Army Challenger fleet sustainment contracts now specify operational readiness thresholds rather than spare parts delivery schedules. This model concentrates risk with prime contractors while transferring lifecycle cost uncertainty from military budgets to industrial balance sheets.
Armored Vehicles Upgrade and Retrofit Market Segmentation
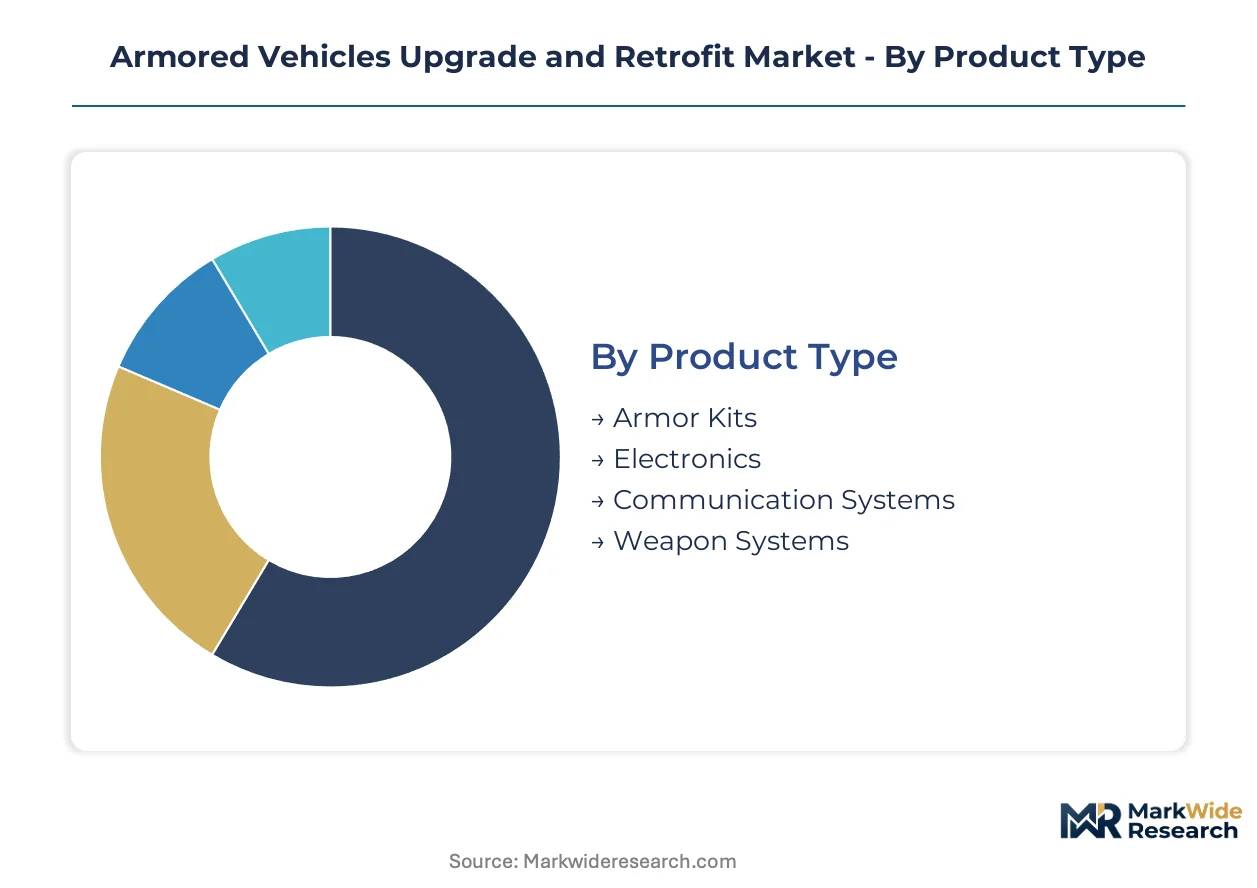
Segmentation in armored vehicle upgrades reveals how procurement budgets fragment across hardware, software, and service layers. Defense ministries prioritize electronics and active protection while law enforcement segments drive demand for lighter, modular retrofit packages.
Product Type:
Premium margins concentrate in integrated electronics suites and active protection systems, while armor kits face commoditization pressure from modular, field-swappable alternatives.
- Armor Kits:Composite and ceramic appliqué panels rated to STANAG 4569 Level 4+ standards, including titanium-ceramic laminates and reactive armor tiles. German Bundeswehr trials of rapidly exchangeable panels are compressing margins on full-platform rebuilds while expanding recurring revenue from module refresh cycles.
- Electronics:Digital battle management architectures, fire control computers, and sensor fusion systems that integrate thermal imaging with ballistic calculators. Demand concentrates in NATO mechanized brigades modernizing legacy analog architectures for network-centric warfare requirements.
- Communication Systems:Software-defined radios and encrypted tactical networks bridging legacy analog interfaces with digital battle management systems.
- Weapon Systems:Remote weapon stations, stabilized turrets, and main gun upgrades including 120mm smoothbore conversions for legacy hulls.
The dominant share belongs to Electronics, while Armor Kits are closing the gap fastest through modular, mission-configurable procurement models.
Technology:
Technology segmentation tracks where defense ministries allocate capability investment versus sustainment spending, with active protection commanding the steepest premium due to qualified supplier scarcity.
- Active Protection:Radar-based interceptor systems including hard-kill and soft-kill countermeasures against anti-tank guided missiles and rocket-propelled grenades. Israeli Trophy variants adapted for Western and legacy Soviet-era hulls are displacing passive armor add-ons as the primary countermeasure in mechanized units.
- Situational Awareness:360-degree camera arrays, distributed aperture sensors, and helmet-mounted cueing systems reducing crew visual blind spots.
- Weapon Integration:Stabilized pintle mounts, coaxial machine gun upgrades, and ammunition handling system modifications.
- Ballistic Resistance:Passive armor enhancements including spaced armor arrays, composite panel bonding, and mine blast protection underbelly plates.
Active Protection captures the highest margin pool, though Situational Awareness is expanding most quickly as digitization penetrates platform-level specifications.
End User:
End user segmentation separates volume-driven military procurement from specialized, higher-margin segments requiring rapid deployment and urban threat calibration.
- Military:National army and marine corps platforms including main battle tanks, infantry fighting vehicles, and armored personnel carriers. NATO fleet obsolescence is compressing upgrade timelines as legacy platforms approach structural fatigue limits, forcing defense ministries to choose between life-extension investments and platform replacement costs.
- Law Enforcement:SWAT vehicles, prisoner transport units, and tactical response platforms operating in high-threat urban environments. Specialized growth corridor for lighter retrofit packages with modular threat calibration capabilities.
- Private Security:Executive protection vehicles and cash-in-transit fleet hardening against ballistic and explosive threats.
- Government Agencies:Border patrol, counter-terrorism units, and critical infrastructure protection vehicles requiring interoperability with military communication standards.
Military end users dominate absolute volume, while Law Enforcement is gaining share fastest through urban stabilization mission requirements.
Service Type:
Service segmentation reflects the shift from capital asset procurement to outcome-based availability contracts, concentrating risk with prime contractors.
- Maintenance:Scheduled overhaul, structural fatigue inspection, and component lifecycle replacement programs. British Army Challenger fleet sustainment contracts now specify operational readiness thresholds rather than spare parts delivery schedules, transferring lifecycle cost uncertainty from military budgets to industrial balance sheets.
- Customization:Mission-specific modifications including climate adaptation, electromagnetic hardening, and crew station reconfiguration.
- Installation:Depot-level integration of armor panels, electronics suites, and powertrain modifications requiring MIL-STD-810 environmental testing protocols.
- Consulting:Fleet modernization roadmapping, threat assessment studies, and configuration trade-off analysis for defense procurement agencies.
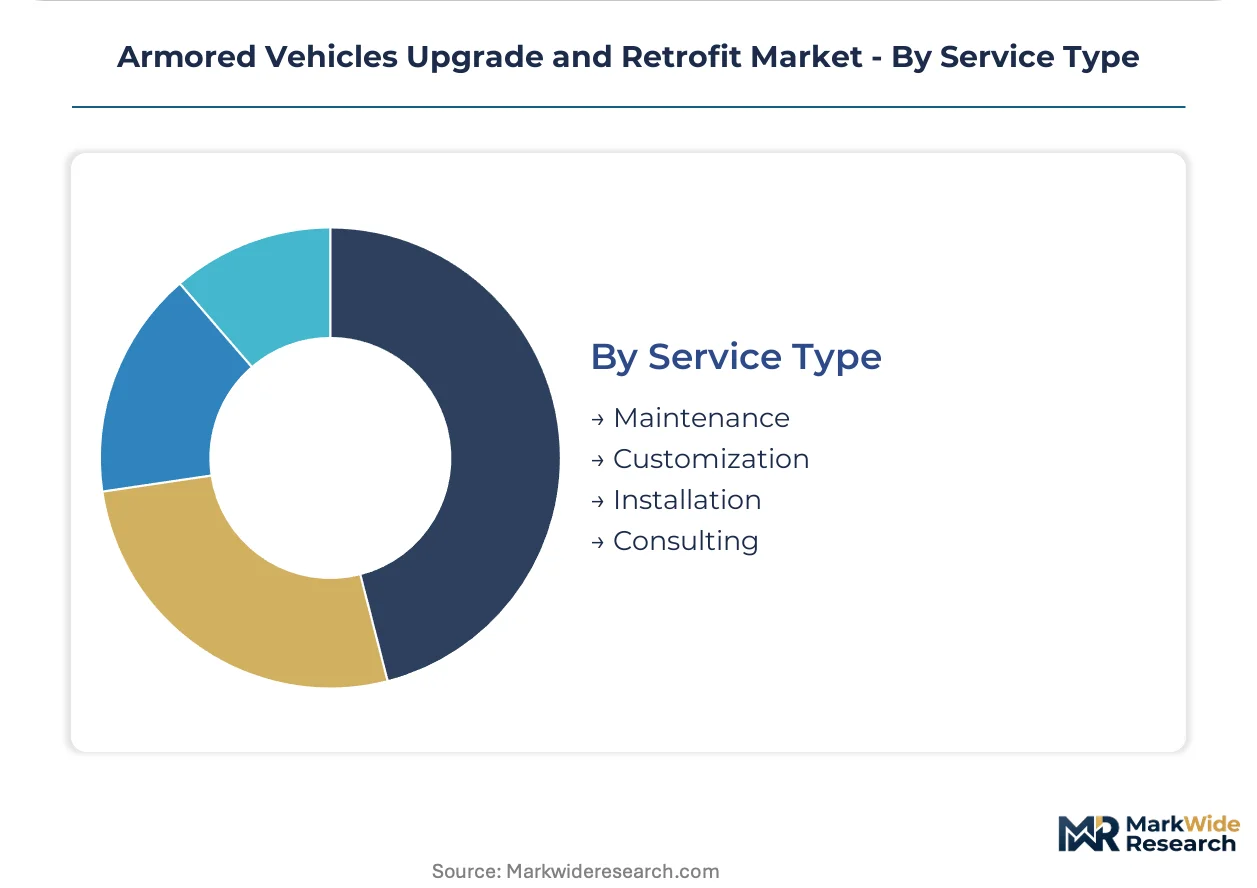
Maintenance holds the largest revenue base, while Consulting is climbing the fastest as defense ministries unbundle long-term service agreements from initial hardware procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Kiel Canal and Hamburg-Bremen port complex underwrites Germany's role as the continental hub for heavy armored vehicle logistics, with rail spurs from Kassel and Munich feeding upgrade depots across Central Europe.
Germany
Krauss-Maffei Wegmann and Rheinmetall AG anchor tracked vehicle upgrade capacity in Kassel and Düsseldorf, drawing cross-border contracts from Poland and the Czech Republic. The European Defence Fund's tightening procurement standards reshape contractor qualification requirements for NATO interoperability. Industrial concentration in Bavaria and North Rhine-Westphalia supports integrated armor foundries and electronics divisions capturing full-upgrade packages.
United States
The U.S. Army's Ground Vehicle Systems Center enforces configuration control that limits vendor substitution mid-program, locking in incumbent suppliers through technical data package restrictions. Export control revisions under the International Traffic in Arms Regulations reshape component sourcing flexibility for platforms with foreign military sales lineage. The Michigan-Ohio industrial corridor hosts depot-level integration facilities for Abrams fleet modernization.
Poland
Warsaw's accelerated Leopard 2 and PT-91 upgrade programs represent uncontracted volume for turret electronics and powertrain overhaul specialists. The EU Defence and Security Procurement Directive opens national upgrade programs to qualified contractors from other member states. Poznań and Wrocław clusters are emerging as maintenance hubs for Soviet-era hull architectures requiring structural modification for Western subsystem integration.
United Kingdom
BAE Systems PLC sustains long-term service agreements with the British Army's Challenger fleet, anchoring recurring revenue through platform life extension programs. The Ministry of Defence's shift toward outcome-based availability contracts transfers lifecycle cost uncertainty from military budgets to industrial balance sheets. Telford and Newcastle facilities concentrate on digital battle management architecture integration for legacy analog platforms.
Israel
Elbit Systems Ltd competes on active protection system integration, differentiating through proprietary Trophy variants adapted for Western and legacy Soviet-era hulls. The Ministry of Defense's dual-use technology controls extend procurement lead times for thermal imaging and encrypted communication subsystems. Haifa and Beersheba engineering clusters specialize in radar-based interceptor technology displacing passive armor add-ons.
Armored Vehicles Upgrade and Retrofit Market Key Industry Players
Listed leaders compete with private specialists across government contracting access, with publicly traded defense conglomerates facing privately held mid-tier firms for platform-specific upgrade programs. The market structure concentrates around integrated prime contractors capable of delivering full-life-cycle solutions from armor fabrication through electronics integration. Three archetypes dominate: diversified conglomerates with captive metallurgical capacity, electronics specialists leveraging software-defined capabilities, and regional champions anchored to single national fleets. Competitive moves center on strategic partnerships for technology licensing and backward integration into specialty alloy supply.
Among diversified conglomerates with integrated foundry operations, Rheinmetall AG and General Dynamics Corporation exemplify the full-upgrade-package model, while BAE Systems PLC occupies a position within the long-term service agreement tier. Elbit Systems Ltd represents the active protection specialization archetype, competing on radar-based interceptor integration without the capital intensity of hull manufacturing. These three anchors illustrate how competitive positioning stratifies across hardware fabrication, electronics integration, and outcome-based sustainment contracting.
| Leading Market Players |
|---|
| General Dynamics Corporation |
| BAE Systems PLC |
| Rheinmetall AG |
| Oshkosh Corporation |
| Thales Group |
| Elbit Systems Ltd |
| Textron Inc. |
| Krauss-Maffei Wegmann |
| Lockheed Martin |
| Others |
Cost & Logistics Intelligence
Twenty-four-month lead times for STANAG 4569-certified composite armor panels concentrate pricing power with German and Austrian metallurgical clusters, while inventory pre-positioning requirements in NATO member territories amplify working capital demands for integrators serving multiple national fleets.
Pricing Analysis
Three-tier pricing structure across full-upgrade packages, modular subsystem retrofits, and field-swappable armor kits stratifies contractor margins by integration depth. Price differentiation hinges on NATO qualification records and captive foundry capacity, with electronics integration commanding premiums over passive armor add-ons. Cost compression in modular armor kits is intensifying because Bundeswehr trials of rapidly exchangeable panels are displacing depot-level rebuilds. Military end users exhibit lowest price sensitivity due to operational readiness mandates, while law enforcement segments prioritize lighter retrofit packages with flexible threat calibration.
Supply Chain Analysis
Inventory pre-positioning for thermal imaging and encrypted communication subsystems extends procurement cycles as EU dual-use technology controls reshape component sourcing flexibility. German, Austrian, and Israeli engineering clusters anchor specialty foundry capacity and radar-based interceptor production. Raw material dependencies center on titanium-ceramic laminates, ballistic-grade steel alloys, and gallium nitride semiconductors for active protection radars. Single-source vulnerability concentrates in qualified armor foundries with NATO certification records. Distribution runs through Kassel and Düsseldorf upgrade depots feeding Central European mechanized brigades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Active protection system integration is disrupting competitive positioning as radar-based interceptors displace passive armor add-ons, while EU Defence Fund procurement standards are reshaping contractor qualification requirements.
For Market Incumbents: Compound defensive moats through backward integration into specialty alloy supply and captive electronics fabrication capacity. Lock in multi-year service agreements with British Army and Bundeswehr fleets before cross-border contracting transparency mandates open national programs to qualified competitors. Prioritize STANAG 4569 certification maintenance as the priority barrier against emerging electronics specialists lacking metallurgical foundry assets.
For New Entrants and Emerging Players: Lead with middleware development bridging software-defined radios with legacy analog battle management architectures in Polish and Czech upgrade programs. Target turret electronics and powertrain overhaul segments where platform heterogeneity resists standardized integration and incumbent primes face margin compression from modular armor kit commoditization. Establish engineering presence in Poznań and Wrocław clusters to access Soviet-era hull modification expertise.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified defense conglomerates spinning off non-core armor fabrication divisions as digital architecture integration shifts value toward software-defined capabilities. Long-term viability favors integrated primes with captive foundry capacity and proven NATO qualification records. Watch Polish Leopard 2 and PT-91 contract awards as the signal indicating whether German industrial concentration holds or cross-border EU procurement opens to qualified competitors from other member states.
| Strategic Initiative | Industry Significance |
|---|---|
| Active Protection System Integration | Trophy variants adapted for Soviet-era hulls displace passive armor in mechanized units. |
| Backward Integration into Specialty Alloys | Captive titanium-ceramic laminate production secures margin control against Austrian foundry bottlenecks. |
| Software-Defined Radio Convergence | Middleware bridging digital-analog interfaces captures value as network-centric warfare penetrates platform specifications. |
| Outcome-Based Availability Contracting | British Army Challenger sustainment transfers lifecycle cost risk from MOD budgets to industrial balance sheets. |
| EU Cross-Border Qualification Investment | Pre-positioning engineering capabilities in Poland and Czech Republic accesses uncontracted Leopard 2 volume. |
Research Approach
Initial hypotheses were tested against primary input from defense procurement officers, platform engineering directors at prime contractors, active protection system integration specialists, and aftermarket service heads at depot-level facilities, and refined through secondary validation against NATO standardization agreement documentation, EU Defence Fund procurement directives, U.S. Army Ground Vehicle Systems Center technical data package regulations, and customs records of titanium and ceramic armor material flows. Bottom-up segment sizing triangulated with top-down defense budget allocation analysis across the analysis window.
Variance decomposition across product type, technology tier, end-user category, and service model dimensions informed volume and value projections throughout the forecast period. CAGRs were derived from segment-level growth rate blending weighted by procurement pipeline visibility. Industry-specific inputs included STANAG 4569 certification timelines, MIL-STD-461 electromagnetic compatibility testing cycles, and powertrain overhaul demand curves tied to legacy platform fatigue life projections.
The analysis sits within stated boundaries; outcomes outside sustained NATO fleet modernization commitments or abrupt EU dual-use technology control revisions would require recalibration. Forecasts reflect documented assumptions regarding procurement timeline stability and qualified supplier capacity expansion. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Armored Vehicles
Armored Vehicles Market
Armored Vehicles
Armoured Personnel Carrier (APC) Market
Armored Vehicles
Armored Vehicle Navigation Systems Market
Armored Vehicles
Armored Fighting Vehicles Market
Armored Vehicles
Armored Personnel Carrier Market
Armored Vehicles
Armor Protection Systems Market
Armored Vehicles
Asia-Pacific Armored Fighting Vehicles Market
Armored Vehicles
Middle-East and Africa Armored Vehicles Market
Armored Vehicles
Boom Arms Market
Armored Vehicles
North America Armored Fighting Vehicles Market
Armored Vehicles
Global Ceramic Armor Market
Armored Vehicles
Europe Armored Fighting Vehicles Market
Armored Vehicles
Armored Vehicle Procurement and Upgrade Market
Armored Vehicles
US Armored Vehicle Market
Armored Vehicles
Armored Vehicle Fire Suppression Systems Market
Armored Vehicles
Military Armored Car Market