
 Armored Personnel Carrier Market | 2026-2036
Armored Personnel Carrier Market Size, Share, and Industry Trends Forecast 2026-2036
Armored Personnel Carrier Market Outlook
EU defense procurement reform is expanding compliance burdens for non-European suppliers while creating protected contracting lanes for domestic manufacturers. Rheinmetall AG leverages its pan-European production footprint to anchor bidding positions across Bundeswehr and NATO joint programs. BAE Systems sustains transatlantic relevance through its US-UK dual-base manufacturing architecture. General Dynamics Corporation dominates North American ground combat vehicle tenders with its integrated design-to-fielding pipeline.
An armored personnel carrier constitutes a protected mobility platform engineered to transport infantry squads under hostile fire, typically incorporating steel or composite armor hulls rated against small-arms and shell-fragment threats while maintaining cross-country speeds exceeding 60 km/h. These vehicles serve military and internal security forces requiring tactical troop deployment in contested environments. Wheeled armored vehicles command the largest procurement volumes due to lower operating costs and strategic mobility advantages on established road networks. Mine resistance technology represents the fastest-growing capability insertion point as blast-protection standards tighten across European and Middle Eastern end users. Transport vehicle configurations retain stable demand from peacekeeping and humanitarian missions where payload flexibility outweighs direct-fire survivability.
The US Department of Defense, NATO Standardization Office, and EU Defence Fund collectively dictate platform interoperability mandates, cybersecurity baselines, and cross-border industrial participation rules that filter vendor eligibility. The EU AI Act's emerging classification of autonomous targeting systems will impose additional certification layers on surveillance and communication technology integrations. Stakeholders must track how NATO's Next-Generation Rotorcraft and ground vehicle convergence studies reshape weight-class definitions and modularity requirements before committing to fixed production architectures.
Market Dynamics
NATO mechanized force recapitalization is compressing platform replacement cycles as member states confront hardened peer threats. The EU Green Deal's defense industrial adaptation measures are simultaneously reshaping procurement criteria toward lower-emission propulsion architectures.
Growth Catalysts
- EU Defence Fund co-financing:Joint capability development programs are pooling member state resources to accelerate tracked and wheeled vehicle procurement. Bundeswehr modernization tenders now mandate cross-border industrial participation.
- Poland:Warsaw's unprecedented armored vehicle procurement pipeline is anchoring European production capacity expansion through multi-billion dollar mechanized brigade recapitalization.
- Mine-resistant hull composites:Advanced ceramic and polymer armor systems are penetrating procurement specifications as blast-protection standards tighten across Middle Eastern end users.
Market Restraints
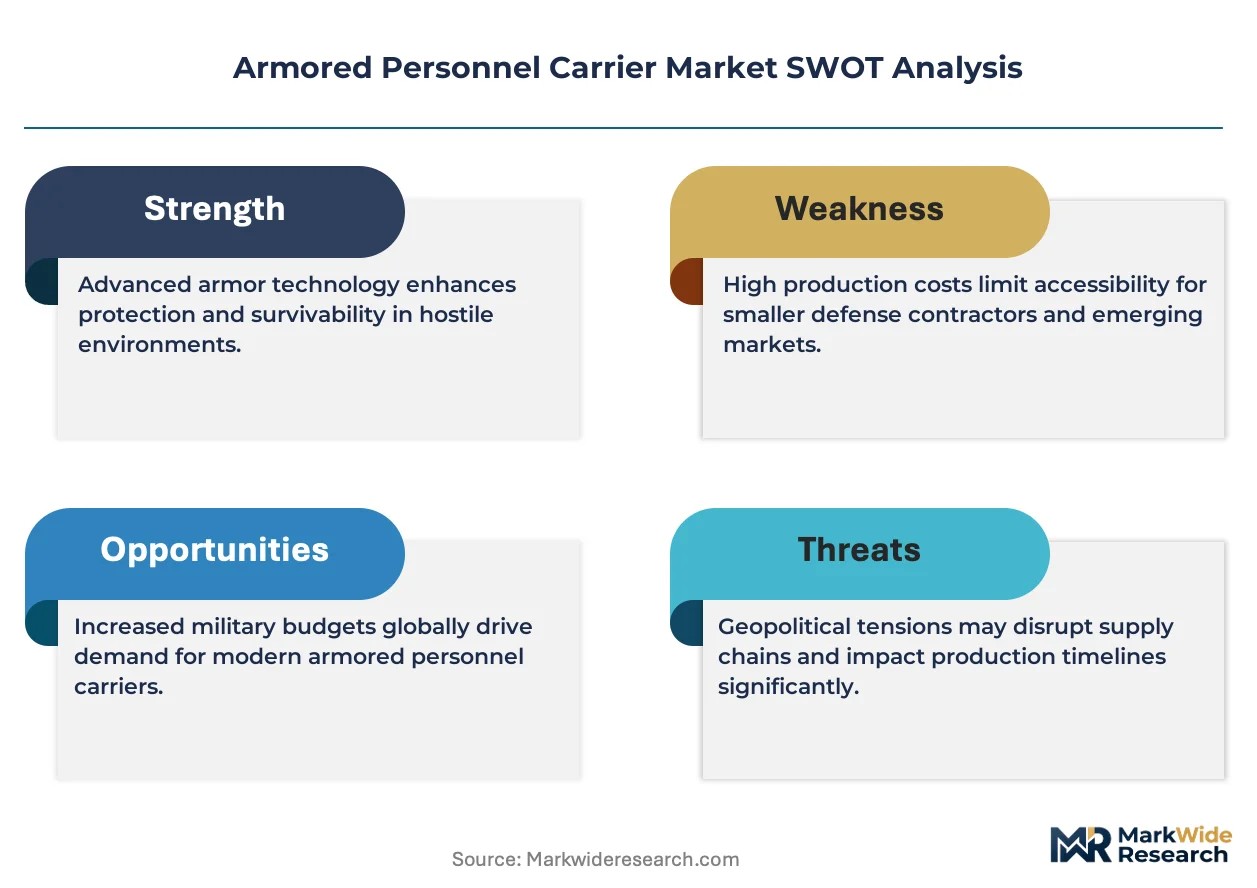
- Specialized steel alloy supply:Ballistic-grade armor plate production concentrates in a limited supplier base, exposing programs to input cost volatility and delivery timeline risk.
- EU AI Act certification layers:Emerging classification of autonomous targeting systems is imposing additional validation burdens on surveillance and communication technology integrations.
- Tracked platform operating economics:Higher fuel consumption and maintenance intensity relative to wheeled alternatives is constraining fleet mix decisions for budget-constrained operators.
Strategic Opportunities
- Hybrid-electric propulsion architectures:The EU Green Deal's emission reduction mandates are creating protected contracting lanes for low-carbon mobility platforms in Bundeswehr and NATO joint programs.
- Urban warfare configurations:Internal security forces in France and Germany are generating demand for compact armored vehicles optimized for narrow-street maneuverability and crowd-control payload flexibility.
- NATO Standardization Office interoperability mandates:Common technical standards for command-and-control interfaces are enabling modular subsystem suppliers to penetrate previously closed national programs.
Industry Challenges
- Systems integration engineering talent:Shortages of specialists capable of fusing armor, mobility, and digital architecture are extending development timelines for next-generation platforms.
- Cross-certification complexity:Divergent national safety and security validation requirements are fragmenting addressable market scope for standardized vehicle designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Armored Personnel Carrier Market |
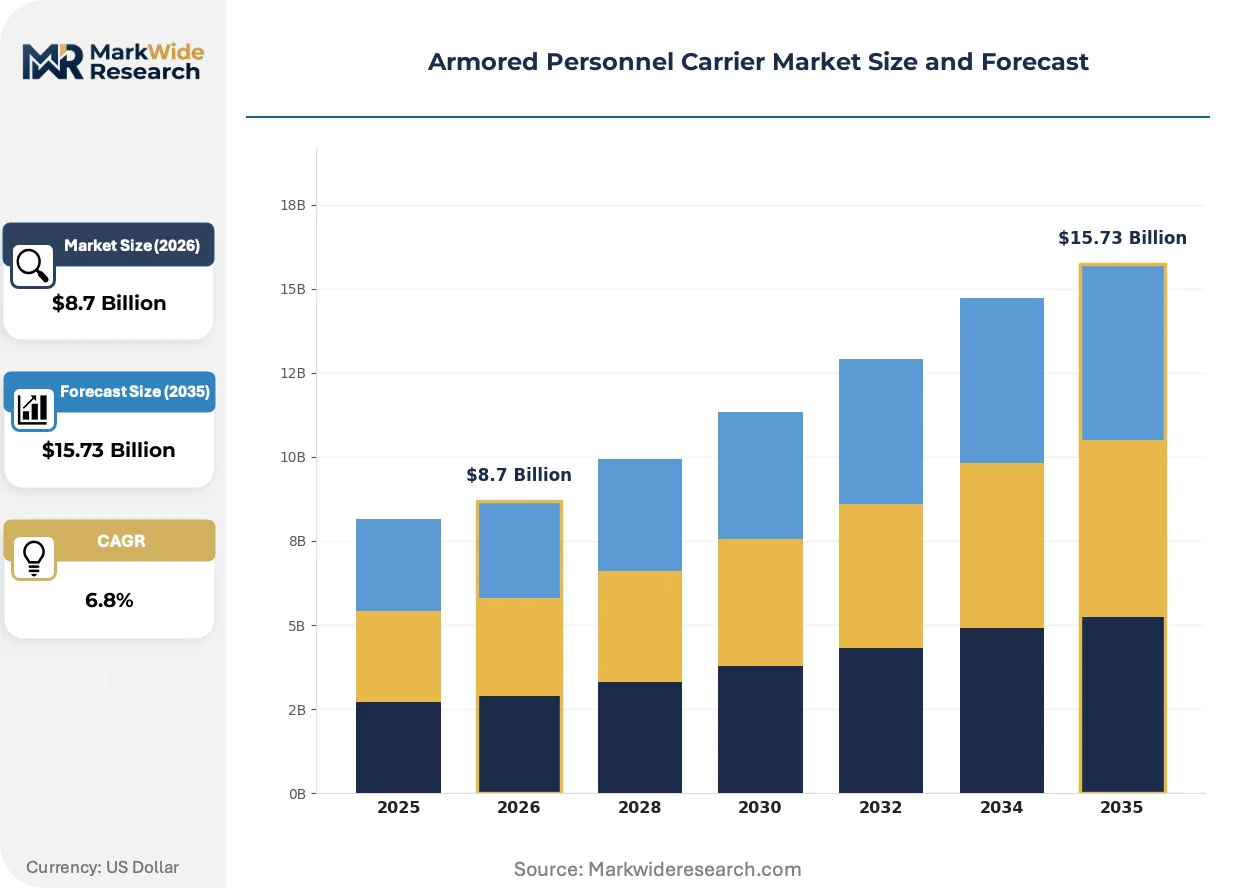
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Light Armored Vehicle, Medium Armored Vehicle, Heavy Armored Vehicle, Wheeled Armored Vehicle End User: Military Forces, Law Enforcement, Private Security, Government Agencies Configuration: Combat Vehicle, Transport Vehicle, Reconnaissance Vehicle, Command Vehicle Technology: Ballistic Protection, Mine Resistance, Surveillance Systems, Communication Systems |
| Companies Covered | General Dynamics Corporation, BAE Systems, Rheinmetall AG, Oshkosh Defense, Krauss-Maffei Wegmann, Navistar International, Patria Oyj, KNDS, Elbit Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Armored Personnel Carrier Market Strategic Shifts
Active protection systems and autonomous mobility architectures are converging to redefine survivability benchmarks. Platform designers must now integrate software-defined capabilities alongside traditional armor physics.
Composite armor matrix technology is absorbing blast energy through layered ceramic and polymer configurations that outperform homogeneous steel at reduced weight. Polish and German procurement offices are mandating these materials in next-generation infantry fighting vehicle tenders. The technology is absorbing engineering resources previously allocated to traditional hull fabrication, compressing supplier margins in conventional armor segments.
The EU AI Act's risk-based classification framework is imposing algorithmic transparency requirements on target acquisition and fire-control systems. Defense contractors must now document training data provenance and decision-audit trails for autonomous subsystem certification. Wheeled reconnaissance platforms with integrated surveillance suites face the steepest compliance burden as member states implement divergent national transposition timelines.
Buyer concentration around NATO joint programs is consolidating vendor qualification pathways. National procurement offices are abandoning fragmented bilateral negotiations in favor of multi-year framework agreements administered through the NATO Support and Procurement Agency. This concentration is most visible in the Nordic-Baltic corridor, where Estonia, Latvia, and Lithuania are pooling vehicle requirements to achieve volume pricing and common logistics architectures.
Armored Personnel Carrier Market Segmentation
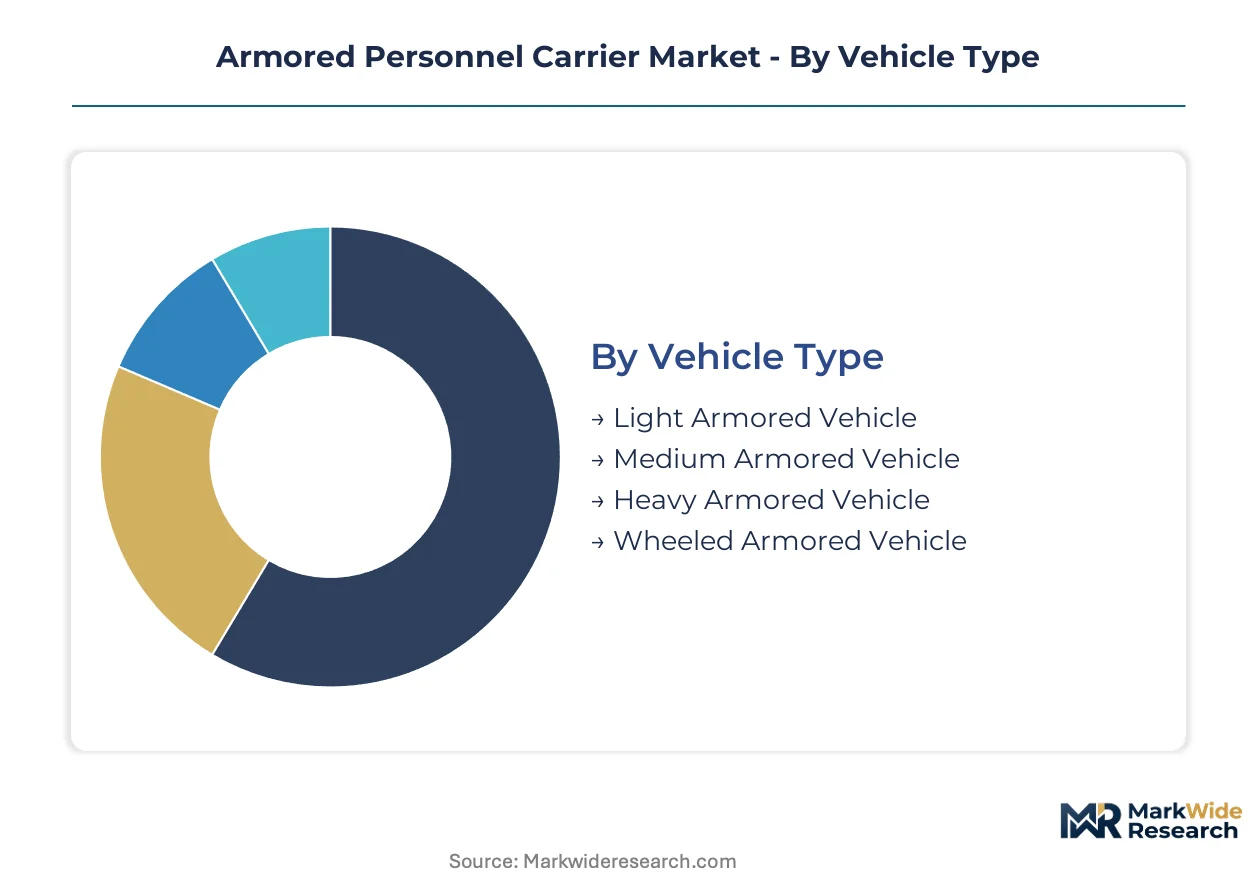
Platform differentiation in the armored personnel carrier market reflects divergent mobility requirements, threat environments, and procurement budget tiers. Buyers select vehicle classes based on operational tempo, terrain constraints, and force structure modernization priorities rather than incremental capability upgrades.
Vehicle Type:
Procurement volume concentrates among operators balancing protection levels against strategic deployability and lifecycle operating costs.
- Wheeled Armored Vehicle:Eight-wheel or six-wheel configurations with modular armor packages rated against small-arms and shell-fragment threats. Poland and Germany are concentrating wheeled platform orders for mechanized brigade recapitalization, driven by lower fuel consumption and road-network mobility advantages over tracked alternatives.
- Heavy Armored Vehicle:Tracked hulls exceeding 30 tonnes with integrated active protection systems and mine-resistant belly plates. Demand is tightening among Middle Eastern end users as blast-protection standards escalate for counter-insurgency operations in contested urban corridors.
- Light Armored Vehicle:Compact platforms under 15 tonnes optimized for rapid air-transport and special operations insertion.
- Medium Armored Vehicle:Mid-weight configurations bridging protection gaps between light reconnaissance and heavy mechanized formations.
Volume sits with wheeled platforms; growth tilts toward heavy vehicles as peer-threat armor penetration drives protection upgrades.
End User:
Budget scale and mission authorization determine platform sophistication, with military operators commanding integrated digital architectures unavailable to civilian agencies.
- Military Forces:National defense ministries procuring through NATO framework agreements or bilateral state-to-state contracts. The United States and Poland are anchoring multi-billion dollar tracked and wheeled replacement programs as mechanized force structures confront hardened peer adversaries.
- Law Enforcement:Internal security forces requiring crowd-control payload flexibility and narrow-street maneuverability. French and German police agencies are generating demand for compact urban warfare configurations optimized for riot containment and high-value convoy protection.
- Government Agencies:Border control and critical infrastructure protection units operating under constrained procurement protocols.
- Private Security:Commercial contractors acquiring surplus military platforms or purpose-built armored SUVs for executive protection details.
Military orders dominate absolute volume; law enforcement represents the steepest expansion trajectory as European internal security budgets decouple from defense spending cycles.
Configuration:
Mission profile dictates hull architecture, with direct-fire platforms requiring turret integration and transport variants prioritizing payload volume over armor thickness.
- Combat Vehicle:Infantry fighting vehicle derivatives with stabilized autocannon mounts and anti-tank missile integration. Polish procurement offices are mandating these configurations in next-generation mechanized brigade tenders as NATO standardization pressures align national requirements.
- Transport Vehicle:Squad carriers with dismountable seating and medical evacuation payload flexibility. Demand remains stable from United Nations peacekeeping contingents and humanitarian missions where troop capacity outweighs direct-fire survivability.
- Reconnaissance Vehicle:Surveillance-integrated platforms with mast-mounted sensors and low-observable hull shaping.
- Command Vehicle:Battle management system nodes with hardened communication suites and extended operational endurance.
Combat configurations absorb the largest share of new procurement; transport variants are gaining share fastest as peacekeeping mission requirements expand.
Technology:
Capability insertion points cluster around survivability enhancements and digital architecture integration, with regulatory certification emerging as a procurement gatekeeper.
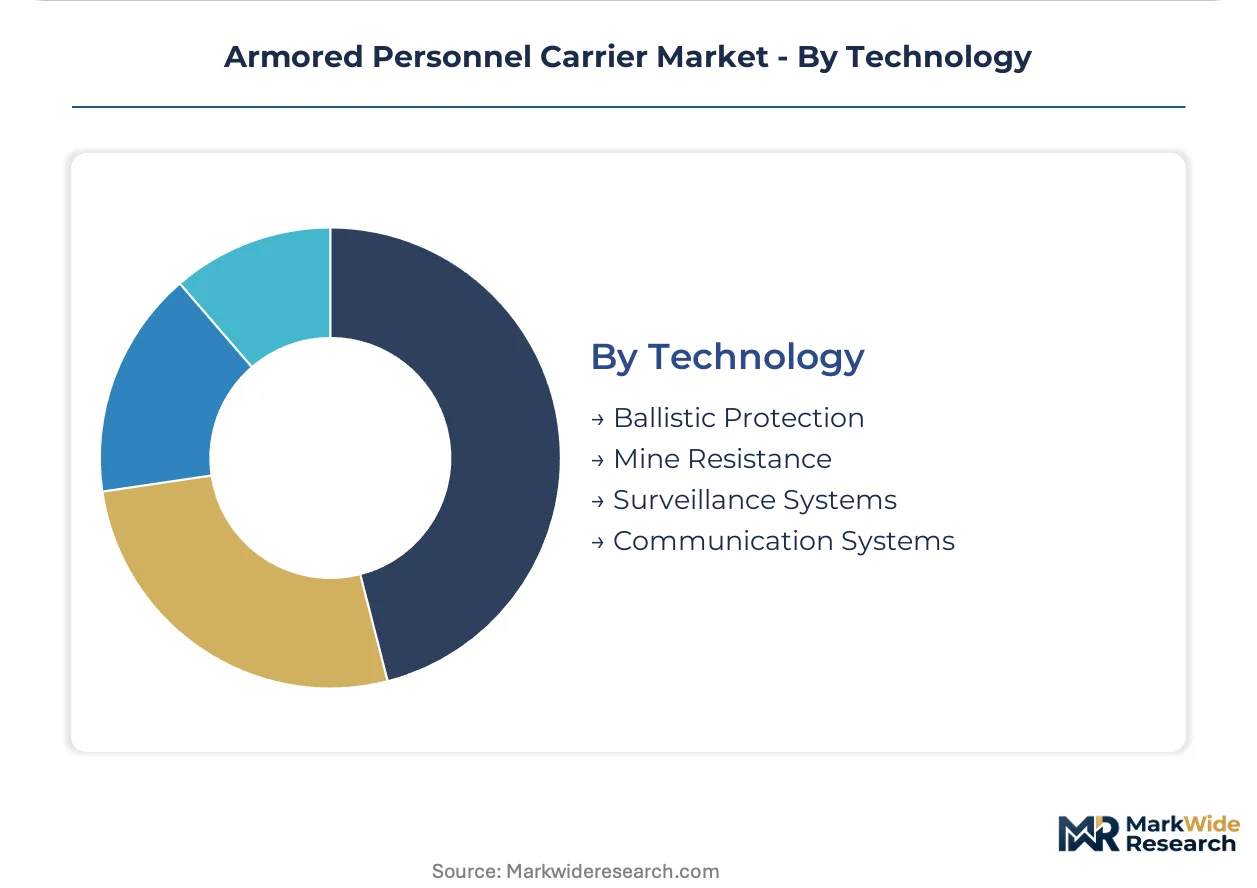
- Mine Resistance:Layered ceramic and polymer composite matrices absorbing blast energy through controlled delamination. German and Polish tenders are now mandating these materials as EU Green Deal defense industrial adaptation measures reshape procurement criteria toward advanced protection systems.
- Surveillance Systems:Electro-optical and infrared sensor suites with algorithmic target classification. The EU AI Act's risk-based framework is imposing additional validation burdens on autonomous subsystem certification, compressing supplier margins for reconnaissance platform integrators.
- Ballistic Protection:Homogeneous and composite armor rated against kinetic energy penetrators and shaped charges.
- Communication Systems:Software-defined radios with NATO interoperability protocols and anti-jam waveforms.
Ballistic protection retains the largest installed base; mine resistance technology is climbing the fastest as blast-threat environments proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones across Central Europe are concentrating armored vehicle production capacity as defense procurement accelerates. Poland's Legnica Special Economic Zone and Germany's Saxony-Anhalt investment corridors anchor the continent's manufacturing density for tracked and wheeled platforms.
United States
The US Department of Defense's multi-billion dollar ground combat vehicle recapitalization drives demand for next-generation infantry carriers. NHTSA and DoD safety standards govern platform certification for domestic and export variants. Michigan and Ohio industrial corridors host the densest concentration of armor fabrication and systems integration facilities.
Germany
Bundeswehr modernization tenders mandate cross-border industrial participation under EU Defence Fund co-financing rules. The EU Green Deal's defense industrial adaptation measures reshape procurement criteria toward lower-emission propulsion architectures. Kassel and Munich production clusters anchor Rheinmetall AG and KNDS manufacturing footprints for NATO joint programs.
Poland
Warsaw's unprecedented mechanized brigade recapitalization anchors European production capacity expansion through multi-billion dollar contracts. EU Defence Fund joint capability development programs pool resources with neighboring Baltic states. Poznań and Świętoszów industrial zones concentrate final assembly and armor subsystem fabrication for wheeled platform fleets.
France
Internal security forces generate demand for compact urban warfare configurations optimized for narrow-street maneuverability. ANSM and CNIL cybersecurity validation requirements filter vendor eligibility for surveillance-integrated platforms. Auvergne-Rhône-Alpes and Île-de-France defense industrial bases specialize in command vehicle digital architectures and active protection systems.
United Kingdom
BAE Systems sustains transatlantic relevance through its US-UK dual-base manufacturing architecture for tracked vehicle exports. Ministry of Defence procurement offices align with NATO Standardization Office interoperability mandates for command-and-control interfaces. Telford and Newcastle production sites concentrate on medium-weight reconnaissance vehicle configurations.
Armored Personnel Carrier Market Competitive Environment
North American producers anchor one tier; European specialists hold integrated design-to-fielding positions across NATO framework agreements. The vendor base clusters around consolidated defense primes with captive armor fabrication and modular subsystem integration capabilities. Two archetypes dominate: pan-European production network operators and transatlantic dual-base manufacturers. Competitive moves concentrate on strategic partnerships for hybrid-electric propulsion development and cross-certification agreements for EU AI Act compliance.
Within the transatlantic tier, General Dynamics Corporation and BAE Systems exemplify dual-hemisphere manufacturing architectures that penetrate both US and European tenders. Rheinmetall AG occupies a position as the anchor European producer leveraging its pan-continental footprint to secure Bundeswehr and NATO joint program awards. These three entities represent the dominant competitive anchors around which mid-tier subsystem suppliers and national champions organize bidding consortia.
| Leading Market Players |
|---|
| General Dynamics Corporation |
| BAE Systems |
| Rheinmetall AG |
| Oshkosh Defense |
| Krauss-Maffei Wegmann |
| Navistar International |
| Patria Oyj |
| KNDS |
| Elbit Systems |
| Others |
Value Chain & Pricing Dynamics
Hybrid-electric propulsion architecture adoption is simultaneously compressing powertrain cost curves and redistributing supplier power toward battery subsystem specialists in Germany and Poland. This technological pivot forces traditional armor fabricators to absorb new certification burdens while competing for platform integration slots against emerging electro-mobility vendors.
Pricing Analysis
Lead-time premiums dominate contract negotiations, with Bundeswehr and NATO joint program offices paying substantial markups for accelerated delivery schedules while spot inventory of surplus wheeled platforms trades at steep discounts. Three-tier pricing structure across premium, standard, and economy levels separates active-protection-integrated heavy vehicles from baseline transport configurations and refurbished legacy fleets. Cost compression in wheeled platform segments is intensifying because Polish production capacity expansion has shortened order backlogs. Budget-constrained operators in the Baltic corridor exhibit the highest price sensitivity, whereas Middle Eastern end users prioritizing mine-resistance specifications demonstrate minimal elasticity.
Supply Chain Analysis
Workforce availability constraints in Kassel, Poznań, and Michigan industrial corridors are extending component qualification timelines for ballistic-grade armor subsystem integration. Geographic supply concentration centers on Germany, Poland, and the United States for final assembly and systems integration, with ceramic armor plate drawing from specialized European foundries and active protection electronics sourcing from Israeli and South Korean component houses. Single-source vulnerability in high-hardness steel alloy supply exposes programs to input cost volatility. Distribution runs through NATO Support and Procurement Agency framework agreements and bilateral state-to-state contracts rather than open commercial channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The armored personnel carrier market occupies a technology-transition phase as active protection systems and autonomous mobility architectures displace passive armor physics as the primary survivability determinant.
For Market Incumbents: Extend platform lifecycle value through software-defined capability insertion, retrofitting digital command-and-control architectures onto existing hull inventories to counter emerging pure-play electro-mobility entrants. Deepen backward integration into ceramic armor matrix production in Poland and Germany to secure input cost stability against specialized steel alloy supply volatility. Prioritize EU AI Act certification investment for surveillance-integrated reconnaissance variants before regulatory divergence fragments addressable market scope. For New Entrants and Emerging Players: Defense technology integrators represent the most accessible channel partner type for penetrating NATO joint program bidding consortia without captive fabrication assets. White-space targets cluster around urban warfare configurations for French and German internal security forces, where compact vehicle demand outpaces established vendor product pipelines, and hybrid-electric subsystem supply to incumbent platform primes lacking in-house electro-mobility expertise. Go-to-market execution should anchor on modular active protection system licensing rather than full-platform competition. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to pan-European defense primes seeking geographic production footprint expansion. Long-term viability favors suppliers with demonstrated NATO Standardization Office interoperability certification and cross-border industrial participation track records. Acquisition target archetypes include mid-tier ceramic armor matrix specialists and software-defined radio subsystem vendors with Bundeswehr validation history. The signal to watch is EU Defence Fund co-financing allocation shifts toward lower-emission propulsion platforms, which would re-rate hybrid-electric capability vendors relative to traditional powertrain suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid-Electric Propulsion Development | EU Green Deal compliance opens protected contracting lanes in Bundeswehr tenders. |
| Mine-Resistant Hull Composite Integration | German and Polish procurement mandates accelerate ceramic armor matrix adoption. |
| EU AI Act Certification Investment | Algorithmic transparency requirements filter reconnaissance platform vendor eligibility. |
| NATO Standardization Office Alignment | Common command-and-control interfaces enable modular subsystem market penetration. |
| Cross-Border Industrial Participation | Joint capability development programs pool Baltic and Central European demand. |
Study Parameters
Document review covered NATO Standardization Office technical specifications, EU Defence Fund program documentation, and national procurement office tender records, complemented by interviews with Bundeswehr platform engineering directors, Polish Ministry of National Defence acquisition leads, Rheinmetall AG program managers, ceramic armor subsystem technical directors, and NATO Support and Procurement Agency contracting officers. Secondary validation drew from SEC 10-K defense segment disclosures, EU official journal contract awards, and national military planning white papers. Bottom-up platform delivery forecasts were triangulated against top-down defense budget appropriation analysis.
Historical delivery volumes were cross-referenced against expert panel input from former national armaments directors and active protection system engineering specialists. Segmentation modeling tracked vehicle type, end user, configuration, and technology insertion point across the projection horizon. CAGRs were derived from weighted regression of platform replacement cycle compression and EU Green Deal procurement criteria evolution. Industry-specific forecast inputs included NATO mechanized force recapitalization commitment levels and blast-protection standard escalation timelines in Middle Eastern operator specifications.
Several conditions sit outside the modeled scope, including sudden geopolitical alliance restructuring, radical propulsion technology disruption beyond hybrid-electric architectures, and divergent national transposition of EU AI Act surveillance system classifications. Forecasts reflect assumptions regarding sustained NATO joint program preference over bilateral procurement fragmentation. Material deviation in EU Defence Fund allocation priorities or specialized steel alloy supply disruptions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Armored Vehicles
Armored Vehicles Upgrade and Retrofit Market
Armored Vehicles
Armor Protection Systems Market
Armored Vehicles
North America Armored Fighting Vehicles Market
Armored Vehicles
Global Ceramic Armor Market
Armored Vehicles
Boom Arms Market
Armored Vehicles
US Armored Vehicle Market
Armored Vehicles
Armored Vehicle Fire Suppression Systems Market
Armored Vehicles
Armoured Personnel Carrier (APC) Market
Armored Vehicles
Middle-East and Africa Armored Vehicles Market
Armored Vehicles
Asia-Pacific Armored Fighting Vehicles Market
Armored Vehicles
Armored Fighting Vehicles Market
Armored Vehicles
Armored Vehicle Navigation Systems Market
Armored Vehicles
Europe Armored Fighting Vehicles Market
Armored Vehicles
Armored Vehicle Procurement and Upgrade Market
Armored Vehicles
Armored Vehicles Market
Armored Vehicles
Military Armored Car Market