
 Military Armored Car Market | 2026-2036
Military Armored Car Market Size, Share, and Industry Trends Forecast 2026-2036
Military Armored Car Market Insights
Border security agencies is rotating share from traditional defense forces as asymmetric threats redefine procurement priorities. Rheinmetall AG leverages its integrated armor steel foundry to control supply timelines for European buyers. BAE Systems anchors UK demand through its long-running Ministry of Defence service contracts. Elbit Systems differentiates via active protection systems and electro-optical suites that retrofit onto existing platforms.
Military armored cars are wheeled or tracked combat vehicles engineered with hardened steel or composite armor hulls, typically rated to STANAG 4569 Level 2-4 for ballistic and blast threats, designed to transport personnel and equipment through hostile environments while maintaining tactical mobility. Light armored vehicles lead volume due to their versatility in urban reconnaissance and rapid deployment scenarios, while mine-resistant ambush protected vehicles command premium positioning as legacy MRAP fleets age and require replacement. Ballistic resistance specifications dominate engineering focus, though NBC protection configurations are gaining traction among peacekeeping organizations operating in chemically contested zones.
STANAG 4569 shapes NATO member procurement by mandating unified protection benchmarks, while the EU Green Deal pressures manufacturers to reduce diesel dependency in military fleets. The US Department of Defense's modular open systems approach directive accelerates electronics refresh cycles across platforms. Stakeholders must weigh armor weight trade-offs against electrification timelines as hybrid drivetrain development advances.
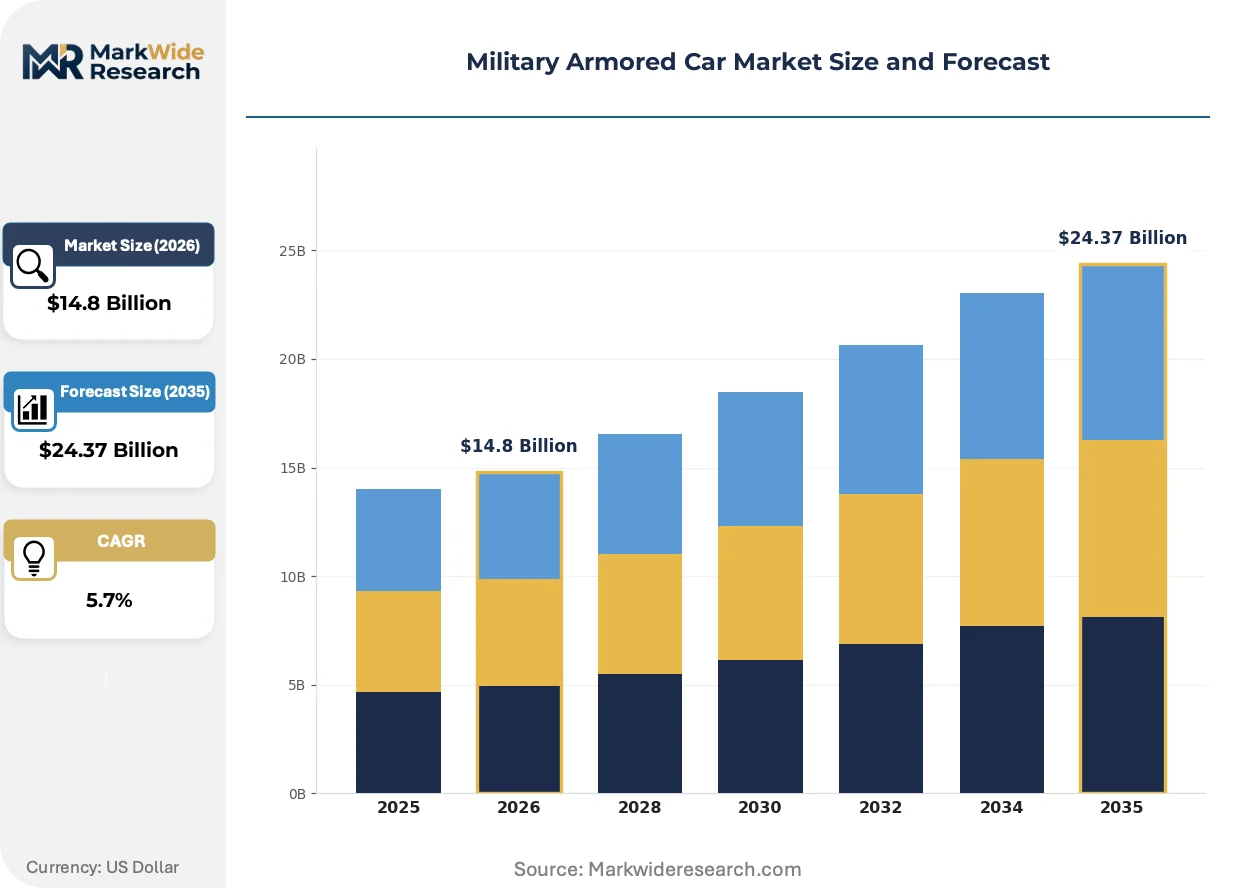
Market Dynamics
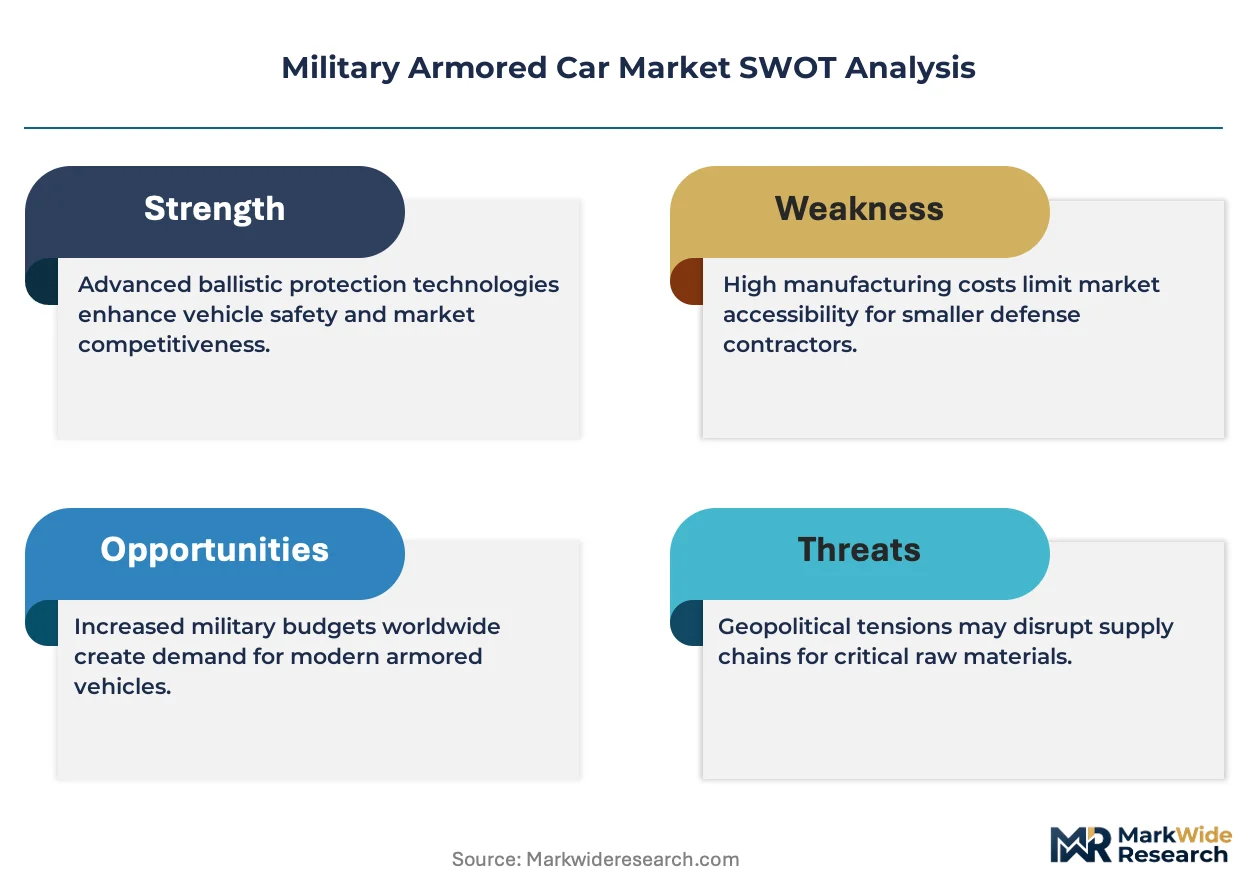
STANAG 4569 ballistic protection standards are forcing NATO members to retire legacy wheeled fleets faster than original depreciation schedules anticipated, compressing replacement cycles and redirecting procurement budgets toward modular armor systems.
Growth Catalysts
- Asymmetric Warfare Doctrine:Border security agencies in the Middle East prioritize light armored vehicles for counter-insurgency patrols along porous frontiers, creating sustained demand for mine-resistant platforms with rapid deployment capability.
- EU Green Deal:Military fleet electrification mandates are accelerating hybrid drivetrain development programs, opening procurement windows for platforms demonstrating reduced diesel dependency.
- NBC Protection Configurations:Peacekeeping organizations operating in chemically contested zones are specifying sealed hull systems with collective protection, expanding addressable market beyond traditional ballistic specifications.
Market Restraints
- Armor Steel Supply Concentration:Integrated foundry capacity concentrates in Central Europe, exposing buyers to extended lead times when geopolitical disruptions affect raw material flows.
- Weight-Mobility Trade-off:STANAG Level 4 protection requirements add substantial mass that degrades tactical mobility in urban reconnaissance scenarios, limiting platform versatility.
- Active Protection System Costs:Electro-optical suites and hard-kill interceptors require specialized maintenance infrastructure that many operating forces lack, constraining adoption to elite units.
Strategic Opportunities
- Retrofit Market Expansion:Aging MRAP fleets in the United States require electronics refresh and armor upgrades rather than full replacement, creating aftermarket service revenue streams.
- Modular Open Systems Architecture:The US Department of Defense directive mandating interoperable electronics interfaces enables third-party subsystem integration, lowering barriers for specialized technology providers.
- Urban Warfare Specialization:Saudi Arabia and UAE procurement patterns favor compact armored cars with 360-degree situational awareness for dense operational environments.
Industry Challenges
- Ballistic Certification Timelines:STANAG 4569 live-fire testing protocols extend development cycles by 18-24 months, delaying platform fielding and freezing procurement decisions.
- Electronics Integration Complexity:Legacy analog systems in existing fleets resist seamless interfacing with digital command-and-control networks, forcing expensive platform-wide rewiring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military Armored Car Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $24.37 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Light Armored Vehicles, Medium Armored Vehicles, Heavy Armored Vehicles, Mine-Resistant Ambush Protected Vehicles Protection Level: Ballistic Resistance, Blast Resistance, Chemical Resistance, NBC Protection Deployment Mode: Reconnaissance, Troop Transport, Command & Control, Medical Evacuation End User: Defense Forces, Paramilitary Units, Peacekeeping Organizations, Border Security Agencies |
| Companies Covered | General Dynamics Corporation, BAE Systems, Rheinmetall AG, Oshkosh Defense, Textron, Hanwha Defense, Elbit Systems, IVECO, INKAS Armored Vehicle Manufacturing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military Armored Car Market Trends and Innovations
Electrification and active protection systems are fragmenting traditional armored vehicle design paradigms, while procurement patterns shift toward modular upgradeability rather than platform longevity.
Composite ceramic armor is fragmenting the historic dominance of rolled homogeneous steel in hull construction. Special operations forces across NATO are specifying silicon carbide and boron carbide tile arrays for weight-critical applications. This material transition is fragmenting supplier bases as traditional steel foundries lose share to aerospace-derived ceramic processors.
The EU Green Deal is mandating carbon footprint disclosures for defense procurement above specified contract values. European manufacturers must now document lifecycle emissions from armor production through platform retirement. Light armored vehicle segments face the steepest compliance costs due to higher production volumes and shorter service lives.
Buyer preference is compressing toward platform-agnostic subsystem procurement. Defense ministries are unbundling electronics, armor kits, and powertrain components from prime contractor specifications. This behavior is most visible in United Kingdom Ministry of Defence contracts, where service-based agreements now dominate capital acquisition for reconnaissance vehicle fleets.
Military Armored Car Market Segmentation
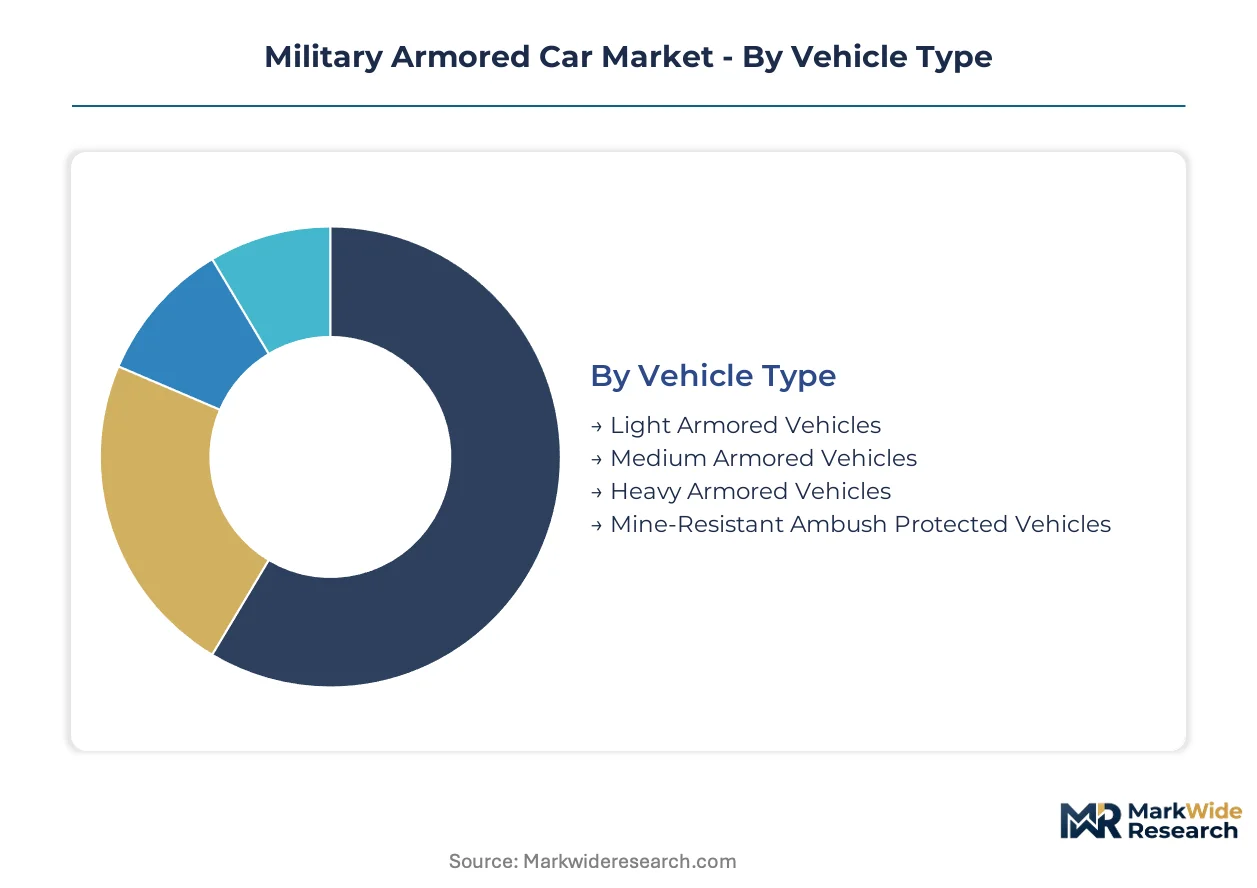
Military armored car segmentation reveals divergent margin pools across protection tiers and deployment modes. Vehicle classification and end-user identity determine procurement timelines, certification requirements, and aftermarket service attach rates.
Vehicle Type:
Margin concentration sits with platforms balancing protection density against tactical mobility, where weight-optimized designs command premium positioning.
- Light Armored Vehicles:Wheeled platforms rated to STANAG Level 2-3 with aluminum or composite hulls prioritize rapid air-transportability. Border security agencies in Saudi Arabia and the UAE concentrate procurement for desert patrol corridors, driven by asymmetric threat profiles requiring high dash speeds across open terrain.
- Mine-Resistant Ambush Protected Vehicles:V-hull geometries and suspended crew capsules define these blast-deflecting platforms. United States Army retrofits dominate demand as legacy MRAP fleets require electronics modernization rather than replacement, constrained by congressional budget caps on new capital programs.
- Medium Armored Vehicles:Multi-role platforms bridging reconnaissance and infantry transport functions with modular armor kits.
- Heavy Armored Vehicles:Tracked or 8x8 wheeled systems carrying autocannon armament and STANAG Level 4+ protection for frontline mechanized units.
The dominant share belongs to Light Armored Vehicles, while Mine-Resistant Ambush Protected Vehicles are closing the gap fastest through retrofit-driven service revenue.
Protection Level:
Certification cost structures fragment this category, with live-fire testing protocols extending development timelines disproportionately for higher-tier ratings.
- Ballistic Resistance:Hardened steel or ceramic composite arrays defeating 7.62mm to 14.5mm ammunition per STANAG 4569 Level 2-4 specifications. NATO member defense forces anchor procurement, compelled by alliance standardization mandates to retire legacy wheeled fleets ahead of original depreciation schedules.
- NBC Protection:Sealed hull systems with collective filtration and overpressure maintenance against chemical, biological, and radiological agents. Peacekeeping organizations operating in Syria and Eastern Ukraine specify these configurations, expanding addressable market beyond traditional ballistic specifications into chemically contested zones.
- Blast Resistance:Underbody armor geometries and energy-absorbing seating designed to mitigate mine and IED detonation effects.
- Chemical Resistance:Specialized coatings and material selections preventing agent penetration at lower certification cost than full NBC systems.
Ballistic Resistance retains the largest installed base, though NBC Protection is expanding most quickly through United Nations procurement windows.
Deployment Mode:
Application-specific electronics integration requirements create divergent engineering cost profiles across operational roles.
- Reconnaissance:Compact platforms with 360-degree electro-optical suites and silent-watch power systems. Saudi Arabian procurement patterns favor these configurations for urban warfare scenarios in dense operational environments, requiring compact turning radii and elevated situational awareness.
- Command & Control:C4ISR-integrated hulls with electromagnetic interference shielding and expanded internal volume for staff operations. British Army service-based contracts prioritize these variants, shifting from capital acquisition to through-life support agreements.
- Troop Transport:High-capacity configurations maximizing personnel carriage over protection density or mobility.
- Medical Evacuation:Specialized variants with surgical lighting, climate control, and stretcher mounting systems for forward trauma stabilization.
Reconnaissance platforms lead procurement volume, while Command & Control variants show the steepest expansion trajectory through NATO digital modernization programs.
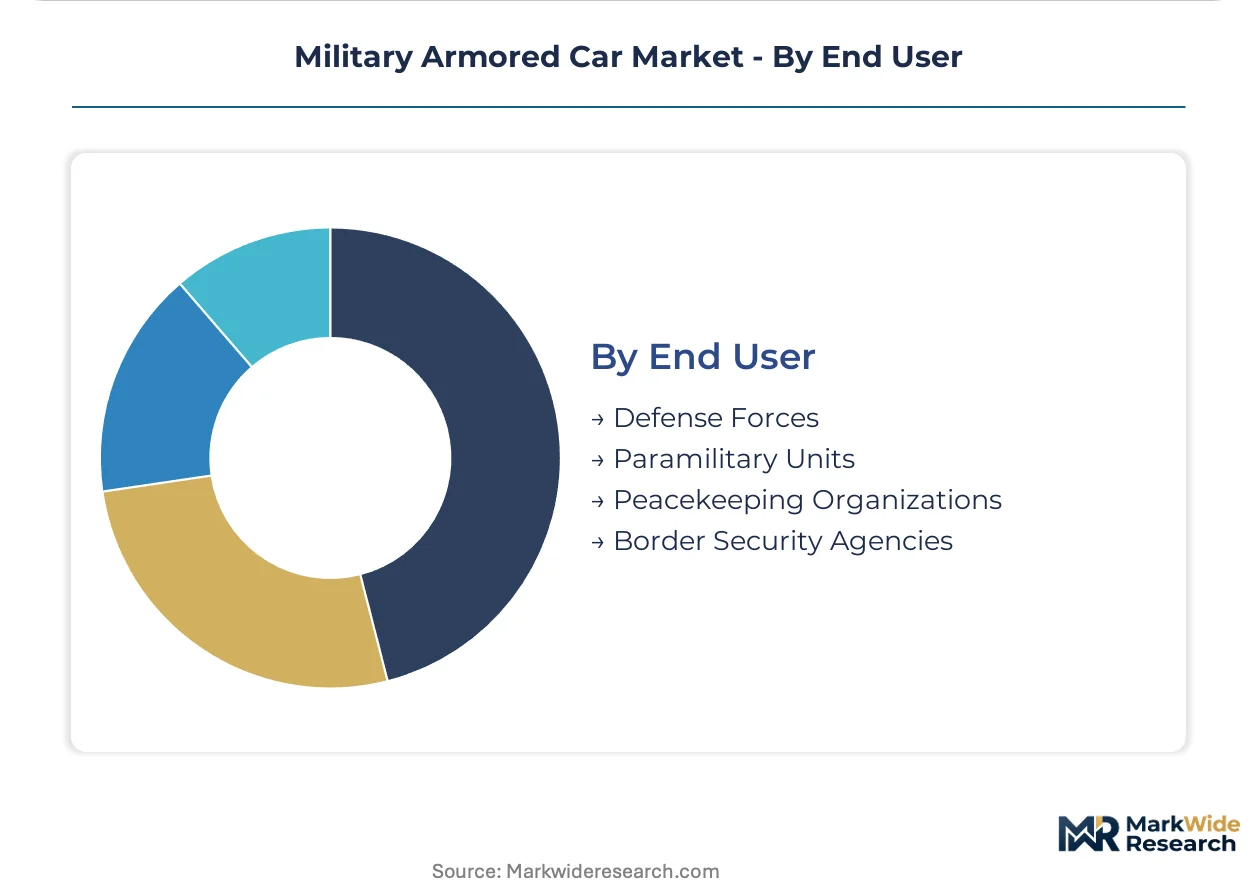
End User:
Budget cycle predictability and maintenance infrastructure sophistication vary sharply across institutional buyer categories.
- Defense Forces:National military establishments with standardized fleet management and depot-level maintenance capabilities. United States Department of Defense modular open systems directives accelerate electronics refresh cycles, mandating interoperable interfaces across prime contractor platforms.
- Border Security Agencies:Paramilitary organizations prioritizing light armored vehicles for counter-insurgency patrols. Middle Eastern procurement concentrates here as asymmetric warfare redefines security priorities, with porous frontiers demanding mine-resistant platforms deployable by tactical airlift.
- Paramilitary Units:Internal security forces with limited technical maintenance infrastructure and rapid deployment requirements.
- Peacekeeping Organizations:Multinational bodies with pooled procurement budgets and strict neutrality markings requirements.
Defense Forces command the dominant procurement share, while Border Security Agencies are gaining share fastest as traditional military budgets face pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Trans-Arabian Pipeline corridor and Red Sea port infrastructure at Jeddah anchor Saudi Arabia's position as the primary demand center for armored vehicle procurement in the Middle East.
United States
Congressional budget caps on new capital programs and the modular open systems approach directive from the Department of Defense are accelerating electronics refresh cycles for legacy MRAP fleets. The Pentagon's through-life support agreements now dominate reconnaissance vehicle procurement over outright purchase. Industrial activity clusters around the Detroit Arsenal in Michigan and the Red River Army Depot in Texas, where retrofit and modernization work concentrates.
Germany
NATO STANAG 4569 standardization mandates and the EU Green Deal's carbon footprint disclosure requirements are compressing development timelines while forcing electrification roadmaps for military fleets. Rheinmetall AG's integrated armor steel foundry in Unterlüß gives domestic buyers supply timeline advantages unavailable to foreign purchasers. The Kiel Canal logistics corridor supports rapid platform deployment to Baltic frontier states.
Saudi Arabia
Asymmetric warfare doctrine along the Yemen border and urban warfare specialization for dense operational environments in Riyadh and Jeddah are driving compact armored car specifications with 360-degree situational awareness. The Saudi Arabian Military Industries localization program mandates increasing domestic content shares in procurement contracts. Vehicle assembly and armor integration facilities concentrate in the King Salman Industrial City in Ras Al-Khair.
United Kingdom
Ministry of Defence service-based contracts shifting from capital acquisition to through-life support agreements are reshaping supplier relationships toward long-term platform stewardship. British Army digital modernization programs prioritize C4ISR-integrated command variants over troop transport configurations. Industrial capability clusters in the West Midlands around Telford and Newcastle-under-Lyme, where BAE Systems maintains deep service infrastructure.
Israel
Active protection system development and electro-optical suite integration for retrofit markets are creating export-oriented engineering capabilities serving NATO upgrade cycles. Elbit Systems anchors a defense technology cluster in Haifa and the Negev region, with specialized maintenance infrastructure supporting regional operator forces lacking indigenous technical depth.
Military Armored Car Market Competitive Landscape
Concentration sits with diversified defense conglomerates possessing integrated armor production and government service contract portfolios. Prime contractors with captive steel foundries and long-running ministry relationships control timeline-critical procurement windows, while specialized technology providers capture subsystem integration opportunities opened by modular open systems directives. Three archetypes dominate: vertically integrated armor manufacturers, electronics-focused retrofit specialists, and state-affiliated champions serving domestic preference policies. Competitive dynamics center on M&A activity consolidating foundry capacity and strategic partnerships securing raw material supply chains against geopolitical disruption.
Within the diversified defense conglomerate tier, General Dynamics Corporation and BAE Systems exemplify scale-driven platform stewardship through service-based contract structures. Rheinmetall AG represents the vertically integrated archetype with captive armor steel production. Among Middle East-based specialists, Elbit Systems occupies a position bridging active protection technology development and NATO retrofit demand.
| Leading Market Players |
|---|
| General Dynamics Corporation |
| BAE Systems |
| Rheinmetall AG |
| Oshkosh Defense |
| Textron |
| Hanwha Defense |
| Elbit Systems |
| IVECO |
| INKAS Armored Vehicle Manufacturing |
| Others |
Pricing and Supply Chain Analysis
Composite ceramic armor substitution for rolled homogeneous steel is redrawing supplier geography toward aerospace-derived processors while compressing price premiums historically commanded by integrated European foundries. This material transition simultaneously fragments procurement channels and erodes legacy cost structures anchored in captive steel production.
Pricing Analysis
Volume-discount tiering structures in military armored car procurement stratify across STANAG certification levels, with Level 4 platforms commanding substantial premiums over Level 2-3 configurations due to extended live-fire testing protocols. Price differentiation hinges on ballistic certification grade and after-sales service bundling, where through-life support agreements now dominate British Army and United States Department of Defense contracts. Cost compression in light armored vehicle segments is intensifying because EU Green Deal compliance mandates add certification overhead without commensurate capability gains. Border security agencies exhibit the highest price sensitivity, constrained by paramilitary budget cycles, while national defense forces with depot-level maintenance infrastructure absorb premium positioning for active protection systems.
Supply Chain Analysis
Strategic stockpiling of armor-grade steel and ceramic precursor materials dominates inventory strategy, as STANAG 4569 certification timelines extend 18-24 months and reward supply security over just-in-time efficiency. Geographic supply concentration centers on Germany, France, and South Korea for rolled homogeneous steel and ceramic composites, with rare earth processing for advanced armor additives drawing from Chinese separation facilities. Raw material dependencies span nickel-alloy steel billets, boron carbide powders, and silicon carbide substrates. Single-source vulnerability in Central European foundry capacity exposes buyers to extended lead times when geopolitical disruptions affect raw material flows. Distribution runs through prime contractor assembly facilities with government-directed logistics corridors, notably the Kiel Canal for Baltic deployments and Trans-Arabian Pipeline-adjacent infrastructure for Saudi Arabian deliveries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Military armored car procurement sits at an early-cycle expansion story, with asymmetric warfare doctrine and NATO STANAG 4569 fleet modernization creating sustained replacement demand across European and Middle Eastern buyers.
For Market Incumbents: Compound defensive positioning through captive foundry capacity expansion in Central Europe and certification investment for NBC protection configurations. Vertical integration into ceramic armor processing counters the threat of aerospace-derived suppliers fragmenting traditional steel-dominated supply structures. Service-based contract structures with the British Ministry of Defence and United States Department of Defense anchor recurring revenue against capital program volatility.
For New Entrants and Emerging Players: Lead with subsystem specialization targeting the retrofit electronics market opened by modular open systems architecture directives. The United States MRAP fleet modernization represents the most penetrable segment, with third-party electro-optical suite integration offering lower barriers than prime platform competition. A go-to-market angle anchored in rapid certification timelines for STANAG Level 2-3 configurations bypasses the 18-24 month development cycles that freeze incumbent procurement decisions.
For Investors and Strategic Acquirers: The market sits at a standardization phase that favors vertically integrated armor manufacturers with government service contract portfolios. Long-term viability over the next decade hinges on electrification readiness and hybrid drivetrain development pipelines. Acquisition targets should demonstrate integrated ceramic processing capabilities or active protection system intellectual property. The signal to watch is European Union defense procurement contract awards for carbon-disclosed platforms, which will separate electrification-capable suppliers from legacy diesel-dependent fleets.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Foundry Capacity Expansion | Rheinmetall's integrated Unterlüß facility secures supply timeline advantages for NATO buyers. |
| Modular Open Systems Certification | United States Department of Defense interoperability mandates enable third-party electronics integration. |
| Ceramic Armor Processing Investment | Silicon carbide tile arrays displace steel in special operations weight-critical applications. |
| Through-Life Support Agreement Conversion | British Army service contracts shift supplier relationships from capital sale to platform stewardship. |
| Hybrid Drivetrain Development Program | EU Green Deal carbon disclosure requirements accelerate electrification roadmap investments. |
Research Methodology
Desk research of NATO procurement databases, national defense ministry budget disclosures, and STANAG 4569 certification records preceded structured interviews with platform engineering directors, military procurement officers, armor materials specialists, and aftermarket service heads. Primary fieldwork across German, British, Saudi Arabian, and United States defense industrial clusters combined with secondary validation from customs trade data, SEC 10-K filings, and EU defense procurement transparency registers. Bottom-up platform shipment tallies by protection level and deployment mode triangulated against top-down defense budget allocation analysis.
Variance decomposition across vehicle type, protection tier, deployment mode, and end-user category anchored the analytical framework over the projection horizon. Segmentation dimensions modeled include light through heavy armored vehicle classifications, STANAG Level 2-4 ballistic ratings, reconnaissance versus command configurations, and defense force versus border security agency procurement patterns. CAGRs derived from replacement cycle compression analysis and fleet modernization program announcements. Industry-specific forecast inputs encompass congressional budget cap trajectories and Saudi Arabian Military Industries localization mandates.
Forecasts assume regulatory continuity in NATO standardization regimes and EU Green Deal implementation timelines; material policy shifts would require re-modeling. Specific risks that could revise projections include STANAG protocol amendments extending certification timelines, rare earth export restrictions affecting ceramic armor supply, and congressional appropriation freezes on United States MRAP modernization. Revision becomes warranted when electrification technology readiness levels cross procurement thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Armored Vehicles
Armored Vehicles Market
Armored Vehicles
Global Ceramic Armor Market
Armored Vehicles
Asia-Pacific Armored Fighting Vehicles Market
Armored Vehicles
Europe Armored Fighting Vehicles Market
Armored Vehicles
Armoured Personnel Carrier (APC) Market
Armored Vehicles
Armored Vehicle Fire Suppression Systems Market
Armored Vehicles
US Armored Vehicle Market
Armored Vehicles
North America Armored Fighting Vehicles Market
Armored Vehicles
Armored Vehicles Upgrade and Retrofit Market
Armored Vehicles
Armored Personnel Carrier Market
Armored Vehicles
Middle-East and Africa Armored Vehicles Market
Armored Vehicles
Armor Protection Systems Market
Armored Vehicles
Armored Vehicle Navigation Systems Market
Armored Vehicles
Armored Fighting Vehicles Market
Armored Vehicles
Armored Vehicle Procurement and Upgrade Market
Armored Vehicles
Boom Arms Market