
 Boom Arms Market | 2026-2036
Boom Arms Market Size, Share, and Industry Trends Forecast 2026-2036
Boom Arms Market Analytics
Maintenance-as-a-service and remote diagnostics is consolidating how boom arm OEMs monetize equipment lifecycles. Shure leverages its channel control in broadcast-adjacent verticals to cross-sell articulating configurations. Audio-Technica anchors its position through manufacturing scale in precision-machined joint assemblies. RODE competes on brand strength within content creator ecosystems where lighter-duty boom arms command premium positioning.
A boom arm is a cantilevered support structure, typically fabricated from high-strength steel or aluminum alloy with wall thicknesses of 2–5 mm, designed to extend reach while managing torsional loads in material handling and load lifting operations. Its primary industrial purpose centers on positioning heavy equipment or suspended loads beyond the fixed footprint of base machinery. Articulating boom arms now lead product type demand due to their maneuverability in confined construction and marine environments, while hydraulic technology captures the dominant margin pool given the complexity of sealed actuator systems and aftermarket parts dependency. Telescoping configurations represent the fastest-growing structural category as mining operators pursue extended vertical reach without rebase repositioning.
OSHA crane and derrick standards in the United States, the EU Machinery Directive and CE marking requirements in Europe, and ISO 4301 classification frameworks collectively shape boom arm design loads, inspection intervals, and market access protocols across jurisdictions. Compliance with these regimes now determines whether OEMs can bid on government-backed infrastructure tenders or marine classification society approvals. Stakeholders must monitor how evolving carbon accounting rules for steel production cascade into material certification costs and supplier qualification timelines.
Market Dynamics
Hydraulic system efficiency mandates from the EU Machinery Directive are forcing OEMs to redesign sealed actuator architectures, while mining operators in Brazil and Australia drive procurement volume for extended-reach telescoping configurations. This dual pressure from regulatory compliance and end-use demand is compressing product development cycles across the supply base.
Growth Catalysts
- EU Machinery Directive CE marking:Certification requirements for hydraulic boom arms are filtering out uncertified suppliers and consolidating procurement toward compliant OEMs with established testing protocols.
- Deep extraction mining:Operators in Chile and South Africa are commissioning telescoping boom arms to access ore bodies beyond conventional reach without rebase repositioning.
- High-strength aluminum alloys:Fabricators are substituting 2–5 mm wall thickness aluminum for steel in marine articulating configurations to reduce corrosion maintenance.
Market Restraints
- Steel input cost volatility:Carbon accounting rules for steel production are cascading into material certification costs and extending supplier qualification timelines for OEMs.
- Hydraulic component supply concentration:Sealed actuator systems depend on a narrow base of certified European and Japanese component suppliers, creating bottleneck risk.
- ISO 4301 classification complexity:Load rating and inspection interval requirements vary across jurisdictions, fragmenting design standardization and raising compliance overhead.
Strategic Opportunities
- Maintenance-as-a-service monetization:Remote diagnostics platforms allow OEMs to capture recurring revenue across equipment lifecycles rather than one-time hardware sales.
- Brazil bulk material handling:Port and mining infrastructure expansion is concentrating new boom arm procurement demand in a geography with limited local fabrication capacity.
- EU Green Deal steel certification:Early compliance with embodied carbon tracking creates preferential positioning for government-backed infrastructure tenders.
Industry Challenges
- Hydraulic technician scarcity:Sealed actuator system repair and field calibration require specialized skills that outpace vocational training pipeline output.
- Marine classification society approval timelines:Articulating configurations for offshore applications face extended certification cycles that delay revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Boom Arms Market |
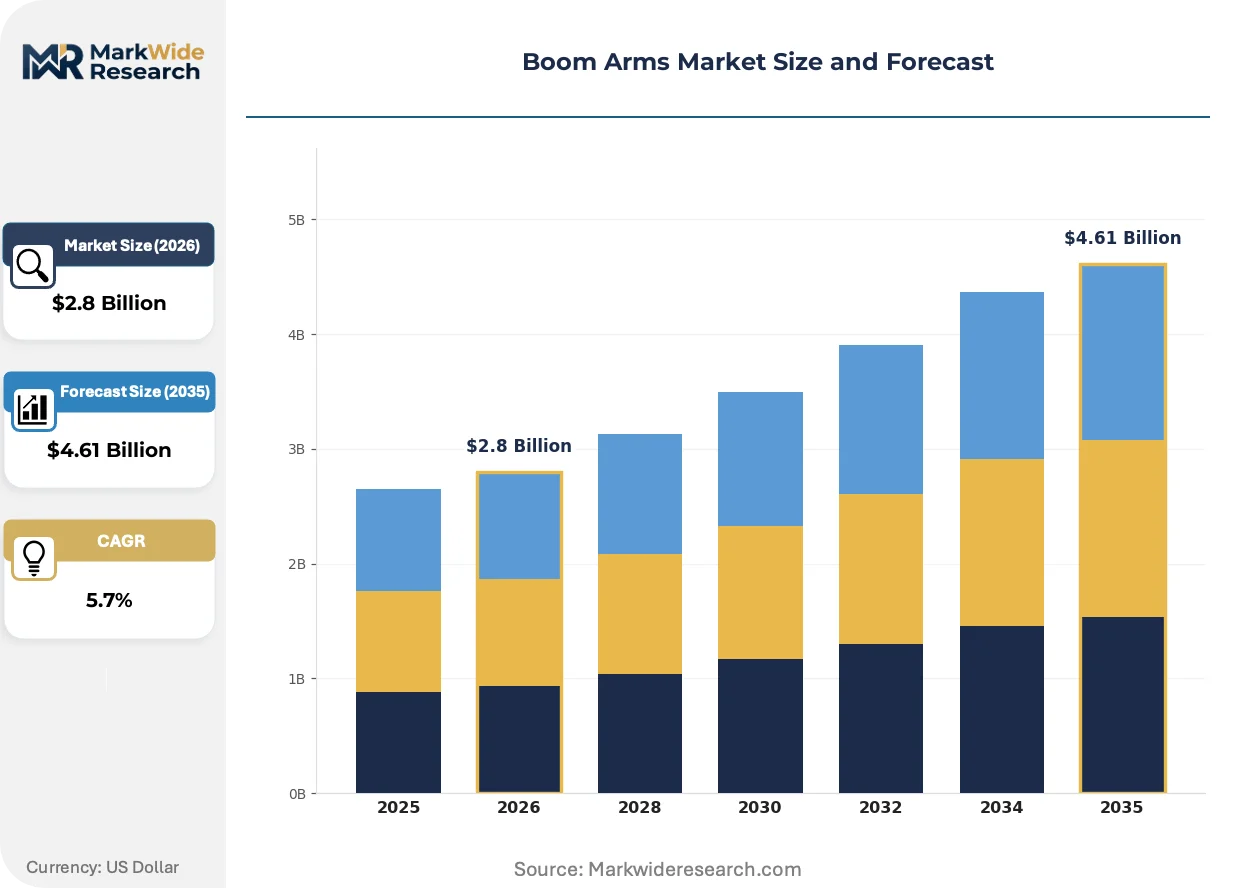
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Boom Arms, Articulating Boom Arms, Telescoping Boom Arms, Hydraulic Boom Arms End User: Construction, Marine, Mining, Aerospace Technology: Pneumatic, Electric, Mechanical, Hybrid Application: Material Handling, Load Lifting, Heavy Equipment, Rigging |
| Companies Covered | Shure, Audio-Technica, RODE, Sennheiser, Samson Technologies, Blue Microphones, BEHRINGER, Neewer, Heil Sound, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Boom Arms Market Evolving Landscape
Electrification of actuation systems and sensor-embedded predictive maintenance are reconfiguring how boom arm OEMs design hardware architectures and monetize aftermarket relationships. These shifts are compressing traditional hydraulic component margins while opening software-enabled service revenue pools.
Sensor-integrated load monitoring is decentralizing maintenance scheduling from fixed calendar intervals to condition-based interventions. Mining operators in Australia are deploying these systems at scale to reduce unplanned downtime in remote extraction sites. This capability is compressing the addressable market for scheduled parts replacement while expanding data services attach rates.
OSHA crane and derrick standard updates in the United States are mandating enhanced operator visibility and proximity sensing for articulating configurations. Fabricators are integrating camera and LiDAR systems into joint assemblies to meet inspection protocols. Construction rental fleets are absorbing these compliance costs fastest, passing premiums through to project contractors.
Buyer consolidation among mining operators is compressing procurement cycles and demanding outcome-based equipment availability guarantees rather than unit sales. Rental and leasing channels are capturing share from direct OEM sales in North American construction verticals. Brazil and Australia exhibit the strongest channel shift, with operators prioritizing fleet flexibility over capital deployment.
Boom Arms Market Segmentation
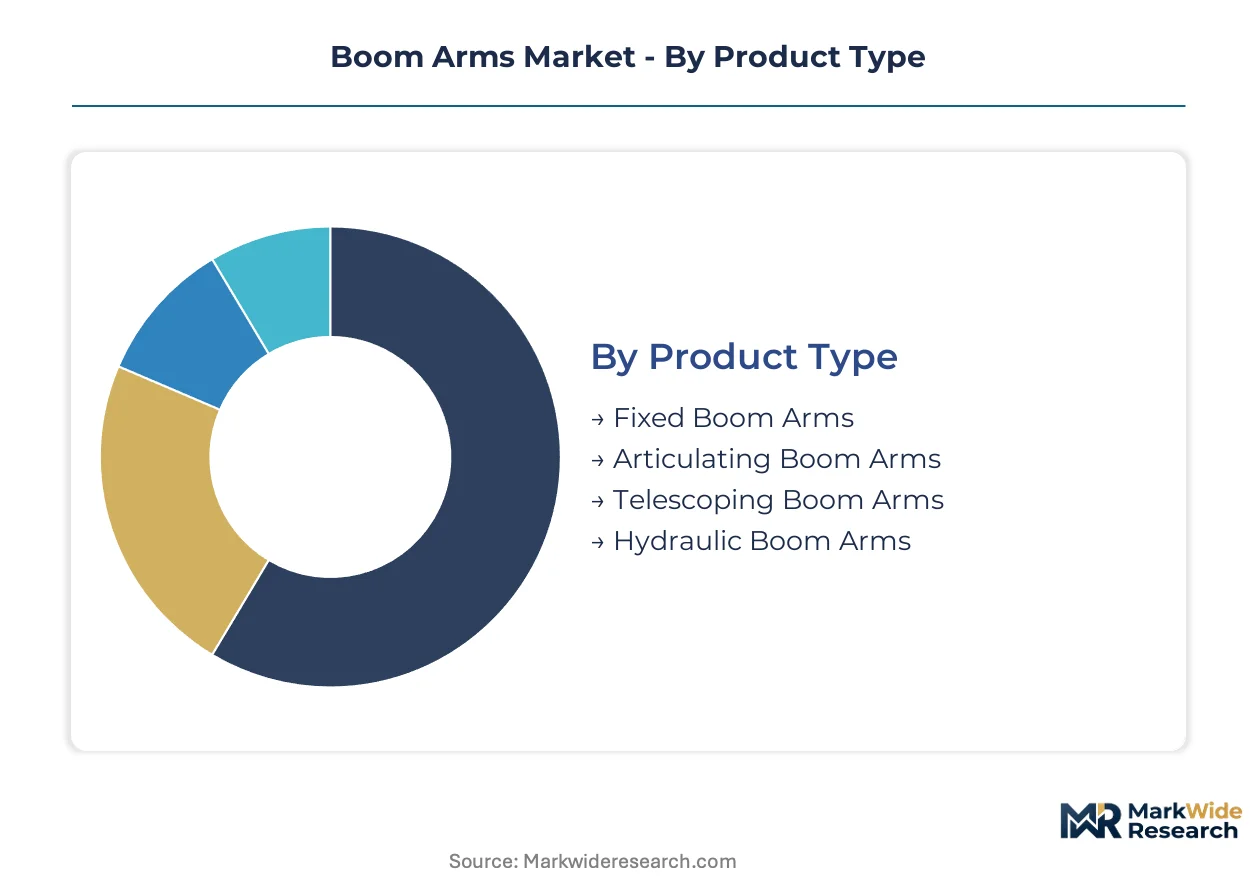
Boom arm procurement decisions pivot on structural configuration, operational environment, and power transmission method. Each segmentation dimension carries distinct capital requirements, certification burdens, and aftermarket revenue profiles that reshape vendor positioning.
Product Type:
Capital intensity escalates sharply with joint complexity and sealed system integration.
- Articulating Boom Arms:Multi-joint cantilever designs with precision-machined bearing assemblies enable maneuverability in confined construction and marine environments. Brazilian port operators and Australian mining contractors now specify these configurations for bulk material handling where rebase repositioning incurs downtime penalties. Demand concentrates where spatial constraints intersect with high-throughput requirements.
- Telescoping Boom Arms:Nested tubular sections with synchronized extension mechanisms deliver vertical reach without footprint expansion. Chilean and South African deep extraction mining operations commission these systems to access ore bodies beyond conventional boom limits. Capital outlays run highest here due to precision cylinder manufacturing and load-tested segment interlocks.
- Fixed Boom Arms:Rigid cantilever structures with welded joint assemblies serve repetitive load positioning in stable environments.
- Hydraulic Boom Arms:Sealed actuator systems with pressurized fluid power transmission dominate heavy-lift specifications under EU Machinery Directive compliance mandates.
Most installed capacity flows through Articulating Boom Arms. Expansion is steepest in Telescoping Boom Arms.
End User:
Application severity and duty cycles determine specification grade and maintenance contract attach rates.
- Mining:Continuous operation in abrasive environments demands corrosion-resistant alloys and predictive sensor integration. Australian operators deploy load-monitoring systems at scale to compress unplanned downtime in remote extraction sites.
- Construction:Rental fleet absorption of OSHA-mandated visibility and proximity sensing systems passes compliance premiums through to project contractors. North American verticals exhibit strongest channel shift toward leasing over direct purchase.
- Marine:Classification society approval timelines for articulating offshore configurations extend revenue recognition cycles.
- Aerospace:Precision positioning requirements for assembly line integration command certified component traceability.
Procurement volume concentrates in Mining. Fleet flexibility requirements are climbing fastest in Construction.
Technology:
Power transmission selection governs maintenance intervals, technician skill requirements, and regulatory compliance scope.
- Hydraulic:Pressurized fluid actuation with sealed cylinder architectures captures dominant margin pools through aftermarket parts dependency. EU efficiency mandates are forcing OEM redesigns of actuator architectures.
- Electric:Motor-driven precision control eliminates fluid contamination risks and reduces noise signatures in enclosed environments.
- Pneumatic:Compressed air systems serve lighter-duty cycles where explosive atmosphere safety protocols apply.
- Mechanical:Direct linkage drive trains persist in cost-sensitive applications with predictable load profiles.
Hydraulic systems retain the largest installed base. Electric configurations are gaining share fastest in sensor-integrated specifications.
Application:
Load dynamics and positioning precision requirements segment hardware specification tiers.
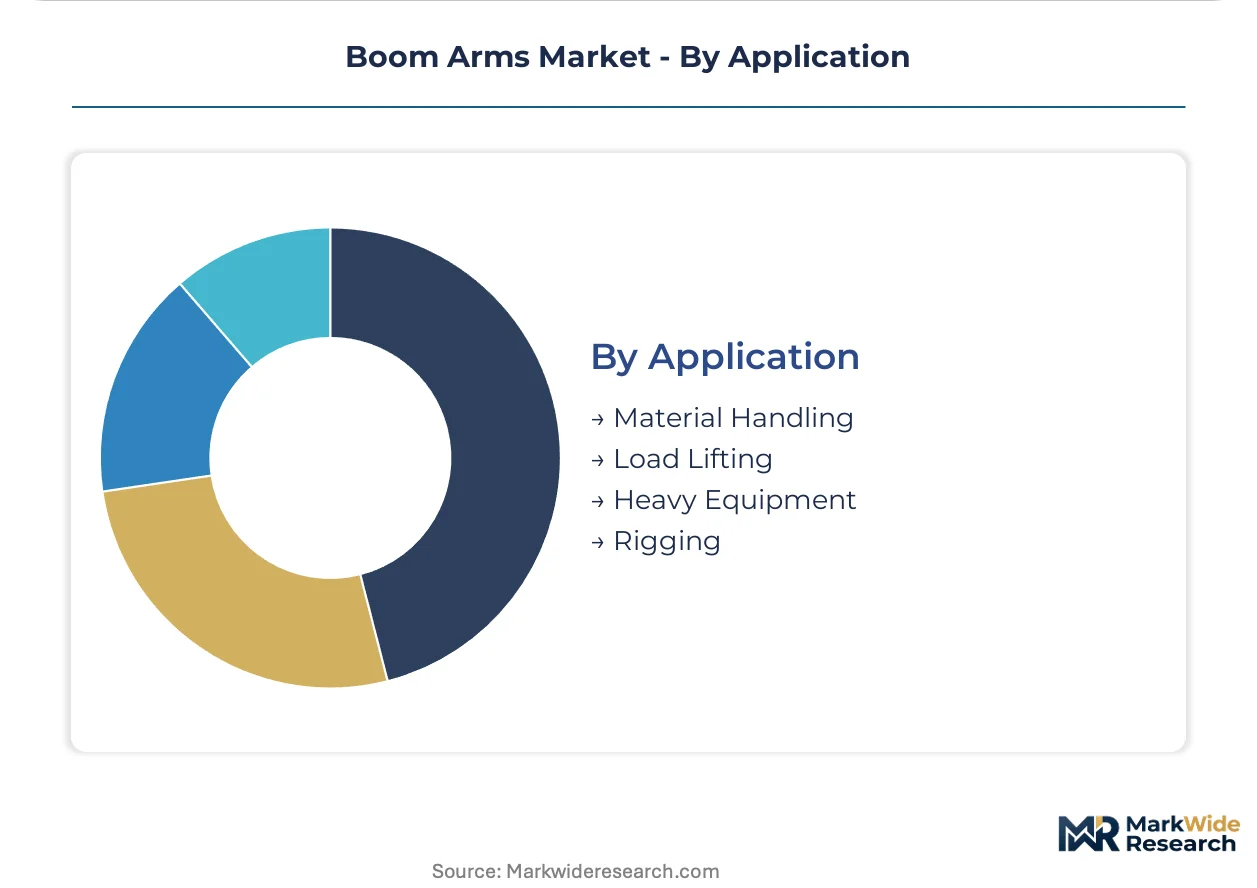
- Material Handling:Continuous cycle operations in bulk commodity ports and mining sites drive telescoping configuration demand. Brazil's infrastructure expansion concentrates procurement where local fabrication capacity remains limited.
- Load Lifting:Vertical displacement specifications under ISO 4301 classification frameworks fragment design standardization across jurisdictions.
- Heavy Equipment:Integrated boom systems on mobile base machinery require torsional load management through high-strength steel or aluminum alloy fabrication.
- Rigging:Temporary suspension applications in entertainment and broadcast verticals favor lighter-duty articulating configurations with premium brand positioning.
Material Handling commands the greatest equipment throughput. Rigging applications show the steepest margin compression from commoditized supply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australia concentrates mining procurement volume while Brazil dominates port infrastructure expansion, with both countries driving telescoping configuration demand. Chilean deep extraction operations and South African ore body access projects are accelerating commissioning cycles for extended-reach systems.
United States
Construction rental fleets absorb OSHA-mandated visibility and proximity sensing premiums fastest, passing compliance costs through to project contractors. The Department of Labor enforces updated crane and derrick standards requiring enhanced operator visibility systems. Texas and Florida infrastructure corridors concentrate articulating boom arm deployment where spatial constraints intersect with high-throughput material handling requirements.
Brazil
Port and mining infrastructure expansion concentrates new boom arm procurement where local fabrication capacity remains limited. ANVISA and national industrial safety frameworks govern equipment certification for bulk material handling operations. The São Paulo industrial corridor anchors regional distribution while Rio Grande do Sul port operators commission telescoping configurations for grain export terminals.
Australia
Mining operators deploy sensor-integrated load monitoring systems at scale to compress unplanned downtime in remote extraction sites. The country's national workplace safety regulator enforces inspection protocols under ISO 4301 classification frameworks adapted for local conditions. Western Australia Pilbara region and Queensland Bowen Basin concentrate deep extraction projects driving telescoping boom arm specifications.
Germany
EU Machinery Directive CE marking requirements filter out uncertified hydraulic component suppliers, consolidating procurement toward OEMs with established testing protocols. The KBA and federal industrial safety administration coordinate enforcement of hydraulic system efficiency mandates. Bavaria and Baden-Württemberg industrial clusters host precision-machined joint assembly fabricators serving marine articulating configurations.
Chile
Deep extraction mining operators commission telescoping boom arms to access ore bodies beyond conventional reach without rebase repositioning. The national mining regulator enforces equipment certification under adapted ISO frameworks for high-altitude operations. Antofagasta Region and Atacama Desert mining districts concentrate procurement demand for corrosion-resistant alloy specifications.
Boom Arms Market Competitive Landscape
Top-tier vendors anchor premium positioning in broadcast-adjacent and precision-machined segments, while mid-scale fabricators compete on regional certification speed and maintenance contract attach rates. The vendor base stratifies across hydraulic system integrators, aluminum alloy specialists, and sensor-embedded predictive maintenance platforms. Strategic archetypes include OEMs with captive sealed actuator supply, fabricators with marine classification society pre-approval, and software-enabled service providers capturing recurring revenue. Dominant competitive moves span backward integration into precision-machined joint assemblies and geographic expansion into Brazil-Australia procurement corridors.
Within the broadcast and content creator ecosystem tier, Shure, Audio-Technica, and RODE exemplify divergent positioning archetypes. Shure leverages channel control in professional audio verticals to cross-sell articulating configurations. Audio-Technica anchors manufacturing scale in precision-machined joint assemblies. RODE occupies brand-strength positioning within lighter-duty segments where premium pricing commands content creator loyalty. These three represent how vendor origin and naming convention signal strategic emphasis—whether through geographic clustering, technical specialization, or ecosystem integration.
| Leading Market Players |
|---|
| Shure |
| Audio-Technica |
| RODE |
| Sennheiser |
| Samson Technologies |
| Blue Microphones |
| BEHRINGER |
| Neewer |
| Heil Sound |
| Others |
Value Network & Pricing Analysis
High-strength steel and aluminum alloy inputs, sourced primarily from German and Japanese mills under EU carbon accounting rules, cascade through three pricing tiers before reaching mining operators and construction rental fleets in Brazil and Australia.
Pricing Analysis
Capacity additions in China are reshaping price floors for standard-grade articulating configurations while premium hydraulic systems retain margin pools through CE marking certification requirements. Three-tier pricing structure across premium, standard, and economy levels separates OEMs with captive sealed actuator supply from fabricators dependent on third-party components. Price differentiation centers on ISO 4301 load rating tier and aftermarket service bundling. Margins are tightening in fixed boom arm categories due to commoditized supply from Southeast Asian fabricators. Mining operators exhibit lowest price sensitivity given outcome-based equipment availability guarantees, while construction rental fleets absorb compliance premiums fastest.
Supply Chain Analysis
Freight cost volatility from Red Sea routing disruptions is amplifying landed cost spreads between European component suppliers and Australian end-users. Manufacturing concentrates in Germany, Japan, and South Korea for precision-machined joint assemblies and sealed hydraulic actuators. Raw material dependencies rest on high-strength steel grades, aluminum alloys with 2–5 mm wall thickness specifications, and specialized bearing steels. Single-source vulnerability concentrates in certified European hydraulic component suppliers. Distribution runs through OEM direct sales, regional equipment distributors, and emerging leasing platforms in North American construction verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The boom arms market compounds steadily as deep extraction mining in Chile and South Africa sustains replacement cycles for telescoping configurations with extended vertical reach requirements.
For Market Incumbents: Anticipate electrification of actuation systems compressing traditional hydraulic aftermarket revenue pools by accelerating sensor-embedded predictive maintenance platform development. Defend position through backward integration into precision-machined joint assemblies and pre-approval pathways with marine classification societies. Channel control in Brazil-Australia procurement corridors offers the strongest defensive moat against emerging regional fabricators. For New Entrants and Emerging Players: Begin with maintenance-as-a-service monetization in remote Australian mining sites where OEM service networks remain thin. Target white-space in corrosion-resistant aluminum articulating configurations for Brazilian port operators facing ANVISA certification backlogs. Partner with established hydraulic component distributors to bypass sealed actuator supply concentration barriers. For Investors and Strategic Acquirers: Roll-up economics work for regional maintenance service platforms because mining operator consolidation demands outcome-based availability guarantees that fragment across equipment vintages. Five-to-ten year viability hinges on software-enabled recurring revenue attach rates overtaking hardware sales dependency. Monitor EU Green Deal steel certification timelines as inflection indicator for preferential government tender positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Joint Assemblies | Captive manufacturing of bearing systems insulates margin pools from certified supplier bottlenecks. |
| Sensor-Embedded Predictive Maintenance Platform Launch | Software-enabled recurring revenue displaces scheduled parts replacement in Australian mining deployments. |
| Marine Classification Society Pre-Approval Investment | Accelerated certification cycles unlock offshore articulating configuration revenue recognition. |
| Long-Term Leasing Partnership with Brazilian Port Operators | Fleet flexibility demand concentrates procurement toward rental channels with limited local fabrication. |
| EU Green Deal Steel Certification Compliance Program | Embodied carbon tracking creates preferential positioning for government-backed infrastructure tenders. |
Research Methodology
Coverage spans Australia, Brazil, Chile, Germany, and the United States, with primary inputs from each market gathered through structured interviews with maintenance directors at mining operations, plant engineers at bulk material handling facilities, OEM procurement teams specifying hydraulic systems, aftermarket service heads managing remote diagnostics platforms, and marine classification society surveyors. Secondary validation draws from SEC 10-K filings of listed equipment manufacturers, ISO 4301 technical committee documentation, EU Machinery Directive implementation guidance, Australian workplace safety regulator inspection protocols, and Brazilian customs data on heavy machinery imports. Bottom-up equipment deployment estimates triangulate against top-down capital expenditure disclosures from major mining operators.
Granularity-level modeling disaggregates volume and value across product type (articulating, telescoping, fixed, hydraulic), end user (mining, construction, marine, aerospace), technology (hydraulic, electric, pneumatic, mechanical), and application (material handling, load lifting, heavy equipment, rigging) dimensions. CAGRs derive from regression analysis of historical procurement patterns against projected infrastructure investment flows and regulatory compliance deadlines. Industry-specific forecast inputs include deep extraction mining depth trajectories in Chile and South Africa, OSHA crane and derrick standard update implementation timelines, and EU hydraulic efficiency mandate phase-in schedules.
Several conditions sit outside the modeled scope, including abrupt commodity price collapses triggering mining capex freezes, trade policy disruptions affecting steel alloy tariff structures, and breakthrough electrification technologies displacing hydraulic architectures faster than replacement cycles allow. Forecasts reflect assumptions about regulatory enforcement consistency and supplier qualification timeline stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Armored Vehicles
Armored Vehicle Fire Suppression Systems Market
Armored Vehicles
Armored Fighting Vehicles Market
Armored Vehicles
Armored Vehicles Market
Armored Vehicles
US Armored Vehicle Market
Armored Vehicles
Armored Vehicle Procurement and Upgrade Market
Armored Vehicles
Europe Armored Fighting Vehicles Market
Armored Vehicles
Middle-East and Africa Armored Vehicles Market
Armored Vehicles
Armor Protection Systems Market
Armored Vehicles
Armored Personnel Carrier Market
Armored Vehicles
Armored Vehicles Upgrade and Retrofit Market
Armored Vehicles
Global Ceramic Armor Market
Armored Vehicles
North America Armored Fighting Vehicles Market
Armored Vehicles
Armoured Personnel Carrier (APC) Market
Armored Vehicles
Armored Vehicle Navigation Systems Market
Armored Vehicles
Asia-Pacific Armored Fighting Vehicles Market
Armored Vehicles
Military Armored Car Market