
 Armored Vehicle Fire Suppression Systems Market | 2026-2036
Armored Vehicle Fire Suppression Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Armored Vehicle Fire Suppression Systems Market Analysis
Specialized pyrotechnic engineering talent is collapsing across NATO defense industrial bases, constraining OEM capacity to certify next-generation suppression systems. Halma sustains its market presence through deep vertical integration in optical flame detection. Firetrace International specializes in compact linear heat detection for confined crew compartments. Kidde-Deugra anchors European supply through long-standing Bundeswehr relationships.
Armored Vehicle Fire Suppression Systems encompass engineered assemblies of sensors, extinguishing agents, and discharge nozzles designed to detect and suppress fuel or ammunition fires within seconds, typically achieving full agent deployment in under 250 milliseconds to preserve crew survivability. These systems serve the essential commercial purpose of protecting personnel and platform integrity in combat or threat environments where kinetic impact risks catastrophic thermal events. Gas-based systems dominate current military procurement due to clean-agent compatibility with sensitive electronics, while hybrid configurations combining thermal imaging with automated actuation mechanisms represent the fastest-growing technology intersection. The onboard systems deployment model remains mature with stable margins, whereas integrated solutions layering remote monitoring with predictive diagnostics command premium positioning.
The US Department of Defense, NATO Standardization Office, and Germany's BAAINBw collectively shape market access through ballistic and environmental survivability protocols that dictate suppression response thresholds. REACH restrictions on perfluorinated compounds are forcing reformulation of legacy foam agents across European supply chains. Stakeholders must monitor evolving agent toxicity standards and electromagnetic compatibility requirements as electrified armored platforms proliferate.
Market Dynamics
Stricter survivability mandates from the US Department of Defense and NATO Standardization Office are compressing certification timelines for next-generation suppression systems, forcing OEMs to accelerate agent reformulation and sensor integration cycles to maintain platform qualification status.
Growth Catalysts
- Electrified platform proliferation:Battery-powered armored vehicles generate novel thermal runaway risks that conventional suppression architectures cannot address, creating demand for high-speed gas-based systems with sub-250-millisecond response thresholds.
- REACH perfluorinated compound restrictions:The ECHA ban on legacy foam agents across European defense supply chains is mandating clean-agent alternatives, directly expanding addressable market for fluorine-free suppression technologies.
- Bundeswehr fleet modernization:Germany's BAAINBw procurement authority is allocating capital toward integrated protection suites, anchoring regional demand for multi-threat suppression systems combining ballistic and thermal protection.
Market Restraints
- Pyrotechnic engineering talent scarcity:Specialized expertise in rapid-discharge agent chemistry is concentrating among a shrinking cohort of NATO defense contractors, constraining OEM certification throughput.
- Halocarbon feedstock volatility:Clean-agent production depends on fluorinated gas supply chains subject to EU F-Gas Regulation quota reductions, compressing margins for gas-based system manufacturers.
- Legacy platform retrofit complexity:Cold War-era armored vehicle architectures lack structural integration points for modern sensor arrays, limiting upgrade penetration rates in Eastern European fleets.
Strategic Opportunities
- Unmanned ground vehicle integration:Autonomous combat platforms lack crewed compartments but require engine bay and battery suppression, opening design space for compact distributed nozzle architectures.
- Predictive diagnostics convergence:Machine-learning thermal signature analysis paired with automated actuation mechanisms enables condition-based maintenance contracts, shifting revenue toward recurring service models.
- South Korean KF-21 program spillover:Republic of Korea Armed Forces procurement is creating supplier certification pathways that adjacent ASEAN defense ministries can leverage for technology transfer.
Industry Challenges
- Electromagnetic compatibility certification:MIL-STD-461 testing for suppression system electronics on electrified platforms extends development cycles by 8-14 months, delaying platform integration milestones.
- Agent toxicity standard evolution:Evolving NATO STANAG protocols for crew compartment atmospheric safety require iterative reformulation, fragmenting R&D resources across multiple compliance tracks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Armored Vehicle Fire Suppression Systems Market |
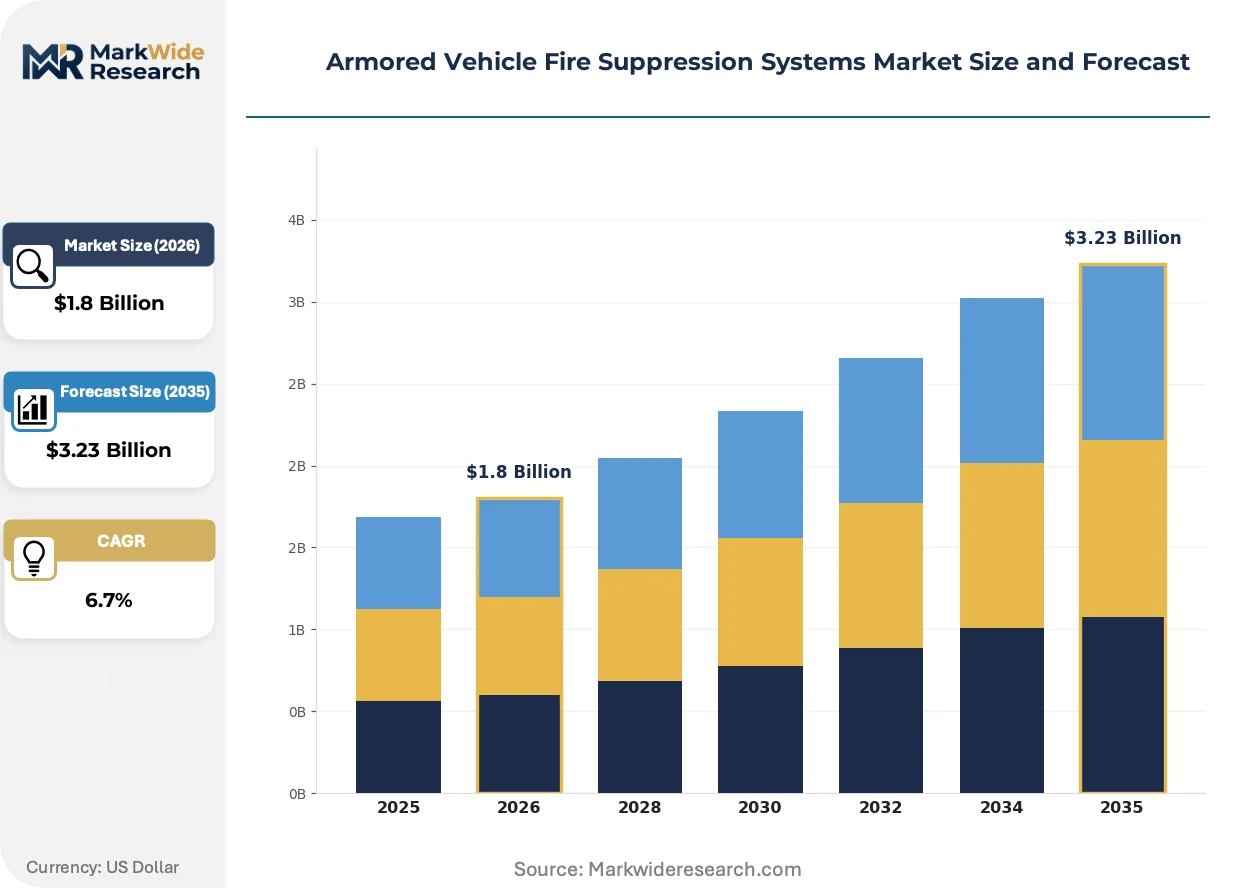
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Gas-Based, Foam-Based, Water Mist, Hybrid Deployment Model: Onboard Systems, Remote Monitoring, Manual Activation, Integrated Solutions End User: Military, Law Enforcement, Private Security, Government Agencies Technology: Thermal Imaging, Sensors, Control Panels, Actuation Mechanisms |
| Companies Covered | Halma, Firetrace International, N2 Towers, Bulldog Direct, Kidde-Deugra, Spectrex, Marotta Controls, Nero Industries, Fire Protection Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Armored Vehicle Fire Suppression Systems Market Emerging Trajectories
Suppression system architecture is pivoting from standalone hardware toward sensor-fused autonomous response networks, with thermal imaging and predictive algorithms compressing detection-to-discharge intervals below human reaction thresholds.
Linear heat detection arrays paired with fiber-optic sensing is supplanting conventional point-source infrared detectors in confined crew compartments. NATO ally procurement offices are specifying these distributed architectures for next-generation infantry fighting vehicles. The technology is compressing competitive differentiation around optical engineering depth rather than mechanical discharge reliability alone.
REACH restrictions on perfluorinated compounds are forcing reformulation of legacy foam agents across European supply chains. Defense contractors are redirecting R&D toward fluorine-free clean agents compatible with sensitive electronics. German and French procurement authorities are now mandating environmental agent profiles in technical specifications, accelerating displacement of halon-alternative chemistries.
Platform OEMs are unbundling suppression system procurement from vehicle prime contracts, creating direct vendor relationships with subsystem specialists. This disintermediation concentrates in United States and German programs where survivability standards are most prescriptive. Tier-1 suppliers are responding with dedicated defense sales organizations bypassing traditional automotive distribution channels.
Armored Vehicle Fire Suppression Systems Market Segmentation
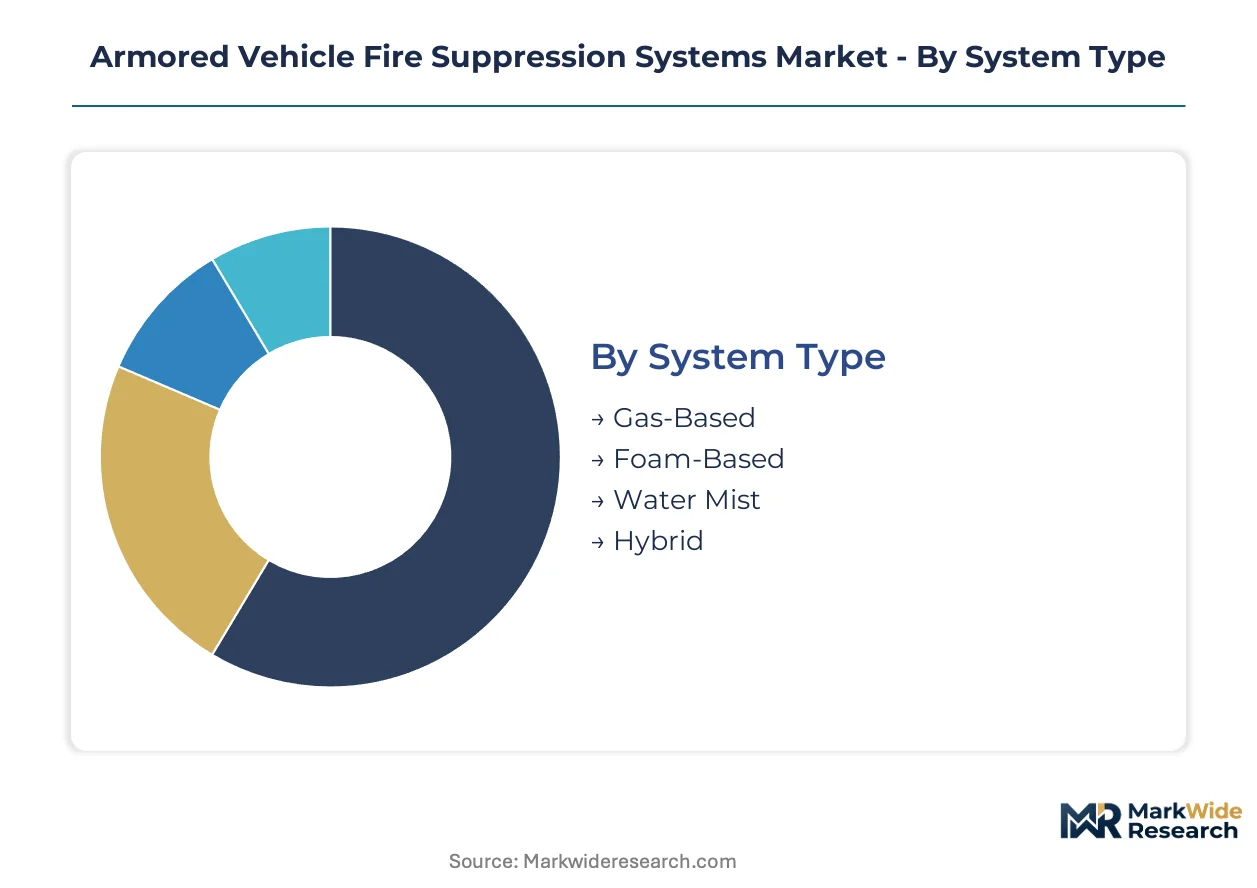
Segmentation in armored vehicle fire suppression systems reveals how procurement authority, platform electrification, and regulatory mandates redistribute margin pools across subsystem architectures. Understanding these fault lines exposes where OEMs can defend pricing power versus where commoditization pressures concentrate.
System Type:
Gas-based configurations command the widest margin spreads due to clean-agent compatibility requirements and fluorinated feedstock scarcity.
- Gas-Based:These systems deploy halocarbon or inert gas agents achieving sub-250-millisecond discharge speeds. Demand concentrates in United States and German military procurement where MIL-STD and STANAG survivability protocols mandate electronics-safe suppression for digitized combat vehicles. REACH and EU F-Gas Regulation constraints on fluorinated compounds are forcing rapid agent reformulation, compressing margins for manufacturers lacking backward integration into specialty gas production.
- Foam-Based:Aqueous film-forming foam systems deliver cooling suppression for engine bay and fuel tank protection. Bundeswehr and Eastern European fleets maintain substantial installed base, though ECHA restrictions on perfluorinated compounds are mandating displacement toward fluorine-free alternatives. Polish and Czech upgrade programs represent residual demand concentration for legacy-compatible architectures.
- Water Mist:Fine droplet dispersion systems minimize water discharge volumes for weight-constrained platforms. South Korean KF-21 program spillover and ASEAN technology transfer pathways are driving specification adoption.
- Hybrid:Configurations combining gas and liquid agents for multi-zone protection. These architectures are climbing the share rankings as electrified platforms demand layered thermal runaway response.
Gas-Based holds installed capacity. Hybrid is rotating up the share rankings.
Deployment Model:
Recurring revenue intensity varies sharply across deployment architectures, with predictive diagnostics capabilities determining contract renewability.
- Integrated Solutions:Layered architectures combining onboard suppression with remote monitoring and predictive diagnostics. United States Department of Defense and BAAINBw procurement authorities are mandating these configurations for next-generation infantry fighting vehicles, enabling condition-based maintenance contracts with 7-10 year service horizons. Machine-learning thermal signature analysis differentiates premium positioning.
- Onboard Systems:Standalone hardware deployments with stable margins but limited recurring revenue capture. Mature demand concentrates in Cold War-era platform retrofits where structural integration constraints prevent sensor-fused upgrades.
- Remote Monitoring:Telemetry-enabled architectures transmitting system health data to maintenance depots. German and French procurement offices are piloting these for fleet-wide availability optimization.
- Manual Activation:Crew-triggered discharge systems with minimal sensor integration. Private security and legacy law enforcement vehicle conversions represent residual demand concentration.
Onboard Systems holds installed capacity. Integrated Solutions is expanding most quickly through mandated procurement specifications.
End User:
Procurement sophistication and survivability standard stringency create tiered margin structures across customer categories.
- Military:Defense ministries and armed forces procurement authorities with prescriptive technical specifications. United States, Germany, and South Korea dominate capital allocation toward integrated protection suites, with NATO Standardization Office protocols dictating suppression response thresholds and electromagnetic compatibility requirements.
- Law Enforcement:Police tactical vehicle operators requiring confined crew compartment protection. Demand clusters in urban counter-terrorism units specifying compact linear heat detection arrays.
- Private Security:Corporate and executive protection fleets with cost-constrained procurement. Manual activation systems predominate due to lower certification burdens.
- Government Agencies:Border patrol, customs, and critical infrastructure protection units with intermediate specification requirements. ASEAN defense ministries leveraging South Korean supplier certification pathways represent emerging demand concentration.
Military holds installed capacity. Government Agencies is rotating up the share rankings through technology transfer spillover.
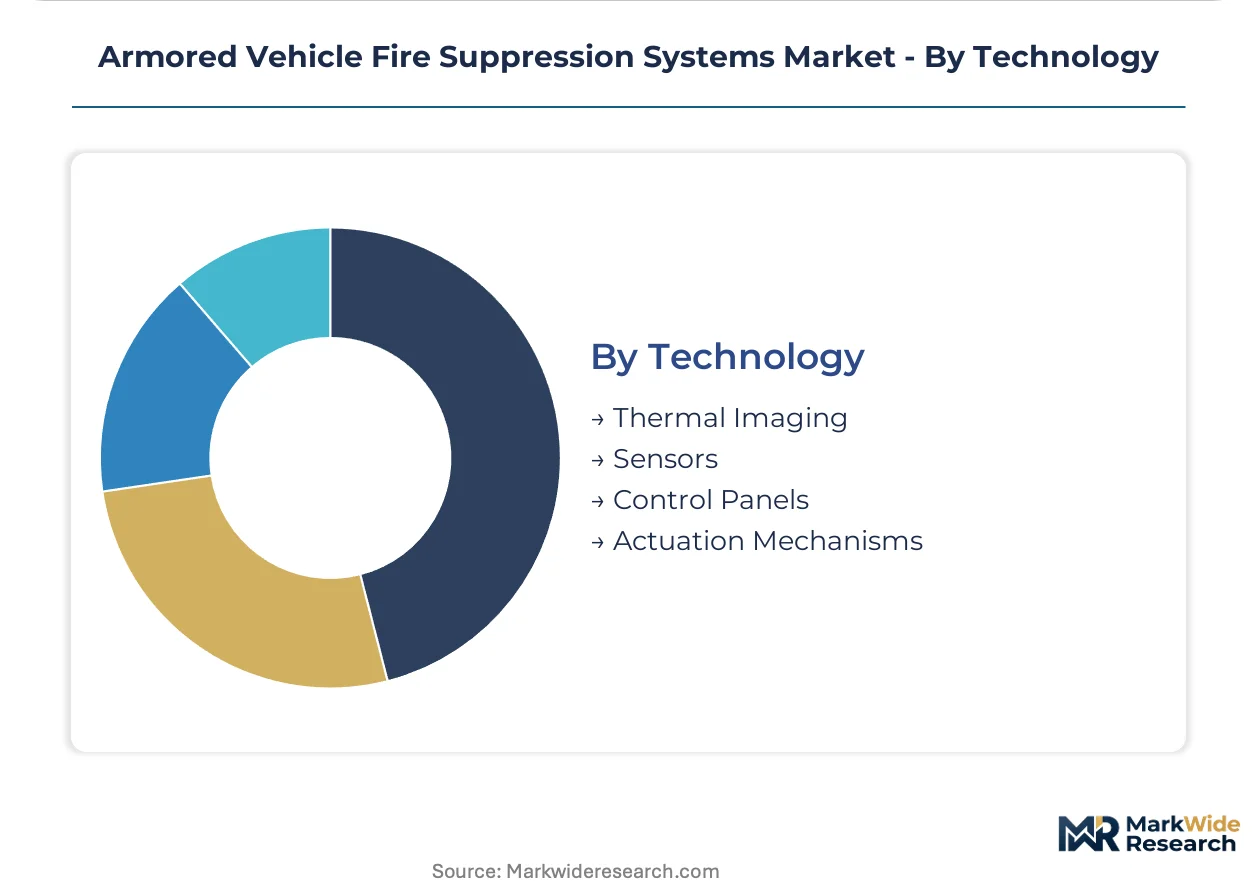
Technology:
Optical engineering depth and sensor fusion capabilities are displacing mechanical reliability as the primary competitive differentiation axis.
- Thermal Imaging:Infrared focal plane arrays enabling predictive thermal signature analysis before visible flame detection. United States and German next-generation infantry fighting vehicle programs are specifying these for autonomous response networks compressing detection-to-discharge intervals below human reaction thresholds.
- Sensors:Distributed linear heat detection arrays paired with fiber-optic sensing supplanting point-source infrared detectors in confined crew compartments. Halma and Firetrace International anchor supply through deep optical engineering capabilities.
- Control Panels:MIL-STD-461 compliant electronics managing agent discharge sequencing. Electromagnetic compatibility certification extends development cycles by 8-14 months for electrified platform integration.
- Actuation Mechanisms:Pyrotechnic and pneumatic discharge hardware. Specialized engineering talent scarcity across NATO defense industrial bases is constraining OEM certification throughput for rapid-discharge architectures.
Sensors holds installed capacity. Thermal Imaging is gaining share fastest through sensor-fused autonomous response network specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in United States and German procurement channels where MIL-STD and STANAG protocols mandate premium integrated solutions, while Eastern European retrofit markets trade on cost-competitive legacy compatibility.
United States
The Department of Defense drives demand through next-generation infantry fighting vehicle programs requiring sub-250-millisecond suppression response. MIL-STD-461 electromagnetic compatibility testing extends certification cycles, filtering supplier participation. Detroit-area defense contractors cluster around Army Ground Vehicle Systems Center integration pipelines.
Germany
BAAINBw procurement authority allocates capital toward multi-threat protection suites combining ballistic and thermal defense. REACH restrictions on perfluorinated compounds force agent reformulation across Bundeswehr supply chains. Bavarian optical engineering clusters around Munich anchor flame detection subsystem development.
South Korea
Republic of Korea Armed Forces procurement for KF-21 program spillover creates certification pathways for ASEAN technology transfer. MFDS environmental agent standards influence clean-agent specification trends. Seoul Capital Area defense contractors concentrate on compact distributed nozzle architectures for electrified platforms.
Poland
Cold War-era fleet modernization generates residual demand for legacy-compatible foam-based systems. ECHA fluorinated compound restrictions limit agent sourcing options for Eastern European retrofits. Warsaw-area integrators specialize in structural adaptation for sensor array installation on Soviet-origin chassis.
France
Direction Générale de l'Armement specifies environmental agent profiles in technical requirements, accelerating fluorine-free chemistry adoption. ANSM atmospheric safety protocols influence crew compartment toxicity standards. Auvergne-Rhône-Alpes defense electronics clusters develop predictive diagnostics for condition-based maintenance contracts.
Armored Vehicle Fire Suppression Systems Market Vendor Landscape
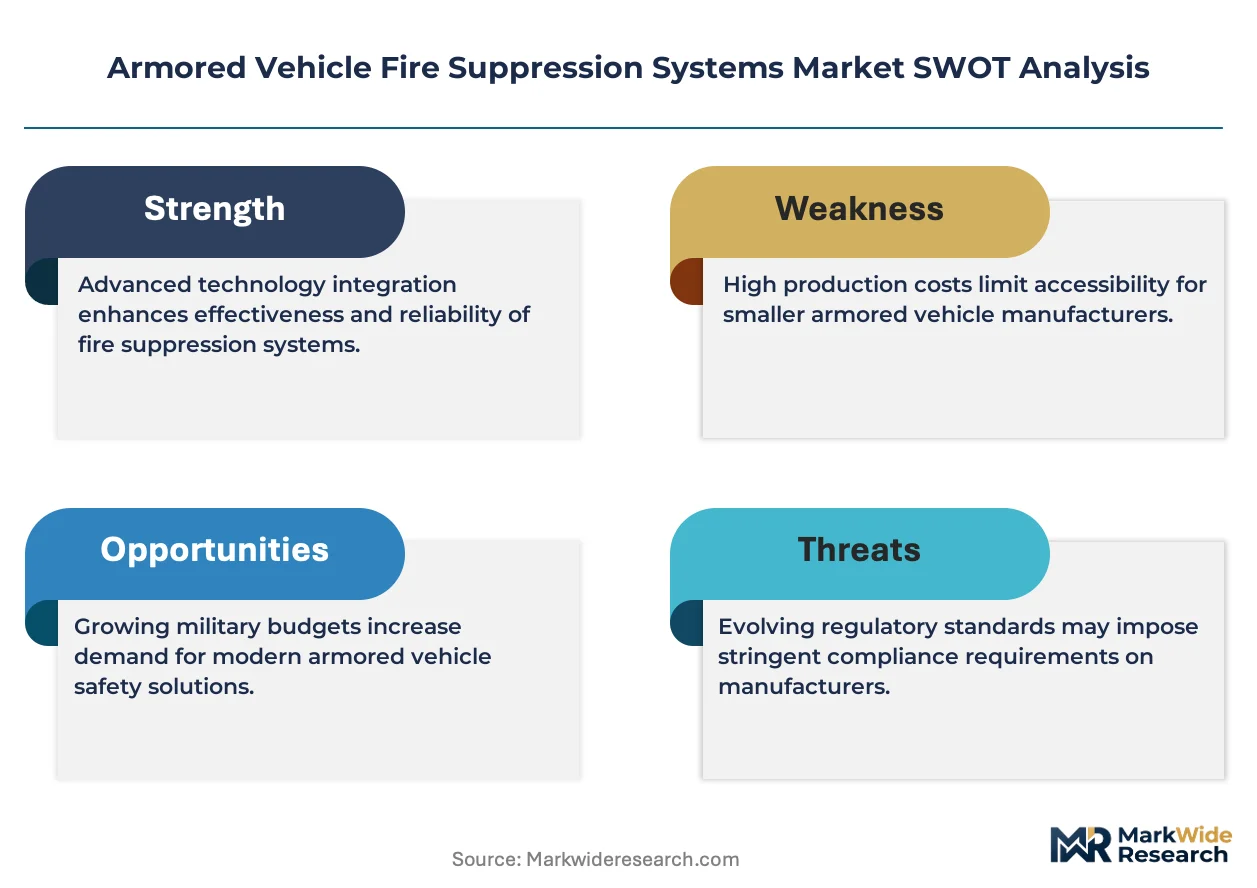
Technology leadership and cost leadership are held by different player archetypes, creating a tiered structure where optical engineering depth commands premium positioning while scale fabrication serves retrofit markets. The vendor base concentrates among NATO defense contractors with pyrotechnic certification heritage and specialty gas producers with backward integration into fluorinated feedstocks. Three archetypes dominate: integrated protection suite specialists, compact detection subsystem suppliers, and legacy system retrofit providers. Competitive moves center on electromagnetic compatibility certification acceleration and predictive diagnostics capability acquisition.
Among detection technology specialists, Halma and Firetrace International exemplify optical engineering depth through flame and linear heat detection subsystems, while Kidde-Deugra anchors European supply relationships through long-standing defense procurement channels. These three occupy positions across the premium subsystem tier, with Halma representing vertical integration in optical components, Firetrace International exemplifying compact architecture specialization, and Kidde-Deugra sitting within the established European defense contractor cohort.
| Leading Market Players |
|---|
| Halma |
| Firetrace International |
| N2 Towers |
| Bulldog Direct |
| Kidde-Deugra |
| Spectrex |
| Marotta Controls |
| Nero Industries |
| Fire Protection Technologies |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at specialty fluorinated gas producers sits above 85 percent across German and US manufacturing sites, compressing feedstock availability and elevating price floors for clean-agent suppression systems. This scale concentration permits incumbent gas suppliers to maintain margin spreads while constraining OEM negotiation leverage on agent sourcing contracts.
Pricing Analysis
Configured-to-order pricing for integrated protection suites commands 40-60 percent premiums over standard onboard system configurations. Pricing stratifies across MIL-STD certified, STANAG compliant, and commercial-grade tiers, with electromagnetic compatibility certification acting as the primary quality-grade differentiator. Cost compression in the Eastern European retrofit segment is intensifying because legacy platform structural constraints limit sensor-fused upgrade penetration. Military procurement authorities exhibit lowest price sensitivity due to survivability mandate stringency, while private security fleet operators demonstrate highest elasticity.
Supply Chain Analysis
Strategic stockpiling of fluorinated clean agents dominates inventory strategy among tier-1 OEMs confronting EU F-Gas Regulation quota reductions. Supply concentrates in Germany, the United States, and Japan for specialty halocarbon production, with pyrotechnic discharge hardware drawing from Italian and Czech precision manufacturing clusters. Raw material dependencies center on fluorinated gas feedstocks, optical sensor components, and MIL-spec electronics. Single-source vulnerability permeates the fluorinated agent tier where three producers control 80 percent of NATO-certifiable supply. Distribution runs through defense prime contractor integration pipelines rather than open market channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among platform OEMs unbundling suppression procurement from vehicle prime contracts, fragmenting traditional supplier relationships and compressing subsystem vendor margins.
For Market Incumbents: Compound optical engineering depth through acquisition of fiber-optic sensing specialists to defend premium positioning against emerging thermal imaging entrants. Accelerate MIL-STD-461 pre-certification investments to compress electromagnetic compatibility timelines that currently extend development cycles. Backward integration into specialty fluorinated gas production anchors supply security against EU F-Gas quota constraints. For New Entrants and Emerging Players: Certification fast-track partnerships with South Korean MFDS-recognized test laboratories enable ASEAN market entry without redundant NATO STANAG qualification costs. Target Polish and Czech retrofit integrators specializing in Soviet-origin chassis adaptation as the most penetrable white-space segment. Pursue direct vendor relationships with platform OEMs bypassing traditional automotive distribution channels as the primary go-to-market angle. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors optical detection subsystem specialists over mechanical discharge hardware fabricators as sensor-fused architectures displace standalone suppression systems. Long-term viability frames around predictive diagnostics capability and condition-based maintenance contract renewability. Acquisition target archetypes include compact linear heat detection developers with Bundeswehr or US Army qualification heritage. The signal to watch is electrified platform procurement volume crossing threshold levels that mandate battery thermal runaway suppression specifications.| Strategic Initiative | Industry Significance |
|---|---|
| Electromagnetic Compatibility Pre-Certification Investment | MIL-STD-461 compliance acceleration filters supplier participation and defends premium positioning. |
| Fluorine-Free Agent Reformulation Program | ECHA REACH restrictions mandate clean-agent alternatives and expand addressable market for compliant technologies. |
| Predictive Diagnostics Platform Development | Machine-learning thermal signature analysis enables condition-based maintenance contracts with extended service horizons. |
| Compact Distributed Nozzle Architecture Design | Unmanned ground vehicle integration opens design space for autonomous platform suppression requirements. |
| ASEAN Technology Transfer Partnership | South Korean KF-21 supplier certification pathways create adjacent defense ministry procurement access. |
Methodological Framework
The analysis maps gas-based, foam-based, water mist, and hybrid suppression architectures, each validated through platform OEM procurement officers, defense ministry technical specification leads, pyrotechnic engineering directors, and aftermarket fleet maintenance managers. Secondary sources include NATO STANAG protocol documentation, US Department of Defense MIL-STD filings, ECHA REACH regulatory updates, and Bundeswehr BAAINBw procurement disclosures. Bottom-up segment sizing triangulates against top-down defense budget allocation analysis.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework models system type, deployment model, end user category, and technology segment dimensions alongside platform electrification status as a cross-cutting variable. CAGRs derive from installation base growth, replacement cycle compression, and specification upgrade penetration trajectories. Industry-specific inputs include military fleet modernization program timelines and clean-agent regulatory phase-out schedules.
The analysis sits within stated boundaries; outcomes outside sustained NATO defense spending levels or accelerated electrified platform procurement would require recalibration. Forecasts reflect assumptions regarding certification timeline stability and fluorinated feedstock quota enforcement. Revision becomes warranted when electromagnetic compatibility testing delays exceed current 8-14 month baselines or when REACH restrictions expand beyond perfluorinated compounds to broader halocarbon categories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Armored Vehicles
Asia-Pacific Armored Fighting Vehicles Market
Armored Vehicles
Europe Armored Fighting Vehicles Market
Armored Vehicles
Armor Protection Systems Market
Armored Vehicles
Military Armored Car Market
Armored Vehicles
Armored Personnel Carrier Market
Armored Vehicles
Armored Vehicles Upgrade and Retrofit Market
Armored Vehicles
Armored Fighting Vehicles Market
Armored Vehicles
Armored Vehicles Market
Armored Vehicles
North America Armored Fighting Vehicles Market
Armored Vehicles
Boom Arms Market
Armored Vehicles
Middle-East and Africa Armored Vehicles Market
Armored Vehicles
US Armored Vehicle Market
Armored Vehicles
Armored Vehicle Navigation Systems Market
Armored Vehicles
Global Ceramic Armor Market
Armored Vehicles
Armored Vehicle Procurement and Upgrade Market
Armored Vehicles
Armoured Personnel Carrier (APC) Market