
 North America Armored Fighting Vehicles Market | 2026-2036
North America Armored Fighting Vehicles Market Size, Share, and Industry Trends Forecast 2026-2036
North America Armored Fighting Vehicles Market Analytics
Steel-hull designs is consolidating around composite and ceramic armor packages that cut weight while preserving ballistic protection. General Dynamics Corporation leverages its Land Systems division to dominate tracked vehicle production from Michigan facilities. BAE Systems plc anchors armored vehicle assembly through its U.S. subsidiary operations. Rheinmetall AG competes via its Lynx platform partnership with American prime contractors.
Armored Fighting Vehicles denote tracked or wheeled platforms engineered to withstand ballistic, mine, and improvised explosive device threats through layered armor architectures typically rated to STANAG 4569 protection levels, serving military forces for direct combat, troop transport, and battlefield reconnaissance. Infantry Fighting Vehicles represent the most mature segment with established upgrade cycles across U.S. and Canadian fleets, while Autonomous technology commands the fastest development trajectory as the U.S. Army's Robotic Combat Vehicle program advances. Conventional drivetrains still occupy the largest installed base, though Hybrid systems are capturing incremental share where silent watch capabilities matter tactically.
The U.S. Department of Defense shapes procurement through Milestone Decision Authority reviews and Joint Capabilities Integration Development System requirements, while Canada's Department of National Defence coordinates acquisition through its Defence Procurement Strategy. The U.S. Army's Ground Vehicle Systems Center enforces survivability standards that filter directly into contractor engineering specifications. Stakeholders must monitor how the U.S. Marine Corps Force Design 2030 restructuring redirects amphibious vehicle investment toward lighter, more expeditionary platforms.
Market Dynamics
The U.S. Army's modernization imperative is compressing development cycles for next-generation combat platforms while forcing legacy industrial capacity to retool for electrified, autonomous architectures.
Growth Catalysts
- Electrification mandates:The Department of Defense's emphasis on hybrid drivetrains and silent watch capabilities is pulling investment into battery-integrated power systems for tactical vehicles.
- Autonomous systems integration:The Robotic Combat Vehicle program is creating funded development pathways for unmanned ground platforms with remote operator stations.
- Southwestern manufacturing clusters:Defense production scale-up in Texas and Arizona is concentrating specialized fabrication capacity and supplier networks for armored hull assembly.
Market Restraints
- Specialized steel and ceramic armor input costs:Ballistic-grade alloy supply constraints and rare earth ceramic pricing volatility are compressing contractor margins on fixed-price development contracts.
- Single-source dependency for critical subsystems:Domestic production of advanced transmission systems concentrates among limited qualified suppliers, creating bottlenecks during surge procurement.
- STANAG 4569 certification timeline friction:Multi-year survivability validation protocols delay platform fielding and extend program risk windows for prime contractors.
Strategic Opportunities
- Canadian fleet recapitalization:The Department of National Defence's Defence Procurement Strategy is opening competitive bidding for armored personnel carrier replacements beyond domestic suppliers.
- Marine Corps expeditionary platform pivot:Force Design 2030 restructuring is redirecting amphibious vehicle investment toward lighter, ship-transportable configurations with reduced logistical footprints.
- AI-enabled predictive maintenance:Convergence of sensor fusion algorithms with vehicle health monitoring is creating aftermarket service revenue streams tied to operational availability contracts.
Industry Challenges
- Electromechanical systems integration talent scarcity:The shallow labor pool for hybrid propulsion engineers and autonomous navigation specialists is extending hiring timelines for critical program roles.
- Legacy fleet interoperability requirements:New platforms must maintain command-and-control compatibility with existing battle management networks, adding software architecture complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Armored Fighting Vehicles Market |
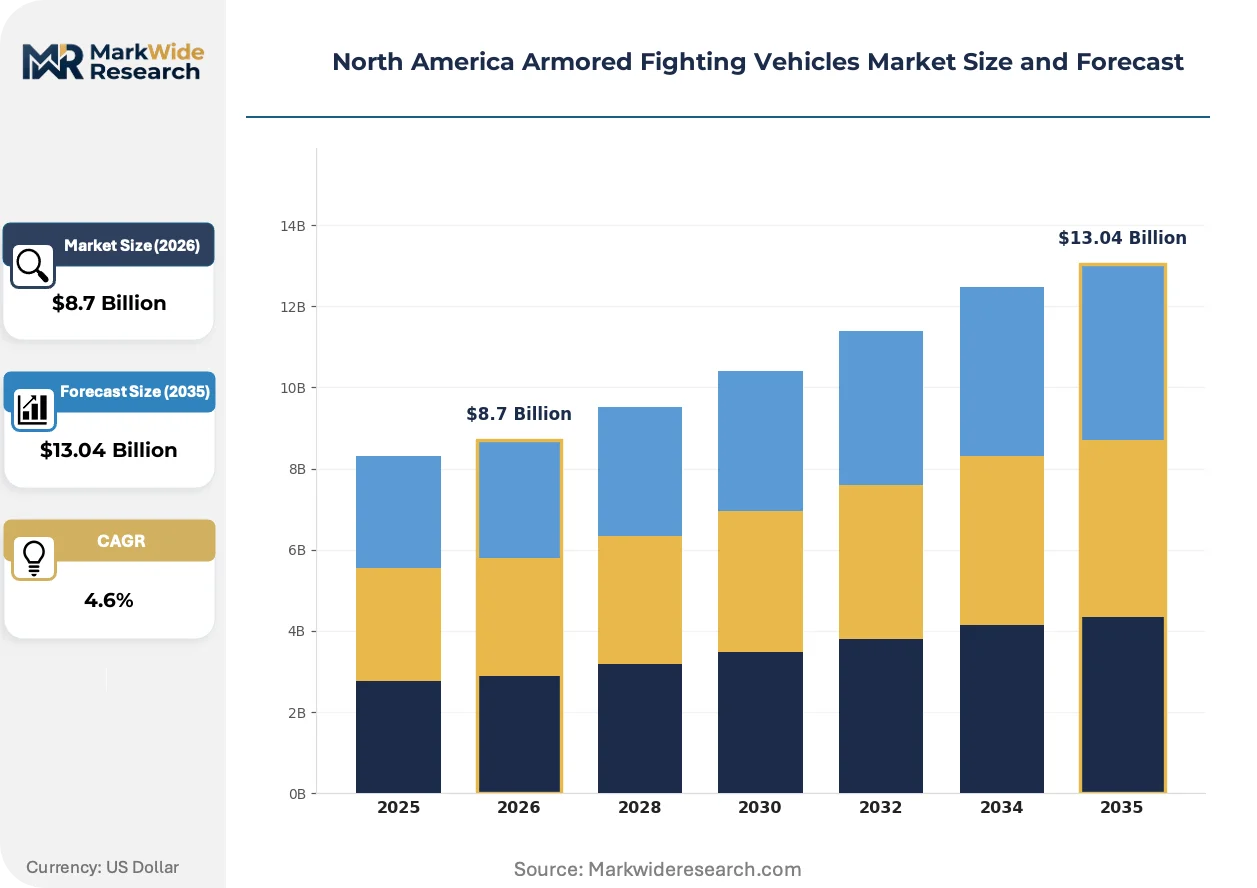
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Main Battle Tank, Armored Personnel Carrier, Infantry Fighting Vehicle, Reconnaissance Vehicle Technology: Hybrid, Electric, Conventional, Autonomous End User: Military Forces, Defense Contractors, Government, Private Security Firms Application: Combat Operations, Tactical Support, Reconnaissance Missions, Peacekeeping Missions |
| Companies Covered | General Dynamics Corporation, BAE Systems plc, Oshkosh Corporation, Textron Systems Corporation, Rheinmetall AG, Leonardo S.p.A., AM General LLC, Thales Group, L3Harris Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Armored Fighting Vehicles Market Evolving Landscape
Platform electrification and modular armor architectures are displacing conventional mechanical designs while procurement models evolve toward performance-based availability contracts rather than unit acquisition.
Hybrid-electric propulsion systems are electrifying tactical vehicle powertrains by enabling silent maneuver and reduced thermal signatures during stationary operations. The U.S. Army's Ground Vehicle Systems Center is accelerating validation of integrated battery packs for reconnaissance variants. This shift is compressing demand for traditional diesel-mechanical transmissions in favor of distributed power electronics.
The Department of Defense's Milestone Decision Authority reviews are tightening survivability verification requirements before production approval. Contractor engineering specifications now mandate iterative ballistic testing against evolving threat profiles. Infantry Fighting Vehicle programs face the steepest compliance burden as the Joint Capabilities Integration Development System prioritizes crew protection metrics.
Canadian and U.S. forces are consolidating maintenance and upgrade contracts under multi-year performance agreements tied to fleet readiness rates. Traditional transactional spare parts procurement is giving way to integrated logistics support packages where contractors retain ownership of critical component inventories. This restructuring is most visible in southwestern U.S. production hubs where prime contractors co-locate sustainment operations with manufacturing facilities.
North America Armored Fighting Vehicles Market Segmentation
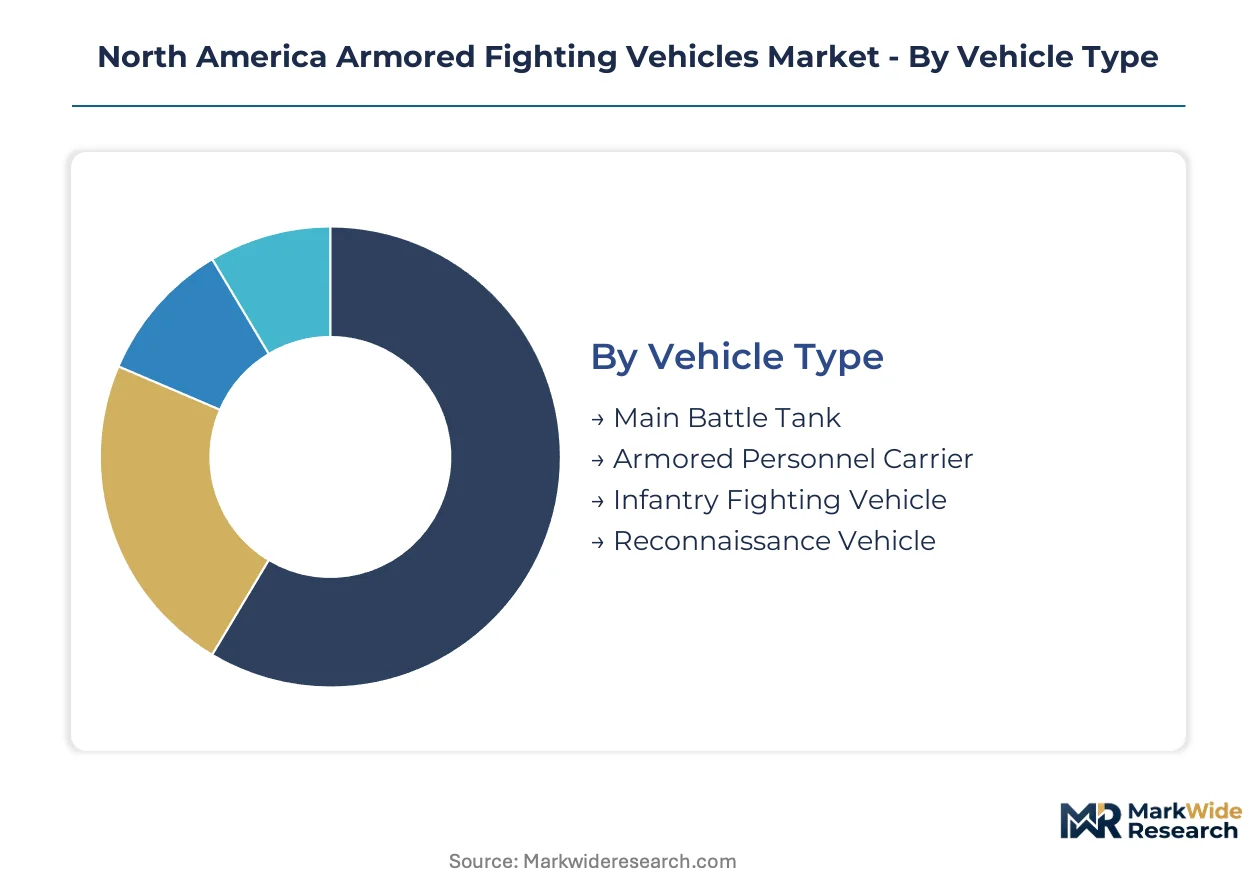
Segmentation in armored fighting vehicles reveals how procurement priorities split between legacy platform sustainment and next-generation capability insertion. Defense buyers balance proven hull designs against electrified, autonomous architectures that demand new supplier ecosystems and training pipelines.
Vehicle Type:
Standardization dominates heavy armor categories where hull designs persist across decades, while lighter platforms permit greater customization for mission-specific configurations.
- Main Battle Tank:Steel-ceramic composite armor packages rated to STANAG 4569 Level 6 protection anchor these 60+ ton platforms. The U.S. Army's M1 Abrams modernization programs concentrate demand in Michigan and Ohio manufacturing corridors, constrained by turret integration lead times for active protection systems.
- Infantry Fighting Vehicle:Tracked hulls with 25-40mm autocannon armament and dismount capacity for 6-8 soldiers. Canadian Army requirements under the Defence Procurement Strategy are driving competition for LAV 6.0 replacements, with silent watch capability emerging as a mandatory specification.
- Armored Personnel Carrier:Wheeled or tracked troop transports emphasizing survivability over firepower. Mexican military modernization is expanding addressable demand south of U.S. border states.
- Reconnaissance Vehicle:Light armor platforms optimized for sensor payload integration and rapid deployment. U.S. Marine Corps Force Design 2030 weight restrictions are accelerating development of amphibious-capable variants.
Leading the category by volume: Infantry Fighting Vehicle. Growing fastest: Reconnaissance Vehicle.
Technology:
Cost tiers separate established mechanical systems from developmental electromechanical architectures requiring substantial non-recurring engineering investment.
- Conventional:Diesel-mechanical powertrains with proven battlefield reliability and established maintenance infrastructure. These systems retain dominance in Canadian and Mexican fleets where upgrade budgets prioritize armor and communications over propulsion.
- Hybrid:Battery-integrated power systems enabling silent maneuver and reduced thermal signatures. The U.S. Army Ground Vehicle Systems Center validation programs are accelerating adoption for reconnaissance variants operating in contested electromagnetic environments.
- Autonomous:Unmanned ground platforms with remote operator stations and AI-enabled navigation. The Robotic Combat Vehicle program is creating funded development pathways, though full-rate production awaits reliability maturation.
- Electric:Fully battery-electric propulsion for light tactical vehicles and support equipment. Range limitations restrict deployment to fixed-base security and convoy escort roles within southwestern U.S. training installations.
Conventional systems retain the largest installed base. Autonomous platforms are climbing the fastest as program funding accelerates.
End User:
Customer type determines specification rigor, with military forces demanding full STANAG certification while private buyers accept commercial armor standards.
- Military Forces:National armies and marine corps requiring full-spectrum survivability against ballistic, mine, and IED threats. U.S. Army Futures Command modernization priorities are compressing development cycles for next-generation combat platforms.
- Defense Contractors:Prime manufacturers and subsystem suppliers procuring testbed vehicles and technology demonstrators. Southwestern U.S. production clusters in Texas and Arizona concentrate this demand near Ground Vehicle Systems Center validation facilities.
- Government:Federal agencies beyond uniformed services, including border patrol and diplomatic security details. These buyers prioritize wheeled platforms with commercial automotive commonality for simplified logistics.
- Private Security Firms:Commercial operators acquiring surplus or downgraded military vehicles for facility protection and high-threat transport. Regulatory fragmentation across U.S. states and Canadian provinces creates compliance complexity for cross-border operations.
Military Forces dominate procurement volume. Defense Contractors represent the steepest expansion trajectory as development program funding increases.
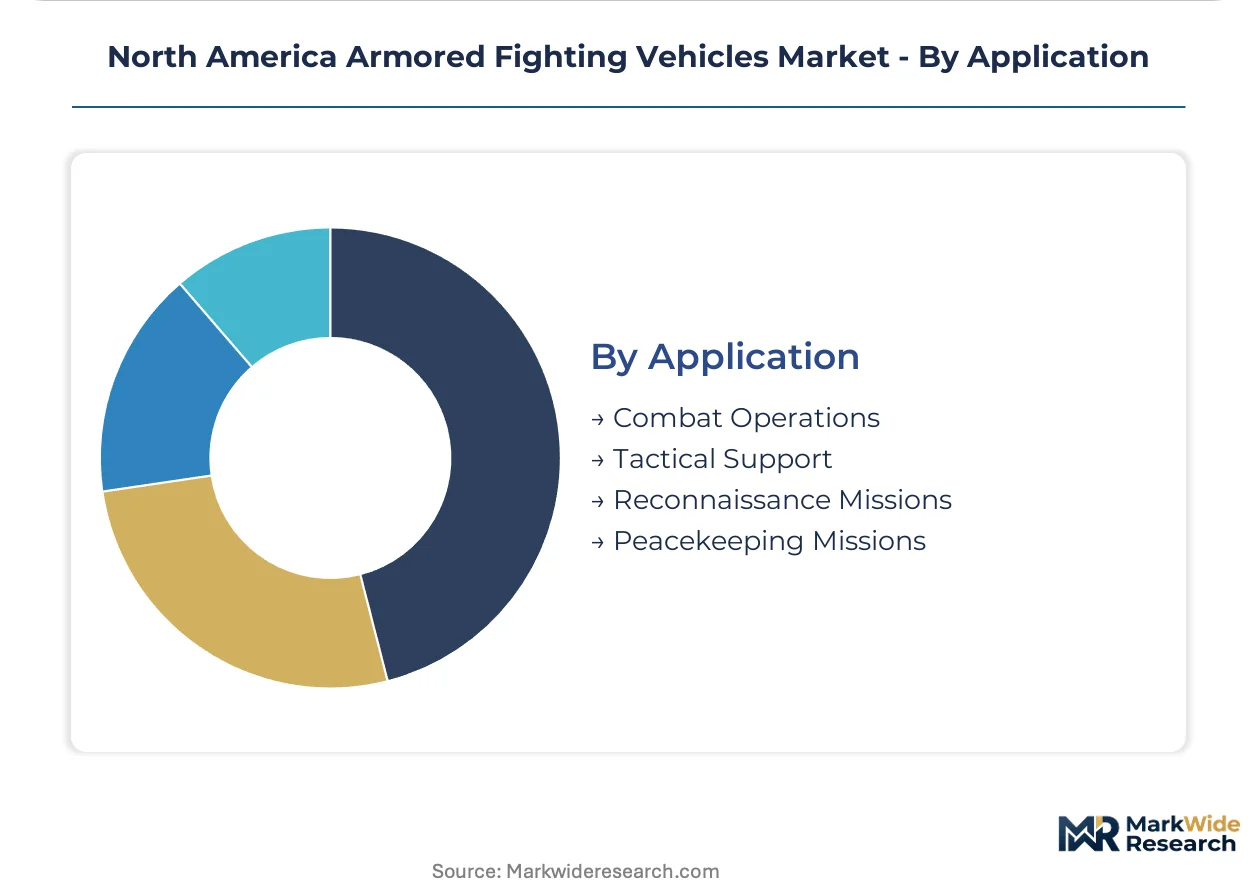
Application:
Geography of deployment shapes platform specifications, with desert and arctic environments imposing distinct thermal management and mobility requirements.
- Combat Operations:Direct fire engagements requiring maximum protection levels and main gun armament. The U.S. Army's emphasis on multi-domain operations is driving integration of counter-drone and electronic warfare capabilities into legacy hulls.
- Tactical Support:Logistics escort, command post mobility, and engineer support missions. Canadian Army procurement under the Defence Procurement Strategy emphasizes modular mission kits for rapid role conversion.
- Reconnaissance Missions:Stealth-priority operations demanding low acoustic and thermal signatures. Hybrid propulsion is gaining preference in this application for silent infiltration capabilities.
- Peacekeeping Missions:Rules-of-engagement-constrained deployments emphasizing visibility and crowd control. These operations favor wheeled platforms with non-lethal systems integration and enhanced crew situational awareness.
Combat Operations leads by platform count. Reconnaissance Missions is gaining share fastest as autonomous systems mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foreign Trade Zone 74 in El Paso anchors defense manufacturing concentration through tariff exemptions on imported armor-grade steel and ceramic composites. This zone feeds assembly lines across the southwestern United States while Canadian and Mexican procurement programs expand the addressable market beyond U.S. borders.
United States
The U.S. Army's Ground Vehicle Systems Center in Warren, Michigan validates next-generation combat platforms while compressing development cycles. The Department of Defense's Milestone Decision Authority reviews enforce survivability standards through Joint Capabilities Integration Development System requirements. Texas manufacturing corridors from Dallas-Fort Worth to San Antonio concentrate tracked vehicle fabrication capacity with co-located supplier networks.
Canada
The Department of National Defence's Defence Procurement Strategy drives armored personnel carrier replacement bidding open to international competition. Canadian Army requirements prioritize silent watch capability and modular mission kits for rapid role conversion. Ontario-based defense contractors cluster near Ottawa-Gatineau to coordinate with federal acquisition authorities.
Mexico
Mexican military modernization programs expand demand for wheeled armored vehicles with commercial automotive commonality. The Secretariat of National Defense coordinates procurement through domestic industrial participation requirements. Northern border states concentrate vehicle assembly operations to serve cross-border logistics and security missions.
North America Armored Fighting Vehicles Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with prime contractors retaining platform integration while subsystem suppliers capture component-level value. The vendor base concentrates around three to five dominant tracked and wheeled vehicle producers with established defense contracting relationships. Strategic archetypes include diversified conglomerates with land systems divisions, pure-play armored vehicle specialists, and European primes partnering for U.S. market access. Competitive moves center on strategic partnerships for technology transfer and capacity expansion in southwestern manufacturing clusters.
Among diversified defense conglomerates, General Dynamics Corporation and BAE Systems plc occupy positions as archetypal prime contractors with integrated land systems capabilities. Rheinmetall AG represents the European partnership model, leveraging platform licensing to access U.S. procurement programs. These three entities exemplify contrasting market entry strategies: organic capability retention, subsidiary-based market presence, and transatlantic joint ventures.
| Leading Market Players |
|---|
| General Dynamics Corporation |
| BAE Systems plc |
| Oshkosh Corporation |
| Textron Systems Corporation |
| Rheinmetall AG |
| Leonardo S.p.A. |
| AM General LLC |
| Thales Group |
| L3Harris Technologies |
| Others |
Value Network & Pricing Analysis
Hybrid propulsion engineering talent scarcity in southwestern U.S. manufacturing clusters widens labor-cost differentials between premium-tier integrated systems and standard mechanical retrofits, compressing margins on fixed-price development contracts while rewarding contractors with captive battery-assembly capacity.
Pricing Analysis
High-volume legacy platform sustainment competes with low-volume next-generation development for margin allocation across contractor portfolios. Three-tier pricing structure across integrated system packages, modular upgrade kits, and consumable spares reflects certification burden differentials under STANAG 4569 validation protocols. Cost compression in development-tier contracts stems from rare earth ceramic pricing volatility and ballistic-grade alloy supply constraints. Defense contractors exhibit lowest price sensitivity given cost-plus contracting structures, while private security firms face acute budget constraints driving surplus vehicle procurement.
Supply Chain Analysis
Dual-sourcing requirements for critical transmission systems mandate multi-supplier qualification across domestic qualified vendors, though actual production concentrates among limited certified facilities. Geographic supply concentration centers on the United States for final assembly, Canada for armor-grade steel inputs, and Mexico for commercial automotive commonality components. Raw material dependencies include rare earth ceramics for composite armor, high-strength ballistic steel alloys, and lithium-ion battery cells for hybrid propulsion. Single-source vulnerability for advanced transmission systems creates surge procurement bottlenecks. Distribution runs through prime contractor co-located sustainment operations with manufacturing facilities in Texas and Arizona defense clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America armored fighting vehicles market sits in a technology-transition phase, with hybrid-electric propulsion displacing conventional diesel-mechanical architectures across U.S. Army modernization programs.
For Market Incumbents: Extend active protection system integration capabilities through backward integration into sensor-fusion software development, countering emerging pure-play autonomous navigation specialists. Add electromechanical systems engineering capacity in Michigan and Ohio corridors to address talent scarcity compressing program timelines. Prioritize certification investment for STANAG 4569 Level 6+ survivability ratings to maintain pricing power against lower-tier competitors. For New Entrants and Emerging Players: The Department of National Defence's Defence Procurement Strategy in Canada opens a window for armored personnel carrier replacement bidding beyond established domestic suppliers. Target Canadian Army requirements for silent watch capability and modular mission kits as the most penetrable segment. Pursue technology licensing partnerships with European primes for platform access rather than ground-up development. Leverage southwestern U.S. Foreign Trade Zone 74 tariff exemptions for imported armor-grade inputs to establish cost-competitive assembly operations. For Investors and Strategic Acquirers: Re-rating potential sits with mid-tier subsystem specialists possessing autonomous navigation or predictive maintenance software stacks given U.S. Army Robotic Combat Vehicle program funding acceleration. Long-term viability favors acquisition targets with established Ground Vehicle Systems Center validation relationships and co-located sustainment contracts. Monitor Marine Corps Force Design 2030 amphibious platform weight restriction announcements as the critical inflection signal for expeditionary vehicle demand redirection.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Propulsion Integration | U.S. Army Ground Vehicle Systems Center validation accelerates battery-pack adoption for reconnaissance variants. |
| Active Protection System Development | Counter-drone and electronic warfare integration addresses multi-domain operations requirements under Joint Capabilities Integration Development System. |
| Autonomous Platform Maturation | Robotic Combat Vehicle program funding creates funded development pathways for unmanned ground systems with remote operator stations. |
| Performance-Based Logistics Contracting | Multi-year availability agreements tied to fleet readiness rates shift revenue from transactional spares to integrated sustainment. |
| Southwestern Manufacturing Cluster Expansion | Texas and Arizona production scale-up concentrates specialized fabrication capacity near Foreign Trade Zone 74 tariff exemptions. |
Research Methodology
Document review covered U.S. Department of Defense budget justification materials, Canadian Department of National Defence procurement announcements, and SEC filings from prime contractors, complemented by interviews with program managers at Ground Vehicle Systems Center, procurement leads at Army Contracting Command, subsystem engineering directors at Tier 1 suppliers, and sustainment operations heads at southwestern production facilities. Secondary validation drew from Milestone Decision Authority documentation, Joint Capabilities Integration Development System requirement sets, and customs records for armor-grade steel and ceramic composite imports. Bottom-up platform-level demand estimates triangulated against top-down defense budget allocation analysis.
Segmentation outputs across vehicle type, propulsion technology, end-user category, and mission application dimensions were modeled across the projection horizon. CAGRs derived from historical procurement cycle analysis and program funding trajectory assessment, with specific inputs including Robotic Combat Vehicle program schedule milestones, Canadian Defence Procurement Strategy competitive bidding timelines, and Marine Corps Force Design 2030 platform weight restriction implementation.
The model assumes a particular technology adoption path; alternative pathways for full battery-electric propulsion in light tactical roles would alter the outlook for hybrid system demand curves. Deviation in STANAG 4569 certification timeline enforcement or rare earth ceramic supply disruption would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Armored Vehicles
Asia-Pacific Armored Fighting Vehicles Market
Armored Vehicles
Armored Vehicle Fire Suppression Systems Market
Armored Vehicles
Armoured Personnel Carrier (APC) Market
Armored Vehicles
Armored Vehicle Procurement and Upgrade Market
Armored Vehicles
Middle-East and Africa Armored Vehicles Market
Armored Vehicles
Armored Vehicles Upgrade and Retrofit Market
Armored Vehicles
Armored Vehicles Market
Armored Vehicles
Military Armored Car Market
Armored Vehicles
Europe Armored Fighting Vehicles Market
Armored Vehicles
Armor Protection Systems Market
Armored Vehicles
Boom Arms Market
Armored Vehicles
Armored Vehicle Navigation Systems Market
Armored Vehicles
Global Ceramic Armor Market
Armored Vehicles
Armored Fighting Vehicles Market
Armored Vehicles
Armored Personnel Carrier Market
Armored Vehicles
US Armored Vehicle Market