
 Argentina Respiratory Devices Market | 2026-2036
Argentina Respiratory Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Argentina Respiratory Devices Market Outlook
Domestic assembly capacity in Buenos Aires province is restructuring as local producers absorb technology transfers from multinational partners. Tecme SA leverages its regional manufacturing footprint to supply public sector tenders across the Southern Cone. ResMed anchors the sleep apnea segment through direct distribution networks and clinician training programs. Drägerwerk AG & Co. KGaA competes in critical care ventilation with intensive care unit installations at flagship public hospitals.
Respiratory devices encompass mechanical apparatus designed to assist, monitor, or replace pulmonary function, typically incorporating flow sensors, pressure valves, and filtration media rated to ISO 18562 biocompatibility standards for breathing gas pathways. These systems serve to maintain airway patency, deliver precise oxygen concentrations, or reduce work of breathing in acute and chronic conditions. Portable oxygen concentrators represent the fastest-growing product category as homecare reimbursement expands and patient mobility preferences intensify. Digital monitoring technology commands premium positioning through remote connectivity and adherence tracking capabilities that reduce emergency readmissions. Hospitals remain the dominant end user channel, though homecare is displacing institutional volume for stable chronic respiratory patients.
ANMAT enforces medical device registration under Resolution 2319-2002, requiring clinical evidence and quality system certification for imported respiratory equipment entering the Argentine market. The national Ministry of Health coordinates procurement through the National Program of Medical Technology, directing device allocation toward provinces with underserved respiratory care infrastructure. Stakeholders must monitor provincial budget execution rates and reimbursement schedule revisions to anticipate demand inflection points.
Market Dynamics
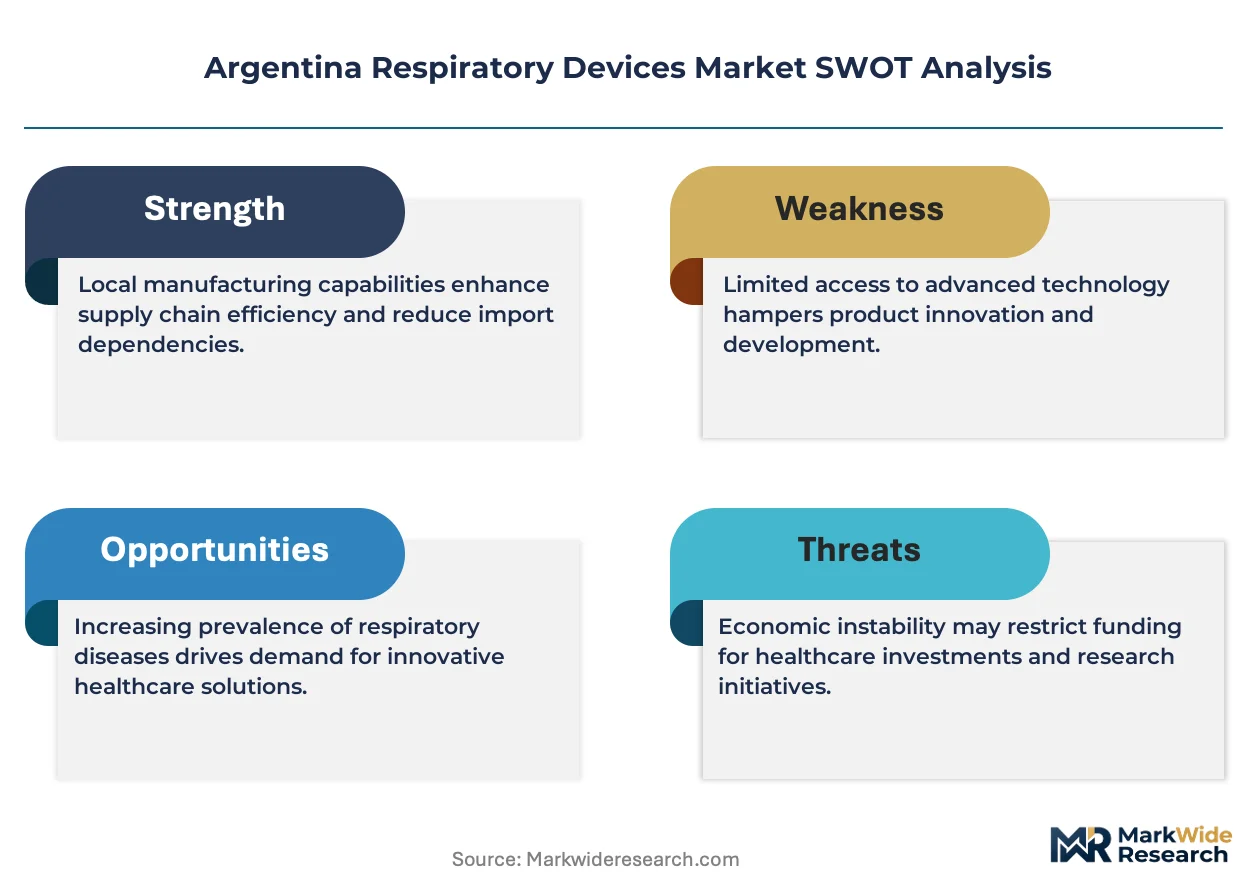
Public hospital procurement consolidation under Argentina's National Program of Medical Technology is compressing vendor margins while favoring suppliers with integrated service networks and provincial logistics capabilities.
Growth Catalysts
- ANMAT Resolution 2319-2002 streamlining:The regulatory pathway for imported respiratory equipment is reducing registration timelines for multinational manufacturers with established quality system certification.
- Buenos Aires tertiary care density:Concentration of specialized pulmonary centers in the province accelerates replacement cycles for aging mechanical ventilators and oxygen delivery infrastructure.
- Homecare reimbursement expansion:National health insurance schedule revisions for portable oxygen concentrators are pulling stable chronic patients out of institutional settings.
Market Restraints
- Import dependency for flow sensors:Domestic producers lack precision manufacturing capabilities for ISO 18562-compliant breathing gas pathway components, exposing the supply chain to currency volatility.
- Provincial budget execution fragmentation:Disparities in fiscal capacity between Buenos Aires, Córdoba, and interior provinces create demand unpredictability for capital equipment tenders.
- Biocompatibility certification costs:Small-scale local assemblers face prohibitive testing expenses for filtration media validation against international standards.
Strategic Opportunities
- Patagonia respiratory care infrastructure gaps:Underserved provinces in southern Argentina present whitespace for mobile diagnostic and tele-ICU service models.
- Digital adherence tracking convergence:Integration of remote connectivity modules with portable oxygen systems enables outcome-based contracting with public payers.
- Technology transfer partnerships:Multinational manufacturers can secure preferential tender access through joint ventures with Tecme SA and other regional assemblers.
Industry Challenges
- Biomedical technician specialization shortage:Critical care ventilation maintenance requires skills scarce outside Buenos Aires metropolitan training centers.
- Legacy equipment integration complexity:New digital monitoring systems face interoperability barriers with installed base of analog ventilators in provincial hospitals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Argentina Respiratory Devices Market |
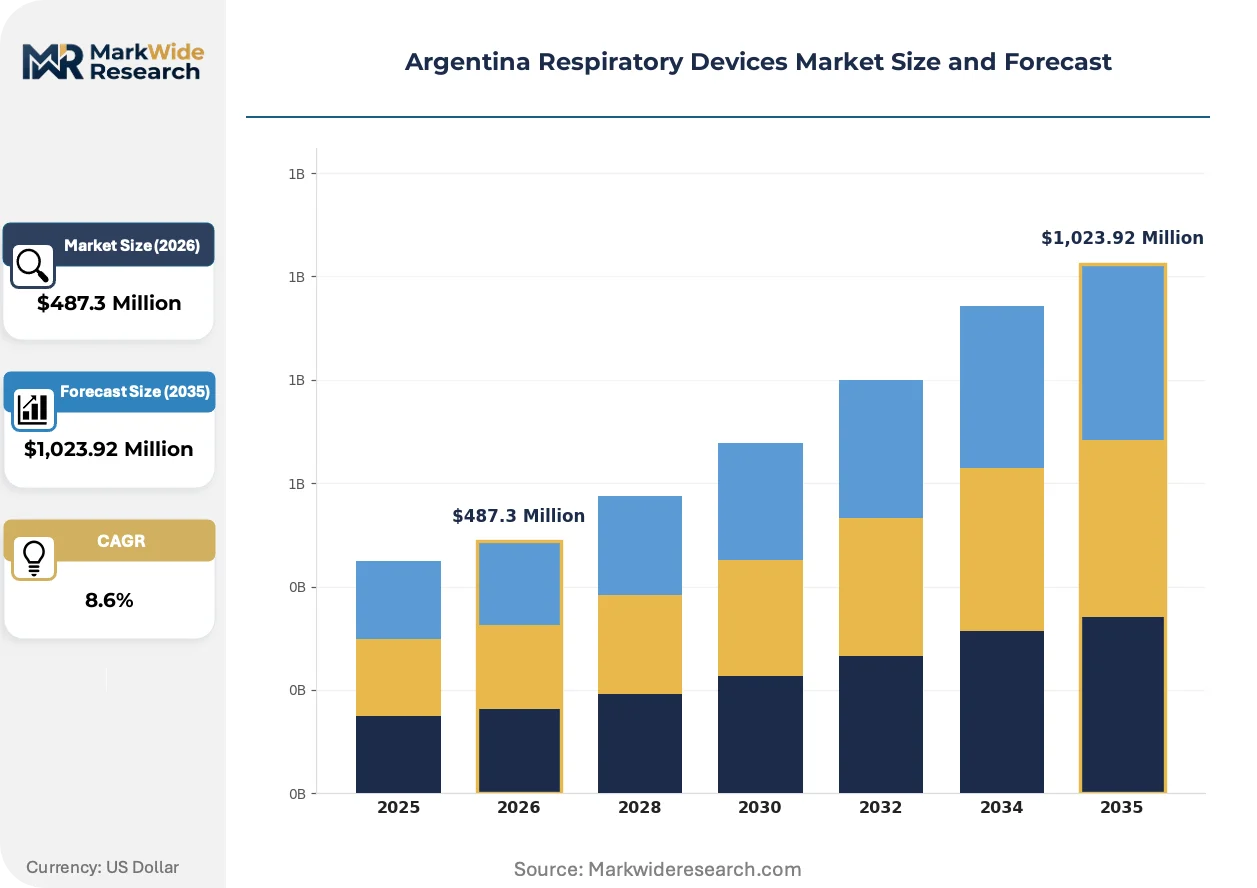
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,023.92 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inhalers, Nebulizers, Oxygen Concentrators, CPAP Devices Application: Asthma, COPD, Sleep Apnea, Respiratory Infections End User: Hospitals, Clinics, Homecare, Rehabilitation Centers Technology: Digital Monitoring, Portable Devices, High-Flow Systems, Non-Invasive |
| Companies Covered | Drägerwerk AG & Co. KGaA, Tecme SA, ResMed, Medtronic, GE Healthcare, Fisher & Paykel Healthcare Limited, Drive DeVilbiss International, Philips Healthcare, Chart Industries, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Argentina Respiratory Devices Market Strategic Shifts
Device connectivity and decentralized care models are restructuring how respiratory support is delivered across Argentine healthcare networks, with implications for vendor business models and procurement specifications.
Portable oxygen concentrator technology is electrifying patient mobility expectations. These battery-powered systems extract nitrogen from ambient air to deliver continuous oxygen flow without cylinder refills. Homecare providers in Buenos Aires province are adopting them at accelerating rates for COPD patient discharge protocols. The technology is electrifying competitive positioning around service radius and response time rather than equipment ownership.
ANMAT is tightening post-market surveillance requirements for Class III respiratory devices under updated risk classification guidelines. Manufacturers must now submit periodic safety reports and adverse event data for mechanical ventilators and anesthesia workstations. The critical care segment is responding by restructuring quality management systems and expanding Buenos Aires-based technical service teams.
Public hospital buying committees are unbundling after-sales service from capital equipment contracts. Provincial procurement offices now separate device acquisition from maintenance agreements, enabling multi-vendor service competition. This pattern is most visible in Córdoba and Santa Fe, where hospital networks are consolidating biomedical engineering functions across facilities.
Argentina Respiratory Devices Market Segmentation
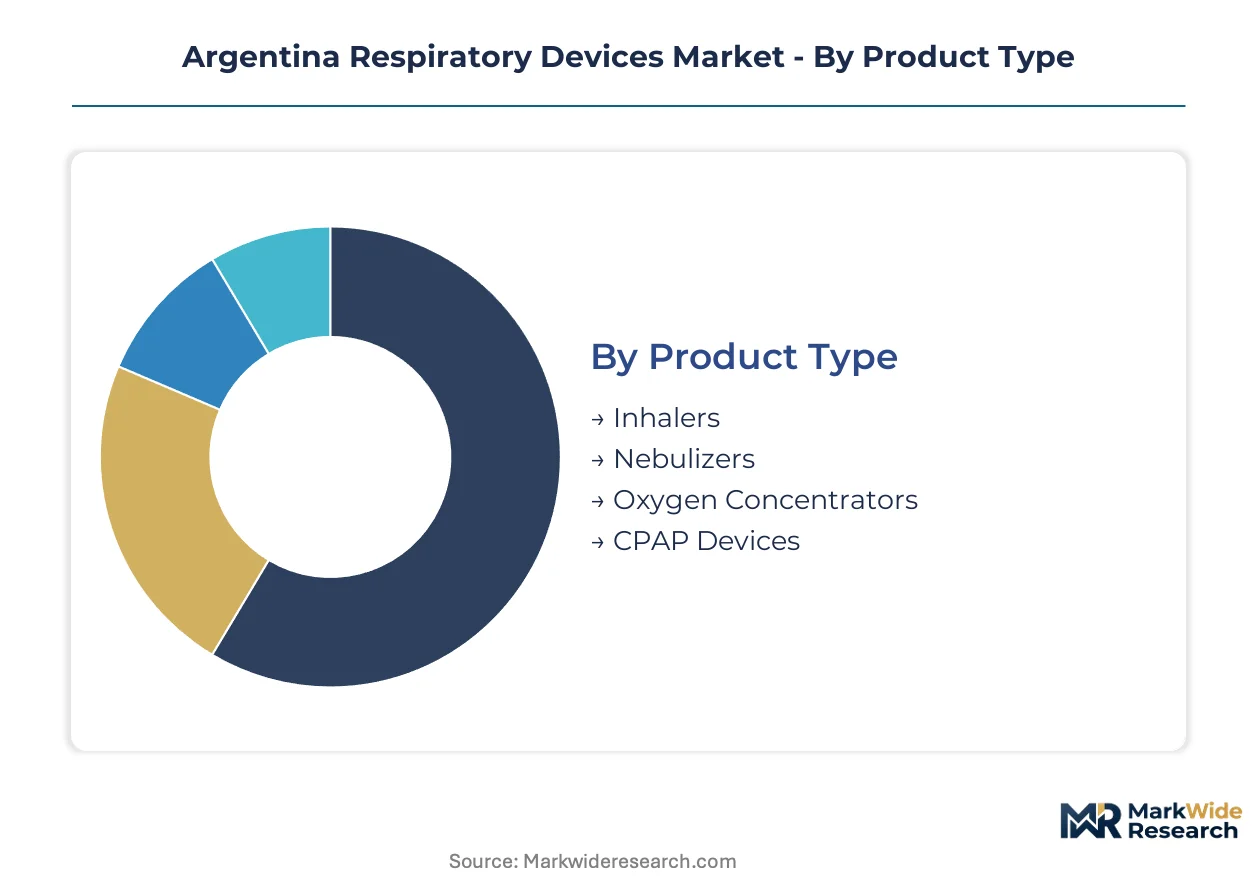
Respiratory device procurement in Argentina fragments across clinical settings and patient acuity levels. Understanding these divisions reveals where ANMAT compliance burdens concentrate and where reimbursement policy shifts redirect volume.
Product Type:
Buyers in this category differentiate by therapy duration and infrastructure requirements.
- Oxygen Concentrators:These systems extract nitrogen from ambient air through pressure swing adsorption or membrane filtration, delivering continuous oxygen flow without cylinder logistics. Demand concentrates in Buenos Aires province homecare networks, where national insurance schedule revisions for portable units pull stable COPD patients out of hospital beds. Currency volatility on imported flow sensors constrains provincial expansion.
- CPAP Devices:Continuous positive airway pressure systems maintain upper airway patency through microprocessor-controlled blower motors and humidification chambers. Sleep apnea diagnosis rates in metropolitan Buenos Aires drive replacement cycles, though clinician training gaps limit penetration in Córdoba and Santa Fe provinces.
- Inhalers:Metered-dose and dry-powder devices deliver bronchodilator and corticosteroid formulations through propellant or breath-actuated mechanisms. Primary care prescription volumes in urban centers dominate procurement.
- Nebulizers:Compressor-driven or ultrasonic systems aerosolize liquid medications for patients with severe airflow limitation. Pediatric asthma protocols in public hospitals sustain demand despite maintenance complexity.
Volume sits with oxygen concentrators; growth tilts toward CPAP devices.
Application:
Therapy selection here tracks disease progression stage and acute versus chronic management needs.
- COPD:Chronic obstructive pulmonary disease requires escalating intervention from bronchodilator inhalers through long-term oxygen therapy to non-invasive ventilation. Buenos Aires tertiary centers manage the most severe cases, while provincial hospitals struggle with diagnostic capacity.
- Sleep Apnea:Obstructive sleep apnea diagnosis depends on polysomnography availability concentrated in capital region sleep laboratories. Home testing device penetration remains limited by reimbursement coding gaps.
- Asthma:Allergic and non-allergic asthma management relies heavily on inhaled corticosteroid adherence, with pediatric cases driving nebulizer volume in public pediatric wards.
- Respiratory Infections:Acute viral and bacterial pneumonias generate surge demand for high-flow nasal cannula systems and mechanical ventilation during seasonal peaks.
COPD captures the largest installed base; sleep apnea claims the steepest expansion trajectory.
End User:
Facility type determines capital budget cycles, technical staffing depth, and patient throughput economics.
- Hospitals:Tertiary care centers in Buenos Aires province manage acute respiratory failure through intensive care ventilation and high-flow oxygen systems. ANMAT registration requirements for Class III devices concentrate compliance costs at this tier.
- Homecare:Durable medical equipment providers deliver portable oxygen concentrators and CPAP systems to discharged chronic patients. Reimbursement schedule revisions are redirecting stable COPD volume from institutional to home settings.
- Clinics:Outpatient pulmonary practices in urban centers handle diagnosis and initial therapy titration for asthma and sleep apnea cases.
- Rehabilitation Centers:Post-acute facilities manage ventilator weaning and pulmonary rehabilitation for patients recovering from critical illness.
Hospitals dominate capital equipment procurement; homecare is displacing institutional volume for stable chronic respiratory patients.
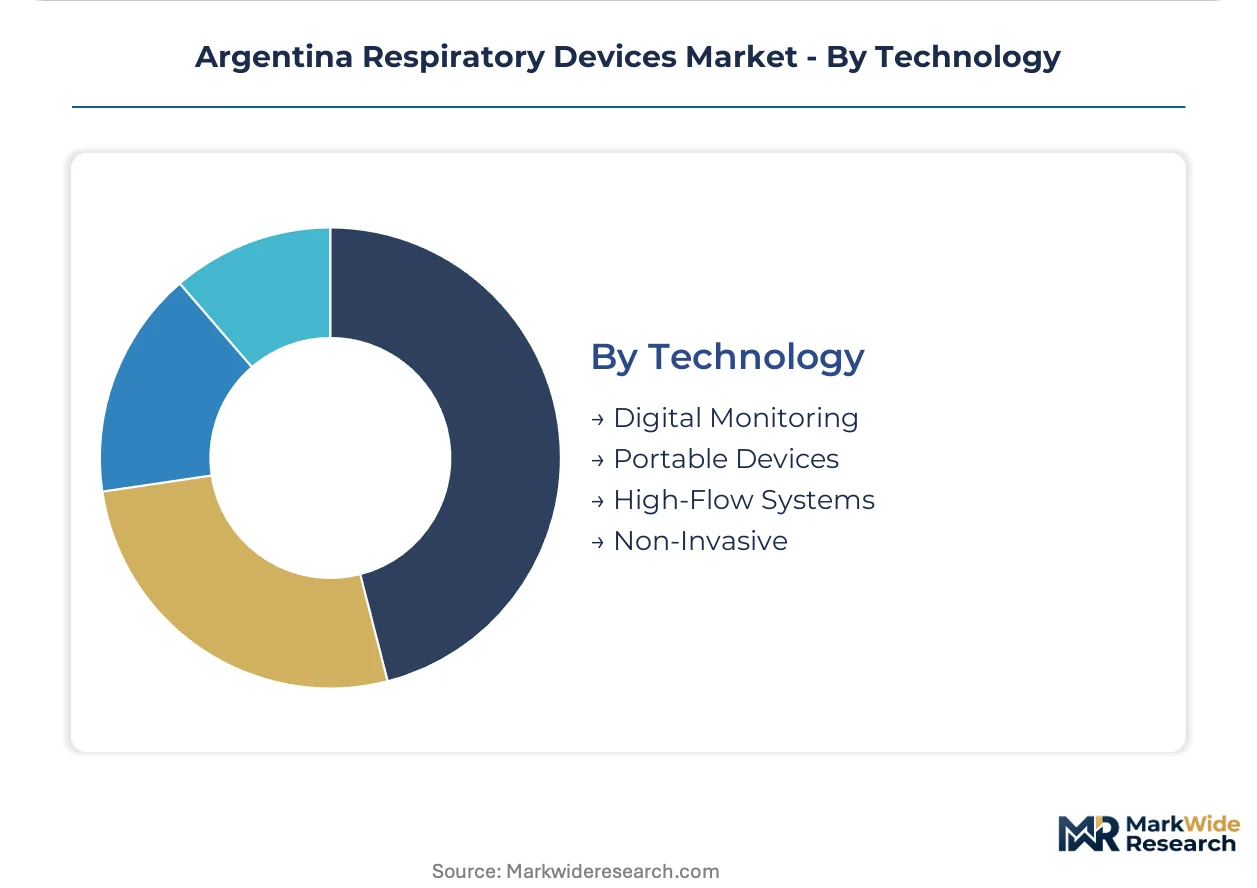
Technology:
Capability tier here separates premium positioning from commodity supply, with connectivity modules commanding service contract attachment.
- Digital Monitoring:Cloud-connected respiratory devices transmit adherence data, therapy efficacy metrics, and equipment fault alerts to centralized monitoring platforms. Remote connectivity reduces emergency readmissions and enables outcome-based contracting with public payers.
- Portable Devices:Battery-powered oxygen concentrators and travel CPAP systems enable patient mobility outside clinical settings. Buenos Aires homecare providers compete on service radius and response time rather than equipment ownership.
- High-Flow Systems:Heated and humidified nasal cannula delivery at flow rates exceeding traditional oxygen therapy bridges patients between conventional oxygen and mechanical ventilation.
- Non-Invasive:CPAP, BiPAP, and adaptive servo-ventilation modes deliver pressure support without endotracheal intubation, preserving patient autonomy and reducing ventilator-associated pneumonia risk.
Non-invasive systems anchor current installed base; digital monitoring integration is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silica sand deposits in Entre Ríos province supply filtration media for respiratory device manufacturing, anchoring Argentina's position in the Southern Cone medical device supply chain.
Buenos Aires Province
Tertiary care density and aging ventilator replacement cycles concentrate demand in Greater Buenos Aires metropolitan clusters. ANMAT Resolution 2319-2002 compliance costs weigh heavily on hospital procurement committees evaluating Class III device tenders. The Pilar industrial corridor hosts domestic assembly operations absorbing technology transfers from multinational partners.
Córdoba
Provincial hospital networks consolidate biomedical engineering functions across facilities, unbundling after-sales service from capital equipment contracts. The National Program of Medical Technology directs device allocation toward underserved respiratory care infrastructure. Córdoba city's medical device distribution hub serves interior provinces with lagging fiscal capacity.
Santa Fe
Rosario's port logistics infrastructure facilitates imported component flows for regional assemblers lacking precision manufacturing capabilities. Provincial budget execution fragmentation creates demand unpredictability for oxygen concentrator tenders. The city anchors service radius competition among homecare providers deploying portable systems.
Mendoza
Andean altitude drives chronic hypoxia prevalence and long-term oxygen therapy requirements in provincial healthcare networks. Reimbursement schedule revisions for portable concentrators pull stable COPD patients toward homecare settings. The city of Mendoza concentrates sleep apnea diagnostic capacity through private clinic networks.
Argentina Respiratory Devices Market Competitive Environment
Global majors compete with regional champions across procurement consolidation and service network integration. The vendor base stratifies into three tiers: multinational manufacturers with direct ANMAT registration, regional assemblers leveraging technology transfer partnerships, and domestic distributors capturing provincial tender volume. Strategic archetypes include integrated critical care suppliers, portable device specialists, and public sector contract aggregators. Capacity expansion in Buenos Aires province and technology licensing agreements represent dominant competitive moves.
Among Germany-based industrial conglomerates with medical device divisions, Drägerwerk AG & Co. KGaA occupies a position exemplifying the integrated critical care archetype. Tecme SA represents regional manufacturing champions absorbing multinational technology transfers to secure public sector tender access. ResMed anchors the portable and homecare device tier through direct distribution investments. These three entities collectively illustrate the competitive structure binding global product development with provincial logistics capabilities.
| Leading Market Players |
|---|
| Drägerwerk AG & Co. KGaA |
| Tecme SA |
| ResMed |
| Medtronic |
| GE Healthcare |
| Fisher & Paykel Healthcare Limited |
| Drive DeVilbiss International |
| Philips Healthcare |
| Chart Industries |
| Others |
Value Chain & Pricing Dynamics
Captive in-house production of flow sensors and pressure valves by multinational manufacturers anchors both supply security and premium pricing power in Argentina's respiratory device market. This backward integration shields tier-one suppliers from currency-driven input cost volatility while compressing margins for domestic assemblers dependent on imported ISO 18562-certified components.
Pricing Analysis
Warranty and preventive maintenance bundling separates premium-tier ventilator contracts from unbundled equipment-only tenders favored by provincial procurement offices. Three-tier pricing structure across premium, standard, and economy levels tracks ANMAT registration status, with Class III device certification commanding service contract attachment. Pricing pressure stems from public hospital buying committees unbundling after-sales service from capital acquisitions. Municipal hospital networks exhibit highest price sensitivity; flagship tertiary centers in Buenos Aires prioritize total cost-of-ownership over upfront equipment cost.
Supply Chain Analysis
Freight cost differentials between Rosario port entry and interior province distribution centers fragment procurement economics for regional assemblers. Precision flow sensor manufacturing concentrates in Germany, Switzerland, and the United States, while filtration media draws from Entre Ríos province silica deposits and Chinese activated carbon suppliers. Single-source vulnerability on microprocessor-controlled blower motors exposes distributors to semiconductor allocation constraints. Distribution runs through Buenos Aires medical device distribution hubs serving provincial hospital networks with lagging fiscal capacity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ANMAT Resolution 2319-2002 erects a cost-of-compliance barrier that rewards manufacturers with established quality system certification and clinical evidence dossiers, filtering out speculative entrants lacking regulatory infrastructure investment capacity.
For Market Incumbents: Anchor service network density in Buenos Aires province to defend against technology transfer partnerships eroding tender access. Expand Buenos Aires-based technical service teams to meet tightened post-market surveillance requirements for Class III devices. Backward integration into filtration media validation capabilities counters biocompatibility certification cost pressures on local joint venture partners. For New Entrants and Emerging Players: Direct-to-clinician digital training platforms offer a low-capital route to bypass consolidated hospital procurement committees. Target Córdoba and Santa Fe provincial networks unbundling biomedical engineering functions across facilities. Homecare reimbursement expansion for portable oxygen concentrators presents the most penetrable segment for service-radius competition. For Investors and Strategic Acquirers: Exit pathways concentrate in regional manufacturing champions with technology transfer partnerships and established ANMAT registration pathways. Long-term viability hinges on provincial budget execution normalization and reimbursement schedule stability. Monitor National Program of Medical Technology device allocation flows as inflection indicator for demand trajectory shifts.| Strategic Initiative | Industry Significance |
|---|---|
| ANMAT Registration Pathway Investment | Resolution 2319-2002 compliance secures preferential tender access for Class III respiratory devices. |
| Provincial Service Network Expansion | Buenos Aires-based technical teams reduce response times for critical care ventilation maintenance contracts. |
| Technology Transfer Partnership | Joint ventures with Tecme SA anchor domestic assembly capacity for public sector procurement consolidation. |
| Digital Adherence Platform Development | Remote connectivity modules enable outcome-based contracting with national health insurance programs. |
| Homecare Reimbursement Strategy | Portable oxygen concentrator positioning captures volume displacement from institutional to home settings. |
Study Parameters
Multi-period observation of ANMAT registration timelines, provincial tender award patterns, and reimbursement schedule revisions anchored the trend analysis, supplemented by interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and homecare equipment distributors. Secondary validation drew from ANMAT device registration databases, National Program of Medical Technology procurement disclosures, provincial health ministry budget execution reports, and ISO 18562 biocompatibility certification records. Bottom-up segment sizing triangulated against top-down macroeconomic healthcare expenditure models.
Input-output matrices mapped product category volumes through end-user channels across the projection horizon, with segmentation dimensions spanning therapy acuity, device portability, and connectivity capability. CAGRs derived from regression analysis against healthcare infrastructure investment cycles and chronic respiratory disease prevalence trajectories. Forecast inputs incorporated currency volatility scenarios on imported precision components and provincial fiscal capacity dispersion indices.
The model holds under stable ANMAT regulatory enforcement and national health insurance reimbursement continuity; deviation in provincial budget execution rates or import tariff regimes would shift volume trajectories. Stakeholders should weight assumptions against their own operating context and risk tolerance for emerging market procurement volatility.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Manual Resuscitators Market
Medical Devices
3D Printing for Surgical Procedures Market
Medical Devices
Hemoconcentrators Market
Medical Devices
Electronic Pill Market
Medical Devices
Keratoprosthesis (Kpro) Market
Medical Devices
IV Fluid Monitoring Device Market
Medical Devices
Neurofeedback Systems Market
Medical Devices
Digital Reading Micropipettes Market
Medical Devices
Neurotechnology Market
Medical Devices
Italy Minimally Invasive Surgery Devices Market
Medical Devices
North America Cardiac Rhythm Management Devices Market
Medical Devices
Global Cardiopulmonary Bypass Accessory Equipment Market
Medical Devices
Ambulatory X-Ray Devices Market
Medical Devices
Global Auto-Injectors Market
Medical Devices
Bunion Correction Systems Market
Medical Devices
Global Cardiac Resuscitation Device Market