
 Asia-Pacific Food Hydrocolloids Market | 2026-2036
Asia-Pacific Food Hydrocolloids Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Food Hydrocolloids Market Outlook
Asset-light toll manufacturing and third-party extraction partnerships are reshaping competitive entry in the Asia-Pacific Food Hydrocolloids Market. Cargill Inc leverages its integrated supply chain from Southeast Asian seaweed cooperatives to maintain cost discipline. CP Kelco anchors its position through specialized fermentation capacity for xanthan gum in regional production hubs. Zhejiang Top Hydrocolloids Co Ltd dominates domestic agar extraction with backward integration into Zhejiang coastal farming operations.
Food hydrocolloids comprise high-molecular-weight polysaccharides and proteins that hydrate in aqueous systems to modify viscosity, gelation, and water-binding properties, typically functioning at concentrations between 0.1% and 2.0% by weight in finished formulations. Carrageenan extracted from Kappaphycus and Eucheuma seaweed species commands the largest volume share due to its cost-efficient gelling in dairy applications. Guar gum faces margin compression from Indian raw material price volatility, though bakery sector demand for clean-label texture modifiers sustains premium positioning. Xanthan gum derived from Xanthomonas campestris fermentation represents the fastest-growing product type as microbial sourcing aligns with plant-based and synthetic-free formulation trends.
China's SAMR enforces GB 2760 food additive standards that restrict carrageenan grades in infant formulas, directly redirecting manufacturer procurement toward refined semi-refined alternatives. Japan's METI and FSSAI in India both mandate detailed hydrocolloid origin labeling, creating compliance costs that favor suppliers with traceable seaweed or microbial supply chains. Stakeholders must monitor evolving clean-label thresholds across Australian, South Korean, and ASEAN regulator frameworks to anticipate reformulation mandates before they disrupt existing supply agreements.
Market Dynamics
Plant-based dairy alternative producers across China, Japan, and South Korea are accelerating their reformulation timelines, forcing hydrocolloid suppliers to compress clean-label certification cycles and relocate technical service teams closer to coastal food processing clusters.
Growth Catalysts
- Japan's METI Clean-Label Guidance:Mandatory origin disclosure for hydrocolloids used in processed foods is redirecting procurement budgets toward suppliers with traceable seaweed farming partnerships and certified extraction facilities.
- Fermentation capacity expansion:Xanthan gum producers are scaling microbial production in regional biotech hubs to capture synthetic-free formulation mandates from plant-based beverage brands.
- Eastern seaboard concentration:China's food processing clusters in Zhejiang and Shandong provinces are consolidating demand for agar and carrageenan, creating localized procurement volumes that justify dedicated supply infrastructure.
Market Restraints
- Indian guar gum price volatility:Monsoon-dependent cultivation cycles in Rajasthan and Gujarat create raw material cost swings that compress margins for bakery sector texture modifier suppliers.
- Seaweed supply concentration:Kappaphycus and Eucheuma farming cooperatives in the Philippines and Indonesia control over half of regional carrageenan feedstock, exposing processors to climate disruption and export licensing delays.
- GB 2760 infant formula restrictions:China's SAMR limits on carrageenan grades force manufacturers to maintain dual inventory systems for refined and semi-refined variants, raising working capital requirements.
Strategic Opportunities
- South Korean functional beverage expansion:Local brands are incorporating gellan gum and pectin into probiotic and collagen drinks, creating premium positioning opportunities for suppliers with MFDS-registered production.
- FSSAI traceability mandates:India's origin labeling requirements for imported hydrocolloids favor regional suppliers with integrated farming-to-extraction documentation systems.
- Enzymatic extraction convergence:Cellulase and pectinase processing methods combined with cold-water extraction are reducing energy inputs and expanding yield recovery rates for agar producers.
Industry Challenges
- Clean-label certification timelines:Australian and ASEAN regulator frameworks lack harmonized thresholds for natural versus processed hydrocolloid classifications, forcing suppliers to run parallel compliance tracks for cross-border shipments.
- Fermentation specialist scarcity:Xanthan gum production requires microbial strain maintenance expertise that remains concentrated in legacy biotech hubs, constraining capacity expansion in emerging production zones.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Food Hydrocolloids Market |
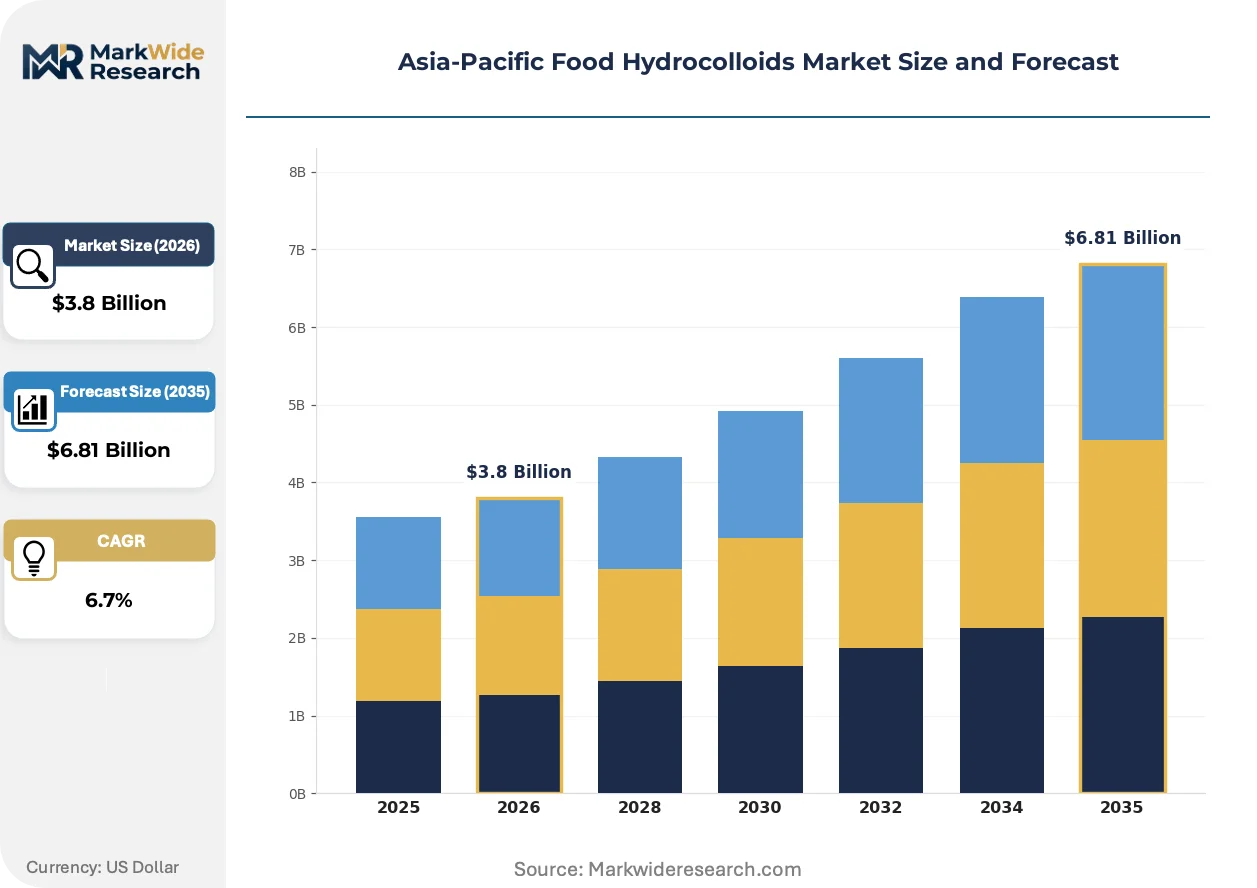
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Agar, Carrageenan, Guar Gum, Xanthan Gum Application: Bakery, Dairy Products, Sauces, Beverages Source: Plant-Based, Seaweed, Microbial, Synthetic End User: Food Manufacturers, Retailers, Restaurants, Catering Services |
| Companies Covered | Cargill Inc, CP Kelco, DuPont de Nemours Inc, Ingredion Incorporated, Kerry Group, Ashland Global Holdings, Koninklijke DSM N V, Archer Daniels Midland Company, Zhejiang Top Hydrocolloids Co Ltd, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Food Hydrocolloids Market Strategic Shifts
Digital traceability platforms and precision fermentation are compressing traditional extraction economics while clean-label mandates rewrite procurement criteria across Asia-Pacific food manufacturing.
Blockchain-enabled supply chain verification is digitizing documentation flows from seaweed farm cooperatives in Southeast Asia through to finished hydrocolloid batches. Major dairy alternative producers in China and Japan are mandating real-time origin tracking for carrageenan and agar purchases. This transparency infrastructure is compressing supplier qualification cycles and raising barriers for traders without direct farming partnerships.
Australia's TGA and South Korea's MFDS are tightening additive safety review protocols for novel hydrocolloid blends used in functional foods. Manufacturers must submit expanded toxicological data packages before market authorization. Infant nutrition and medical food segments are experiencing the longest approval delays, redirecting R&D investment toward established GRAS-listed variants with existing regulatory dossiers.
Direct contracting between hydrocolloid extractors and plant-based food brands is displacing traditional distributor networks in China and India. Large dairy alternative producers are negotiating multi-year offtake agreements with Zhejiang and Tamil Nadu extraction facilities. This channel consolidation is visible most acutely in the oat milk and cultured dairy segments, where formulation stability requirements favor supplier relationships with embedded technical service capabilities.
Asia-Pacific Food Hydrocolloids Market Segmentation
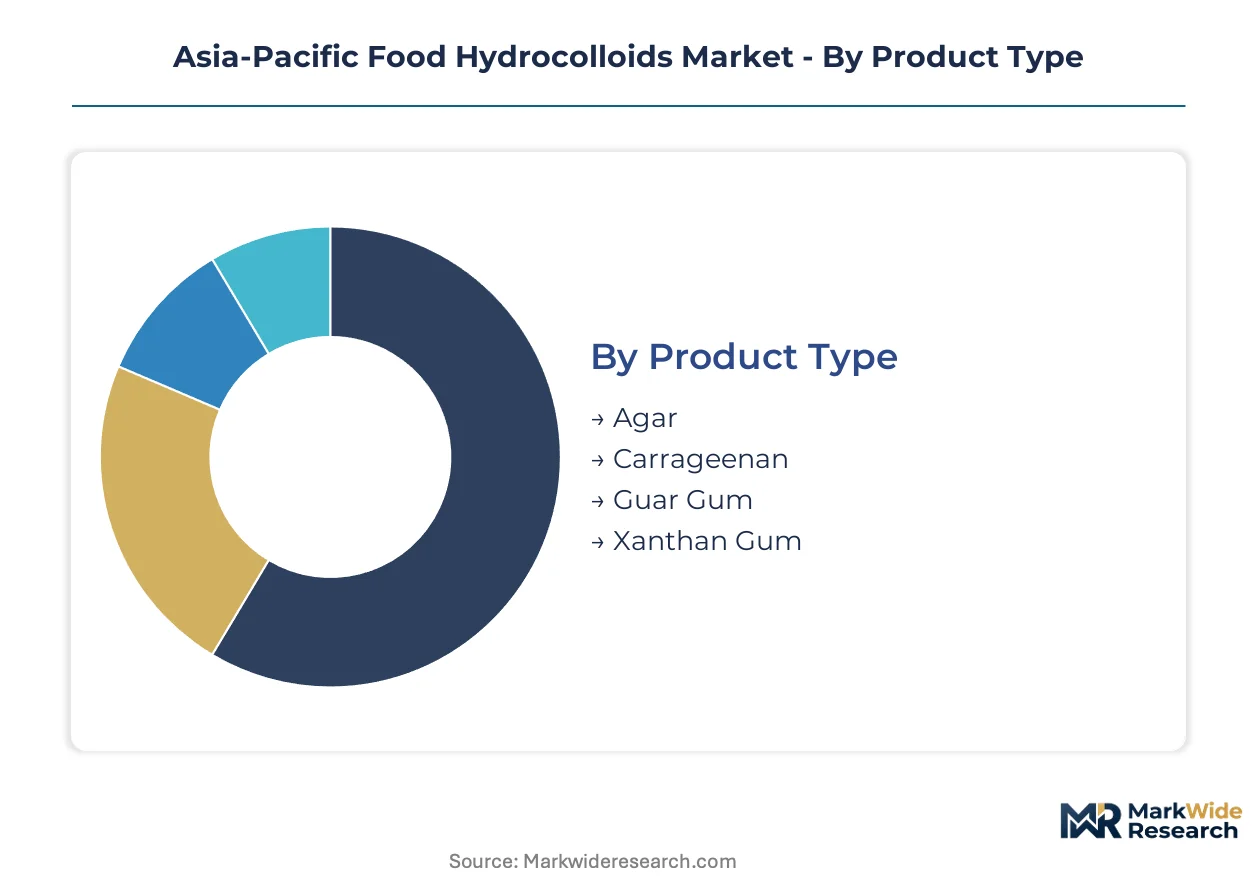
Segmentation in the Asia-Pacific Food Hydrocolloids Market reveals how technical service requirements, regulatory compliance burdens, and supply chain proximity reshape supplier selection. Buyers prioritize partners with localized extraction capabilities and clean-label certification support.
Product Type:
After-sales service intensity varies sharply across hydrocolloid categories, with fermentation-based products demanding microbial strain maintenance expertise and seaweed extracts requiring farm-to-facility traceability documentation.
- Carrageenan:Extracted primarily from Kappaphycus and Eucheuma seaweed species, this sulfated galactan delivers cost-efficient thermoreversible gelling for dairy applications. Demand concentrates in China's eastern seaboard dairy clusters, where SAMR's GB 2760 standards force dual inventory systems for refined and semi-refined grades.
- Xanthan Gum:Produced via Xanthomonas campestris fermentation, this extracellular polysaccharide provides exceptional pH stability and pseudoplastic flow. South Korean and Japanese plant-based beverage manufacturers are accelerating procurement as METI clean-label guidance favors microbial over synthetic sourcing.
- Agar:Zhejiang coastal farming operations supply the Gelidium and Gracilaria feedstock for this gelling agent used in confectionery and microbiological media.
- Guar Gum:Rajasthan and Gujarat cultivation cycles expose processors to monsoon-dependent price volatility that compresses bakery sector margins.
Carrageenan holds the largest share; momentum sits with Xanthan Gum.
Application:
Application-driven segmentation exposes how formulation complexity dictates hydrocolloid blend sophistication and technical support requirements.
- Dairy Products:Carrageenan-protein interactions stabilize chocolate milk and prevent whey separation in cultured products. China's infant formula restrictions redirect procurement toward semi-refined grades, while Japanese processors demand origin-disclosed seaweed sourcing under METI guidance.
- Beverages:Gellan gum and pectin incorporation into South Korean probiotic and collagen drinks creates premium positioning for MFDS-registered suppliers. Xanthan gum suspension properties serve oat milk and nut-based alternatives requiring long-term phase stability.
- Bakery:Guar gum and cellulose derivatives manage moisture retention in gluten-free formulations facing clean-label scrutiny.
- Sauces:Xanthan gum and modified starches control viscosity and prevent syneresis in shelf-stable emulsions.
Dairy Products commands volume leadership; Beverages is climbing the fastest.
Source:
Source-based segmentation tracks how regulatory frameworks and consumer preference shifts redistribute procurement across extraction and production methods.
- Seaweed:Kappaphycus and Eucheuma farming cooperatives in the Philippines and Indonesia control over half of regional carrageenan and agar feedstock. Climate disruption and export licensing delays expose processors to supply interruption.
- Microbial:Xanthomonas campestris fermentation delivers synthetic-free hydrocolloids aligned with plant-based formulation trends. Capacity expansion concentrates in regional biotech hubs where specialist strain maintenance expertise remains scarce.
- Plant-Based:Guar and locust bean gums from Indian and African cultivation satisfy clean-label bakery and sauce applications.
- Synthetic:Chemically modified cellulose derivatives persist in industrial applications despite declining food-grade authorization.
Seaweed dominates current supply; Microbial is gaining share fastest.
End User:
End user segmentation illuminates how procurement scale, technical sophistication, and traceability requirements fragment the customer base.
- Food Manufacturers:Large dairy alternative producers in China and India negotiate multi-year offtake agreements directly with Zhejiang and Tamil Nadu extraction facilities. Embedded technical service capabilities determine supplier selection for formulation stability-critical segments.
- Retailers:Private-label brands demand blockchain-enabled origin verification for clean-label product lines, compressing supplier qualification cycles.
- Restaurants:Commercial kitchens source hydrocolloid blends through redistributors for texture modification in prepared sauces and desserts.
- Catering Services:Institutional foodservice operators prioritize cost-stable, long-shelf-life hydrocolloid systems for large-batch preparation.
Food Manufacturers represent the largest procurement volume; Retailers show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power tilts toward Chinese coastal extractors commanding Zhejiang and Shandong agar supply, while Indian guar processors absorb monsoon-driven raw material volatility that erodes margin capture.
China
Eastern seaboard dairy clusters in Zhejiang and Shandong concentrate demand for carrageenan and agar, with SAMR's GB 2760 standards forcing manufacturers into dual inventory systems for refined and semi-refined grades. SAMR enforcement of infant formula restrictions redirects procurement toward certified semi-refined alternatives. Qingdao and Ningbo processing hubs now host embedded technical service teams from major suppliers to compress clean-label certification cycles for plant-based beverage brands.
Japan
Plant-based dairy alternative producers in Kanto and Kansai regions accelerate reformulation timelines, creating urgency for hydrocolloid origin disclosure. METI clean-label guidance mandates detailed seaweed sourcing documentation for processed food applications. Tokyo-Osaka corridor manufacturers now require real-time farm-to-batch traceability, favoring suppliers with direct Philippine and Indonesian cooperative partnerships over trader intermediaries.
India
Rajasthan and Gujarat guar cultivation cycles expose bakery sector suppliers to monsoon-dependent price swings that compress working capital efficiency. FSSAI origin labeling requirements for imported hydrocolloids redirect procurement toward regional extractors with integrated farming-to-extraction documentation. Tamil Nadu coastal facilities are negotiating multi-year offtake agreements directly with dairy alternative producers, bypassing traditional distributor networks.
South Korea
Functional beverage brands in Seoul Capital Area incorporate gellan gum and pectin into probiotic and collagen drink lines, creating premium positioning for MFDS-registered suppliers. MFDS tightening of additive safety review protocols for novel hydrocolloid blends extends approval timelines for infant nutrition segments. Busan-Ulsan biotech hubs are scaling fermentation capacity for xanthan gum to capture synthetic-free formulation mandates from domestic plant-based brands.
Australia
Clean-label product lines from Sydney and Melbourne retailers demand blockchain-enabled origin verification, compressing supplier qualification cycles for carrageenan and agar purchases. TGA tightening of safety review protocols for novel hydrocolloid blends in functional foods requires expanded toxicological data packages. Queensland and New South Wales food manufacturers prioritize GRAS-listed variants with existing regulatory dossiers to circumvent approval delays in medical food segments.
Asia-Pacific Food Hydrocolloids Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream with extraction and fermentation assets. Market structure tilts toward consolidation among integrated seaweed processors and microbial fermentation operators, with mid-scale traders facing margin compression from traceability mandates. Three archetypes dominate: coastal extractors with backward integration into farming cooperatives, biotech-anchored fermentation specialists, and diversified ingredient platforms with regional toll manufacturing networks. Capacity expansion and direct offtake contracting with plant-based brands constitute the dominant competitive moves reshaping channel relationships.
Within the integrated extractor tier, Zhejiang Top Hydrocolloids Co Ltd occupies a position exemplifying coastal Chinese backward integration into seaweed farming operations. Cargill Inc and CP Kelco represent the multinational platform archetype, leveraging Southeast Asian supply chain infrastructure and regional fermentation capacity respectively. These three entities anchor the competitive map, with Zhejiang-based operations commanding domestic agar supply and the two multinational platforms competing on technical service proximity to eastern seaboard dairy clusters.
| Leading Market Players |
|---|
| Cargill Inc |
| CP Kelco |
| DuPont de Nemours Inc |
| Ingredion Incorporated |
| Kerry Group |
| Ashland Global Holdings |
| Koninklijke DSM N V |
| Archer Daniels Midland Company |
| Zhejiang Top Hydrocolloids Co Ltd |
| Others |
Value Chain & Pricing Dynamics
Monsoon-dependent guar cultivation cycles in Rajasthan and Gujarat determine both the three-tier pricing structure across premium, standard, and economy certification grades and the supply chain's reliance on Indian subcontinent extraction capacity. Food manufacturers absorb working capital volatility while coastal Chinese agar processors capture margin premiums through Zhejiang farming integration.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake agreements that stratify across premium, standard, and economy tiers based on FSSAI traceability certification and volume scale. Price differentiation stems from clean-label grade certification and embedded technical service bundling. Cost compression in standard-tier carrageenan intensifies because SAMR's dual inventory requirements raise working capital burdens. Small bakery sector processors show highest price sensitivity; large dairy alternative producers demonstrate lowest sensitivity due to formulation stability premiums.
Supply Chain Analysis
Philippine and Indonesian export licensing regimes for Kappaphycus and Eucheuma seaweed constrain feedstock flows to regional processors. Geographic supply concentrates in China, Indonesia, and the Philippines for seaweed extracts, with India anchoring guar gum feedstock. Raw material dependencies include Gelidium and Gracilaria seaweed species, Xanthomonas campestris microbial strains, and Rajasthan guar splits. Single-source vulnerability runs through Philippine cooperative concentration for carrageenan. Distribution runs through direct contracting between Zhejiang extraction facilities and plant-based beverage brands, displacing traditional trader networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service attach rates for fermentation strain maintenance and clean-label certification support expand faster than commodity hydrocolloid volumes, creating recurring revenue pools that outperform extraction margins.
For Market Incumbents: Build regulatory dossier moats by securing pre-approved GRAS variants for infant nutrition segments before TGA and MFDS extend safety review timelines. Deepen backward integration into Tamil Nadu and Zhejiang coastal farming operations to secure traceable feedstock for METI-compliant origin disclosure. Channel control through embedded technical teams in Qingdao and Ningbo processing hubs defends against toll manufacturing entrants. For New Entrants and Emerging Players: South Korean functional beverage gellan gum supply represents the most penetrable entry point given MFDS registration gaps and premium positioning opportunities. Mid-scale enzymatic extraction facilities in ASEAN markets with cellulase processing capabilities offer white-space acquisition targets. Go-to-market through direct offtake negotiations with Seoul Capital Area probiotic brands bypasses established distributor relationships. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated extractor platforms with captive farming partnerships over standalone traders. Long-term viability hinges on fermentation capacity scalability and blockchain traceability infrastructure deployment. Acquisition targets should demonstrate SAMR pre-certification for semi-refined carrageenan grades. The signal to watch is MFDS approval velocity for novel hydrocolloid blends in medical food segments as a demand inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seaweed Farming | Zhejiang coastal operations secure traceable Gelidium feedstock for METI-compliant agar supply. |
| Fermentation Capacity Expansion | Busan-Ulsan biotech hubs scale Xanthomonas campestris production for synthetic-free beverage mandates. |
| Blockchain Traceability Deployment | Real-time farm-to-batch verification satisfies Australian retailer clean-label procurement requirements. |
| Long-term Supply Agreement | Multi-year offtake contracts with eastern seaboard dairy clusters lock in volume commitments. |
| Clean-Label Certification Investment | FSSAI-registered documentation systems capture Indian origin labeling compliance premiums. |
Study Parameters
Cross-validation between extraction facility technical directors and plant-based beverage formulation leads anchors the qualitative findings. Primary interviews with seaweed cooperative managers, fermentation strain maintenance specialists, SAMR regulatory consultants, and dairy alternative procurement heads combined with secondary validation from FSSAI additive registry filings, MFDS safety review databases, Chinese customs trade data, and ASEAN food processing investment disclosures. Bottom-up volume modeling and top-down value triangulation reconcile supply-side capacity with demand-side procurement patterns.
Calibration against historical GB 2760 amendment impacts and METI guidance implementation timelines informs the analytical framework across the projection horizon. Segmentation dimensions include hydrocolloid source type, application viscosity requirements, certification grade tier, and regional regulatory cluster. CAGRs derive from compound growth trajectory analysis applied to procurement volume trends. Forecast inputs incorporate monsoon variability indices for Indian guar cultivation and Philippine cooperative export licensing velocity.
Practitioners should monitor SAMR infant formula restriction enforcement intensity and MFDS novel blend approval delays for early signals of demand redirection. Forecasts reflect assumptions regarding sustained plant-based dairy alternative reformulation momentum and stable ASEAN seaweed cooperative governance. Material shifts in Philippine export licensing protocols or Rajasthan monsoon failure frequency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Components and Additives
France Food Preservatives Market
Food Components and Additives
Blackcurrant Powder Market
Food Components and Additives
Japan Food Hydrocolloids Market
Food Components and Additives
Asia-Pacific Food Anti Caking Agents Market
Food Components and Additives
Global Food Carbohydrase Market
Food Components and Additives
France Food Hydrocolloids Market
Food Components and Additives
China Food Hydrocolloids Market
Food Components and Additives
Linoleic Acid Market
Food Components and Additives
Fructo-Oligosaccharides (FOS) Market
Food Components and Additives
Polyunsaturated Fatty Acids Market
Food Components and Additives
Food Grade Iron Powder Market
Food Components and Additives
Global Zeaxanthin Market
Food Components and Additives
Bergamot Polyphenol Ingredient Systems Market
Food Components and Additives
Fermentation Defoamer Market
Food Components and Additives
Edible Oil Co-Products and by-Products Market
Food Components and Additives
Europe Food Hydrocolloids Market