
 North America Food Antimicrobial and Antioxidants Market | 2026-2036
North America Food Antimicrobial and Antioxidants Market Size, Share, and Industry Trends Forecast 2026-2036
North America Food Antimicrobial and Antioxidants Market Analytics
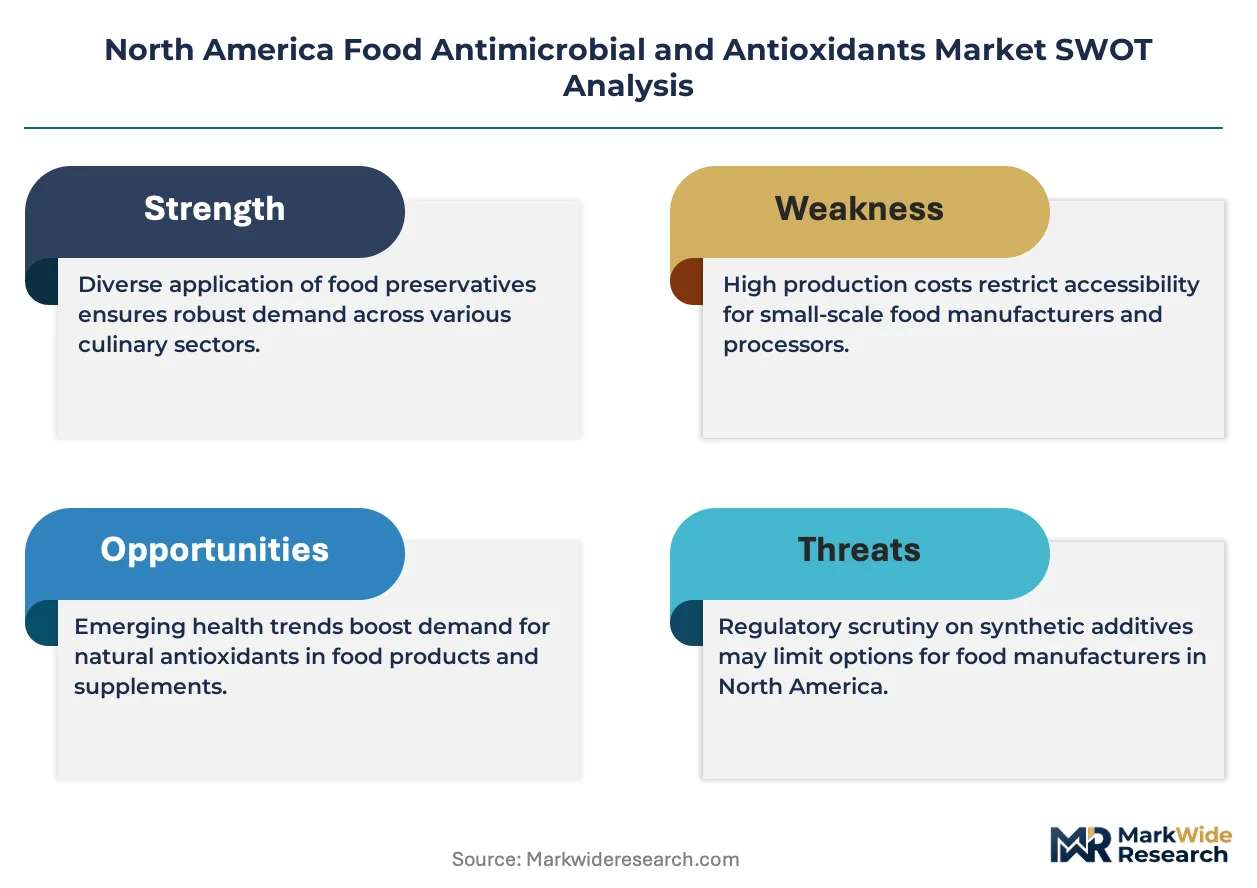
Plant-derived rosemary extract and green tea polyphenols are displacing synthetic butylated hydroxytoluene in poultry and red meat applications, realigning cost structures across the value chain. DuPont de Nemours Inc leverages its biotechnology platform to engineer fermentation-derived antimicrobial peptides for clean-label positioning. Kemin Industries Inc anchors its portfolio in spearmint and oregano oil extracts, supplying major U.S. protein processors with GRAS-certified shelf-life solutions. Kerry Group competes through integrated taste-and-nutrition systems that bundle antimicrobial and antioxidant functionality into single ingredient platforms.
Food antimicrobials and antioxidants comprise functional additives that inhibit microbial spoilage and oxidative rancidity through mechanisms including free-radical scavenging, metal chelation, and cell-membrane disruption, typically dosed at 100-500 ppm depending on substrate fat content and water activity. Their primary commercial purpose centers on extending distribution reach for perishable foods while maintaining sensory and nutritional integrity under refrigerated or ambient supply chain conditions. Natural antioxidants occupy the fastest-expanding margin pool as brand owners reformulate away from petroleum-derived synthetics to meet retailer clean-label mandates. Synthetic antimicrobials retain volume dominance in commodity meat processing where cost-per-unit preservation remains the decisive procurement criterion. Shelf life extension applications command premium pricing relative to color retention, reflecting the direct linkage between microbiological stability and food safety liability exposure.
The FDA governs additive safety through the GRAS notification pathway and food additive petition process, while USDA-FSIS maintains jurisdiction over antimicrobial usage in inspected meat and poultry facilities, creating a dual-compliance architecture that elevates documentation burdens for cross-category suppliers. The EPA additionally regulates antimicrobial substances with pesticidal claims under FIFRA, adding a third regulatory layer for suppliers targeting surface-sanitizing applications in processing plants. Stakeholders must monitor the convergence of state-level clean-label legislation in California and New York with federal harmonization efforts, as divergent compliance requirements threaten to fragment formulation strategies across the region.
Market Dynamics
Clean-label mandates from major U.S. retailers are forcing reformulation across the processed meat value chain, compressing demand for synthetic preservatives while elevating plant-derived alternatives to default specification status.
Growth Catalysts
- USDA-FSIS regulatory convergence:Unified compliance standards for antimicrobial residues in inspected facilities reduce documentation redundancy for cross-border suppliers operating between U.S. and Canadian meat processing corridors.
- Great Plains protein cluster concentration:Dense aggregation of large-scale beef and poultry operations in Nebraska, Kansas, and Iowa creates localized demand density that justifies dedicated antioxidant blending facilities.
- Rosemary extract extraction technology:Supercritical CO2 extraction methods now yield carnosic acid concentrations exceeding 25%, matching synthetic BHT performance thresholds in lipid oxidation inhibition.
Market Restraints
- Natural extract input volatility:Weather-dependent rosemary and green tea harvests in California and Washington state create 15-40% raw material cost swings that synthetic suppliers do not face.
- Dual-jurisdiction compliance burden:Suppliers must simultaneously satisfy FDA GRAS notification requirements and USDA-FSIS antimicrobial usage protocols, doubling regulatory overhead relative to non-meat additive categories.
- Petroleum-derived synthetic lock-in:Commodity beef processors in Texas and Colorado maintain BHT and TBHQ contracts indexed to stable petrochemical feedstock pricing, delaying natural substitution timelines.
Strategic Opportunities
- California clean-label legislation:State-level mandates for simplified ingredient declarations on processed foods create first-mover advantage for GRAS-certified plant extract suppliers establishing West Coast formulation partnerships.
- Antimicrobial-antioxidant convergence:Single-ingredient platforms combining shelf-life extension with pathogen inhibition command 20-35% formulation premiums versus standalone additives in premium sausage and deli meat segments.
- Mexican export corridor expansion:USDA-FSIS equivalency agreements enabling U.S. meat exports to Mexican retail chains drive demand for label-friendly preservatives that satisfy both countries' import documentation requirements.
Industry Challenges
- GRAS self-determination expertise scarcity:Few formulation chemists possess simultaneous competency in toxicological data packages, FDA notification protocols, and sensory impact modeling required for clean-label antimicrobial development.
- Legacy synthetic infrastructure stranding:Petrochemical-derived antioxidant production assets in the Gulf Coast region face accelerated depreciation as brand owners accelerate natural reformulation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Food Antimicrobial and Antioxidants Market |
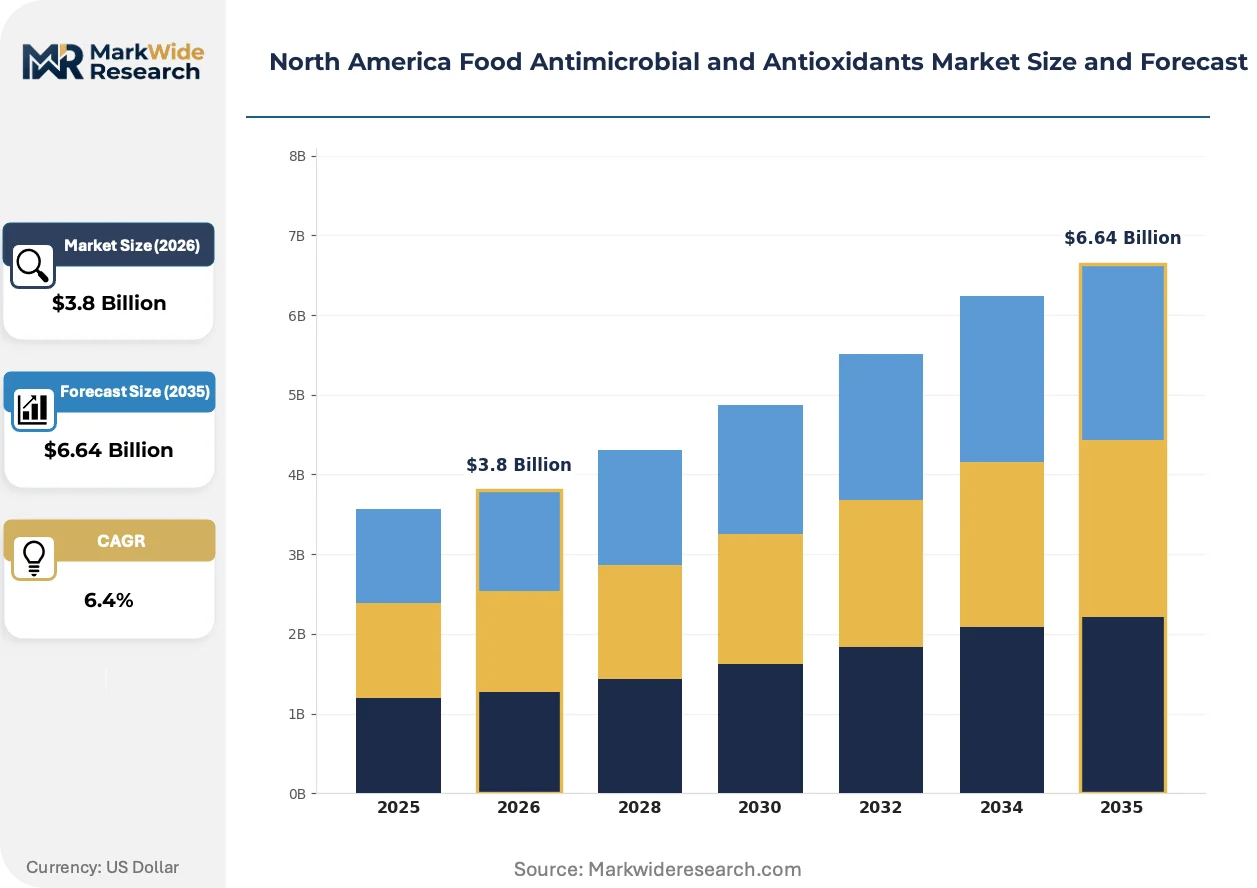
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Antimicrobials, Synthetic Antimicrobials, Natural Antioxidants, Synthetic Antioxidants End User: Food & Beverage Industry, Pharmaceuticals, Cosmetics, Animal Feed Application: Preservation, Flavor Enhancement, Color Retention, Shelf Life Extension Form: Liquid, Powder, Granular, Emulsified |
| Companies Covered | Archer Daniels Midland Company, Kalsec Inc, DuPont de Nemours Inc, International Flavors & Fragrances, Givaudan, Koninklijke DSM NV, Corbion NV, Kerry Group, Kemin Industries Inc, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Food Antimicrobial and Antioxidants Market Evolving Landscape
Biotechnology platforms are displacing traditional extraction methods as the primary innovation vector, with fermentation-derived peptides and enzymatic modification of plant matrices now competing directly with agricultural sourcing for cost and performance parity.
Fermentation-derived antimicrobial peptides are integrating into clean-label positioning strategies through precision biotechnology platforms that engineer bacteriocins with targeted activity against Listeria and Salmonella. Mid-sized U.S. poultry processors in the Southeast are adopting these solutions at pilot scale, with full specification integration expected within 24-36 months as unit economics achieve convergence with synthetic organic acid blends.
USDA-FSIS updated compliance guidelines for antimicrobial interventions in ready-to-eat meat products are compressing formulation windows for suppliers serving deli and hot dog segments. The directive tightens residual monitoring protocols and documentation requirements, forcing additive suppliers to invest in real-time analytical capabilities at customer processing sites or risk specification exclusion.
Retailer-driven procurement consolidation is concentrating buying power among three national grocery banners that now mandate clean-label shelf-life solutions as a condition of supplier qualification. This shift is displacing traditional distributor-mediated additive sales in favor of direct technical partnerships between extract suppliers and protein processor R&D functions, with the most visible impact in private-label processed meat programs across the Midwest and Northeast.
North America Food Antimicrobial and Antioxidants Market Segmentation
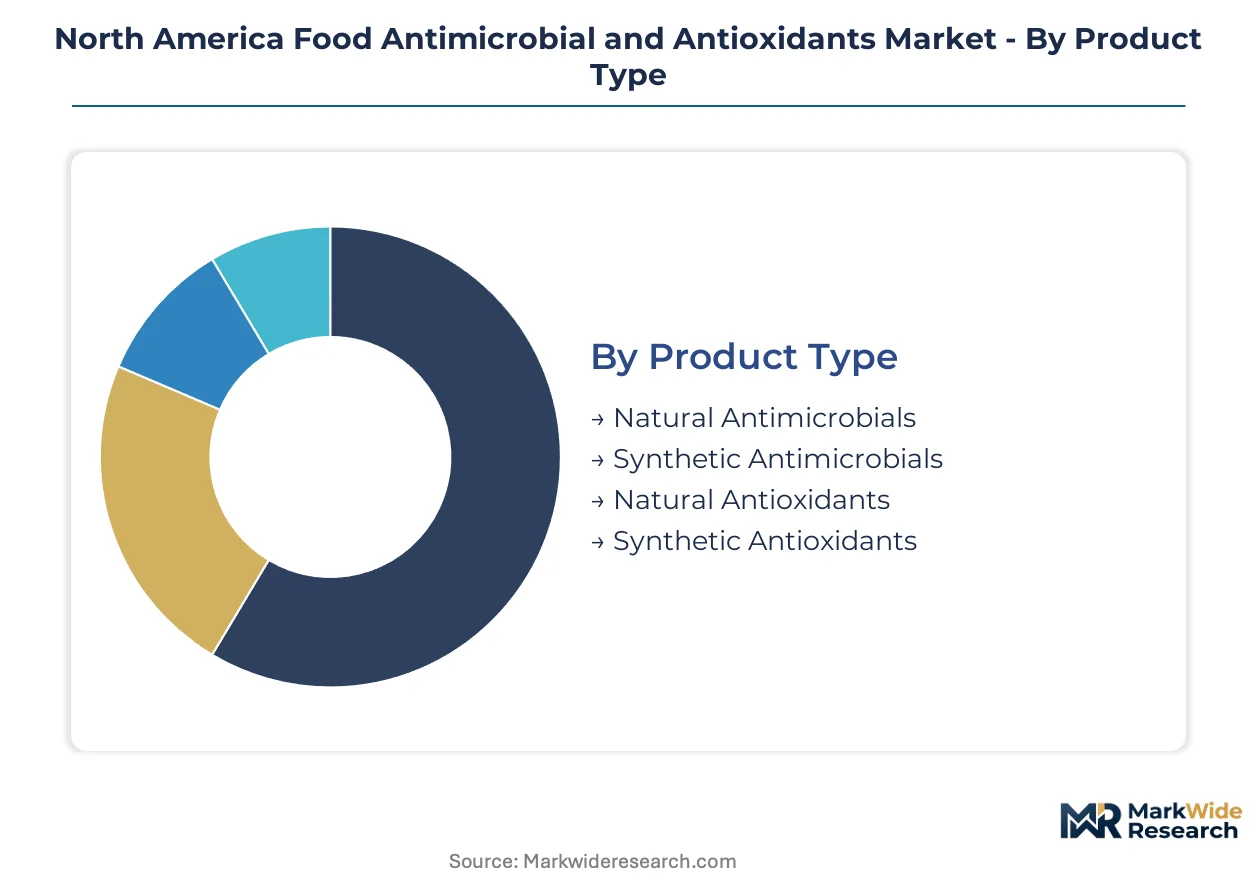
Procurement patterns in North American food antimicrobials and antioxidants diverge sharply across product origin, end-use specifications, and delivery formats. Each segmentation axis reveals distinct margin structures and technical requirements that reshape supplier positioning across the value chain.
Product Type:
Cost-per-unit preservation thresholds separate commodity buyers from clean-label adopters across this category.
- Natural Antimicrobials:Plant-derived extracts including rosemary, oregano, and green tea polyphenols inhibit Listeria and Salmonella through membrane disruption mechanisms. U.S. poultry processors in the Southeast are specifying these for private-label retail programs under Whole Foods and Kroger clean-label mandates.
- Synthetic Antimicrobials:Organic acid salts and benzoate derivatives dominate high-volume beef and pork processing in Nebraska and Kansas where cost-per-pound preservation drives procurement. USDA-FSIS documentation requirements for residual monitoring favor established synthetic suppliers with analytical infrastructure.
- Natural Antioxidants:Tocopherol concentrates and carnosic acid extracts from spearmint and rosemary displace petroleum-derived alternatives in premium sausage applications.
- Synthetic Antioxidants:BHT and TBHQ maintain specification lock-in at commodity beef processors across Texas and Colorado through petrochemical feedstock price stability.
Synthetic antimicrobials lead volumes today; natural antioxidants are gaining share fastest.
End User:
Application-specific regulatory pathways create divergent compliance burdens across buyer categories.
- Food & Beverage Industry:Meat and poultry processors account for concentrated demand, with large-scale facilities in Iowa and Arkansas requiring dual FDA-USDA compliance documentation. Clean-label reformulation timelines are compressing from 36 months to 18 months under retailer pressure.
- Pharmaceuticals:Excipient-grade antioxidants for softgel and tablet formulations require USP certification and batch-level residual testing that synthetic suppliers struggle to meet.
- Cosmetics:Topical antimicrobial preservatives face separate EPA FIFRA registration for surface-sanitizing claims, fragmenting supplier qualification requirements.
- Animal Feed:FDA Center for Veterinary Medicine oversight applies distinct safety thresholds for antioxidant stabilization of rendered fats and oilseed meals.
Food and beverage processors command the dominant volume position; pharmaceutical applications show the steepest margin expansion trajectory.
Application:
Functional priority determines pricing architecture across preservation outcomes.
- Preservation:Microbial inhibition systems targeting Clostridium and Listeria species carry premium positioning due to direct food safety liability exposure. USDA-FSIS intervention guidelines for ready-to-eat products tightened residual documentation requirements.
- Flavor Enhancement:Antioxidant systems that prevent lipid oxidation-derived off-flavors in frozen poultry are bundling with taste-masked organic acid delivery formats.
- Color Retention:Nitrite-alternative curing systems using celery powder and cherry powder extracts are displacing synthetic alternatives in natural-labeled deli meats.
- Shelf Life Extension:Combined antimicrobial-antioxidant platforms command formulation premiums in premium sausage and hot dog segments across the Midwest.
Shelf life extension applications generate the highest unit economics; color retention solutions are expanding most quickly through natural-labeled product launches.
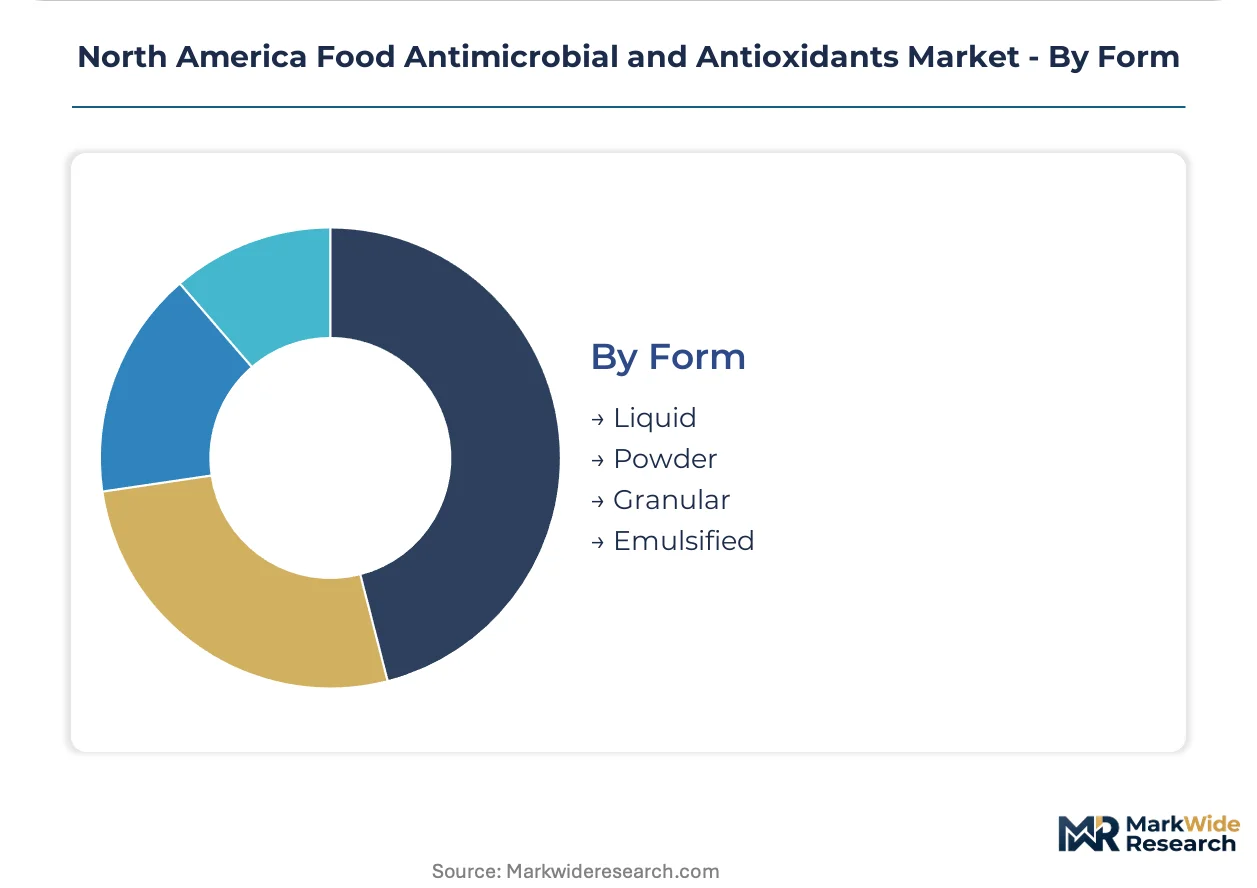
Form:
Processing equipment compatibility and dispersion requirements segment supply by delivery mechanism.
- Liquid:Acid-based antimicrobial blends integrate directly into brine injection systems at beef and pork processing facilities. Nebraska and Kansas protein clusters favor liquid delivery for high-throughput continuous processing lines.
- Powder:Dry antioxidant premixes for spice and seasoning blends require specialized milling to prevent segregation in low-moisture applications.
- Granular:Free-flowing carrier-based formats suit automated dispensing equipment at mid-sized poultry processors upgrading from manual batching.
- Emulsified:Oil-in-water delivery systems stabilize lipid-soluble antioxidants in high-fat emulsion products including sausages and pâtés.
Liquid forms dominate current procurement volumes; emulsified formats are climbing the fastest as clean-label sausage applications multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Great Plains protein processing corridor anchors North American demand for food antimicrobials and antioxidants, with Nebraska, Kansas, and Iowa hosting dense clusters of large-scale beef and poultry operations that drive localized procurement patterns. FDA and USDA-FSIS regulatory convergence is reshaping compliance requirements across the region, while state-level clean-label mandates in California and New York fragment formulation strategies.
United States
Great Plains beef and poultry processors in Nebraska, Kansas, and Iowa generate concentrated demand for dual-compliant antimicrobial systems. USDA-FSIS updated intervention guidelines for ready-to-eat products tighten residual documentation requirements, forcing additive suppliers to invest in real-time analytical capabilities. Southeast poultry processors in Arkansas and Georgia are adopting fermentation-derived antimicrobial peptides at pilot scale.
California
State-level clean-label legislation mandates simplified ingredient declarations on processed foods, creating first-mover advantage for GRAS-certified plant extract suppliers. Rosemary and green tea harvests in California's Central Valley supply raw material inputs, though weather-dependent yields create 15-40% cost volatility. West Coast formulation partnerships are emerging between extract suppliers and protein processor R&D functions.
Texas
Commodity beef processors in Texas maintain BHT and TBHQ contracts indexed to stable petrochemical feedstock pricing, delaying natural substitution timelines. FDA GRAS notification requirements apply to reformulation efforts, but procurement decisions prioritize cost-per-unit preservation. Gulf Coast synthetic antioxidant production assets face accelerated depreciation as brand owners accelerate natural reformulation timelines.
Canada
Cross-border meat processing corridors between Ontario and U.S. Midwest states benefit from unified USDA-FSIS compliance standards that reduce documentation redundancy. Health Canada and CFIA oversight of antimicrobial residues in inspected facilities aligns with U.S. protocols. Toronto-area protein processors are specifying clean-label shelf-life solutions for export to U.S. retail chains.
Mexico
USDA-FSIS equivalency agreements enabling U.S. meat exports to Mexican retail chains drive demand for label-friendly preservatives satisfying both countries' import documentation. NOM-243-SSA1-2010 food safety standards govern additive usage in domestic processing. Northern border states including Nuevo León are developing cold-chain infrastructure that extends distribution reach for perishable foods requiring antimicrobial protection.
North America Food Antimicrobial and Antioxidants Market Competitive Landscape
Global majors compete with regional champions across technology platforms and regulatory compliance capabilities, producing a tiered structure where biotechnology-enabled suppliers capture premium positioning while commodity synthetics defend volume. Three archetypes dominate: fermentation-derived peptide specialists, integrated taste-and-nutrition platforms, and agricultural extraction purists. Competitive moves concentrate on strategic partnerships with protein processor R&D functions and portfolio diversification into combined antimicrobial-antioxidant systems.
Among biotechnology-anchored players, DuPont de Nemours Inc exemplifies the precision fermentation archetype through engineered antimicrobial peptide development. Kemin Industries Inc and Kerry Group occupy positions within the plant-extract and integrated-systems tiers respectively, with Kemin anchoring spearmint and oregano oil supply relationships and Kerry bundling functionality into single-ingredient platforms. Archer Daniels Midland Company represents the agricultural commodity extraction archetype with scale advantages in tocopherol concentrates.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Kalsec Inc |
| DuPont de Nemours Inc |
| International Flavors & Fragrances |
| Givaudan |
| Koninklijke DSM NV |
| Corbion NV |
| Kerry Group |
| Kemin Industries Inc |
| Others |
Value Network & Pricing Analysis
California clean-label legislation gates both qualified supply and premium-tier pricing access by mandating GRAS-certified plant extracts for processed meat formulations, forcing suppliers to absorb certification costs or forfeit West Coast market entry. This regulatory filter compresses margins for non-compliant synthetics while concentrating pricing power among extract suppliers with established FDA notification pathways.
Pricing Analysis
Input-cost pass-through from weather-dependent rosemary and green tea harvests drives 15-40% raw material swings that synthetic suppliers avoid, forcing natural extract providers to index contracts to agricultural commodity futures. Three-tier pricing structure across premium, standard, and economy levels separates fermentation-derived peptides from CO2-extracted botanicals from commodity BHT. Pricing pressure stems from petroleum feedstock stability locking commodity beef processors into synthetic contracts. Mid-sized poultry processors in the Southeast show highest price sensitivity due to thin operating margins, while premium sausage makers absorb formulation premiums for clean-label positioning.
Supply Chain Analysis
Single-source vulnerability sits with California's Central Valley rosemary and Washington state green tea harvests, which supply raw material inputs for natural antioxidant production. The supply chain draws from agricultural extraction in the United States, fermentation biotechnology in Canada, and petrochemical synthesis in Texas and Louisiana. Tariff exposure on cross-border botanical imports from Canada creates compliance documentation burdens. Distribution runs through direct technical partnerships between extract suppliers and protein processor R&D functions, displacing traditional distributor-mediated sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where California's clean-label mandates command 20-35% formulation premiums versus Texas commodity processing corridors with synthetic lock-in.
For Market Incumbents: Deepen backward integration into rosemary and spearmint cultivation in California's Central Valley to secure input-cost stability against weather volatility. Fortify USDA-FSIS compliance documentation capabilities at customer processing sites to defend specification status against fermentation-derived peptide challengers. For New Entrants and Emerging Players: The price-point gap between premium fermentation peptides and economy synthetic organic acids creates entry space for mid-tier CO2-extracted botanicals. Target mid-sized poultry processors in Arkansas and Georgia upgrading from manual batching to automated dispensing. Lead with GRAS self-determination expertise as a bundled service to accelerate customer qualification timelines. For Investors and Strategic Acquirers: Valuations sit cheapest among agricultural extraction specialists with scale advantages in tocopherol concentrates but limited biotechnology capabilities. The five-to-ten year viability window favors suppliers with dual natural-synthetic portfolios capable of serving fragmented state-level mandates. Watch for USDA-FSIS equivalency agreement expansions with Mexican retail chains as inflection signal for cross-border formulation demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Botanical Cultivation | Captive rosemary supply in California's Central Valley insulates against 15-40% harvest volatility. |
| GRAS Certification Infrastructure Buildout | In-house toxicological data packages accelerate FDA notification timelines for clean-label customers. |
| Fermentation-Derived Peptide Scale-Up | Precision biotechnology platforms target Listeria and Salmonella with unit economics converging toward synthetics. |
| Direct Technical Partnership Model | Bypassing distributor channels captures retailer-driven procurement consolidation among national grocery banners. |
| Cross-Border Compliance Harmonization | Unified USDA-FSIS documentation serves U.S.-Canada meat processing corridors and Mexican export channels. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with protein processor R&D directors, GRAS notification consultants, USDA-FSIS compliance officers, and retail category buyers with secondary validation through FDA GRAS notice inventories, USDA-FSIS directive archives, and state-level clean-label legislation databases. Bottom-up volume modeling from individual facility specifications and top-down value estimation from disclosed procurement contracts were triangulated for convergence.
Segment-weighting across the analysis window applied product-type splits between natural and synthetic antimicrobials and antioxidants, end-user differentiation across meat processing and pharmaceutical excipient grades, application prioritization by preservation versus color retention functionality, and form-factor distribution between liquid injection systems and emulsified delivery. CAGRs were derived from facility expansion announcements and reformulation timeline disclosures across the projection horizon.
Caveats apply where California harvest volatility, USDA-FSIS intervention guideline revisions, or retailer mandate acceleration could materially shift the outlook. Forecasts reflect documented assumptions about regulatory convergence timelines and clean-label adoption rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Components and Additives
Germany Food Preservatives Market
Food Components and Additives
Polydextrose Market
Food Components and Additives
Europe Food Stabilizers Market
Food Components and Additives
North America Native Starch Market
Food Components and Additives
Europe Food Anti Caking Agents Market
Food Components and Additives
Food Coating Market
Food Components and Additives
Fructo-Oligosaccharides (FOS) Market
Food Components and Additives
Fractionated Fatty Acid Market
Food Components and Additives
North America Food Hydrocolloids Market
Food Components and Additives
Modified Wheat Starch Market
Food Components and Additives
Polyunsaturated Fatty Acids Market
Food Components and Additives
Food Antioxidant Market
Food Components and Additives
Food Grade Polyvinyl Acetate Market
Food Components and Additives
Germany Food Hydrocolloids Market
Food Components and Additives
US Food Hydrocolloids Market
Food Components and Additives
Linoleic Acid Market