
 Food Premix Market | 2026-2036
Food Premix Market Size, Share, and Industry Trends Forecast 2026-2036
Food Premix Market Analysis
Capital-intensity divergence between integrated nutrient producers and blenders is rotating competitive advantage toward backward-integrated players with fermentation and synthesis assets. DSM-Firmenich leverages captive vitamin B and omega-3 production to secure margin pools that toll-blenders cannot match. Glanbia PLC anchors its position through dairy-protein adjacencies and premix formulation for sports nutrition. Barentz International competes as a European distribution and formulation specialist with technical service capabilities across multiple nutrient categories.
Food premix denotes a homogeneous blend of vitamins, minerals, amino acids, nucleotides, and other functional micronutrients dosed at precise concentrations, typically manufactured via tumble blending or high-shear mixing to achieve coefficient of variation below five percent for uniform fortification. The primary purpose is to enable food and beverage manufacturers to achieve accurate, stable nutrient delivery without handling individual raw materials. Vitamin premixes occupy the largest value share given their use across bakery and dairy applications, while nutraceutical premixes are expanding fastest as beverage brands incorporate adaptogens and botanical actives. Mineral blends retain mature, price-competitive dynamics in mass-market flour and rice fortification programs.
The European Food Safety Authority (EFSA) and FDA govern maximum permitted levels and health claim substantiation, forcing reformulation cycles when novel nutrient forms seek approval. India's FSSAI and China's SAMR impose distinct label and purity standards that create separate specification burdens for exporters. REACH and EU Green Deal sustainability reporting requirements are beginning to penetrate supplier qualification criteria. Stakeholders must monitor evolving maximum level harmonization between Codex Alimentarius and national regulators to anticipate reformulation obligations and qualification barriers.
Market Dynamics
Reformulation pressure from clean-label mandates is compressing premix specification cycles as food manufacturers accelerate transitions from synthetic to fermentation-derived nutrient forms. This structural force is reshaping supplier qualification criteria and tightening backward integration requirements across vitamin-mineral blend supply chains.
Growth Catalysts
- EFSA Maximum Level Harmonization:The European Food Safety Authority's updated nutrient reference values are forcing standardization across multi-country product portfolios, reducing formulation complexity for exporters.
- Infant Nutrition Fortification:Dairy and formula manufacturers in India and sub-Saharan Africa are expanding micronutrient dosing to meet WHO complementary feeding guidelines.
- Fermentation-Derived Vitamins:Biotechnology advances in microbial B-vitamin production are lowering cost structures for label-compliant premix alternatives.
Market Restraints
- Vitamin B12 Supply Concentration:Captive fermentation capacity for cobalamin concentrates in China creates input vulnerability for non-integrated blenders.
- REACH Compliance Burden:EU chemical registration requirements for novel nutrient forms extend qualification timelines by 18-24 months.
- Mineral Price Volatility:Zinc and selenium compound costs fluctuate with mining output from concentrated South African and Peruvian deposits.
Strategic Opportunities
- Adaptogen-Infused Beverages:Sports nutrition and functional drink brands are requesting botanical-actives premixes combining ashwagandha with standard vitamin matrices.
- India FSSAI Micronutrient Mandates:Government rice and wheat fortification programs create institutional procurement volume for domestic premix manufacturers.
- Direct-to-Manufacturer Digital Channels:E-procurement platforms are enabling smaller food processors to access customized premix formulations without distributor markups.
Industry Challenges
- Formulation Chemist Scarcity:Technical expertise in micronutrient stability modeling and matrix interaction analysis remains concentrated among senior specialists at integrated producers.
- Legacy ERP Integration:Food manufacturers' existing inventory systems struggle to track lot-level nutrient potency degradation, complicating just-in-time premix ordering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Premix Market |
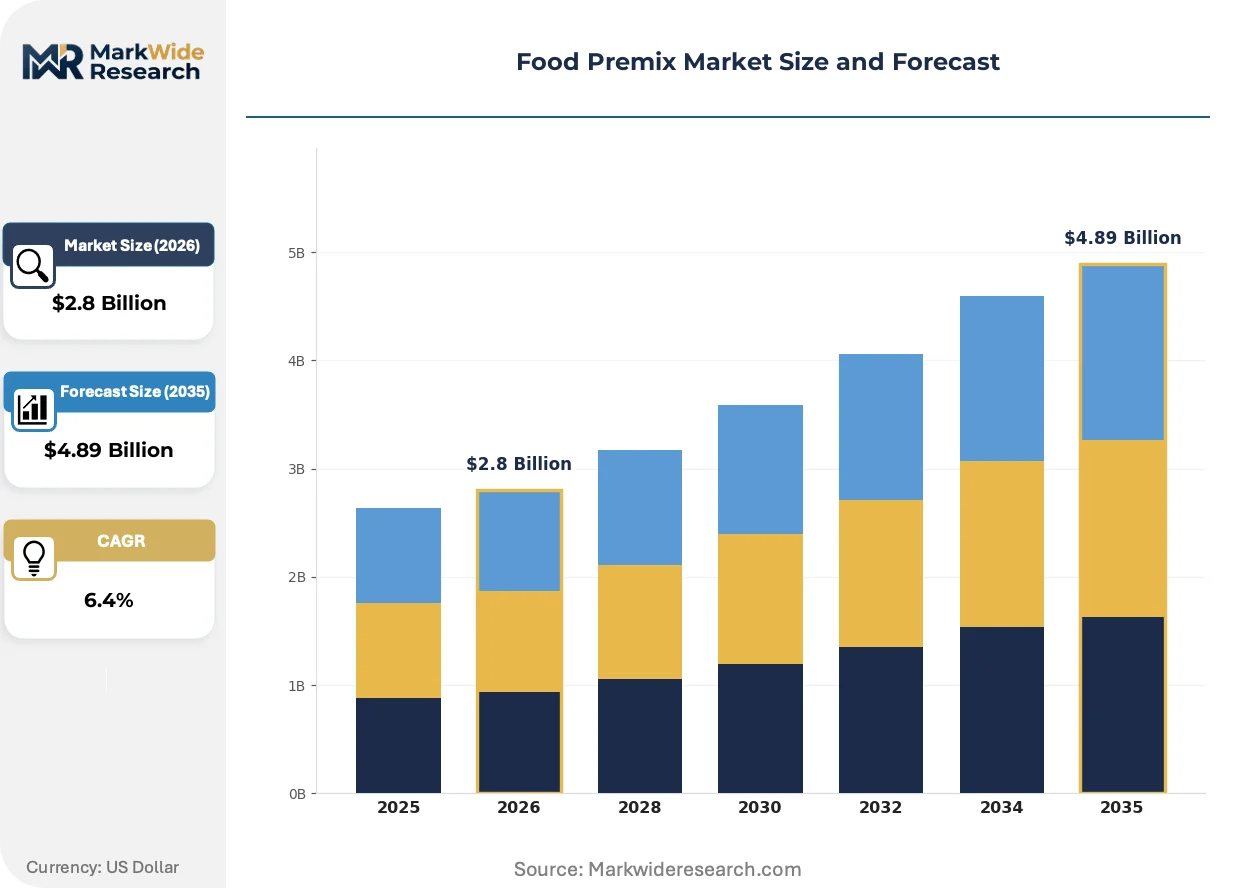
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Minerals, Nutraceuticals, Flavor Enhancers Application: Bakery, Beverages, Dairy, Meat Products End User: Food Manufacturers, Dietary Supplement Suppliers, Retailers, HoReCa Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesalers |
| Companies Covered | Corbion N.V., Archer-Daniels-Midland Company, DSM-Firmenich, Barentz International, BASF SE, Glanbia PLC, SternVitamin GmbH and Co. KG, Vitablend Nederland B.V., Prinova Group LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Premix Market Emerging Trajectories
Fermentation biotechnology and precision dosing hardware are converging to transform how micronutrients are synthesized, blended, and verified. These developments are compressing the gap between nutrient production and finished food integration.
Microencapsulation technology using lipid-shell matrices is supplanting standard spray-dried vitamin powders in heat-sensitive applications. Bakery and extruded snack manufacturers are adopting these forms at accelerating rates to reduce overage requirements. The shift is compressing margin structures for conventional powder suppliers while enabling precise nutrient retention through high-temperature processing.
The EU Green Deal's sustainability reporting requirements are penetrating supplier qualification protocols across Northern European food manufacturers. Downstream buyers now demand carbon footprint documentation for vitamin and mineral inputs. Premix blenders serving German and Dutch dairy processors are restructuring procurement to prioritize fermentation-derived over chemically synthesized nutrients.
Consolidated food manufacturers are unbundling premix specification from traditional distribution relationships. Direct technical partnerships with nutrient producers are replacing multi-tier procurement for large bakery and dairy groups. This pattern is most visible in North American and Western European markets where buyer concentration has reached thresholds justifying dedicated formulation support.
Food Premix Market Segmentation
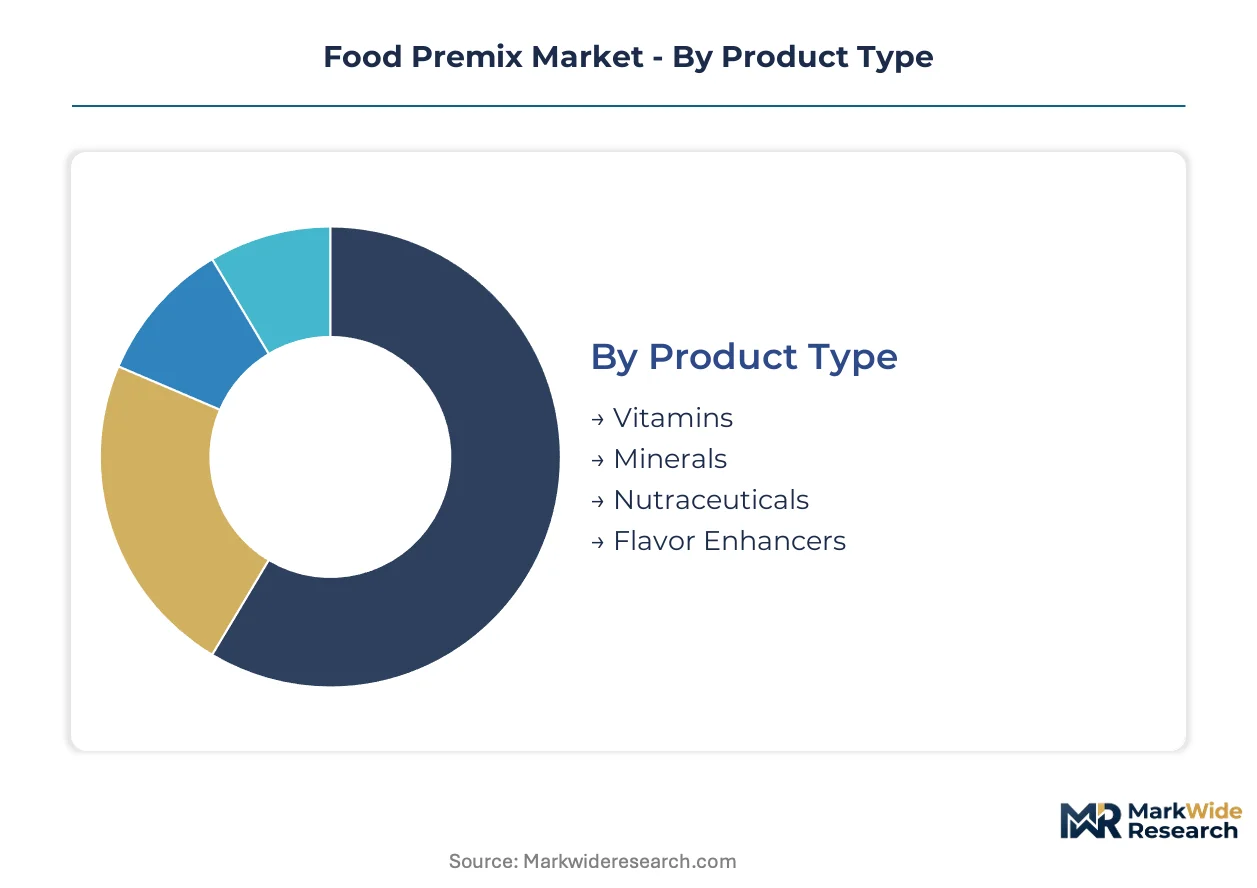
Food premix segmentation reveals distinct margin architectures across nutrient categories and application verticals. Manufacturers optimize procurement by matching premix specifications to processing conditions and regulatory requirements in target markets.
Product Type:
Premium capture concentrates in vitamin and nutraceutical premixes where formulation complexity and stability expertise create pricing power.
- Vitamins:Homogeneous blends of fat-soluble and water-soluble compounds requiring precise coefficient of variation below five percent. Demand concentrates in Indian bakery and African dairy fortification programs driven by government micronutrient mandates and WHO complementary feeding guidelines.
- Nutraceuticals:Functional matrices combining adaptogens, botanical actives, and bioactive peptides with standard vitamin bases. Sports nutrition brands in North America and Western Europe are accelerating procurement of ashwagandha-infused premixes for recovery-positioned beverages.
- Minerals:Zinc, iron, selenium, and calcium compounds for mass-market flour and rice fortification.
- Flavor Enhancers:Masking systems and taste modulators for high-potency nutrient delivery without sensory compromise.
The dominant share belongs to Vitamins, while Nutraceuticals is closing the gap fastest.
Application:
Volume scale differentiates this category, with dairy and bakery absorbing premix tonnage at divergent specification intensities.
- Dairy:Infant formula, fortified milk, and fermented products requiring heat-stable vitamin forms and microencapsulated mineral delivery. Indian dairy processors and sub-Saharan African manufacturers are expanding dosing to meet EFSA-aligned maximum level standards.
- Bakery:Vitamin D, folic acid, and B-complex fortification for bread and extruded snacks. German and Dutch manufacturers prioritize fermentation-derived nutrient forms to satisfy EU Green Deal sustainability reporting requirements.
- Beverages:Ready-to-drink functional drinks and sports nutrition liquids demanding cold-process stable premix formats.
- Meat Products:Iron and zinc fortification for processed meats with matrix-specific binding requirements.
Dairy commands the largest volume position, though Beverage applications are climbing the fastest as functional drink portfolios expand.
End User:
Procurement sophistication separates this category, with integrated manufacturers demanding technical partnership depth that fragmented buyers cannot leverage.
- Food Manufacturers:Consolidated bakery and dairy groups in North America and Western Europe are unbundling premix specification from distribution relationships, pursuing direct technical partnerships with nutrient producers for dedicated formulation support.
- Dietary Supplement Suppliers:Capsule, tablet, and powder brands requiring GMP-compliant premix documentation and lot-level potency verification.
- Retailers:Private-label food and supplement brands with standardized specification requirements and volume-tiered pricing.
- HoReCa:Foodservice operators with limited technical resources and distributor-dependent procurement patterns.
Food Manufacturers retain the deepest margin contribution, while Dietary Supplement Suppliers are gaining share fastest through nutraceutical portfolio expansion.
Distribution Channel:
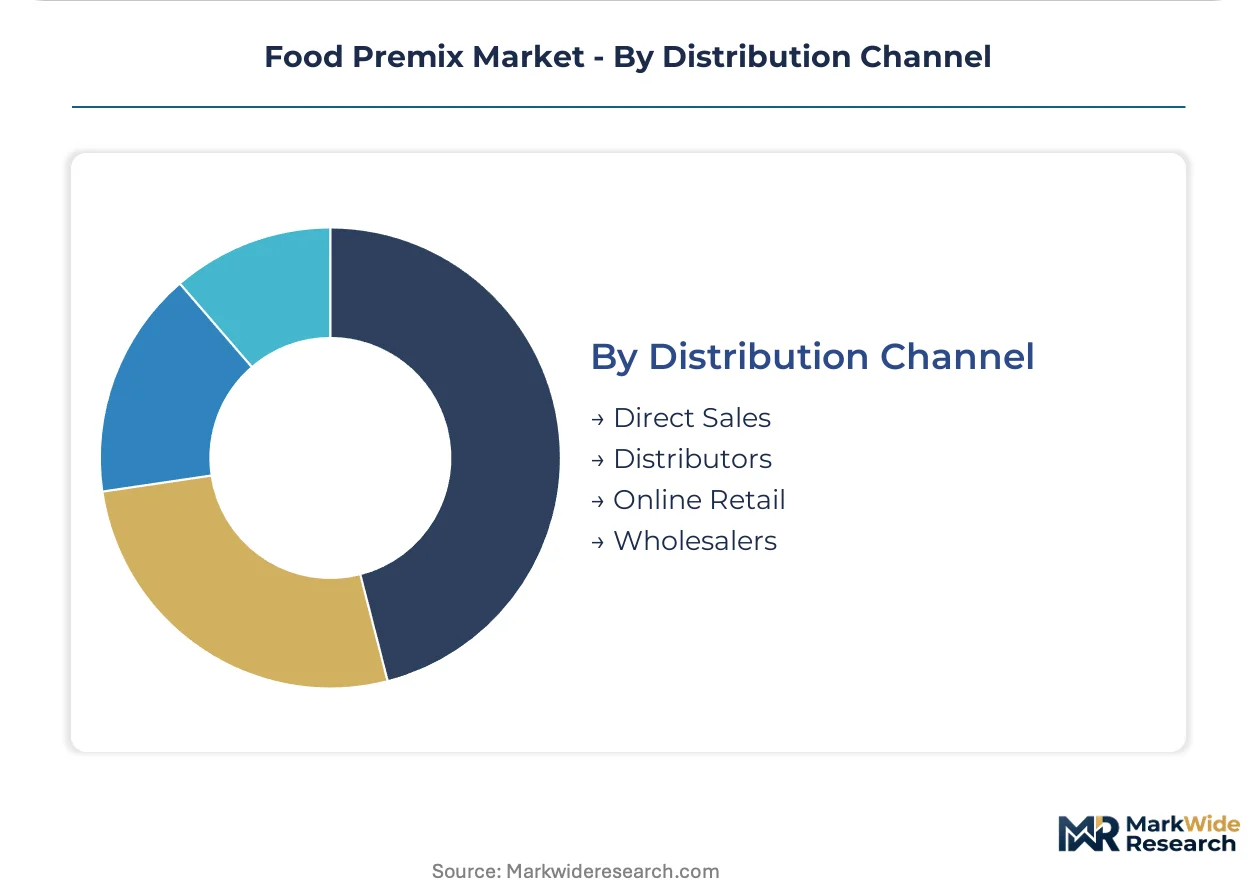
Channel selection determines qualification burden and working capital intensity for premix suppliers serving fragmented versus concentrated demand.
- Direct Sales:Technical partnership model for large-scale dairy and bakery groups requiring dedicated formulation chemists and stability modeling support. E-procurement platforms are enabling smaller food processors to access customized formulations without distributor markups.
- Distributors:Multi-tier relationships for mid-market manufacturers lacking in-house technical resources, with Barentz International and regional specialists providing formulation services across nutrient categories.
- Online Retail:Digital channels for small-batch supplement manufacturers and startup food brands with limited minimum order quantities.
- Wholesalers:Commodity mineral blends for government rice and wheat fortification programs with institutional procurement protocols.
Direct Sales generates the highest value per ton, while Online Retail is expanding most quickly as digital procurement platforms democratize technical access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. Indian buyers prioritize cost-efficient mineral blends for government fortification programs, while German and Dutch dairy processors absorb premium pricing for fermentation-derived nutrients meeting EU Green Deal sustainability criteria.
India
FSSAI mandates for rice and wheat fortification drive institutional procurement volumes. Government micronutrient programs distribute through state food departments. Dairy clusters in Gujarat and Maharashtra expand vitamin premix dosing for fortified milk powders targeting urban consumers.
Germany
REACH compliance requirements extend qualification timelines for novel nutrient forms. EFSA maximum level harmonization reduces multi-country formulation complexity for exporters. Dairy processors in Bavaria and North Rhine-Westphalia prioritize carbon footprint documentation for vitamin inputs.
United States
FDA substantiation requirements for health claims force reformulation cycles when novel nutrient forms seek approval. Sports nutrition brands accelerate procurement of adaptogen-infused premixes. Manufacturing concentration in Wisconsin and California supports direct technical partnerships between large food groups and nutrient producers.
China
SAMR label and purity standards create separate specification burdens for exporters targeting domestic versus export markets. Captive fermentation capacity for cobalamin concentrates in coastal provinces creates input cost advantages for integrated producers. Yangtze River Delta food manufacturers expand microencapsulated mineral procurement for heat-sensitive applications.
Brazil
ANVISA fortification regulations for wheat and corn flour sustain mineral blend demand. Price volatility in zinc and selenium compounds from Peruvian mining output affects formulation costs. São Paulo state processors lead adoption of vitamin premixes for fortified dairy beverages targeting Northeast regional markets.
Food Premix Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes. Backward-integrated producers with fermentation and synthesis assets capture margin pools unavailable to toll-blenders. The market structures around three strategic archetypes: integrated nutrient producers with captive vitamin B and omega-3 production, dairy-protein adjacent formulators, and distribution-specialists with technical service capabilities. M&A activity concentrates among fermentation asset acquisitions, while direct-to-manufacturer digital channels reshape procurement relationships.
Within the integrated production tier, DSM-Firmenich and BASF SE occupy positions anchored by synthesis and fermentation capabilities. Glanbia PLC exemplifies the dairy-protein adjacent archetype, leveraging nutritional expertise for sports nutrition premix formulation. Barentz International represents the European distribution and formulation specialist model with multi-nutrient technical services.
| Leading Market Players |
|---|
| Corbion N.V. |
| Archer-Daniels-Midland Company |
| DSM-Firmenich |
| Barentz International |
| BASF SE |
| Glanbia PLC |
| SternVitamin GmbH and Co. KG |
| Vitablend Nederland B.V. |
| Prinova Group LLC |
| Others |
Supply Flow & Price Mechanics
Fermentation asset utilization rates above 85 percent in Chinese vitamin B12 facilities establish cost floors that toll-blenders cannot undercut. This scale concentration compresses margin pools for non-integrated premix suppliers while enabling backward-integrated players to capture pricing power through captive cobalamin supply.
Pricing Analysis
Technical service contracts and stability modeling support drive lifetime value capture beyond commodity premix tonnage. Pricing stratifies across fermentation-derived premium tiers, standard synthetic vitamin matrices, and economy mineral blends for government fortification programs. Cost compression in standard vitamin premixes is intensifying as Indian and Chinese capacity expansions flood export markets. Government procurement offices in sub-Saharan Africa exhibit highest price sensitivity, while German dairy processors absorb premium positioning for EU Green Deal-compliant nutrient forms.
Supply Chain Analysis
Strait of Malacca transit routes underpin vitamin A and E concentrate flows from Southeast Asian palm oil derivatives to European blenders. Supply concentration in China, India, and the Netherlands shapes global premix availability, with Chinese fermentation capacity for B-vitamins and Indian mineral compound processing anchoring upstream tiers. Raw material dependencies span cobalt salts for B12 synthesis, selenium dioxide from Peruvian mining output, and palm-derived vitamin E precursors. Single-source vulnerability in Chinese cobalamin fermentation creates structural risk exposure. Distribution runs through direct technical partnerships for consolidated dairy groups and multi-tier distributor networks for mid-market bakery processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as clean-label reformulation splits demand between fermentation-derived and synthetic nutrient camps. Food manufacturers unbundling premix specification from traditional distribution relationships create white-space for specialized formulators.
For Market Incumbents: Fortify captive fermentation capacity in B-vitamin and omega-3 assets to defend margin pools against toll-blender competition. Expand technical service teams in India and Germany to capture government fortification program volumes and EU Green Deal sustainability reporting demand. Deepen direct partnerships with consolidated North American dairy groups before distributor relationships reconstitute.
For New Entrants and Emerging Players: FSSAI fast-track certification for rice and wheat fortification premixes unlocks institutional procurement channels in India's government micronutrient programs. Target microencapsulated mineral formulations for heat-sensitive bakery applications in Germany and the Netherlands. Pursue digital platform go-to-market models enabling small-batch customization without distributor markups.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors fermentation biotechnology specialists with commercial-scale microbial vitamin production. Long-term viability rests on backward integration depth rather than blending capacity alone. Acquisition target archetype: European premix formulators with established EFSA regulatory dossiers and sustainability documentation capabilities. Signal to watch: REACH registration timelines for novel nutrient forms crossing 24-month thresholds.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Assets | Captive vitamin B12 production secures margin pools unavailable to toll-blenders facing Chinese supply concentration. |
| Microencapsulation Technology Licensing | Lipid-shell matrix patents enable heat-stable premix positioning for bakery and extruded snack manufacturers. |
| Direct-to-Manufacturer Digital Platform Launch | E-procurement channels bypass distributor markups for mid-market food processors seeking customized formulations. |
| EU Green Deal Compliance Certification | Carbon footprint documentation unlocks premium positioning with German and Dutch dairy processor procurement panels. |
| Joint Venture with Indian Mineral Compound Processor | Local production partnerships capture FSSAI-mandated rice and wheat fortification program volumes. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with premix formulation chemists, dairy processor procurement directors, and FSSAI regulatory affairs specialists; and secondary validation against customs trade databases, EFSA maximum level determinations, and SEC filings from integrated nutrient producers. Bottom-up volume modeling triangulated against top-down market sizing across vitamin, mineral, and nutraceutical premix categories.
Across the analysis window, forecasts applied segmented growth rate derivation by product type, application vertical, and regional regulatory cluster. CAGRs were computed from annualized shipment data and capacity expansion announcements. Modeled inputs included fermentation capacity utilization rates, REACH registration timelines for novel nutrient forms, and government fortification program procurement volumes.
The analysis sits within stated boundaries; outcomes outside sustained EFSA-FSSAI regulatory harmonization progress would require recalibration. Forecasts reflect assumptions regarding mineral price volatility and biotechnology cost reduction curves. Revision becomes warranted when Chinese cobalamin supply concentration crosses threshold concentrations or EU Green Deal sustainability reporting mandates accelerate beyond current phase-in schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Components and Additives
Food Grade Alginate Market
Food Components and Additives
Polydextrose Market
Food Components and Additives
Japan Food Hydrocolloids Market
Food Components and Additives
Natural Antioxidants Market
Food Components and Additives
Food Grade Calcium Carbonate Market
Food Components and Additives
North America Native Starch Market
Food Components and Additives
Europe Food Hydrocolloids Market
Food Components and Additives
Canada Food Hydrocolloids Market
Food Components and Additives
Flavonoids Market
Food Components and Additives
Food Grade Iron Powder Market
Food Components and Additives
South America Food Hydrocolloids Market
Food Components and Additives
Inulin and Fructooligosaccharide Market
Food Components and Additives
Russia Food Hydrocolloids Market
Food Components and Additives
Food Grade Silica Market
Food Components and Additives
Soybean by-Products Market
Food Components and Additives
Fructo-Oligosaccharides (FOS) Market