
 Japan Food Hydrocolloids Market | 2026-2036
Japan Food Hydrocolloids Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Food Hydrocolloids Market Foresight
Japan is fragmenting its food hydrocolloids supply base as domestic processors diversify beyond traditional gelatin imports. Cargill Incorporated leverages its global agricultural network to secure consistent pectin supply for Japanese dairy clients. Ingredion anchors the starch-derived hydrocolloid segment with modified formulations tailored to local texture preferences. CP Kelco U.S., Inc specializes in microbial fermentation-based gellan gum, competing on clean-label positioning against conventional seaweed extracts.
Food hydrocolloids comprise high-molecular-weight biopolymers—polysaccharides and proteins—that hydrate in aqueous systems to form viscous solutions, gels, or stable emulsions through mechanisms including hydrogen bonding, ionic cross-linking, and entanglement; these functional properties enable precise control over mouthfeel, shelf stability, and water retention in processed foods. Gelatin maintains mature volume leadership in Japan's confectionery and dessert segments, though margin compression from raw material volatility constrains producer profitability. Agar commands premium positioning within traditional Japanese wagashi and modern plant-based formulations, where its thermo-reversible gelation and absence of animal origin support clean-label differentiation. Carrageenan competes aggressively in dairy applications, particularly ultrahigh-temperature processed beverages where protein stabilization at low dosage rates determines cost efficiency.
METI enforces food additive standards through the Food Sanitation Act, while the Consumer Affairs Agency mandates allergen labeling that shapes hydrocolloid selection for manufacturers targeting sensitive consumer segments. JIS standards for food-grade biopolymers establish quality benchmarks that importers must satisfy for customs clearance and commercial distribution. Stakeholders must monitor evolving plant-based certification protocols and regional sourcing requirements as Japanese food processors recalibrate supply chains toward domestic and Asia-Pacific hydrocolloid origins.
Market Dynamics
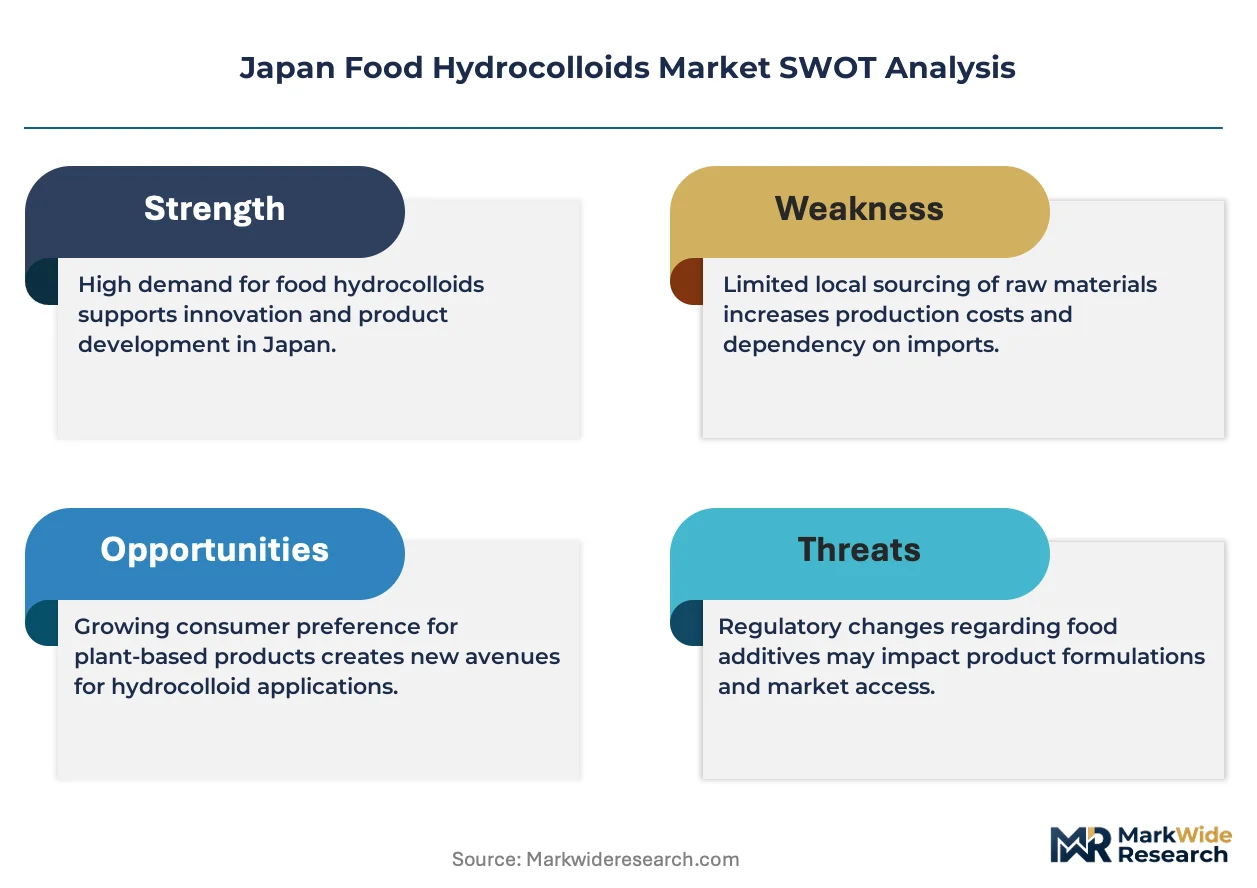
Japanese food hydrocolloids procurement is fragmenting as domestic processors recalibrate supply chains away from traditional gelatin imports toward plant-based alternatives, driven by METI's sustainable food system mandates and clean-label consumer preferences in Tokyo's dense food processing cluster.
Growth Catalysts
- Clean-label dairy expansion:Japanese manufacturers are reformulating yogurt and plant-based milk with agar and gellan gum to replace synthetic stabilizers, responding to Consumer Affairs Agency allergen labeling requirements.
- METI's sustainable sourcing mandate:The ministry's push for domestic plant-based hydrocolloid cultivation is accelerating konjac and tara gum production in Hokkaido and Kyushu agricultural zones.
- Wagashi modernization:Traditional confectionery producers are scaling thermo-reversible agar applications for premium export markets, leveraging Japan's existing seaweed processing infrastructure.
Market Restraints
- Seaweed supply volatility:Agar and carrageenan raw material costs fluctuate with warming-induced harvest variability in Pacific coastal regions, compressing processor margins.
- Import dependency for pectin:Citrus-derived pectin supply concentrates in Mediterranean and Latin American growing regions, exposing Japanese dairy formulators to currency and logistics risk.
- Gelatin substitution ceiling:Animal-derived gelatin retains functional advantages in aerated confectionery and pharmaceutical capsules that plant-based alternatives cannot replicate at equivalent dosage efficiency.
Strategic Opportunities
- Kansai region penetration:Osaka-Kobe food processing corridors remain underdeveloped for microbial fermentation hydrocolloids, offering first-mover positioning for gellan gum suppliers.
- Cell-cultured meat scaffolding:Emerging Japanese cultivated protein startups require novel hydrocolloid matrices for texture engineering, creating demand outside traditional food applications.
- JIS certification harmonization:Alignment of domestic biopolymer quality standards with ASEAN food-grade protocols would unlock export pathways for Japanese hydrocolloid processors into Southeast Asian markets.
Industry Challenges
- Clean-label formulation expertise gap:Japanese food technologists trained in synthetic additive systems lack practical experience with plant-based hydrocolloid synergies and hydration kinetics.
- Dual certification timelines:Simultaneous compliance with Food Sanitation Act additive approvals and JIS quality benchmarks extends product launch cycles by 8-14 months for new hydrocolloid entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Food Hydrocolloids Market |
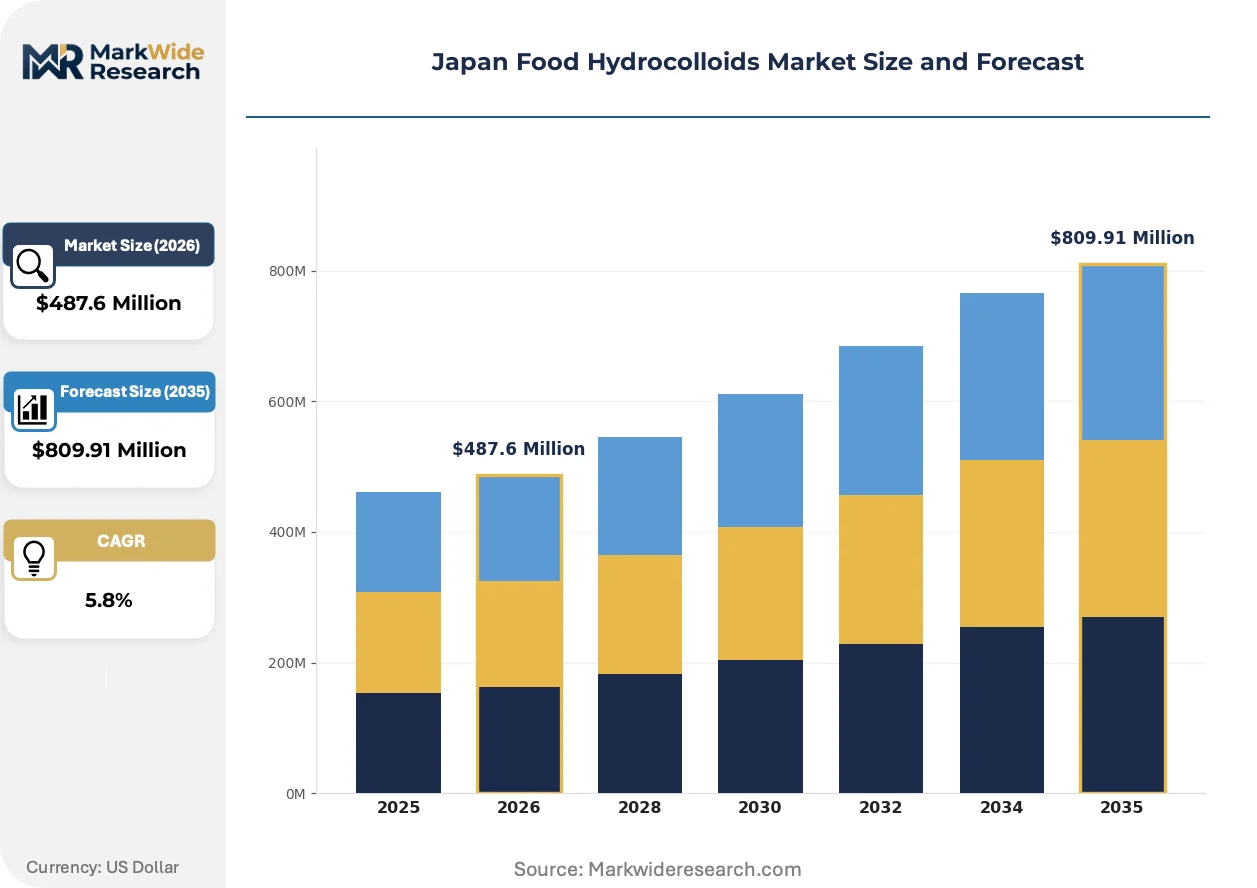
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $809.91 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gelatin, Pectin, Agar, Carrageenan Application: Dairy Products, Bakery Goods, Sauces, Beverages End User: Food Manufacturers, Restaurants, Retail Chains, Caterers Form: Powder, Granular, Liquid, Sheet |
| Companies Covered | DuPont, Ingredion, Cargill Incorporated, Behn Meyer, Darling Ingredients Inc, Ashland, CP Kelco U.S., Inc, Archer Daniels Midland Company, Koninklijke DSM N.V., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Food Hydrocolloids Market Shifts & Advancements
Japan's food hydrocolloids sector is pivoting toward precision fermentation and enzymatic modification techniques that deliver functional equivalence at lower dosage rates, while regulatory pressure and procurement model evolution reshape competitive positioning.
Precision fermentation-derived gellan gum is rendering obsolete traditional kelp-extracted alginate in UHT dairy stabilization. Major Japanese beverage manufacturers are adopting low-acyl gellan variants for protein suspension at one-third the conventional dosage. This transition compresses input costs while satisfying METI's domestic biotechnology promotion targets.
METI's Food Sanitation Act enforcement is tightening additive purity thresholds for microbial polysaccharides. The revised standards mandate reduced endotoxin limits in fermentation-derived hydrocolloids, forcing domestic producers to upgrade filtration infrastructure. Dairy and plant-based beverage segments are absorbing compliance costs through reformulation rather than supplier switching.
Tokyo-based food processors are consolidating hydrocolloid procurement through direct partnerships with Hokkaido agricultural cooperatives, bypassing traditional trading house intermediaries. This channel disintermediation concentrates volume commitments with domestic konjac and tara gum suppliers, reducing exposure to import logistics volatility while shortening lead times for Kanto region manufacturing facilities.
Japan Food Hydrocolloids Market Segmentation
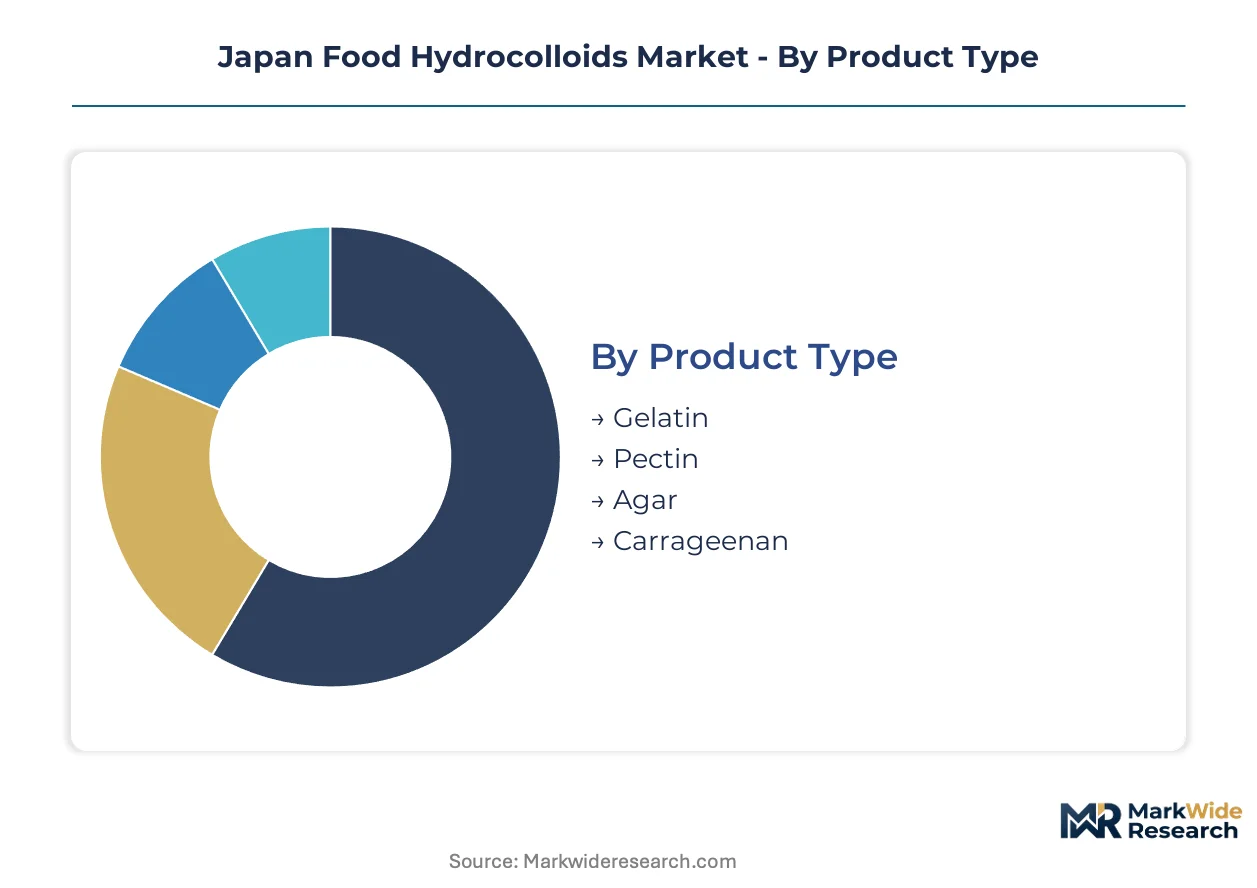
Segmentation reveals how METI's sustainable sourcing mandates and Tokyo's clean-label dairy reformulation are redistributing demand across hydrocolloid types and procurement channels. Manufacturers navigate JIS quality benchmarks while recalibrating supply chains toward plant-based alternatives.
Product Type:
Cost tier determines procurement strategy as animal-derived hydrocolloids face margin pressure from raw material volatility while plant-based alternatives command premium positioning.
- Gelatin:Collagen-derived protein hydrocolloid extracted through acid or alkaline processing of bovine and porcine tissues. Tokyo's confectionery manufacturers rely on gelatin for aerated desserts and pharmaceutical capsules where thermo-irreversible gelation and foam stability prove irreplaceable despite clean-label headwinds.
- Agar:Seaweed-extracted polysaccharide blend of agarose and agaropectin forming thermo-reversible gels with superior clarity. Wagashi producers in Kanto and Kansai leverage agar for traditional and export-oriented premium confections, though warming-induced Pacific harvest variability constrains supply security.
- Pectin:Citrus peel and apple pomace-derived galacturonic acid polymer requiring amidation for low-sugar applications. Japanese dairy formulators depend on Mediterranean and Latin American citrus supply chains, exposing procurement to currency fluctuation and maritime logistics disruption.
- Carrageenan:Sulfated galactan extracted from red algae species Kappaphycus and Eucheuma. UHT beverage processors in Osaka-Kobe corridors favor carrageenan for protein stabilization at sub-0.05% dosage rates, optimizing cost efficiency in high-volume production.
Gelatin holds installed capacity in mature confectionery applications. Agar is rotating up the share rankings as wagashi modernization accelerates.
Application:
Volume concentration follows Japan's dairy processing cluster density, with Kanto region facilities driving bulk procurement of stabilizing and gelling agents.
- Dairy Products:Yogurt, plant-based milk alternatives, and processed cheese requiring protein suspension and syneresis control. METI's clean-label mandates are pushing Tokyo manufacturers toward agar-gellan gum blends replacing synthetic stabilizers in drinkable yogurt segments.
- Beverages:UHT-processed milk drinks, fruit juices, and functional beverages demanding long-term suspension stability. Low-acyl gellan gum variants are displacing traditional alginate in Japanese beverage manufacturing, achieving equivalent protein suspension at one-third conventional dosage.
- Bakery Goods:Bread improvers, cake glazes, and cream fillings utilizing hydrocolloids for moisture retention and shelf-life extension. Hokkaido wheat processors integrate domestic konjac flour for gluten-free formulations targeting allergen-sensitive consumer segments.
- Sauces:Dressings, condiments, and prepared sauces requiring viscosity modification and emulsion stability. Kansai-based food service manufacturers favor xanthan-guar synergies for cold-process mayonnaise alternatives.
Dairy Products holds installed capacity. Beverages is expanding most quickly as precision fermentation hydrocolloids penetrate UHT stabilization.
End User:
Customer type dictates procurement sophistication, with large-scale manufacturers leveraging direct agricultural cooperative partnerships while food service operators depend on distributor intermediaries.
- Food Manufacturers:Industrial-scale processors of packaged foods and beverages with in-house formulation laboratories. Tokyo's dense food processing cluster is consolidating hydrocolloid procurement through direct Hokkaido konjac cooperative agreements, bypassing traditional trading house channels.
- Retail Chains:Private-label product developers and ready-meal suppliers requiring standardized ingredient specifications. Major Japanese convenience store operators are mandating clean-label hydrocolloid declarations for house-brand dessert and beverage lines.
- Restaurants:Independent and chain food service operators utilizing hydrocolloids for texture-modified menu items. Osaka's fine-dining sector experiments with agar and gellan gum for molecular gastronomy applications.
- Caterers:Institutional and event food service providers requiring bulk hydrocolloid supply for large-batch preparation. Hotel banquet operations in Kyushu source sheet-form agar for traditional dessert presentations.
Food Manufacturers holds installed capacity. Retail Chains is gaining share fastest as private-label clean-label reformulation accelerates.
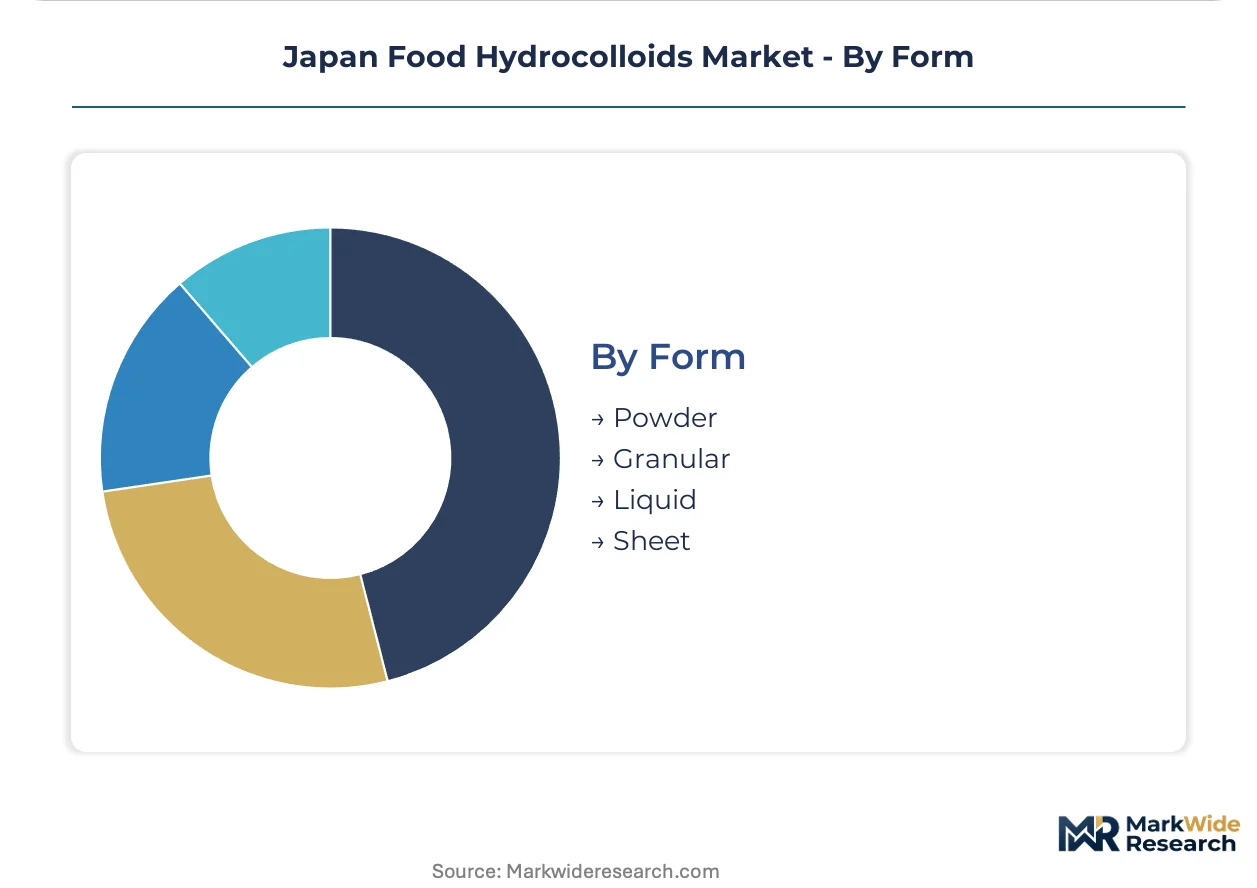
Form:
Supply concentration varies by processing infrastructure, with powder and liquid forms dominating industrial procurement while sheet and granular formats serve traditional applications.
- Powder:Spray-dried or milled hydrocolloid requiring hydration protocols for activation. Japanese dairy and beverage manufacturers standardize on powder formats for automated dosing systems and extended ambient storage stability.
- Liquid:Pre-hydrated colloidal dispersions eliminating dissolution time and dust exposure. Emerging cultivated meat startups in Tokyo require liquid gellan gum for sterile matrix preparation in cell scaffolding applications.
- Granular:Coarse-particle agar and gelatin for controlled hydration kinetics. Traditional wagashi artisans in Kyoto prefer granular agar for manual temperature-controlled gelation.
- Sheet:Pre-cast agar strips for direct portioning without weighing equipment. Japanese commercial caterers and institutional kitchens utilize sheet agar for consistent batch preparation of traditional desserts.
Powder holds installed capacity. Liquid is climbing the fastest as biotechnology applications emerge beyond conventional food processing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
METI's sustainable food system mandates and clean-label dairy reformulation are redistributing hydrocolloid demand across Japan's industrial geography. Regional procurement patterns reflect proximity to agricultural cooperatives, seaweed processing infrastructure, and fermentation biotechnology clusters.
Kanto/Tokyo
Tokyo's dense food processing corridor drives bulk procurement of gelling and stabilizing agents for yogurt and plant-based milk reformulation. METI's Food Sanitation Act enforcement tightens additive purity thresholds for microbial polysaccharides used in UHT beverages. Major beverage manufacturers in Saitama and Kanagawa prefectures are adopting precision fermentation-derived gellan gum at reduced dosage rates.
Kansai/Osaka
Osaka-Kobe food processing corridors remain underdeveloped for microbial fermentation hydrocolloids, creating first-mover positioning opportunities. The Consumer Affairs Agency's allergen labeling requirements shape hydrocolloid selection for manufacturers targeting sensitive consumer segments in this region. UHT beverage processors in Osaka prefecture favor carrageenan for protein stabilization at sub-0.05% dosage rates in high-volume production.
Hokkaido
Domestic konjac and tara gum cultivation is accelerating in Hokkaido's agricultural zones under METI's sustainable sourcing mandate. Tokyo-based food processors are consolidating procurement through direct partnerships with Hokkaido agricultural cooperatives, bypassing traditional trading house intermediaries. This channel disintermediation concentrates volume commitments with domestic suppliers, reducing exposure to import logistics volatility.
Kyushu
Seaweed processing infrastructure in Kyushu supports agar production for traditional wagashi and modern plant-based formulations. Warming-induced harvest variability in Pacific coastal regions constrains supply security for agar and carrageenan raw materials. Hotel banquet operations in Fukuoka source sheet-form agar for traditional dessert presentations, sustaining regional specialty applications.
Chubu/Nagoya
Nagoya's industrial base supports modified starch and starch-derived hydrocolloid processing for bakery and sauce applications. JIS standards for food-grade biopolymers establish quality benchmarks that regional processors must satisfy for commercial distribution. Hokkaido wheat processors supply konjac flour to Chubu-based gluten-free formulation facilities targeting allergen-sensitive consumer segments.
Japan Food Hydrocolloids Market Competitive Landscape
Capability concentration sits with biotechnology specialists mastering precision fermentation; scale advantage sits with diversified agricultural processors controlling global supply chains. The market structures around three tiers: multinational ingredient conglomerates with integrated agricultural networks, regional specialists in seaweed extraction and plant-based hydrocolloids, and domestic biotechnology firms commercializing microbial fermentation platforms. Competitive moves center on backward integration into raw material sourcing and strategic partnerships with Hokkaido agricultural cooperatives to secure domestic supply commitments.
Within the multinational tier, Cargill Incorporated and Ingredion exemplify scale-driven positioning through global agricultural networks and starch-derived hydrocolloid portfolios. CP Kelco U.S., Inc occupies a specialist position in microbial fermentation-based gellan gum, competing on clean-label differentiation against conventional seaweed extracts. These three companies represent contrasting archetypes: agricultural commodity leverage, modified starch formulation expertise, and biotechnology platform specialization respectively.
| Leading Market Players |
|---|
| DuPont |
| Ingredion |
| Cargill Incorporated |
| Behn Meyer |
| Darling Ingredients Inc |
| Ashland |
| CP Kelco U.S., Inc |
| Archer Daniels Midland Company |
| Koninklijke DSM N.V. |
| Others |
Supply & Pricing Matrix
Import dependency for citrus-derived pectin determines both the premium commanded by domestic konjac alternatives and the elongated supply chains Japanese dairy formulators must navigate. METI's sustainable sourcing mandates and Pacific seaweed harvest variability compress margins across animal-derived and plant-based hydrocolloid tiers simultaneously.
Pricing Analysis
Geographic price spreads widen between Mediterranean-imported pectin and Hokkaido-sourced konjac, with the latter capturing premium positioning through shortened lead times. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade under JIS standards and volume commitment scale. Cost compression in standard-tier carrageenan is intensifying because warming-induced Pacific harvest variability constrains supply security. Retail chains exhibit highest price sensitivity due to private-label margin pressure, while cultivated meat startups show lowest sensitivity given sterile matrix requirements.
Supply Chain Analysis
Upstream feedstock for agar and carrageenan draws from Pacific coastal seaweed harvesting zones in Kyushu and Shikoku, while pectin rests on citrus cultivation in Spain, Italy, and Mexico. Raw material dependencies center on red algae species Kappaphycus and Eucheuma, citrus peel galacturonic acid polymers, and microbial fermentation substrates for gellan gum. Single-source vulnerability concentrates in Mediterranean pectin supply, exposing Japanese formulators to currency fluctuation and maritime logistics disruption. Distribution runs through direct partnerships with Hokkaido agricultural cooperatives, bypassing traditional Tokyo trading house intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Practical expertise in plant-based hydrocolloid synergies and hydration kinetics remains scarce among Japanese food technologists trained in synthetic additive systems, creating competitive moats for biotechnology specialists and agricultural cooperatives with in-house formulation capabilities.
For Market Incumbents: Entrench position through backward integration into Hokkaido konjac cultivation and tara gum processing, securing captive supply against import logistics volatility. Invest in precision fermentation capacity expansion to meet METI's reduced endotoxin thresholds for microbial polysaccharides, converting regulatory compliance burden into clean-label differentiation against seaweed-extracted competitors. For New Entrants and Emerging Players: Pursue white-space positioning in Osaka-Kobe microbial fermentation hydrocolloids, where beverage processors remain dependent on carrageenan for UHT protein stabilization. Target cultivated meat scaffolding applications in Tokyo, where sterile liquid gellan gum requirements outpace domestic biotechnology supply. Establish direct Hokkaido cooperative partnerships to bypass entrenched trading house channels. For Investors and Strategic Acquirers: METI's Food Sanitation Act revisions reshaping the acquisition landscape toward domestic biotechnology platforms with upgraded filtration infrastructure. Long-term viability favors precision fermentation specialists over seaweed extraction assets given warming-induced harvest variability. Monitor JIS-ASEAN harmonization negotiations as signal for Southeast Asian export pathway unlock.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hokkaido Cultivation | Captive konjac supply reduces exposure to Mediterranean pectin currency fluctuation. |
| Precision Fermentation Capacity Expansion | Low-acyl gellan gum production meets METI endotoxin thresholds at reduced dosage rates. |
| Direct Cooperative Partnership Agreements | Channel disintermediation shortens lead times for Kanto region dairy manufacturers. |
| JIS Certification Harmonization Investment | ASEAN alignment unlocks export pathways for domestic hydrocolloid processors. |
| Cultivated Meat Scaffolding R&D Partnership | Tokyo cell-protein startups require novel sterile matrix preparation capabilities. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of METI regulatory filings, JIS standards documentation, and Food Sanitation Act enforcement records. Interviews with food formulation technologists at Kanto dairy processors, procurement leads at Hokkaido agricultural cooperatives, and regulatory affairs specialists at microbial fermentation facilities informed demand-side and supply-side validation. Customs trade data, biotechnology platform disclosures, and seaweed harvest reports provided secondary triangulation. Bottom-up segmentation modeling and top-down macroeconomic calibration ensured cross-verification.
Forecast inputs include hydrocolloid type substitution rates, METI sustainable sourcing mandate implementation pace, and regional procurement channel evolution across the analysis window. Segmentation dimensions encompass product type, application, end user, and form, with additional modeling of JIS certification tier and domestic versus import sourcing origin. CAGRs derive from volume trajectory analysis adjusted for regulatory inflection points and raw material supply constraints. Industry-specific inputs incorporate Pacific coastal temperature anomaly projections and Hokkaido agricultural cooperative expansion timelines.
Sensitivities concentrate around warming-induced seaweed harvest variability, citrus pectin supply disruption, and METI endotoxin threshold enforcement timing. Forecasts reflect documented assumptions regarding biotechnology platform adoption rates and cooperative partnership consolidation. Cross-checking against Japan Food Chemical Research Foundation production statistics and MAFF agricultural output reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Components and Additives
Brazil Food Hydrocolloids Market
Food Components and Additives
Food Antimicrobial and Antioxidants Market
Food Components and Additives
Blackcurrant Powder Market
Food Components and Additives
Polyunsaturated Fatty Acids Market
Food Components and Additives
Australia Food Hydrocolloids Market
Food Components and Additives
Linoleic Acid Market
Food Components and Additives
Global Food Carbohydrase Market
Food Components and Additives
USA Food Premix Market
Food Components and Additives
Soybean by-Products Market
Food Components and Additives
Polyphenols Market
Food Components and Additives
Canada Food Hydrocolloids Market
Food Components and Additives
Food Texture Market
Food Components and Additives
Isoflavones Market
Food Components and Additives
Fermentation Defoamer Market
Food Components and Additives
North America Food Antimicrobial and Antioxidants Market
Food Components and Additives
Food Grade Xanthan Gum Market