
 Engine Oil Pan Market | 2026-2036
Engine Oil Pan Market Size, Share, and Industry Trends Forecast 2026-2036
Engine Oil Pan Market Analysis
Aftermarket distribution channels are rewriting procurement relationships between Tier-1 suppliers and independent service networks. Mann+Hummel leverages its filtration and fluid management portfolio to anchor long-term supply contracts with European vehicle assemblers. Dana Incorporated competes through integrated thermal management expertise that extends its reach beyond passive oil containment into active system design. Pacific Industrial specializes in stamped metal forming for Japanese OEMs, sustaining manufacturing scale advantages in high-volume compact vehicle programs.
An engine oil pan is a stamped, cast, or molded reservoir mounted beneath the internal combustion engine block, typically fabricated from aluminum alloy, stamped steel, or fiber-reinforced polymer composites with wall thicknesses ranging from 1.5 mm to 4.0 mm depending on material and duty cycle, designed to store engine lubricant, dissipate thermal energy, and house the oil pickup tube and drain port. Aluminum product types now lead value generation as automakers pursue mass reduction targets, while composite segments represent the fastest-growing material category driven by electric-hybrid powertrain packaging constraints. Standard size configurations remain the mature volume base, though heavy-duty variants command superior margin pools in commercial vehicle applications where thermal cycling durability requirements escalate.
The EPA Corporate Average Fuel Economy standards and EU REACH chemical compliance frameworks shape material selection protocols, forcing suppliers to validate alternative substrates against recyclability and emissions thresholds. NHTSA crashworthiness regulations additionally dictate structural integration requirements for oil pan mounting interfaces in light-duty truck platforms. Stakeholders must monitor evolving powertrain electrification roadmaps to calibrate capacity allocation between traditional internal combustion architectures and emerging hybrid-electric configurations where oil pan geometries and thermal loads diverge materially.
Market Dynamics
Material substitution mandates are compressing traditional steel oil pan architectures as EPA Corporate Average Fuel Economy standards and EU F-Gas Regulation force automakers to validate aluminum and composite substrates against thermal cycling and recyclability thresholds.
Growth Catalysts
- EU F-Gas Regulation:The framework accelerates displacement of steel oil pans by mandating material efficiency in automotive thermal systems, compelling Tier-1 suppliers to retool stamping lines for aluminum alloy forming.
- Hybrid-electric powertrain packaging:Electric-hybrid architectures demand compact, thermally efficient oil containment solutions that composite materials uniquely satisfy through geometric design freedom.
- Germany-Japan-US manufacturing clusters:Concentrated powertrain production in Stuttgart, Aichi Prefecture, and Detroit anchors supplier investment in localized aluminum casting and composite molding capacity.
Market Restraints
- Aluminum alloy price volatility:Primary aluminum input costs fluctuate with energy pricing, compressing margin stability for stamped and cast oil pan producers locked into annual supply agreements.
- Steel supplier concentration:Legacy high-strength steel substrate supply concentrates among a limited set of European and East Asian mills, creating vulnerability for manufacturers maintaining dual-material product lines.
- Composite recycling infrastructure gaps:Fiber-reinforced polymer oil pans face end-of-life processing limitations under EU REACH chemical compliance frameworks, restricting circular economy claims.
Strategic Opportunities
- Commercial vehicle heavy-duty variants:Thermal cycling durability requirements in long-haul trucking create premium margin pools for aluminum oil pans with enhanced ribbing and integrated cooling galleries.
- Aftermarket channel digitization:Independent service networks are consolidating procurement through platform-based purchasing, enabling direct supplier relationships that bypass traditional distributor markups.
- Thermal management convergence:Integration of oil pan functions with active cooling circuits and filtration modules is hybridizing product architectures into higher-value system sales.
Industry Challenges
- Multi-material welding certification:Joining aluminum oil pans to steel engine blocks requires specialized friction stir and laser welding protocols that extend validation timelines under NHTSA structural integrity requirements.
- Legacy tooling amortization:Steel stamping die sets represent sunk capital that resists rapid material pivots, forcing parallel production runs that strain working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Engine Oil Pan Market |
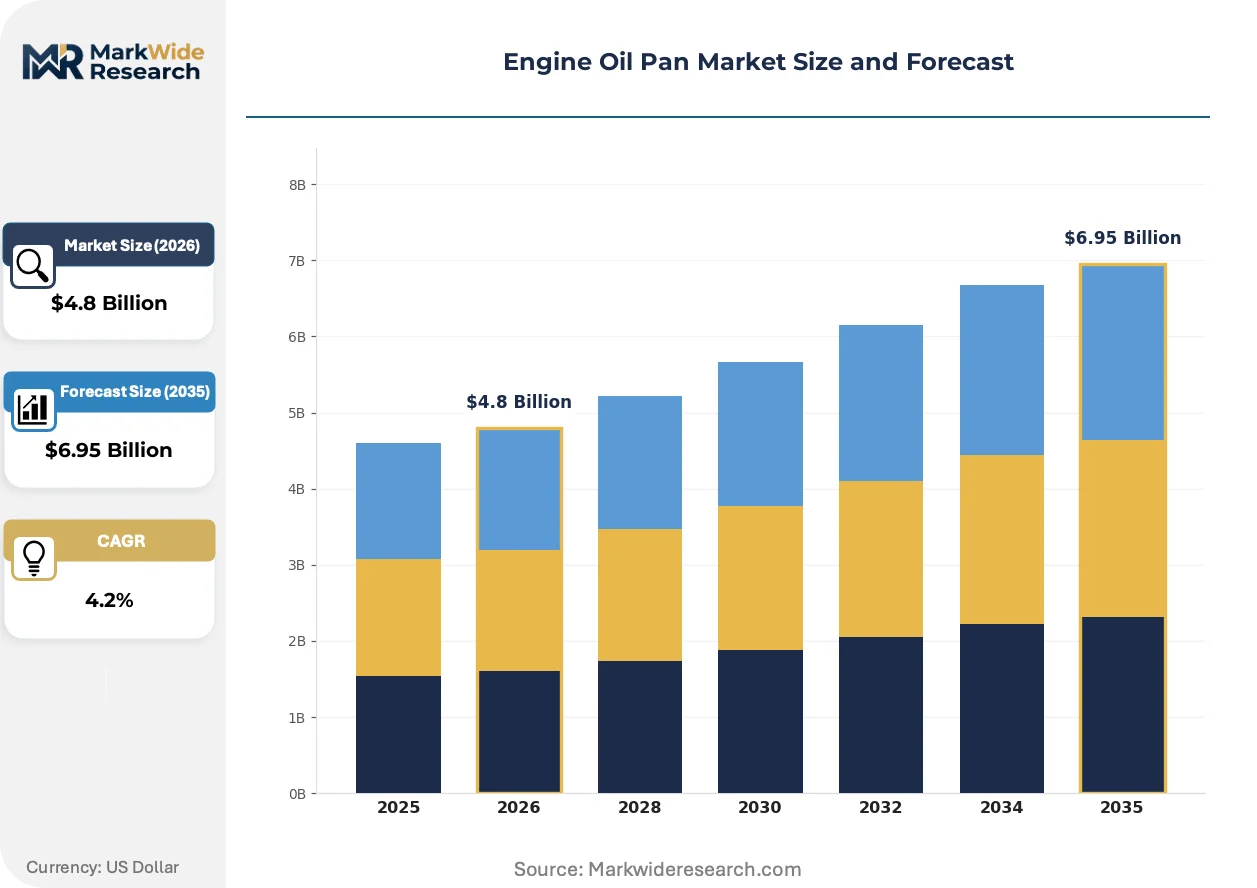
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.95 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel, Aluminum, Composite, Plastic End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers Size: Standard, Extended, Compact, Heavy-Duty Installation: Onshore, Off-road, Light-duty, Commercial |
| Companies Covered | Mann+Hummel, Ahresty, Dana Incorporated, Hwashin, American Axle & Manufacturing, Pacific Industrial, Polytec Group, Yorozu, MAHLE GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Engine Oil Pan Market Emerging Trajectories
Active thermal management integration is transforming oil pans from passive reservoirs into functional system components, while material science advances and procurement digitization rewrite supplier competitive positioning.
Aluminum-silicon alloy casting with integrated cooling passages is hybridizing traditional oil containment with active thermal regulation functions. European OEMs are adopting these designs for mild-hybrid powertrains where thermal loads fluctuate between electric and combustion modes. The convergence is compressing supplier margins on standalone stamped products while rewarding system-level design capabilities.
EPA Corporate Average Fuel Economy standards are tightening material selection protocols by mandating mass reduction documentation across vehicle subsystems. The regulation forces oil pan suppliers to validate aluminum and composite alternatives against crashworthiness and recyclability criteria simultaneously. Light-duty truck platforms face the steepest compliance burden due to NHTSA mounting interface requirements that differ materially from passenger car architectures.
Fleet operators and independent service networks are consolidating parts procurement through vertically integrated purchasing platforms that disintermediate traditional aftermarket distributors. The channel shift concentrates buying power among fewer decision-makers who demand outcome-based warranty terms rather than unit pricing. North American commercial vehicle segments exhibit the most aggressive procurement consolidation, compressing supplier margins while extending contract durations.
Engine Oil Pan Market Segmentation
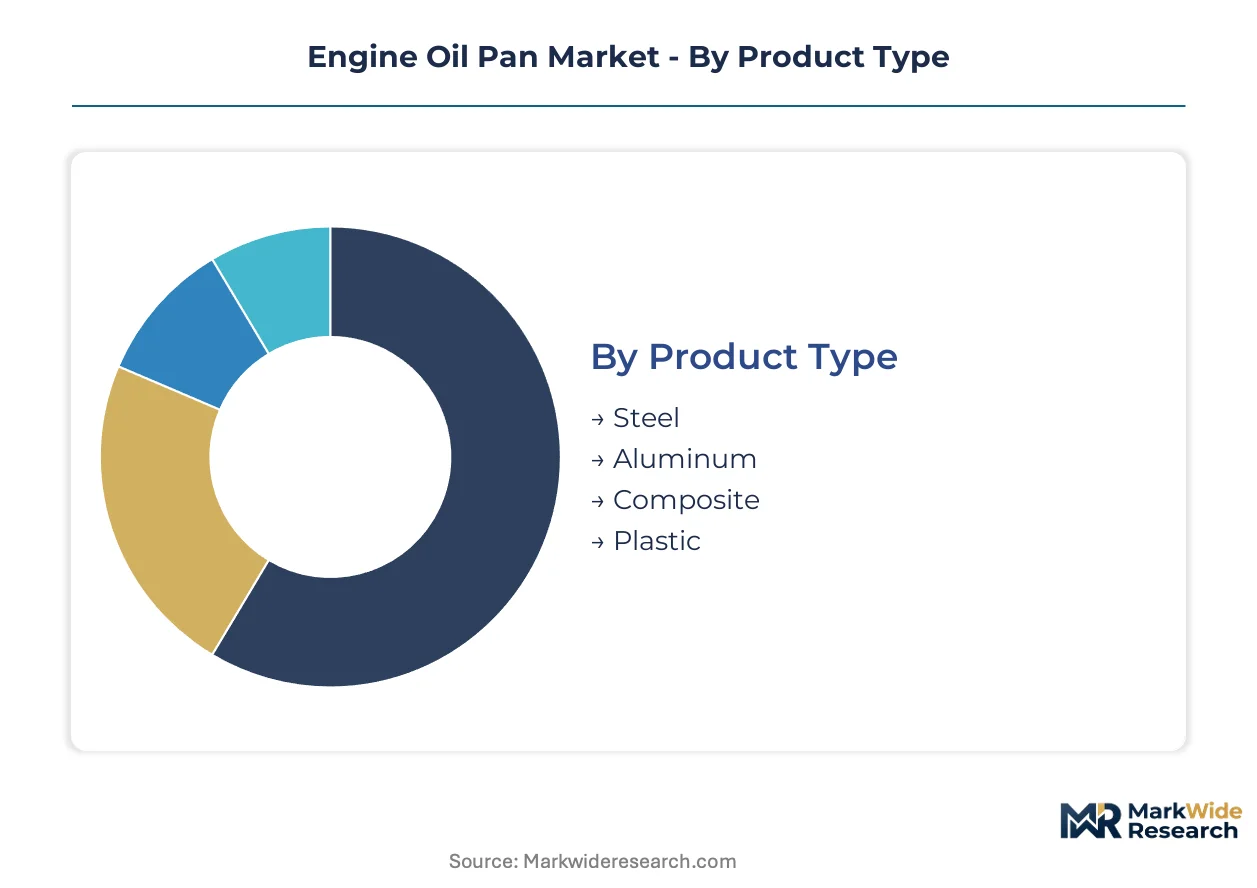
Segmentation in the Engine Oil Pan Market reveals how material selection and channel strategy determine margin capture. Aftermarket service intensity varies dramatically by product durability and vehicle duty cycle, reshaping supplier investment priorities.
Product Type:
After-sales service intensity differs sharply by material—aluminum pans generate lower warranty claims but command premium replacement pricing, while composite designs create specialized repair network dependencies.
- Aluminum:Cast and stamped aluminum alloys with wall thicknesses of 2.0–3.5 mm dominate OEM specifications for light-duty vehicles. Demand concentrates in Stuttgart and Detroit manufacturing corridors where EPA fuel economy mandates drive mass reduction programs.
- Steel:Stamped cold-rolled high-strength steel remains the cost baseline for commercial vehicle applications. Production gravity sits with legacy East Asian and European mill networks, though EU F-Gas Regulation accelerates displacement toward lighter substrates.
- Composite:Fiber-reinforced polymer formulations address hybrid-electric packaging constraints through geometric design freedom.
- Plastic:Thermoplastic variants serve niche economy vehicle segments with limited thermal cycling exposure.
Aluminum holds the largest share; momentum sits with composite materials climbing the fastest.
End User:
Cost tier stratification separates captive OEM supply from fragmented aftermarket procurement, with Tier-1 suppliers occupying the margin-rich middle ground.
- OEMs:Original equipment manufacturers specify oil pans at vehicle platform conception, locking suppliers into multi-year program contracts with stringent thermal cycling validation protocols.
- Aftermarket Providers:Independent service networks consolidate procurement through digitized purchasing platforms that disintermediate traditional distributors and demand extended warranty terms.
- Vehicle Assemblers:Final assembly operations in Germany, Japan, and the United States anchor localized supplier capacity investment for just-in-sequence delivery.
- Tier-1 Suppliers:Integrated system houses combine oil containment with filtration and thermal management functions, capturing value from component convergence.
OEMs command volume leadership; aftermarket channels are gaining share fastest through procurement consolidation.
Size:
Application severity drives specification divergence—passenger car standardization contrasts with commercial vehicle customization.
- Standard:Configurations for compact and mid-size passenger cars represent the mature volume base, with aluminum stamping lines optimized for high-throughput production.
- Heavy-Duty:Reinforced ribbing and integrated cooling galleries address thermal cycling durability in long-haul trucking. Premium margin pools concentrate with North American fleet operators facing severe duty cycles.
- Extended:Larger capacity designs serve high-displacement engines in light-duty truck platforms.
- Compact:Reduced-form-factor pans accommodate hybrid-electric powertrain packaging constraints.
Standard sizes dominate unit volume; heavy-duty variants deliver the steepest margin expansion.
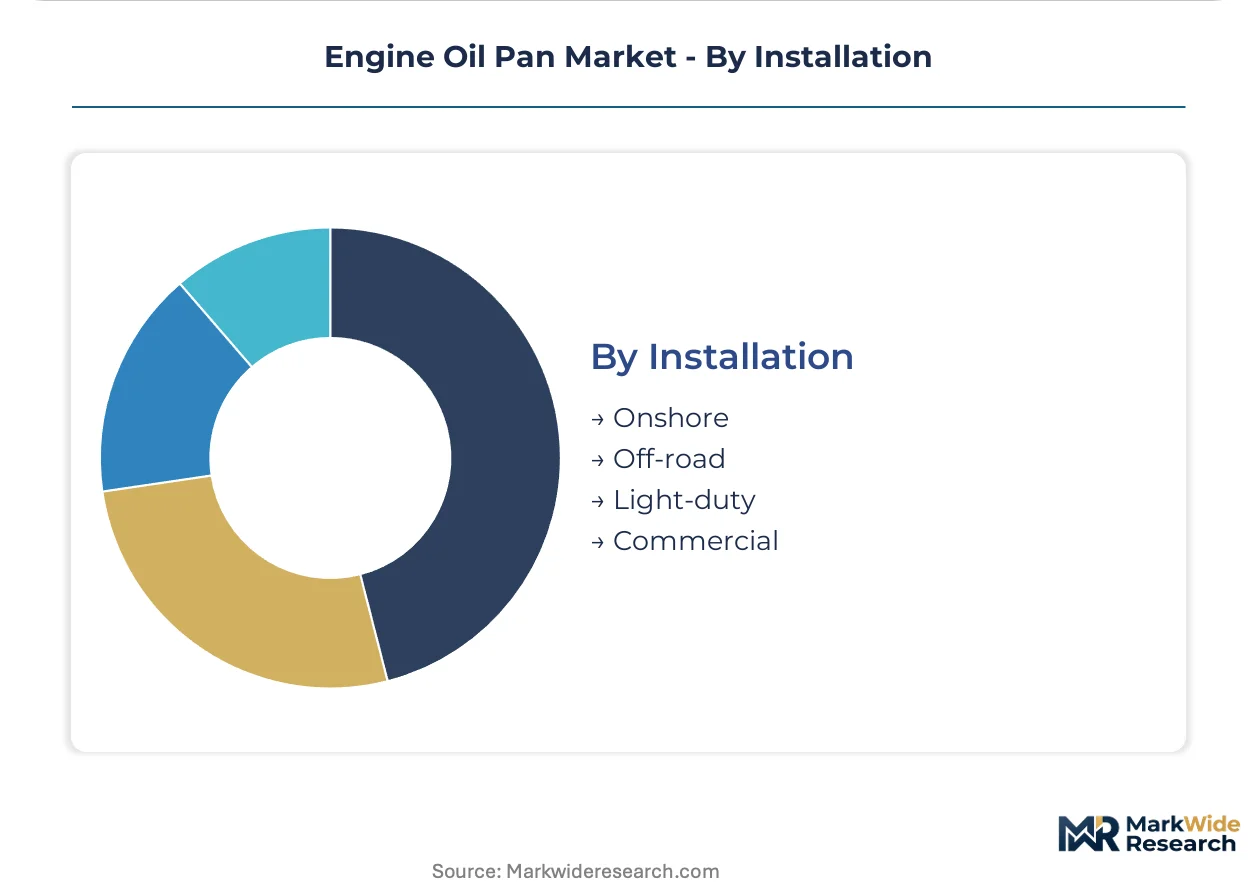
Installation:
Geographic and operational context determines structural requirements and replacement frequency.
- Light-duty:Passenger car and light truck installations prioritize mass reduction and crashworthiness under NHTSA structural integrity protocols.
- Commercial:On-highway trucking applications demand enhanced thermal management and extended service intervals.
- Onshore:Standard road-going vehicle configurations face regulated emissions and recyclability thresholds.
- Off-road:Agricultural and construction equipment installations require impact-resistant architectures for unimproved terrain exposure.
Light-duty installations generate the highest unit volumes; commercial applications sustain premium pricing tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg anchors European aluminum casting capacity for powertrain suppliers serving Stuttgart's OEM corridor. This maritime infrastructure underwrites raw material flows from Norwegian smelters to German forming operations.
United States
Detroit's powertrain manufacturing corridor drives aluminum oil pan specification for light-duty truck platforms. NHTSA crashworthiness protocols dictate structural mounting interfaces that differ from passenger car architectures. Michigan-based stamping operations supply just-in-sequence delivery to final assembly plants across the Midwest.
Germany
Stuttgart's OEM engineering centers mandate mass reduction documentation across vehicle subsystems under EU F-Gas Regulation material-efficiency standards. REACH chemical compliance frameworks restrict substrate selection to validated recyclable alternatives. Bavarian aluminum foundries retool capacity to serve mild-hybrid thermal management requirements.
Japan
Aichi Prefecture's compact vehicle production clusters sustain high-volume stamped metal forming operations. METI energy-efficiency guidelines accelerate displacement from steel to aluminum substrates in thermal systems. Nagoya-area suppliers optimize thin-wall casting processes for hybrid-electric packaging constraints.
China
Yangtze River Delta automotive corridors concentrate aluminum die-casting capacity for domestic OEM electrification roadmaps. MIIT fuel consumption standards enforce mass reduction targets across powertrain subsystems. Shanghai-area fabricators scale composite molding lines for electric-hybrid geometric design requirements.
South Korea
Ulsan-Busan manufacturing clusters anchor steel-to-aluminum transition programs for export-focused vehicle assemblers. The country's national industrial regulator enforces automotive material-efficiency benchmarks aligned with EU trade compliance. Gyeongnam Province suppliers integrate thermal management functions into system-level oil containment designs.
Engine Oil Pan Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in a structure where filtration-thermal convergence determines margin capture. The vendor base organizes around three strategic archetypes: integrated system houses combining containment with active cooling, stamped metal specialists serving high-volume compact programs, and composite formulators addressing hybrid-electric packaging constraints. Competitive positioning hardens through M&A activity targeting thermal management capabilities and strategic partnerships for aluminum alloy supply security.
Among German integrated system houses, MAHLE GmbH and Mann+Hummel occupy positions where filtration and fluid management portfolios anchor long-term OEM supply relationships. Dana Incorporated exemplifies the North American system integrator archetype, while Pacific Industrial represents Japanese stamped metal specialization for high-volume manufacturing corridors. These three named entities illustrate how geographic clustering and capability convergence separate premium-tier suppliers from commodity component fabricators.
| Leading Market Players |
|---|
| Mann+Hummel |
| Ahresty |
| Dana Incorporated |
| Hwashin |
| American Axle & Manufacturing |
| Pacific Industrial |
| Polytec Group |
| Yorozu |
| MAHLE GmbH |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Chinese aluminum die-casting corridors is compressing spot pricing for stamped oil pan substrates while forcing European suppliers into longer-term contract structures to defend margin stability under EU F-Gas Regulation compliance costs.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement negotiations, with heavy-duty commercial variants commanding aluminum alloy premiums against stamped steel baselines. Price differentiation rests on thermal cycling certification grades and integrated cooling gallery complexity. Cost compression in standard passenger car segments is intensifying because OEMs are consolidating supplier panels under mass reduction mandates. Fleet operators exhibit the highest price sensitivity, while German OEM engineering centers remain least sensitive to unit cost when thermal management integration is bundled.
Supply Chain Analysis
Primary aluminum feedstock draws from Norwegian smelters, Russian ingot flows, and Australian bauxite refining corridors before converging on German and Chinese forming operations. Secondary dependencies include cold-rolled high-strength steel from Japanese and European mill networks, plus glass fiber and resin systems for composite formulations. Single-source vulnerability concentrates in specialized friction stir welding equipment for aluminum-to-steel joining protocols. Distribution runs through just-in-sequence delivery networks anchored to Stuttgart, Detroit, and Aichi Prefecture assembly corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Engine oil pan incumbents face a substitution defense against composite material displacement in hybrid-electric powertrain architectures, where geometric design freedom threatens traditional metal forming value capture.
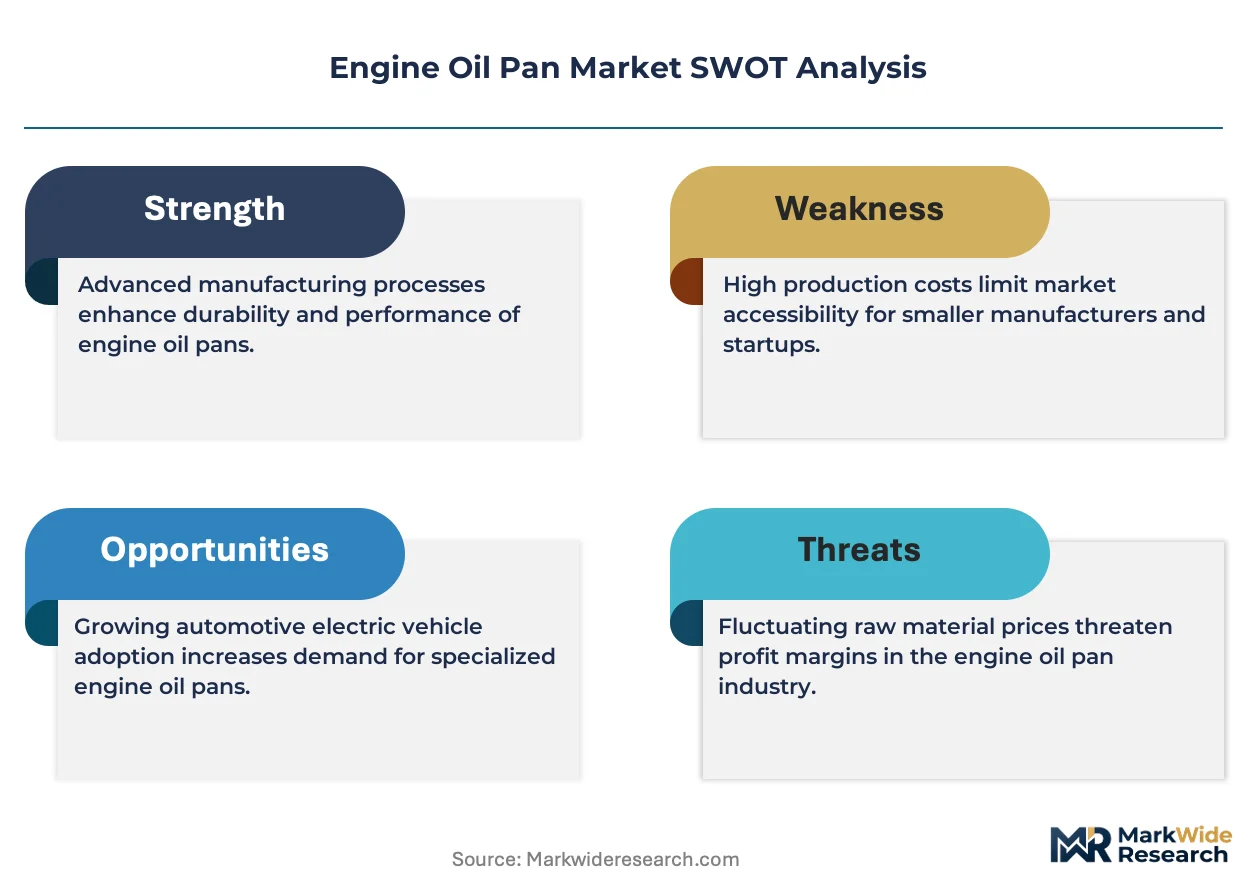
For Market Incumbents: Build thermal management integration moats by acquiring active cooling circuit specialists and securing captive aluminum alloy supply agreements with Norwegian smelter networks. Retooling legacy steel stamping lines for aluminum alloy forming under EU F-Gas Regulation timelines represents the critical capacity lever. Composite recycling infrastructure gaps under REACH frameworks create temporary defensive positioning against full material substitution. For New Entrants and Emerging Players: Mid-market commercial vehicle fleet operators in North America represent the most penetrable entry point, as these buyers consolidate procurement through digitized platforms and demand outcome-based warranty terms rather than legacy distributor relationships. Composite formulation capabilities for hybrid-electric packaging constraints offer technical differentiation. Direct supplier relationships with independent service networks bypass traditional aftermarket markups. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across aluminum casting and composite molding capacity as dual-material production runs strain working capital. Acquisition targets should emphasize system-level design houses combining oil containment with filtration and thermal management functions, rather than standalone stamped component fabricators. The signal to watch is OEM platform standardization announcements that collapse variant counts and concentrate volume among fewer qualified suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Alloy Supply | Captive access to Norwegian smelter networks insulates margin stability against LME price volatility. |
| Thermal Management Capability Acquisition | System-level design convergence rewards integrated containment-cooling-filtration portfolios under EPA fuel economy mandates. |
| Composite Recycling Infrastructure Investment | EU REACH end-of-life processing capabilities unlock circular economy claims and defend against regulatory restriction. |
| Aftermarket Platform Direct Relationships | Disintermediation of traditional distributors captures margin compression from consolidated fleet procurement. |
| Friction Stir Welding Certification Expansion | NHTSA structural integrity protocols for aluminum-to-steel joining create qualified supplier scarcity. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and aluminum foundry operations managers; and secondary validation through vehicle production databases, IHS Markit registration data, SEC filings from listed automotive suppliers, and EU regulatory filings under F-Gas and REACH frameworks. Bottom-up segment sizing triangulated against top-down powertrain production forecasts.
Forecast inputs considered vehicle class stratification, propulsion architecture evolution between internal combustion and hybrid-electric configurations, content per vehicle by material substrate, and regional production cluster capacity allocation. CAGRs were derived from regression analysis across historical production volumes and projected powertrain mix shifts throughout the forecast period. Aluminum alloy price elasticity and composite adoption curves in hybrid platforms served as sensitivity anchors.
Stress conditions across aluminum LME pricing bands, EU F-Gas Regulation enforcement timelines, and hybrid-electric powertrain penetration rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about OEM platform life cycles and supplier qualification timelines. Cross-checking against IHS Markit powertrain production forecasts is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Radiator Hose Market
Automotive Parts
Africa Passenger Vehicles Lubricants Market
Automotive Parts
Two-Wheeler Lubricants Market
Automotive Parts
Asia-Pacific Electric Power Steering Market
Automotive Parts
Europe Automotive Aftermarket Spare Parts Market
Automotive Parts
Latin America Automotive Parts Zinc Die Casting Market
Automotive Parts
Bulgaria Automotive Engine Oils Market
Automotive Parts
Automotive Crankshaft Materials Market
Automotive Parts
Automotive Screenwash Products Market
Automotive Parts
Diesel Common Rail Injection System Market
Automotive Parts
Automotive Brake Caliper Market
Automotive Parts
Automotive Oil Pans Market
Automotive Parts
Automotive Brake Wheel Cylinder Market
Automotive Parts
Automotive Coolant Aftermarket Market
Automotive Parts
Automotive Exhaust System Market
Automotive Parts
Autonomous Forklift Market