
 Europe Motorcycle Parts and Accessories Market | 2026-2036
Europe Motorcycle Parts and Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Motorcycle Parts and Accessories Market Analytics
Carbon fiber is broadening its share in fairings and structural components as manufacturers trade metal weight for performance gains. Dainese S.p.A. anchors its position through advanced composite research in protective riding gear. Akrapovic competes with titanium and carbon exhaust systems engineered for Euro 5 compliance. SW-MOTECH GmbH and Co. KG dominates the touring luggage segment with modular rack systems designed for adventure motorcycles.
Europe motorcycle parts and accessories encompass replacement components, protective equipment, and performance upgrades manufactured to OEM tolerances or aftermarket specifications, typically using aluminum alloys, hardened steel, carbon fiber prepregs, and engineering plastics rated for vibration fatigue and weather exposure. Brake systems and suspension parts draw the highest aftermarket spend as riders prioritize safety upgrades over cosmetic modifications. Carbon fiber components represent the fastest-expanding material category, though aluminum engine components still occupy the largest volume share due to thermal conductivity requirements. Online retailers are capturing share from specialty stores by offering fitment verification tools and direct-to-rider logistics across national borders.
REACH regulates chemical substances in coatings and plating processes, while the EU Green Deal pressures suppliers to reduce lifecycle emissions in manufacturing. ECE R22.05 and the forthcoming ECE R22.06 helmet standards reshape product development timelines for protective gear makers. Stakeholders must track regulatory divergence between EU harmonized standards and member-state enforcement intensity to anticipate compliance costs and certification delays.
Market Dynamics
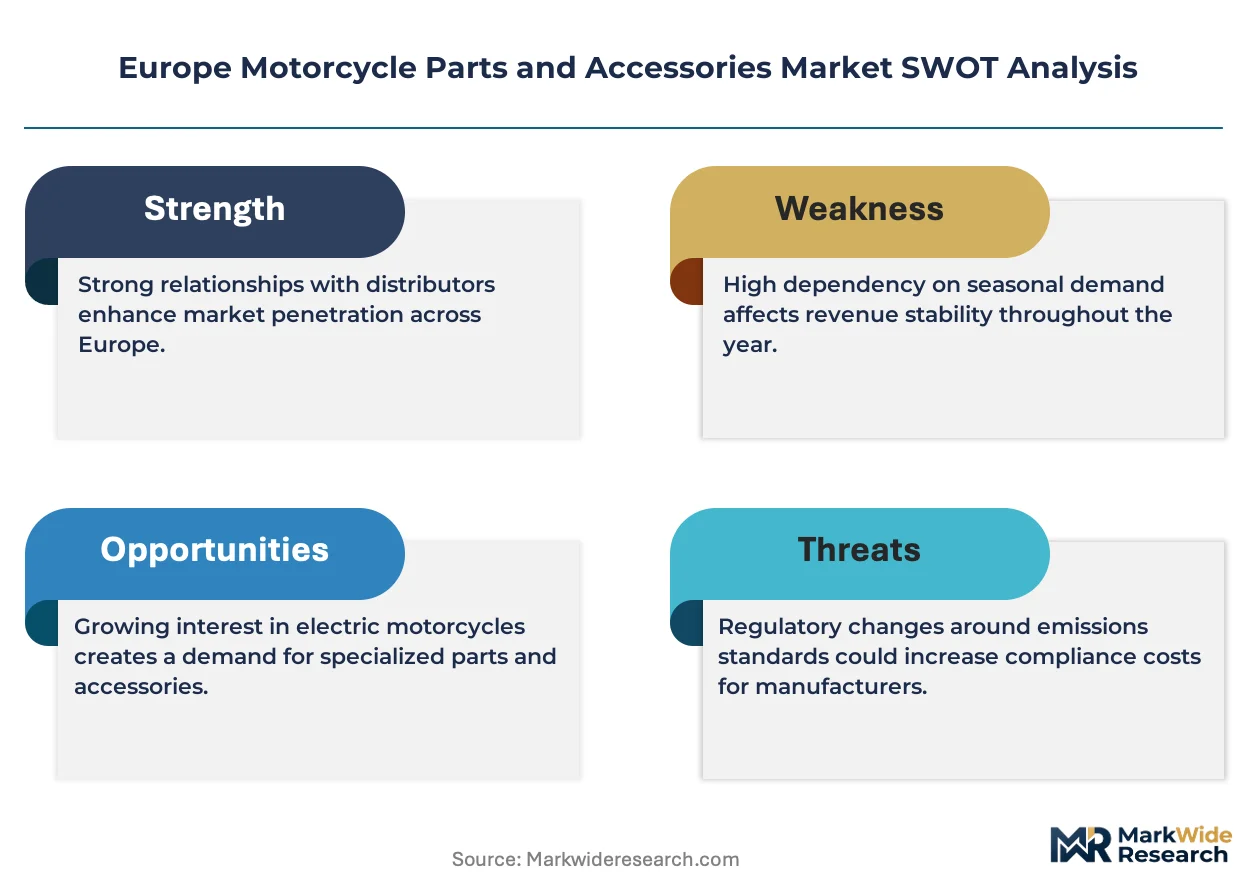
REACH compliance and the EU Green Deal are forcing suppliers to reformulate chrome plating chemistries and exhaust catalyst compositions, compressing development timelines while raising certification costs across the European supply base.
Growth Catalysts
- Touring segment expansion:Adventure motorcycle sales in Germany and France are pulling demand for modular luggage systems and long-distance protective gear through specialized retail channels.
- ECE R22.06 helmet mandate:The upgraded protective equipment standard is accelerating replacement cycles as riders upgrade to certified rotational-impact systems.
- Carbon fiber prepregs:Composite manufacturing advances are lowering unit costs for structural fairings, enabling broader adoption beyond racing applications into premium street motorcycles.
Market Restraints
- Titanium supply concentration:Exhaust system manufacturers face input cost volatility as sponge titanium production concentrates in a limited supplier base outside Europe.
- Chrome plating substitution limits:REACH restrictions on hexavalent chromium have not yet yielded commercially viable alternatives meeting thermal and corrosion specifications for exhaust tips and trim.
- Euro 5 compliance friction:The emission standard tightens catalyst loading requirements, raising material costs for aftermarket exhaust makers without equivalent performance gains.
Strategic Opportunities
- Poland and Czech Republic manufacturing:Lower labor costs and EU membership provide tariff-free access to Western European distribution networks for component assembly operations.
- Direct-to-rider e-commerce:Fitment verification algorithms and cross-border logistics integration are opening channel share previously held by national specialty retailers.
- CSRD disclosure requirements:The Corporate Sustainability Reporting Directive creates first-mover advantage for suppliers with verified lifecycle emission data in procurement decisions.
Industry Challenges
- Composite technician scarcity:Carbon fiber layup and autoclave operation skills are concentrated in aerospace and motorsport sectors, constraining workforce expansion for motorcycle component production.
- ECE type approval timelines:Exhaust and lighting component certification delays of 8-14 months compress product launch windows and inventory planning cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Motorcycle Parts and Accessories Market |
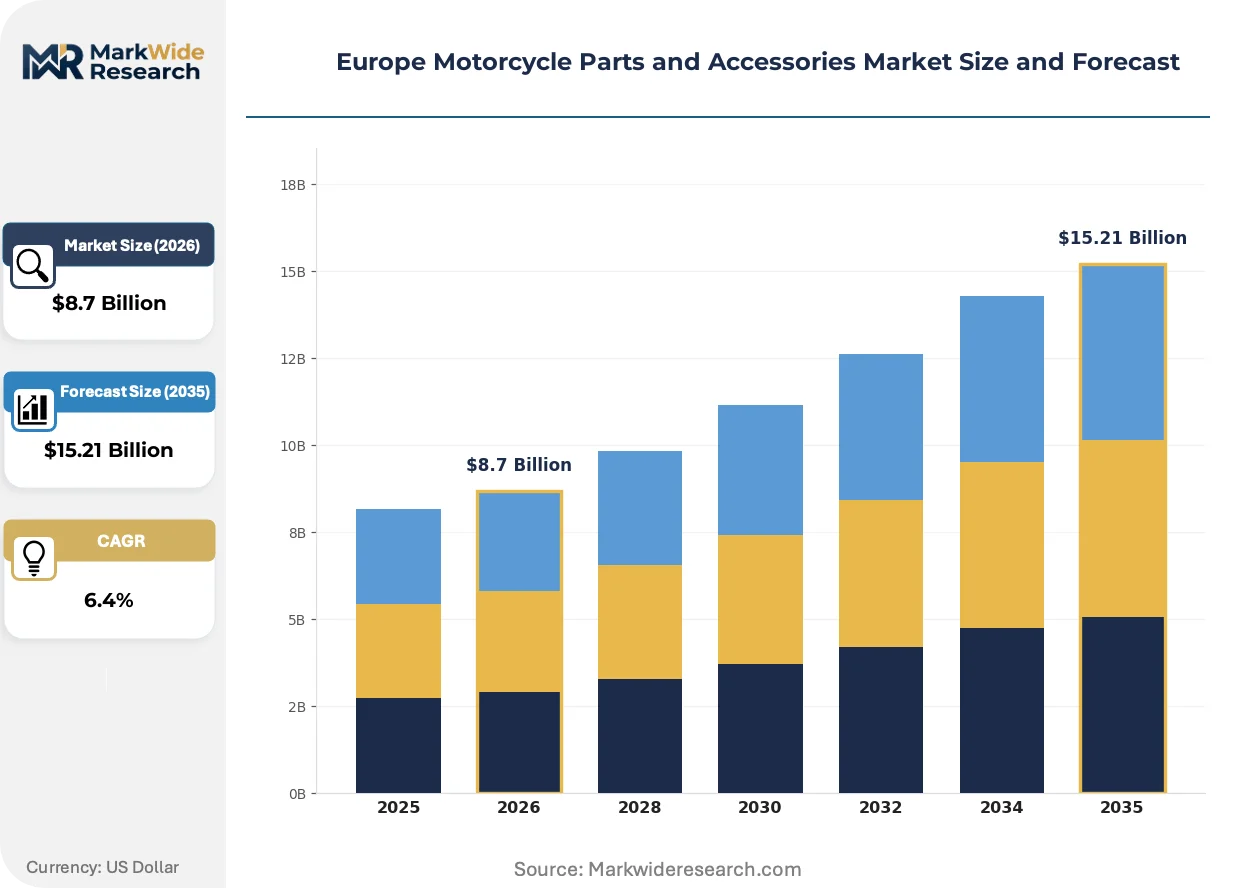
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
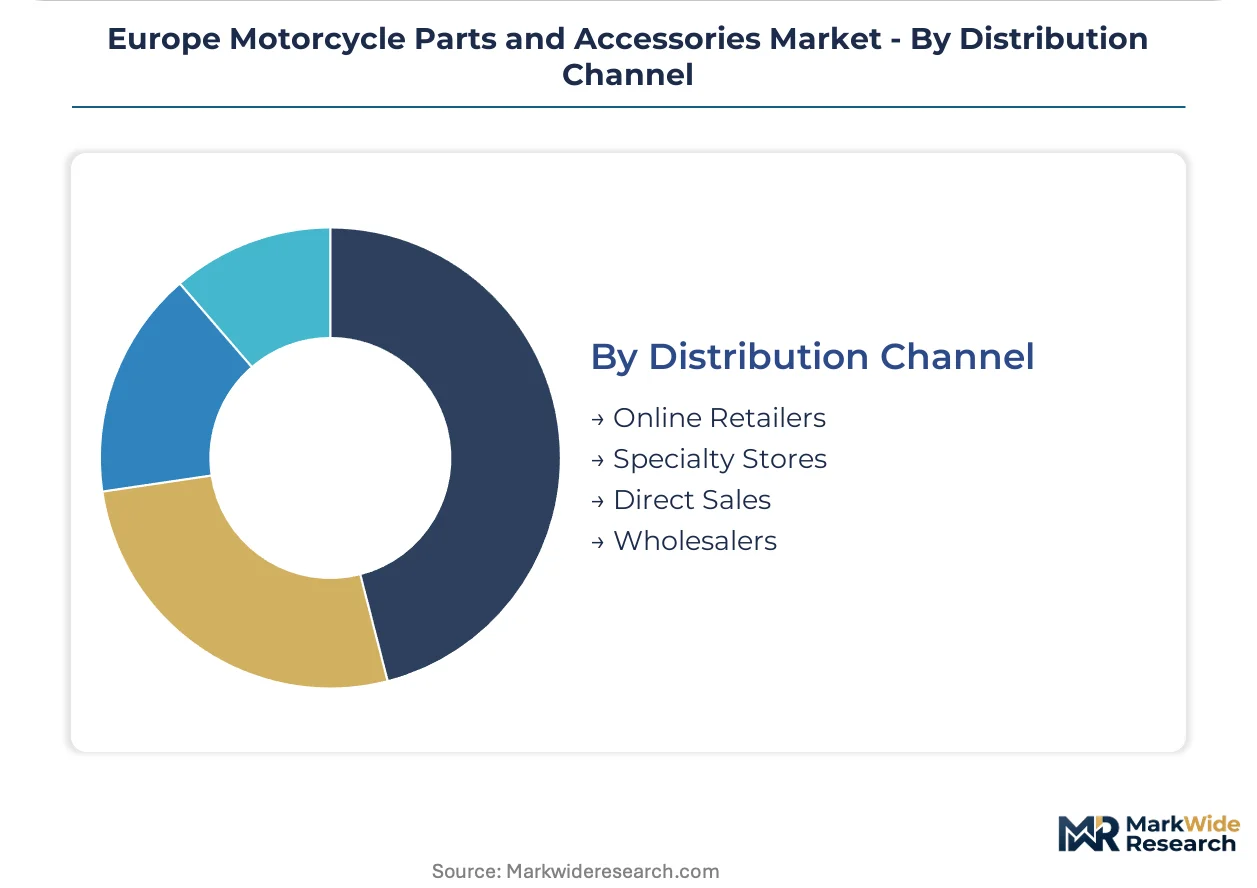
| Segmentation | Product Type: Engine Components, Electrical Systems, Suspension Parts, Brake Systems End User: Individual Riders, Dealerships, Aftermarket Providers, Service Shops Material: Aluminum, Steel, Carbon Fiber, Plastic Distribution Channel: Online Retailers, Specialty Stores, Direct Sales, Wholesalers |
| Companies Covered | Alpinestars USA Inc., SW-MOTECH GmbH and Co. KG, Dainese S.p.A, GIVI S.P.A., Akrapovic, Caberg S.p.a., ABUS August Bremicker Sons KG, Sena Technologies Inc., Schuberth GmbH, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Motorcycle Parts and Accessories Market Evolving Landscape
Material science advances and regulatory compression are simultaneously reshaping product development priorities and procurement patterns across the European motorcycle parts ecosystem.
Automated fiber placement is automating carbon component manufacturing for fairings and structural subframes. Premium Italian and German manufacturers are adopting robotic layup cells to reduce cycle times and scrap rates. This automation is compressing the cost gap between composite and aluminum alternatives in medium-volume production runs.
REACH authorization requirements for chromium trioxide are forcing plating shops to invest in trivalent chromium lines or physical vapor deposition alternatives. The industrial consequence is a supply bottleneck for decorative exhaust finishes as conversion timelines stretch across 18-24 months. Italian component clusters in Emilia-Romagna are responding fastest due to existing environmental compliance infrastructure.
Rider purchasing behavior is fragmenting across channel types as younger buyers complete research phases through social video platforms before executing transactions through manufacturer-direct portals. National specialty retailers in France and Spain are losing share to cross-border specialists offering fitment databases and return logistics. This channel rotation is most visible in protective gear categories where sizing uncertainty previously favored physical inspection.
Europe Motorcycle Parts and Accessories Market Segmentation
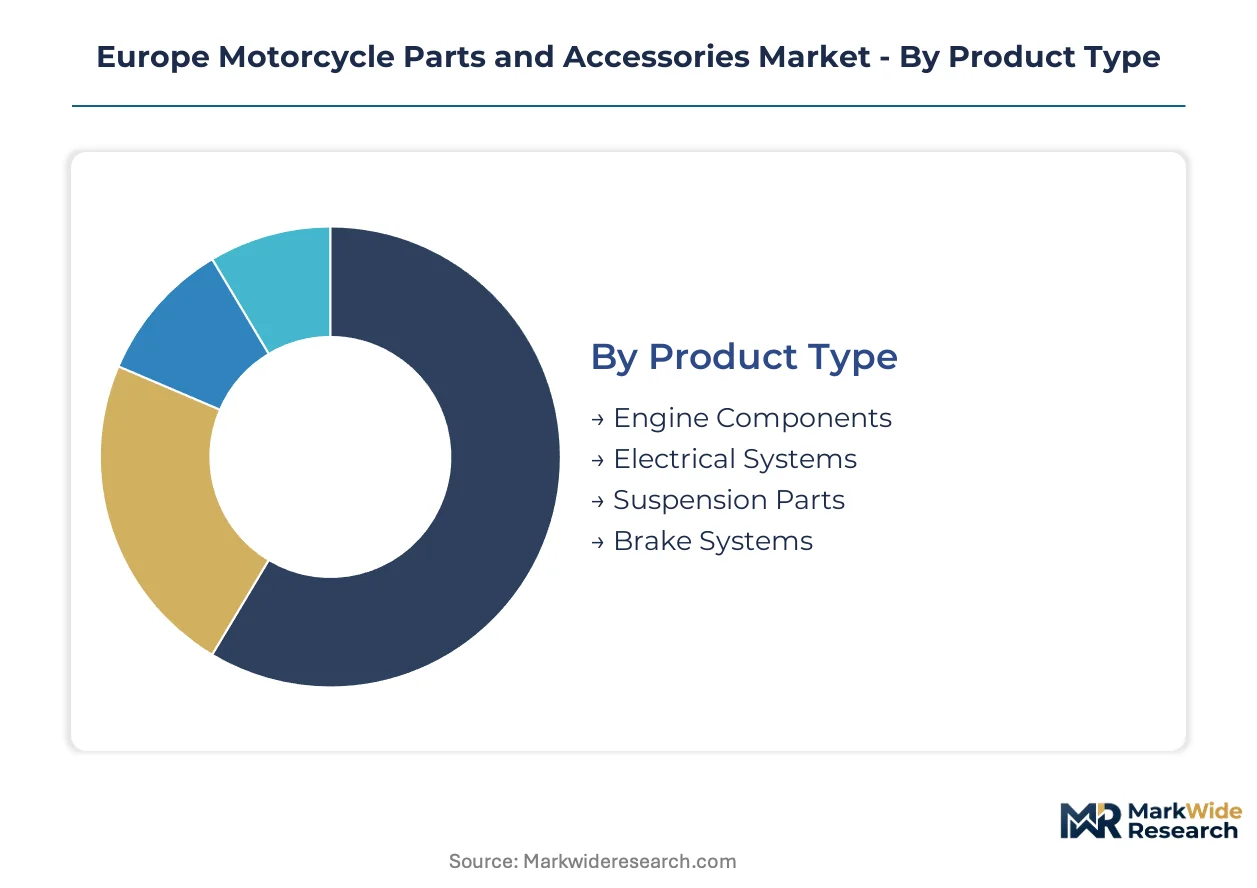
Segmentation in Europe motorcycle parts and accessories reveals how material constraints, regulatory compliance, and channel economics partition value capture. Suppliers configure production around REACH-mandated material transitions and the uneven digital maturity of national retail markets.
Product Type:
Supply concentration in precision-machined components determines margin distribution across replacement and upgrade categories.
- Engine Components:Aluminum castings and forged pistons dominate thermal management specifications for European powertrains. Italian foundries in Emilia-Romagna and German suppliers around Stuttgart absorb the bulk of OEM sourcing for high-performance applications.
- Electrical Systems:Wiring harnesses, ECU modules, and lighting assemblies face ECE type approval timelines of 8-14 months. French and German electronics specialists are consolidating procurement for connected rider systems and LED lighting upgrades.
- Suspension Parts:Telescopic forks and rear shock absorbers require hardened steel tubes and precision damping valving.
- Brake Systems:Sintered brake pads and stainless steel braided lines command the highest aftermarket spend per transaction.
Engine Components absorb the bulk of installed capacity; Electrical Systems is expanding most quickly as rider demand shifts toward integrated connectivity and lighting upgrades.
End User:
Channel power asymmetries between consolidated dealerships and fragmented service shops reshape pricing and inventory terms.
- Individual Riders:Direct purchasing concentrates in protective gear and cosmetic modifications where fitment verification tools reduce return rates. German and French riders drive premium luggage system sales through manufacturer portals.
- Dealerships:Authorized networks capture warranty-related replacement volume and OEM-specified upgrade paths. Italian dealer groups in northern regions maintain the densest service coverage for premium marques.
- Aftermarket Providers:Independent distributors stock fast-moving brake and suspension parts across multiple brand fitments.
- Service Shops:Repair facilities prioritize same-day availability of consumables over brand loyalty.
Dealerships retain the largest share of warranty-captive volume; Individual Riders is climbing the fastest as direct-to-rider e-commerce erodes traditional retail intermediation.
Material:
REACH compliance timelines and the EU Green Deal carbon intensity requirements are forcing reformulation decisions across plating and composite operations.
- Aluminum:Cast and forged alloys retain dominance in engine blocks, wheels, and structural brackets due to thermal conductivity and weight trade-offs. German smelter partnerships secure primary metal supply for Tier-1 suppliers.
- Carbon Fiber:Prepreg autoclave processing for fairings and subframes is automating through robotic fiber placement. Italian manufacturers lead adoption as aerospace-trained technicians migrate into motorcycle component production.
- Steel:Hardened alloys remain essential for suspension tubes, brake rotors, and frame structures.
- Plastic:Engineering polymers rated for UV stability and vibration fatigue serve bodywork and electrical housings.
Aluminum commands the greatest production volume; Carbon Fiber is gaining share fastest as automation compresses cost premiums against metal alternatives.
Distribution Channel:
Logistics integration and fitment database accuracy are becoming the primary competitive variables as cross-border commerce scales.
- Online Retailers:Algorithmic fitment verification and return logistics integration are capturing share from national specialty stores. Cross-border specialists based in the Netherlands and Germany lead warehouse network density.
- Specialty Stores:Physical inspection advantages persist in protective gear sizing and complex luggage system configuration. French and Spanish independents face margin compression from direct manufacturer pricing.
- Direct Sales:OEM-branded portals control premium component pricing and exclusive product launches.
- Wholesalers:Bulk distributors serve service shops with consolidated brake pad, filter, and lubricant procurement.
Online Retailers is expanding most quickly; Specialty Stores retains the highest margin per transaction in premium protective equipment categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Germany, France, and Italy where touring culture and racing heritage sustain premium component purchases. REACH enforcement intensity varies across member states, creating compliance cost differentials that reshape supplier location decisions.
Germany
Adventure motorcycle sales in Bavaria and Baden-Württemberg pull demand for modular luggage systems and long-distance protective gear. KBA enforces Euro 5 emission standards with particular rigor, compressing aftermarket exhaust certification timelines. Stuttgart anchors precision machining clusters supplying aluminum engine components to OEMs across the continent.
Italy
Racing heritage in Emilia-Romagna sustains premium carbon fiber fairing and protective gear manufacturing. ECHA REACH restrictions on hexavalent chromium have accelerated plating shop consolidation in Lombardy and Veneto. Bologna-Mirandola industrial districts host the densest concentration of motorsport-trained composite technicians migrating into motorcycle component production.
France
Touring riders in Île-de-France and Auvergne-Rhône-Alpes expand purchases of protective equipment and connectivity systems. ANSM enforces ECE R22.06 helmet standards with member-state specific testing protocols that extend approval timelines. Lyon-based specialty retailers face margin compression from cross-border e-commerce specialists operating from the Netherlands and Germany.
United Kingdom
Post-Brexit regulatory divergence creates certification friction for exhaust and lighting components entering EU distribution networks. Midlands manufacturing clusters retain capacity in aluminum casting and precision steel fabrication despite trade documentation burdens. London-anchored direct-to-rider platforms capture growing share of protective gear sales through algorithmic fitment verification.
Poland
Lower labor costs and EU membership attract component assembly operations serving Western European distribution networks. Warsaw and Krakow industrial zones host expanding operations for brake system and electrical harness manufacturing. CSRD disclosure requirements create procurement advantage for Polish suppliers with verified lifecycle emission data.
Europe Motorcycle Parts and Accessories Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with protective gear and exhaust systems favoring branded positions while engine components concentrate around OEM supply relationships. The vendor base organizes into three tiers: integrated specialists controlling composite and material science IP, regional fabricators competing on logistics proximity, and contract assemblers serving price-sensitive replacement demand. Consolidation pressures mount as REACH compliance costs favor scaled operators with dedicated environmental compliance infrastructure. Geographic expansion into Poland and Czech Republic manufacturing zones and portfolio diversification into connected rider systems represent the dominant competitive moves reshaping positioning.
Among Italian specialists, Dainese S.p.A. and GIVI S.P.A. exemplify the integrated archetype combining material science capabilities with brand equity in protective equipment and luggage systems. SW-MOTECH GmbH and Co. KG represents the German engineering-focused tier, occupying a position defined by precision manufacturing and modular system architecture. These three entities anchor the premium tier where composite expertise and regulatory compliance infrastructure create defendable positioning against lower-cost regional competitors.
| Leading Market Players |
|---|
| Alpinestars USA Inc. |
| SW-MOTECH GmbH and Co. KG |
| Dainese S.p.A |
| GIVI S.P.A. |
| Akrapovic |
| Caberg S.p.a. |
| ABUS August Bremicker Sons KG |
| Sena Technologies Inc. |
| Schuberth GmbH |
| Others |
Value Network & Pricing Analysis
REACH authorization requirements for chromium trioxide gate qualified supply access for decorative exhaust finishes and premium trim components, compressing the supplier base capable of serving OEM and Tier-1 procurement tiers while elevating pricing premiums for REACH-compliant plating operations.
Pricing Analysis
Volume-mass engine components trade on thin margins anchored to aluminum ingot benchmarks and German foundry capacity utilization, while carbon fiber fairings and protective gear command tiered pricing stratification across premium racing, standard street, and economy replacement tiers. Price differentiation rests on ECE type approval certification status and autoclave processing automation levels, with unapproved exhaust systems facing margin erosion from Euro 5 catalyst loading cost inflation. Dealerships absorb the greatest price sensitivity due to warranty-captive volume terms, whereas direct-to-rider channels sustain premium capture through fitment verification tooling.
Supply Chain Analysis
ECE R22.06 certification gating restricts helmet and protective equipment sourcing to qualified Italian and German manufacturers with rotational-impact testing infrastructure, concentrating premium supply in Emilia-Romagna and Bavaria industrial clusters. Raw material dependencies draw from Japanese carbon fiber prepregs, Ukrainian titanium sponge, and German primary aluminum smelters. Single-source vulnerability concentrates in aerospace-trained composite technician pools shared with motorsport sectors. Distribution runs through Netherlands-anchored cross-border specialists and German direct-to-rider platforms eroding French and Spanish specialty store intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The European motorcycle parts sector is executing a material-transition phase as carbon fiber automation displaces aluminum-intensive legacy architectures across fairing and structural component categories.
For Market Incumbents: Deploy autoclave robotics capacity to compress composite cycle times and scrap rates against emerging Polish assembly competitors. Defensive consolidation moves require acquiring aerospace-trained technician pipelines from Bologna-Mirandola industrial districts and securing trivalent chromium plating lines ahead of REACH authorization bottlenecks. The threat of titanium supply concentration outside Europe demands backward integration into long-term sponge sourcing agreements or alternative exhaust material architectures. For New Entrants and Emerging Players: CSRD disclosure requirements in Poland and Czech Republic open a window for component assembly operations with verified lifecycle emission data capturing procurement preference from Western European OEMs. White-space targets concentrate in electrical harness manufacturing for connected rider systems and LED lighting upgrades where ECE type approval timelines deter incumbent expansion. A direct-to-rider go-to-market angle leveraging algorithmic fitment verification can bypass national specialty retail gatekeepers in France and Spain. For Investors and Strategic Acquirers: Accelerated plating shop consolidation in Lombardy and Veneto is the leading indicator that REACH-compliant environmental infrastructure is becoming a scarce, value-capturing asset. Long-term viability favors vertically integrated specialists controlling composite IP and regulatory compliance infrastructure over pure-play assemblers exposed to labor cost arbitrage. The signal to monitor is technician migration rates from aerospace into motorcycle component production, which will determine carbon fiber capacity scaling feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Autoclave Robotics Deployment | Italian manufacturers compress composite cycle times to challenge aluminum cost structures. |
| Trivalent Chromium Plating Conversion | REACH-compliant shops in Emilia-Romagna capture decorative exhaust finish premiums. |
| Polish Assembly Expansion | EU membership provides tariff-free access to German and French distribution networks. |
| Direct-to-Rider Platform Buildout | Netherlands-based cross-border specialists displace French specialty store intermediation. |
| Aerospace Technician Recruitment | Bologna-Mirandola clusters secure composite layup skills from motorsport sectors. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs across this analysis, combining structured interviews with component procurement managers at German and Italian OEMs, composite production supervisors in Emilia-Romagna industrial districts, and aftermarket distribution heads at Netherlands-based cross-border specialists. Secondary validation drew from ECHA REACH authorization databases, KBA vehicle registration statistics, ECE type approval documentation, and EU customs import records for titanium sponge and carbon fiber prepregs. Bottom-up production capacity estimates triangulated against top-down consumption flow analysis across the projection horizon.
Data-stream reconciliation integrated shipment volumes from German foundries, Italian autoclave operators, and Polish assembly plants against end-user purchasing patterns captured through direct-to-rider platform analytics and specialty retail channel surveys. Segmentation modeling spanned product type, material category, end-user archetype, and distribution channel dimensions, with CAGRs derived from regression analysis of historical production trends and regulatory phase-in schedules. Forecast inputs incorporated Euro 5 emission standard compliance cost trajectories and ECE R22.06 helmet replacement cycle acceleration.
The model assumes a particular technology adoption path for automated fiber placement in carbon component manufacturing; alternative pathways involving out-of-autoclave processing or thermoplastic composites would alter the outlook for Italian manufacturer cost positioning. Forecasts reflect assumptions regarding REACH enforcement intensity consistency across member states and titanium supply chain stability. A model refresh is warranted upon material change in EU Green Deal carbon intensity requirements or ECE regulatory amendment timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automatic Gearbox Valves Market
Automotive Parts
Europe Automotive Lubricants Market
Automotive Parts
Brazil Automotive Hydraulic Actuators Market
Automotive Parts
Germany Automotive Parts Aluminium Die Casting Market
Automotive Parts
Suspension Spring Market
Automotive Parts
Electric Vehicle Brake Pad Market
Automotive Parts
Brazil Automotive Parts Magnesium Die Casting Market
Automotive Parts
Power Liftgate Market
Automotive Parts
France Automotive Parts Magnesium Die Casting Market
Automotive Parts
Global Automotive Parts Remanufacturing Market
Automotive Parts
Global Automotive Plastics Market
Automotive Parts
Australia Automotive Parts Magnesium Die Casting Market
Automotive Parts
Gasoline Direct Injection Market
Automotive Parts
Automotive Slack Adjuster Market
Automotive Parts
Electric Vehicle Aluminum Electric Drive Parts Market
Automotive Parts
Car Phone Holder Market