
 Bulgaria Automotive Engine Oils Market | 2026-2036
Bulgaria Automotive Engine Oils Market Size, Share, and Industry Trends Forecast 2026-2036
Bulgaria Automotive Engine Oils Market Outlook
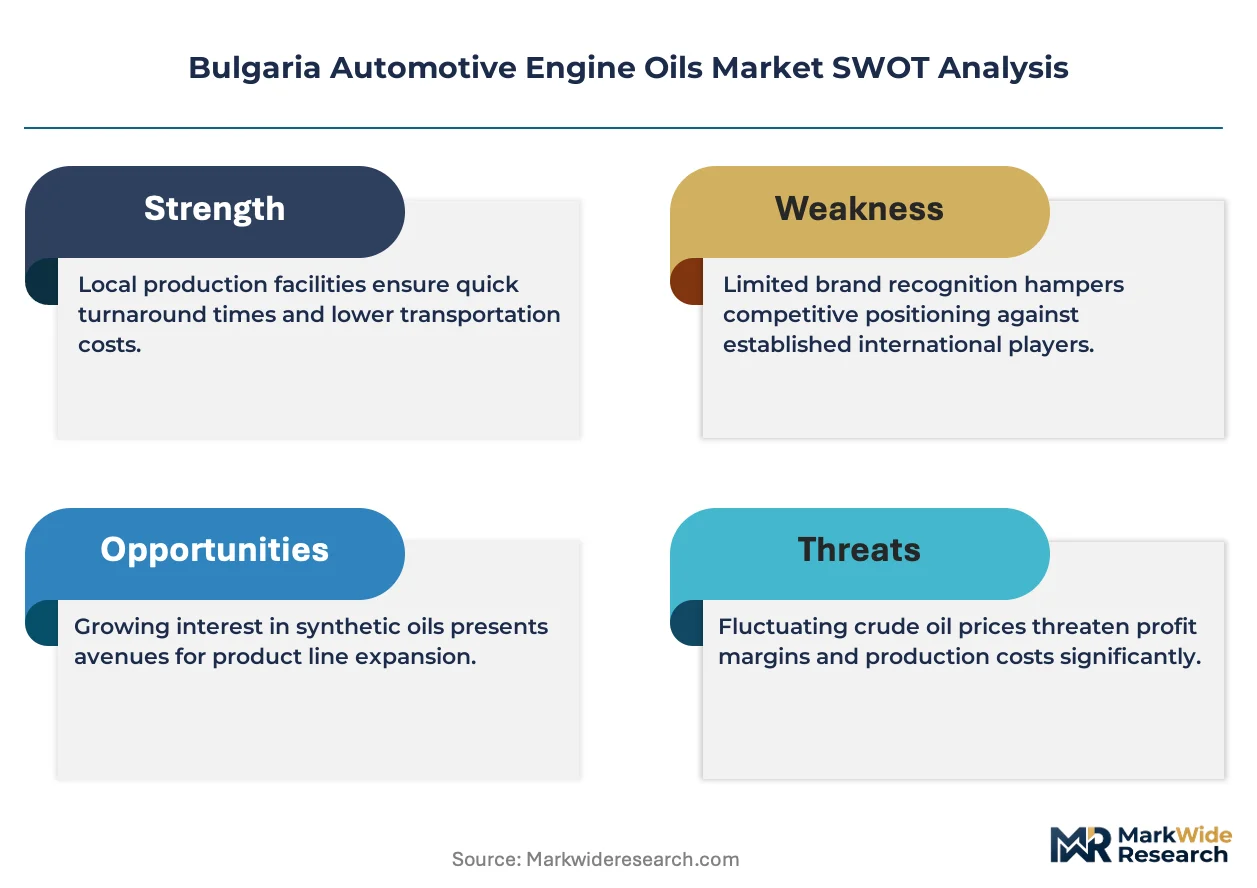
The independent garage channel is reshaping how engine oils reach Bulgarian vehicle owners. LIQUI MOLY leverages its German technical reputation to anchor premium positioning in Sofia's service networks. Prista Oil competes through localized blending operations near Burgas. Royal Dutch Shell Plc extends its retail footprint via partnerships with national fuel station chains across the Danube corridor.
Automotive engine oils are lubricant formulations designed to reduce friction between internal combustion engine components, typically classified by SAE viscosity grades and API performance categories that specify thermal stability, oxidation resistance, and wear protection under operating temperatures exceeding 150°C. Their primary commercial purpose is to extend engine operational life while maintaining fuel efficiency compliance. Synthetic oils command margin pools in passenger vehicle applications where extended drain intervals justify premium positioning. Mineral oils still occupy volume leadership in heavy-duty vehicle fleets operating cost-sensitive routes through the Balkan transit corridor. Aftermarket providers dominate distribution structure, though OEM specifications increasingly govern product approval for newer engine architectures entering Bulgaria from EU assembly plants.
Bulgaria's national environmental regulator enforces EU REACH compliance on lubricant additive chemistry, while the country's consumer protection authority monitors labeling accuracy under harmonized EU standards. These frameworks push formulators toward lower SAPS (sulfated ash, phosphorus, sulfur) chemistries compatible with exhaust after-treatment systems. The Ministry of Transport's vehicle inspection regime indirectly shapes demand by tightening emission thresholds that stress oil condition. Stakeholders must track how BIS-equivalent conformity assessment procedures evolve for bio-based oil claims entering the Bulgarian market from Black Sea trade routes.
Market Dynamics
EU REACH enforcement on lubricant additive chemistry is collapsing the formulation space available to Bulgarian blenders, forcing rapid migration toward lower SAPS chemistries that protect exhaust after-treatment systems in newer EU-sourced vehicles.
Growth Catalysts
- EU emission alignment:Bulgaria's Ministry of Transport inspection regime tightens emission thresholds, stressing oil condition and accelerating drain interval compression in Sofia and Plovdiv fleet operations.
- Synthetic technology maturation:Extended drain interval formulations reduce total cost of ownership for passenger vehicle owners, pulling adoption upward in urban service networks.
- Black Sea trade route access:Burgas port infrastructure enables cost-efficient raw material import for localized blending operations serving Balkan transit corridor demand.
Market Restraints
- Additive chemistry cost volatility:SAPS-compliant additive packages command premium input pricing, compressing blender margins on economy-tier formulations.
- Import dependency concentration:Base oil supply chains route through Romanian and Greek refining corridors, exposing Bulgarian formulators to transit disruption risk.
- Technical limitation in bio-based claims:BIS-equivalent conformity assessment procedures for bio-lubricant certification remain underdeveloped, blocking premium positioning for sustainable formulations.
Strategic Opportunities
- Underpenetrated Plovdiv industrial zone:Aging heavy-duty fleets in Bulgaria's second city operate on mineral oil drain intervals, creating white space for synthetic conversion programs.
- Channel innovation via fuel station partnerships:National petrol retail networks seek service bay differentiation through premium lubricant tie-ups, bypassing traditional garage distribution.
- Technology convergence in predictive maintenance:Oil condition monitoring systems paired with telematics platforms enable subscription-based lubricant supply models for commercial fleet operators.
Industry Challenges
- Formulation chemist scarcity:Bulgarian technical universities produce limited lubricant engineering specialists, forcing blenders to recruit from Romanian and Serbian talent pools.
- Certification timeline compression:OEM approval cycles for new engine architectures entering from EU assembly plants outpace local laboratory testing capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bulgaria Automotive Engine Oils Market |
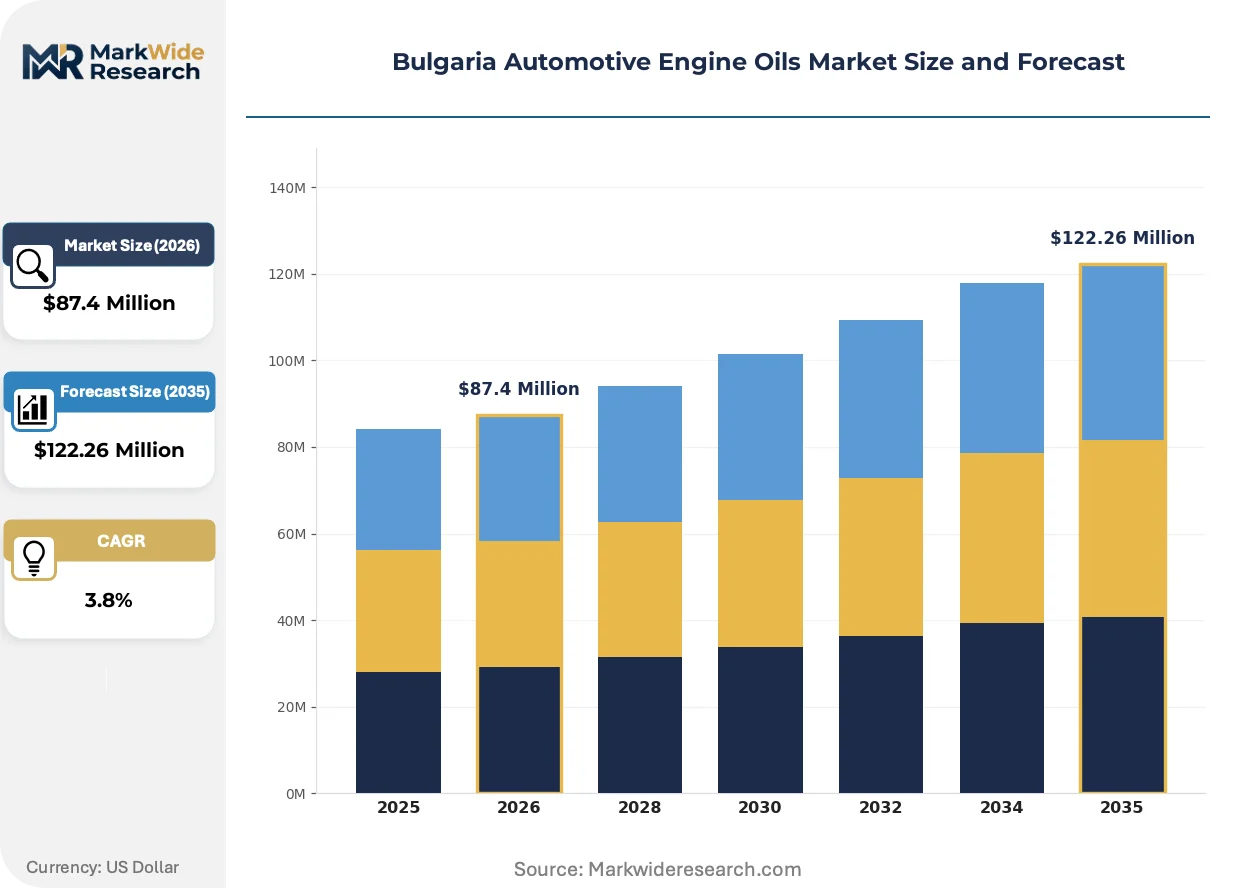
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $122.26 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mineral Oils, Synthetic Oils, Semi-Synthetic Oils, Bio-Based Oils End User: OEMs, Aftermarket Providers, Independent Garages, Vehicle Assemblers Application: Passenger Vehicles, Commercial Vehicles, Motorcycles, Heavy-Duty Vehicles Packaging Type: Drum, Bottle, Bag, Bulk |
| Companies Covered | Royal Dutch Shell Plc, Gazprom, BP PLC (Castrol), Motul, LIQUI MOLY, ExxonMobil Corporation, TotalEnergies, AVIA International, Prista Oil, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bulgaria Automotive Engine Oils Market Strategic Shifts
Formulation chemistry, compliance architecture, and procurement logic are simultaneously transforming how engine oils reach Bulgarian vehicle owners. Three distinct vectors are compressing legacy operating models.
Lower SAPS additive technology is collapsing the performance gap between premium synthetic and mid-tier mineral formulations. Independent garages in Sofia's service networks adopt these chemistries to satisfy EU emission inspection requirements without absorbing full synthetic pricing. The compression enables margin defense for mid-market blenders while eroding traditional tier differentiation.
REACH enforcement through ECHA guidance documents tightens allowable phosphorus and sulfur thresholds in lubricant formulations. Bulgarian environmental regulators apply these standards through national permitting procedures, pushing formulators toward Group III base oils. Heavy-duty fleet operators face accelerated compatibility testing for exhaust after-treatment systems.
Buyer concentration among national fuel station chains is consolidating aftermarket access points. These retailers negotiate direct supply agreements with multinational formulators, disintermediating traditional wholesale distributors. The Danube corridor corridor exhibits the most visible channel compression, with independent garages losing volume to integrated service bay operations.
Bulgaria Automotive Engine Oils Market Segmentation
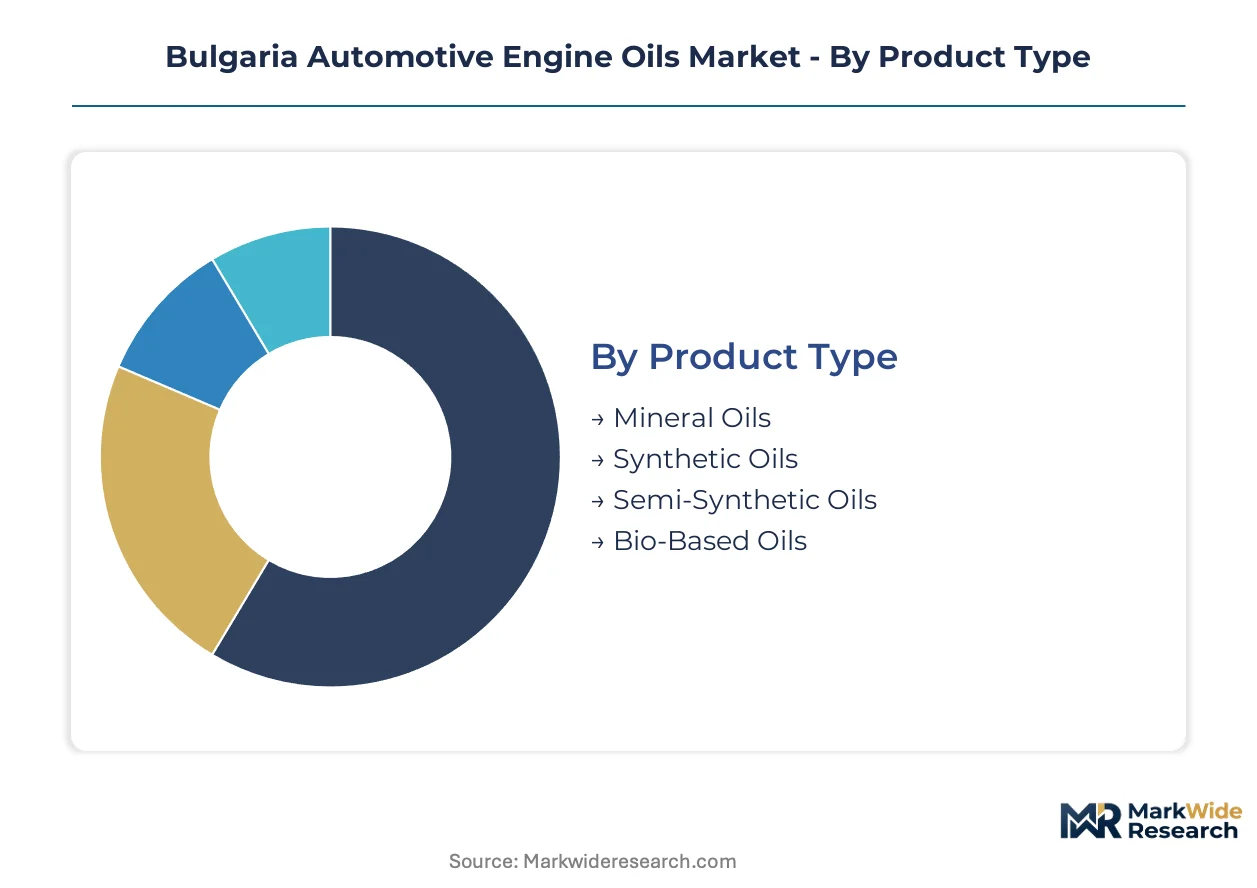
Engine oil segmentation in Bulgaria tracks divergent pressure points across formulation chemistry, procurement channels, and vehicle duty cycles. Understanding how demand fragments across these dimensions exposes where margin pools concentrate and where conversion opportunities remain underexploited.
Product Type:
Use-case spectrum spans from cost-driven mineral formulations in aging transit fleets to precision-engineered synthetics in EU-compliant passenger vehicles.
- Synthetic Oils:Group III and PAO-based formulations deliver thermal stability above 150°C and extended drain intervals. Sofia's premium service networks specify these chemistries for newer EU-sourced vehicles facing tightened emission inspection thresholds. REACH-compliant additive packages drive input cost premiums that compress blender margins.
- Mineral Oils:Solvent-refined base stocks dominate heavy-duty applications across the Balkan transit corridor. Burgas-based blenders serve Plovdiv industrial zone fleets operating on compressed maintenance budgets and shorter drain intervals.
- Semi-Synthetic Oils:Group II-plus formulations occupy the conversion zone between mineral and full synthetic tiers.
- Bio-Based Oils:Vegetable-derived base stocks face certification bottlenecks under BIS-equivalent conformity procedures, limiting premium positioning.
The dominant share belongs to Mineral Oils, while Synthetic Oils is closing the gap fastest.
End User:
Procurement concentration varies sharply between specification-driven OEM channels and price-sensitive independent service networks.
- Independent Garages:Sofia and Plovdiv service bays source through wholesale distributors or direct blender relationships, prioritizing inventory turns over brand loyalty. These operators face customer pressure to minimize service costs while satisfying EU emission inspection requirements.
- Aftermarket Providers:National fuel station chains negotiate direct supply agreements with multinational formulators, disintermediating traditional distribution layers. Danube corridor retailers integrate service bay operations to capture lubricant-plus-labor revenue.
- OEMs:Vehicle assemblers importing from EU plants specify approved lubricant chemistries for warranty compliance.
- Vehicle Assemblers:Limited domestic assembly operations create narrow demand concentration.
Aftermarket Providers command volume leadership, though Independent Garages retain the steepest expansion trajectory through network densification.
Application:
Vehicle duty cycles segment demand across thermal loading profiles and operating environment severity.
- Passenger Vehicles:Urban stop-start driving in Sofia and Plovdiv stresses oxidation stability requirements. Extended drain interval synthetics reduce total ownership cost for private owners, pulling adoption upward in dealer-affiliated service networks.
- Heavy-Duty Vehicles:Cross-border transit fleets operating through the Balkan corridor prioritize mineral oil economics over performance margins. Operators face accelerated compatibility testing for exhaust after-treatment systems under tightened inspection regimes.
- Commercial Vehicles:Light and medium-duty delivery fleets occupy intermediate specification territory.
- Motorcycles:Two-stroke and four-stroke formulations serve limited but specialized demand.
Passenger Vehicles holds the dominant position, with Heavy-Duty Vehicles expanding most quickly through fleet renewal cycles.
Packaging Type:
Logistics economics and consumption velocity determine format selection across the supply chain.
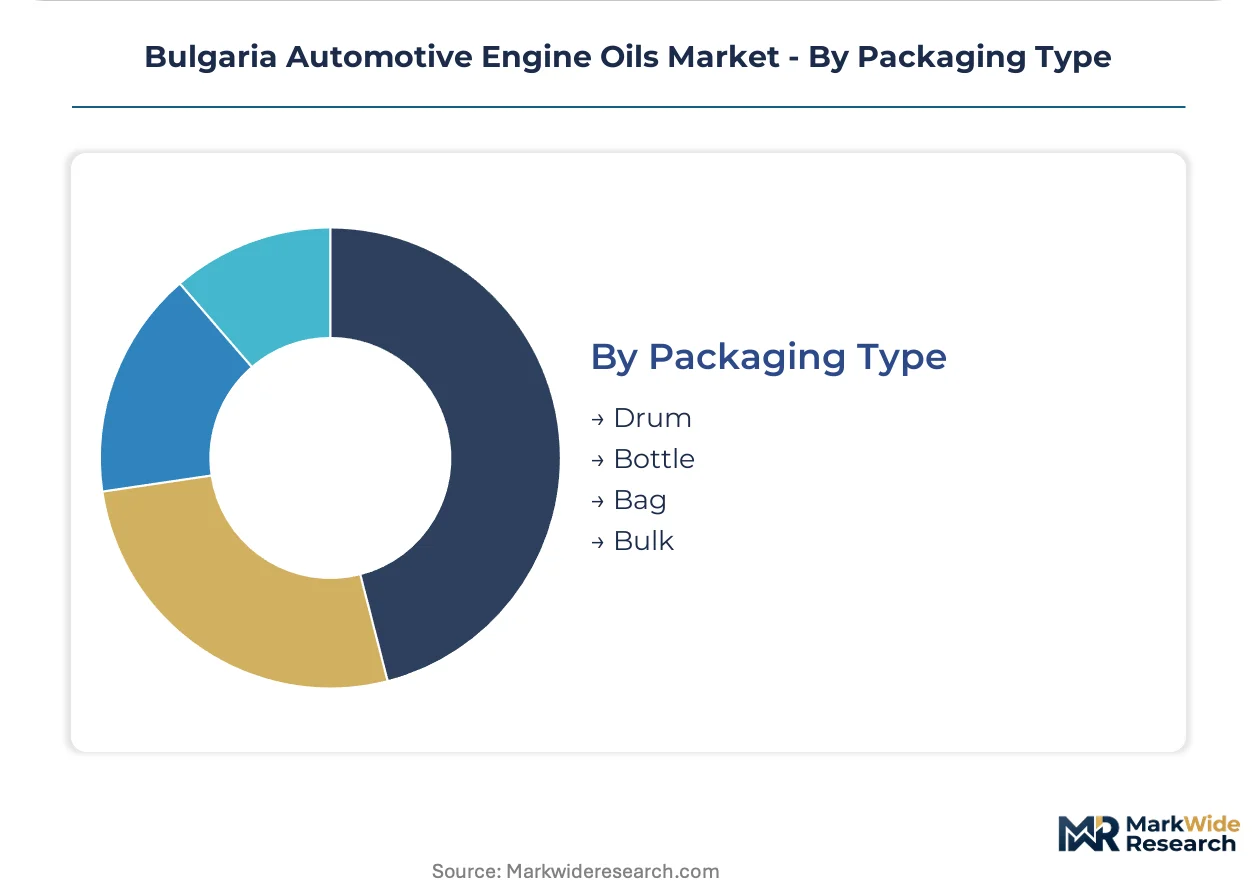
- Drum:200-liter steel containers serve high-volume fleet operators and industrial garages with predictable consumption rates. Burgas port infrastructure enables cost-efficient bulk import for localized drum filling operations.
- Bottle:Retail-format liters and four-liter containers dominate fuel station convenience sales and independent garage shelf stock.
- Bulk:Tanker-delivered volumes supply integrated service bay operations and large fleet depots.
- Bag:Flexible intermediate formats occupy niche applications with space-constrained storage.
Drum packaging leads industrial procurement, while Bottle formats gain share fastest through retail channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU structural funds and national vehicle inspection regimes are redistributing automotive engine oil demand across Bulgaria's economic geography. Sofia, Plovdiv, and Burgas anchor distinct procurement patterns shaped by fleet density, industrial activity, and port access.
Sofia Capital Region
Corporate fleet operators and premium passenger vehicle service networks concentrate demand for synthetic formulations. The Ministry of Transport's tightened emission inspection thresholds accelerate drain interval compression in urban commercial garages. Sofia's dealer-affiliated service bays specify OEM-approved chemistries for newer EU-sourced vehicles entering through western border corridors.
Plovdiv Industrial Zone
Aging heavy-duty transit fleets operating cost-sensitive Balkan routes sustain mineral oil volume leadership. Fleet managers face accelerated compatibility testing for exhaust after-treatment systems under national inspection regime tightening. Independent garages in Plovdiv's industrial periphery source through wholesale distributors prioritizing inventory velocity over brand loyalty.
Burgas Black Sea Port
Localized blending operations leverage port infrastructure for cost-efficient raw material import serving regional demand. The city's logistics clusters supply drum-format volumes to high-consumption fleet depots across southeastern Bulgaria. Burgas-based formulators compete on delivery velocity to industrial zones lacking direct rail connections to Romanian refining corridors.
Danube River Corridor
National fuel station chains consolidate aftermarket access points through integrated service bay operations. Retailers negotiate direct supply agreements with multinational formulators, disintermediating traditional wholesale distribution layers. Ruse and Pleven garage networks lose volume to convenience-driven motorists prioritizing single-stop service transactions.
Bulgaria Automotive Engine Oils Market Competitive Environment
On the supply side, the industry is tiered across multinational integrated oil companies, regional blending specialists, and national distribution networks. Three strategic archetypes dominate: technology licensors leveraging R&D scale, port-adjacent blenders optimizing logistics economics, and fuel retail integrators capturing convenience-driven demand. Competitive moves concentrate on strategic partnerships with national petrol networks and backward integration into base oil sourcing.
Among German-anchored formulators, LIQUI MOLY occupies the premium-tier technical positioning vector. Royal Dutch Shell Plc exemplifies fuel retail integration through national station chain partnerships. Prista Oil represents the port-adjacent regional blender archetype with Burgas-based operations.
| Leading Market Players |
|---|
| Royal Dutch Shell Plc |
| Gazprom |
| BP PLC (Castrol) |
| Motul |
| LIQUI MOLY |
| ExxonMobil Corporation |
| TotalEnergies |
| AVIA International |
| Prista Oil |
| Others |
Value Chain & Pricing Dynamics
Burgas port infrastructure anchors Bulgarian blending capacity, and its throughput dynamics directly shape downstream pricing power for formulators serving Sofia and Plovdiv service networks. REACH-compliant additive chemistry costs cascade through the value chain, compressing margins on economy-tier mineral formulations while defending premium synthetic positioning.
Pricing Analysis
Certification level (API SP/ILSAC GF-6) creates the primary spread between premium synthetics and mineral economy tiers. Three-tier pricing structure across premium, standard, and economy levels stratifies around drain interval performance and OEM approval status. Cost compression in mid-market semi-synthetics is intensifying because independent garages in Sofia's service networks adopt lower SAPS chemistries without absorbing full synthetic pricing. Heavy-duty fleet operators in the Balkan transit corridor exhibit highest price sensitivity, while dealer-affiliated service bays for EU-sourced passenger vehicles show lowest.
Supply Chain Analysis
Extended payment terms from Bulgarian blenders to Burgas port logistics providers reflect working capital constraints in a raw-material-import-dependent structure. Base oil supply concentrates in Romania, Greece, and regional Black Sea refining corridors. Formulation chemistry draws from German and Austrian additive specialists, with SAPS-compliant packages commanding premium input pricing. Single-source vulnerability runs through Romanian refining transit routes. Distribution runs through national fuel station chains disintermediating traditional wholesale layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bulgaria's automotive engine oils market sits at a high-growth inflection as EU REACH enforcement collapses available formulation space and forces rapid chemistry migration. This regulatory compression creates asymmetric opportunity for positioned players.
For Market Incumbents: Build certification moats around OEM approval cycles for new engine architectures entering from EU assembly plants. Deepen backward integration into base oil sourcing through Romanian refining corridor partnerships to defend margin position against additive cost volatility. Anchor channel control via exclusive supply agreements with national fuel station chains consolidating the Danube corridor aftermarket. For New Entrants and Emerging Players: Build out synthetic conversion programs targeting Plovdiv's aging heavy-duty fleets operating on mineral oil drain intervals. The underpenetrated industrial zone offers white space for extended-drain-interval formulations. Pursue technology convergence plays pairing oil condition monitoring with telematics platforms for subscription-based fleet supply models. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because REACH compliance costs disproportionately burden non-integrated blenders lacking scale. Target port-adjacent regional specialists with Burgas logistics positioning and established independent garage relationships. Watch ECHA guidance document releases tightening phosphorus and sulfur thresholds as the signal for accelerated consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Oil Sourcing | Secures supply from Romanian refining corridors against transit disruption risk. |
| Lower SAPS Formulation Development | Aligns with ECHA REACH enforcement protecting exhaust after-treatment systems. |
| Fuel Station Chain Partnership | Captures convenience-driven demand bypassing traditional garage distribution layers. |
| Predictive Maintenance Platform Integration | Enables subscription revenue models for commercial fleet operators in Sofia. |
| Port-Adjacent Blending Capacity Expansion | Leverages Burgas infrastructure for cost-efficient raw material import serving Balkan demand. |
Study Parameters
The analysis maps synthetic, mineral, semi-synthetic, and bio-based formulation tiers, each validated through blender operations managers, independent garage owners, fuel station chain procurement leads, and fleet maintenance directors across Sofia, Plovdiv, and Burgas. Primary fieldwork combined with secondary validation from customs trade records, EU ECHA guidance documents, and national vehicle registration databases. Bottom-up volume triangulation against top-down macroeconomic anchors ensured segmentation consistency.
Forecast assumptions held EU emission alignment trajectory and REACH enforcement timelines fixed while varying fleet renewal rates and synthetic adoption curves across the projection horizon. Modeled dimensions span formulation chemistry, procurement channel, vehicle duty cycle, and packaging format. CAGRs derived from regression analysis against vehicle parc aging and inspection regime tightening. Industry-specific inputs include drain interval compression rates and additive package cost trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Black Sea trade route competitors or accelerated bio-lubricant certification breakthroughs would shift outcomes. Macroeconomic volatility in Balkan transit freight, regulatory deviation from EU alignment timelines, or disruptive telematics platform entry would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Global Automotive Adaptive Suspension System Market
Automotive Parts
Automotive Tire Molds Market
Automotive Parts
Automotive Trailing Arm Market
Automotive Parts
Europe Automotive Parts Zinc Die Casting Market
Automotive Parts
Nigeria Commercial Vehicles Lubricants Market
Automotive Parts
Automotive Cooling Fan Market
Automotive Parts
Mexico Automotive Parts Aluminum Die Casting Market
Automotive Parts
Global Automotive Parts Remanufacturing Market
Automotive Parts
Steering Wheel Armature Market
Automotive Parts
Autocatalyst Market
Automotive Parts
Global Automotive Cooler Market
Automotive Parts
Industrial Bearings Market
Automotive Parts
Argentina Automotive Engine Oils Market
Automotive Parts
France Commercial Vehicles Lubricants Market
Automotive Parts
Automotive Piston System Market
Automotive Parts
Mechanical Performance Tuning Components Market