
 Hearables Market | 2026-2036
Hearables Market Size, Share, and Industry Trends Forecast 2026-2036
Hearables Market Intelligence
Embedded firmware engineering talent scarcity is redrawing competitive boundaries in the hearables sector. Apple leverages its silicon design ecosystem to sustain end-to-end hardware-software control. Samsung Electronics anchors its position through manufacturing scale across multiple product tiers. Sony Corporation differentiates via acoustic engineering heritage and studio-grade codec support.
Hearables are wearable audio devices integrating miniature transducers, Bluetooth radios, and biometric sensors into ear-worn form factors, typically operating on 2.4 GHz ISM bands with power budgets under 50 milliwatts per earbud for all-day use. Their primary commercial purpose spans music reproduction, voice communication, health monitoring, and augmented hearing assistance. True wireless configurations now lead volume shipments while active noise cancellation technology commands the dominant margin pool. Fitness tracking applications within the application dimension are expanding fastest as optical heart rate and SpO2 sensors migrate from wrist-worn to ear-worn platforms.
FCC certification requirements govern radio emissions for US market entry while CE marking under the EU Radio Equipment Directive shapes European product compliance pathways. China's MIIT enforces SRRC type approval for wireless transmission modules, creating a three-jurisdiction testing burden for global launches. FDA oversight of hearing-aid-classified devices increasingly overlaps with consumer hearables as manufacturers blur the prescription and direct-to-access boundaries. Stakeholders must monitor how health-claim regulatory boundaries evolve as biometric accuracy becomes a marketing and liability battleground.
Market Dynamics
AI-driven adaptive audio algorithms are compressing development cycles and redefining how manufacturers differentiate premium from standard tiers, forcing firmware engineering talent into acute scarcity.
Growth Catalysts
- FCC Part 15 Certification:Clear radio emission standards in the United States reduce time-to-market uncertainty for Bluetooth Low Energy devices, accelerating enterprise procurement cycles.
- Remote Professional End-Use:Distributed workforces require voice-assistance-enabled devices for virtual collaboration, expanding commercial demand beyond consumer music applications.
- Optical Biometric Migration:SpO2 and heart rate sensors moving from wrist-worn to ear-worn platforms is opening health-monitoring revenue streams.
Market Restraints
- Tri-Jurisdiction Testing Burden:FCC, CE marking under EU Radio Equipment Directive, and MIIT SRRC type approval create redundant certification costs for global launches.
- Firmware Engineering Concentration:Embedded audio processing expertise clusters in Germany, the United States, and South Korea, creating hiring bottlenecks.
- Hearing Aid Substitution Threat:FDA-regulated prescription devices compete for the same augmented hearing use case with superior reimbursement pathways.
Strategic Opportunities
- India Manufacturing Incentives:PLI scheme subsidies for electronics assembly attract hearables production away from traditional coastal China concentration.
- Clinical Trial Data Monetization:Biometric accuracy validation creates defensible IP for direct-to-consumer hearing health claims.
- Augmented Reality Convergence:Spatial audio processing combined with head-tracking sensors enables immersive enterprise training applications.
Industry Challenges
- Health-Claim Liability Exposure:FDA oversight overlap with consumer devices creates marketing compliance complexity as biometric accuracy becomes a litigation vector.
- Legacy Audio Codec Fragmentation:Multiple proprietary and open-source standards complicate interoperability testing and firmware bloat.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hearables Market |
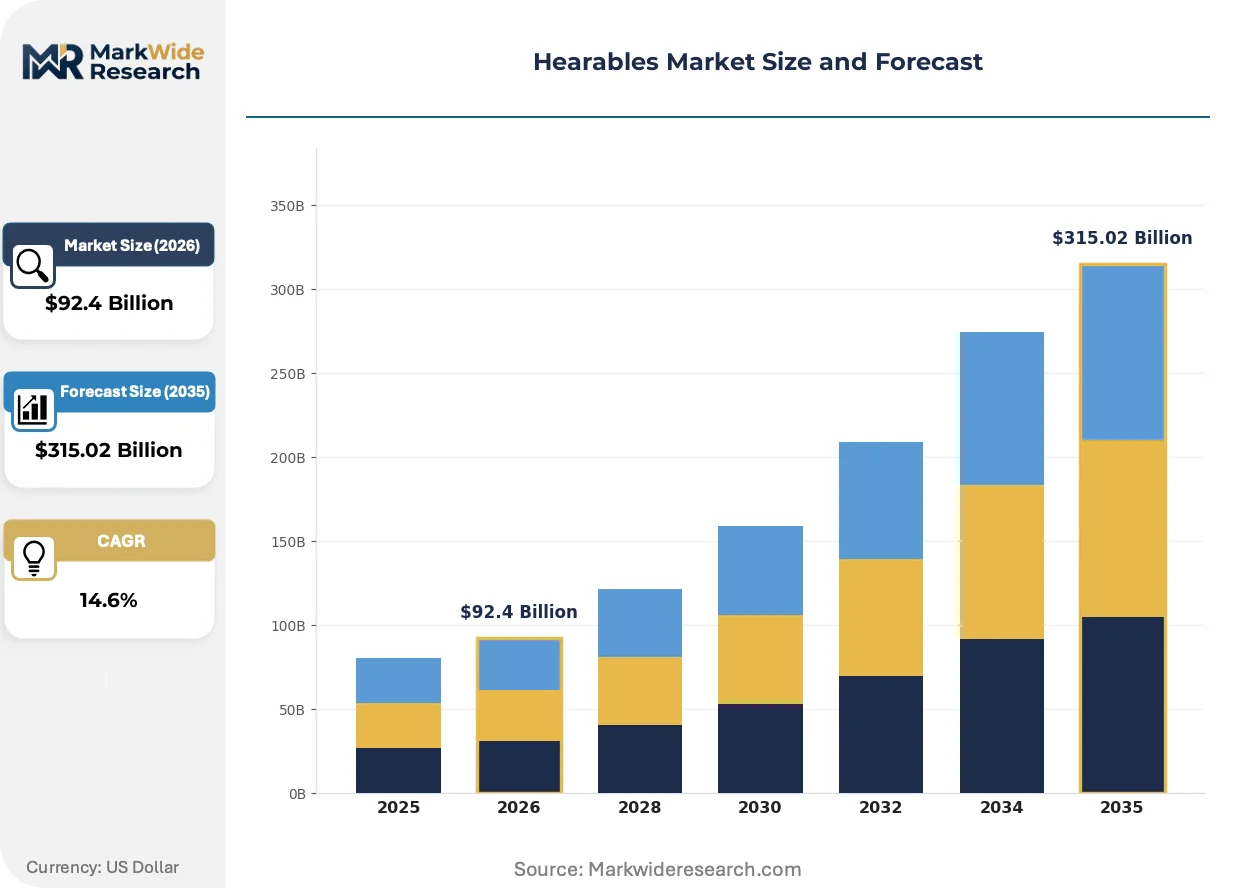
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $315.02 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: True Wireless, Wired Earbuds, Over-Ear, In-Ear Technology: Bluetooth, Active Noise Cancellation, Voice Control, Touch Sensors End User: Consumers, Fitness Enthusiasts, Gamers, Professionals Application: Music Streaming, Fitness Tracking, Voice Assistance, Gaming |
| Companies Covered | Bose Corporation, Sennheiser Electronic GmbH & Co. KG, Apple Inc., Starkey Hearing Technologies, WS Audiology, Samsung Electronics, Jabra (GN Store Nord A/S), Xiaomi, Sony Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hearables Market Strategic Shifts & Innovations
Silicon design autonomy and on-device machine learning are redrawing competitive boundaries, compressing the gap between component suppliers and finished-device brands.
On-device neural processing units for real-time noise suppression is supplanting cloud-dependent voice recognition in premium hearables. Enterprise buyers with data sovereignty requirements are accelerating adoption. This shift compresses dependence on third-party AI platforms and protects sensitive voice data.
EU AI Act risk classification for biometric identification systems is forcing health-claim documentation standards. Manufacturers must maintain algorithmic transparency records. Fitness-tracking hearables with SpO2 monitoring face heightened conformity assessment burdens.
Direct-to-consumer hearing health screening is disrupting traditional audiology channel structures. Telehealth platforms are bundling hearables with remote diagnostic services. Germany and the United States show the fastest channel reconfiguration as prescription-device boundaries blur.
Hearables Market Segmentation
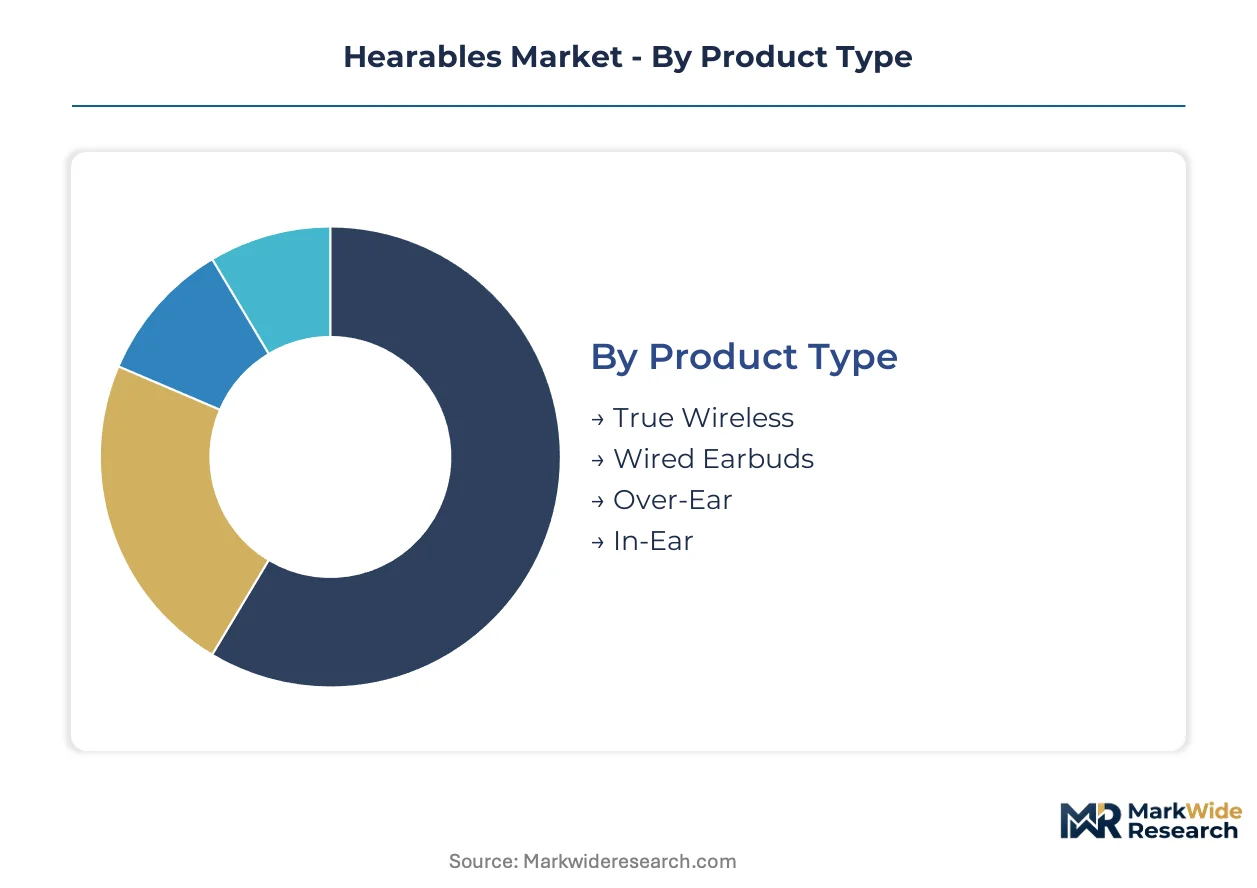
Segmentation in hearables reveals how margin pools shift between audio performance tiers and biometric-enabled health applications. Manufacturers configure product roadmaps around distinct certification requirements and end-use specifications that reshape component sourcing strategies.
Product Type:
Margin concentration sits with configurations integrating active noise cancellation and optical biometric sensors, where component integration complexity sustains premium pricing power.
- True Wireless:Completely untethered ear-worn devices operating on Bluetooth Low Energy with independent power management per earbud. Demand concentrates among remote professionals in the United States and Germany where FCC Part 15 and CE marking compliance enables enterprise procurement at scale. Active noise cancellation and voice-assistance integration command the dominant margin pool as firmware engineering scarcity limits competitive entry.
- Over-Ear:Circumaural designs housing larger acoustic drivers and extended battery enclosures for studio-grade reproduction and immersive gaming applications. Demand concentrates in China and Germany where audiophile end-users and esports professionals drive replacement cycles for high-impedance driver configurations and spatial audio processing.
- In-Ear:Canal-sealing designs optimized for acoustic isolation and biometric sensor proximity to vascular tissue. Fitness enthusiasts in the United States drive adoption for SpO2 and heart rate monitoring during high-intensity training.
- Wired Earbuds:Passive analog designs relying on device-hosted DACs and amplifiers for signal processing. Budget-conscious consumer segments and legacy device compatibility requirements sustain residual volume in price-sensitive geographies.
True Wireless holds installed capacity. Over-Ear is rotating up the share rankings.
Technology:
Cost tier differentiation separates premium devices with on-device neural processing from standard tiers dependent on cloud-dependent voice recognition architectures.
- Active Noise Cancellation:Hybrid feedforward-feedback microphone arrays with real-time DSP processing to generate anti-phase acoustic cancellation. Enterprise buyers in Germany with data sovereignty requirements accelerate adoption of on-device processing variants that eliminate cloud voice data transmission. This technology commands the steepest expansion trajectory as hybrid work policies institutionalize virtual collaboration infrastructure.
- Bluetooth:2.4 GHz ISM band radio implementations spanning Classic, Low Energy, and LE Audio protocols with LC3 codec support. Volume shipments concentrate in China where MIIT SRRC type approval and manufacturing scale economics enable cost-optimized module sourcing.
- Voice Control:Natural language processing pipelines for hands-free device operation and virtual assistant integration. Professionals in the United States drive demand for multi-language wake-word recognition in distributed workforce deployments.
- Touch Sensors:Capacitive and force-sensitive input surfaces for gesture-based playback and call control. Consumer preference for haptic feedback interfaces sustains adoption across mid-tier product configurations.
Bluetooth holds installed capacity. Active Noise Cancellation is rotating up the share rankings.
End User:
Application intensity varies sharply across user profiles, with biometric accuracy requirements and battery endurance specifications reshaping component selection priorities.
- Professionals:Voice-assistance-enabled devices for virtual collaboration, call clarity optimization, and multi-point Bluetooth connectivity across workstation and mobile endpoints. Remote professionals in the United States and Germany drive replacement cycles as enterprise IT departments standardize on certified devices for HIPAA and GDPR compliance.
- Fitness Enthusiasts:Optical heart rate and SpO2 monitoring with sweat-resistant IP ratings and secure fit mechanics for high-motion activities. Demand concentrates in the United States where direct-to-consumer health screening applications disrupt traditional wrist-worn wearable categories.
- Gamers:Low-latency wireless protocols, spatial audio processing, and boom-microphone configurations for team communication. Esports professionals in China and Germany drive adoption of sub-20ms latency implementations.
- Consumers:General-purpose music reproduction and casual voice communication without specialized biometric or gaming optimizations. Price sensitivity and brand loyalty dynamics dominate purchase decisions in mass-market distribution channels.
Consumers hold installed capacity. Professionals is rotating up the share rankings.
Application:
Volume concentration remains with entertainment use cases while health-monitoring applications gain share fastest as sensor migration from wrist-worn platforms accelerates.
- Fitness Tracking:Continuous physiological monitoring including heart rate variability, SpO2, and core temperature estimation through optical photoplethysmography. Fitness enthusiasts in the United States and Germany drive adoption as telehealth platforms bundle hearables with remote diagnostic services, expanding fastest among all application categories.
- Music Streaming:High-fidelity audio reproduction with codec support for lossless and spatial audio formats. Audiophile consumers in China and Germany sustain demand for LDAC and aptX Adaptive implementations.
- Voice Assistance:Hands-free virtual assistant access and real-time translation services. Enterprise procurement in the United States accelerates deployment for productivity workflow integration.
- Gaming:Immersive spatial audio with head-tracking sensors and low-latency wireless connectivity. Esports professionals in China drive specifications for competitive advantage in tournament environments.
Music Streaming holds installed capacity. Fitness Tracking is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC Part 15 certification anchors the United States as the regulatory benchmark for Bluetooth Low Energy device market entry. Enterprise procurement cycles accelerate where radio emission standards reduce compliance uncertainty.
United States
Remote professionals drive replacement cycles for voice-assistance-enabled devices as enterprise IT departments standardize on certified hardware for HIPAA compliance. FDA oversight increasingly overlaps with consumer hearables as prescription and direct-to-access boundaries blur. Austin and Boston clusters concentrate firmware engineering talent for adaptive audio algorithm development.
China
Manufacturing scale economics enable cost-optimized Bluetooth module sourcing for global volume shipments. MIIT enforces SRRC type approval for wireless transmission modules, creating testing burdens for export-bound production. Shenzhen and Dongguan house integrated assembly ecosystems spanning component sourcing to finished-device packaging.
Germany
Audiophile end-users and enterprise buyers with data sovereignty requirements accelerate adoption of on-device processing variants. CE marking under the EU Radio Equipment Directive shapes European compliance pathways for regional market entry. Berlin and Munich clusters concentrate embedded audio processing expertise.
South Korea
Silicon design ecosystems sustain end-to-end hardware-software control for premium tier differentiation. MFDS regulatory frameworks govern health-claim classifications as biometric sensors migrate to ear-worn platforms. Seoul Capital Area anchors manufacturing scale across multiple product tiers.
India
PLI scheme subsidies for electronics assembly attract production diversification away from traditional coastal China concentration. BIS certification requirements create domestic market entry protocols for imported wireless devices. Karnataka and Tamil Nadu states host expanding contract manufacturing facilities for export-bound assembly.
Hearables Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with silicon autonomy and manufacturing scale as the primary dividing lines. The upper tier commands premium pricing through captive chip design and firmware ecosystems, while mid-tier players compete on manufacturing velocity and channel reach. Two strategic archetypes dominate: vertically integrated technology conglomerates with semiconductor divisions, and acoustic engineering specialists with studio-grade heritage. Competitive moves concentrate on strategic partnerships for AI algorithm licensing and geographic expansion into India under PLI incentives.
Within the integrated technology tier, Apple Inc. and Samsung Electronics exemplify silicon design autonomy as a defensive moat, while Sony Corporation occupies a position bridging acoustic engineering heritage with consumer electronics scale. Bose Corporation and Sennheiser Electronic GmbH & Co. KG represent the specialist archetype, anchoring premium positioning through transducer craftsmanship and professional audio credibility. Jabra, operating under GN Store Nord A/S, sits within the enterprise-focused vector where HIPAA and GDPR compliance certification drives procurement decisions.
| Leading Market Players |
|---|
| Bose Corporation |
| Sennheiser Electronic GmbH & Co. KG |
| Apple Inc. |
| Starkey Hearing Technologies |
| WS Audiology |
| Samsung Electronics |
| Jabra (GN Store Nord A/S) |
| Xiaomi |
| Sony Corporation |
| Others |
Cost & Logistics Intelligence
Sixty-day lead times for Bluetooth Low Energy module procurement concentrate pricing power with integrated silicon designers in South Korea and the United States, while contract manufacturers in coastal China absorb margin compression through volume scale. This inventory dynamic separates premium tier pricing anchored in firmware autonomy from standard tier competition fought on assembly velocity and component sourcing arbitrage.
Pricing Analysis
Geographic price spreads between German audiophile markets and Indian mass-market channels exceed threefold for equivalent driver configurations, with CE marking and BIS certification tiers creating quality-grade differentiation. Three-tier pricing structure across premium, standard, and economy levels separates active noise cancellation with on-device neural processing from cloud-dependent voice recognition variants and basic Bluetooth implementations. Cost compression in the economy tier intensifies as Shenzhen-based module suppliers consolidate, while enterprise buyers in Germany show lowest price sensitivity due to HIPAA and GDPR compliance requirements. Fitness enthusiasts in the United States demonstrate highest price sensitivity for biometric-enabled configurations where wrist-worn wearable alternatives compete.
Supply Chain Analysis
Forty-five days of inventory coverage for optical biometric sensors reflects single-source vulnerability as manufacturing concentrates in China, South Korea, and Taiwan for MEMS microphones and neural processing units. The supply chain draws from rare earth magnet suppliers in China for miniature transducer assemblies, lithium-ion cell producers in South Korea for power management, and German precision acoustic component specialists for high-impedance driver configurations. Tariff exposure runs through MIIT SRRC certification requirements that fragment global production footprints. Distribution runs through enterprise IT procurement channels in the United States and Germany, direct-to-consumer telehealth platforms, and mass-market electronics retail in China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hardware margins compress toward commodity levels while firmware licensing and hearing health subscription services expand faster than device shipments, creating service-attach economics that favor captive ecosystem control over unit volume capture.
For Market Incumbents: Compound defensive positioning through backward integration into neural processing unit design and exclusive algorithm licensing agreements that raise switching costs for enterprise procurement. Firmware engineering scarcity in Austin and Boston clusters threatens margin sustainability as talent competition intensifies. Priority investment in FDA 510(k) pathway preparation for direct-to-consumer hearing health claims creates regulatory moats against prescription device substitution.
For New Entrants and Emerging Players: FCC Part 15 certification fast-track enables rapid market entry for voice-assistance-enabled devices targeting remote professional segments in the United States where enterprise standardization creates procurement pull-through. White-space concentrates in India PLI scheme manufacturing incentives and clinical trial data monetization for biometric accuracy validation. Go-to-market leverage through telehealth platform bundling disrupts traditional audiology channel structures faster than direct retail competition.
For Investors and Strategic Acquirers: Carve-out targets emerge from acoustic engineering specialists with studio-grade heritage but limited silicon autonomy, where firmware talent scarcity erodes standalone viability within a five-to-ten year horizon. Acquisition focus centers on embedded audio processing boutiques in Berlin and Munich with EU AI Act compliance documentation already established. Signal to watch is FDA enforcement action on consumer hearables making unsubstantiated hearing health claims, which would accelerate prescription-device boundary clarification and channel reconfiguration.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Design Autonomy Investment | Captive neural processing unit development eliminates cloud dependency for enterprise data sovereignty requirements. |
| Clinical Trial Data Monetization | Biometric accuracy validation creates defensible IP for direct-to-consumer hearing health claims against FDA scrutiny. |
| India PLI Scheme Manufacturing Expansion | Production subsidies attract assembly diversification away from coastal China concentration for export-bound volume. |
| EU AI Act Compliance Documentation | Algorithmic transparency records for biometric identification systems preempt heightened conformity assessment burdens. |
| Telehealth Platform Partnership | Remote diagnostic service bundling disrupts traditional audiology channel structures in Germany and the United States. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FCC equipment authorization databases, MIIT SRRC type approval registries, and EU Medical Device Regulation guidance documents. Primary interviews engaged embedded firmware engineering directors, enterprise IT procurement officers, biomedical sensor specialists, and telehealth platform executives across the United States, Germany, and China. Secondary validation incorporated Bluetooth SIG specification releases, FDA 510(k) clearance databases, and customs trade flow records. Bottom-up component cost modeling and top-down market sizing triangulate volume and value estimates.
Segmentation dimensions modeled include product configuration, processing architecture, biometric sensor integration, end-user application intensity, and regional regulatory cluster across the analysis window. CAGRs derive from installed base replacement cycles, enterprise procurement standardization trajectories, and sensor migration patterns from wrist-worn to ear-worn platforms. Industry-specific inputs incorporate Bluetooth Low Energy protocol adoption curves, active noise cancellation DSP licensing rates, and optical photoplethysmography accuracy validation costs.
Underlying assumptions cover sustained enterprise remote work infrastructure investment, stable tri-jurisdiction certification cost structures, and gradual FDA prescription-device boundary clarification, with deviation risk concentrated in firmware engineering talent availability and EU AI Act enforcement timing. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Sunflower Husk Pellets Market
Others
Fresh Apples Market
Others
Communication Base Station Body Market
Others
Europe Polycarbonate Sheets Market
Others
Global OTA Testing Market
Others
Paper Shredder Market
Others
Duty Free Retail Market
Others
Brazil Cane Sugar Market
Others
Stand-Up Pouch Valves Market
Others
Air Separation Module Kit Market
Others
South Korea Intellectual Property Market
Others
Europe Smart Homes Market
Others
Workbench Tanks Market
Others
Server Market
Others
Vacuum Evaporators Market
Others
Advanced Fiber-Based Gasket Market