
 US Luxury Travel Market | 2026-2036
US Luxury Travel Market Size, Share, and Industry Trends Forecast 2026-2036
US Luxury Travel Market Insights
Ultra-premium experiential tiers are reorganizing competitive dynamics in US luxury travel. Abercrombie & Kent leverages decades of expedition expertise to dominate polar and safari itineraries. Fischer Travel sustains its position through extreme discretion and bespoke service for billionaires. Elite Global Journeys differentiates via deep specialization in multi-generational family voyages.
Luxury travel in the United States encompasses curated, high-service journeys priced above mass-market thresholds, typically incorporating private transportation, exclusive lodging, and personalized itinerary design with 24/7 concierge support. Its commercial purpose centers on transforming discretionary wealth into memorable, status-affirming experiences that command premium pricing. Adventure travel and wellness retreats represent the fastest-expanding experience categories as affluent Americans prioritize health optimization and physical challenge. Exclusive resorts anchor the largest margin pools within service types due to extended stays and ancillary spending on spas, dining, and private excursions.
The FAA regulates private aviation safety standards that directly shape itinerary feasibility and regional accessibility for luxury operators. The FTC monitors advertising claims in travel marketing, while state-level hospitality codes in California, Florida, and New York enforce accommodation standards that define baseline luxury thresholds. Stakeholders must track evolving TSA protocols for private terminal screening and anticipate how municipal short-term rental restrictions in gateway cities could constrain exclusive lodging supply.
Market Dynamics
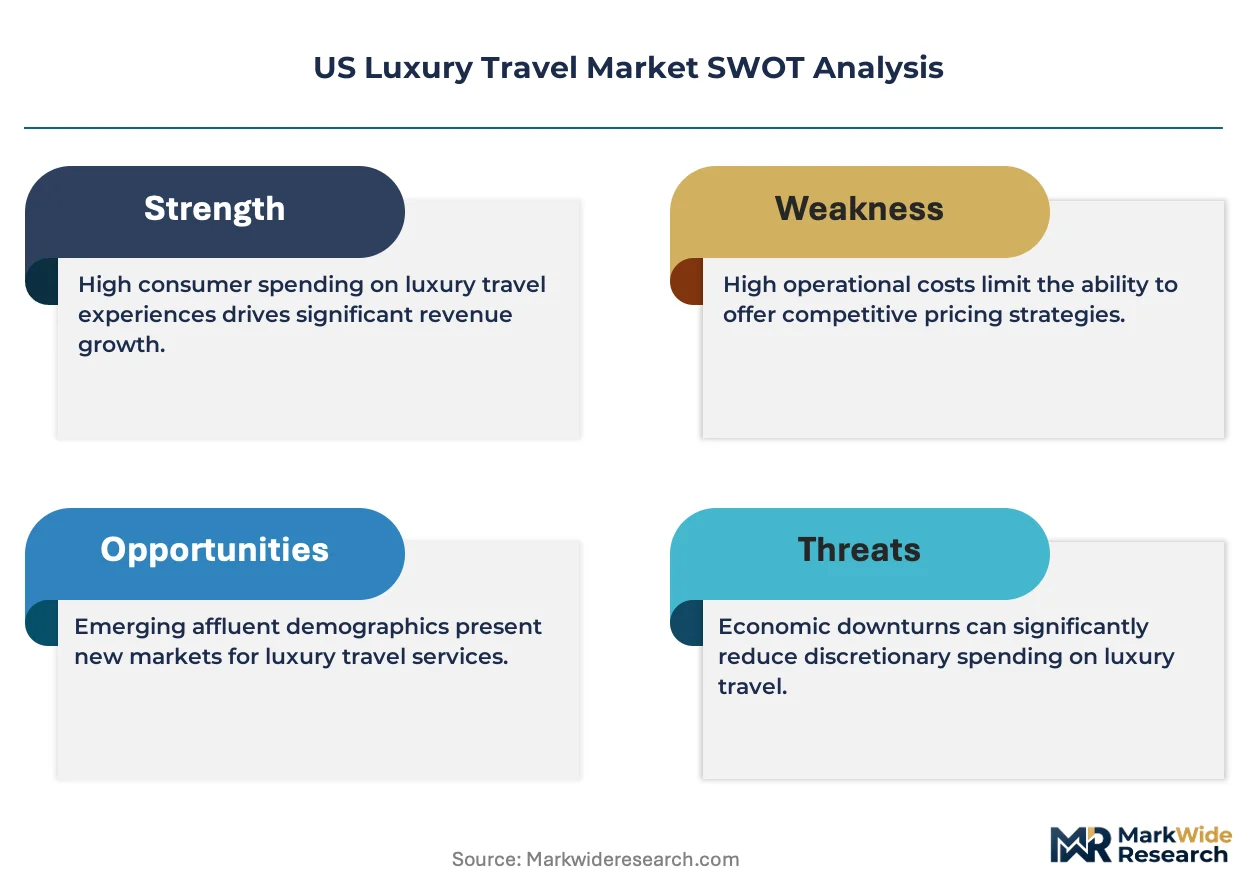
Ultra-high-net-worth individuals are redirecting discretionary wealth toward curated experiential journeys, compressing booking lead times while demanding granular personalization. This behavioral pivot is restructuring operator economics around concierge density and itinerary exclusivity rather than volume throughput.
Growth Catalysts
- FAA Modernization Initiatives:Upgraded private aviation infrastructure reduces point-to-point friction for remote destination access. Luxury operators leverage expanded general aviation capacity to reach secondary markets previously inaccessible via commercial routes.
- California-Florida-New York Affluent Clustering:Metropolitan gateway cities concentrate demand density within three-hour flight radii of premium resorts and private terminals. Operators optimize hub-and-spoke logistics around these population centers.
- Wellness Technology Integration:Biohacking protocols and longevity diagnostics are embedding into retreat programming. Properties invest in on-site medical partnerships and personalized health optimization tracks.
Market Restraints
- Jet Fuel Price Volatility:Private aviation fuel constitutes 35-45% of charter operating costs. Operators face margin compression during supply shocks without contractual pass-through mechanisms.
- California Coastal Development Restrictions:Municipal zoning in Malibu, Carmel, and Napa Valley constrains new ultra-luxury lodging supply. Existing properties capture scarcity rents while expansion remains permit-constrained.
- Pilot Certification Bottlenecks:FAA Part 135 operator staffing requirements limit fleet scaling. Training pipeline delays extend crew recruitment cycles for specialized aircraft categories.
Strategic Opportunities
- Multi-Generational Family Voyages:Operators design age-differentiated activity tracks within unified itineraries. This segment commands extended booking windows and higher per-capita ancillary spend.
- IRA Clean Energy Tax Credits:Sustainable aviation fuel investments and property renewable retrofits qualify for federal incentives. Forward-integrated operators capture operational cost reductions plus marketing differentiation.
- Private Terminal Channel Expansion:TSA PreCheck-equivalent screening protocols at fixed-base operators streamline security friction. Partnerships with Signature Flight Support and Atlantic Aviation extend reach.
Industry Challenges
- Concierge Talent Scarcity:Bilingual, culturally fluent itinerary designers command premium compensation. Boutique operators lose staff to larger hospitality groups with equity participation structures.
- Property Management System Integration:Legacy reservation platforms lack API connectivity with private aviation booking engines. Middleware development requires specialized technical investment without immediate revenue attribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Luxury Travel Market |
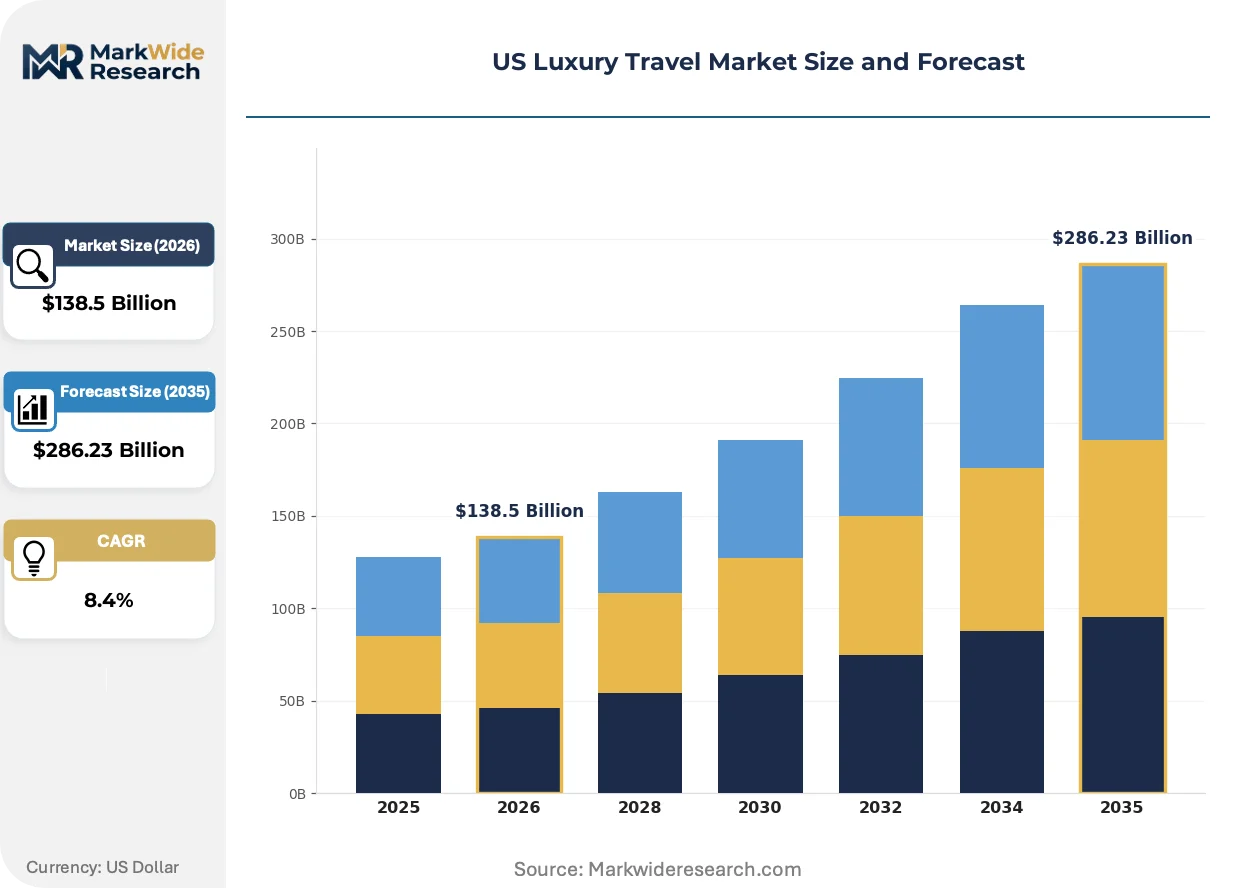
| Market Size in 2026 | $138.5 Billion |
| Market Size in 2035 | $286.23 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Luxury Cruises, Private Yacht Charters, Luxury Train Travel, Exclusive Resorts Customer Type: Affluent Families, Honeymooners, Business Travelers, Solo Travelers Booking Channel: Direct Booking, Travel Agencies, Online Travel Platforms, Concierge Services Travel Experience: Adventure Travel, Cultural Tours, Wellness Retreats, Culinary Experiences |
| Companies Covered | Scott Dunn, D.A. Luxury Travel, Elite Global Journeys, MK Luxury Travel, Avant-Garde Travel, Fischer Travel, Easy Escapes Travel, Magma Global, Abercrombie & Kent, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Luxury Travel Market Trends and Innovations
Artificial intelligence and biometric authentication are compressing friction points across the luxury journey, from predictive preference modeling to seamless terminal passage. These technologies are redistributing value capture between operators who own the data layer and those merely executing physical service delivery.
Dynamic pricing algorithms are bifurcating revenue management strategies across the sector. Large operators deploy machine-learning models that adjust rates in real-time based on competitor availability, demand signals, and guest lifetime value scores. Smaller boutiques resist algorithmic transparency, preserving opacity as a differentiation mechanism. The technology is compressing margin for mid-tier properties while enabling premium capture at the extremes.
FTC guidelines on influencer marketing disclosures are tightening enforcement around aspirational travel content. The regulator now requires explicit material connection statements for hosted stays and gifted experiences. California-based operators face the strictest interpretation, with state attorneys general pursuing deceptive advertising claims against properties using undisclosed compensated testimonials. Compliance investments are diverting marketing budget from content production to legal review.
Family office direct booking is displacing traditional travel advisor intermediaries for ultra-high-net-worth segments. Wealth management firms are hiring in-house travel specialists or acquiring boutique agencies to capture advisory fees. This channel shift concentrates demand among operators with institutional sales infrastructure. The pattern is most visible in New York and Miami, where single-family offices maintain dedicated lifestyle management functions.
US Luxury Travel Market Segmentation
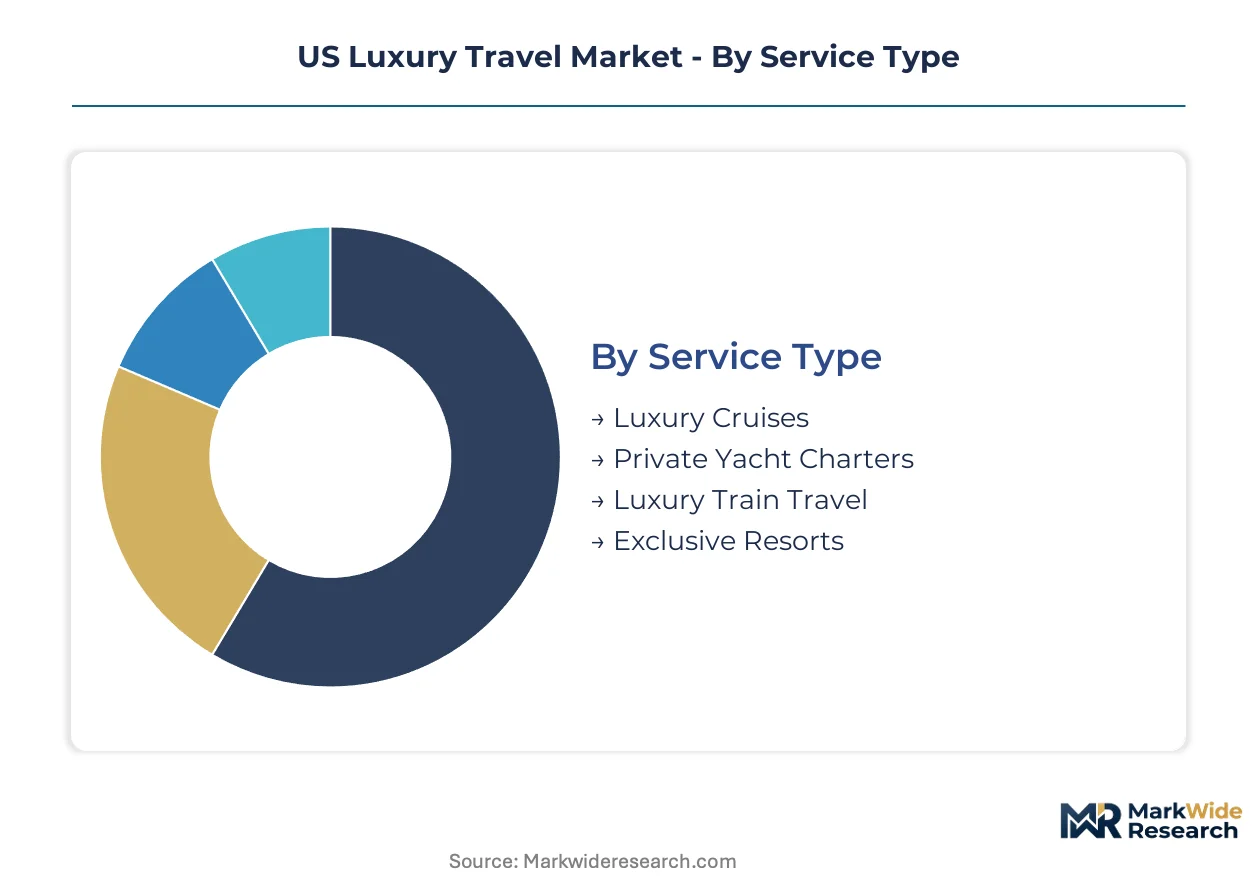
Luxury travel operators calibrate inventory and staffing around distinct service configurations, traveler psychographics, and procurement pathways. Segment-level profitability varies dramatically across these dimensions, with direct-booking wellness properties commanding margin premiums while agency-dependent cruise lines absorb intermediary commissions.
Service Type:
Exclusive Resorts and Private Yacht Charters concentrate demand among domestic ultra-high-net-worth individuals, while Luxury Train Travel and Luxury Cruises draw significant international visitation to US gateway markets.
- Exclusive Resorts:Extended-stay properties in Napa Valley, the Hamptons, and Aspen anchor the highest ancillary spend pools. California and Florida coastal municipalities constrain new supply through zoning, entrenching scarcity pricing at established properties.
- Private Yacht Charters:Vessel categories range from 80-foot day cruisers to 200-plus-foot expedition yachts with helicopter capacity. Miami and Fort Lauderdale function as primary embarkation hubs for Caribbean and Bahamian itineraries.
- Luxury Cruises:Small-ship expedition vessels carrying under 200 passengers dominate the US premium tier, accessing remote Alaskan and Pacific Northwest waterways.
- Luxury Train Travel:Rocky Mountaineer and private car services on Amtrak heritage routes serve nostalgic affluent segments.
Exclusive Resorts commands the established base. The steepest expansion runs through Private Yacht Charters.
Customer Type:
Affluent Families generate the longest booking windows and highest per-capita spend, while Solo Travelers compress lead times and prioritize flexibility over loyalty program attachment.
- Affluent Families:Multi-generational voyages require age-differentiated activity tracks within unified itineraries. Operators design separate programming for children, parents, and grandparents at shared destinations.
- Business Travelers:Bleisure extensions blend corporate obligations with leisure components, particularly in New York and Los Angeles where C-suite schedules accommodate compressed luxury experiences.
- Honeymooners:Celebration-oriented bookings concentrate in Maldives, Bora Bora, and Italian lake districts despite US operator intermediation.
- Solo Travelers:Female-led solo luxury travel is expanding fastest, with dedicated single-occupancy cabin inventory on expedition vessels and group departure structures that mitigate security concerns.
Affluent Families commands the established base. The steepest expansion trajectory belongs to Solo Travelers.
Booking Channel:
Direct Booking and Concierge Services capture the highest lifetime value travelers, while Online Travel Platforms and Travel Agencies serve acquisition and fill-in functions respectively.
- Concierge Services:Family offices and wealth management firms employ in-house travel specialists who bypass traditional agency structures. New York and Miami single-family offices maintain dedicated lifestyle management functions.
- Direct Booking:Operator-owned digital platforms capture guest preference data for predictive personalization. Properties invest in CRM infrastructure to reduce intermediary dependency.
- Travel Agencies:Virtuoso and Signature Travel Network members retain relevance for complex multi-destination itineraries requiring specialized expertise.
- Online Travel Platforms:Luxury tier penetration remains limited due to rate parity constraints and brand positioning conflicts.
Travel Agencies commands the established base. The steepest expansion runs through Concierge Services.
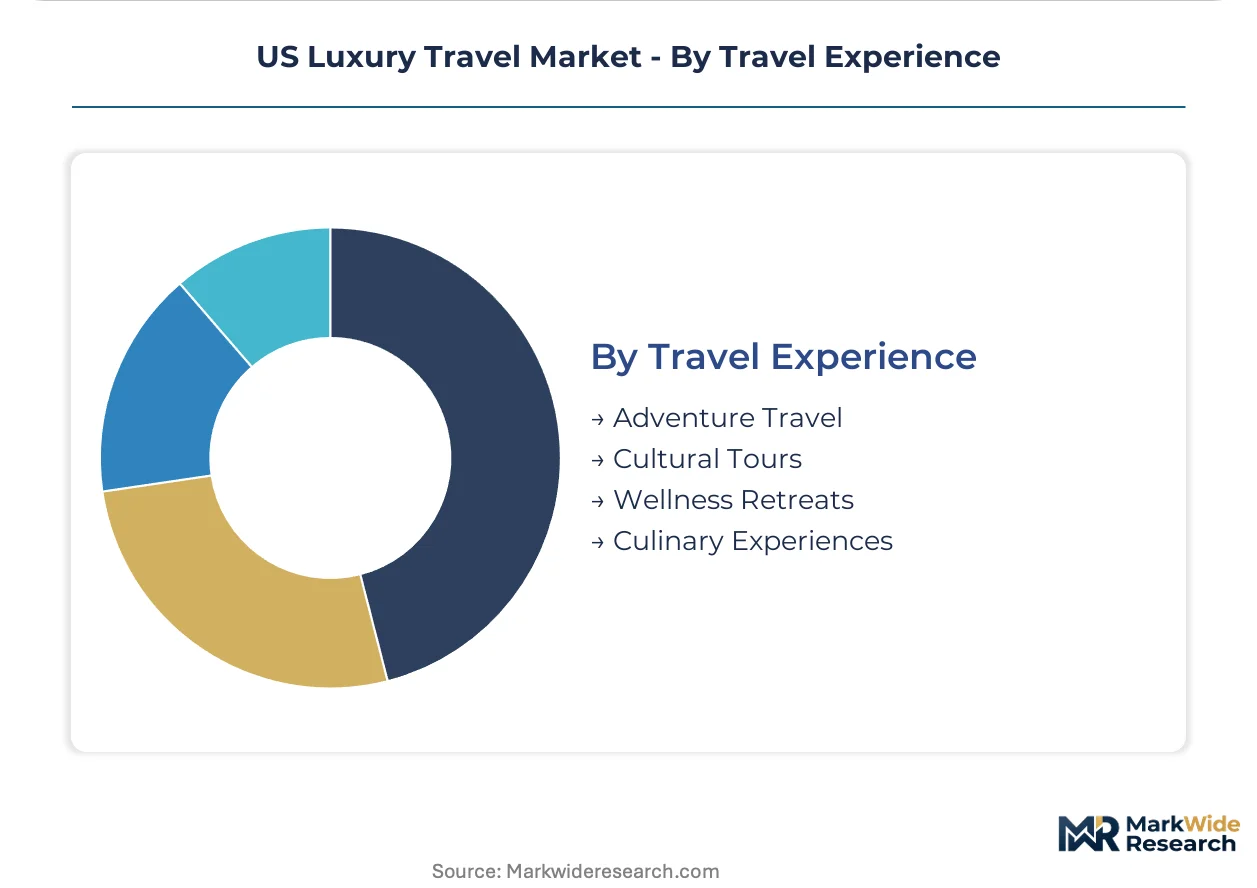
Travel Experience:
Wellness Retreats and Adventure Travel concentrate in domestic destinations accessible via private aviation, while Culinary Experiences and Cultural Tours distribute across international itineraries.
- Wellness Retreats:Biohacking protocols and longevity diagnostics embed into programming. Properties partner with Mayo Clinic, Cleveland Clinic, and boutique functional medicine practices for on-site medical services.
- Adventure Travel:Polar expeditions, safari extensions, and remote wilderness access dominate ultra-premium tiers. Physical conditioning prerequisites filter participant pools.
- Culinary Experiences:Chef's table access, vineyard harvest participation, and foraging expeditions integrate local food systems into itinerary design.
- Cultural Tours:Private museum access, archaeologist-led site visits, and artist studio immersions serve intellectually oriented affluent segments.
Cultural Tours commands the established base. The steepest expansion runs through Wellness Retreats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic luxury travel demand flows from three primary origin corridors—California, Florida, and New York—toward secondary destination markets across the Mountain West, Pacific Northwest, and Southeast. The FAA's modernization of private aviation infrastructure enables point-to-point connectivity between these clusters, compressing journey times for ultra-high-net-worth travelers.
California
Napa Valley wine country and coastal municipalities in Malibu and Carmel generate concentrated demand for extended-stay exclusive resorts. Municipal zoning restrictions constrain new ultra-luxury lodging supply, entrenching scarcity pricing at established properties. The California Coastal Commission enforces development limitations that protect shoreline access while limiting hospitality expansion.
Florida
Miami and Fort Lauderdale function as primary embarkation hubs for private yacht charters serving Caribbean and Bahamian itineraries. Affluent seasonal residents from the Northeast and Latin America concentrate demand during winter months. The Florida Department of Environmental Protection regulates marina expansion and coastal construction permits affecting new yacht facility development.
New York
Manhattan anchors the highest density of family offices employing in-house travel specialists who bypass traditional agency structures. Single-family offices maintain dedicated lifestyle management functions that direct discretionary spending toward curated experiential journeys. The New York State Department of Financial Services oversees wealth management firm conduct affecting travel advisory fee structures.
Mountain West
Aspen and Jackson Hole capture ski-season demand from coastal ultra-high-net-worth individuals seeking private aviation accessibility. Extended-stay properties command premium pricing during peak winter and summer adventure travel windows. The FAA's Denver and Salt Lake City air traffic modernization supports secondary market connectivity for remote destination access.
Pacific Northwest
Small-ship expedition vessels depart Seattle for Alaskan waterways, serving affluent segments prioritizing remote wilderness access. Luxury train services on heritage routes connect the region to Rocky Mountain destinations. The Washington State Department of Ecology regulates cruise and yacht emissions affecting itinerary feasibility in protected waterways.
US Luxury Travel Market Competitive Landscape
Listed hospitality conglomerates compete with private specialist agencies across itinerary customization depth and client relationship exclusivity. The market structures around three tiers: expedition heritage operators with decades of polar and safari expertise, ultra-discrete boutiques serving billionaire clients through extreme personalization, and multi-generational family voyage specialists designing age-differentiated programming. Dominant competitive moves include strategic partnerships with private terminal operators and portfolio diversification into wellness retreat programming.
Within the expedition heritage tier, Abercrombie & Kent and Fischer Travel occupy distinct positioning—one leveraging decades of polar and safari itinerary expertise, the other sustaining relationships through extreme discretion and bespoke service architecture. Elite Global Journeys exemplifies the multi-generational family voyage specialization, designing unified itineraries with differentiated activity tracks for children, parents, and grandparents. These three operators represent contrasting archetypes for how luxury travel providers capture premium pricing through non-replicable relationship depth rather than volume throughput.
| Leading Market Players |
|---|
| Scott Dunn |
| D.A. Luxury Travel |
| Elite Global Journeys |
| MK Luxury Travel |
| Avant-Garde Travel |
| Fischer Travel |
| Easy Escapes Travel |
| Magma Global |
| Abercrombie & Kent |
| Others |
Pricing and Supply Chain Analysis
Capacity reservation agreements with fixed-base operators lock in private aviation access and price visibility for luxury travel providers, insulating high-end operators from jet fuel volatility while securing terminal priority at California, Florida, and New York gateway markets.
Pricing Analysis
Legacy fleet versus next-generation aircraft pricing gaps structure charter rate differentiation across the luxury aviation tier. Three-tier pricing structure across ultra-long-range, heavy, and mid-size jet categories segments the market by range capability and cabin configuration. Price differentiation rests on FAA Part 135 certification tier and pilot experience thresholds, with newer entrants undercutting established operators on repositioning costs. Pricing pressure stems from sustainable aviation fuel premiums as operators absorb compliance costs without full pass-through mechanisms. Corporate family offices demonstrate lowest price sensitivity, while bleisure-extended business travelers compress discretionary spend.
Supply Chain Analysis
Extended aircraft refurbishment lead times stretch 18-24 months for cabin interior completions at specialist facilities. Geographic supply concentrates in United States, United Kingdom, and Switzerland for bespoke aviation interiors and ultra-luxury hospitality fixtures. Raw material dependencies span Italian leather, rare hardwoods, and advanced avionics components from specialized tier-two suppliers. Supply chain risk centers on single-source vulnerability for expedition-grade vessel hull fabrication and custom aircraft completions. Distribution runs through direct operator relationships with family offices and wealth management firms, bypassing traditional travel agency intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across booking channels and experience tiers creates niche formation opportunities as ultra-high-net-worth travelers abandon standardized packages for hyper-personalized service architectures.
For Market Incumbents: Consolidate concierge talent pools through equity participation structures that retain bilingual itinerary designers against hospitality group poaching. Acquire specialized wellness retreat properties in Napa Valley and Aspen to capture extended-stay ancillary spend. Defensive priority centers on FAA Part 135 operator certification depth as pilot training bottlenecks constrain competitor fleet scaling. For New Entrants and Emerging Players: FAA Part 135 certification fast-tracks through acquisition of existing air carrier certificates rather than de novo applications. White-space targets include female-led solo luxury travel segments and multi-generational family voyage programming with age-differentiated activity tracks. Penetrable geography centers on Pacific Northwest expedition vessel operations serving Alaskan waterways. Go-to-market angle leverages TSA PreCheck-equivalent screening partnerships at fixed-base operators to reduce security friction. For Investors and Strategic Acquirers: Boutique operators with embedded family office relationships and decades of expedition heritage command premium multiples in fragmented consolidation plays. Long-term viability favors properties with renewable energy retrofits qualifying for IRA Clean Energy Tax Credits, reducing operational cost exposure. Signal to watch is municipal short-term rental restriction tightening in gateway cities, which would constrain exclusive lodging supply and entrench scarcity pricing at established assets.| Strategic Initiative | Industry Significance |
|---|---|
| Private Terminal Channel Partnership | Signature Flight Support and Atlantic Aviation alliances compress security friction for ultra-high-net-worth travelers. |
| Wellness Technology Integration | Mayo Clinic and Cleveland Clinic on-site medical partnerships differentiate retreat programming for longevity-focused segments. |
| Sustainable Aviation Fuel Investment | IRA Clean Energy Tax Credits offset operational cost premiums while supporting marketing differentiation. |
| Multi-Generational Itinerary Design | Age-differentiated activity tracks within unified voyages capture extended booking windows and higher ancillary spend. |
| Dynamic Pricing Algorithm Deployment | Machine-learning revenue management enables real-time rate adjustment based on competitor availability and guest lifetime value scores. |
Research Methodology
Cross-validation between primary interviews with luxury travel operators and secondary analysis of FAA regulatory filings anchors the qualitative findings. Stakeholder consultations spanned private aviation charter executives, exclusive resort general managers, family office lifestyle directors, and wellness retreat programming leads. Secondary sources incorporated FAA air carrier certification databases, TSA private terminal screening protocols, state-level hospitality code filings from California and Florida, and municipal zoning records from Napa Valley and Malibu. Bottom-up itinerary cost modeling and top-down market sizing triangulated volume estimates.
Sensitivity analysis around jet fuel price assumptions and booking channel mix shifts tested forecast robustness across the projection horizon. Segmentation dimensions modeled included service type, customer psychographic, procurement pathway, and travel experience category. CAGRs were derived from trend extrapolation adjusted for regulatory modernization impacts and demographic clustering patterns. Industry-specific inputs incorporated FAA infrastructure investment timelines and IRA incentive qualification thresholds.
Decision-makers should treat outputs as directional under base assumptions of continued ultra-high-net-worth wealth concentration and sustained private aviation demand; material deviation in fuel price volatility or municipal zoning restrictiveness would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Coloring Apps Market
Others
Digital LUX Meter Market
Others
Free Space Optics (FSO) Market
Others
Medical Simulation Market
Others
Asia-Pacific IVD Regulatory Affairs Outsourcing Market
Others
Aircraft Exterior Lighting Market
Others
Cloud Broadcasting Solutions Market
Others
Security Envelopes Market
Others
Post Consumer Recycled Bottles Market
Others
United States Smart Homes Market
Others
Mobile Computer Cart Market
Others
AI In Government And Public Services Market
Others
Global Bio-Based Chemicals Market
Others
Thermal Insulation Solution for LNG and LPG Market
Others
Receiving Scales Market
Others
Global Car Wax Market