
 Aerospace Tester Market | 2026-2036
Aerospace Tester Market Size, Share, and Industry Trends Forecast 2026-2036
Aerospace Tester Market Analysis
Software-defined diagnostics and predictive maintenance subscriptions is repositioning how aerospace testers capture recurring revenue. Bureau Veritas leverages its global laboratory network to sustain long-term service contracts with tier-one aerostructure suppliers. SGS SA anchors its aerospace testing portfolio through specialized non-destructive testing capabilities in European manufacturing clusters. Intertek Group plc differentiates by competing on accelerated certification timelines for commercial aviation programs.
An aerospace tester comprises calibrated instrumentation systems designed to measure structural integrity, avionic performance, and environmental tolerance across parameters including vibration spectra, thermal cycling ranges, and electromagnetic compatibility thresholds; these systems verify compliance before airworthiness release. Automatic Test Equipment dominates capital expenditure among product categories due to its integration into production lines for avionics and engine control units. Non-Destructive Testing technology leads technology adoption as aging fleet mandates from regulators expand crack-detection and composite-scanning workloads. MRO Providers represent the fastest-growing end-user channel as airlines outsource airframe and engine test cycles to specialized third-party facilities.
FAA airworthiness directives, EASA Part-21 design organization requirements, and ISO 17025 laboratory accreditation standards collectively shape product specifications, audit frequencies, and cross-border market access for testing service providers. The EPA and OSHA impose additional environmental and workplace safety constraints on test facility operations, particularly for chemical processing and high-energy electromagnetic testing environments. Stakeholders must monitor evolving software validation requirements from aviation regulators as digital twin and model-based systems engineering methods displace physical test artifacts.
Market Dynamics
Software-defined diagnostics is compressing equipment replacement cycles while predictive maintenance subscriptions restructure revenue recognition for aerospace testing providers. This shift forces capital-intensive hardware manufacturers to build recurring revenue streams through data analytics platforms.
Growth Catalysts
- FAA Airworthiness Directives:Aging fleet mandates for narrow-body aircraft expand non-destructive testing workloads across MRO facilities in the United States.
- Next-Generation Avionics:Automatic Test Equipment integration into production lines for engine control units drives capital expenditure among tier-one suppliers.
- Composite Airframe Proliferation:Carbon fiber-reinforced polymer structures require specialized ultrasonic and thermographic inspection protocols distinct from metallic airframe methods.
Market Restraints
- Calibration Equipment Concentration:Precision instrumentation supply concentrates among German and Swiss metrology specialists, creating single-source vulnerability.
- ISO 17025 Accreditation Costs:Laboratory certification maintenance consumes 15-20% of annual operating budgets for mid-sized testing service providers.
- Electromagnetic Shielding Materials:Anechoic chamber construction depends on ferrite tile and carbon-loaded foam supply chains vulnerable to rare earth price volatility.
Strategic Opportunities
- Urban Air Mobility Certification:eVTOL manufacturers in the United States require novel environmental testing protocols for distributed electric propulsion systems.
- Digital Twin Convergence:Model-based systems engineering methods combine with physical test data to reduce prototype iteration cycles for aerostructure programs.
- Third-Party MRO Channel Expansion:Airlines outsource engine test cell operations to specialized facilities, opening service contract opportunities outside OEM captive networks.
Industry Challenges
- Electromagnetic Compatibility Specialist Shortage:MIL-STD-461 and DO-160 qualification expertise resides with aging workforce cohorts approaching retirement.
- Multi-Standard Certification Timelines:Simultaneous FAA, EASA, and Transport Canada validation extends program schedules by 8-14 months for new test equipment platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerospace Tester Market |
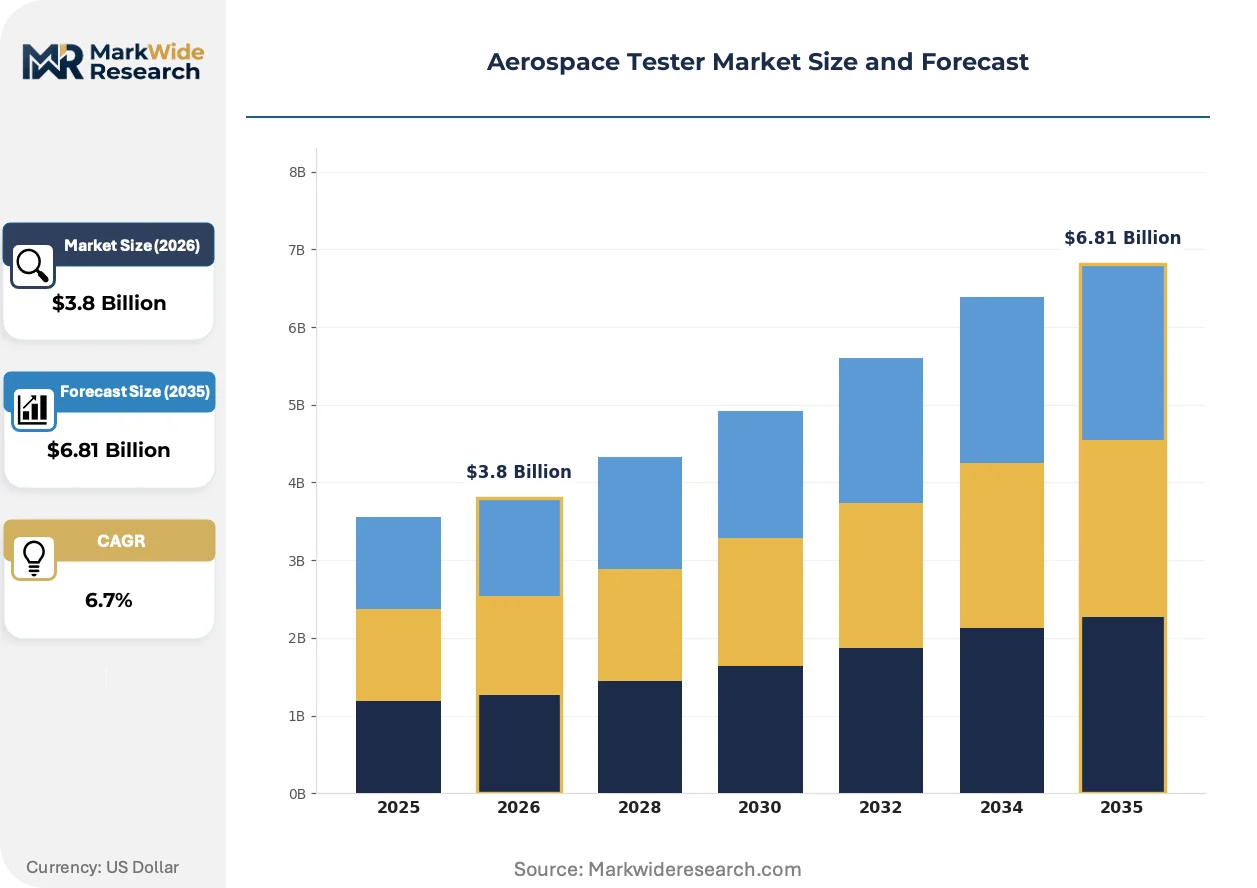
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Test Equipment, Handheld Testers, Flight Test Instrumentation, Ground Test Systems End User: Defense, Commercial Aviation, Space Agencies, MRO Providers Technology: Functional Testing, Non-Destructive Testing, Software Testing, Simulation Testing Application: Aircraft Testing, Component Testing, System Testing, Environmental Testing |
| Companies Covered | Applus+, Bureau Veritas, Element Materials Technology, Eurofins Scientific, DEKRA, SGS SA, TÜV SÜD, MISTRAS Group, Intertek Group plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerospace Tester Market Emerging Trajectories
Physical test artifacts are yielding to virtual validation environments, forcing equipment manufacturers to reposition hardware as data capture nodes within broader digital ecosystems. This compression of the test-certification pipeline demands new interoperability standards.
Model-based systems engineering is overtaking document-centric design verification for next-generation aircraft programs. Boeing and Airbus suppliers adopt digital thread architectures that feed physical test data back into simulation models. This convergence is overtaking traditional stage-gate review processes, compressing development timelines by integrating virtual and physical validation loops.
EASA Part-21 design organization requirements now mandate traceability from test results to certification artifacts through automated data management systems. European aerostructure suppliers invest in laboratory information management systems to satisfy audit frequency intensification. Composite manufacturing clusters in Germany and France face the steepest compliance burden as regulator scrutiny shifts toward automated crack-detection algorithm validation.
Airlines unbundle airframe inspection contracts from engine overhaul agreements, creating discrete procurement events for specialized testing services. Third-party MRO providers capture these disaggregated contracts through dedicated test cell investments. This pattern concentrates in the United States where carrier consolidation has produced sophisticated procurement functions capable of multi-source qualification.
Aerospace Tester Market Segmentation
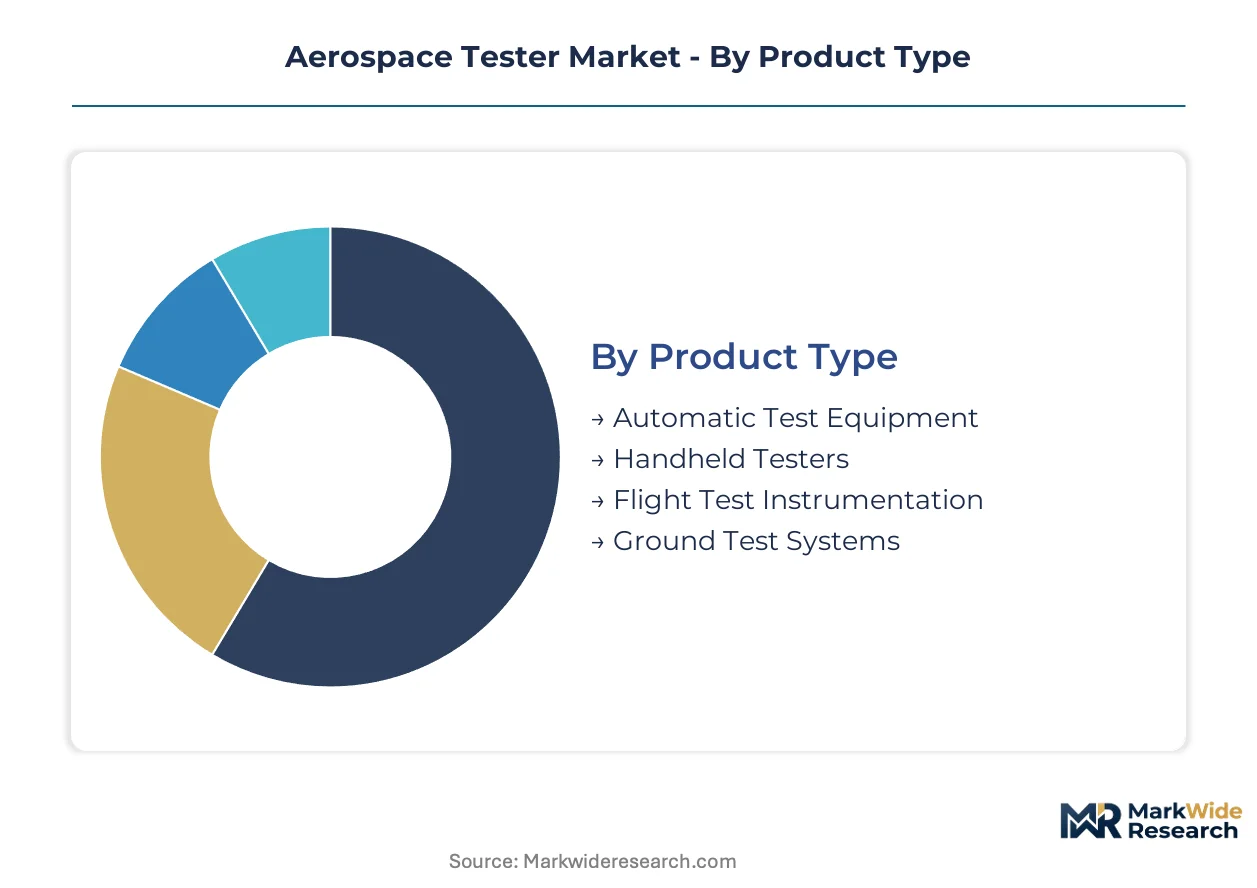
Aerospace tester procurement patterns diverge sharply across capital intensity, regulatory exposure, and operational tempo. Segmentation reveals where equipment replacement cycles compress and where long-dated service contracts dominate revenue recognition.
Product Type:
Capital deployment varies by an order of magnitude across product categories, with production-line integration driving the steepest upfront commitments.
- Automatic Test Equipment:Rack-mounted systems execute parametric verification of avionics and engine control units at line speed. Tier-one suppliers in the United States anchor demand through factory-floor integration mandates from Boeing and Airbus narrow-body programs.
- Ground Test Systems:Engine test cells and structural load rigs demand civil infrastructure investment exceeding the instrumentation itself. MRO facilities in Texas and Arizona concentrate procurement as airlines outsource powerplant validation cycles.
- Flight Test Instrumentation:Telemetry pods and data acquisition units for certification campaigns.
- Handheld Testers:Portable diagnostic units for line maintenance and A-check interventions.
Automatic Test Equipment absorbs the bulk of installed capacity; Ground Test Systems is expanding most quickly through third-party MRO channel development.
End User:
Customer procurement sophistication shapes contract structures, from cost-plus defense awards to competitive tender in commercial aviation.
- MRO Providers:Third-party maintenance facilities disaggregate airframe inspection from engine overhaul, creating discrete testing procurement events. Specialized test cell operators in the United States capture outsourced validation cycles from consolidated carrier fleets.
- Commercial Aviation:Airlines and lessors mandate non-destructive testing protocols for aging narrow-body fleets under FAA airworthiness directives. Procurement functions negotiate multi-source qualification for crack-detection services.
- Defense:Military airframe and propulsion testing through captive depots and contractor-operated facilities.
- Space Agencies:Environmental qualification for launch vehicle and satellite components.
Commercial Aviation commands the largest equipment installed base; MRO Providers climb the fastest as outsourcing accelerates.
Technology:
Technology selection tracks material evolution in airframe construction and software complexity in avionics architectures.
- Non-Destructive Testing:Ultrasonic, thermographic, and radiographic methods verify composite airframe integrity without structural disassembly. EASA certification requirements intensify automated crack-detection algorithm validation for carbon fiber-reinforced polymer structures.
- Software Testing:Model-based systems engineering and digital twin validation displace physical test artifacts for avionics verification. FAA software validation standards now govern tool qualification for automatic code generation environments.
- Functional Testing:Parametric verification of electrical and hydraulic subsystem performance.
- Simulation Testing:Hardware-in-the-loop environments for flight control law validation.
Non-Destructive Testing dominates current workload volumes; Software Testing gains share fastest as physical-digital convergence accelerates.
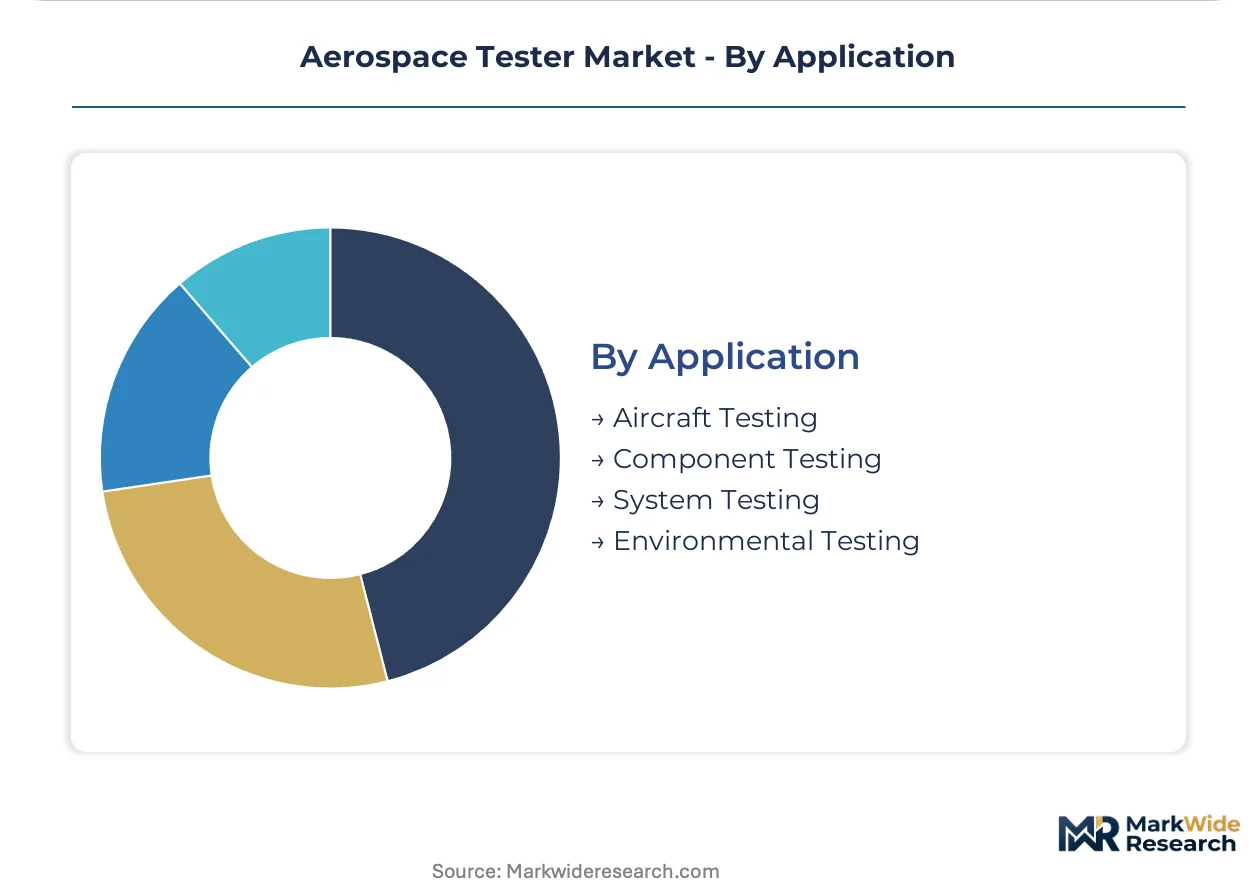
Application:
Application scope determines facility certification tier and regulatory audit frequency.
- Aircraft Testing:Full-airframe structural and systems integration validation for type certification. OEM integrated test facilities in Washington State and Toulouse concentrate this activity through dedicated flight test centers.
- Environmental Testing:Thermal cycling, vibration spectra, and electromagnetic compatibility qualification. EPA and OSHA constraints apply to chemical processing and high-energy electromagnetic test chamber operations.
- Component Testing:Piece-part validation for aerostructure and propulsion subsystems.
- System Testing:Integrated avionics and flight control verification.
Aircraft Testing claims the deepest capital commitment per installation; Environmental Testing shows the steepest expansion trajectory through eVTOL certification demands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Test equipment production clusters in Germany and Switzerland supply precision instrumentation worldwide, while consumption concentrates where OEMs and MRO facilities operate integrated validation centers. The United States absorbs the largest share of installed capacity through Boeing supplier networks and third-party maintenance outsourcing.
United States
FAA airworthiness directives for aging narrow-body fleets expand non-destructive testing workloads across MRO facilities. The FAA mandates enhanced crack-detection protocols under revised compliance schedules. Texas and Arizona concentrate engine test cell investments as airlines outsource powerplant validation cycles to specialized third-party operators.
Germany
Carbon fiber-reinforced polymer airframe production drives demand for ultrasonic and thermographic inspection systems. EASA Part-21 design organization requirements intensify automated crack-detection algorithm validation mandates. Bavaria and Baden-Württemberg host composite manufacturing clusters where suppliers invest in laboratory information management systems for audit traceability.
France
Airbus narrow-body and eVTOL programs anchor environmental testing demand for distributed electric propulsion systems. EASA certification timelines for novel aircraft configurations extend validation protocols. Toulouse maintains integrated flight test centers where full-airframe structural validation concentrates for type certification campaigns.
United Kingdom
Defense airframe and propulsion testing through contractor-operated facilities sustains ground test system procurement. The country's national aerospace regulator enforces design organization requirements aligned with EASA frameworks. Midlands and South England clusters house captive depots and specialized test cell operators serving military aviation programs.
Japan
Space agency environmental qualification requirements for launch vehicle components expand simulation testing investments. METI standards govern electromagnetic compatibility test chamber construction and high-energy testing safety protocols. Nagoya and Tokyo metropolitan areas concentrate avionics suppliers integrating automatic test equipment into production lines for engine control units.
Aerospace Tester Market Vendor Landscape
Capital-heavy integrated test facility operators compete with asset-light diagnostic service providers across the aerospace testing value chain. Market structure tilts toward consolidation among global laboratory networks that sustain long-term service contracts through multi-site accreditation. Three archetypes dominate: full-service multinationals with ISO 17025 networks, specialized non-destructive testing boutiques, and OEM-captive validation centers. Competitive moves center on strategic partnerships with tier-one aerostructure suppliers and geographic expansion through accreditation transfer to emerging manufacturing clusters.
Within the full-service multinational tier, Bureau Veritas, SGS SA, and Intertek Group plc exemplify the laboratory network archetype. Bureau Veritas leverages its global footprint to anchor recurring revenue through integrated test facility management. SGS SA occupies a position emphasizing specialized non-destructive testing capabilities in European manufacturing concentrations. Intertek Group plc sits within the accelerated certification segment, competing on compressed timelines for commercial aviation program validation.
| Leading Market Players |
|---|
| Applus+ |
| Bureau Veritas |
| Element Materials Technology |
| Eurofins Scientific |
| DEKRA |
| SGS SA |
| TÜV SÜD |
| MISTRAS Group |
| Intertek Group plc |
| Others |
Supply Flow & Price Mechanics
Tier-one aerostructure suppliers in the United States anchor procurement volumes through multi-year service contracts, locking in subscription-based pricing for predictive maintenance platforms while transactional hardware sales face margin compression.
Pricing Analysis
Cost-down pressure on automatic test equipment accelerates as Boeing and Airbus narrow-body production lines demand line-speed integration at scale. Three-tier pricing structure across premium, standard, and economy levels separates FAA-certified systems from ISO 17025 laboratory-grade units and uncertified diagnostic tools. Price differentiation traces to certification tier and after-sales service bundling. MRO providers exhibit highest price sensitivity due to disaggregated contract procurement, while OEM captive facilities absorb premium tiers for integrated test facility management.
Supply Chain Analysis
Precision instrumentation supply rests on German and Swiss metrology specialists, with carbon-loaded foam and ferrite tile for anechoic chambers drawing from Japanese and Chinese specialty material producers. Raw material dependencies span rare earth elements for electromagnetic shielding, high-purity ceramics for ultrasonic transducers, and calibrated reference standards from national measurement institutes. Single-source vulnerability concentrates in Swiss precision motion control systems. Distribution runs through OEM-direct channels for production-line equipment and specialized test cell operators for MRO service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software-defined diagnostics is displacing capital-intensive hardware sales, compressing equipment replacement cycles while predictive maintenance subscriptions capture recurring revenue streams.
For Market Incumbents: Anchor market position through ISO 17025 accreditation transfer to emerging eVTOL manufacturing clusters in Texas and Arizona, defending against specialized non-destructive testing boutiques. Deepen backward integration into calibration reference standards to offset German and Swiss single-source vulnerability. Prioritize laboratory information management system investments to satisfy EASA Part-21 audit traceability mandates. For New Entrants and Emerging Players: Third-party MRO test cell operators in the United States represent the most penetrable buyer archetype as airlines unbundle inspection contracts from engine overhaul agreements. Target environmental testing protocols for distributed electric propulsion systems in urban air mobility certification. Pursue accelerated certification timeline positioning against Intertek Group plc's established commercial aviation program validation. For Investors and Strategic Acquirers: The window for entry favors asset-light diagnostic service providers with recurring revenue platforms over capital-heavy integrated test facility operators. Long-term viability hinges on digital twin convergence capabilities combining physical test data with model-based systems engineering. Watch electromagnetic compatibility specialist workforce demographics as MIL-STD-461 expertise cohorts approach retirement.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Launch | Captures recurring revenue from Boeing and Airbus tier-one suppliers seeking operational data analytics. |
| ISO 17025 Accreditation Expansion | Opens multi-source qualification opportunities with consolidated US carrier fleets outsourcing validation cycles. |
| Digital Twin Integration Partnership | Compresses prototype iteration timelines for carbon fiber-reinforced polymer aerostructure programs. |
| eVTOL Environmental Test Protocol Development | Addresses novel distributed electric propulsion certification demands from FAA and EASA regulators. |
| Electromagnetic Compatibility Specialist Acquisition | Secures scarce MIL-STD-461 and DO-160 qualification expertise before workforce retirement waves. |
Methodological Framework
Regulatory filings from FAA, EASA, and EPA, alongside ISO 17025 accreditation databases and aerospace OEM supplier disclosures, formed the secondary backbone for market sizing and compliance requirement mapping. Primary interviews with MRO facility directors, tier-one aerostructure procurement managers, electromagnetic compatibility test engineers, and laboratory information management system vendors validated equipment replacement cycle assumptions and pricing model transitions. Bottom-up triangulation across automatic test equipment unit deployments and top-down validation through service contract value analysis ensured segmentation integrity.
Historical trendline analysis of capital expenditure patterns across Boeing and Airbus narrow-body production ramps established baseline growth trajectories. The projection framework modeled demand across product type, end user, technology, and application dimensions, with regional regulatory cluster intensity as an aerospace-specific overlay. CAGRs derived from equipment replacement cycle compression rates and predictive maintenance subscription penetration curves, calibrated against FAA airworthiness directive compliance schedule acceleration.
Revisions become necessary when EASA software validation requirements for digital twin methods materialize ahead of physical test artifact displacement timelines, or when rare earth price volatility disrupts anechoic chamber construction supply. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Wireless Asset Management Market
Others
Brown Ht Market
Others
Ultrasonic Flow Meter Market
Others
Spend Analytics Market
Others
Cat Food Market
Others
Europe Refrigerated Display Cases Market
Others
Griffin Beaker Market
Others
Android STB and TV Market
Others
South Asia Geosynthetics Market
Others
Aircraft Lighting Market
Others
Italy 3D Printing Construction Market
Others
Versatile Video Coding Market
Others
Global Smartphone ODM Market
Others
Surface Green Mining Market
Others
Global Video Processing Platform Market
Others
Europe Indoor Air Purification Market