
 Solar Panel Testers Market | 2026-2036
Solar Panel Testers Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Panel Testers Market Insights
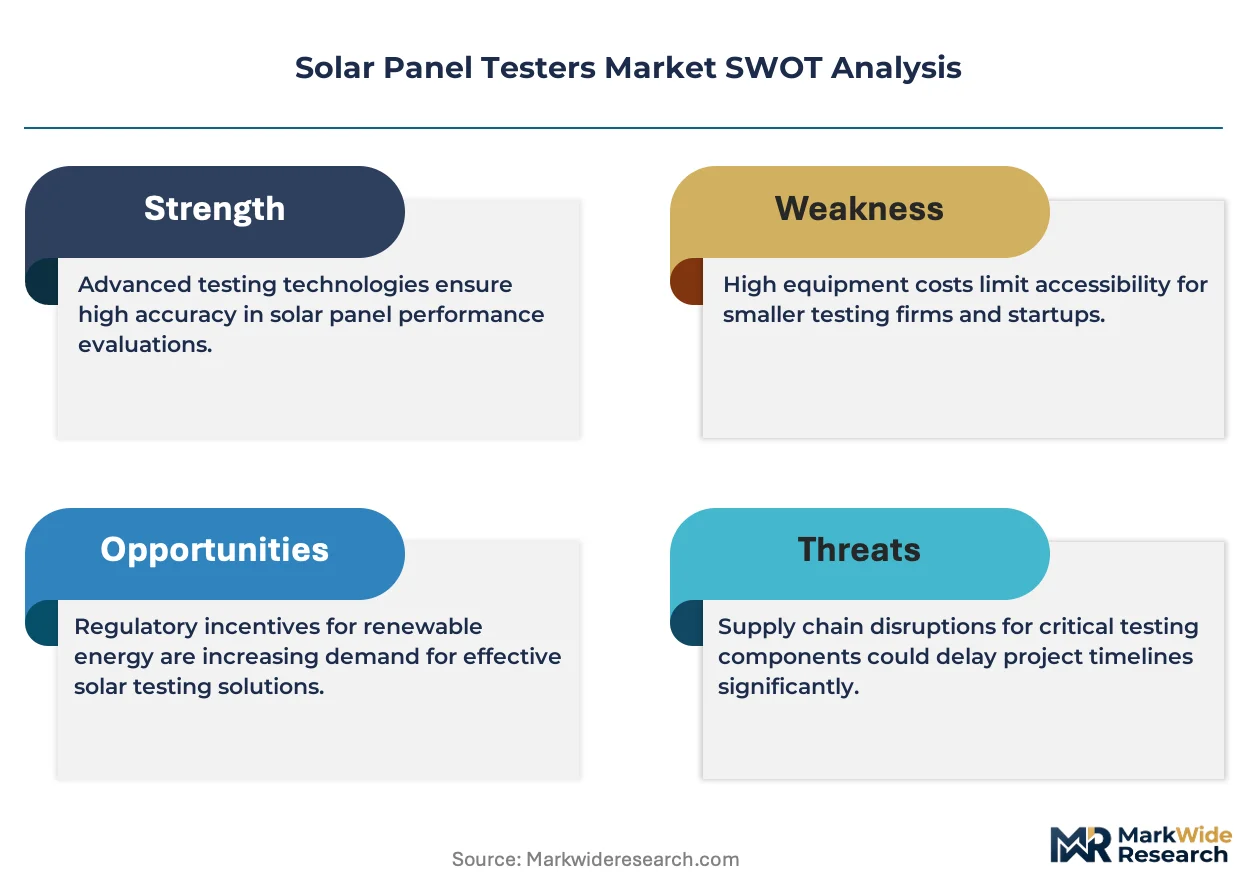
Asset-light leasing models for precision testing equipment are reconfiguring competitive dynamics among solar panel tester suppliers. Fluke leverages its established channel presence in North American electrical distribution to sustain service revenue streams alongside hardware sales. Megger competes through specialized insulation resistance testing protocols that anchor its position in utility-scale commissioning workflows. HIOKI dominates portable power analyzer design, extending its reach from laboratory calibration into field deployment scenarios for Asian installers.
Solar panel testers comprise calibrated instruments that measure electrical output, thermal performance, and material integrity of photovoltaic modules under standard test conditions of 1000 W/m² irradiance and 25°C cell temperature. These devices verify power ratings, detect microcracks through electroluminescence imaging, and ensure long-term reliability across manufacturing and operational life cycles. IV curve tracers capture the fastest-growing margin pool as utility-scale projects demand precise maximum power point verification under variable irradiance. Electroluminescence technology leads quality assurance segments for cell-level defect detection, while thermal imaging occupies mature maintenance applications with slower replacement cycles.
IEC standards govern European module certification, while UL 1703 and subsequent UL 61730 standards shape North American product safety and performance testing requirements. China's GB/T 9535 national standard and MIIT efficiency benchmarks mandate domestic manufacturers to maintain captive testing infrastructure. India's BIS certification regime and CEA grid interconnection rules compel installer-grade verification tools for project commissioning. Stakeholders must monitor evolving efficiency tier thresholds and harmonization gaps between regional certification protocols when allocating R&D and distribution investments.
Market Dynamics
Utility-scale solar deployment in India and Southeast Asia is accelerating procurement of field-grade IV curve tracers and electroluminescence inspection systems, while IEC 61215 and UL 1703 certification tightening forces manufacturers to upgrade captive testing infrastructure.
Growth Catalysts
- India's PLI scheme for solar manufacturing:Domestic module production incentives under the country's production-linked incentive framework are compelling new fabrication facilities to install inline electroluminescence and thermal imaging stations.
- Perovskite-silicon tandem commercialization:Next-generation cell architectures require modified IV curve characterization protocols, expanding the addressable instrument base beyond conventional silicon testing.
- Utility-scale commissioning protocols:Grid interconnection rules in multiple jurisdictions now mandate field-level power verification before energization, embedding tester procurement into project finance milestones.
Market Restraints
- Reference cell supply concentration:Calibrated reference cells for irradiance standardization rely on a narrow supplier base in Germany and Japan, creating input vulnerability for tester manufacturers.
- Technical bandwidth limitations:Electroluminescence imaging systems face throughput ceilings below 1,500 modules per hour, constraining their deployment in gigawatt-scale manufacturing lines.
- Regulatory fragmentation:Divergent certification requirements between IEC, UL, and China's GB/T 9535 standards force redundant testing infrastructure investments by multinational module producers.
Strategic Opportunities
- Vietnam's manufacturing migration:Module assembly capacity relocation from China to Vietnam is generating greenfield demand for integrated testing lines among first-time facility operators.
- Drone-mounted thermal inspection:Aerial thermography convergence with machine vision algorithms enables rapid defect mapping across operational utility-scale arrays without manual ladder access.
- California's SB 100 compliance pathways:The state's renewable portfolio mandates are accelerating repowering of aging solar assets, creating aftermarket testing demand for degradation assessment and warranty claims.
Industry Challenges
- Electroluminescence image interpretation:Shortage of technicians trained in crack propagation analysis and cell-level defect classification slows commissioning timelines and inflates service costs.
- Multi-standard calibration complexity:Test equipment must maintain traceability to both IEC 60904 and ASTM E948 reference conditions, complicating firmware architecture and extending development cycles.
- Integration with MES platforms:Manufacturing execution system connectivity requires custom protocol bridges, fragmenting the addressable market for standardized turnkey solutions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Panel Testers Market |
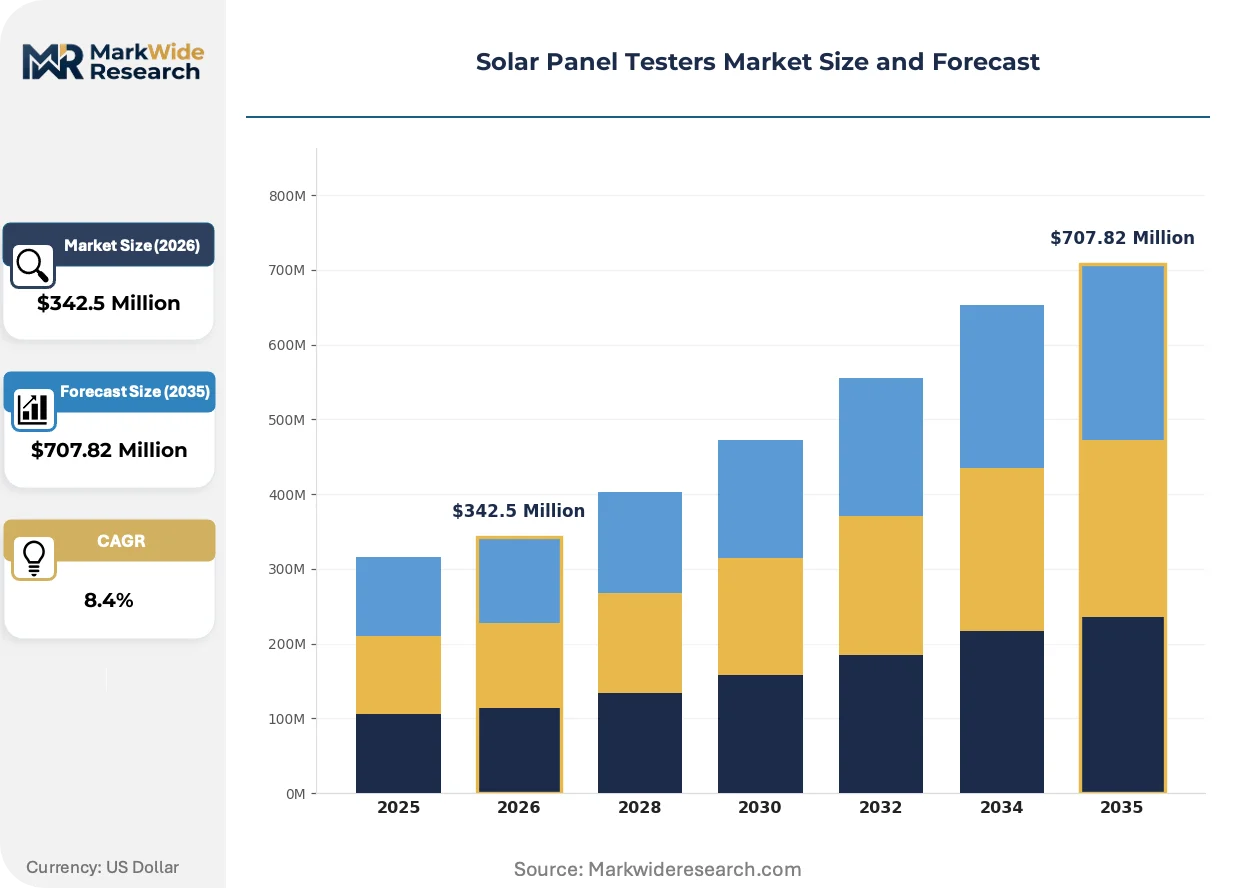
| Market Size in 2026 | $342.5 Million |
| Market Size in 2035 | $707.82 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Meters, Insulation Testers, IV Curve Tracers, Multimeters Technology: Thermal, Electroluminescence, Photovoltaic, Infrared End User: Installers, Manufacturers, Inspectors, Researchers Application: Field Testing, Laboratory Testing, Quality Assurance, Maintenance |
| Companies Covered | Fluke, Megger, HIOKI, HT Instruments, GMC-Instruments, BENNING, Metrel, Seaward Electronic, Chroma ATE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Panel Testers Market Trends and Innovations
Digital instrumentation architectures are compressing measurement cycle times while cloud-based data logging reconfigures how testing intelligence flows between fabrication floors and asset management platforms.
Machine-vision electroluminescence inspection is digitizing defect detection workflows in cell and module production. Tier-1 manufacturers in China and Southeast Asia are deploying these systems at line speeds approaching 2,400 modules per hour. The technology is digitizing quality assurance by replacing manual visual inspection with algorithmic crack classification, compressing labor content per watt of capacity.
Europe's F-Gas Regulation phase-down is accelerating adoption of air-cooled thermal imaging systems in place of refrigerant-dependent cooled detectors. Industrial consequence includes sensor architecture redesigns and supply chain requalification for European tester suppliers. Module manufacturers with EU export exposure are prioritizing equipment compliant with the revised fluorinated gas restrictions.
Leasing arrangements for precision field equipment are displacing capital purchase models among independent engineering firms and smaller EPC contractors. Equipment-as-a-service contracts bundle calibration maintenance and firmware updates, reducing upfront barriers for commissioning teams. This pattern is most visible in India's distributed solar segment where project-scale variability discourages owned-fleet investment.
Solar Panel Testers Market Segmentation
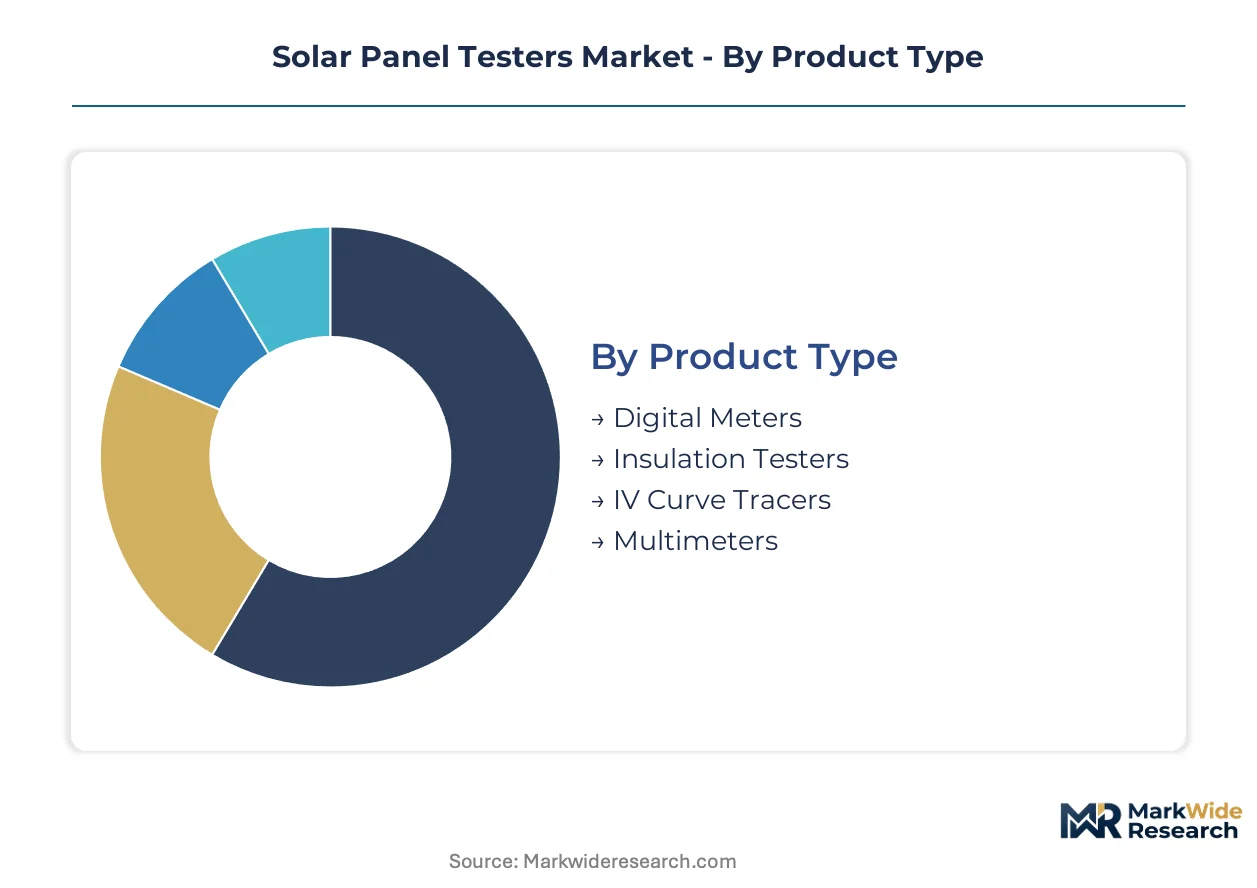
Segmentation in the solar panel testers market reveals divergent equipment lifecycles and margin structures. Product type determines replacement frequency, while technology choice governs capital intensity and service revenue potential across manufacturing and operational deployments.
Product Type:
IV curve tracers and digital meters turn over fastest due to firmware obsolescence and calibration drift, while insulation testers and multimeters persist longer in field inventories.
- IV Curve Tracers:These instruments capture current-voltage characteristics under variable irradiance conditions, essential for maximum power point verification. Demand concentrates in India's utility-scale commissioning workflows where CEA grid interconnection rules mandate field-level power validation before energization.
- Digital Meters:Calibrated measurement devices for DC voltage, current, and resistance parameters with integrated data logging. Installers in Southeast Asia prioritize these for distributed solar deployments where portability outweighs laboratory precision.
- Insulation Testers:Specialized equipment for dielectric withstand verification and ground fault detection in high-voltage string configurations.
- Multimeters:General-purpose diagnostic tools for routine electrical troubleshooting across residential and commercial installations.
Digital meters anchor the volume base while IV curve tracers gain share at the steepest rate.
Technology:
Cost tier differentiation separates premium electroluminescence systems from commoditized thermal imaging, with photovoltaic and infrared occupying intermediate positions.
- Electroluminescence:High-resolution imaging systems detect microcracks and cell-level defects through light emission under forward bias. China's tier-1 manufacturers deploy these at line speeds approaching 2,400 modules per hour, compressing labor content per watt of capacity.
- Thermal:Infrared-based temperature mapping identifies hot spots and interconnect failures in operational arrays. Europe's F-Gas Regulation phase-down is accelerating air-cooled sensor adoption among module producers with EU export exposure.
- Photovoltaic:Standard reference cell-based measurement for irradiance standardization and power rating verification.
- Infrared:Passive thermal detection for preventive maintenance without electrical connection requirements.
Thermal imaging anchors the volume base while electroluminescence gains share at the steepest rate.
End User:
Application maturity varies sharply: manufacturers demand continuous inline testing, while researchers drive specification evolution for next-generation cell architectures.
- Manufacturers:Captive testing infrastructure for production line quality control and certification compliance. India's PLI scheme for solar manufacturing is compelling new fabrication facilities to install inline electroluminescence and thermal imaging stations.
- Installers:Field deployment teams requiring portable verification tools for project commissioning and warranty documentation. Equipment-as-a-service contracts are displacing capital purchases among smaller EPC contractors in India's distributed solar segment.
- Inspectors:Third-party certification bodies and independent engineering firms conducting acceptance testing.
- Researchers:Laboratory and pilot line operators characterizing perovskite-silicon tandem cells and other advanced architectures.
Installers anchor the volume base while manufacturers gain share at the steepest rate.
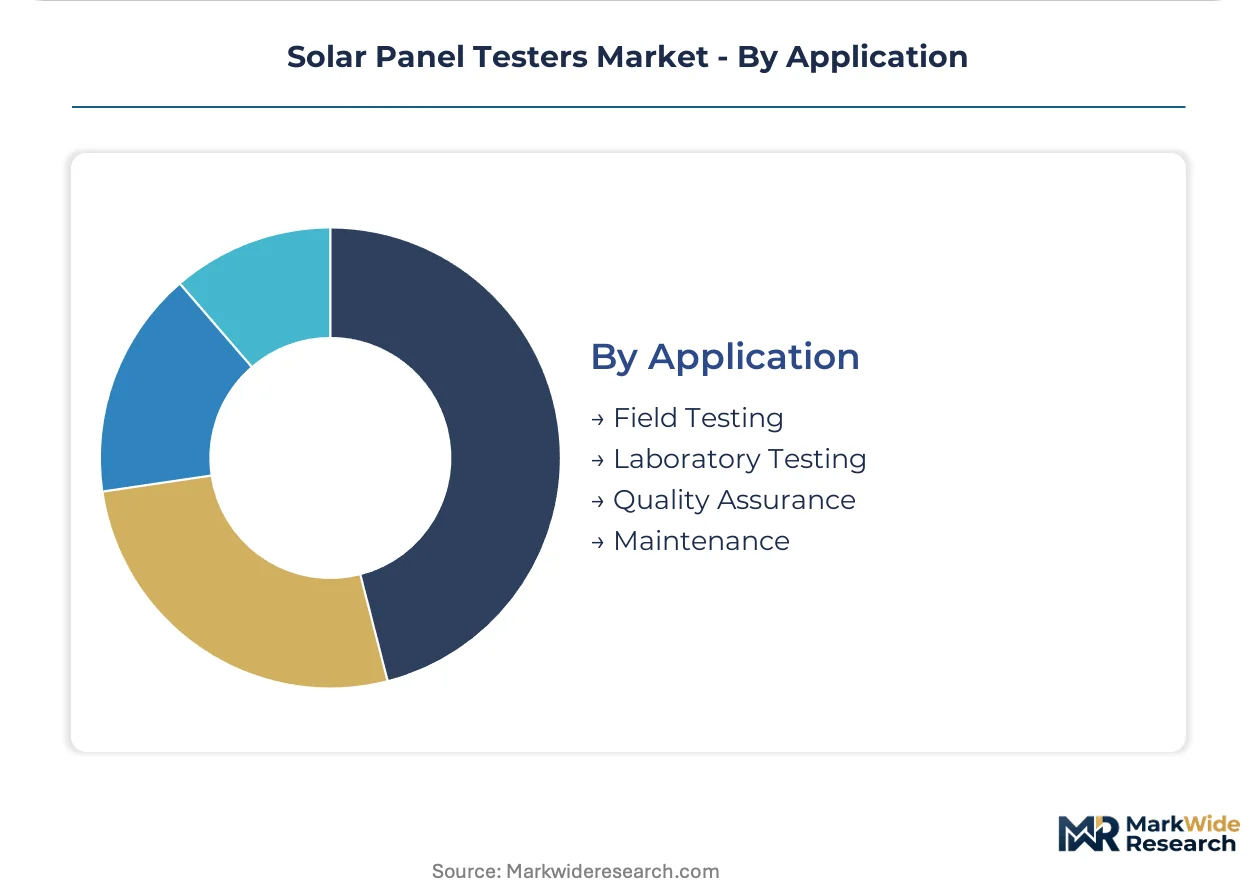
Application:
Volume concentration favors field testing for operational asset bases, while laboratory testing commands premium pricing for certification-grade precision.
- Field Testing:On-site power verification and defect detection for commissioned arrays. Drone-mounted thermal inspection is enabling rapid defect mapping across operational utility-scale arrays without manual ladder access.
- Quality Assurance:Inline production monitoring for cell and module fabrication. Machine-vision electroluminescence is digitizing quality assurance by replacing manual visual inspection with algorithmic crack classification.
- Laboratory Testing:Controlled environment characterization for IEC 61215, UL 1703, and GB/T 9535 certification compliance.
- Maintenance:Periodic degradation assessment and warranty claim documentation for aging assets. California's SB 100 compliance pathways are accelerating repowering demand for degradation assessment.
Field testing anchors the volume base while quality assurance gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Utility-scale solar developers in India and Southeast Asia represent the dominant buyer archetype for field-grade IV curve tracers, while tier-1 module manufacturers in China drive captive inline testing infrastructure investments. Procurement patterns cluster around manufacturing hubs and high-growth installation markets with active certification tightening.
China
Domestic module production capacity expansions under MIIT efficiency benchmarks are driving parallel investments in inline electroluminescence and thermal imaging stations. GB/T 9535 national standards mandate captive testing infrastructure for tier-1 producers. Yangtze River Delta manufacturing clusters near Shanghai host the densest concentration of machine-vision inspection system deployments.
India
PLI scheme incentives for solar manufacturing are compelling new fabrication facilities in Gujarat and Tamil Nadu to install integrated testing lines. CEA grid interconnection rules mandate field-level power verification before energization, embedding tester procurement into project finance milestones. Installer-grade verification tools dominate procurement in Rajasthan and Karnataka utility-scale corridors.
Germany
Reference cell calibration supply concentration in Bavaria and Baden-Württemberg creates input vulnerability for irradiance standardization equipment. IEC 61215 certification requirements and F-Gas Regulation phase-down are accelerating air-cooled thermal imaging adoption among module producers with EU export exposure. Fraunhofer research institutes in Munich anchor perovskite-silicon tandem characterization protocol development.
United States
California SB 100 compliance pathways are accelerating repowering of aging solar assets, creating aftermarket testing demand for degradation assessment and warranty claims. UL 1703 and subsequent UL 61730 standards shape product safety and performance testing requirements for domestic module producers. Independent engineering firms in Texas and Arizona deploy equipment-as-a-service contracts for distributed solar commissioning.
Vietnam
Module assembly capacity relocation from China is generating greenfield demand for integrated testing lines among first-time facility operators in northern industrial provinces. BIS-equivalent quality protocols for export markets compel electroluminescence and thermal imaging station installations. Bac Ninh and Hai Phong manufacturing zones concentrate new entrant procurement activity.
Solar Panel Testers Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement channels in distributed solar segments. Market structure tilts toward consolidation in manufacturing-grade electroluminescence systems while field equipment remains contested among regional electrical distributors. Three archetypes dominate: precision instrumentation incumbents with calibration service networks, portable equipment specialists with Asian manufacturing footprints, and emerging leasing-platform operators. Competitive moves center on geographic expansion through distribution partnerships and backward integration into sensor component supply.
Among precision instrumentation incumbents, Fluke and Megger exemplify channel-control archetypes with established electrical distribution presence in North America and Europe. HIOKI occupies a specialist position in portable power analyzer design, extending from laboratory calibration into field deployment scenarios. These three companies represent divergent strategic positions: Fluke anchors service revenue streams alongside hardware sales, Megger anchors utility-scale commissioning workflows through specialized protocols, and HIOKI dominates Asian installer procurement through portability-focused engineering.
| Leading Market Players |
|---|
| Fluke |
| Megger |
| HIOKI |
| HT Instruments |
| GMC-Instruments |
| BENNING |
| Metrel |
| Seaward Electronic |
| Chroma ATE |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in China's electroluminescence imaging module production is compressing equipment margins while simultaneously accelerating supplier consolidation around tier-1 manufacturers with captive calibration capabilities. This utilization dynamic forces pricing discipline on component vendors and amplifies bargaining power for buyers in India and Southeast Asia procuring integrated testing lines.
Pricing Analysis
Certification level creates the primary spread between premium IEC 61215-compliant systems and economy-grade field instruments lacking full traceability. Three-tier pricing structure across premium, standard, and economy levels dominates, with differentiation anchored in calibration certificate authority and firmware update bundling. Cost compression in the economy tier is intensifying because Vietnamese and Indian first-time facility operators prioritize capital efficiency over precision specifications. Installer-grade portable testers exhibit highest price sensitivity, while tier-1 Chinese manufacturers demonstrate lowest sensitivity due to regulatory compliance mandates.
Supply Chain Analysis
Export-control regimes on high-resolution infrared sensor arrays limit flows from US and German component suppliers to Chinese system integrators, fragmenting sourcing strategies. Manufacturing concentrates in China, Germany, and Japan, with reference cell calibration drawing from Bavarian laboratories and Hokkaido crystal growth facilities. German reference cell supply and Japanese precision sensor output represent critical input dependencies. Single-source vulnerability in calibrated reference cell supply creates procurement risk for IV curve tracer manufacturers. Distribution runs through regional electrical distributors in North America and direct OEM relationships in Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Shortage of technicians trained in electroluminescence image interpretation represents the binding constraint on market expansion, creating scarcity premiums for firms with certified training infrastructure and algorithmic defect classification capabilities.
For Market Incumbents: Entrench service revenue streams by embedding firmware-locked calibration subscriptions that reduce customer churn. Expand backward integration into reference cell supply through partnerships with Fraunhofer institutes to neutralize German supply concentration risk. Prioritize IEC 61215 protocol certification investments to defend against emerging Asian competitors lacking European laboratory access.
For New Entrants and Emerging Players: Pursue equipment-as-a-service contracts in India's distributed solar segment where project-scale variability discourages capital ownership. Target Vietnam's greenfield manufacturing zones for integrated testing line deployments among first-time facility operators lacking technical procurement experience. Lead with bundled training and certification programs to differentiate from established hardware vendors.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among precision instrumentation incumbents with captive calibration service networks, positioning them for superior cash flow stability across the analysis window. Acquisition focus should center on firms with algorithmic crack classification IP and established technician certification programs. Monitor India's PLI scheme disbursement velocity as the critical inflection signal for manufacturing-grade equipment demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Service Network Expansion | Fluke's established North American electrical distribution presence sustains service revenue alongside hardware sales. |
| Algorithmic Defect Classification Development | Machine-vision electroluminescence systems digitize quality assurance by replacing manual visual inspection workflows. |
| Reference Cell Supply Partnership | Fraunhofer institutes in Munich anchor perovskite-silicon tandem characterization protocol development for next-generation testing. |
| Equipment-as-a-Service Platform Launch | Leasing arrangements displace capital purchases among India's distributed solar EPC contractors facing project-scale variability. |
| Air-Cooled Sensor Architecture Redesign | Europe's F-Gas Regulation phase-down accelerates adoption of refrigerant-independent thermal imaging systems. |
Research Methodology
A spread of perspectives from module manufacturing executives, EPC procurement managers, independent engineering firm technical directors, and calibration laboratory operators converged on the working assumptions underlying this analysis. Primary interviews with tier-1 Chinese producers, Indian PLI scheme beneficiaries, and German reference cell suppliers combined with secondary validation against IEC certification databases, CEA grid interconnection filings, and MIIT efficiency benchmark disclosures. Bottom-up equipment procurement tracking and top-down solar capacity installation forecasts provided triangulation anchors.
Demand-supply balance modeling across the projection horizon incorporated product type segmentation by replacement frequency, technology tier by capital intensity, and end-user category by application maturity. Segmentation dimensions included IV curve tracer versus electroluminescence system deployment, field versus laboratory testing environments, and utility-scale versus distributed solar project scales. CAGRs derived from installed base growth rates, equipment lifecycle assumptions, and regulatory mandate implementation timelines. Perovskite-silicon tandem commercialization curves and F-Gas Regulation phase-down schedules served as technology-specific forecast inputs.
Sensitivities concentrate around India's PLI scheme disbursement velocity, reference cell supply disruptions from German or Japanese sources, and harmonization gaps between IEC, UL, and GB/T 9535 certification protocols. Forecasts reflect documented assumptions regarding technician training pipeline expansion and algorithmic defect classification adoption curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Ultra Mobile Devices (UMD) Market
Others
Trusted Platform Module (TPM) Market
Others
Global Flexible PVC Films Market
Others
Global Simulation in Healthcare Market
Others
Telecom Transformers Market
Others
Computer on Module Market
Others
Binoculars Market
Others
South Korea Intellectual Property Market
Others
North America Forklift Truck Market
Others
Aircraft Lighting Market
Others
Refractometer Market
Others
Hip Tendinitis Market
Others
Prunes Market
Others
Brazil Lime Market
Others
Sandbags Market
Others
Global Application Testing Services Market