
 Fiber Intermediates Market | 2026-2036
Fiber Intermediates Market Size, Share, and Industry Trends Forecast 2026-2036
Fiber Intermediates Market Analysis
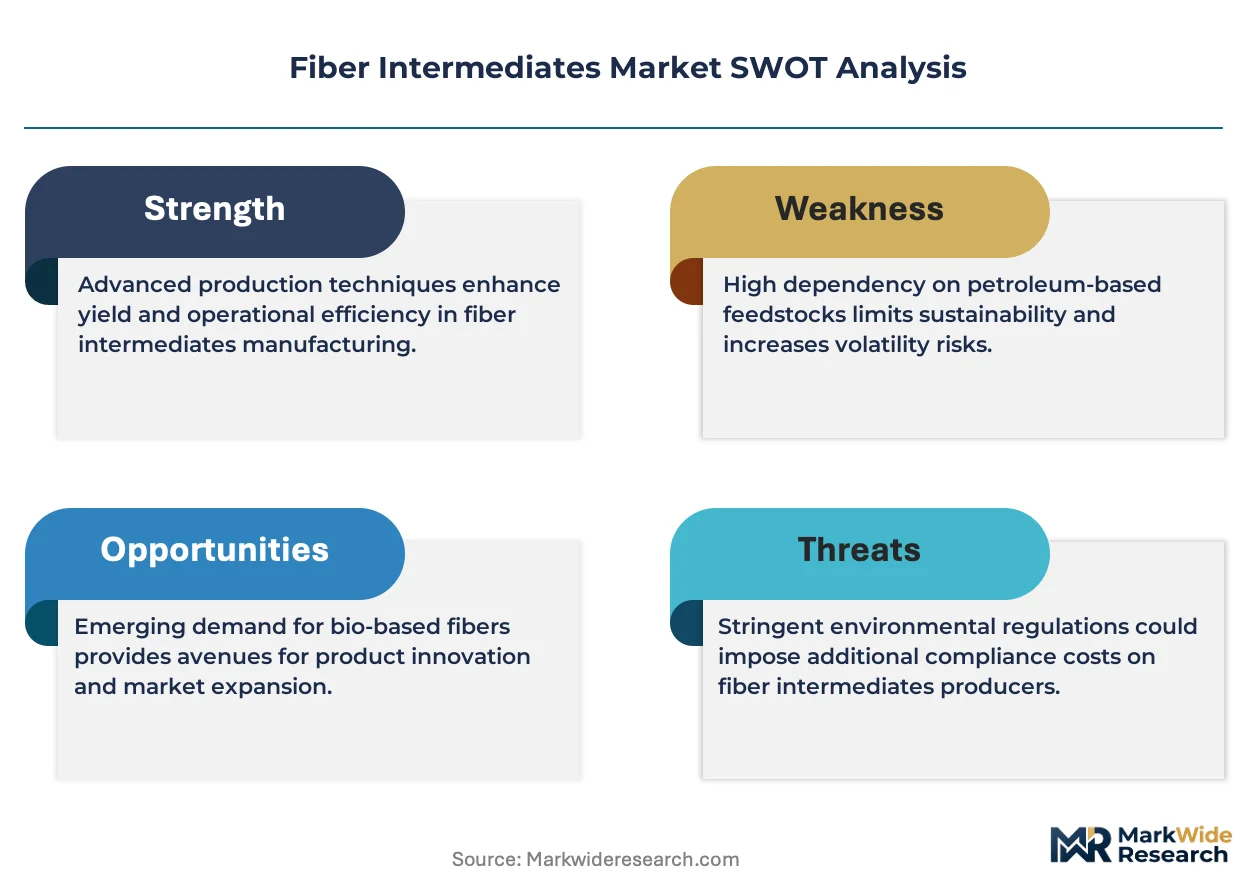
REACH compliance is broadening the cost-of-entry calculus for fiber intermediate suppliers serving European automotive and textile buyers. BASF SE leverages its integrated Ludwigshafen complex to sustain captive caprolactam supply chains that bypass third-party qualification bottlenecks. Invista anchors its position through proprietary adiponitrile technology that dominates nylon 6,6 precursor economics.
Fiber intermediates comprise the chemical precursors—principally purified terephthalic acid (PTA), monoethylene glycol (MEG), caprolactam, and adipic acid—that polymerize into synthetic fibers with denier ranges from 0.5 to 20 dtex for textile and industrial end uses. Polyester intermediates command the largest volume share given PTA-MEG integration with downstream PET resin and filament operations, while nylon 6 intermediates capture premium margins in automotive airbag yarn and tire cord applications where high tenacity specifications exceed 8.0 grams per denier. Acrylic intermediates occupy a mature niche in outdoor upholstery and carbon fiber precursors, with acrylonitrile feedstock volatility compressing margin pools.
EPA emissions standards under the Clean Air Act, EU REACH substance restrictions, and China's MEE environmental inspections collectively tighten effluent and VOC thresholds for caprolactam and PTA producers. The EU F-Gas Regulation indirectly pressures fluoropolymer-based fiber processing aids, accelerating shifts to water-based spin finishes. Stakeholders must monitor regulatory divergence between jurisdictions where compliance costs fragment competitive positioning.
Market Dynamics
Automotive lightweighting mandates are compressing specification tolerances for high-tenacity nylon 6,6 intermediates while REACH substance restrictions force reformulation of legacy adipic acid catalyst systems across European supply chains.
Growth Catalysts
- EU REACH substance restrictions:Chemical safety assessments are accelerating qualification of bio-based caprolactam alternatives for automotive airbag yarn producers seeking to preempt authorization bottlenecks.
- China's MEE environmental inspections:Consolidation of PTA capacity in Zhejiang and Jiangsu provinces is concentrating feedstock access for downstream PET filament operations serving textile export clusters.
- Automotive upholstery lightweighting:Polyester intermediate demand is tightening as seating manufacturers substitute heavier leather and vinyl with recycled PET fabrics to meet Corporate Average Fuel Economy targets.
Market Restraints
- Paraxylene feedstock volatility:Crude-linked aromatic pricing swings compress PTA margin pools when naphtha crackers operate below nameplate capacity in Middle Eastern and Asian complexes.
- Adiponitrile supply concentration:Proprietary butadiene-based technology licensing restrictions limit new nylon 6,6 precursor entrants and sustain incumbent pricing power in tire cord applications.
- Acrylonitrile demand displacement:Acrylic fiber consumption is eroding as outdoor upholstery buyers pivot to solution-dyed polyester alternatives with superior UV degradation resistance.
Strategic Opportunities
- India's PLI scheme for technical textiles:Caprolactam producers can capture import substitution benefits as domestic nylon 6 filament capacity expands around Surat and Mumbai clusters.
- EU F-Gas Regulation phase-down:Fluoropolymer-based spin finish displacement creates white space for water-based processing aid formulations in high-speed POY spinning operations.
- Carbon fiber precursor convergence:Acrylonitrile producers are repositioning acrylamide copolymer technology toward aerospace-grade PAN precursor markets with tenfold margin premiums over commodity textile applications.
Industry Challenges
- Process control engineering talent scarcity:Caprolactam and adipic acid operations require specialized expertise in catalytic hydrogenation and oxidation reactor management that aging workforces in European and North American complexes cannot replenish.
- REACH authorization timeline compression:Substance of Very High Concern dossier preparation demands 18-24 month lead times that outpace product development cycles for bio-based intermediate alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fiber Intermediates Market |
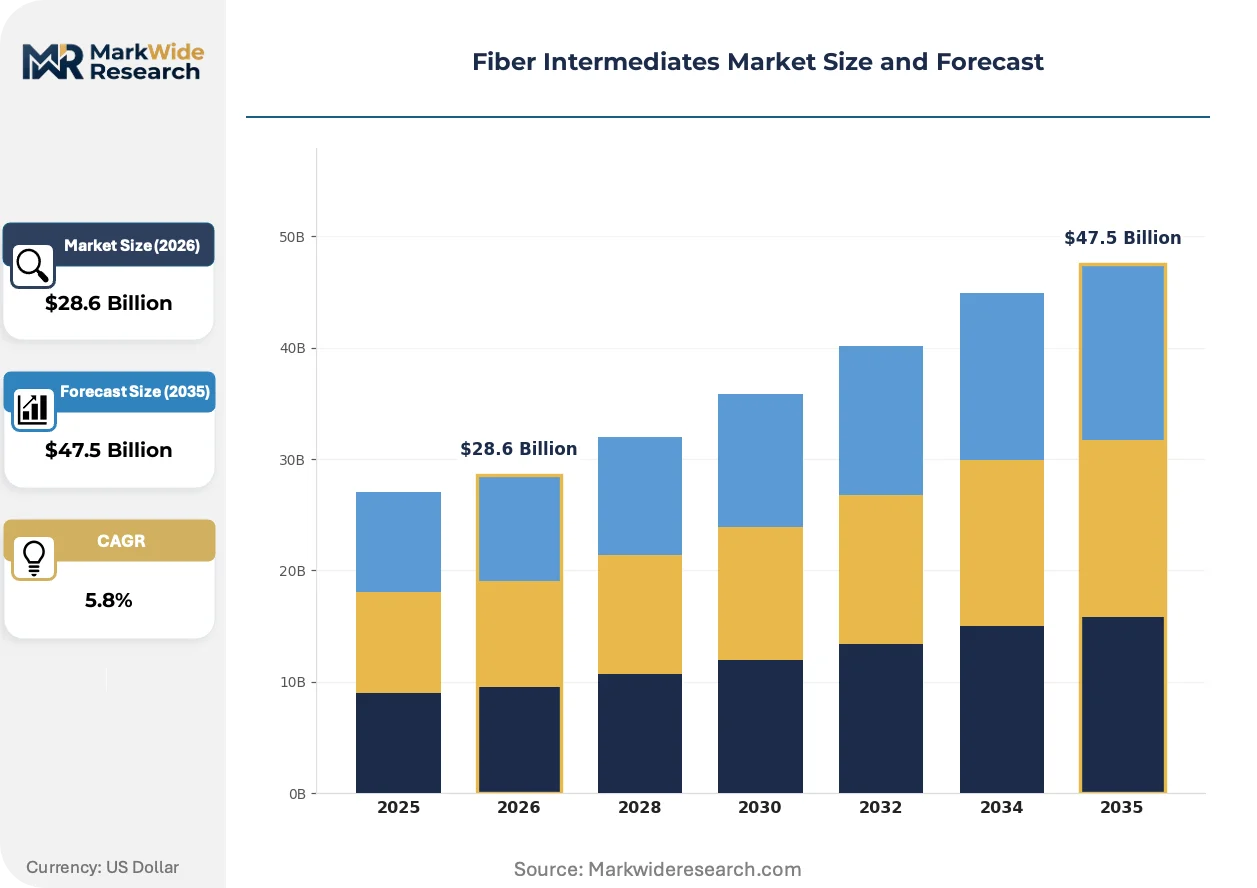
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $47.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nylon 6, Polyester, Acrylic, Polypropylene End User: Textiles, Automotive, Industrial, Home Furnishings Application: Clothing, Upholstery, Carpeting, Industrial Fabrics Technology: Spinning, Weaving, Knitting, Extrusion |
| Companies Covered | Reliance Industries Limited, BASF SE, Dow Chemical Company, Invista, Fiber Intermediate Products Company, Daicel Corporation, DSM Fiber Intermediates, Domo Chemicals, Chevron Phillips Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fiber Intermediates Market Emerging Trajectories
Process intensification technologies are collapsing capital intensity thresholds for intermediate production while regulatory chemistry constraints accelerate feedstock diversification strategies across polyester and nylon precursor chains.
Membrane-based PTA purification is unifying crystallization and solvent recovery steps into single-unit operations that slash steam consumption. Indian and Southeast Asian polyester producers are retrofitting legacy Amoco-style oxidation trains with hollow-fiber separation modules to bypass crystallizer bottlenecks. This technology compression is enabling 150,000-tonne-per-annum expansions on footprints previously limited to 50,000 tonnes.
China's MEE wastewater discharge standards are forcing caprolactam producers to deploy anaerobic ammonia oxidation (anammox) bioreactors for nitrogen removal from Beckmann rearrangement effluent. Sinopec and Hengyi affiliates are commissioning zero-liquid-discharge complexes in Ningbo and Zhuhai that recycle 98% of process water. These installations are reshaping competitive positioning as water-stressed inland provinces restrict new chemical project approvals.
Automotive tier-one suppliers are consolidating intermediate procurement under single-source framework agreements that bundle PTA, MEG, and specialty additives into delivered polymer pricing. This specification transfer compresses spot market participation by fiber intermediate traders and concentrates volume commitments with integrated producers possessing captive logistics infrastructure. The model is most visible in German and Czech automotive textile corridors where just-in-sequence filament delivery mandates eliminate inventory buffers.
Fiber Intermediates Market Segmentation
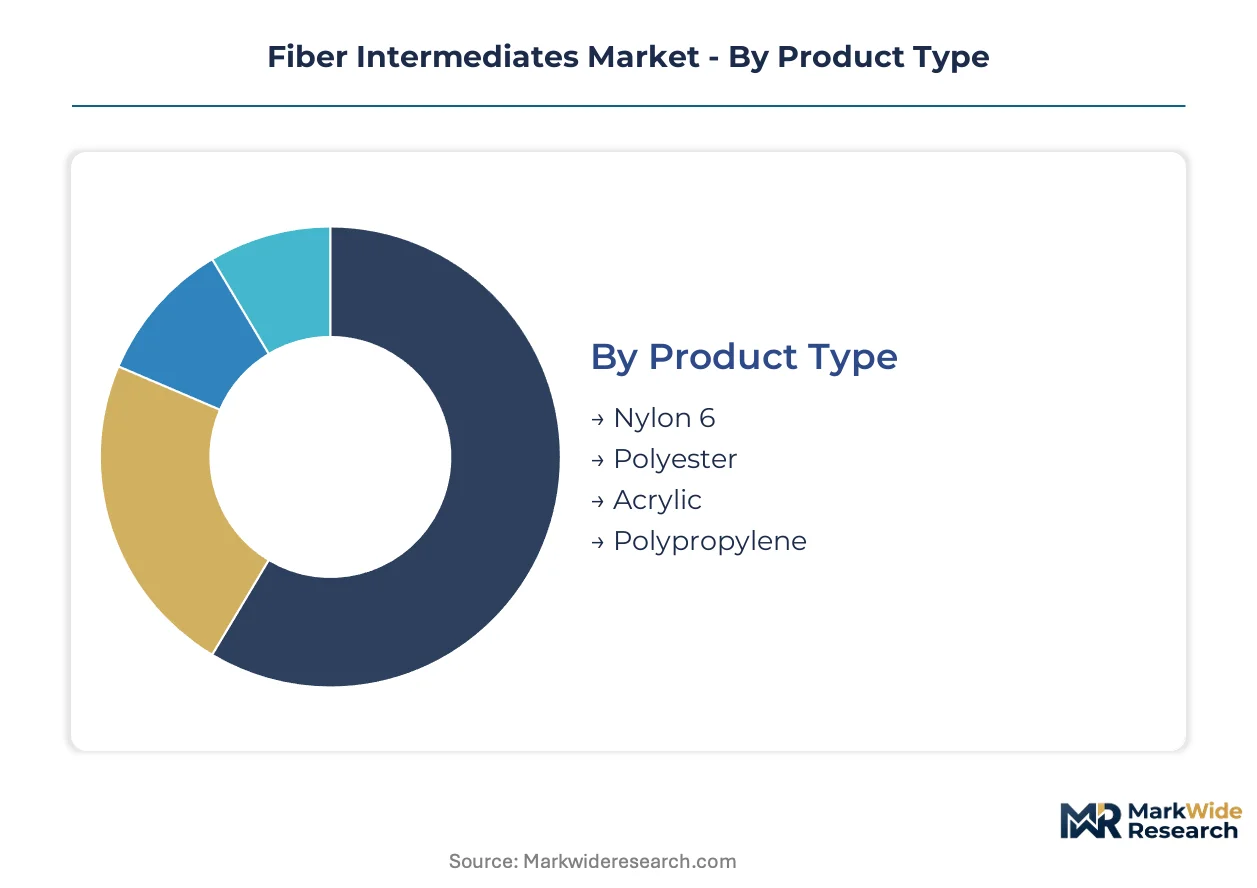
Fiber intermediates fragment across polymer chemistry, end-use performance specifications, and conversion technology. Each dimension carries distinct margin profiles and regulatory exposure that reshape supplier priorities.
Product Type:
Supply concentration clusters around integrated complexes with captive feedstock access and scale-advantaged oxidation or hydrogenation trains.
- Polyester:PTA-MEG integration dominates volume flows, with purified terephthalic acid specifications tightening for bottle-grade and textile-grade differentiation. Demand concentrates in Zhejiang province spinning mills serving export-oriented fabric mills, where MEE wastewater standards force zero-liquid-discharge retrofits that smaller producers cannot finance.
- Nylon 6:Caprolactam polymerization yields high-tenacity filament for automotive airbag yarn and tire cord where specifications exceed 8.0 grams per denier. German and Czech automotive textile corridors anchor premium offtake, with REACH substance restrictions accelerating bio-based alternative qualification timelines.
- Acrylic:Acrylonitrile feedstock volatility compresses margin pools across outdoor upholstery applications.
- Polypropylene:Propylene-based fiber precursors serve industrial geotextile and carpet backing markets with lower energy intensity than condensation polymers.
Polyester absorbs the bulk of installed capacity; nylon 6 is expanding most quickly on automotive lightweighting mandates.
End User:
Customer concentration varies sharply, with automotive procurement consolidating under tier-one framework agreements while textile buying fragments across thousands of mills.
- Textiles:Filament and staple fiber demand concentrates in Surat, Mumbai, and Jiangsu clusters where polyester POY and FDY spinning capacity exceeds downstream weaving throughput.
- Automotive:Seating, airbag, and tire cord specifications tighten as OEMs substitute recycled PET fabrics for leather and vinyl to meet CAFE targets. Just-in-sequence delivery mandates in German and Czech corridors eliminate inventory buffers and concentrate procurement with integrated suppliers.
- Industrial:High-tenacity nylon 6,6 and aramid precursors serve conveyor belting and rope applications where failure tolerance approaches zero.
- Home Furnishings:Carpeting and upholstery demand pivots toward solution-dyed polyester with superior UV degradation resistance, displacing acrylic alternatives.
Textile offtake maintains volume dominance; automotive represents the steepest expansion trajectory on specification upgrading.
Application:
Performance requirements diverge across wear resistance, flammability, and dye uptake specifications that dictate intermediate purity grades.
- Clothing:Polyester filament for fast fashion and athleisure demands rapid dye cycle compatibility and moisture-wicking surface treatments.
- Upholstery:Automotive and residential seating specifications prioritize abrasion resistance and flame retardancy, with REACH restrictions on legacy additives forcing reformulation.
- Carpeting:Nylon 6,6 BCF yarn dominates commercial installations for resilience under heavy foot traffic, while polypropylene gains share in disposable residential applications.
- Industrial Fabrics:Geotextiles, filtration media, and reinforcement scrims require UV stabilization and chemical resistance that command intermediate purity premiums.
Upholstery commands intermediate purity premiums; industrial fabrics are climbing the fastest on infrastructure spending.
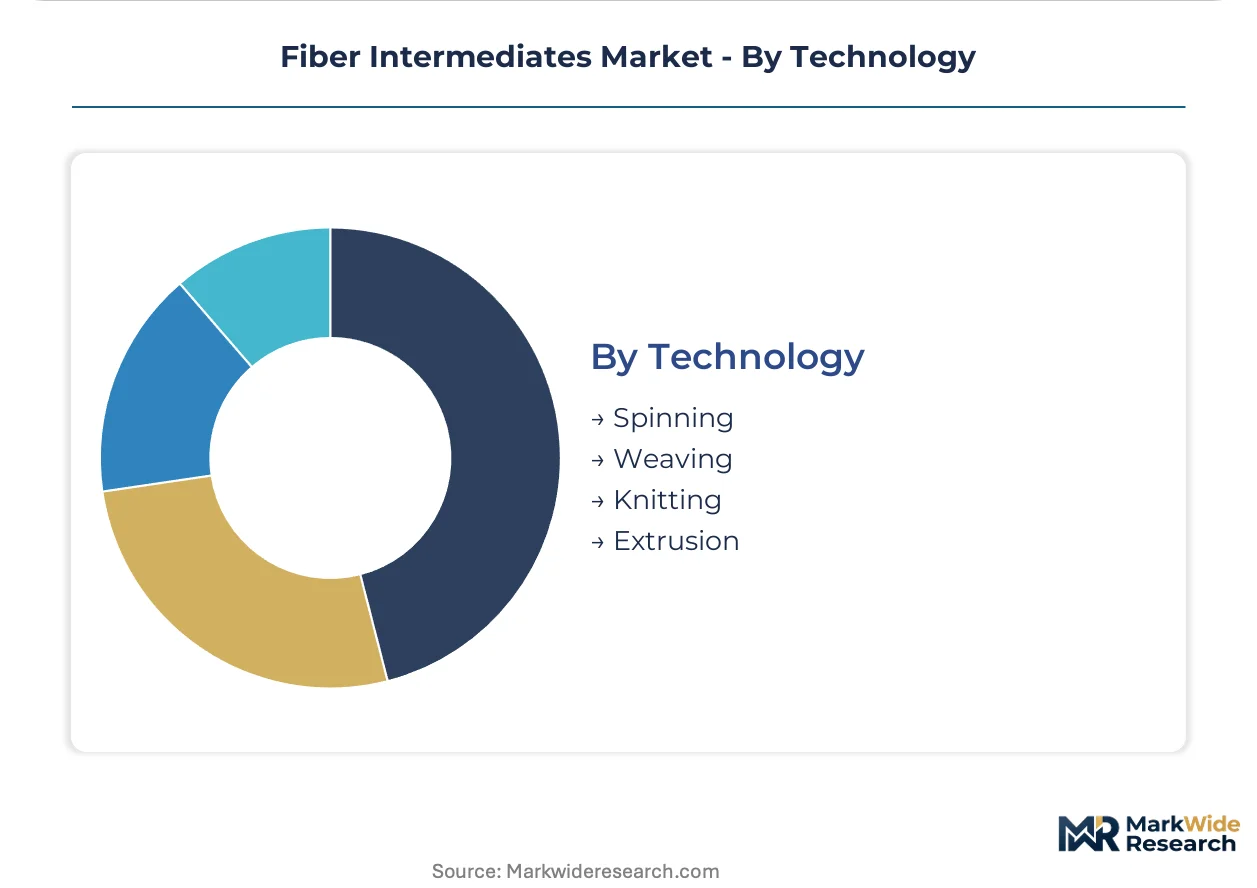
Technology:
Conversion technology selection locks in intermediate morphology and downstream processing economics.
- Spinning:Melt spinning of polyester and nylon dominates synthetic fiber output, with POY, FDY, and DTY variants requiring differentiated intermediate viscosity and moisture specifications.
- Weaving:Warp and weft preparation demands filament with controlled interlacing performance and sizing compatibility.
- Knitting:Circular and flatbed knitting of staple fiber and textured filament serves apparel and technical fabric markets with rapid style turnover.
- Extrusion:Monofilament and tape extrusion for industrial netting and strapping applications requires narrow molecular weight distribution in intermediate polymers.
Spinning anchors capacity deployment; extrusion is gaining share fastest on industrial specialty expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Zhejiang province's Zhoushan Petrochemical Zone anchors the densest concentration of PTA and caprolactam capacity globally, with integrated refineries feeding downstream filament operations.
China
MEE wastewater inspections are shuttering small caprolactam producers in inland provinces while concentrating supply around Ningbo and Zhuhai zero-liquid-discharge complexes. The dual carbon goals accelerate coal-to-chemical capacity retirements. Jiangsu province spinning mills now source 70% of PTA feedstock from Zhejiang integrated complexes via dedicated pipeline corridors.
Germany
REACH substance restrictions force automotive textile suppliers to reformulate adipic acid catalyst systems ahead of 2026 authorization deadlines. The KBA enforces material compliance documentation across seating and airbag yarn supply chains. Ludwigshafen's chemical complex sustains captive caprolactam supply chains that bypass third-party qualification bottlenecks for tier-one automotive contracts.
United States
EPA Clean Air Act emissions standards tighten VOC thresholds for adiponitrile operations serving tire cord manufacturers. NHTSA fuel economy mandates compress seating specification tolerances for recycled PET fabrics. Texas Gulf Coast paraxylene crackers supply PTA producers with feedstock cost advantages when naphtha spreads widen against crude benchmarks.
India
PLI scheme incentives for technical textiles accelerate Surat and Mumbai nylon 6 filament capacity expansions. BIS quality certification requirements concentrate import substitution benefits with domestic caprolactam producers. Gujarat's Dahej petroleum complex anchors planned PTA-MEG integration projects targeting polyester POY spinning clusters.
Japan
METI carbon neutrality roadmaps pressure caprolactam producers to deploy hydrogen-derived feedstock pathways. JIS standards tighten intermediate purity specifications for automotive airbag yarn exports. Chubu region chemical complexes maintain specialized adiponitrile technology licensing positions serving regional tire cord manufacturers.
Fiber Intermediates Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across fiber intermediate supply chains. The market structure concentrates around integrated petrochemical complexes with captive feedstock access and scale-advantaged oxidation trains. Three archetypes dominate: global diversified chemical majors with backward integration into paraxylene and butadiene, regional specialists with proprietary catalytic technologies, and captive producers serving affiliated textile operations. Competitive moves center on zero-liquid-discharge retrofits for regulatory compliance and single-source framework agreements bundling intermediates with logistics services.
Within the diversified chemical major tier, BASF SE and Dow Chemical Company exemplify integrated operations spanning upstream aromatics through downstream polymer supply. Invista occupies a specialized position through proprietary adiponitrile technology licensing that dominates nylon 6,6 precursor economics. Reliance Industries Limited anchors the captive producer archetype with refinery-integrated PTA capacity feeding affiliated spinning operations.
| Leading Market Players |
|---|
| Reliance Industries Limited |
| BASF SE |
| Dow Chemical Company |
| Invista |
| Fiber Intermediate Products Company |
| Daicel Corporation |
| DSM Fiber Intermediates |
| Domo Chemicals |
| Chevron Phillips Chemical Company |
| Others |
Supply Flow & Price Mechanics
Paraxylene feedstock costs cascade through PTA and caprolactam pricing tiers, with naphtha-linked volatility compressing margins for non-integrated producers while captive refinery complexes in Zhejiang and Texas Gulf Coast sustain cost advantages across contract and spot markets.
Pricing Analysis
Short lead-time premiums for automotive airbag yarn intermediates sustain 15-20% markups over standard textile-grade contracts, while spot inventory discounts deepen during Chinese New Year demand lulls. Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified bio-based caprolactam from conventional adipic acid catalyst systems and unbranded commodity PTA. Pricing pressure stems from adiponitrile supply concentration that limits new nylon 6,6 precursor entrants. Tier-one automotive suppliers exhibit lowest price sensitivity due to just-in-sequence delivery mandates, whereas Surat spinning mills negotiate aggressively on MEG volumes.
Supply Chain Analysis
Reverse-logistics flows for spent Beckmann rearrangement catalysts and recovered adipic acid from tire cord manufacturing are concentrating around Ludwigshafen and Ningbo zero-liquid-discharge complexes. Supply concentrates in China, Germany, and India, with PTA capacity clustering in Zhejiang province and caprolactam production anchoring in Ningbo and Zhuhai. Raw material dependencies rest on paraxylene from Middle Eastern naphtha crackers, butadiene for adiponitrile synthesis, and ammonia for caprolactam hydrogenation. Single-source vulnerability pervades adiponitrile technology licensing. Distribution runs through pipeline corridors feeding Jiangsu spinning mills and just-in-sequence rail links to German automotive textile corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fiber intermediates sector is traversing a catalytic technology transition, with membrane-based PTA purification and anammox bioreactor wastewater systems displacing legacy Amoco-style oxidation trains and conventional nitrogen removal across Chinese and European complexes.
For Market Incumbents: Lock in captive feedstock access through refinery-integrated paraxylene supply chains that insulate against naphtha spread volatility threatening non-integrated PTA producers. Prioritize zero-liquid-discharge retrofits at Ningbo and Ludwigshafen complexes to preempt MEE and REACH effluent enforcement that will shutter smaller competitors. Deepen backward integration into butadiene for adiponitrile production to defend proprietary technology licensing positions against bio-based alternative entrants. For New Entrants and Emerging Players: India's PLI scheme for technical textiles opens a window for domestic caprolactam production serving Surat and Mumbai nylon 6 filament expansions. Target water-based spin finish formulations for high-speed POY spinning operations as EU F-Gas Regulation phase-down displaces fluoropolymer processing aids. Pursue carbon fiber precursor markets for acrylonitrile copolymers where aerospace-grade PAN commands tenfold margin premiums over commodity textile applications. For Investors and Strategic Acquirers: Sinopec and Hengyi affiliates commissioning zero-liquid-discharge complexes in Ningbo and Zhuhai is the leading indicator that environmental compliance will consolidate Chinese supply over a 5-10 year horizon. Acquire regional specialists with proprietary catalytic hydrogenation expertise in caprolactam and adipic acid operations where aging European and North American workforces cannot replenish technical talent. Monitor REACH authorization timeline compression for bio-based caprolactam alternatives as signal of incumbent vulnerability.| Strategic Initiative | Industry Significance |
|---|---|
| Zero-Liquid-Discharge Retrofit | MEE inspections in China are shuttering non-compliant caprolactam producers, concentrating supply with upgraded complexes. |
| Backward Integration into Paraxylene | Refinery-integrated PTA operations in Zhejiang bypass naphtha spread volatility compressing standalone producer margins. |
| Bio-Based Caprolactam Qualification | REACH substance restrictions on legacy adipic acid catalysts accelerate alternative authorization timelines for automotive yarn. |
| Single-Source Framework Agreement | German automotive textile corridors bundle PTA, MEG, and additives into delivered polymer pricing, eliminating spot market participation. |
| Carbon Fiber Precursor Repositioning | Acrylonitrile producers pivot acrylamide copolymer technology toward aerospace-grade PAN markets with superior margin profiles. |
Methodological Framework
Multi-period observation of PTA and caprolactam capacity utilization rates, MEE inspection enforcement patterns, and REACH authorization timelines anchored the trend analysis, supplemented by interviews with plant managers at integrated petrochemical complexes, procurement leads at automotive tier-one suppliers, distribution channel partners in Surat and Jiangsu textile clusters, and technical R&D directors specializing in catalytic hydrogenation. Secondary validation drew from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings of diversified chemical majors, and EPA Clean Air Act emissions disclosures. Bottom-up capacity modeling and top-down demand aggregation from end-use sectors provided triangulation.
Segment-weighting across product type, end user, application, and technology dimensions structured the analytical framework, with polymer chemistry and conversion technology carrying distinct margin profile assumptions across the projection horizon. CAGRs derived from installed capacity expansion announcements, regulatory-driven retrofit timelines, and automotive lightweighting mandate compliance schedules. Forecast inputs incorporated naphtha-to-paraxylene spread trajectories and adiponitrile technology licensing restrictions.
The model assumes a particular technology adoption path; alternative pathways for membrane-based PTA purification or hydrogen-derived caprolactam feedstocks would alter the outlook if cost thresholds shift unexpectedly. Forecasts reflect assumptions about REACH authorization pacing and MEE enforcement continuity. Practitioners should monitor naphtha spread volatility, bio-based intermediate qualification timelines, and zero-liquid-discharge commissioning rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fibers
Global Fiberglass Mold Market
Fibers
Viscose Staple Fiber Market
Fibers
Global Glass Fiber Reinforced Gypsum (GFRG) Market
Fibers
Triacetate Cellulose Market
Fibers
Polytetrahydrofuran Market
Fibers
Activated Carbon Fiber (ACF) Market
Fibers
Europe Carbon Fiber Market
Fibers
E-Glass Fiber Market
Fibers
Acoustical Fiber Board Market
Fibers
Asia-Pacific Carbon Fiber Market
Fibers
Metal Fiber Felt Market
Fibers
Ceramic Fiber Market
Fibers
Continuous Fiber Thermoplastic (CFT) Market
Fibers
Carbon Fiber Market
Fibers
North America Carbon Fiber Market
Fibers
Bleached Linter Cellulose Market