
 North America Optical Fiber Raw Material Market | 2026-2036
North America Optical Fiber Raw Material Market Size, Share, and Industry Trends Forecast 2026-2036
North America Optical Fiber Raw Material Market Insights
Software-defined network management is shifting how raw material suppliers monetize fiber deployments. Corning Incorporated leverages captive silica refining to sustain margin control across the value chain. OFS Fitel anchors its position through specialized coating chemistry for high-count ribbon cables.
North America optical fiber raw material encompasses silica-based preforms, polymer coatings, and reinforcement elements engineered to precise refractive-index tolerances for light transmission across telecommunications and sensing systems. Glass fiber dominates volume demand, while specialty fiber captures premium pricing in military and sensing applications. Silica material grades differentiate suppliers, with telecom providers and government agencies representing the largest end-user pools.
FCC broadband equity standards, EPA emissions rules for chemical vapor deposition, and OSHA fiber handling protocols collectively shape product certification and facility siting across the United States and Canada. The FCC's BEAD program mandates domestic content thresholds that redirect procurement patterns. Stakeholders must monitor how NIST optical standards evolve to assess which material grades qualify for federal infrastructure subsidies.
Market Dynamics
FCC broadband equity mandates are restructuring raw material procurement by requiring domestic content verification at the silica refining stage, forcing suppliers to relocate purification capacity from offshore to Texas and Arizona chemical processing corridors.
Growth Catalysts
- BEAD Program Mandates:The FCC's Broadband Equity, Access, and Deployment program requires fiber infrastructure funded through its $42 billion allocation to meet domestic sourcing thresholds. This redirects preform procurement toward North American silica refiners.
- Data Center Cluster Expansion:Hyperscale facility construction in Northern Virginia, Dallas-Fort Worth, and Phoenix is consuming ribbon cable at volumes that justify dedicated coating chemistry production lines within the region.
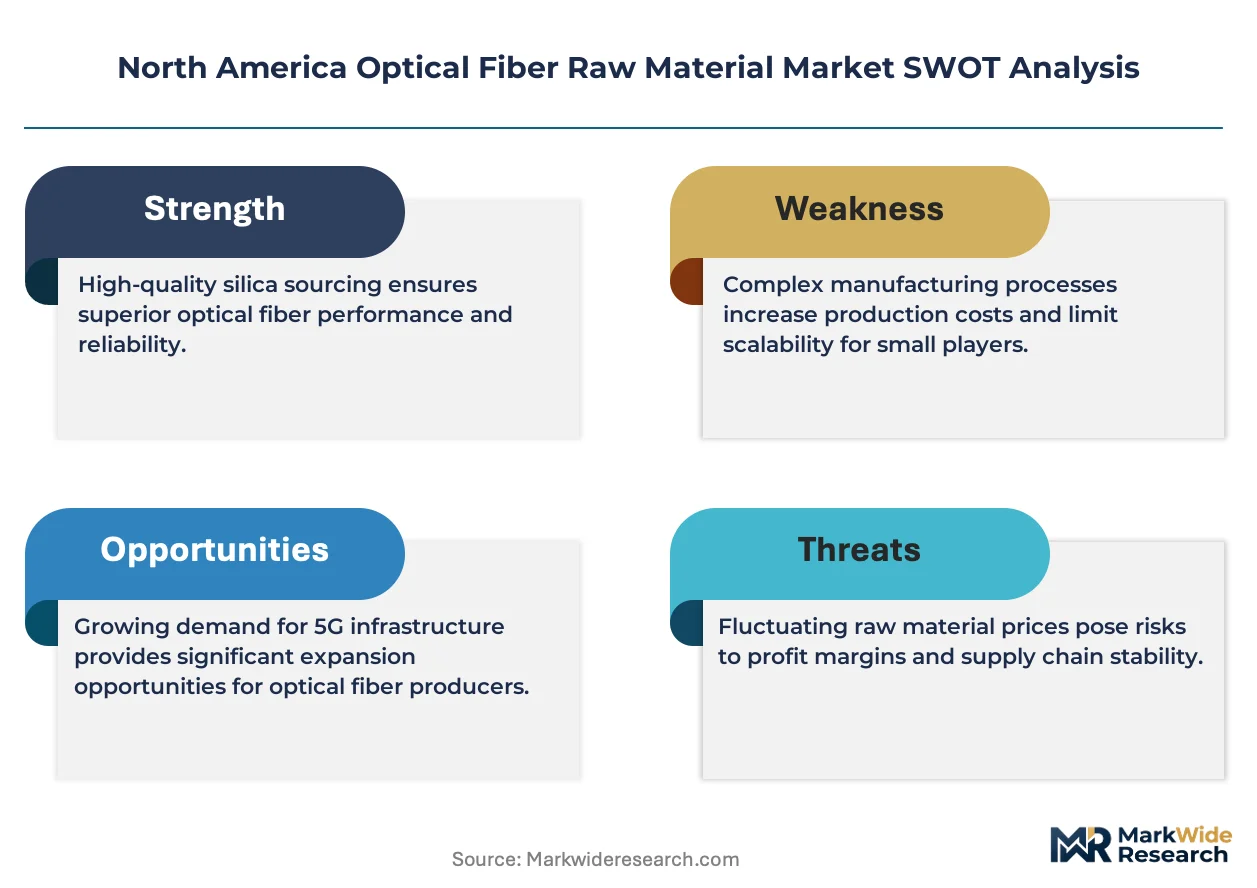
- Silica Purification:Advances in chemical vapor deposition process control are reducing optical attenuation in telecom-grade fiber, enabling longer unrepeatered spans that reduce installation labor costs for rural deployments.
Market Restraints
- High-Purity Silica Concentration:Semiconductor-grade silicon tetrachloride supply concentrates among Gulf Coast petrochemical complexes, exposing fiber preform manufacturers to hurricane-related production interruptions.
- EPA Emissions Compliance:Chemical vapor deposition facilities face tightening volatile organic compound limits under Clean Air Act Title V permits, extending environmental review timelines for greenfield purification plants.
- Copper Cable Residual:Legacy coaxial infrastructure in multi-dwelling units and established suburban neighborhoods delays fiber-to-the-premises conversion where building access agreements prove contentious.
Strategic Opportunities
- Canadian Arctic Connectivity:Indigenous community broadband initiatives and mining camp communications are creating demand for armored submarine cable components that withstand permafrost heave and ice scour.
- Polymer Coating Innovation:Low-smoke zero-halogen formulations for data center plenum routing command price premiums over standard acrylate coatings while meeting NFPA 90A fire safety protocols.
- Smart Grid Integration:Distributed fiber optic sensing for power line temperature and vibration monitoring converges photonic hardware with utility operational technology, opening adjacent demand from FERC-regulated transmission operators.
Industry Challenges
- Specialized Technician Scarcity:Fusion splicing and optical time-domain reflectometry certification programs at community colleges cannot match deployment workforce requirements in rural Montana and New Mexico markets.
- Preform-to-Fiber Capital Intensity:Draw tower installations exceeding 30 meters in height require specialized structural foundations and climate-controlled draw environments that extend facility commissioning timelines.
- OSHA Silica Exposure Protocols:Respirable crystalline silica monitoring requirements for raw material handling operations mandate continuous personal sampling and medical surveillance programs that elevate operational overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Optical Fiber Raw Material Market |
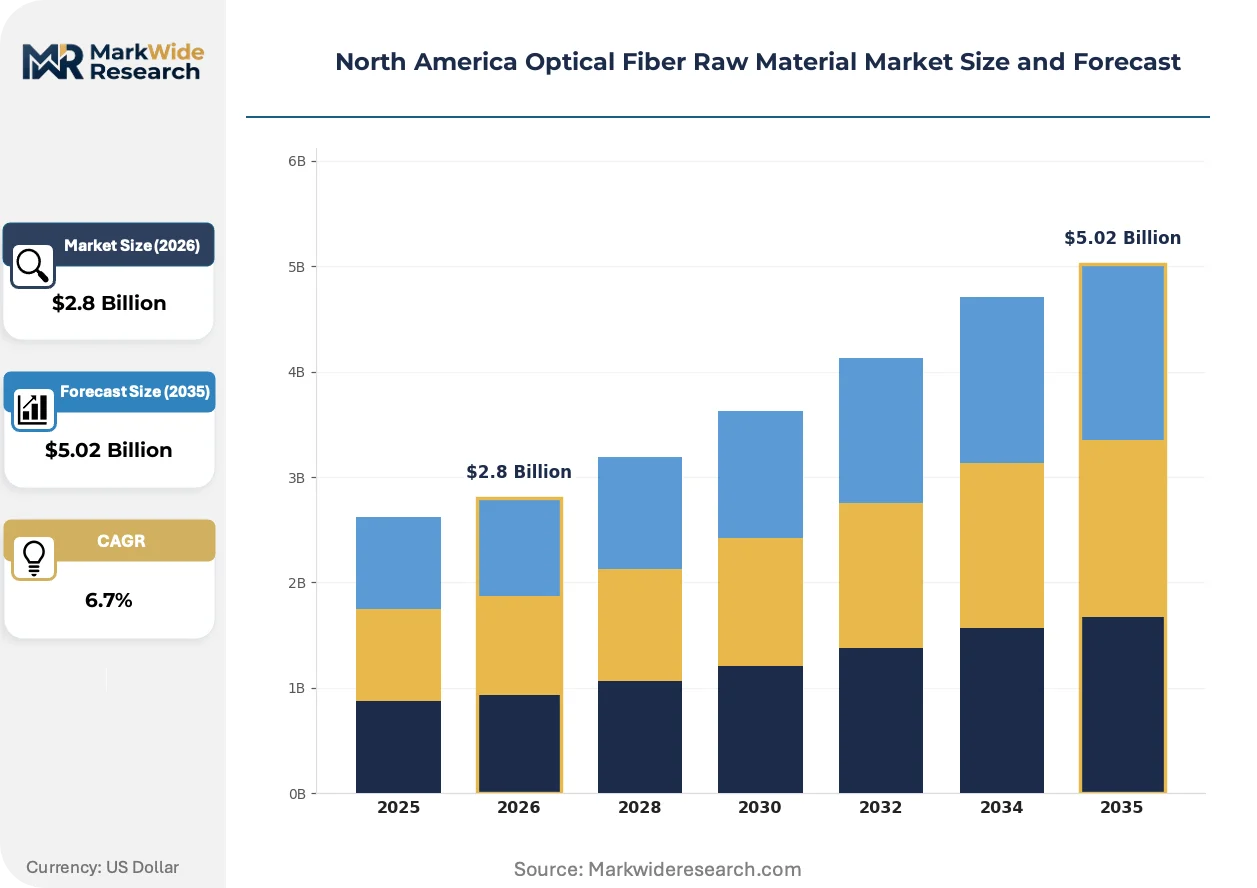
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glass Fiber, Plastic Fiber, Specialty Fiber, Hybrid Fiber Material: Silica, Polymer, Coating Material, Reinforcement Application: Telecommunications, Data Centers, Industrial Networking, Military End User: Telecom Providers, ISPs, Enterprises, Government Agencies |
| Companies Covered | Corning Incorporated, CommScope Holding Company, OFS Fitel, General Cable Corporation, Prysmian Group, AFL, Superior Essex, Furukawa Electric, Sterlite Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Optical Fiber Raw Material Market Trends and Innovations
Material science advances and procurement protocol evolution are compressing the traditional separation between raw material specification and finished cable performance verification.
Multicore fiber is unifying spatial division multiplexing with existing single-mode infrastructure by embedding multiple light-guiding channels within a single cladding structure. Verizon and AT&T laboratory trials are validating compatibility with conventional ribbon cable manufacturing equipment. This unification is collapsing the distinction between metro and long-haul fiber grades, enabling suppliers to standardize preform designs across deployment types.
EPA New Source Performance Standards for synthetic organic chemical manufacturing are compelling silica precursor producers to install regenerative thermal oxidizers and continuous emissions monitoring systems. The industrial consequence is a 15-24 month extension in air permit acquisition timelines for new chemical vapor deposition capacity. Texas and Louisiana environmental agencies are responding by creating consolidated permit review tracks for fiber supply chain investments.
Buyers are consolidating vendor qualification lists around suppliers offering integrated preform-to-coating material certification. Tier-one cable manufacturers are displacing multi-source procurement with single-source accountability contracts that bundle silica purity guarantees with coating adhesion specifications. This concentration is most visible in California, where CPUC-mandated middle-mile projects require documented material traceability from refined sand to installed cable.
North America Optical Fiber Raw Material Market Segmentation
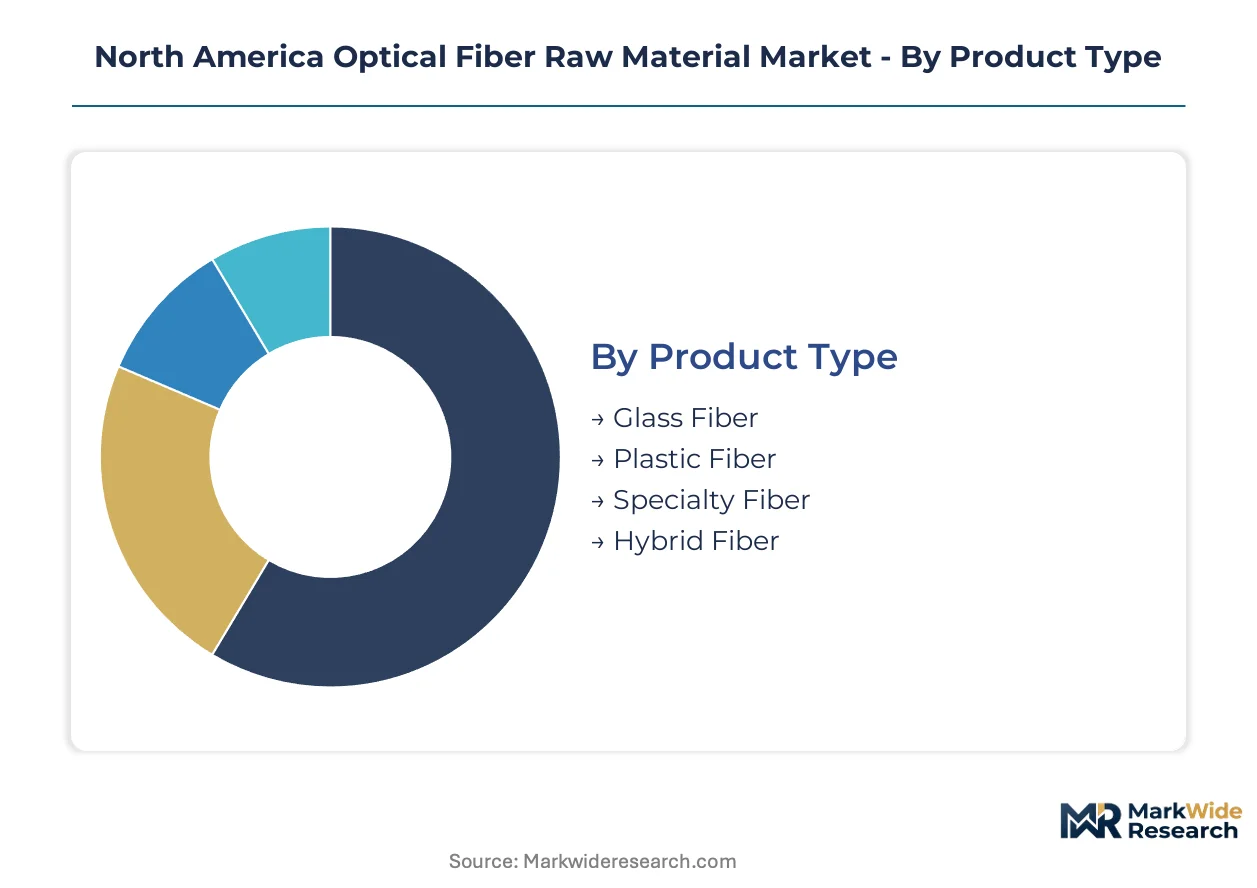
Raw material procurement patterns in North America optical fiber diver sharply across end-use specifications, with hyperscale data centers demanding coating chemistries that differ materially from rural telecom deployments. Segmentation reveals how silica purity grades, polymer formulations, and reinforcement architectures align with distinct buyer technical requirements and regulatory exposure.
Product Type:
Buyers differentiate primarily by attenuation tolerance and environmental durability requirements, with data center operators prioritizing bend-insensitive designs while military programs specify radiation-hardened variants.
- Glass Fiber:Silica-based single-mode and multimode constructions dominate volume demand, with Texas and Virginia data center corridors consuming ribbon cable formats at scale. FCC BEAD program rural buildouts sustain standard telecom-grade consumption despite price compression from offshore suppliers.
- Specialty Fiber:Polarization-maintaining and rare-earth-doped variants command premium positioning for distributed acoustic sensing and laser pump applications. Canadian Arctic connectivity initiatives and US military sensing programs concentrate demand in radiation-tolerant and temperature-extreme specifications.
- Plastic Fiber:Perfluorinated polymer cores serve short-reach automotive and industrial automation links where bend radius flexibility outweighs attenuation penalties.
- Hybrid Fiber:Composite glass-plastic constructions address constrained installation environments in multi-dwelling units where legacy conduit dimensions limit pure glass deployment.
Glass fiber leads volumes today; specialty fiber is gaining share fastest.
Material:
Cost tier stratification separates semiconductor-grade silica refiners from commodity polymer compounders, with environmental compliance burden concentrating procurement among integrated suppliers.
- Silica:High-purity silicon tetrachloride and synthetic quartz feedstocks form the optical core, with chemical vapor deposition process control determining attenuation performance. Gulf Coast petrochemical corridor concentration exposes supply continuity to hurricane seasonality.
- Coating Material:UV-curable acrylates and low-smoke zero-halogen formulations protect the glass surface from microbending and moisture ingress. NFPA 90A plenum routing mandates in California and New York data centers drive specification upgrades from standard to fire-rated chemistries.
- Polymer:Buffer tubes and cable jackets employ polyethylene and polypropylene compounds, with resin selection driven by outdoor aerial versus underground deployment mechanics.
- Reinforcement:Aramid yarns and fiberglass rods provide tensile strength for installation pulling loads, with armored submarine cable variants incorporating steel wire for ice scour protection in Canadian Arctic deployments.
Silica dominates value capture; coating material is climbing the fastest on specification upgrades.
Application:
Volume scale separates metro fiber builds from niche industrial networks, with data center interconnection demanding ribbon cable formats that reshape preform and coating production line configurations.
- Telecommunications:Verizon and AT&T infrastructure programs consume standard single-mode fiber at massive scale, with FCC broadband equity mandates redirecting procurement toward domestic content-verified supply chains.
- Data Centers:Hyperscale facility construction in Northern Virginia, Dallas-Fort Worth, and Phoenix drives high-fiber-count ribbon cable consumption. Low-latency requirements favor bend-insensitive fiber designs with specialized coating adhesion properties.
- Industrial Networking:Manufacturing automation and process control applications deploy ruggedized cable with enhanced chemical and temperature resistance for refinery and automotive plant environments.
- Military:Aerospace and naval platforms specify radiation-hardened and high-strength variants, with ITAR compliance restrictions limiting supplier qualification pools.
Telecommunications leads volumes today; data centers are expanding most quickly.
End User:
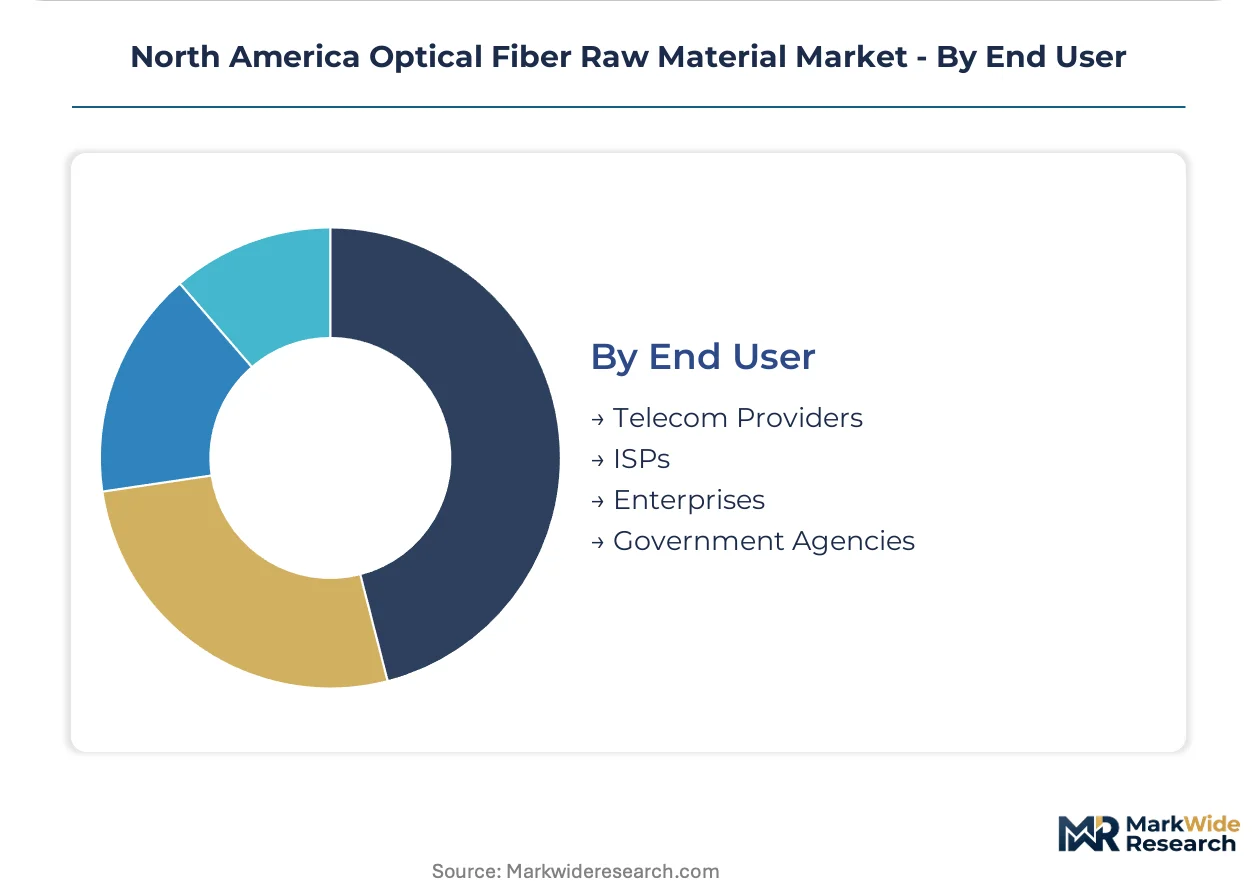
Procurement sophistication varies dramatically, with government agencies imposing material traceability requirements that Tier-1 cable manufacturers satisfy through integrated preform-to-coating certification.
- Telecom Providers:Verizon, AT&T, and regional carriers dominate volume procurement, consolidating vendor lists around suppliers offering bundled silica purity and coating adhesion guarantees. BEAD program domestic content thresholds reshape qualification criteria.
- ISPs:Competitive local exchange carriers and municipal networks purchase through distributor channels, with price sensitivity favoring standard specifications over premium formulations.
- Enterprises:Financial services and healthcare campus networks drive demand for plenum-rated and security-sensitive fiber installations, with HIPAA compliance influencing physical layer documentation requirements.
- Government Agencies:Federal and state broadband programs mandate domestic sourcing verification at the silica refining stage, with CPUC-mandated California middle-mile projects requiring documented material chain-of-custody.
Telecom providers lead volumes today; government agencies are gaining procurement share fastest on infrastructure stimulus deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's Arctic connectivity initiatives contrast with Mexico's industrial automation corridors, revealing how geography and policy divergence reshape raw material demand patterns across North America.
United States
Verizon and AT&T infrastructure programs consume silica preforms at massive scale across Texas and Virginia data center corridors. FCC BEAD program mandates redirect procurement toward domestic content-verified supply chains with documented silica refining provenance. Northern Virginia's hyperscale facility cluster drives ribbon cable coating chemistry production at dedicated regional lines.
Canada
Indigenous community broadband initiatives and mining camp communications armored submarine cable components for permafrost heave resistance. Federal connectivity subsidies prioritize northern deployment with material traceability requirements from refined sand to installed cable. Ontario and Quebec chemical processing corridors host purification capacity serving Arctic submarine cable specifications.
Mexico
Manufacturing automation in automotive and aerospace maquiladoras deploys ruggedized fiber for process control networks. Mexican federal industrial development programs incentivize fiber infrastructure in export-oriented manufacturing zones. Baja California and Nuevo León industrial corridors concentrate demand for temperature-extreme cable specifications.
North America Optical Fiber Raw Material Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated preform-to-coating suppliers commanding premium positioning against component-focused compounders. Market structure tilts toward consolidation among Gulf Coast silica refiners exposed to hurricane seasonality, while coating chemistry remains more fragmented. Three archetypes dominate: captive silica refiners with petrochemical integration, specialized coating formulators serving data center specifications, and diversified cable manufacturers backward-integrating into material production. Capacity expansion and strategic partnerships represent the dominant competitive moves, as environmental permitting timelines favor brownfield expansions over greenfield developments.
Among North American-based suppliers, Corning Incorporated exemplifies the captive refiner archetype through its integrated silica supply chain, while OFS Fitel occupies a specialist position in high-count ribbon cable coating chemistry. CommScope Holding Company represents the diversified cable manufacturer archetype with material production capabilities spanning multiple specification tiers.
| Leading Market Players |
|---|
| Corning Incorporated |
| CommScope Holding Company |
| OFS Fitel |
| General Cable Corporation |
| Prysmian Group |
| AFL |
| Superior Essex |
| Furukawa Electric |
| Sterlite Technologies |
| Others |
Pricing and Supply Chain Analysis
FCC BEAD program domestic content thresholds are compelling cable manufacturers to requalify suppliers around silica refining provenance, forcing capacity relocation to Texas and Arizona chemical processing corridors and compressing margins for offshore-dependent compounders.
Pricing Analysis
Capacity additions in the Texas and Louisiana Gulf Coast petrochemical corridor are reshaping price floors for semiconductor-grade silicon tetrachloride. Contract-based long-term offtake agreements dominate, with price differentiation resting on silica purity certification and coating chemistry specification tiers. Cost compression in standard telecom-grade fiber is intensifying because offshore suppliers are absorbing tariff exposure to defend volume share. Municipal networks and competitive local exchange carriers exhibit highest price sensitivity, while hyperscale data center operators prioritize coating adhesion guarantees over unit economics.
Supply Chain Analysis
FCC domestic content mandates are redirecting procurement toward North American silica refiners with documented chain-of-custody from refined sand to installed cable. High-purity silicon tetrachloride feedstock draws from Texas, Louisiana, and limited Ontario chemical processing capacity. Chemical vapor deposition equipment, rare-earth doping precursors, and UV-curable acrylate resin formulations represent critical input dependencies. Hurricane seasonality along the Gulf Coast creates single-source vulnerability for purification capacity. Distribution runs through Tier-1 cable manufacturers with integrated preform-to-coating certification serving qualified vendor lists at Verizon, AT&T, and BEAD program recipients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America optical fiber raw material market reads as a late-cycle quality story, with hyperscale data center operators and federal broadband programs converging demand toward low-smoke zero-halogen coating specifications and documented material traceability.
For Market Incumbents: Anchor market position through captive silica refining investments in Texas and Arizona chemical processing corridors to satisfy FCC BEAD program domestic content verification requirements. Deepen backward integration into coating chemistry formulation for high-count ribbon cable specifications demanded by Northern Virginia and Dallas-Fort Worth hyperscale clusters. Defend against offshore price competition by bundling silica purity guarantees with NFPA 90A plenum-rated coating certifications. For New Entrants and Emerging Players: Capture procurement share in Canadian Arctic connectivity initiatives requiring armored submarine cable components with permafrost heave and ice scour resistance specifications underserved by incumbent coating formulators. Target Indigenous community broadband programs and mining camp communications networks with temperature-extreme fiber designs. Differentiate through specialized reinforcement architectures rather than competing on standard telecom-grade silica economics. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized coating chemistry formulators possessing NFPA 90A plenum-rated formulations and documented supply chain traceability systems. Long-term viability hinges on positioning for federal infrastructure stimulus deployment cycles and hyperscale data center construction waves. Watch EPA New Source Performance Standards permitting timelines as inflection indicators for brownfield versus greenfield capacity economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silica Refining | FCC BEAD domestic content mandates require documented refining provenance from Texas and Arizona corridors. |
| Coating Chemistry Capacity Expansion | Hyperscale data center construction in Northern Virginia and Phoenix consumes high-count ribbon cable formulations. |
| Arctic Cable Specification Development | Canadian federal connectivity subsidies prioritize armored submarine components for permafrost heave resistance. |
| Long-term Supply Agreement with Tier-1 Cable Manufacturers | Verizon and AT&T infrastructure programs consolidate procurement around integrated preform-to-coating certification. |
| Joint Venture with Gulf Coast Petrochemical Complex | Semiconductor-grade silicon tetrachloride supply concentrates among hurricane-exposed Louisiana and Texas facilities. |
Research Methodology
Coverage spans the United States, Canada, and Mexico, with primary inputs from each national market combining executive interviews with optical fiber preform manufacturing directors, procurement leads at Tier-1 cable manufacturers, chemical vapor deposition process engineers, and regulatory affairs specialists at FCC program recipients. Secondary validation draws from SEC 10-K filings of listed suppliers, EPA Title V air permit databases, FCC BEAD program funding allocation records, and customs trade data for silica precursor imports. Bottom-up demand modeling triangulates against top-down infrastructure spending projections.
Rate-of-change decomposition separates volume growth from specification mix shifts across the analysis window. Segmentation dimensions include product type, material grade, application, and end-user procurement sophistication. CAGRs derive from modeled deployment timelines for Verizon and AT&T infrastructure programs, hyperscale data center construction pipelines, and FCC broadband equity funding disbursement schedules. Industry-specific forecast inputs incorporate chemical vapor deposition capacity utilization rates and coating chemistry production line commissioning timelines.
EPA emissions rule amendments, hurricane-related production interruptions along the Gulf Coast, and BEAD program funding disbursement delays are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding domestic content threshold enforcement and silica refining capacity expansion schedules. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fibers
Polytetrahydrofuran Market
Fibers
4-Strand Fan-Shaped Strand Wire Rope Market
Fibers
Global Basalt Fiber Market
Fibers
Fiberglass Cloth Market
Fibers
Asia Pacific Ceramic Fiber Market
Fibers
Basalt Continuous Fiber (BCF) Market
Fibers
Thermoformed Fiber Market
Fibers
Global Fiber Reinforced Composites Market
Fibers
Global Electronic Fiberglass Market
Fibers
Carbon Fiber Wrap Market
Fibers
Micro-Fibrillated Cellulose Market
Fibers
Precision Fiber Molding Market
Fibers
Global Bicomponent Fiber Market
Fibers
Renewable Carbon Fibers Market
Fibers
Asia-Pacific Insoluble Dietary Fibers Market
Fibers
Global Concrete Fiber Market