
 AR Collaboration Software Market | 2026-2036
AR Collaboration Software Market Size, Share, and Industry Trends Forecast 2026-2036
AR Collaboration Software Market Insights
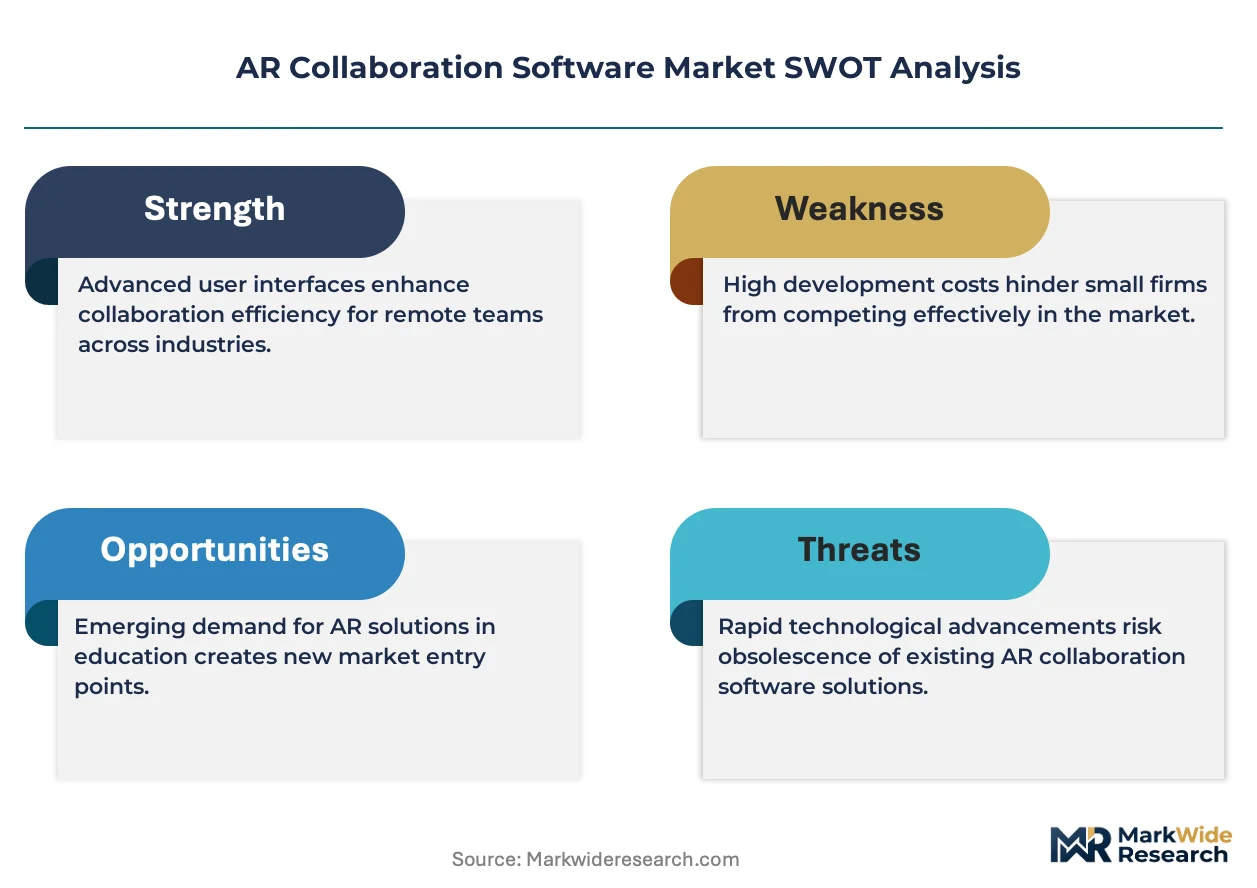
Subscription-based project financing and equipment-leasing models is tilting competitive dynamics toward asset-light entrants that bypass heavy upfront infrastructure spend. Microsoft leverages its Azure cloud backbone to anchor enterprise deployments across manufacturing verticals. PTC specializes in industrial AR overlays that sustain premium positioning through deep CAD integration.
AR collaboration software fuses spatial computing, real-time video streaming, and 3D annotation to enable geographically distributed teams to manipulate shared virtual objects with sub-100-millisecond latency. The technology serves industrial troubleshooting, surgical training, and architectural co-design by projecting persistent digital twins onto physical environments. Remote Assistance applications dominate current deployment value as manufacturers prioritize downtime reduction over immersive training. Cloud-based Platforms capture the fastest expansion trajectory as IT departments trade capital expenditure for elastic compute scaling. Wearable Devices remain a concentrated margin pool despite hardware unit constraints, since head-mounted displays command higher per-seat software attach rates.
FDA scrutiny of AR-guided surgical workflows shapes healthcare adoption timelines and validation requirements for clinical collaboration tools. The EU AI Act and GDPR impose algorithmic transparency and cross-border data localization standards that vendors must architect into platform foundations. Stakeholders must weigh regulatory compliance investment against vertical-specific certification barriers when selecting geographic expansion sequences.
Market Dynamics
Cloud-based platform architectures are compressing deployment timelines from months to weeks, forcing incumbent vendors to abandon perpetual-license models and restructure engineering teams around subscription-native delivery.
Growth Catalysts
- EU AI Act compliance mandates:Algorithmic transparency requirements for AR-guided workflows in German automotive plants are accelerating procurement of GDPR-aligned collaboration suites with built-in audit trails.
- Industrial downtime reduction:Real-time remote assistance on assembly lines delivers measurable productivity gains, with maintenance teams prioritizing sub-100-millisecond latency tools over immersive training modules.
- Azure backbone penetration:Microsoft's cloud infrastructure enables elastic compute scaling that mid-market manufacturers previously could not access, expanding addressable demand beyond Fortune 500 accounts.
Market Restraints
- Head-mounted display supply concentration:Hardware unit constraints in specialized optics manufacturing limit wearable device availability, capping software attach rate expansion regardless of platform demand.
- CAD integration complexity:Deep industrial AR overlay functionality requires proprietary data format compatibility that locks buyers into single-vendor ecosystems and extends sales cycles.
- Cross-border data localization:GDPR's data sovereignty provisions fragment cloud architecture investments, forcing vendors to maintain redundant European infrastructure that elevates operational overhead.
Strategic Opportunities
- Surgical training vertical expansion:FDA validation pathways for AR-guided clinical workflows, once cleared, unlock healthcare procurement budgets that dwarf industrial maintenance spending.
- Equipment-leasing channel innovation:Asset-light financing models bypass heavy upfront infrastructure spend, enabling mid-cap entrants to compete against established platform providers.
- Architectural co-design convergence:Fusing spatial computing with building information modeling software creates persistent digital twin workflows for distributed construction teams.
Industry Challenges
- Spatial computing talent scarcity:Sub-100-millisecond latency engineering requires specialized video streaming expertise that outpaces university pipeline output, inflating compensation costs.
- Legacy system integration friction:Industrial buyers demand seamless connectivity with existing enterprise resource planning and manufacturing execution systems, extending implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AR Collaboration Software Market |
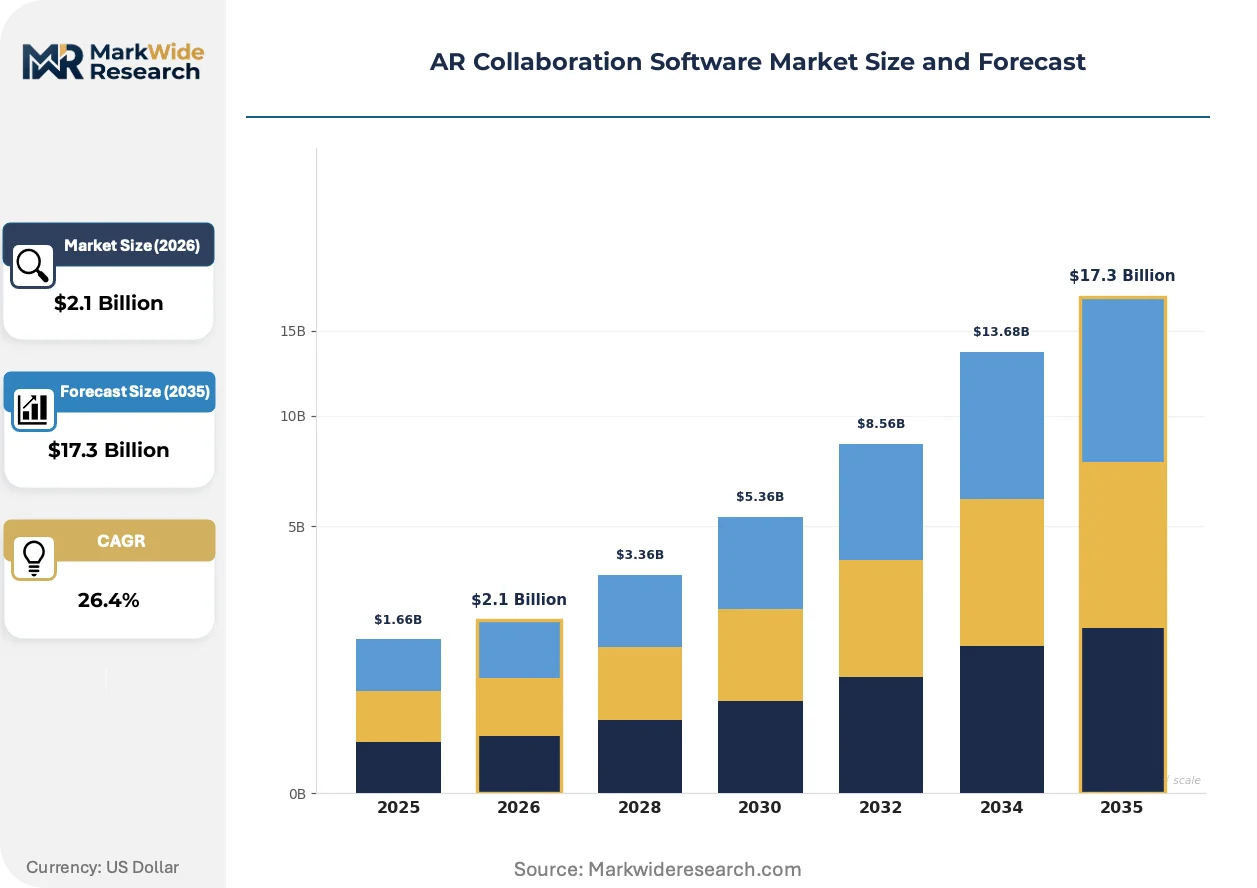
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $17.3 Billion |
| CAGR (2026 – 2036) | 26.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Remote Assistance, Training Simulation, Collaborative Design, Event Planning End User: Corporate, Education, Healthcare, Government Technology: Mobile AR, Wearable Devices, Web-based Solutions, Cloud-based Platforms Deployment: On-Premise, Public Cloud, Private Cloud, Hybrid Cloud |
| Companies Covered | Microsoft, Google, Unity Technologies, PTC, TeamViewer, Magic Leap, Adobe, Autodesk, NVIDIA Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AR Collaboration Software Market Trends and Innovations
Edge computing distribution and 5G network slicing are collapsing the infrastructure barriers that previously confined high-fidelity AR collaboration to on-premise deployments, redrawing competitive boundaries between cloud-native and legacy vendors.
Spatial computing with real-time 3D annotation is collapsing the distinction between physical and virtual troubleshooting environments. Automotive OEMs in Stuttgart and Wolfsburg deploy these tools for quality assurance workflows that previously required on-site specialist travel. The compression of expertise delivery costs is forcing consulting-heavy business models toward software-margin economics.
The EU AI Act's algorithmic transparency mandates are reshaping healthcare adoption timelines for surgical training applications. Vendors must now architect explainability features into platform foundations before clinical validation, extending development cycles but creating compliance moats against non-European competitors. German university hospitals are piloting these certified workflows ahead of broader European rollout.
Subscription-native procurement is displacing perpetual-license purchasing in mid-market manufacturing segments. Industrial buyers in Bavaria and Baden-Württemberg now prioritize operational expenditure models that align software costs with production volume fluctuations. This behavioral shift favors asset-light entrants with elastic cloud architectures over established vendors with legacy license maintenance obligations.
AR Collaboration Software Market Segmentation
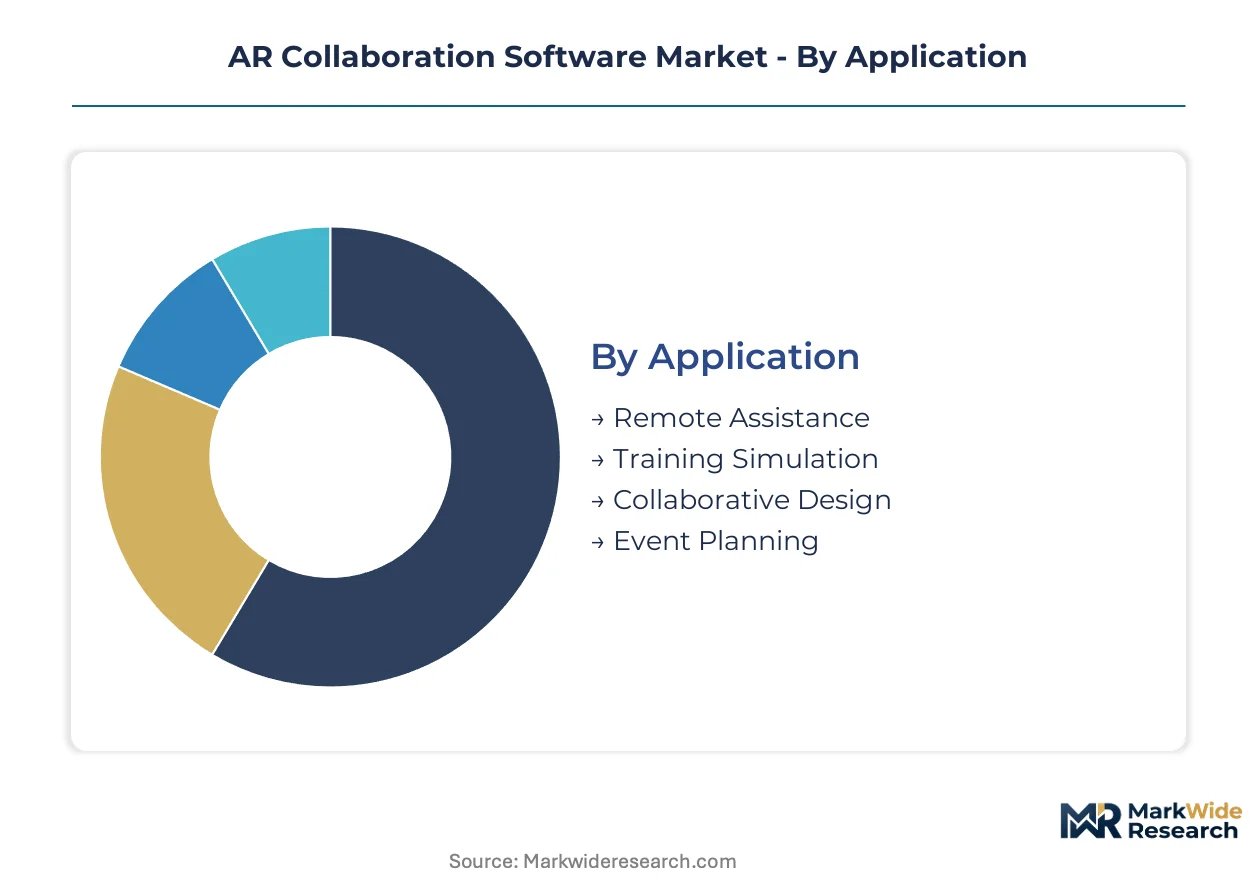
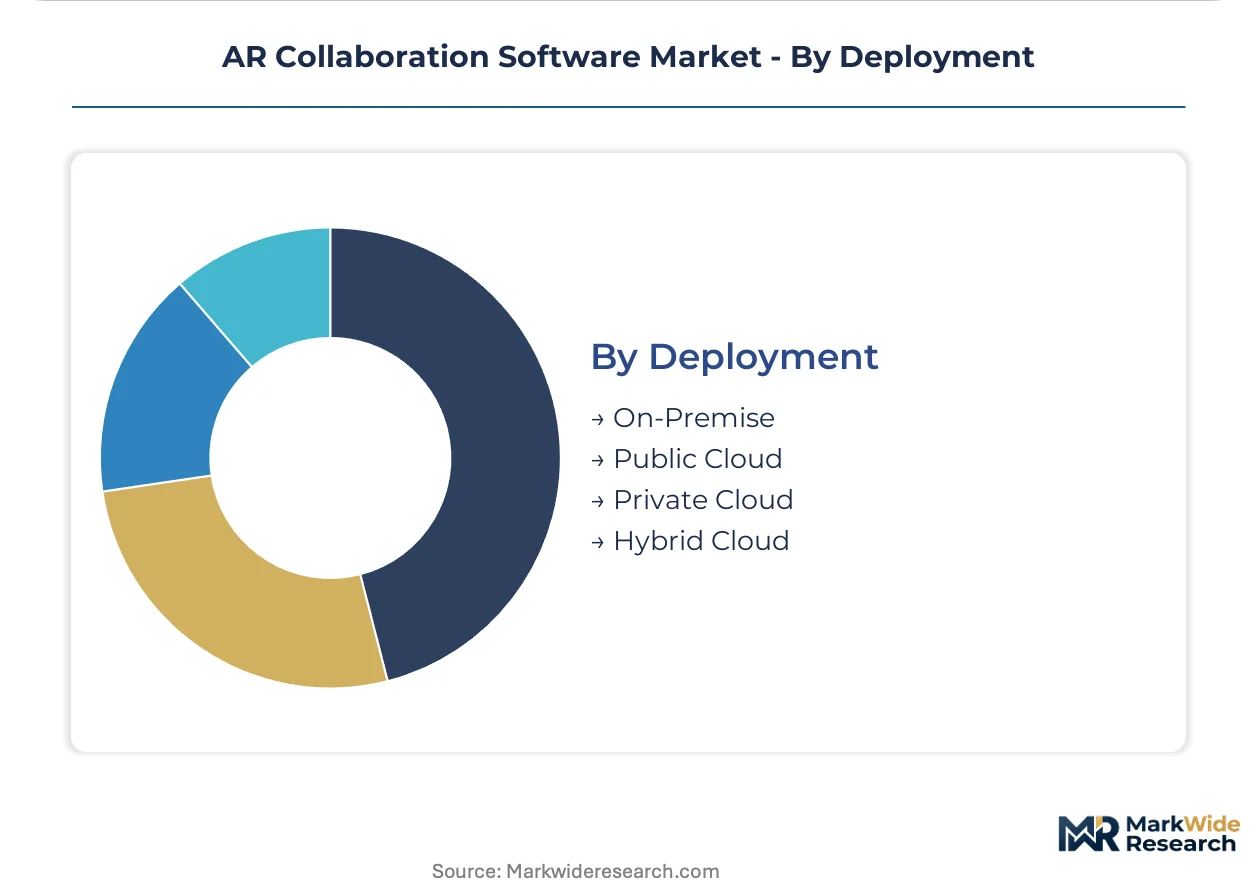
Segmentation in AR collaboration software reveals divergent procurement rhythms across use cases and infrastructure models. Industrial buyers prioritize latency-critical remote assistance over immersive training, while cloud-native architectures compress deployment cycles compared to legacy on-premise installations.
Application:
Cycle times vary sharply across use cases, with downtime-driven maintenance applications commanding immediate procurement decisions while training and design modules face extended pilot phases.
- Remote Assistance:Real-time video streaming with sub-100-millisecond latency enables assembly line troubleshooting without specialist travel. German automotive OEMs in Stuttgart and Wolfsburg deploy these tools for quality assurance workflows, prioritizing measurable downtime reduction over capital expenditure controls.
- Training Simulation:Persistent digital twin environments support surgical and industrial skill acquisition through repeatable spatial scenarios. FDA validation requirements in the United States and EU AI Act compliance mandates in Europe extend development timelines before clinical deployment authorization.
- Collaborative Design:Architectural co-design fuses building information modeling with spatial computing for distributed construction teams.
- Event Planning:Temporary spatial overlays support venue visualization and stakeholder walkthroughs before physical buildout.
Remote Assistance anchors the volume base while Training Simulation gains share at the steepest rate.
End User:
Procurement authority concentrates differently across sectors, with industrial corporations consolidating purchasing decisions while healthcare and education fragment across departmental budgets.
- Corporate:Manufacturing conglomerates deploy AR collaboration suites across quality assurance and maintenance functions with centralized IT governance. Azure backbone penetration enables elastic scaling that mid-market manufacturers previously could not access.
- Healthcare:German university hospitals pilot FDA-validated surgical training workflows ahead of broader European rollout under EU AI Act algorithmic transparency mandates.
- Education:Technical universities integrate spatial computing curricula with vendor-sponsored equipment-leasing programs.
- Government:Defense and infrastructure agencies require on-premise deployments with strict data sovereignty compliance.
Corporate deployments dominate current procurement value while Healthcare represents the fastest-growing trajectory once regulatory clearances finalize.
Technology:
Hardware-software bundling economics create divergent margin structures, with wearable devices commanding premium attach rates despite unit constraints while mobile and web solutions compete on volume accessibility.
- Cloud-based Platforms:Subscription-native architectures compress deployment timelines from months to weeks, forcing incumbent vendors to abandon perpetual-license models. GDPR-aligned data sovereignty requirements in Europe reshape vendor roadmaps toward redundant regional infrastructure.
- Wearable Devices:Head-mounted displays sustain concentrated margin pools through higher per-seat software attach rates, though specialized optics manufacturing constraints limit hardware availability regardless of platform demand.
- Mobile AR:Smartphone-based spatial computing lowers entry barriers for field service applications without dedicated hardware investment.
- Web-based Solutions:Browser-accessible collaboration tools bypass app store distribution friction for cross-enterprise deployments.
Wearable Devices capture premium pricing while Cloud-based Platforms expand most quickly through mid-market manufacturing adoption.
Deployment:
Data residency requirements and latency sensitivity drive architectural fragmentation, with regulated industries rejecting public cloud while latency-critical applications demand edge proximity.
- Public Cloud:Elastic compute scaling aligns software costs with production volume fluctuations, favoring asset-light entrants over established vendors with legacy license maintenance obligations. Bavarian and Baden-Württemberg manufacturers prioritize operational expenditure models.
- Private Cloud:Isolated infrastructure satisfies GDPR cross-border data localization mandates and healthcare patient data protection requirements.
- Hybrid Cloud:Split architectures balance sensitive data on-premise with collaborative workloads in elastic cloud environments.
- On-Premise:Air-gapped deployments persist in defense and critical infrastructure sectors with zero external connectivity tolerance.
Public Cloud anchors the volume base while Private Cloud climbs the fastest as regulatory compliance investments accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government procurement incentives and industrial modernization programs are redirecting software investment toward AR-enabled remote assistance across manufacturing clusters worldwide.
United States
FDA validation pathways for AR-guided surgical workflows are extending healthcare adoption timelines while creating compliance moats. The IRA's advanced manufacturing tax credits accelerate industrial digitization in Midwest automotive plants. Detroit and Chicago manufacturing corridors deploy remote assistance tools for assembly line troubleshooting without specialist travel.
Germany
EU AI Act algorithmic transparency mandates accelerate procurement of GDPR-aligned collaboration suites with built-in audit trails. KBA automotive safety standards integrate wearable AR into quality assurance protocols. Stuttgart and Wolfsburg automotive OEMs prioritize sub-100-millisecond latency tools for downtime reduction over capital expenditure controls.
China
MIIT industrial internet initiatives subsidize cloud-based platform adoption across state-owned manufacturing conglomerates. GB standards for smart factory interoperability reshape vendor certification requirements. Yangtze River Delta electronics manufacturers deploy spatial computing for distributed supply chain coordination.
Japan
METI Society 5.0 roadmaps prioritize human-machine collaboration technologies in precision manufacturing. JIS standards for industrial software interoperability extend sales cycles for foreign platform providers. Nagoya automotive cluster integrates AR collaboration into supplier quality management workflows.
United Kingdom
UK Research and Innovation funding streams support surgical training simulation development in NHS pilot programs. MHRA regulatory alignment with EU MDR creates dual certification pathways for clinical collaboration tools. London fintech and Cambridge biotech clusters adopt remote assistance for distributed R&D team coordination.
AR Collaboration Software Market Competitive Landscape
Channel-controlling players compete with product-specialist players for procurement authority in enterprise manufacturing accounts. The vendor base organizes around three strategic archetypes: cloud infrastructure incumbents leveraging existing enterprise relationships, industrial software specialists with deep CAD integration capabilities, and emerging spatial computing native platforms. Dominant competitive moves include subscription-native delivery restructuring and regional data sovereignty infrastructure deployment.
Within the cloud infrastructure tier, Microsoft leverages Azure backbone penetration to anchor enterprise deployments across manufacturing verticals. PTC occupies a position exemplifying industrial software specialists through deep CAD integration capabilities that sustain premium positioning. TeamViewer represents the remote connectivity heritage segment transitioning toward spatial computing feature sets.
| Leading Market Players |
|---|
| Microsoft |
| Unity Technologies |
| PTC |
| TeamViewer |
| Magic Leap |
| Adobe |
| Autodesk |
| NVIDIA Corporation |
| Others |
Pricing and Supply Chain Analysis
Specialized optics manufacturing concentration in Taiwan and South Korea funnels margin capture toward head-mounted display vendors, compressing software attach rate economics for platform providers downstream. Cloud-native entrants exploit this hardware bottleneck by decoupling subscription pricing from device procurement cycles.
Pricing Analysis
Certification level creates the primary spread between FDA-validated surgical suites and industrial maintenance tools without clinical validation. Three-tier pricing structure across premium, standard, and economy levels aligns with GDPR audit trail depth and latency performance guarantees. Cost compression in mid-market manufacturing subscriptions intensifies because Azure-anchored competitors trade margin for enterprise footprint expansion. Automotive OEMs in Stuttgart demonstrate least price sensitivity due to downtime reduction ROI visibility, while Bavarian mid-cap manufacturers negotiate volume-scaled operational expenditure models.
Supply Chain Analysis
Tariff exposure between China and the United States dominates component sourcing decisions for wearable device optics and edge computing chipsets. Taiwan, South Korea, and Germany anchor specialized display manufacturing and precision sensor fabrication. Raw material dependencies span rare-earth magnet substrates, high-refractive-index glass, and gallium nitride semiconductors. Single-source vulnerability concentrates in diffractive waveguide suppliers serving Magic Leap and HoloLens ecosystems. Distribution runs through direct enterprise sales teams for Fortune 500 accounts and channel partners for mid-market manufacturing penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated automotive OEM procurement offices that negotiate enterprise-wide AR collaboration licenses across multiple plant locations, fragmenting vendor pricing autonomy.
For Market Incumbents: Pre-empt subscription-native entrants by restructuring perpetual-license maintenance revenue into consumption-aligned pricing tiers before mid-market manufacturing accounts complete vendor switching cycles. Acquire specialized CAD integration boutiques in Stuttgart and Wolfsburg to defend against PTC's ecosystem lock-in. Prioritize redundant European cloud infrastructure investment to neutralize GDPR compliance as a competitive wedge.
For New Entrants and Emerging Players: Establish a beachhead in surgical training simulation where FDA validation pathways create incumbent-free procurement windows for compliant first-movers. Target German university hospital pilot programs ahead of broader EU AI Act enforcement rollout. Pursue equipment-leasing channel partnerships with technical universities to bypass capital expenditure approval bottlenecks.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed remote connectivity platforms transitioning toward spatial computing feature development. Five-to-ten year viability hinges on cloud infrastructure anchoring rather than hardware attachment economics. Monitor FDA 510(k) clearance velocity for AR-guided surgical workflows as the inflection signal distinguishing platform sustainability from feature-vendor obsolescence.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Azure backbone anchoring enables elastic scaling for mid-market manufacturing accounts previously locked out of enterprise-grade deployments. |
| Acquisition of Specialist Firm | CAD integration boutiques in German automotive clusters defend against ecosystem lock-in by industrial software incumbents. |
| Geographic Expansion | Redundant European cloud infrastructure neutralizes GDPR compliance as a competitive differentiator for non-European vendors. |
| Product Launch | FDA-validated surgical training modules unlock healthcare procurement budgets dwarfing industrial maintenance spending. |
| Strategic Partnership | Equipment-leasing alliances with technical universities bypass capital expenditure approval cycles for asset-light entrants. |
Research Methodology
Cross-validation between primary interviews with industrial IT directors and secondary analysis of hyperscaler capex disclosures anchors the qualitative findings. Conversations with platform engineers, hospital biomedical engineers, automotive procurement leads, and channel integration specialists informed deployment friction assessments. SEC filings, Azure infrastructure expansion announcements, FDA 510(k) databases, and EU AI Act implementation guidance provided external validation. Bottom-up triangulation across application segments converged with top-down cloud spending forecasts.
Calibration against historical adoption curves in adjacent enterprise software categories informed penetration assumptions across the projection horizon. Segmentation dimensions modeled include deployment architecture, organization size tier, vertical industry, integration complexity level, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted pricing trajectories and hardware attach rate evolution. Edge computing distribution patterns and 5G network slicing rollout schedules served as industry-specific forecast inputs.
Stress conditions across hardware supply constraints, GDPR enforcement intensity, and FDA validation timeline variability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about cloud infrastructure maturation and regulatory compliance investment requirements. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
AR in Education Market
Virtual Reality (VR) and Augmented Reality (AR)
AR and VR in Training Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality for Consumer Market
Virtual Reality (VR) and Augmented Reality (AR)
Europe Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Commercial Augmented Reality Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality Content Creation Market
Virtual Reality (VR) and Augmented Reality (AR)
AR and VR Solutions Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Collaboration Platform Market
Virtual Reality (VR) and Augmented Reality (AR)
Social VR Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Augmented and Mixed Reality (VR/AR) Market
Virtual Reality (VR) and Augmented Reality (AR)
Data Glove Market
Virtual Reality (VR) and Augmented Reality (AR)
Global AR and VR Smart Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
US Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
India Virtual Production Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Mirror Market
Virtual Reality (VR) and Augmented Reality (AR)
South Korea Metaverse Market