
 Data Glove Market | 2026-2036
Data Glove Market Size, Share, and Industry Trends Forecast 2026-2036
Data Glove Market Insights
The capability gap between sensor-integrated specialists and peripheral assemblers is unwinding as R&D intensity separates viable competitors from commodity players. Manus VR leverages proprietary inertial tracking stacks to sustain premium positioning in enterprise VR deployments. HaptX anchors its defensibility through pneumatic haptic arrays that dominate force-feedback fidelity benchmarks. Microsoft competes via platform integration, extending Azure cloud pipelines into gesture-capture workflows for industrial clients.
A data glove is a wearable human-computer interface instrumented with flex sensors, inertial measurement units, or optical markers to capture hand kinematics and render tactile feedback, typically operating at sub-millimeter positional accuracy for real-time digital twin synchronization. Haptic Gloves command the dominant revenue share due to force-feedback complexity and medical-grade certification requirements, while Gesture Recognition Gloves represent the fastest-expanding category as contactless industrial controls displace legacy interfaces. Sensor-based technology leads unit volumes through cost-efficient MEMS integration, though Magnetic Tracking captures margin pools in surgical simulation where electromagnetic immunity proves critical.
FDA 510(k) pathways govern clinical deployment in the United States, while CE marking under the EU MDR framework constrains European market access for biometric patient-contact devices. Japan's METI subsidizes haptic R&D consortia, directly shaping domestic procurement preferences for domestic-manufactured gloves. Stakeholders must monitor evolving electromagnetic compatibility standards and reimbursement code expansions for telerehabilitation to calibrate geographic prioritization and product certification roadmaps.
Market Dynamics
Haptic fidelity requirements in surgical simulation are compressing development cycles for force-feedback architectures while biometric certification under EU MDR and FDA 510(k) pathways simultaneously extends commercialization timelines.
Growth Catalysts
- EU AI Act compliance mandates:Biometric wearables deployed in clinical settings across Germany and France must demonstrate algorithmic transparency, creating procurement preference for pre-certified haptic systems in medical training centers.
- Automotive design studio demand:Virtual clay modeling workflows in Japan and the United States are integrating gesture-capture gloves to compress styling iteration cycles and reduce physical prototype expenditure.
- MEMS cost curves:Inertial measurement unit integration at consumer-electronics scale is lowering entry thresholds for industrial-grade hand tracking in logistics and warehouse automation.
Market Restraints
- Neodymium magnet supply concentration:Electromagnetic tracking subsystems depend on rare-earth processing dominated by Chinese state-controlled refiners, exposing margin volatility to export quota fluctuations.
- Pneumatic actuator maintenance burden:Force-feedback gloves requiring compressed-air infrastructure face deployment friction in mobile telerehabilitation settings where clinic-grade pneumatic supply is unavailable.
- FDA 510(k) predicate device scarcity:Novel haptic architectures lacking established equivalence pathways face extended review timelines, delaying revenue recognition for breakthrough sensor configurations.
Strategic Opportunities
- METI-subsidized domestic manufacturing:Japanese haptic R&D consortia receive direct fiscal support, creating localized procurement preferences for gloves assembled within national supply chains.
- Contactless industrial controls:Gesture recognition gloves are penetrating hazardous-environment operations in chemical processing and nuclear maintenance where physical interface contamination poses operational risk.
- ISO 13485 certification arbitrage:Medical device quality management pre-certification enables faster CE marking under EU MDR, opening European hospital network procurement channels for compliant manufacturers.
Industry Challenges
- Electromagnetic compatibility engineering talent scarcity:Surgical simulation environments demand specialists capable of isolating haptic feedback systems from MRI and electrosurgical interference, constraining product development velocity.
- Legacy EMR integration complexity:Biometric data capture from rehabilitation gloves must interface with heterogeneous hospital information systems, requiring bespoke API development for each major platform.
- Patent thickets around flex sensor architectures:Established intellectual property portfolios covering resistive bend-sensing technologies complicate clean-room design efforts for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Glove Market |
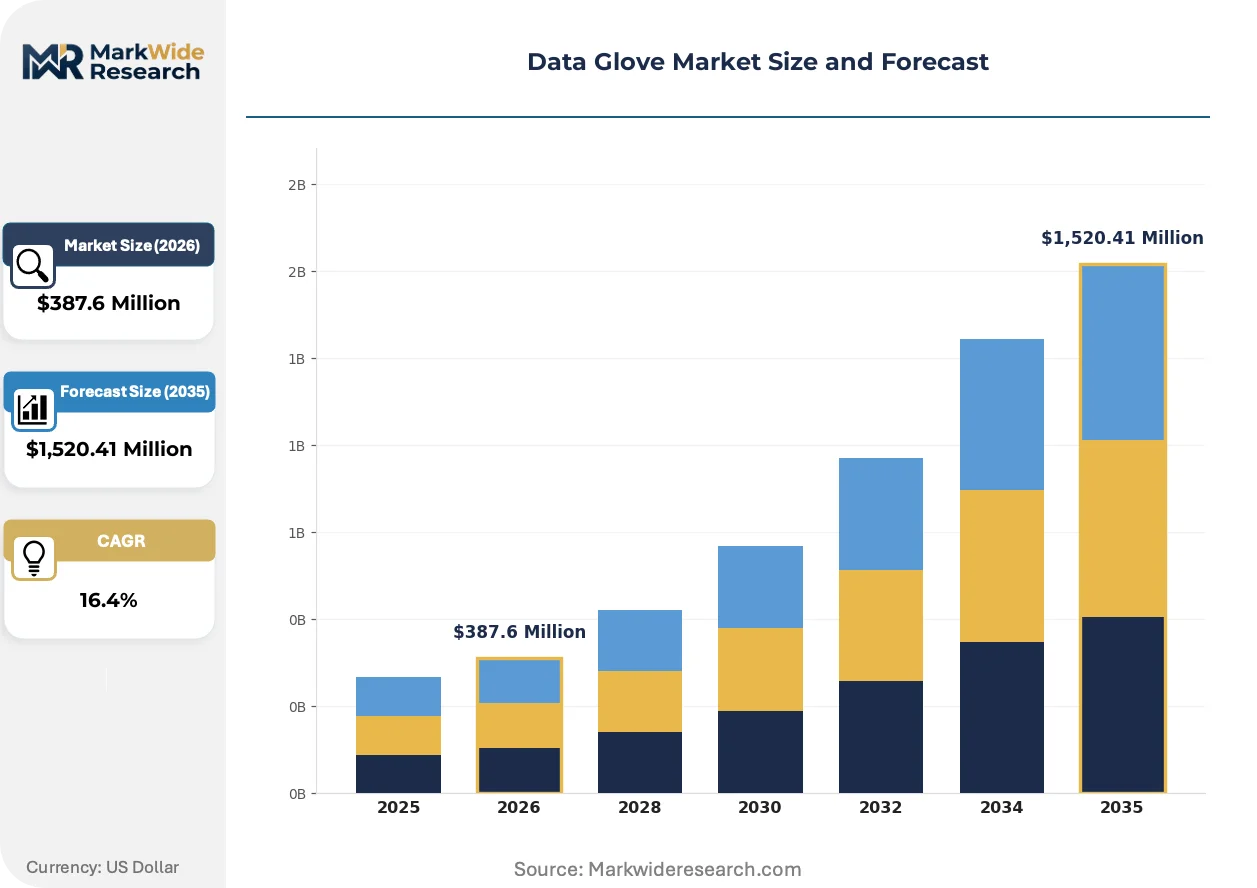
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,520.41 Million |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Haptic Gloves, VR Gloves, AR Gloves, Gesture Recognition Gloves Technology: Sensor-based, Optical Tracking, Inertial Tracking, Magnetic Tracking End User: Gaming Industry, Healthcare Sector, Education & Training, Research Institutes Application: Virtual Reality, Augmented Reality, Simulation Training, Rehabilitation |
| Companies Covered | Manus VR, CyberGlove Systems, HaptX, Microsoft, SenseGlove, Noitom, HTC Vive, Teslasuit, Immersion Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Glove Market Trends and Innovations
Convergence between cloud-based gesture analytics and edge-compute haptic rendering is redefining latency benchmarks while regulatory fragmentation across biometric jurisdictions forces modular certification architectures.
Soft pneumatic actuators woven into textile substrates are supplanting rigid exoskeleton frames in medical-grade force-feedback gloves. Rehabilitation centers in Germany and the United States are piloting these compliant mechanisms for stroke patient hand therapy. The structural consequence is compression of unit economics for clinical deployments previously requiring machined aluminum kinematic structures.
EU MDR Annex XVI expansion is capturing previously unregulated wellness devices with biometric patient contact into medical device classification. Industrial design studios in France and Italy now face unexpected conformity assessment obligations for gesture gloves used in ergonomic studies. Haptic hardware vendors are responding by bifurcating product lines into certified clinical tiers and unregulated enterprise tiers with identical sensor cores but divergent documentation packages.
Hospital procurement departments are consolidating vendor relationships through multi-year managed service agreements rather than capital equipment purchases. Telerehabilitation platforms in Japan and the United States are unbundling glove hardware from software subscriptions, shifting revenue recognition toward recurring clinical outcome fees. This reconfiguration is most visible in German statutory health insurance reimbursement pilots where per-session haptic therapy codes are displacing upfront device acquisition budgets.
Data Glove Market Segmentation
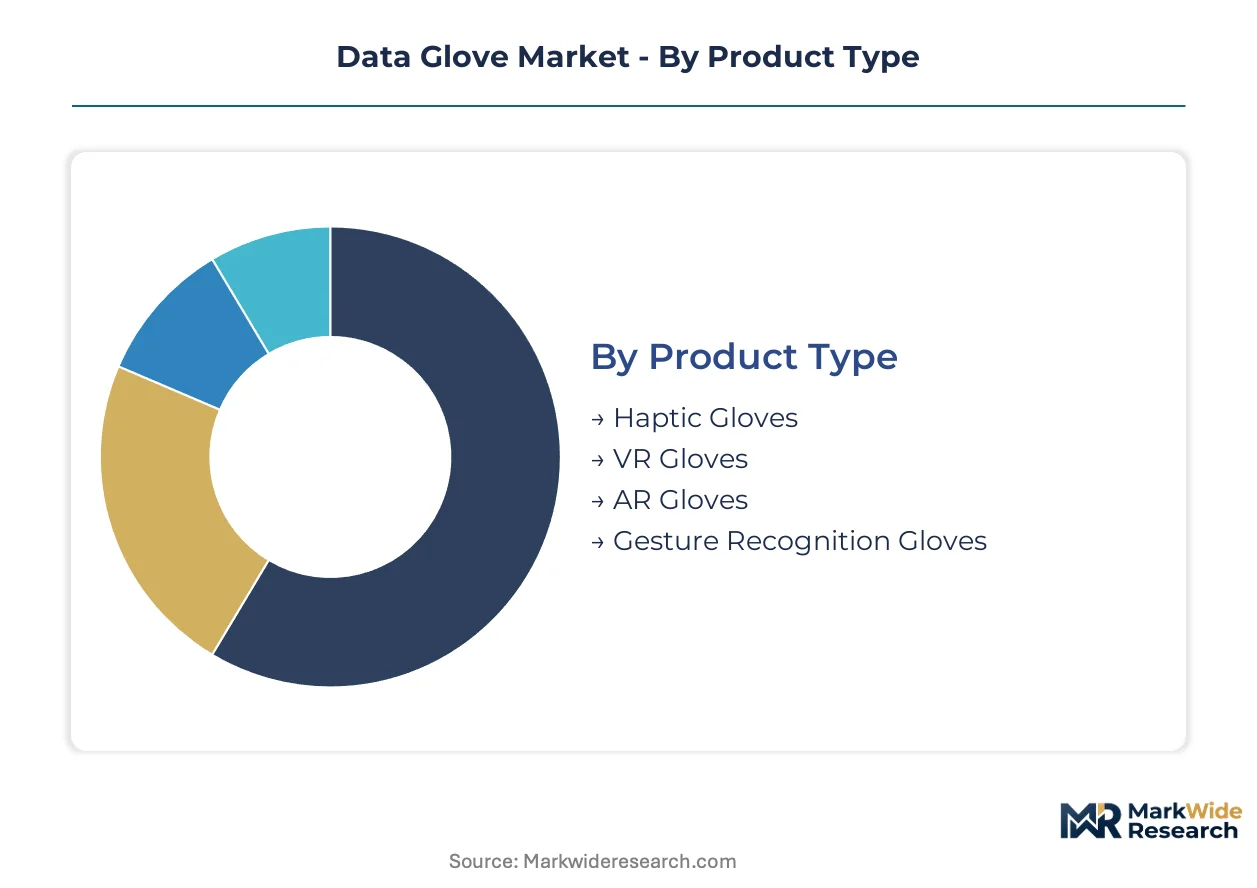
Product architecture in data gloves determines regulatory pathway complexity and reimbursement eligibility. Certification requirements diverge sharply across clinical versus enterprise deployments, forcing vendors to maintain parallel SKUs with identical sensor cores but divergent documentation.
Product Type:
FDA 510(k) and EU MDR frameworks create tiered commercial barriers where force-feedback complexity directly correlates with premarket submission burden.
- Haptic Gloves:Pneumatic or electromechanical actuators deliver calibrated force feedback for surgical simulation and industrial design review. German medical training centers and Japanese automotive studios anchor procurement volumes due to reimbursement code availability and METI-subsidized domestic manufacturing preferences.
- Gesture Recognition Gloves:Contactless hand tracking via inertial or optical sensors enables hazardous-environment operation without physical interface contamination. Chemical processing facilities in the United States and nuclear maintenance operations in France are displacing legacy control panels with these systems.
- VR Gloves:Integrated haptic rendering for immersive enterprise training scenarios.
- AR Gloves:Overlay gesture control for field service and assembly guidance applications.
Established volume favors Haptic Gloves; emerging adoption favors Gesture Recognition Gloves.
Technology:
Cost curves and electromagnetic immunity requirements partition the addressable market by end-use criticality.
- Sensor-based:MEMS flex sensors and inertial measurement units capture finger kinematics at consumer-electronics scale economics. Warehouse automation and logistics operations in the United States leverage this cost efficiency for high-volume hand tracking deployments.
- Magnetic Tracking:Electromagnetic field generators and coil arrays achieve sub-millimeter positional accuracy immune to optical occlusion. Surgical simulation suites in Germany and Japan specify this architecture for MRI-compatible training environments where metallic interference must be eliminated.
- Optical Tracking:Camera-based markerless hand reconstruction for VR entertainment and retail installations.
- Inertial Tracking:IMU fusion algorithms for mobile applications lacking fixed infrastructure.
Unit economics concentrate in Sensor-based architectures; margin pools concentrate in Magnetic Tracking.
End User:
Procurement authority and reimbursement structure determine contract value and sales cycle duration.
- Healthcare Sector:Hospital networks and rehabilitation clinics require ISO 13485 quality management and FDA 510(k) or CE MDR certification for patient-contact devices. Telerehabilitation platforms in the United States and Japan are unbundling hardware from software subscriptions, shifting revenue toward per-session clinical outcome fees.
- Gaming Industry:Consumer entertainment and location-based VR venues prioritize latency reduction and wireless tether elimination over medical-grade documentation. Esports training facilities in Germany and the United States drive refresh cycles for haptic fidelity improvements.
- Education & Training:University engineering programs and corporate learning departments with capital equipment budgets.
- Research Institutes:Academic laboratories and government R&D consortia with grant-funded procurement flexibility.
Contract value peaks in Healthcare Sector; volume velocity peaks in Gaming Industry.
Application:
Latency tolerance and force-feedback fidelity requirements stratify hardware specifications and pricing tiers.
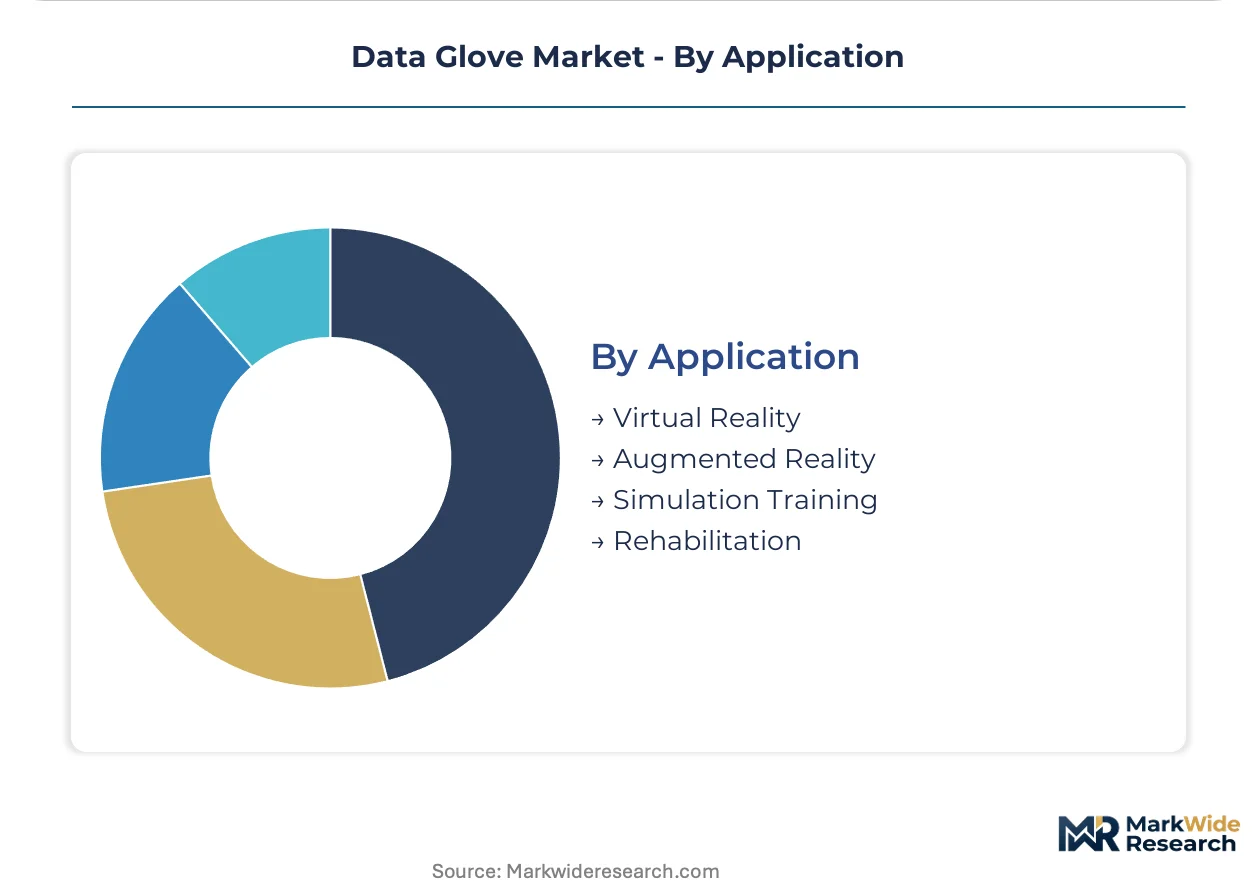
- Simulation Training:High-fidelity haptic rendering for surgical skill acquisition and hazardous procedure rehearsal. Medical simulation centers in Germany, the United States, and Japan consolidate vendor relationships through multi-year managed service agreements rather than capital purchases.
- Rehabilitation:Biometric hand therapy for stroke and trauma patients with telerehabilitation platform integration. Soft pneumatic actuators woven into textile substrates are supplanting rigid exoskeleton frames, compressing unit economics for clinical deployments.
- Virtual Reality:Immersive enterprise training and entertainment applications with moderate force-feedback requirements.
- Augmented Reality:Field overlay guidance with gesture control for manufacturing and maintenance workflows.
Recurring revenue potential concentrates in Rehabilitation; upfront contract value concentrates in Simulation Training.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in German medical simulation centers while cost-optimized procurement dominates Japanese automotive studios, creating a trans-Atlantic pricing asymmetry that vendors navigate through tiered product architectures.
United States
Hospital networks in Boston and Houston drive demand for FDA 510(k)-cleared haptic systems in surgical training programs. Medicare reimbursement pilots for telerehabilitation are expanding per-session billing codes. Medical simulation clusters in California and Texas anchor procurement volumes for force-feedback gloves.
Germany
Automotive design studios in Munich and Stuttgart integrate gesture-capture gloves into virtual clay modeling workflows. EU AI Act compliance mandates for biometric algorithmic transparency reshape procurement specifications. Medical training centers in Berlin and Hamburg consolidate vendor relationships through multi-year managed service agreements.
Japan
METI-subsidized haptic R&D consortia in Tokyo and Osaka create domestic manufacturing preferences for locally assembled gloves. PMDA consultation pathways accelerate novel sensor configurations for rehabilitation applications. Automotive OEMs in Nagoya anchor demand for high-fidelity force-feedback systems in styling iteration cycles.
France
ANSM oversight of biometric patient-contact devices captures industrial design studios under unexpected EU MDR Annex XVI conformity obligations. Nuclear maintenance operations in Provence-Alpes-Côte d'Azur deploy gesture recognition gloves for hazardous-environment controls. Hospital networks in Paris pilot soft pneumatic actuator rehabilitation programs for stroke patients.
United Kingdom
MRI-compatible surgical simulation suites in London and Manchester specify electromagnetic tracking architectures immune to optical occlusion. NHS procurement frameworks favor ISO 13485-certified vendors for patient-contact rehabilitation devices. Research consortia in Cambridge and Oxford drive pilot deployments of textile-integrated haptic systems.
Data Glove Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with pneumatic haptic specialists commanding premium positioning against MEMS-integrated volume manufacturers. The vendor base separates into three strategic tiers: proprietary tracking stack developers, platform-integrated cloud service extenders, and component-scale sensor integrators. Dominant competitive moves include ISO 13485 pre-certification for accelerated European market access and METI-aligned domestic manufacturing partnerships for Japanese procurement preference.
Within the proprietary technology tier, Manus VR and HaptX exemplify divergent defensibility strategies—one through inertial tracking integration, the other through pneumatic force-feedback fidelity. Microsoft occupies a platform-anchored position extending cloud pipelines into industrial gesture-capture workflows. These three players represent the structural segmentation between sensor-integrated specialists, haptic fidelity leaders, and ecosystem-integrated technology providers.
| Leading Market Players |
|---|
| Manus VR |
| CyberGlove Systems |
| HaptX |
| Microsoft |
| SenseGlove |
| Noitom |
| HTC Vive |
| Teslasuit |
| Immersion Corporation |
| Others |
Pricing and Supply Chain Analysis
Soft pneumatic actuator substitution for rigid electromechanical haptic architectures is redrawing component sourcing maps from machined aluminum suppliers in Germany toward textile-integrated manufacturing clusters in East Asia, simultaneously collapsing unit production costs and compressing premium pricing bandwidth for clinical-grade force-feedback gloves.
Pricing Analysis
The customization-premium spread spans three-tier pricing structure across premium, standard, and economy levels, with FDA 510(k)-cleared haptic systems commanding substantial documentation premiums over enterprise-tier gesture gloves sharing identical MEMS sensor cores. Price differentiation hinges on ISO 13485 certification grade and after-sales service bundling, particularly for hospital network managed service agreements. Cost compression in standard-tier sensor-based gloves is intensifying because MEMS integration at consumer-electronics scale erodes hardware margins. Gaming industry buyers exhibit highest price sensitivity, while German medical simulation centers demonstrate lowest sensitivity due to reimbursement code availability.
Supply Chain Analysis
Inbound logistics costs from Shanghai and Shenzhen ports to European distribution hubs have elevated working capital requirements for neodymium magnet-dependent electromagnetic tracking subsystems. Component sourcing concentrates in China for rare-earth processing, Japan for precision MEMS fabrication, and Germany for medical-grade pneumatic actuators. Raw material dependencies include neodymium magnets, soft textile substrates, and inertial measurement units. Single-source vulnerability around Chinese state-controlled rare-earth refiners exposes margin volatility to export quota fluctuations. Distribution runs through authorized medical device distributors for healthcare sector deployments and direct OEM relationships for automotive design studio procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Data glove penetration remains in early-cycle expansion, with telerehabilitation platform integration serving as the primary demand accelerant as per-session billing codes displace capital equipment budgets across Japanese and US hospital networks.
For Market Incumbents: Shield proprietary pneumatic haptic architectures from MEMS-based commoditization by deepening ISO 13485 certification moats and securing multi-year managed service agreements with German medical training centers. Vertical integration into soft actuator textile manufacturing reduces dependency on East Asian substrate suppliers while capturing margin pools from rehabilitation applications.
For New Entrants and Emerging Players: Cloud-based gesture analytics service layers represent underexploited territory where incumbents under-serve mid-market logistics operators lacking in-house integration capabilities. Gesture recognition gloves for hazardous-environment industrial controls in French nuclear maintenance and US chemical processing offer the most penetrable entry point. A software-first go-to-market angle unbundling hardware from subscription analytics bypasses capital-intensive certification barriers.
For Investors and Strategic Acquirers: The market sits at a platform-consolidation phase that favors specialized haptic fidelity developers with defensible pneumatic IP over commodity sensor integrators. Acquisition targets should demonstrate PMDA consultation pathway progress or METI-aligned domestic manufacturing partnerships. The signal to watch is reimbursement code expansion for telerehabilitation in US Medicare pilots and German statutory health insurance frameworks.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Pre-certification Investment | Accelerates CE marking under EU MDR for German hospital network access. |
| METI-Aligned Domestic Manufacturing Partnership | Captures Japanese procurement preference through subsidized local assembly. |
| Software-Companion Development for Telerehabilitation | Enables per-session revenue models displacing capital equipment sales. |
| Magnetic Tracking Architecture R&D | Secures MRI-compatible positioning for surgical simulation premium tier. |
| Gesture Analytics Platform Integration | Extends Azure cloud pipelines into industrial client workflow automation. |
Research Methodology
Cross-validation between primary interviews with haptic hardware engineering directors and secondary validation through FDA 510(k) filing databases anchors the qualitative findings. Stakeholder engagement encompassed biomedical engineers at German medical simulation centers, GPO contracts managers at US hospital networks, procurement leads at Japanese automotive OEMs, and regulatory affairs specialists navigating EU MDR Annex XVI. Secondary sources included PMDA consultation pathway records, METI R&D consortium disclosures, CMS Medicare reimbursement code filings, and customs data on neodymium magnet trade flows. Bottom-up unit economics modeling triangulated against top-down addressable market sizing.
Sensitivity analysis across pneumatic actuator cost curves, MEMS integration trajectories, and reimbursement code adoption timelines shaped the analytical framework. Segmentation dimensions modeled encompass product architecture, tracking technology, end-user sector, and application criticality across the projection horizon. CAGRs derived from weighted scenario analysis incorporating regulatory approval velocity and platform unbundling trends. Industry-specific forecast inputs included electromagnetic compatibility certification timelines and soft actuator textile manufacturing yield rates.
Forecasts assume regulatory continuity in FDA 510(k) predicate device pathways and EU MDR Annex XVI classification scope; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
AR/VR Chip Market
Virtual Reality (VR) and Augmented Reality (AR)
Global AR and VR Smart Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality (VR) Simulator Market
Virtual Reality (VR) and Augmented Reality (AR)
Asia-Pacific Augmented and Virtual Reality in Manufacturing Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Prototype Market
Virtual Reality (VR) and Augmented Reality (AR)
Location-Based VR Entertainment Market
Virtual Reality (VR) and Augmented Reality (AR)
AR and VR Solutions Market
Virtual Reality (VR) and Augmented Reality (AR)
Europe Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Reality Connected Service Market
Virtual Reality (VR) and Augmented Reality (AR)
Telepresence Equipment Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Learning Market
Virtual Reality (VR) and Augmented Reality (AR)
US Virtual Tour Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Tour Market
Virtual Reality (VR) and Augmented Reality (AR)
AR Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
Middle East and Africa Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Head Show Market