
 US Metaverse Market | 2026-2036
US Metaverse Market Size, Share, and Industry Trends Forecast 2026-2036
US Metaverse Market Insights
The US metaverse is restructuring around a sharp split between enterprise-grade platforms with dedicated hardware stacks and lightweight consumer experiences running on existing devices. Epic Games leverages its Unreal Engine dominance to anchor high-fidelity industrial simulation contracts, while Roblox sustains a youth-centric creator economy with lower barrier-to-entry tooling. Meta competes aggressively on vertical integration, controlling headset manufacturing, operating systems, and content distribution through its Quest ecosystem.
The metaverse constitutes persistent, shared virtual environments rendered through real-time 3D engines, requiring sub-20ms motion-to-photon latency for user retention and spatial audio processing above 48kHz sample rates for immersion. Gaming applications currently dominate transaction volume, though enterprise training modules built on Mixed Reality and AI-driven 3D Modeling represent the fastest-expanding margin pool as manufacturers replace physical prototyping. Non-fungible Tokens remain structurally volatile, with liquidity concentrated in speculative collectibles rather than functional utility layers.
FCC spectrum rules for 6GHz and 60GHz bands shape wireless headset performance thresholds, while SEC disclosure requirements for tokenized virtual assets determine platform compliance costs. California's emerging digital asset framework and New York's financial services oversight create a patchwork that fragments national deployment timelines. Stakeholders must monitor whether NHTSA extends distracted-driving classifications to augmented windshields, as this would reshape automotive AR investment priorities overnight.
Market Dynamics
The US metaverse market splits sharply between enterprise-grade platforms requiring dedicated hardware stacks and lightweight consumer experiences running on existing devices. FCC spectrum allocations for unlicensed millimeter-wave bands determine wireless headset deployment feasibility across both segments.
Growth Catalysts
- Defense Training Mandates:Pentagon procurement directives now specify immersive simulation for workforce preparation. Contractors accelerate mixed-reality deployment for maintenance and combat readiness modules.
- California Venture Density:San Francisco Bay Area clusters concentrate developer talent and seed-stage funding. This geography sustains platform innovation cycles unavailable elsewhere domestically.
- Unlicensed Spectrum Access:FCC rules for 6GHz and 60GHz bands reduce hardware manufacturers' radio certification burdens. Lower compliance friction accelerates wireless headset iteration timelines.
Market Restraints
- Display Panel Concentration:Micro-OLED supply concentrates among Asian component specialists. US headset assemblers face input bottlenecks and price volatility for sub-20ms motion-to-photon latency screens.
- SEC Token Disclosure Burden:Virtual asset disclosure requirements inflate platform compliance costs. Tokenized metaverse real estate offerings face registration friction that chills speculative liquidity.
- Substitute Platform Threat:Cloud-rendered gaming services on conventional screens satisfy casual immersion demand without hardware purchases. This limits addressable market expansion for dedicated headset ecosystems.
Strategic Opportunities
- Texas Enterprise Corridor:Underpenetrated industrial zones in Houston and Dallas-Fort Worth lack immersive training vendor presence. Energy and aerospace maintenance sectors present white-space deployment potential.
- AI-Generated Asset Pipelines:Convergence of generative models with real-time 3D engines collapses content production costs. Procedural environment generation enables mid-market enterprise adoption previously blocked by artwork budgets.
- Automotive AR Windshields:NHTSA regulatory clarity on augmented-display classification would unlock OEM integration contracts. Tier-1 suppliers await distraction-testing standards to commit production capacity.
Industry Challenges
- Spatial Audio Engineering Scarcity:48kHz+ sample-rate processing expertise concentrates among gaming audio veterans. Enterprise platform builders compete for limited talent pools capable of physiological immersion design.
- Legacy ERP Integration Friction:Industrial metaverse deployments require real-time data bridges to existing manufacturing execution systems. Custom middleware development extends implementation timelines and inflates professional services costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Metaverse Market |
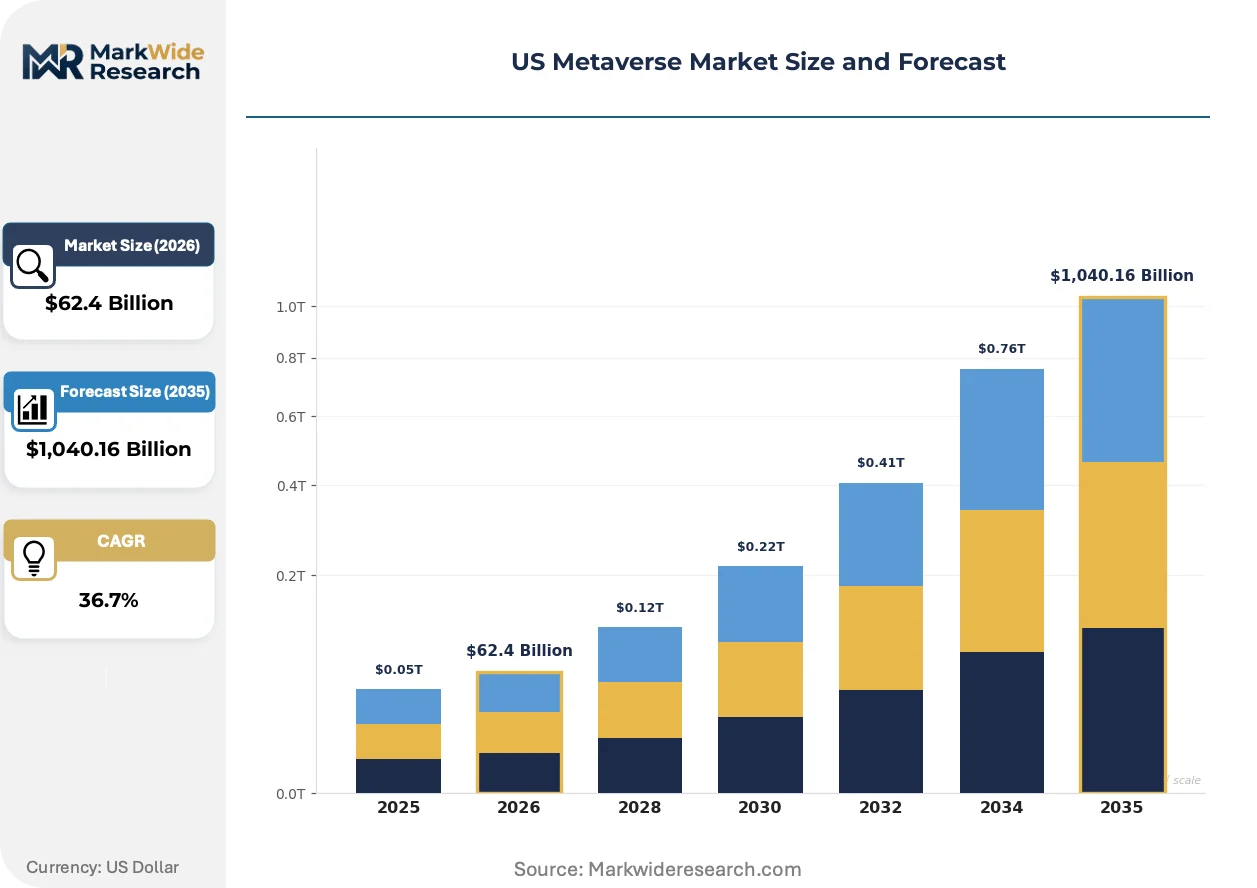
| Market Size in 2026 | $62.4 Billion |
| Market Size in 2035 | $1,040.16 Billion |
| CAGR (2026 – 2036) | 36.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Virtual Reality, Augmented Reality, Mixed Reality, Non-fungible Tokens Application: Gaming, Social Interaction, Virtual Commerce, Education Technology: Blockchain, 3D Modeling, AI, Cloud Computing End User: Enterprises, Retailers, Content Creators, Consumers |
| Companies Covered | Epic Games, Roblox, Meta, Decentraland, Unity, Microsoft, NVIDIA, IMVU, Google, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Metaverse Market Trends and Innovations
Real-time 3D engine technology is consolidating around two divergent optimization paths: photorealistic industrial simulation versus lightweight mobile rendering. This technical bifurcation reshapes vendor specialization and buyer procurement criteria across the US market.
Neural radiance fields and Gaussian splatting are consolidating volumetric capture workflows for enterprise digital-twin construction. Automotive and aerospace manufacturers adopt these techniques to compress physical prototyping cycles. The technology is consolidating previously fragmented photogrammetry and LiDAR processing pipelines into unified asset pipelines, reducing specialist headcount requirements.
FCC proceedings on expanded 6GHz unlicensed access are reshaping wireless headset performance thresholds. Favorable rulings would enable multi-gigabit local streaming without licensed spectrum costs. Hardware manufacturers in California and Washington state are front-loading R&D to capitalize on anticipated rulemakings, while lobbying coalitions form around interference protection claims from incumbent users.
Enterprise procurement of immersive training modules is fragmenting from centralized IT mandates toward departmental self-service acquisition. Manufacturing operations teams now pilot mixed-reality solutions without corporate technology committee approval. This pattern concentrates in Midwest industrial corridors where plant managers control discretionary capital budgets and face immediate workforce turnover pressures.
US Metaverse Market Segmentation
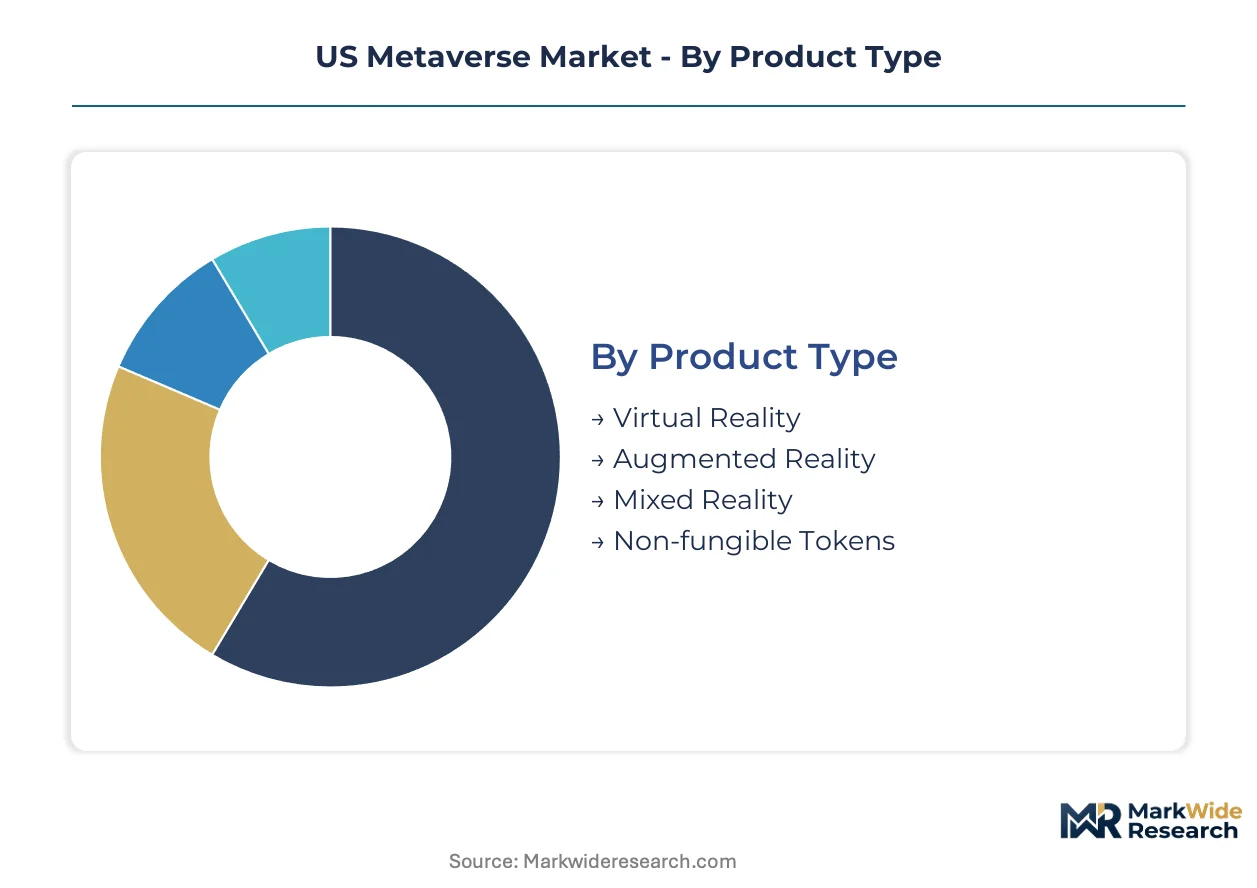
Segmentation reveals how capital deployment and technical requirements fragment across the US metaverse landscape. Hardware-intensive layers demand specialized component supply chains, while software and service segments scale through cloud infrastructure.
Product Type:
Capital intensity varies dramatically across hardware and non-hardware segments, with dedicated headsets requiring the heaviest upfront manufacturing investment.
- Virtual Reality:Fully immersive headsets with sub-20ms motion-to-photon latency specifications dominate defense training procurement in California and Texas. Pentagon procurement mandates for workforce simulation sustain demand concentration among contractors with cleared facility access.
- Augmented Reality:Overlay devices integrating spatial mapping with 48kHz+ audio processing anchor enterprise maintenance workflows. NHTSA pending rulings on automotive windshield classification determine whether OEM integration contracts materialize for Tier-1 suppliers.
- Mixed Reality:Combines passthrough cameras with holographic rendering for industrial digital-twin applications.
- Non-fungible Tokens:SEC disclosure requirements inflate compliance costs for tokenized virtual real estate offerings.
Virtual Reality absorbs the bulk of installed capacity; Mixed Reality is expanding most quickly.
Application:
Revenue concentration tilts toward segments with measurable productivity outcomes rather than entertainment value alone.
- Gaming:Transaction volume currently dominates platform revenue, though cloud-rendered substitutes on conventional screens constrain dedicated headset ecosystem expansion. Youth-centric creator economies sustain lower barrier-to-entry tooling demand.
- Virtual Commerce:Retailers pilot immersive storefronts where spatial audio and real-time 3D rendering replicate physical browsing. Implementation concentrates among Bay Area venture-backed platforms with direct-to-consumer logistics integration.
- Social Interaction:Persistent shared environments prioritize low-latency networking over graphical fidelity.
- Education:K-12 and vocational modules face procurement friction from decentralized district purchasing authority.
Gaming retains the largest revenue base; Virtual Commerce is climbing the fastest as retailers seek differentiation from conventional e-commerce.
Technology:
Platform builders select technology stacks based on whether their target segment prioritizes decentralization, visual fidelity, or computational scale.
- AI:Generative models collapsing content production costs enable mid-market enterprise adoption previously blocked by artwork budgets. Procedural environment generation pipelines now serve manufacturing operations teams in Midwest industrial corridors.
- 3D Modeling:Neural radiance fields and Gaussian splatting consolidate volumetric capture for automotive and aerospace digital-twin construction. These techniques compress physical prototyping cycles while reducing specialist headcount requirements.
- Blockchain:Distributed ledger infrastructure underpins tokenized asset ownership with liquidity concentrated in speculative collectibles.
- Cloud Computing:Edge rendering architectures reduce headset hardware requirements but demand FCC spectrum clarity for wireless streaming performance.
3D Modeling anchors the deepest installed expertise; AI is gaining share fastest as generative tooling democratizes asset creation.
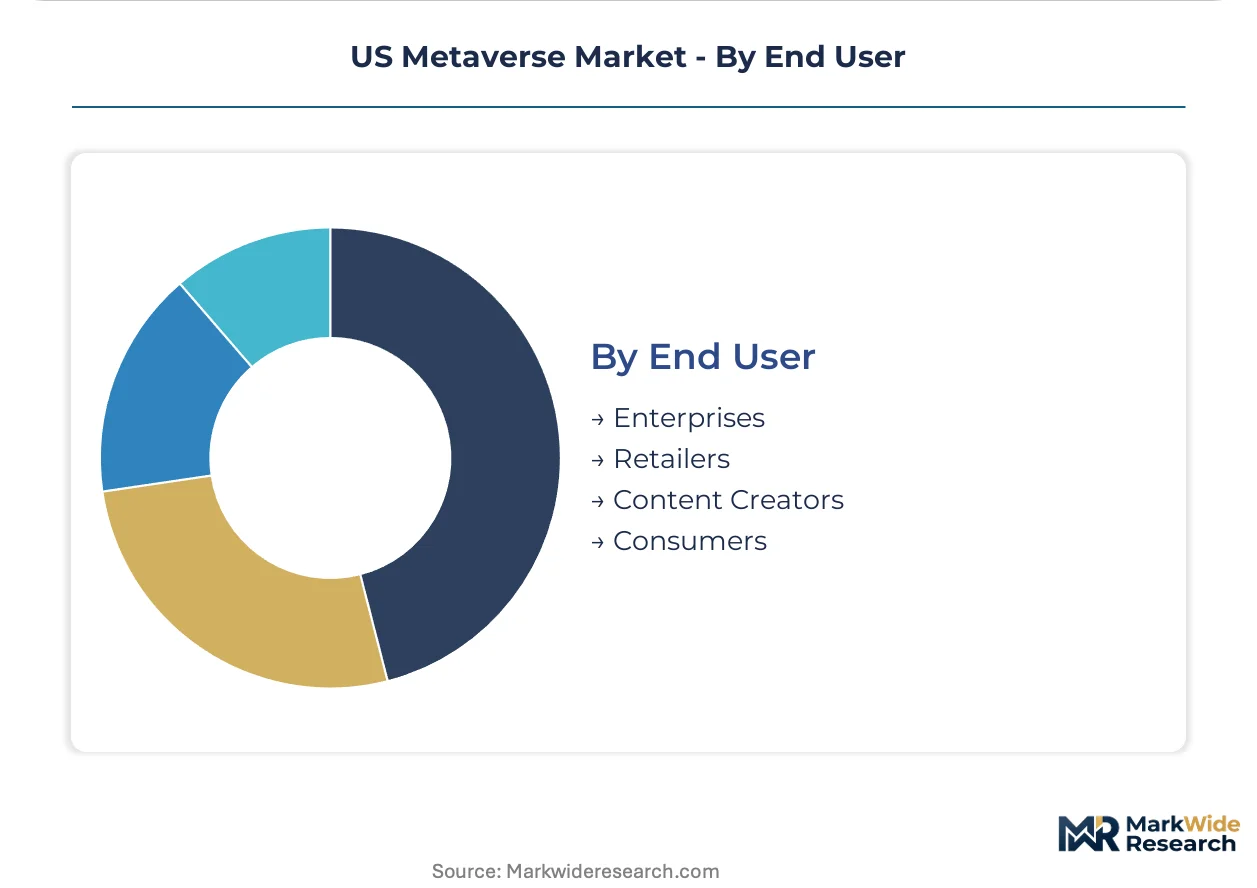
End User:
Procurement authority patterns determine sales cycle length and customization requirements across buyer categories.
- Enterprises:Manufacturing operations teams in Midwest plant manager roles now pilot mixed-reality solutions without corporate technology committee approval. Departmental self-service acquisition fragments from centralized IT mandates where workforce turnover pressures are acute.
- Content Creators:Independent developers and studios monetize through platform revenue-sharing agreements with tooling access tiered by commercial success thresholds.
- Retailers:Omnichannel operators experiment with virtual showrooms but measure ROI against conventional digital marketing spend.
- Consumers:Hardware purchase decisions hinge on content library depth and wireless headset comfort for extended sessions.
Enterprises command the largest contract values; Content Creators represent the steepest expansion trajectory as generative tooling lowers production barriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
San Francisco Bay Area venture density anchors US metaverse innovation, concentrating developer talent and seed-stage funding unavailable elsewhere domestically. Texas enterprise corridors and Midwest industrial zones present underpenetrated expansion vectors for immersive training vendors.
California
Defense contractors in San Diego and Los Angeles accelerate mixed-reality deployment for maintenance and combat readiness modules. FCC spectrum rules for 6GHz and 60GHz bands reduce hardware manufacturers' radio certification burdens in this jurisdiction. Silicon Valley sustains platform innovation cycles through Epic Games and Meta's vertical integration across headset manufacturing, operating systems, and content distribution.
Texas
Energy and aerospace maintenance sectors in Houston and Dallas-Fort Worth lack immersive training vendor presence, creating white-space deployment potential. State procurement frameworks for industrial simulation remain less restrictive than coastal jurisdictions. Departmental self-service acquisition concentrates among plant managers controlling discretionary capital budgets in Midland-Odessa energy corridors.
New York
Financial services oversight from state regulators fragments national deployment timelines for tokenized virtual assets. SEC disclosure requirements inflate platform compliance costs for metaverse real estate offerings. Manhattan-based retailers pilot immersive storefronts where spatial audio and real-time 3D rendering replicate physical browsing.
Illinois
Manufacturing operations teams in Chicago industrial corridors pilot mixed-reality solutions without corporate technology committee approval. Workforce turnover pressures drive immediate adoption of procedural environment generation for mid-market enterprise training. Custom middleware development extends implementation timelines for legacy ERP integration with manufacturing execution systems.
Washington
Cloud computing infrastructure in Seattle metropolitan area supports edge rendering architectures reducing headset hardware requirements. FCC proceedings on expanded 6GHz unlicensed access reshape wireless headset performance thresholds for Pacific Northwest hardware manufacturers. Spatial audio engineering scarcity concentrates competition for limited talent pools capable of physiological immersion design.
US Metaverse Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across divergent optimization paths. The market structures around photorealistic industrial simulation versus lightweight mobile rendering. Three archetypes dominate: engine licensors controlling real-time 3D pipelines, platform operators with captive hardware ecosystems, and cloud infrastructure providers enabling edge-rendered experiences. Competitive moves concentrate on strategic partnerships with defense contractors and portfolio diversification into generative AI tooling.
Among California-based platform operators, Epic Games and Meta occupy positions at opposing ends of the vertical integration spectrum. Epic exemplifies the engine-licensor archetype leveraging Unreal Engine dominance for high-fidelity industrial contracts. Meta anchors the fully integrated model controlling manufacturing through its Quest ecosystem. Washington-based Microsoft sits within the enterprise productivity tier, representing hybrid cloud-rendered and device-native deployment options.
| Leading Market Players |
|---|
| Epic Games |
| Roblox |
| Meta |
| Decentraland |
| Unity |
| Microsoft |
| NVIDIA |
| IMVU |
| Others |
Pricing and Supply Chain Analysis
Captive hardware manufacturing by California-based platform operators anchors both supply security and pricing power across the US metaverse landscape. This backward integration into headset production, combined with in-house operating system development, insulates vertically integrated players from component volatility while enabling premium positioning against asset-light competitors dependent on third-party assembly.
Pricing Analysis
Outcome-based pricing tied to workforce training throughput anchors enterprise contracts, with defense contractors paying premiums for cleared-facility delivery and sub-20ms latency guarantees. Price differentiation separates defense-grade hardware with FCC-certified 60GHz radios from consumer-tier devices lacking millimeter-wave support. Cost compression in consumer VR intensifies as cloud-rendered gaming substitutes erode dedicated headset demand. Mid-market manufacturers exhibit highest price sensitivity, deferring procurement until AI-generated asset pipelines reduce content production minimums.
Supply Chain Analysis
Single-source vulnerability sits with Asian micro-OLED specialists concentrated in South Korea and Taiwan, where sub-20ms motion-to-photon latency panel production remains capacity-constrained. US headset assemblers draw from Japanese precision optics, Chinese rare-earth magnet suppliers, and domestic FCC-certified radio module fabricators. Tariff exposure on Chinese component inputs threatens margin stability for hardware manufacturers without diversified sourcing. Distribution runs through direct enterprise sales teams for defense contracts and consumer electronics retail channels for mass-market deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
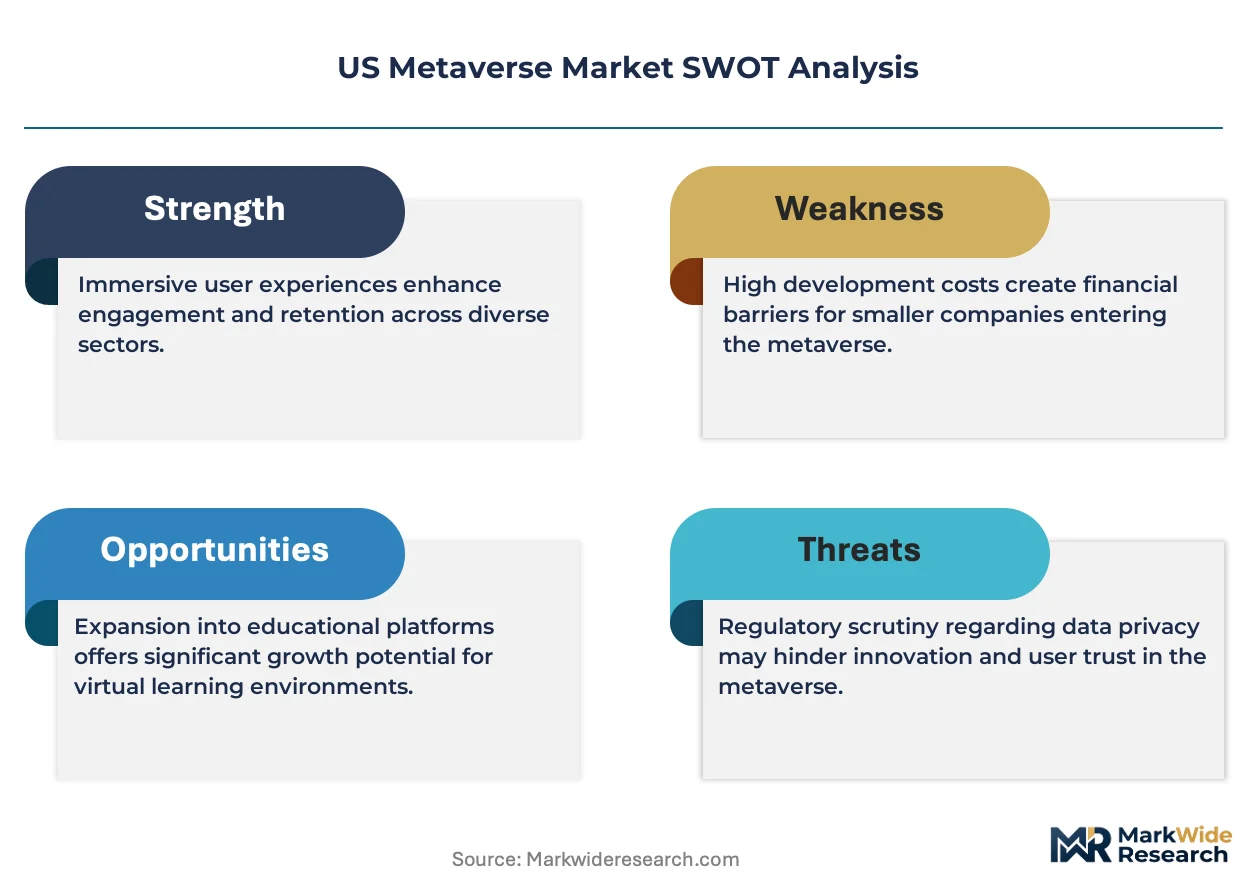
The US metaverse market functions as a cost-of-compliance story where SEC disclosure requirements for tokenized virtual assets create regulatory moats favoring incumbent platforms with established legal infrastructure.
For Market Incumbents: Hedge against cloud-rendered substitution by deepening enterprise software integration and securing NHTSA automotive AR certification ahead of distraction-testing standards. Prioritize captive micro-OLED supply agreements with South Korean panel specialists to defend hardware margins against Asian component volatility. FCC spectrum lobbying coalitions represent critical defensive infrastructure for wireless headset performance leadership. For New Entrants and Emerging Players: Plant managers in Texas energy corridors and Midwest manufacturing operations represent underserved buyer archetypes with discretionary capital budgets and immediate workforce turnover pressures. White-space deployment potential concentrates in Houston-Dallas aerospace maintenance and Chicago industrial training where legacy ERP integration friction has stalled incumbent penetration. Go-to-market execution should emphasize departmental self-service acquisition bypassing centralized IT procurement committees. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by cloud infrastructure providers seeking edge-rendered immersive capabilities. Long-term viability favors platforms with demonstrated defense contracting relationships and generative AI tooling integration rather than speculative tokenized real estate exposure. The signal to watch is NHTSA regulatory clarity on augmented windshield classification, which would unlock Tier-1 supplier OEM integration contracts and reshape automotive AR investment priorities.| Strategic Initiative | Industry Significance |
|---|---|
| FCC Spectrum Coalition Formation | Lobbying for expanded 6GHz unlicensed access enables multi-gigabit wireless headset streaming without licensed spectrum costs. |
| Defense Contracting Certification | Cleared-facility access for Pentagon immersive training mandates secures multi-year procurement relationships with maintenance module providers. |
| AI Asset Pipeline Integration | Procedural environment generation collapses content production costs for mid-market enterprise adoption in Midwest industrial corridors. |
| Micro-OLED Supply Diversification | Reduced dependence on South Korean and Taiwanese panel specialists mitigates input bottlenecks for sub-20ms latency screen procurement. |
| Automotive AR Windshield Partnership | Tier-1 supplier collaboration positions platforms for NHTSA regulatory clarity on augmented-display distraction classification. |
Research Methodology
SEC filings, FCC rulemaking dockets, and defense procurement databases formed the secondary backbone of this analysis, supplemented by hyperscaler capex disclosures and venture funding records from California-based technology investors. Primary interviews with platform engineering leads, defense contracting officers, manufacturing operations managers, and spatial audio engineering specialists validated quantitative assumptions. Bottom-up segment sizing triangulated against top-down market aggregation across hardware, software, and services layers.
Historical trendline analysis of immersive technology adoption curves informed projection frameworks across the analysis window, with segmentation modeling spanning product type, application, technology stack, and end-user procurement authority. CAGRs derived from fitted growth curves incorporating AI tooling penetration rates, FCC spectrum allocation timelines, and enterprise training budget elasticity. Forecast inputs included defense procurement directive implementation schedules and micro-OLED manufacturing capacity expansion announcements.
Revisions become necessary when NHTSA distraction-testing standards materialize, SEC token disclosure rules shift, or micro-OLED supply concentration disrupts hardware deployment timelines. Forecasts reflect documented assumptions about spectrum access, component availability, and regulatory enforcement intensity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
3D Telepresence Market
Virtual Reality (VR) and Augmented Reality (AR)
France Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Firefighter Simulator Market
Virtual Reality (VR) and Augmented Reality (AR)
Asia-Pacific Augmented Reality (AR) and Mixed Reality (MR) Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented Reality (AR) and Mixed Reality (MR) Market
Virtual Reality (VR) and Augmented Reality (AR)
US Augmented and Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
North America Augmented Reality (AR) and Mixed Reality (MR) Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality for Consumer Market
Virtual Reality (VR) and Augmented Reality (AR)
Neuro-Gaming Technology Market
Virtual Reality (VR) and Augmented Reality (AR)
Para-Virtualization Market
Virtual Reality (VR) and Augmented Reality (AR)
AR-VR Head Display Equipment Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented Reality and Virtual Reality (AR/VR) in Aviation Market
Virtual Reality (VR) and Augmented Reality (AR)
Global VR for Medical Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Ski Machines Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented Reality Headsets Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality Content Creation Market