
 AR and VR in Training Market | 2026-2036
AR and VR in Training Market Size, Share, and Industry Trends Forecast 2026-2036
AR and VR in Training Market Outlook
South Korea's government-backed immersive technology clusters is reconfiguring regional supply dynamics for training hardware and software components. Attensi leverages its Nordic origins to sustain dominance in corporate behavioral simulation for energy and logistics clients. CAE anchors its position through in-house production of flight and medical simulators with integrated VR architectures. Strivr competes aggressively in North American sports and retail workforce onboarding through its cloud-streamed headset deployments.
AR and VR in training denotes immersive digital environments that overlay or replace physical reality to simulate operational scenarios, typically requiring sub-20ms motion-to-photon latency and 90Hz minimum refresh rates to prevent user disorientation. These systems reduce live-training costs, eliminate physical risk exposure, and enable repeatable skill rehearsal across hazardous or expensive operational contexts. Healthcare application segments command premium pricing due to FDA validation requirements and liability-sensitive deployment environments. Cloud-based delivery mode represents the fastest-expanding structural channel as 5G infrastructure and edge computing reduce on-premise hardware dependency for enterprise clients. Mixed reality technology occupies an emerging margin pool where holographic patient anatomy overlays blend physical instrument handling with digital visual guidance.
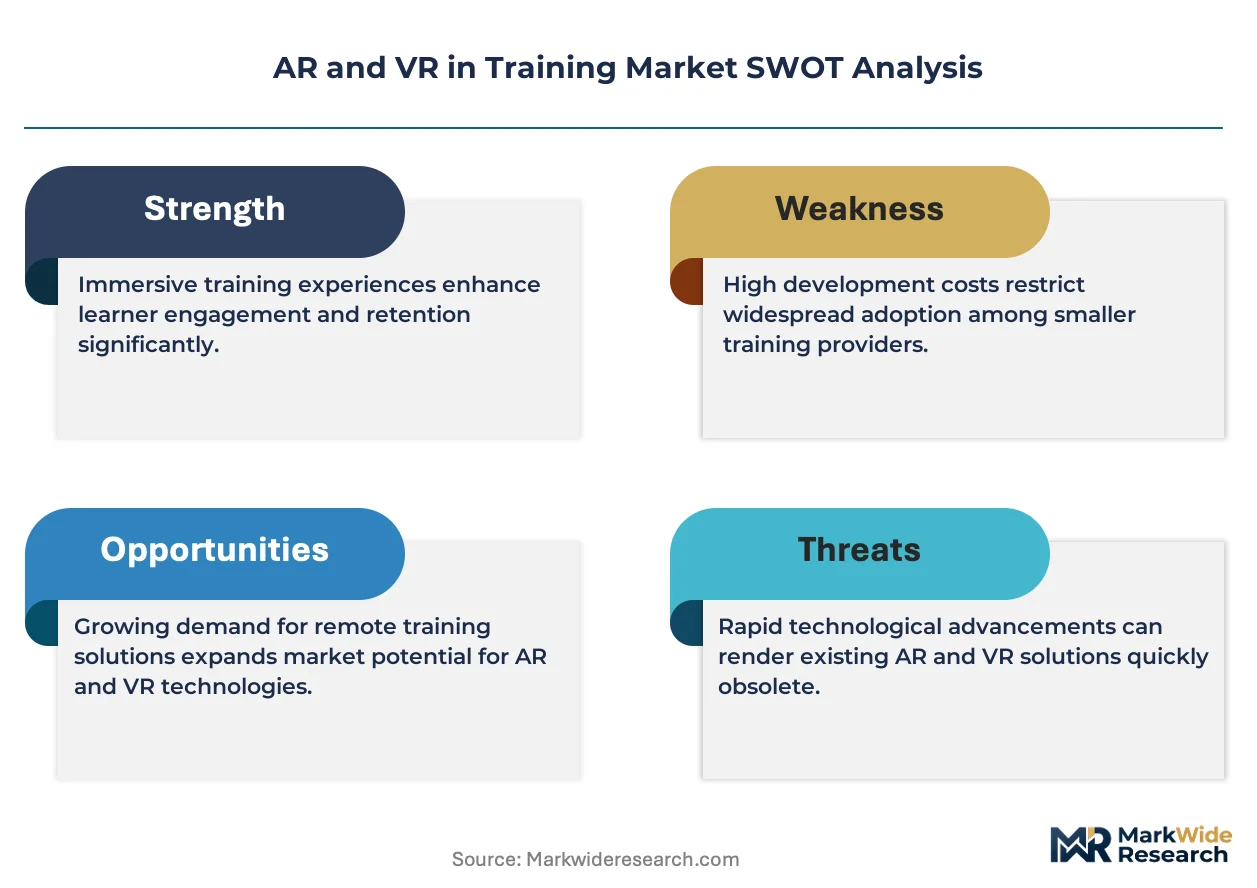
FDA software-as-medical-device guidance and OSHA workplace safety standards jointly determine product certification pathways and enterprise procurement eligibility in the United States. The EU AI Act and GDPR compliance frameworks impose additional algorithmic transparency and biometric data handling requirements on training platform vendors serving European corporates and government clients. Stakeholders must monitor evolving regulatory divergence between jurisdictions to determine whether to architect unified global platforms or regionally segmented compliance builds.
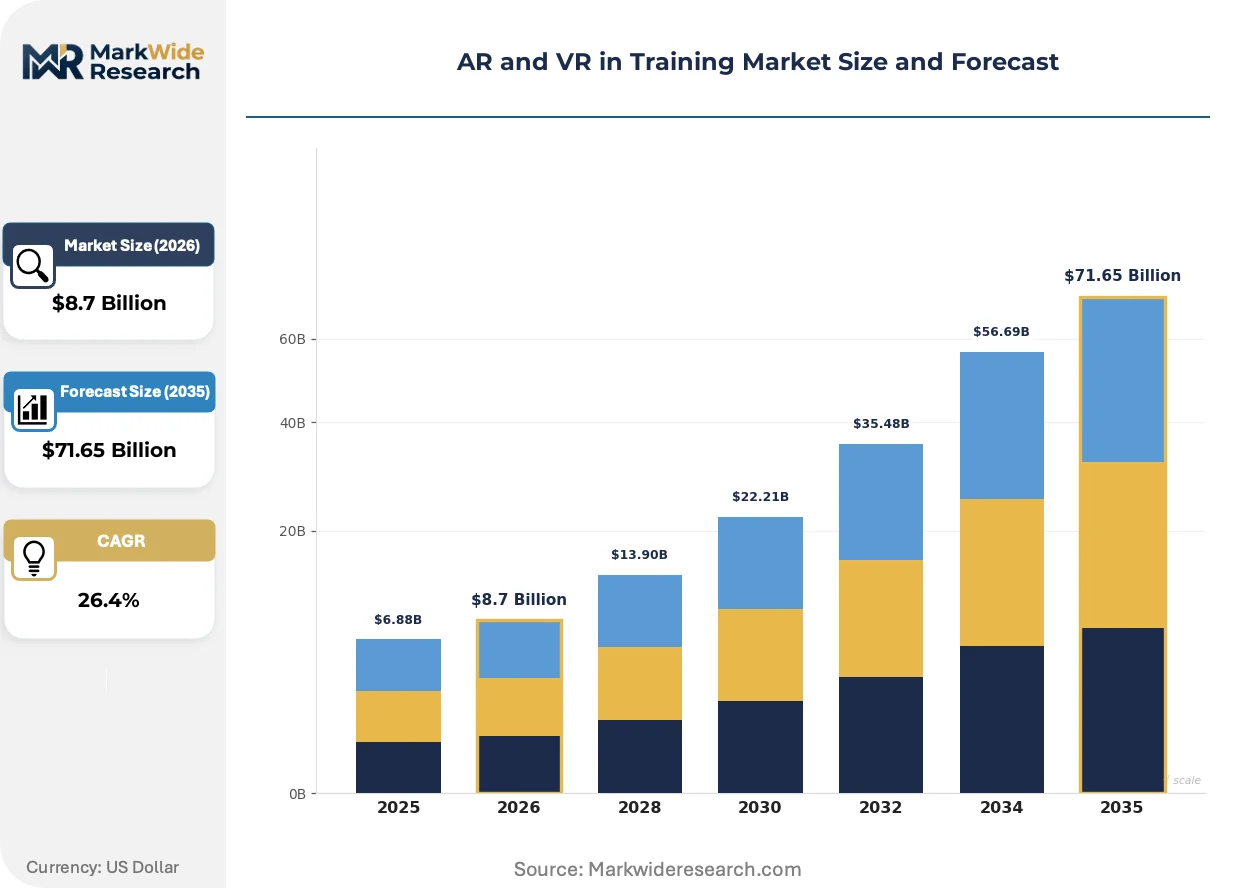
Market Dynamics
Cloud-streamed headset deployments are collapsing on-premise hardware dependency for enterprise training platforms, while FDA software-as-medical-device guidance compresses product development timelines for healthcare simulation vendors.
Growth Catalysts
- 5G Infrastructure Rollout:South Korea's government-backed immersive technology clusters accelerate edge computing deployment for low-latency training delivery. Hospital systems and defense contractors in the United States now procure enterprise-scale platforms requiring sub-20ms motion-to-photon latency.
- FDA Medical Device Software Validation:The guidance framework creates procurement eligibility pathways for surgical simulation vendors serving liability-sensitive healthcare environments. Premium pricing persists in this segment due to compliance-driven vendor qualification requirements.
- Holographic Anatomy Overlays:Mixed reality technology blends physical instrument handling with digital visual guidance, opening margin pools in patient care protocol training. Nordic corporate behavioral simulation specialists leverage this convergence for energy and logistics workforce development.
Market Restraints
- Display Panel Supply Concentration:Micro-OLED and pancake lens manufacturing concentrates among Asian component suppliers, creating input cost volatility for headset producers targeting 90Hz minimum refresh rates.
- Biometric Data Handling Friction:GDPR compliance frameworks impose algorithmic transparency requirements on European corporate and government training deployments, extending sales cycles for platform vendors.
- Motion Sickness Technical Limitations:Latency thresholds below 20ms remain difficult to sustain across wireless streaming architectures, constraining adoption in high-movement training scenarios such as flight simulation.
Strategic Opportunities
- OSHA Workplace Safety Mandates:United States enterprise procurement eligibility increasingly requires immersive hazard exposure training, creating regulatory tailwinds for construction and manufacturing simulation platforms.
- EU AI Act Algorithmic Transparency:European government clients now specify explainable AI requirements for adaptive training modules, favoring vendors with documented decision-pathway architectures.
- Cloud-Native Delivery Convergence:Edge computing and 5G infrastructure enable subscription-based training access, displacing capital-intensive on-premise simulator installations for mid-market logistics and retail clients.
Industry Challenges
- Immersive Content Development Talent Scarcity:3D environment design and haptic feedback programming skills remain concentrated among gaming industry veterans, constraining platform customization velocity for specialized industrial applications.
- Legacy LMS Integration Complexity:Enterprise learning management system architectures require bespoke API development for competency tracking, extending implementation timelines for healthcare and defense training contracts.
- Cross-Jurisdictional Certification Timelines:FDA validation requirements for medical device software diverge from EU MDR pathways, forcing vendors to architect regionally segmented compliance builds rather than unified global platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AR and VR in Training Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $71.65 Billion |
| CAGR (2026 – 2036) | 26.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Healthcare, Manufacturing, Military, Education Technology: AR, VR, Mixed Reality, Holography End User: Corporates, Educational Institutions, Government, Training Providers Delivery Mode: Cloud-Based, On-Premise, Mobile, Web-Based |
| Companies Covered | Attensi, Transfr, Strivr, CAE, Osso VR, NipsApp Game Studios, G-Cube, ENGAGE XR, SweetRush Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AR and VR in Training Market Strategic Shifts
Spatial computing architectures are actively compressing the boundary between physical instrument handling and digital scenario generation, reshaping how hazardous operational contexts are rehearsed without live exposure.
Cloud-native streaming protocols are collapsing the capital barrier to enterprise VR deployment. Mid-market logistics operators now access surgical-grade simulation fidelity through subscription models rather than seven-figure on-premise installations. This compression is displacing traditional flight and medical simulator hardware vendors from downstream training service contracts.
REACH chemical safety documentation requirements and RoHS substance restrictions are reshaping headset component sourcing for European enterprise clients. Manufacturers must now trace restricted substances through haptic feedback actuator supply chains. Medical training platforms serving EU government tenders face additional CSRD sustainability reporting obligations that extend vendor qualification timelines.
Buying committees now mandate outcome-based competency verification rather than seat-time metrics for training procurement. Defense contractors and hospital systems in the United States prioritize platforms with embedded skills assessment analytics. This behavioral pivot favors Nordic simulation specialists with documented behavioral change measurement frameworks over legacy content libraries.
AR and VR in Training Market Segmentation
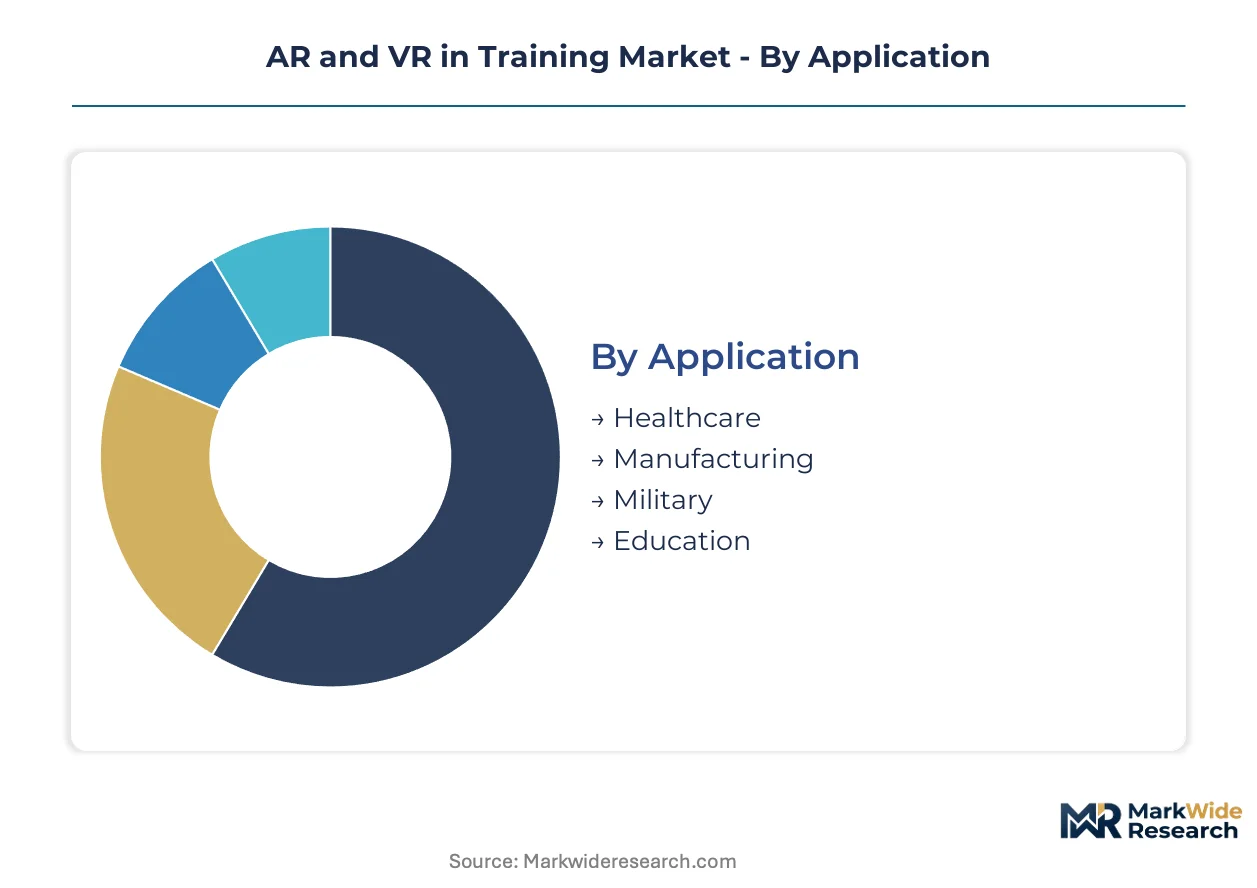
Training platform procurement cycles vary dramatically across application contexts, with healthcare validation timelines stretching years while retail onboarding modules refresh quarterly. Understanding these velocity differentials enables vendors to calibrate R&D investment and partnership strategies against revenue predictability.
Application:
Healthcare contracts turn over slowest due to FDA software-as-medical-device validation requirements, while education procurement cycles accelerate fastest as institutions pilot subscription-based immersive curricula.
- Healthcare:Surgical simulation and patient care protocol training demand sub-20ms motion-to-photon latency and 90Hz refresh rates to prevent user disorientation. Hospital systems in the United States concentrate procurement in this segment, driven by liability-sensitive deployment environments and premium pricing tolerance for FDA-validated platforms.
- Manufacturing:Hazard exposure rehearsal for assembly line operations and equipment maintenance blends physical instrument handling with digital scenario generation. OSHA workplace safety mandates in the United States are reshaping enterprise procurement eligibility, creating regulatory tailwinds for construction and industrial simulation platforms.
- Military:Defense contractors deploy enterprise-scale platforms requiring edge computing infrastructure for low-latency delivery.
- Education:Institutional pilot programs favor cloud-streamed headset deployments over capital-intensive installations.
Healthcare dominates installed base. Education is where expansion concentrates.
Technology:
Hardware refresh rates stratify by immersion depth, with mixed reality commanding development investment as holographic overlays bridge physical-digital boundaries.
- AR:Overlay architectures superimpose digital guidance onto physical workspaces without occluding environmental awareness. Logistics operators in Europe prioritize this modality under GDPR-constrained biometric data handling frameworks that limit full immersion capture.
- VR:Fully immersive environments replace physical reality entirely, demanding sustained sub-20ms latency across wireless streaming architectures. Flight simulation and surgical training concentrate demand here, though motion sickness technical limitations constrain adoption in high-movement scenarios.
- Mixed Reality:Holographic patient anatomy overlays blend physical instrument handling with digital visual guidance, opening margin pools in precision-dependent training contexts.
- Holography:Volumetric display technologies enable multi-viewer anatomical visualization without headset encumbrance.
VR retains the deepest installed base. Mixed Reality is climbing the fastest as hardware converges.
End User:
Budget authority and compliance burden diverge sharply, with government tenders demanding algorithmic transparency while corporate buyers prioritize outcome-based competency verification.
- Corporates:Energy and logistics workforce development programs favor behavioral simulation platforms with documented change measurement frameworks. Nordic specialists leverage this preference against legacy content libraries.
- Educational Institutions:Universities and vocational schools pilot immersive curricula through subscription models that displace capital-intensive on-premise installations.
- Government:Defense and healthcare agencies mandate embedded skills assessment analytics and explainable AI requirements for adaptive training modules.
- Training Providers:Third-party instructional firms aggregate content across modalities to serve mid-market clients lacking internal development capabilities.
Corporates anchor current revenue. Government tenders represent the steepest expansion trajectory.
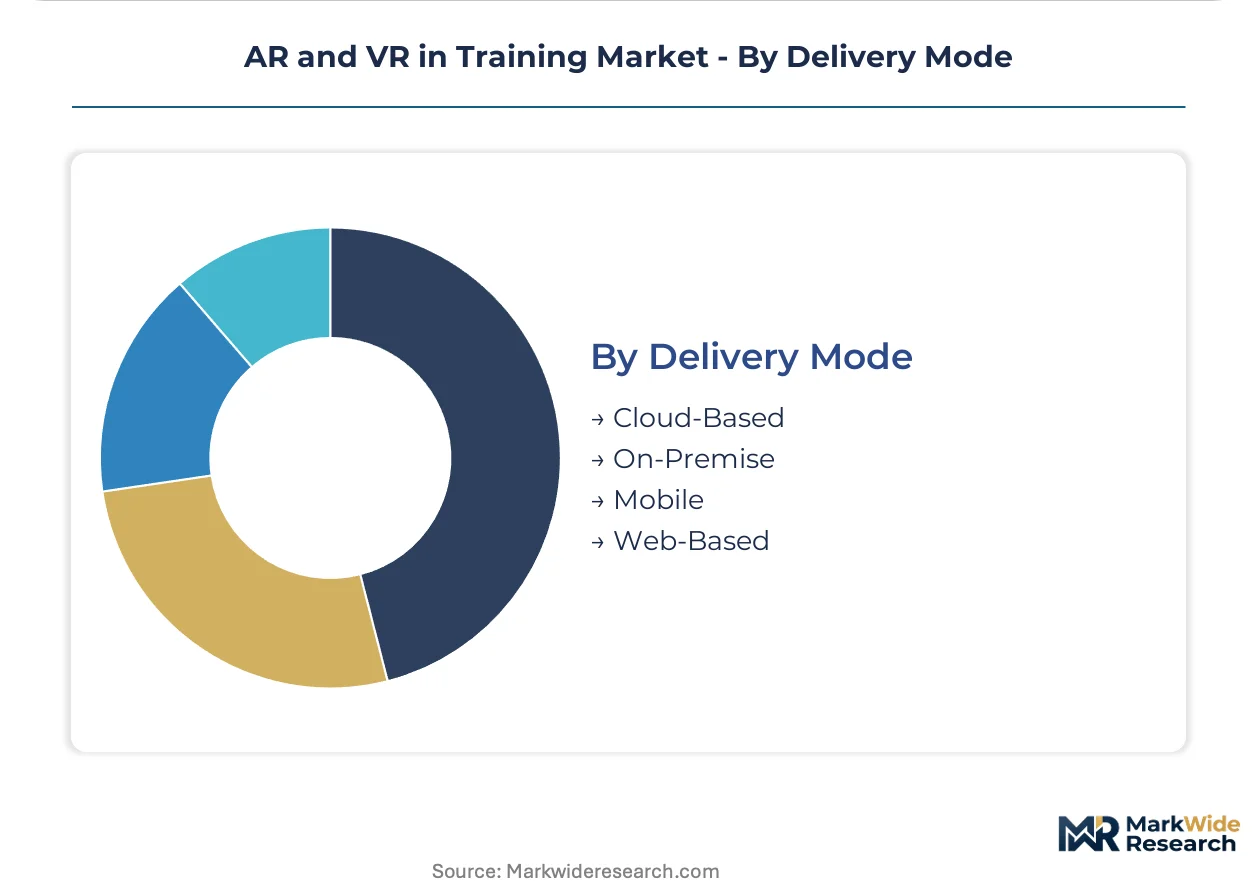
Delivery Mode:
Infrastructure dependency determines addressable market breadth, with cloud-native protocols collapsing the capital barrier for mid-market entrants previously excluded from simulator-grade fidelity.
- Cloud-Based:5G infrastructure and edge computing enable subscription-based training access with surgical-grade simulation fidelity. South Korea's government-backed immersive technology clusters accelerate regional deployment of these architectures.
- On-Premise:Capital-intensive installations persist in defense and healthcare contexts requiring air-gapped security or sub-20ms latency guarantees difficult to sustain across wireless streaming.
- Mobile:Smartphone-dependent AR experiences sacrifice immersion depth for deployment ubiquity in field-based maintenance training.
- Web-Based:Browser-streamed content enables rapid pilot deployment without hardware procurement cycles, though limited haptic integration constrains skill transfer efficacy.
On-Premise retains legacy contracts. Cloud-Based is gaining share fastest as 5G infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA software-as-medical-device guidance anchors procurement pathways in the United States, while South Korea's government-backed clusters and European regulatory frameworks create divergent compliance environments across major training technology markets.
United States
Hospital systems and defense contractors drive enterprise-scale platform procurement requiring sub-20ms motion-to-photon latency. OSHA workplace safety mandates reshape eligibility for construction and manufacturing simulation vendors. Greater Boston and Seattle-Tacoma concentrate surgical simulation development alongside Pentagon-adjacent defense contractors.
South Korea
Seoul Capital Area hosts government-backed immersive technology clusters accelerating edge computing deployment for low-latency training delivery. MFDS medical software frameworks align with international validation standards for regional export competitiveness. Busan-Ulsan corridor anchors hardware component manufacturing for micro-OLED display panels.
Germany
Industrial conglomerates in North Rhine-Westphalia procure hazard exposure simulation for precision manufacturing workforce development. REACH chemical safety documentation and RoHS substance restrictions reshape headset component sourcing obligations. Bavaria's Munich-Stuttgart corridor concentrates automotive and aerospace training platform integration.
United Kingdom
London financial services and North Sea energy operators deploy behavioral simulation for compliance and safety-critical workforce protocols. GDPR biometric data handling frameworks extend sales cycles for full-immersion platform vendors. Cambridge-Oxford arc anchors mixed reality research commercialization.
Japan
Tokyo-Kanto manufacturing bases and Osaka-Kansai medical device clusters sustain dual demand tracks for precision training systems. METI industrial digitization programs subsidize SME adoption of cloud-streamed simulation platforms. Nagoya-Chubu corridor concentrates automotive assembly line VR training deployment.
AR and VR in Training Market Competitive Environment
Capability concentration sits with specialized healthcare and defense simulation developers; scale advantage sits with cloud-native platform operators serving mid-market corporate clients. The vendor base stratifies across three tiers: FDA-validated medical device specialists, Nordic-originated behavioral simulation firms, and cloud-streaming workforce onboarding platforms. Dominant competitive moves include strategic partnerships with 5G infrastructure operators and portfolio diversification into mixed reality holographic overlays.
Within the healthcare-validated tier, Osso VR and CAE occupy positions anchored by regulatory compliance pathways, while Attensi exemplifies the Nordic behavioral simulation archetype serving energy and logistics verticals. Strivr represents cloud-native delivery models competing through subscription-based headset deployments. These three patterns—regulatory anchoring, geographic specialization, and infrastructure leverage—define the competitive geometry without any single vendor commanding cross-vertical dominance.
| Leading Market Players |
|---|
| Attensi |
| Transfr |
| Strivr |
| CAE |
| Osso VR |
| NipsApp Game Studios |
| G-Cube |
| ENGAGE XR |
| SweetRush Inc. |
| Others |
Value Chain & Pricing Dynamics
The Busan-Ulsan corridor's micro-OLED freight costs transmit directly through headset bill-of-materials, amplifying price spreads between FDA-validated surgical simulation tiers and mid-market logistics training bundles while compressing margins for hardware-as-a-service operators.
Pricing Analysis
United States hospital systems pay three to five times European corporate rates for equivalent hardware specifications due to FDA software-as-medical-device validation overhead and liability-sensitive deployment environments. Pricing stratifies across premium, standard, and economy tiers where certification grade and after-sales service bundling drive differentiation. Cost compression in the mid-market logistics segment is intensifying because cloud-native platform operators displace capital-intensive on-premise installations. Government tenders exhibit lowest price sensitivity due to algorithmic transparency mandates; retail workforce onboarding programs show highest sensitivity to per-seat subscription economics.
Supply Chain Analysis
Export-control regimes limiting semiconductor lithography equipment flows to Chinese foundries are reshaping display driver IC sourcing strategies for headset manufacturers targeting 90Hz refresh rates. Micro-OLED and pancake lens manufacturing concentrates in South Korea, Japan, and Taiwan, drawing from rare earth element refineries in China and photoresist chemical suppliers in Germany. Single-source vulnerability pervades haptic feedback actuator supply chains where Japanese precision motor producers dominate. Distribution runs through enterprise IT procurement channels for healthcare and defense clients, while direct-to-end-user subscription models bypass traditional AV integrators for mid-market corporate deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity pervades this market as buying committees pivot from seat-time metrics to outcome-based competency verification, creating niche openings for behavioral measurement specialists and adaptive AI module developers.
For Market Incumbents: Insulate FDA-validated healthcare positions through in-house production of surgical simulation hardware rather than outsourced assembly, while accelerating backward integration into edge computing infrastructure to defend against cloud-native entrants. Threat of displacement looms from Nordic behavioral simulation specialists with documented change measurement frameworks; certification investment in EU AI Act algorithmic transparency pathways provides defensive leverage. For New Entrants and Emerging Players: Pursue white-space in European corporate behavioral simulation where GDPR-constrained biometric data handling frameworks extend sales cycles for incumbent full-immersion vendors. Mid-market logistics operators in Germany and Japan present most penetrable demand due to cloud-native delivery preference and OSHA-aligned safety mandate compliance requirements. Go-to-market angle should emphasize subscription-based headset deployment with embedded skills assessment analytics. For Investors and Strategic Acquirers: Cloud-native platform operators with 5G infrastructure partnerships represent the priority acquisition archetype for exposure to fastest-expanding delivery mode segments. Long-term viability hinges on sustained edge computing deployment velocity and mixed reality holographic overlay development pipelines. Signal to watch is MFDS medical software framework alignment activity among Seoul Capital Area clusters as inflection indicator for regional export competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Software-as-Medical-Device Submission | Creates procurement eligibility pathways for surgical simulation vendors serving liability-sensitive hospital systems. |
| 5G Infrastructure Partnership | Enables sub-20ms motion-to-photon latency guarantees for cloud-streamed enterprise training deployments. |
| EU AI Act Algorithmic Transparency Investment | Qualifies adaptive training modules for European government tenders requiring explainable AI specifications. |
| Backward Integration into Micro-OLED Sourcing | Reduces display panel supply concentration risk for headset producers targeting 90Hz refresh rates. |
| Mixed Reality Holographic Overlay Development | Opens margin pools in precision-dependent training contexts blending physical instrument handling with digital guidance. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA 510(k) clearance databases, SEC 10-K filings from headset component suppliers, and South Korean MFDS medical software registration records. Interviews with surgical simulation product managers, hospital biomedical engineers, defense contractor training officers, and 5G infrastructure deployment leads inform demand-side validation. Bottom-up triangulation against top-down macroeconomic indicators ensures segmentation integrity across application, technology, and delivery mode dimensions.
Forecast inputs include modeled adoption curves for cloud-based versus on-premise deployment, hardware refresh rate tier migration patterns, and regulatory validation timeline differentials across jurisdictions. Segmentation dimensions span healthcare, manufacturing, military, and education applications; AR, VR, mixed reality, and holography technologies; and cloud-based, on-premise, mobile, and web-based delivery modes. CAGRs derive from fitted growth curves calibrated against historical adoption analogs in enterprise software and medical device markets.
Macroeconomic conditions sit as an overlay; deviation in 5G infrastructure capex cycles or semiconductor equipment export control enforcement would shift the trajectory. Forecasts reflect assumptions about sustained edge computing deployment velocity and regulatory pathway stability. Material shifts in FDA software-as-medical-device guidance or EU AI Act implementation timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
Commercial Augmented Reality Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
Europe Virtual Reality (VR) Health Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Fitting Room Market
Virtual Reality (VR) and Augmented Reality (AR)
5G and Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Telepresence Equipment Market
Virtual Reality (VR) and Augmented Reality (AR)
US Augmented and Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Europe Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Virtual Reality in Therapy Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Mixed Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality for Consumer Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Production Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Mirror Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Reality Connected Service Market
Virtual Reality (VR) and Augmented Reality (AR)
Para-Virtualization Market
Virtual Reality (VR) and Augmented Reality (AR)
AR-VR Head Display Equipment Market
Virtual Reality (VR) and Augmented Reality (AR)
Global AR and VR Smart Glasses Market