
 India Virtual Production Market | 2026-2036
India Virtual Production Market Size, Share, and Industry Trends Forecast 2026-2036
India Virtual Production Market Insights
BIS IS 13252 certification for electronic display equipment is reorganizing vendor eligibility across India's virtual production sector. Green Rain Studios LLP leverages proprietary LED volume infrastructure to dominate high-end commercial work in Mumbai. Qube Cinema sustains technology leadership through deep specialization in real-time rendering pipelines for regional cinema. Annapurna Studios anchors South Indian demand with integrated on-premises production facilities in Hyderabad.
Virtual production in India fuses real-time rendering engines, motion-capture arrays, and LED volume stages to generate photorealistic backgrounds without physical location shoots; typical LED configurations deploy 2.8mm pixel pitch panels in 270-degree volumes with camera-tracking integration via Unreal Engine or Unity. LED Volume technology captures the largest share of capital expenditure as studios replace green-screen infrastructure. Cloud-Based deployment represents the fastest-expanding segment, though On-Premises systems retain margin concentration due to recurring technical service contracts. Feature Films application drives premium pricing, while Commercials application generates higher volume throughput for mid-tier operators.
TRAI broadcast quality mandates and BIS equipment certification together elevate compliance costs for new entrants, effectively filtering supplier pools. CDSCO medical-device-adjacent imaging standards indirectly shape motion-capture hardware import pathways. The central bank's digital payment infrastructure supports cloud-based remote production billing models. Stakeholders must monitor how RBI cross-border data rules and state-level film subsidy programs jointly determine where production capacity expands next.
Market Dynamics
LED volume infrastructure is compressing production timelines for Indian film studios while BIS certification requirements filter vendor pools and reshape capital deployment patterns across Maharashtra and Telangana.
Growth Catalysts
- Real-time rendering engines:Unreal Engine and Unity adoption in Mumbai studios eliminates location scouting costs and accelerates post-production workflows for feature films.
- PLI scheme incentives:Domestic manufacturing subsidies for electronic components reduce import dependency for LED panel assemblies used in volume stages.
- Hyderabad studio cluster:Annapurna Studios and surrounding facilities anchor integrated production ecosystems that attract South Indian regional cinema projects.
Market Restraints
- Import concentration for motion-capture hardware:CDSCO medical-device-adjacent imaging standards create customs friction for specialized camera tracking equipment.
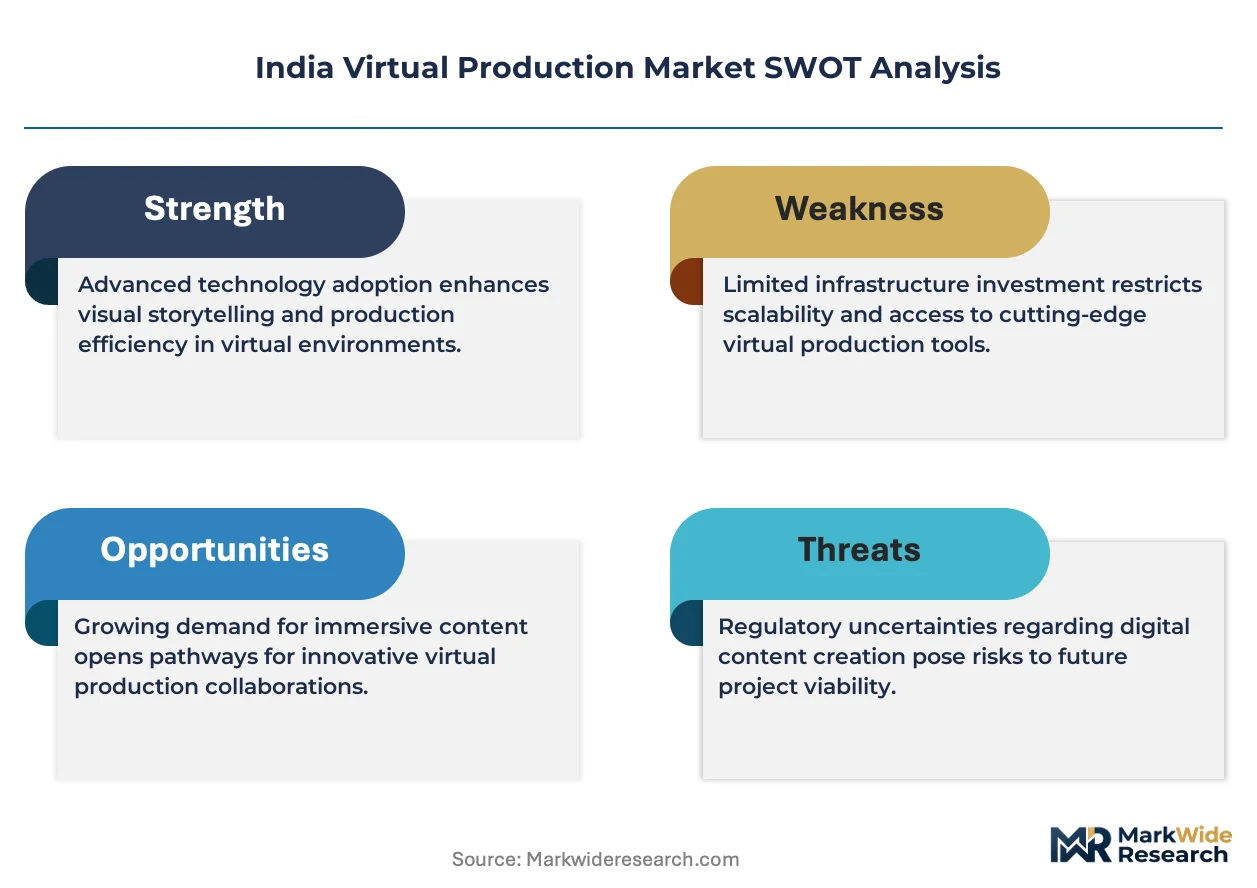
- Technical limitation in 2.8mm pixel pitch:Close-proximity shooting demands higher-resolution panels that remain cost-prohibitive for mid-tier operators.
- BIS IS 13252 compliance timelines:Certification delays for LED display equipment extend vendor onboarding cycles and constrain rapid capacity expansion.
Strategic Opportunities
- Telangana film subsidy programs:State-level production incentives attract streaming platform content investment beyond traditional Bollywood centers.
- Cloud-based remote production:RBI digital payment infrastructure enables distributed billing models for post-production services across smaller cities.
- Convergence of AI-assisted pre-visualization:Machine learning tools integrated with LED volumes compress pre-production planning cycles for commercial advertising.
Industry Challenges
- Unreal Engine technical artist shortage:Real-time rendering specialization remains scarce in Indian VFX training pipelines.
- Capex intensity for 270-degree volumes:LED panel procurement and camera-tracking arrays demand upfront investment that strains independent studio balance sheets.
- Cross-border data compliance:RBI rules on international data transfers complicate cloud-based collaboration with foreign post-production houses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Virtual Production Market |
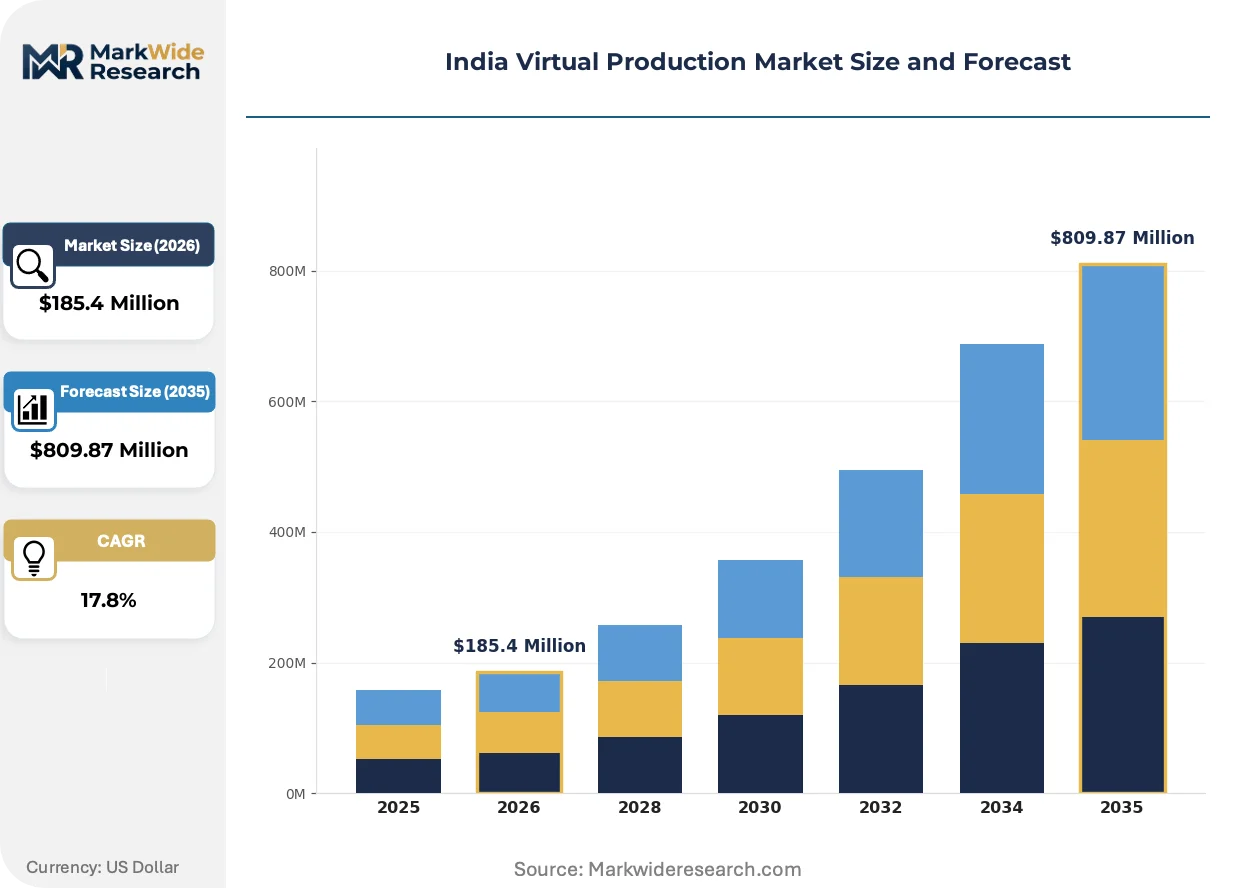
| Market Size in 2026 | $185.4 Million |
| Market Size in 2035 | $809.87 Million |
| CAGR (2026 – 2036) | 17.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Real-Time Rendering, Motion Capture, LED Volume, AR Integration End User: Film Studios, Television Networks, Advertising Agencies, Independent Producers Application: Feature Films, Television Shows, Commercials, Live Events Deployment: On-Premises, Cloud-Based, Hybrid, Remote Production |
| Companies Covered | Green Rain Studios LLP, Liminal - VR/AR Agency, Adobe Inc., Qube Cinema, Media.Monks (S4 Capital), Annapurna Studios, Intellistudios (DB Productions), TILTLABS, Cineom, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Virtual Production Market Trends and Innovations
Virtual production workflows are fragmenting traditional post-production hierarchies as real-time technologies compress decision cycles and regulatory compliance becomes a competitive differentiator.
Camera-tracking sensor arrays are miniaturizing from room-scale installations to wearable and handheld configurations. Independent commercial producers in Mumbai are adopting these compact systems for rapid-turnaround advertising shoots. This compression is miniaturizing the minimum viable studio footprint and enabling boutique operators to compete for mid-budget projects.
TRAI broadcast quality mandates are tightening technical specifications for content delivered to streaming platforms. These rules elevate encoding and color-grading requirements for virtual production outputs. Feature film segments are responding by investing in calibrated reference monitoring infrastructure to ensure compliance.
Service unbundling is separating LED volume rental from technical supervision and post-production finishing. Mid-tier studios in Hyderabad are purchasing fractional stage time rather than owning complete facilities. This pattern concentrates in commercial advertising, where project-based budgeting favors variable cost structures over fixed infrastructure ownership.
India Virtual Production Market Segmentation
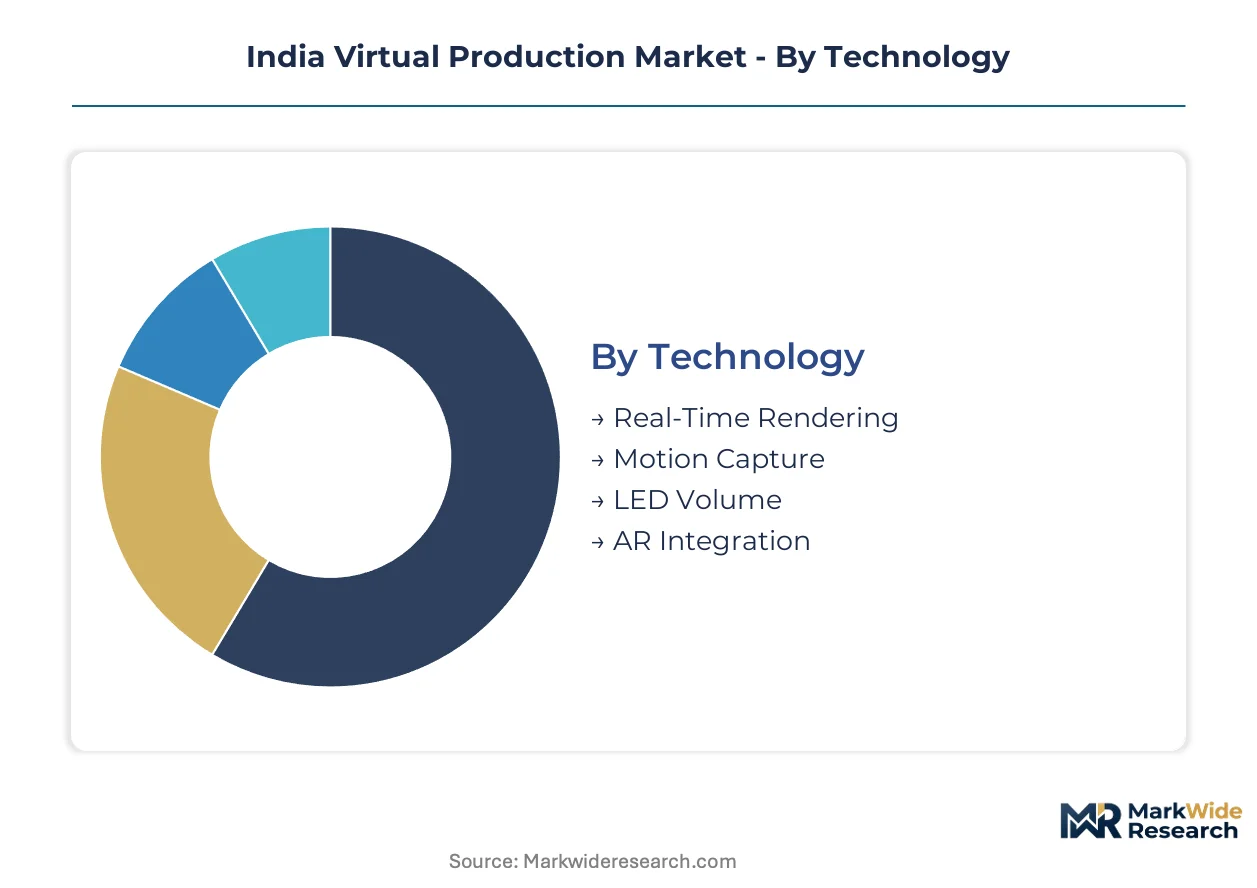
Segmentation in India's virtual production market reveals how regulatory compliance, capital intensity, and workflow specialization split demand across distinct technology tiers and customer profiles. Understanding these divides clarifies where BIS certification burdens fall heaviest and where cloud-based alternatives are gaining traction.
Technology:
BIS IS 13252 certification requirements apply unevenly across technology categories, with LED Volume and AR Integration facing stricter display equipment scrutiny than software-centric alternatives.
- LED Volume:Deploys 2.8mm pixel pitch panels in 270-degree configurations with Unreal Engine camera tracking. Demand concentrates in Mumbai and Hyderabad film studios where Annapurna Studios and Green Rain Studios LLP anchor high-end commercial production. BIS certification timelines for imported display modules extend vendor onboarding cycles.
- Real-Time Rendering:Unreal Engine and Unity pipelines eliminate location scouting costs and compress post-production workflows. Maharashtra-based feature film producers drive adoption as talent scarcity for technical artists creates pricing premiums for certified operators.
- Motion Capture:Room-scale sensor arrays and wearable tracking hardware. CDSCO medical-device-adjacent imaging standards create customs friction for specialized camera tracking equipment imports.
- AR Integration:Overlay rendering for live broadcast augmentation. Telangana television networks deploy this for regional news programming with lower capital thresholds than full LED volumes.
LED Volume handles the majority of throughput; Real-Time Rendering is expanding most quickly on share as software licensing outpaces hardware procurement cycles.
End User:
Capital deployment capacity separates end user tiers, with state-level film subsidy eligibility further stratifying which customer types can absorb upfront infrastructure costs.
- Film Studios:Integrated production facilities with captive LED volumes and in-house technical teams. Hyderabad's Annapurna Studios exemplifies this tier, leveraging Telangana subsidy programs to anchor South Indian regional cinema projects.
- Advertising Agencies:Project-based commercial producers purchasing fractional stage time rather than owning complete facilities. Mumbai's mid-tier operators dominate this segment with rapid-turnaround shoots for consumer brands.
- Television Networks:TRAI broadcast quality mandates drive calibrated reference monitoring investments for streaming-compliant output.
- Independent Producers:Boutique operators adopting miniaturized camera-tracking arrays to compete for mid-budget projects with compressed studio footprints.
Film Studios command the largest capital allocations; Advertising Agencies are gaining share fastest through service unbundling and variable cost structures.
Application:
Margin structure varies sharply by application, with feature films justifying premium equipment investments while commercials generate volume throughput for asset-light operators.
- Feature Films:Premium pricing tier with extended production timelines demanding full 270-degree LED volumes and certified color-grading pipelines. Bollywood productions in Maharashtra anchor this segment.
- Commercials:Higher volume throughput with compressed schedules favoring fractional stage rentals and AI-assisted pre-visualization. Mumbai's advertising cluster drives regional demand concentration.
- Television Shows:Streaming platform content with TRAI encoding compliance requirements elevating technical specification investments.
- Live Events:Real-time broadcast augmentation with AR Integration for sports and entertainment programming.
Feature Films absorb the deepest capital commitments; Commercials are climbing the fastest as mid-tier operators proliferate.
Deployment:
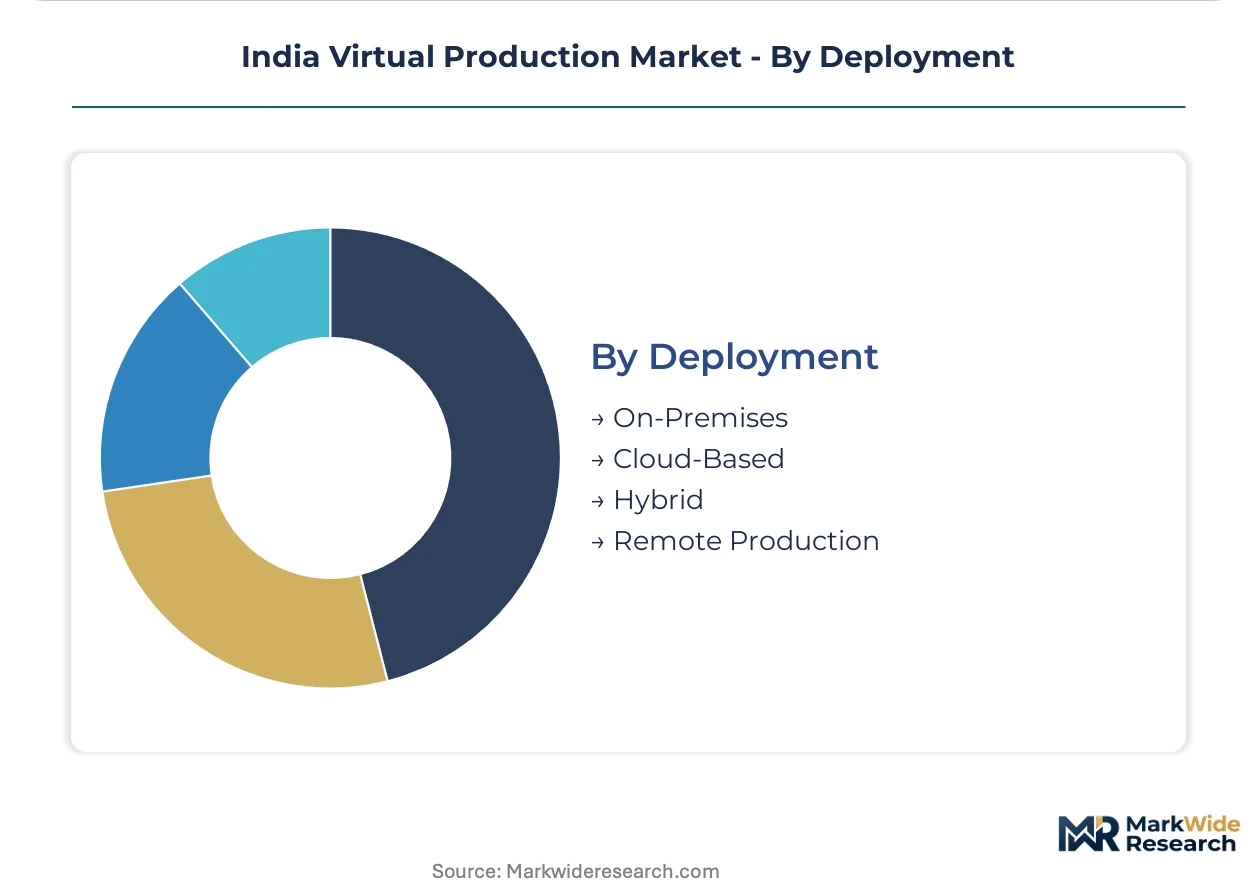
RBI cross-border data rules and digital payment infrastructure jointly determine which deployment models can scale across India's distributed production geography.
- On-Premises:Captive LED volume stages with recurring technical service contracts generating margin concentration. Hyderabad and Mumbai studio clusters retain this model for premium tier productions.
- Cloud-Based:Remote rendering and collaborative post-production with distributed billing models enabled by central bank digital payment rails. This segment faces RBI data localization constraints for international collaboration.
- Hybrid:Split workflows combining on-premises capture with cloud-based finishing. Emerging pattern among mid-tier studios managing BIS compliance costs.
- Remote Production:Location-independent directing with real-time streaming feeds. Smaller cities leverage this to access Mumbai and Hyderabad technical talent without physical relocation.
On-Premises retains the dominant revenue share; Cloud-Based deployment shows the steepest expansion trajectory as RBI infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Film studios and advertising agencies concentrate in Maharashtra and Telangana, where state-level production incentives and established technical infrastructure create distinct buyer archetypes with divergent capital deployment capacities.
Maharashtra
Bollywood production houses and Mumbai-based commercial operators drive LED volume demand for feature films and rapid-turnaround advertising shoots. BIS IS 13252 certification requirements for electronic display equipment filter vendor eligibility and extend procurement timelines. Green Rain Studios LLP anchors the Mumbai cluster with proprietary infrastructure dominating high-end commercial work.
Telangana
Annapurna Studios and surrounding facilities anchor integrated production ecosystems serving South Indian regional cinema. State-level film subsidy programs attract streaming platform content investment beyond traditional Bollywood centers. Hyderabad's studio cluster retains on-premises deployment models with recurring technical service contracts generating margin concentration.
Karnataka
Bengaluru-based technology service providers support cloud-based remote production workflows with distributed billing models. RBI digital payment infrastructure enables smaller operators to access Mumbai and Hyderabad technical talent without physical relocation. The state's software specialization creates demand for real-time rendering pipeline integration.
Tamil Nadu
Chennai's established film industry infrastructure supports motion-capture hardware deployment for regional cinema production. CDSCO medical-device-adjacent imaging standards create customs friction for specialized camera tracking equipment imports. Local studios adopt miniaturized sensor arrays to compress minimum viable studio footprints.
Delhi-NCR
Advertising agencies and television networks in the National Capital Region deploy AR integration for live broadcast augmentation with lower capital thresholds than full LED volumes. TRAI broadcast quality mandates drive calibrated reference monitoring investments for streaming-compliant output. The region's media concentration supports fractional stage time purchasing rather than captive infrastructure ownership.
India Virtual Production Market Competitive Landscape
Player mix skews toward integrated studio operators with captive LED volumes and specialized technology vendors with deep rendering pipeline expertise. Market structure exhibits tiered concentration where premium-tier facilities in Mumbai and Hyderabad absorb disproportionate capital allocation. Three archetypes dominate: proprietary infrastructure owners, real-time rendering specialists, and cloud-based service orchestrators. Competitive dynamics center on capacity expansion through LED volume construction and strategic partnerships bridging hardware procurement with technical talent access.
Within the integrated studio tier, Annapurna Studios and Green Rain Studios LLP exemplify captive infrastructure models with on-premises production ecosystems. Qube Cinema occupies a position among rendering pipeline specialists serving regional cinema markets. These three entities represent distinct strategic postures—geographic anchoring, proprietary volume ownership, and software-centric specialization—without overlapping segment focus.
| Leading Market Players |
|---|
| Green Rain Studios LLP |
| Liminal - VR/AR Agency |
| Adobe Inc. |
| Qube Cinema |
| Media.Monks (S4 Capital) |
| Annapurna Studios |
| Intellistudios (DB Productions) |
| TILTLABS |
| Cineom |
| Others |
Pricing and Supply Chain Analysis
Ninety-to-one-hundred-twenty-day BIS certification timelines for LED display modules concentrate pricing power among established vendors with pre-certified inventory, while compressing margins for new entrants facing extended vendor onboarding cycles in Maharashtra and Telangana studio clusters.
Pricing Analysis
Cost-plus contracts with semiconductor price indexation dominate LED panel procurement for 270-degree volume stages. Pricing stratifies across BIS-certified premium tiers, volume-scale standard tiers, and uncertified economy imports. Cost compression in mid-tier operator segments intensifies as 2.8mm pixel pitch panels face technical limitation pressures. Advertising agencies purchasing fractional stage time exhibit highest price sensitivity; integrated film studios with captive infrastructure show lowest.
Supply Chain Analysis
Strategic stockpiling of LED driver ICs and camera-tracking sensors prevails over just-in-time approaches due to CDSCO customs friction and BIS compliance delays. Manufacturing concentrates in China, South Korea, and Taiwan for display modules, motion-capture arrays, and rendering hardware. Supply chain risk centers on single-source vulnerability for specialized camera-tracking equipment. Distribution runs through Mumbai and Hyderabad studio clusters with technical service contract bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's virtual production market functions as a service-attach opportunity where recurring technical supervision and post-production finishing contracts expand faster than hardware procurement cycles, rewarding operators with integrated workflow capabilities.
For Market Incumbents: Consolidate LED volume capacity in Hyderabad and Mumbai through phased expansion of 270-degree stages, locking in BIS-certified vendor relationships before compliance timelines extend further. Threat substitution from cloud-based remote production demands captive technical talent pools. Backward integration into LED panel assembly via PLI scheme incentives reduces import dependency exposure. For New Entrants and Emerging Players: Differentiate on AI-assisted pre-visualization services bundled with fractional LED volume rentals, targeting commercial advertising agencies in Delhi-NCR and Bengaluru with compressed project timelines. The most penetrable white-space sits in mid-budget regional cinema productions seeking Telangana subsidy eligibility without full infrastructure ownership. Go-to-market through service unbundling partnerships with established Mumbai studios. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because technical service contracts and post-production finishing generate margin concentration independent of hardware depreciation cycles. Acquisition targets should display integrated on-premises production ecosystems with state-level subsidy access. Monitor RBI cross-border data rule enforcement as inflection indicator for cloud-based deployment scalability.| Strategic Initiative | Industry Significance |
|---|---|
| LED Volume Capacity Expansion | Annapurna Studios and Green Rain Studios LLP anchor demand concentration through proprietary infrastructure ownership. |
| BIS Certification Investment | Pre-certified vendor pools filter competition and extend procurement timelines for new market entrants. |
| Technical Talent Acquisition | Unreal Engine specialization scarcity in Indian VFX training pipelines creates pricing premiums for certified operators. |
| Cloud-Based Service Orchestration | RBI digital payment infrastructure enables distributed billing models across smaller cities beyond studio clusters. |
| State Subsidy Program Alignment | Telangana film subsidy programs attract streaming platform content investment beyond traditional Bollywood centers. |
Research Methodology
Initial hypotheses were tested against primary input from virtual production facility directors, BIS certification consultants, LED panel procurement managers, and regional cinema producers, and refined through secondary validation against TRAI broadcast quality filings, BIS IS 13252 certification databases, PLI scheme disclosure documents, and RBI cross-border data regulation circulars. Bottom-up studio capacity estimates triangulated with top-down market sizing across technology and deployment segments.
Variance decomposition across the projection horizon isolates technology adoption rates, regulatory compliance timeline shifts, and state subsidy program expansions as primary uncertainty sources. Segmentation modeling spans LED volume configurations, real-time rendering pipelines, motion-capture hardware, and AR integration tiers crossed with on-premises, cloud-based, hybrid, and remote production deployment modes. CAGRs derive from installed base growth curves and capital expenditure intensity patterns specific to feature film and commercial advertising production cycles.
The analysis sits within stated boundaries; outcomes outside sustained PLI scheme incentives, stable BIS certification processing capacity, or continued streaming platform content investment would require recalibration. Forecasts reflect documented assumptions regarding LED panel cost trajectories and technical artist pipeline development. Revision becomes warranted when RBI data localization enforcement crosses thresholds that materially constrain cloud-based collaboration architectures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Learning Market
Virtual Reality (VR) and Augmented Reality (AR)
AR Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
VR HMD Shipment Market
Virtual Reality (VR) and Augmented Reality (AR)
Automotive Augmented Reality (AR) HUD System Market
Virtual Reality (VR) and Augmented Reality (AR)
Location Based VR Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Mobile Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Smart Glasses for Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Canada Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Dressing Room Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality (VR) Simulator Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Reality Automotive Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented Reality Software Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Immersive Technology Market
Virtual Reality (VR) and Augmented Reality (AR)
Smart Augmented Reality Glasses for B2B Market
Virtual Reality (VR) and Augmented Reality (AR)
Florida Augmented and Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Extended Reality (XR) Market