
 Virtual Reality for Consumer Market | 2026-2036
Virtual Reality for Consumer Market Size, Share, and Industry Trends Forecast 2026-2036
Virtual Reality for Consumer Market Outlook
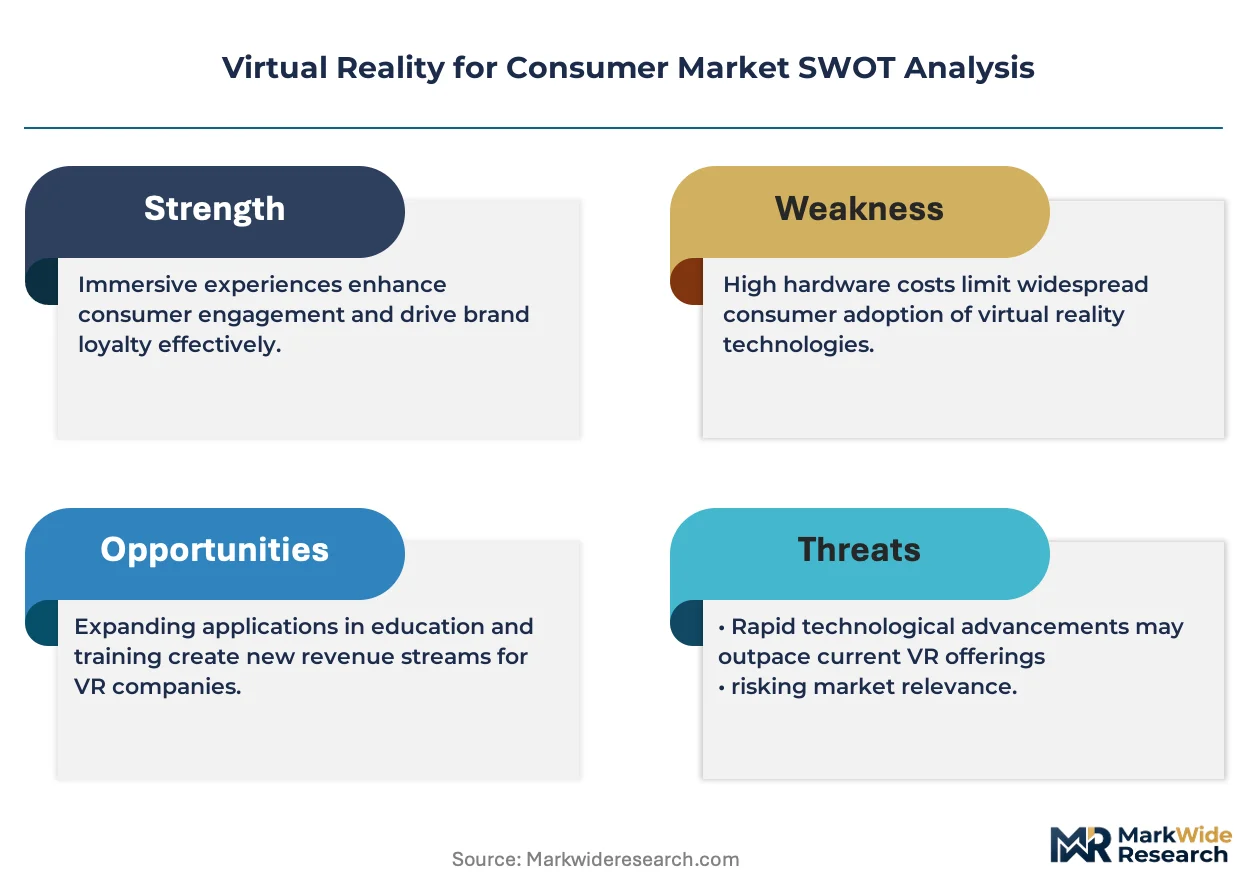
The EU AI Act is hardening compliance requirements for eye-tracking and biometric data collection in consumer VR headsets, elevating engineering costs for new entrants. Meta leverages its social platform integration to sustain ecosystem lock-in across hardware and software layers. Sony anchors its position through exclusive gaming content pipelines that differentiate PlayStation VR from cross-platform competitors. Valve specializes in premium PC-tethered experiences that dominate enthusiast segments with precision tracking systems.
Virtual Reality for Consumer encompasses immersive head-mounted displays, motion controllers, and spatial computing software delivering stereoscopic 3D environments with sub-20ms motion-to-photon latency for entertainment and social applications. Headsets and consoles concentrate the highest margin pools where integrated hardware-software stacks command premium positioning, while smartphone-based VR faces structural decline as dedicated devices improve affordability. Gaming applications lead volume adoption among teens and young adults, though social interaction platforms represent the fastest-growing engagement category as persistent virtual worlds expand beyond entertainment into digital commerce and community infrastructure.
FCC equipment authorization rules in the United States govern radio frequency emissions from wireless VR headsets, while GDPR and the EU AI Act jointly constrain biometric data processing across European consumer deployments. China's MIIT enforces GB standards for electromagnetic compatibility and network security on domestically sold devices, creating divergent certification pathways for multinational vendors. Stakeholders must monitor evolving interoperability mandates between competing hardware ecosystems as regulatory pressure on data portability intensifies across major consumer markets.
Market Dynamics
Eye-tracking biometric sensors in consumer headsets face escalating compliance burdens under the EU AI Act, forcing hardware engineers to redesign data pipelines before products reach European retail channels. This regulatory compression is reshaping development timelines and certification budgets across the entire headset supply base.
Growth Catalysts
- Foveated Rendering:This GPU efficiency technique reduces computational load by 50-70% during high-fidelity gaming sessions. Console manufacturers embed the capability into next-generation system architectures.
- Social Platform Integration:Persistent virtual worlds transform headsets into communication infrastructure. Digital commerce and community events now occur inside immersive environments rather than on flat screens.
- GB Standards Compliance:China's MIIT certification pathway accelerates domestic market access for locally manufactured devices. Multinational vendors establish captive production facilities in Shenzhen and Chengdu to satisfy electromagnetic compatibility mandates.
Market Restraints
- Display Panel Concentration:OLED microdisplay fabrication concentrates in South Korean and Taiwanese foundries. Supply disruptions at single-source suppliers cascade through assembly schedules.
- Motion-to-Photon Latency Floors:Sub-20ms latency requirements demand specialized ASICs and high-refresh panels. Cost curves for these components flatten below premium price tiers.
- Biometric Data Friction:GDPR Article 9 restrictions on processing special category data complicate eye-tracking deployment across EU member states. Legal review extends product launch windows by 8-14 months.
Strategic Opportunities
- Fitness and Wellness Applications:Exergaming and virtual training environments attract health-conscious demographics outside traditional gaming cohorts. Heart rate integration and metabolic tracking expand addressable use cases.
- India PLI Scheme:Production-linked incentives for electronics manufacturing attract assembly investments. Domestic value-add requirements create localization partnerships for component sourcing.
- Cloud Rendering Architectures:Edge computing infrastructure offloads GPU processing from local hardware. Low-latency 5G networks enable lightweight headset designs at reduced bill-of-materials cost.
Industry Challenges
- Optical Engineering Talent Scarcity:Waveguide design and pancake lens optimization require specialized physics expertise. Compensation inflation in Silicon Valley and Taipei outpaces regional hiring budgets.
- Multi-Jurisdiction Certification Overhead:FCC, CE marking, and MIIT approvals demand parallel testing protocols. Documentation translation and regulatory consulting consume 12-18% of pre-launch engineering resources.
- Content-Platform Interoperability:Proprietary SDKs and store exclusives fragment developer attention. Cross-platform engine optimization increases QA complexity and certification risk.
Report Scope
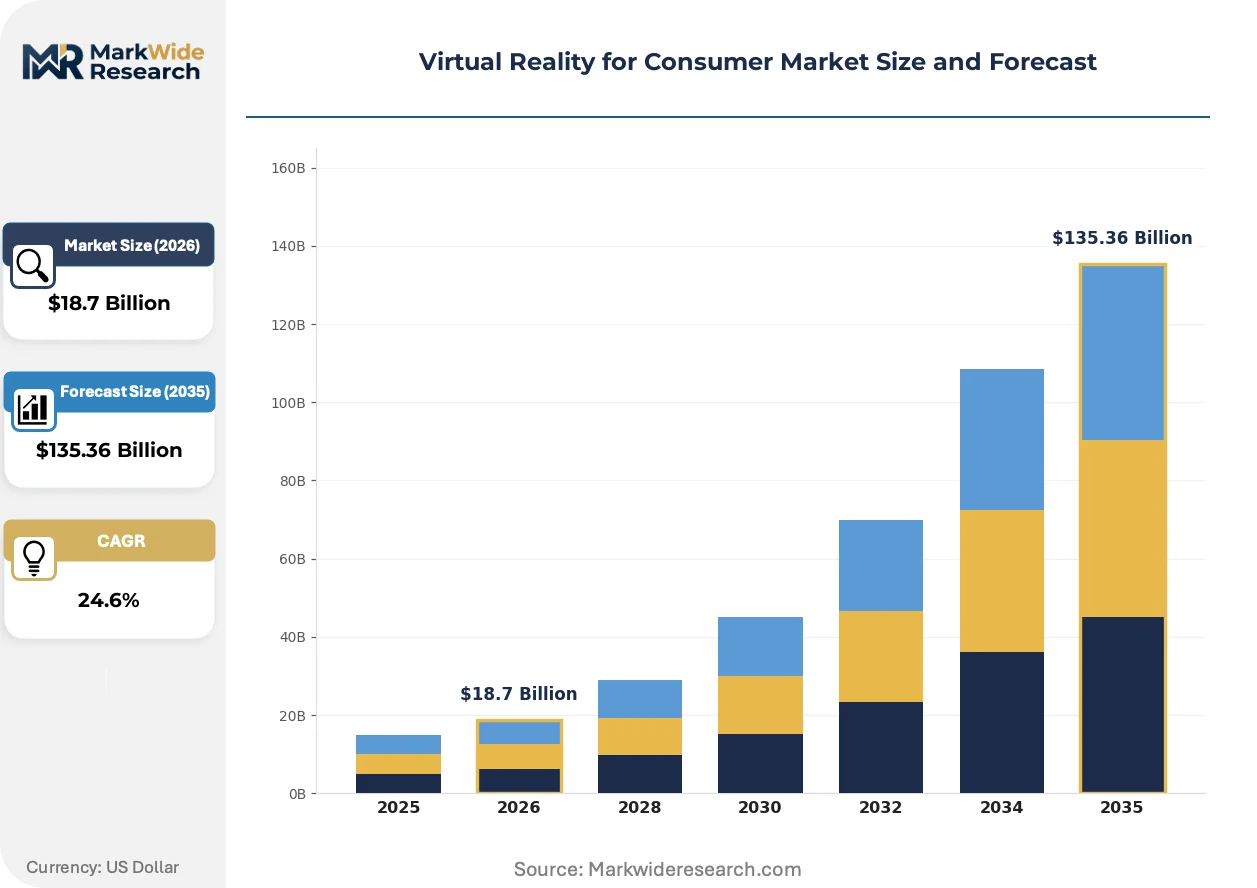
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Virtual Reality for Consumer Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $135.36 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Headsets, Smartphones, PCs, Consoles Application Area: Gaming, Education, Training, Social Interaction Content Type: Games, Simulations, Movies, Experiences User Demographic: Teens, Young Adults, Professionals, Casual Users |
| Companies Covered | Valve, Google, Meta, VRChat, Varjo, Apple, HTC, Beat Games, Sony, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Virtual Reality for Consumer Market Strategic Shifts
Spatial computing interfaces are migrating from entertainment peripherals toward general-purpose computing platforms. Three converging developments—sensor fusion, regulatory harmonization efforts, and distribution model experimentation—are compressing the timeline for mainstream adoption.
Pancake optical stacks are integrating polymer-based folded optics to reduce headset thickness below 25 millimeters. Gaming peripheral manufacturers adopt these modules for 2024-2025 product refreshes at mid-tier price points. The structural consequence is that premium form factors are integrating into mass-market hardware faster than previous display transitions permitted.
The EU AI Act's biometric data classification is forcing hardware vendors to implement on-device processing architectures. Eye-tracking inference must occur locally rather than in cloud pipelines to avoid high-risk system designations. European consumer deployments now require edge AI accelerators that add 8-12 dollars to bill-of-materials costs, compressing margin structures for entry-level SKUs.
Enterprise procurement pilots for training and simulation are spilling into consumer channel strategies. Hardware vendors now sell direct-to-business before retail launch to amortize certification costs across guaranteed volume commitments. This pattern is most visible in Germany and Japan where industrial safety regulations mandate VR-based hazardous environment training for energy and manufacturing sectors.
Virtual Reality for Consumer Market Segmentation
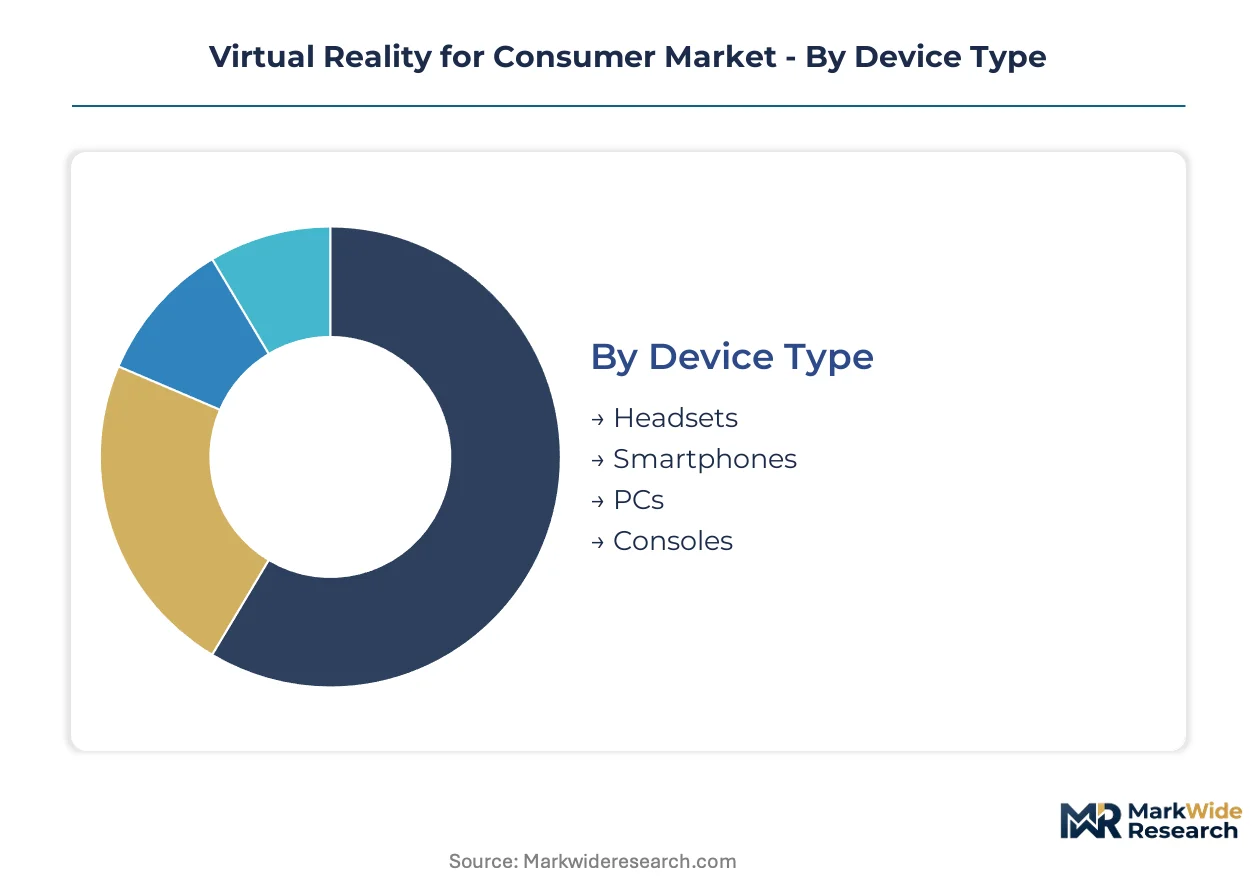
Segmentation in consumer VR reveals divergent capital requirements across hardware categories and distinct engagement patterns across user cohorts. Understanding these divides helps vendors allocate R&D budgets and prioritize certification pathways.
Device Type:
Headset manufacturing demands the heaviest upfront investment in optical engineering and sensor integration, while smartphone-based VR requires minimal dedicated hardware expenditure.
- Headsets:Integrated display panels, pancake optics, and eye-tracking arrays define the premium tier. Shenzhen and Chengdu production clusters absorb the majority of assembly capacity for tethered and standalone units alike, driven by MIIT certification requirements that favor localized supply chains.
- Consoles:Closed ecosystems leverage exclusive content pipelines to justify hardware subsidies. Sony's PlayStation VR anchors this segment through first-party studio acquisitions that lock developers into proprietary SDKs.
- PCs:Valve Index and comparable tethered systems target enthusiast segments with external tracking base stations and high-refresh panels. Precision motion controllers command premium positioning above console alternatives.
- Smartphones:Cardboard-derived viewers and snap-on housings face structural decline as dedicated headsets achieve sub-$300 price points. Samsung and Google have exited active development of phone-dependent VR platforms.
Headsets absorb the bulk of installed capacity; consoles are expanding most quickly through bundled hardware-software offerings.
Application Area:
Volume concentration varies sharply by engagement depth, with gaming commanding session frequency while social platforms capture daily active user growth.
- Gaming:First-person shooters and rhythm games dominate session time among teens and young adults. Foveated rendering integration in next-generation console architectures reduces GPU thermal loads during extended play.
- Social Interaction:Persistent virtual worlds transform headsets into communication infrastructure. Meta Horizon and comparable platforms now host digital commerce and community events that extend beyond entertainment into lifestyle utility.
- Training:Hazardous environment simulations for energy and manufacturing sectors spill into consumer channel strategies through enterprise procurement pilots. German industrial safety regulations mandate VR-based certification programs that amortize hardware development costs.
- Education:K-12 deployments and university laboratory simulations drive institutional purchasing cycles. Content licensing models favor subscription revenue over perpetual sales in this segment.
Gaming retains the deepest engagement metrics; social interaction is gaining share fastest as platform network effects compound.
Content Type:
Production economics diverge between real-time rendered experiences and pre-computed cinematic content, with implications for storage, bandwidth, and hardware requirements.
- Games:Interactive mechanics demand sub-20ms motion-to-photon latency and high-refresh display panels. Unity and Unreal Engine licensing fees concentrate developer attention on premium storefronts with established user bases.
- Experiences:Location-based entertainment and museum installations drive B2B hardware sales. Immersive documentary productions from National Geographic and comparable studios expand addressable audiences beyond traditional gaming cohorts.
- Simulations:Physics-accurate environments for flight training and medical procedures require specialized input peripherals. Haptic glove integration adds $200-400 to consumer system costs.
- Movies:180-degree and 360-degree video formats struggle against flat-screen competition for narrative attention. Distribution remains fragmented across Meta Quest TV, YouTube VR, and studio-exclusive applications.
Games command the highest per-user revenue; experiences show the steepest expansion trajectory as location-based venues reopen post-pandemic.
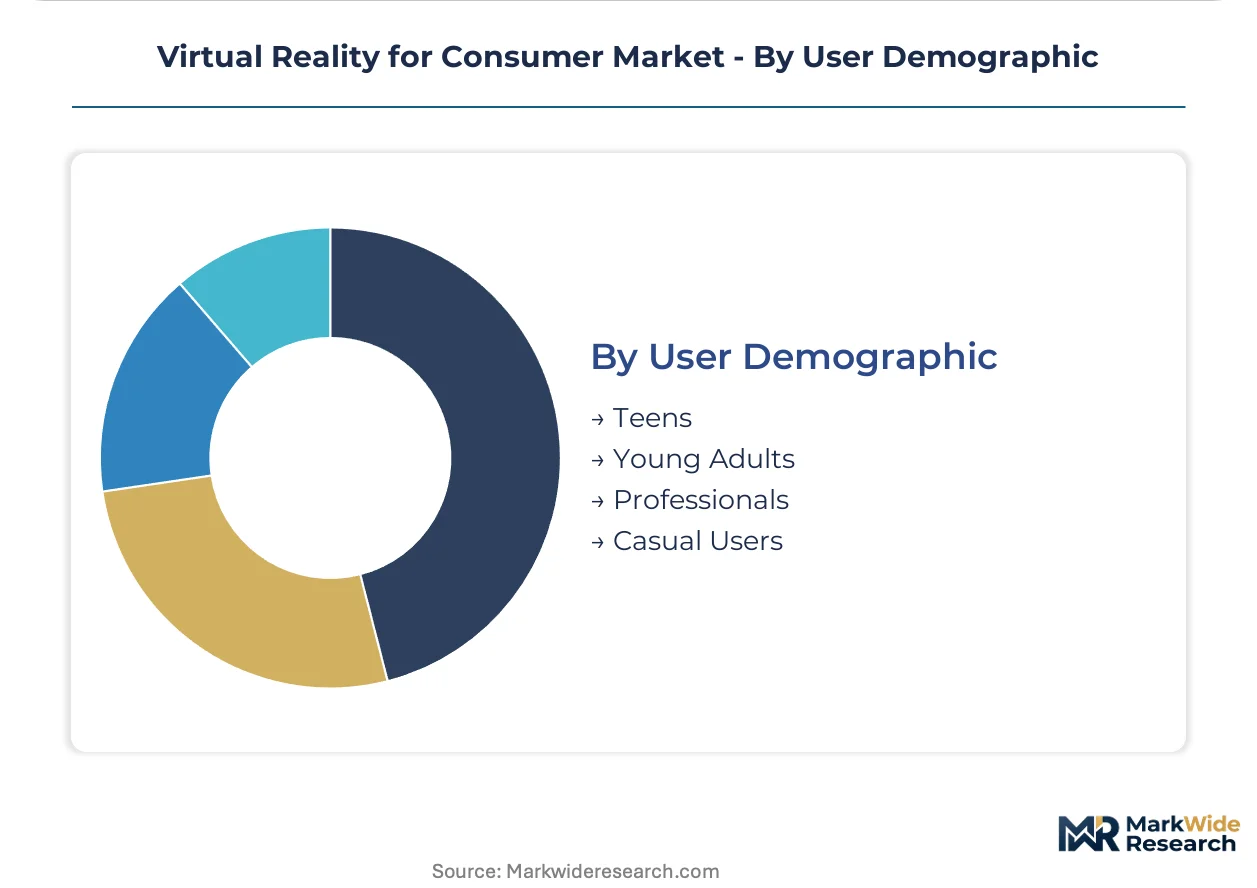
User Demographic:
Hardware purchasing power and content preferences stratify sharply across age and professional identity, with implications for pricing architecture and marketing channel selection.
- Young Adults:University students and early-career professionals represent the core addressable market for standalone headsets. Fitness and wellness applications attract health-conscious users outside traditional gaming demographics.
- Teens:Parental purchase decisions hinge on content moderation tools and screen-time management features. COPPA compliance and comparable youth data protections constrain social platform feature development.
- Professionals:Remote collaboration tools and virtual office environments drive enterprise procurement that subsidizes personal hardware acquisition. Spatial computing interfaces migrate from entertainment peripherals toward general-purpose productivity platforms.
- Casual Users:Infrequent engagement patterns favor low-cost smartphone-based solutions or shared household console access. Retention challenges in this cohort limit lifetime value calculations for subscription services.
Young Adults absorb the bulk of installed capacity; Professionals are climbing the fastest as hybrid work arrangements normalize virtual presence tools.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen's Qianhai Free Trade Zone concentrates headset assembly capacity through MIIT-certified production clusters that serve both domestic Chinese demand and export markets.
United States
FCC equipment authorization rules govern wireless VR headset emissions, while FDA oversight applies to wellness applications with biometric sensors. Seattle and Menlo Park host engineering centers where social platform integration drives hardware-software co-development. Meta's Reality Labs operations anchor West Coast optical engineering talent pools.
China
GB standards for electromagnetic compatibility and network security create divergent certification pathways for multinational vendors. MIIT enforces domestic value-add requirements that accelerate captive production facility establishment. Chengdu and Shenzhen production clusters absorb the majority of global headset assembly capacity through vertically integrated supply chains.
Germany
Industrial safety regulations mandate VR-based hazardous environment training for energy and manufacturing sectors, creating enterprise procurement spillover into consumer channels. KBA and regional labor authorities enforce certification requirements that amortize hardware development costs. Bavaria's Munich-Stuttgart corridor concentrates optical engineering expertise for premium tethered systems.
Japan
METI promotes spatial computing adoption through cross-industry consortia linking consumer entertainment with enterprise simulation demand. JIS standards govern electromagnetic compatibility for domestically sold devices. Tokyo and Osaka metropolitan areas host development studios that specialize in location-based entertainment content pipelines.
South Korea
OLED microdisplay fabrication concentrates in Seoul and Suwon foundries, creating supply dependencies that cascade through global assembly schedules. MFDS oversight applies to wellness applications with health-monitoring sensors. Pangyo Techno Valley hosts hardware engineering centers where foveated rendering architectures receive priority R&D allocation.
Virtual Reality for Consumer Market Competitive Environment
United States producers anchor the social platform integration tier; Finnish and Japanese specialists hold precision optics and location-based entertainment positions. The vendor base concentrates around three strategic archetypes: closed-ecosystem console manufacturers, open-platform PC peripheral vendors, and mobile-derived standalone headset producers. Capacity expansion through Shenzhen production partnerships and strategic technology licensing for eye-tracking ASICs constitute the dominant competitive moves.
Within the closed-ecosystem tier, Sony Corporation and Meta Platforms, Inc. exemplify divergent approaches to hardware-software integration. Valve Corporation occupies a position among PC-tethered specialists that prioritize precision tracking over mass-market accessibility. These three anchors represent the spectrum from console-exclusive content pipelines through social platform lock-in to enthusiast-grade open architectures.
| Leading Market Players |
|---|
| Valve |
| Meta |
| VRChat |
| Varjo |
| Apple |
| HTC |
| Beat Games |
| Sony |
| Others |
Value Chain & Pricing Dynamics
Optical engineering talent scarcity in Silicon Valley and Taipei drives labor-cost differentials that widen pricing-tier spreads between premium tethered systems and entry-level standalone headsets. Shenzhen assembly clusters compress mid-tier pricing through captive production capacity, while EU AI Act compliance costs elevate European retail premiums.
Pricing Analysis
Lead-time-driven pricing stratifies across fulfillment windows, with premium SKUs commanding markups for sub-30-day delivery against spot-inventory discounts for prior-generation hardware. Three-tier pricing structure across enthusiast, mainstream, and entry-level segments differentiates by foveated rendering capability and eye-tracking precision. Pricing pressure stems from OLED microdisplay supply constraints and MIIT certification overhead. Casual users exhibit highest price sensitivity, while enterprise procurement pilots show lowest sensitivity due to amortized training budgets.
Supply Chain Analysis
Freight cost volatility from Asian manufacturing hubs to Western distribution centers compresses margin structures for entry-level SKUs with thinner unit economics. Component sourcing concentrates in China, South Korea, and Taiwan, with pancake optics and eye-tracking ASICs drawing from specialized foundries. Single-source vulnerability pervades OLED microdisplay procurement from Seoul and Suwon facilities. Distribution runs through direct-to-consumer channels and enterprise procurement pilots ahead of retail launches.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pancake optical stacks are displacing legacy Fresnel lens architectures, compressing form-factor timelines and reshaping competitive positioning across hardware tiers. This technology transition favors vendors with captive optical engineering capacity.
For Market Incumbents: Acquire specialized waveguide design teams to secure talent pools against compensation inflation. Consolidate certification resources across FCC, CE marking, and MIIT pathways to reduce parallel testing overhead. Defend against cloud-rendering entrants by embedding edge AI accelerators into hardware reference designs. For New Entrants and Emerging Players: Fitness and wellness application stacks offer technology-first wedge opportunities outside saturated gaming cohorts. Target health-conscious demographics with heart rate-integrated exergaming peripherals. Pursue India PLI scheme partnerships for assembly localization and component sourcing advantages. For Investors and Strategic Acquirers: Re-rating potential sits with eye-tracking ASIC specialists given EU AI Act on-device processing mandates. Five-to-ten-year viability hinges on regulatory harmonization across biometric data frameworks. Monitor enterprise procurement pilot volumes as inflection signal for consumer channel spillover timing.| Strategic Initiative | Industry Significance |
|---|---|
| Eye-Tracking ASIC Acquisition | EU AI Act compliance accelerates demand for on-device biometric inference accelerators. |
| Shenzhen Production Partnership | MIIT certification requirements favor localized assembly for Chinese market access. |
| Cloud Rendering Architecture Launch | 5G edge computing infrastructure enables lightweight headset designs at reduced BOM cost. |
| Fitness Application Platform Integration | Health-conscious demographics outside gaming cohorts expand addressable user base. |
| Enterprise Procurement Pilot Expansion | German industrial safety regulations mandate VR training, amortizing hardware development costs. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with optical engineering directors, hardware procurement leads at gaming studios, MIIT certification consultants, and enterprise training program managers validated supply-side assumptions. FDA 510(k) filings, FCC equipment authorization databases, EMA guidance documents, and MIIT GB standard publications provided secondary triangulation. Bottom-up headset shipment modeling and top-down entertainment hardware spending analysis converged on segment-level estimates.
Granularity-level modeling disaggregated volume and value across device type, application area, content type, and user demographic dimensions throughout the projection horizon. CAGRs derived from fitted growth curves applied to installed base expansion and replacement cycle assumptions. Foveated rendering adoption rates and eye-tracking sensor penetration served as technology-specific forecast inputs alongside regulatory compliance cost trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EU AI Act enforcement escalation or OLED microdisplay supply disruption scenarios. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
AR in Healthcare Market
Virtual Reality (VR) and Augmented Reality (AR)
Commercial Augmented Reality Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
Immersive Simulator Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Reality (AR) Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Ski Machines Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality Training Market
Virtual Reality (VR) and Augmented Reality (AR)
AR and VR in Training Market
Virtual Reality (VR) and Augmented Reality (AR)
Telepresence Equipment Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Reality (AR) Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
Europe Augmented Reality (AR) and Mixed Reality (MR) Market
Virtual Reality (VR) and Augmented Reality (AR)
Asia-Pacific Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Asia-Pacific Virtual Reality (VR) Health Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Tour Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Augmented and Mixed Reality (VR/AR) Market
Virtual Reality (VR) and Augmented Reality (AR)
Neuro-Gaming Technology Market
Virtual Reality (VR) and Augmented Reality (AR)
Spatial Augmented Reality Market